
 Aluminium Rolled Products Market | 2026-2036
Aluminium Rolled Products Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminium Rolled Products Market Analysis
Continuous casting and twin-roll casting integration is tilting cost curves toward thinner-gauge, higher-strength alloys for automotive and packaging end uses. Novelis leverages its closed-loop recycling network to sustain premium positioning in beverage can sheet across North America and Europe. Hindalco Industries anchors its rolled products strategy on captive alumina-to-foil integration, dominating thin-gauge supply for pharmaceutical and food packaging in South Asia. Constellium SE competes on aerospace-qualified plate and sheet, occupying the high-performance segment with airframe alloy certifications.
Aluminium rolled products are flat-rolled semi-finished goods produced by hot and cold rolling of cast slabs or continuous-cast strip, typically ranging from 0.006 mm foil to 150 mm plate, with alloys designated by the AA 1xxx through 8xxx series based on principal alloying elements. These products serve as input materials for forming, fabrication, and assembly across transportation, building, consumer goods, and electrical applications. Sheet commands the largest volume share given its ubiquity in automotive body panels and construction cladding, while foil represents the fastest-expanding margin pool as battery-grade separator substrates and flexible packaging demand intensify. Coil formats dominate logistics-efficient supply chains, particularly for continuous processing lines in automotive stamping and can manufacturing.
The US EPA tailpipe standards and NHTSA fuel economy rules mandate fleet-wide efficiency gains that directly expand aluminium sheet content per vehicle. The EU Green Deal and REACH chemical compliance frameworks impose embodied carbon tracking and substance restrictions that filter market access for non-European suppliers. China's MEE dual carbon enforcement and GB standards on energy consumption intensity are restructuring domestic smelter and rolling mill competitiveness. Stakeholders must monitor evolving carbon border adjustment mechanisms and alloy-specific certification requirements to secure long-term supply contracts with regulated OEMs and packaging multinationals.
Market Dynamics
Automotive lightweighting mandates are compressing gauge requirements and tightening alloy specifications across the aluminium rolled products value chain. OEMs now specify certified low-carbon sheet for body-in-white applications, forcing rolling mills to reconfigure casting and thermal processing lines.
Growth Catalysts
- US NHTSA fuel economy rules:Fleet efficiency mandates expand aluminium sheet content per vehicle platform. Body panel specifications now favor 6xxx-series alloys for strength-to-weight ratios.
- Battery separator foil demand:Electric vehicle production pulls ultra-thin foil substrates for cell assembly. Cell manufacturers qualify mills on thickness consistency and surface cleanliness metrics.
- Germany's automotive corridor concentration:OEM sourcing clusters around Munich-Stuttgart drive premium alloy demand. Certified low-carbon supply chains win multi-year supply contracts.
Market Restraints
- Primary aluminium ingot price volatility:LME price swings compress rolling margins unpredictably. Mills hedge exposure through long-term alumina supply agreements.
- China smelter concentration:Domestic capacity controls under MEE dual carbon enforcement limit export availability. Non-Chinese buyers face allocation constraints.
- Steel advanced high-strength alloys:AHSS grades compete for structural automotive applications below 1.2 mm gauge. Cost-per-kilogram differentials favor steel in non-skin panels.
Strategic Opportunities
- India packaging foil penetration:Pharmaceutical and food flexibles demand outpaces domestic thin-gauge capacity. Import substitution incentives under PLI scheme attract rolling investment.
- EU carbon border adjustment mechanism:CBAM phase-in creates first-mover advantage for low-carbon certified mills. Embodied carbon documentation becomes contract prerequisite.
- Continuous-twin roll casting convergence:Hybrid casting-rolling lines collapse capital intensity for thin-gauge production. Technology licensors target mid-cap regional mills.
Industry Challenges
- Automotive alloy certification timelines:OEM qualification cycles span 18-24 months for new sheet grades. Mill R&D allocation strains against near-term volume targets.
- Scrap segregation and closed-loop logistics:Post-consumer alloy sorting complexity limits recycling yield. Automotive stamping scrap requires dedicated collection infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminium Rolled Products Market |
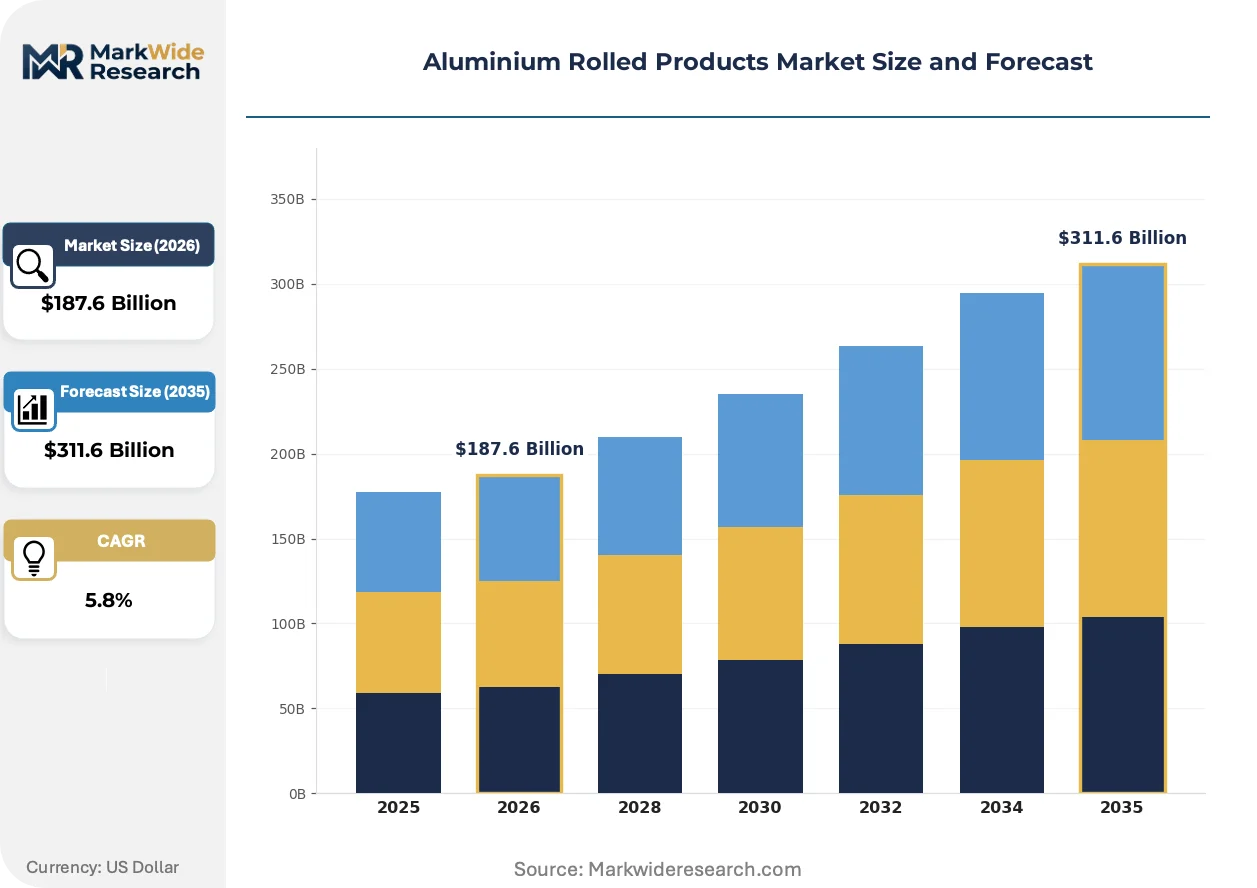
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $311.6 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sheet, Plate, Foil, Coil End User: Aerospace, Automotive, Construction, Packaging Thickness: Thin, Medium, Thick, Ultra-Thin Application: Heat Exchangers, Electrical Conductors, Building Facades, Industrial Equipment |
| Companies Covered | Hindalco Industries Ltd., Constellium SE, UACJ Corporation, Novelis Inc., Granges AB, Arconic, Norsk Hydro ASA, Alcoa Corporation, Aluminum Corporation of China Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminium Rolled Products Market Emerging Trajectories
Process intensification and digital metallurgy are compressing development cycles for automotive-qualified alloys. Rolling mills invest in inline sensing and predictive quality systems to reduce offline testing.
Twin-roll casting to 3-6 mm gauge is collapsing the conventional slab-hot rolling-cold rolling sequence for packaging and automotive strip. Beverage can body stock producers adopt this route for 3xxx and 5xxx alloys. Capital requirements fall 40-50% versus ingot-based flows, enabling regional mill entry.
The EU Green Deal's embodied carbon tracking requirements are filtering supplier qualification criteria for European automotive and packaging buyers. Non-European mills face documentation burdens that delay contract awards. German OEMs now require Scope 3 emissions declarations back to bauxite mining.
Buyer concentration among multinational beverage and automotive assemblers is consolidating procurement into direct mill relationships, bypassing traditional distributors. Long-term offtake agreements with volume commitments replace spot purchases. North American can sheet contracts now run 5-7 years with price collars tied to Midwest premium indices.
Aluminium Rolled Products Market Segmentation
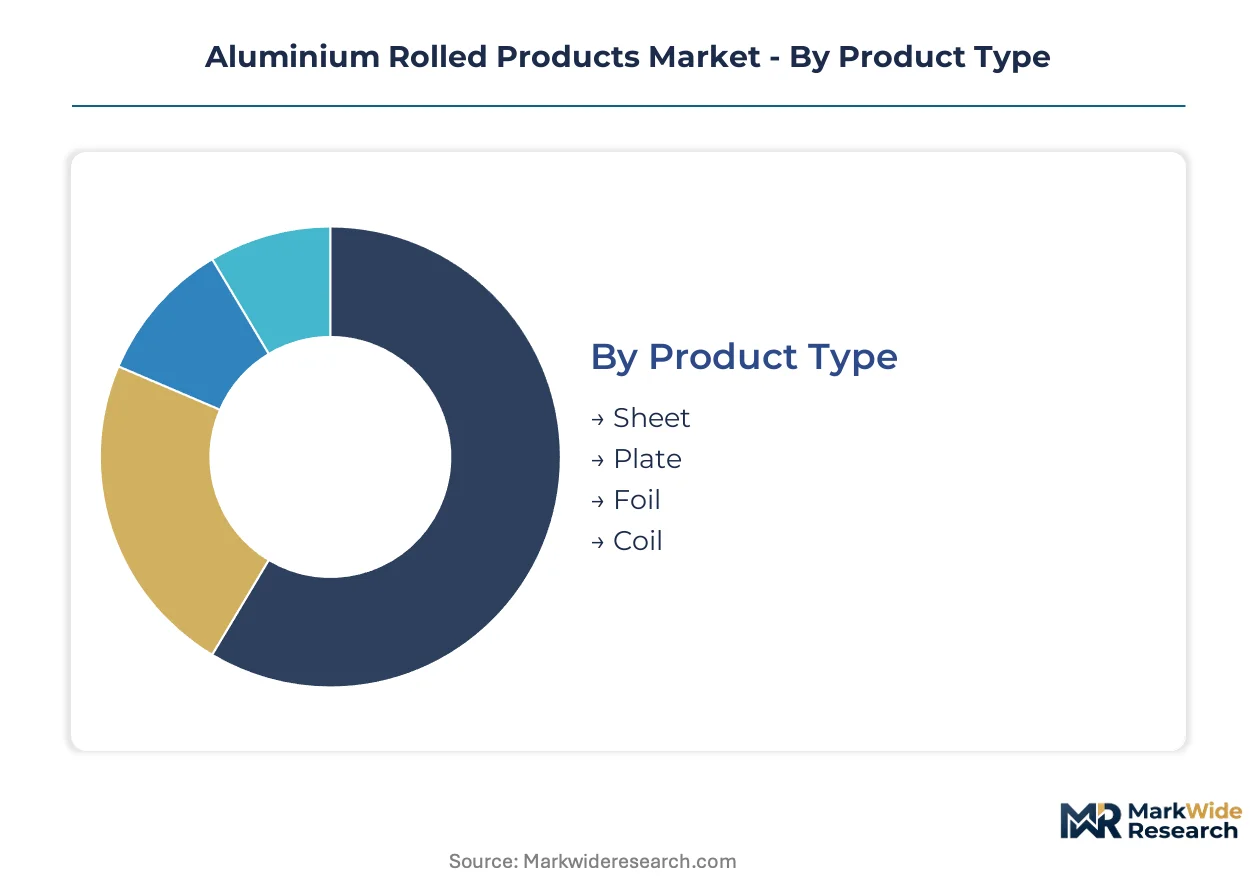
Aluminium rolled products span dimensional, functional, and industry-specific boundaries that dictate alloy selection, processing routes, and margin structures. Understanding how demand fragments across these dimensions reveals where capital deployment and qualification efforts concentrate.
Product Type:
Flat-rolled formats serve distinct use-case spectra from structural load-bearing to barrier protection, each demanding specialized casting and rolling configurations.
- Sheet:Hot- and cold-rolled flat products typically 0.2-6.0 mm thick, serving automotive body panels and construction cladding. German OEMs in the Munich-Stuttgart corridor specify certified low-carbon 6xxx-series sheet for body-in-white applications, with qualification cycles spanning 18-24 months.
- Foil:Rolled products below 0.2 mm, extending to 0.006 mm for battery separator substrates and pharmaceutical packaging. Electric vehicle cell manufacturers in South Korea and Japan qualify mills on thickness consistency and surface cleanliness metrics, pulling ultra-thin gauge capacity expansion.
- Plate:Thickness above 6.0 mm for aerospace airframes, mold tooling, and heavy equipment structures. Airframe alloy certifications from FAA and EASA restrict supplier pools to mills with dedicated heat-treatment lines.
- Coil:Continuously wound strip formats optimizing logistics for high-volume stamping and can manufacturing operations. Beverage multinationals in North America negotiate 5-7 year offtake agreements with price collars tied to Midwest premium indices.
The dominant share belongs to Sheet, while Foil is closing the gap fastest.
End User:
Customer industries impose divergent technical standards, with automotive and aerospace demanding the most stringent alloy certification protocols.
- Automotive:Body panels, structural components, and battery enclosures driving lightweighting compliance with US NHTSA fuel economy rules. OEMs now mandate Scope 3 emissions documentation back to bauxite mining under EU Green Deal supplier criteria.
- Packaging:Beverage cans, food flexibles, and pharmaceutical blisters where 3xxx and 5xxx alloys dominate. India's PLI scheme for import substitution attracts thin-gauge rolling investment as domestic demand outpaces capacity.
- Aerospace:Airframe plate and sheet requiring 7xxx and 2xxx alloy certifications from FAA and EASA. Constellium SE and limited competitors occupy this high-performance segment with restricted qualified supplier lists.
- Construction:Building facades, roofing, and cladding systems favoring 1xxx and 3xxx series for corrosion resistance. China's GB standards on energy consumption intensity restructure domestic mill competitiveness for architectural coil supply.
Automotive commands the largest volume allocation, though Packaging offers the steepest expansion trajectory.
Thickness:
Gauge specifications determine casting route economics and end-use accessibility, with thinner dimensions commanding premium positioning.
- Ultra-Thin:Below 0.05 mm for battery separator substrates and capacitor foils. Twin-roll casting convergence enables 3-6 mm direct strip production, collapsing capital intensity versus conventional slab routes.
- Thin:0.05-0.5 mm range for flexible packaging and heat exchanger fins. Hindalco Industries anchors captive alumina-to-foil integration dominating South Asian pharmaceutical and food packaging supply.
- Medium:0.5-3.0 mm serving automotive body panels and can body stock. Continuous-twin roll casting lines target this gauge band for regional mill entry with 40-50% lower capital requirements.
- Thick:Above 3.0 mm for structural plate, tooling, and industrial equipment. Ingot-based hot rolling remains necessary for aerospace-qualified thick plate given microstructure requirements.
Medium gauge generates the highest absolute tonnage, yet Ultra-Thin delivers the strongest margin expansion.
Application:
Functional use cases fragment demand across thermal management, electrical transmission, architectural, and industrial equipment markets.
- Building Facades:Architectural cladding and curtain wall systems requiring anodizing-grade surface quality. EU Green Deal embodied carbon tracking filters non-European supplier qualification for European construction projects.
- Heat Exchangers:Brazing sheet and fin stock for HVAC and automotive thermal systems. Clad products with 4xxx-series brazing layers demand precise rolling reduction schedules.
- Electrical Conductors:Busbar and cable wrap applications where 1xxx-series purity grades minimize resistivity. Grid infrastructure investment in India and Southeast Asia pulls conductor-grade strip demand.
- Industrial Equipment:Chemical processing vessels, mold bases, and machinery components. Corrosion-resistant alloys compete with stainless steel on total lifecycle cost in marine and chemical environments.
Building Facades holds the established position, while Heat Exchangers is gaining share fastest on electric vehicle thermal management requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEMs and beverage multinationals concentrate procurement in five countries where rolling mill capacity, regulatory frameworks, and end-user density align. Each geography presents distinct qualification barriers and alloy specification trends.
United States
NHTSA fuel economy mandates expand 6xxx-series sheet content per vehicle platform. EPA tailpipe standards filter supplier pools through lifecycle emissions documentation. Detroit-Windsor automotive corridor OEMs negotiate 5-7 year can sheet offtake agreements with Midwest premium index collars.
Germany
Munich-Stuttgart automotive corridor drives premium alloy demand for body-in-white applications. EU Green Deal embodied carbon tracking requires Scope 3 declarations back to bauxite mining. KBA vehicle certification protocols extend mill qualification cycles to 18-24 months for new sheet grades.
China
Dual carbon enforcement under MEE restructures smelter and rolling mill competitiveness. GB standards on energy consumption intensity limit export availability from domestic capacity controls. Yangtze River Delta packaging clusters pull thin-gauge foil investment under import substitution incentives.
India
Pharmaceutical and food flexibles demand outpaces domestic thin-gauge rolling capacity. PLI scheme incentives attract regional mill entry for packaging foil penetration. Maharashtra and Gujarat industrial corridors concentrate pharmaceutical blister and flexible packaging conversion.
Japan
Battery separator substrate demand from South Korean and Japanese cell manufacturers qualifies mills on thickness consistency metrics. METI industrial standards govern ultra-thin foil surface cleanliness specifications. Kansai region rolling mills supply capacitor and battery-grade ultra-thin gauge output.
Aluminium Rolled Products Market Vendor Landscape
Channel-controlling players compete with product-specialist players across three discernible tiers. Integrated aluminium majors with captive alumina-to-rolling flows occupy the top tier, commanding premium positioning through alloy certification depth. Mid-cap regional mills with continuous-twin roll casting lines compete on capital efficiency for packaging and standard automotive strip. Pure-play recyclers with closed-loop logistics anchor the third tier, securing beverage can sheet contracts through scrap segregation capabilities. Capacity expansion and strategic partnerships dominate competitive moves, with mills prioritizing long-term offtake agreements over spot market exposure.
Within the integrated major tier, Hindalco Industries Ltd. and Novelis Inc. exemplify divergent geographic anchoring strategies, with the former representing captive upstream control and the latter closed-loop recycling networks. Constellium SE occupies a position on the aerospace-qualified vector, where airframe alloy certifications restrict qualified supplier lists. These three entities collectively illustrate how certification depth, geographic footprint, and vertical integration configuration stratify competitive positioning across automotive, packaging, and aerospace end uses.
| Leading Market Players |
|---|
| Hindalco Industries Ltd. |
| Constellium SE |
| UACJ Corporation |
| Novelis Inc. |
| Granges AB |
| Arconic |
| Norsk Hydro ASA |
| Alcoa Corporation |
| Aluminum Corporation of China Limited |
| Others |
Supply Flow & Price Mechanics
The Hamburg-Rotterdam barge corridor moves primary aluminium ingot from German smelters to Dutch and Belgian rolling mills, with freight cost spikes during Rhine low-water events feeding directly into Midwest premium index volatility and compressing margins for non-integrated mills serving automotive stamping plants.
Pricing Analysis
Cost-plus contracts with LME primary aluminium indexation dominate long-term offtake agreements between rolling mills and automotive OEMs, with price collars tied to Midwest premium indices protecting both parties from extreme volatility. Certification grade and volume scale drive price differentiation, with aerospace-qualified plate commanding substantial premiums over standard automotive sheet. Pricing pressure stems from steel advanced high-strength alloys competing for structural applications below 1.2 mm gauge. Tier 2 automotive suppliers exhibit highest price sensitivity, while German OEMs in the Munich-Stuttgart corridor prioritize embodied carbon documentation over unit cost.
Supply Chain Analysis
Upstream feedstock flows from Chinese smelters under MEE dual carbon enforcement, Russian primary metal facing trade restrictions, and Middle Eastern low-carbon producers with captive energy. Bauxite, alumina, and primary ingot constitute the critical input trinity. Supply chain risk centers on single-source vulnerability for aerospace-qualified alloys given limited FAA and EASA certified mills. Distribution runs through direct mill relationships with multinational beverage and automotive assemblers, bypassing traditional metal distributors as procurement consolidates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power has shifted toward consolidated multinational assemblers in beverage and automotive, with procurement teams consolidating supplier pools and demanding decade-long offtake commitments with stringent carbon documentation requirements.
For Market Incumbents: Build certification moats around Scope 3 emissions tracking back to bauxite mining, locking in German OEM supply contracts before EU carbon border adjustment mechanisms fully phase in. Invest in continuous-twin roll casting capacity in India under PLI scheme incentives to capture packaging foil demand outpacing domestic supply. Threats include emerging Chinese mills with hybrid casting-rolling technology and steel AHSS grades competing for gauge-critical automotive applications. For New Entrants and Emerging Players: Establish a beachhead in India's pharmaceutical and food flexible packaging segment, where thin-gauge foil demand outstrips regional rolling capacity and import substitution incentives reduce capital recovery risk. Target mid-cap regional mills with technology licensing from twin-roll casting equipment providers, bypassing the capital intensity of conventional slab-hot rolling routes. Go-to-market angle: certified low-carbon supply chains for European packaging multinationals facing EU Green Deal embodied carbon tracking requirements. For Investors and Strategic Acquirers: Carve-out targets emerge from integrated aluminium majors divesting non-core rolling assets to focus on upstream smelting and alumina refining. Long-term viability favors mills with closed-loop recycling infrastructure and automotive alloy certification depth. Watch for inflection signals in battery separator foil qualification cycles, as South Korean and Japanese cell manufacturers accelerate capacity expansion and pull new mill entrants into their approved supplier lists.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alumina Refining | Captive alumina supply insulates Hindalco and Novelis from LME volatility and secures low-carbon feedstock claims for EU automotive contracts. |
| Continuous-Twin Roll Casting Technology Licensing | Hybrid casting-rolling lines enable regional mill entry with 40-50% lower capital intensity for packaging and standard automotive strip. |
| Long-term Supply Agreement with German OEMs | Munich-Stuttgart corridor contracts spanning 5-7 years with Scope 3 documentation requirements lock out non-compliant competitors. |
| Closed-Loop Recycling Network Expansion | Novelis leverages post-consumer beverage can collection infrastructure to sustain premium positioning in North American can sheet. |
| Aerospace Alloy Certification Investment | FAA and EASA airframe qualifications restrict supplier pools to Constellium SE and limited competitors, defending high-performance margins. |
Methodological Framework
The analysis maps automotive body-in-white sheet, battery separator foil, aerospace plate, and beverage can stock segments, each validated through rolling mill operations directors, automotive Tier 1 procurement managers, beverage multinational supply chain leads, and packaging converter technical directors. Primary fieldwork combined with secondary validation from customs trade data, SEC 10-K filings, LME warehouse stock reports, and OECD aluminium market statistics. Bottom-up capacity and demand modeling triangulated against top-down macroeconomic drivers.
Assumptions held fixed include NHTSA fuel economy rule stringency, EU carbon border adjustment mechanism phase-in schedules, and China MEE dual carbon enforcement intensity. Variables included LME primary aluminium price bands, battery electric vehicle penetration curves, and twin-roll casting technology adoption rates across regional mills. Segmentation modeling spanned product type, end-use industry, thickness gauge, and regional production cluster. CAGRs derived from rolling mill capacity expansion announcements, OEM platform aluminum content disclosures, and packaging demand elasticity estimates.
Stress conditions across Rhine water levels affecting barge freight, China export tax policy shifts, and automotive platform aluminum content reversals were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these assumptions and could revise with unanticipated regulatory acceleration or battery chemistry shifts displacing aluminium foil substrates. Cross-checking against IEA critical minerals demand projections and automotive industry aluminum content forecasts is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Global High Purity Titanium Powder Market
Metals
Global Ultra Fine Copper Powder Market
Metals
Electrolytic Iron Market
Metals
Aluminum Flat-Rolled Products Market
Metals
United States Aluminum Extrusion Market
Metals
Russia Metal Fabrication Market
Metals
Metal Coil Lamination Market
Metals
Global Aluminum Market
Metals
Tin Chloride Market
Metals
Metal Forging Parts Market
Metals
Japan Aluminium Powder Market
Metals
Aluminum Fluoride Market
Metals
North America Metal Casting Market
Metals
Aluminum Hot Rolling Mill Market
Metals
Asia-Pacific Metal Finishing Market
Metals
Bearing Steel Market