
 Galvanizing Market | 2026-2036
Galvanizing Market Size, Share, and Industry Trends Forecast 2026-2036
Galvanizing Market Analysis
Multi-source procurement among tier-one steel buyers is rebalancing toward vertically integrated mills with captive zinc supply. ArcelorMittal leverages its European hot-dip galvanizing network to secure long-term automotive contracts. POSCO Holdings anchors Asia-Pacific supply through integrated zinc coating lines at its Pohang complex. Nippon Steel Corporation differentiates via high-strength galvannealed grades for electric vehicle chassis applications.
Galvanizing applies a protective zinc layer to steel through hot-dip immersion or electroplating, typically achieving coating weights of 90–600 g/m² to prevent oxidative corrosion in structural and automotive environments. Hot-dip galvanizing dominates volume output due to its cost efficiency in construction and infrastructure applications, while galvannealed steel captures premium positioning in automotive body-in-white manufacturing where weldability and paint adhesion are critical. Alloy coatings represent the fastest-growing product category as OEMs specify zinc-aluminum-magnesium formulations for extended service life in coastal and industrial atmospheres.
REACH in Europe restricts hexavalent chromium in passivation treatments, forcing coating houses to adopt trivalent alternatives or silicate-based finishes. China's MEE enforces stricter effluent standards on galvanizing bath operations, raising compliance costs for smaller electroplaters. India's BIS certification mandates IS 277 compliance for galvanized steel sheets used in roofing and cladding. Stakeholders must monitor how carbon border adjustments and evolving alloy specifications reshape sourcing economics between integrated mills and independent coaters.
Market Dynamics
Automotive electrification is compressing traditional galvanizing specifications while expanding demand for ultra-high-strength coated steels in battery enclosure architectures, forcing coating houses to retool bath chemistry and annealing parameters.
Growth Catalysts
- India's PLI scheme for specialty steel:Production-linked incentives accelerate domestic galvanizing capacity for electrical equipment and automotive stampings, drawing fresh capital into Maharashtra and Gujarat coating clusters.
- Zinc-aluminum-magnesium alloy coatings:Extended corrosion resistance in coastal infrastructure projects drives specification upgrades across Middle Eastern desalination plants and Southeast Asian port facilities.
- REACH trivalent passivation mandates:European coating houses retrofit lines to eliminate hexavalent chromium, creating certified supplier premiums for construction and appliance OEMs sourcing compliant material.
Market Restraints
- Zinc price volatility:London Metal Exchange fluctuations compress independent coaters' margins when long-term construction contracts lock in fixed pricing.
- Supply concentration in zinc concentrate:Smelter network tightness in Peru and Australia constrains raw material security for non-integrated galvanizing operations.
- Aluminum substitution in lightweighting:EV manufacturers specify extruded aluminum battery trays and body panels, displacing galvanized steel in certain structural applications.
Strategic Opportunities
- Saudi Arabia's NEOM and Red Sea Project pipeline:Giga-scale coastal construction creates demand for 50+ year service-life coatings in corrosive marine atmospheres.
- Digital coating weight monitoring:Inline X-ray fluorescence systems enable real-time bath chemistry adjustment, reducing zinc consumption and reject rates simultaneously.
- Japan's METI carbon-neutral steel roadmap:Green hydrogen-reduced substrate compatibility with existing hot-dip lines opens premium positioning for early-adopting mills.
Industry Challenges
- Skilled bath operator scarcity:Experienced technicians who manage zinc bath temperature, aluminum content, and dross removal are retiring faster than training programs replace them.
- Dual certification complexity:Simultaneous compliance with automotive IATF standards and construction EN 1090 requirements strains quality management systems at multi-segment coaters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Galvanizing Market |
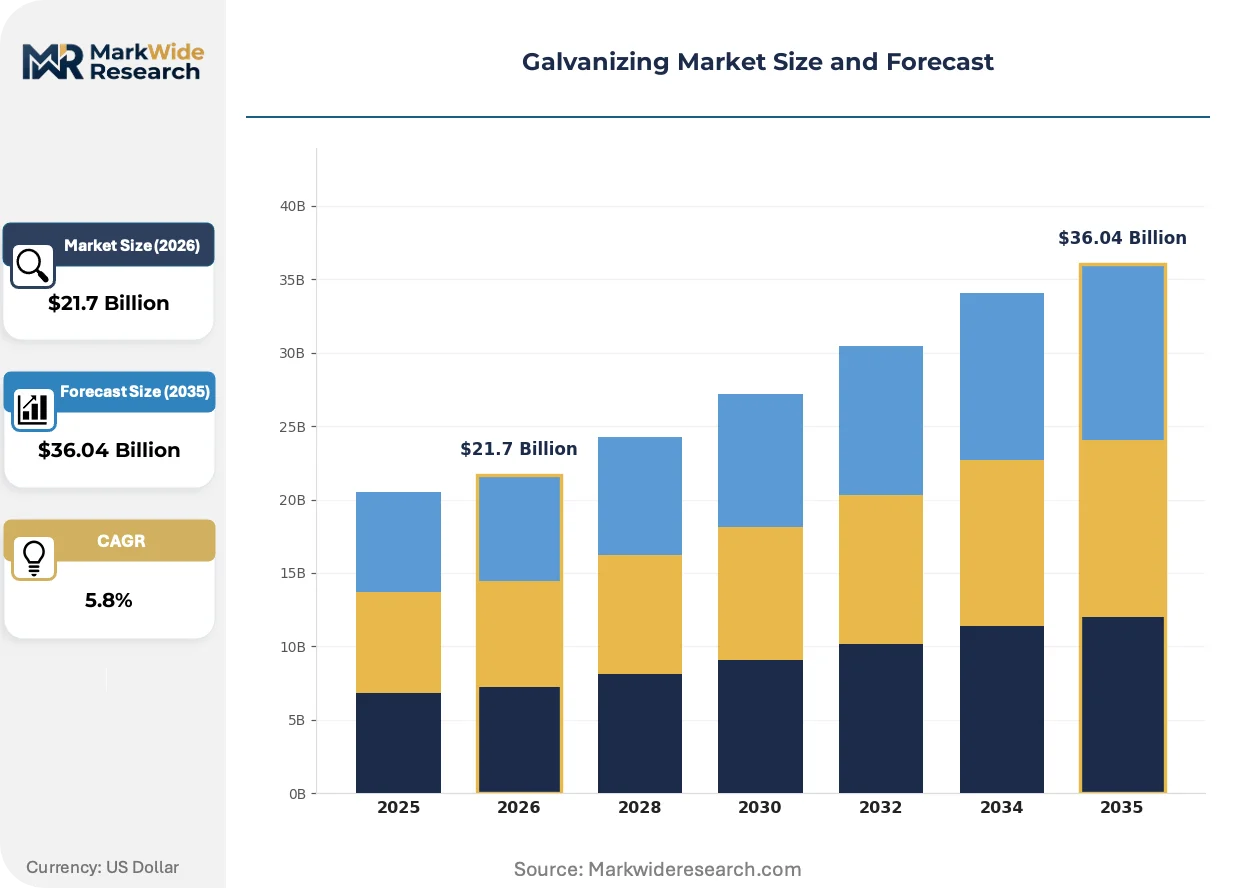
| Market Size in 2026 | $21.7 Billion |
| Market Size in 2035 | $36.04 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Zinc Coatings, Alloy Coatings, Galvannealed Steel, Hot-Dip Galvanizing End User: Construction, Automotive, Electrical, Manufacturing Application: Corrosion Protection, Building Structures, Automotive Components, Electrical Equipment Distribution Channel: Direct Sales, Distributors, Online Sales, Retail |
| Companies Covered | POSCO Holdings, JFE Steel Corporation, ArcelorMittal, Tata Steel, JSW Steel Limited, Nippon Steel Corporation, Steel Dynamics Inc., NLMK Group, thyssenkrupp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Galvanizing Market Emerging Trajectories
Coating technology convergence with digital process control is compressing specification variance while extending service-life guarantees, reshaping how mills compete on consistency rather than commodity volume.
Zinc-aluminum-magnesium coating formulations are unifying corrosion protection and cut-edge resistance in a single layer, eliminating post-galvanizing touch-up requirements. Automotive OEMs in Germany and Japan specify these alloys for underbody components exposed to road salt and stone impact. The technology is unifying previously separate pre-treatment and coating steps, reducing line footprint and energy intensity at integrated steelworks.
China's MEE effluent discharge standards now mandate closed-loop water systems and sludge recovery at galvanizing facilities, eliminating direct discharge to municipal treatment networks. Smaller electroplaters in the Yangtze and Pearl River deltas face six-figure retrofit costs or forced consolidation. High-volume construction coaters with captive waste processing capabilities capture market share from non-compliant independents.
Steel buyers now consolidate supplier panels around mills offering certified carbon footprints and alloy traceability through blockchain-linked mill test certificates. Tier-one automotive stampers in the US Midwest and northern Mexico disqualify coaters lacking Scope 3 emissions documentation. This behavior concentrates procurement among vertically integrated producers with in-house zinc smelting and renewable power purchase agreements.
Galvanizing Market Segmentation
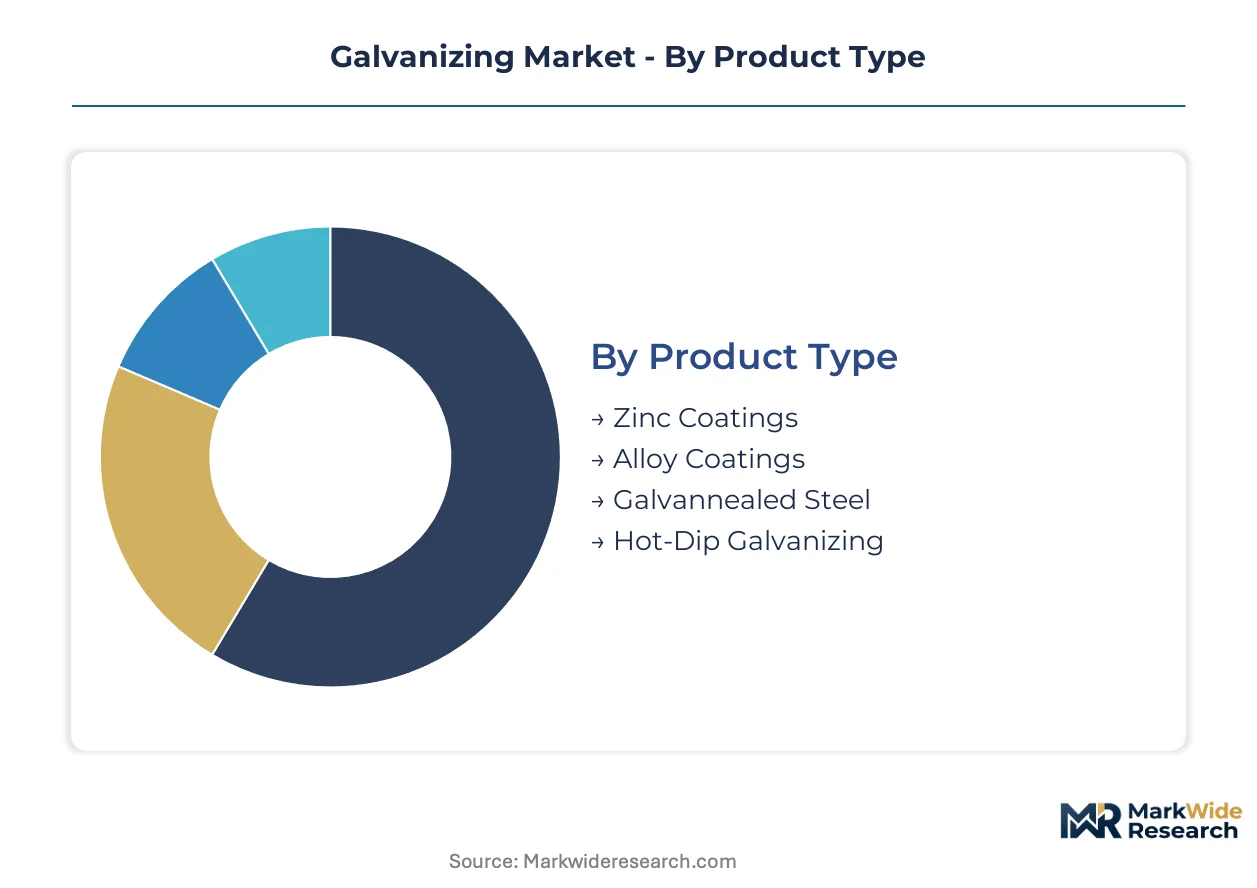
Segmentation in the galvanizing market reveals how coating specifications diverge across end-use durability requirements and procurement channel economics. Understanding these divisions exposes where margin pools concentrate and which technology investments align with demand trajectories.
Product Type:
Customization intensity spans from standardized commodity coatings to engineered alloy formulations with precise metallurgical controls.
- Hot-Dip Galvanizing:Immersion coating process deposits zinc layers of 90–600 g/m² through molten bath chemistry. Construction procurement in India's western industrial corridor and Gulf coastal infrastructure projects drives volume, though energy intensity at bath operations faces tightening MEE effluent standards in China.
- Alloy Coatings:Zinc-aluminum-magnesium formulations deliver 50+ year corrosion resistance in marine atmospheres through sacrificial protection and cut-edge healing. NEOM and Red Sea Project specifications in Saudi Arabia accelerate demand for these premium formulations over conventional zinc layers.
- Zinc Coatings:Baseline corrosion protection through pure zinc deposition dominates volume output in standard construction and appliance applications.
- Galvannealed Steel:Annealed zinc-iron intermetallic layers optimize weldability and paint adhesion for automotive body-in-white stampings.
Most installed capacity flows through Hot-Dip Galvanizing. Expansion is steepest in Alloy Coatings.
End User:
Margin structures diverge sharply between project-based construction procurement and contract-manufactured automotive supply.
- Construction:Infrastructure frameworks, roofing, and cladding specifications under IS 277 in India and EN 1090 in Europe demand certified coating weights. Saudi giga-projects and Southeast Asian port facilities specify extended-service-life alloys, compressing procurement cycles around qualified supplier panels.
- Automotive:Electric vehicle chassis architectures and battery enclosures require ultra-high-strength coated steels with precise annealing parameters. German and Japanese OEMs mandate galvannealed grades with documented carbon footprints through blockchain-linked mill test certificates.
- Electrical:Transformer housings, transmission towers, and cable management systems specify galvanized steel for grounding continuity and weather resistance.
- Manufacturing:General industrial equipment and appliance housings consume standard zinc coatings through distributor channels.
Construction channels the highest absolute tonnage. Automotive commands the steepest specification premiums.
Application:
Functional requirements separate atmospheric exposure applications from enclosed electrical environments with distinct corrosion mechanisms.
- Corrosion Protection:Atmospheric and marine exposure applications prioritize coating longevity over substrate mechanical properties. Coastal Middle Eastern desalination plants and Southeast Asian port facilities specify Zn-Al-Mg alloys for chloride resistance.
- Building Structures:Structural steel frameworks for commercial and industrial construction under India's PLI scheme for specialty steel accelerate domestic galvanizing capacity expansion in Maharashtra and Gujarat clusters.
- Automotive Components:Underbody stampings exposed to road salt and stone impact unify corrosion and mechanical performance requirements.
- Electrical Equipment:Enclosed transformer and switchgear housings prioritize uniform coating continuity for grounding performance over extreme atmospheric durability.
Building Structures absorbs the majority of coating volume. Corrosion Protection applications are climbing the fastest on alloy specification upgrades.
Distribution Channel:
Channel selection reflects order scale, specification complexity, and the buyer's technical assessment capability.
- Direct Sales:Tier-one automotive stampers and construction contractors with in-house metallurgical expertise negotiate long-term contracts with integrated mills. ArcelorMittal and POSCO Holdings anchor supply through direct relationships with certified carbon footprint documentation.
- Distributors:Regional stockists serve mid-scale construction and manufacturing buyers requiring rapid fulfillment of standard coating specifications.
- Online Sales:Digital platforms capture spot procurement for maintenance, repair, and small-project galvanized steel requirements.
- Retail:Hardware and building material outlets serve consumer and light commercial roofing and fencing applications.
Direct Sales channels the highest value per ton. Distributors maintain the broadest geographic coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The western industrial corridor of India concentrates the densest clustering of galvanizing capacity serving automotive and electrical equipment manufacturers. Regional demand trajectories diverge sharply between mature markets with tightening environmental compliance and emerging economies accelerating infrastructure deployment.
China
Coastal infrastructure frameworks and renewable energy installations drive sustained procurement of corrosion-resistant steel. The Ministry of Ecology and Environment enforces stricter effluent standards on galvanizing bath operations, raising compliance costs for smaller electroplaters. Yangtze River Delta coating facilities face six-figure retrofit investments or forced consolidation into compliant integrated mills.
India
Automotive stampers and electrical equipment manufacturers anchor demand across Maharashtra and Gujarat coating clusters. The Production-Linked Incentive scheme for specialty steel accelerates domestic galvanizing capacity expansion. JSW Steel and Tata Steel operate major facilities in the western industrial corridor serving tier-one manufacturing customers.
Germany
Automotive OEMs specify galvannealed grades with documented carbon footprints for electric vehicle chassis applications. REACH mandates trivalent passivation alternatives to hexavalent chromium, forcing coating houses to retrofit process lines. Ruhr Valley integrated mills capture certified supplier premiums from construction and appliance OEMs sourcing compliant material.
Japan
High-strength galvannealed grades for battery enclosure architectures command specification premiums from domestic automotive manufacturers. METI's carbon-neutral steel roadmap creates premium positioning for mills demonstrating green hydrogen-reduced substrate compatibility. Chubu region steelworks invest in inline coating weight monitoring systems to reduce zinc consumption.
Saudi Arabia
NEOM and Red Sea Project giga-scale coastal construction creates demand for extended service-life coatings in corrosive marine atmospheres. Zinc-aluminum-magnesium alloy specifications dominate procurement for 50-year durability requirements. Eastern Province desalination plants and port facilities drive specification upgrades over conventional zinc layers.
Galvanizing Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue alloy formulation specialization and carbon-certified supply chains. The vendor base concentrates around vertically integrated steel mills with captive zinc smelting and renewable power purchase agreements. Three archetypes dominate: integrated mills with in-house coating lines, independent coaters serving regional construction markets, and specialty alloy developers targeting automotive OEMs. Capacity expansion and strategic partnerships represent the dominant competitive moves as players secure long-term raw material security.
Within the integrated mill tier, POSCO Holdings anchors Asia-Pacific supply through its Pohang complex coating operations. ArcelorMittal exemplifies the European network archetype with hot-dip galvanizing lines serving automotive contract manufacturers. Nippon Steel Corporation occupies a position among high-strength coated steel specialists targeting electric vehicle chassis applications.
| Leading Market Players |
|---|
| POSCO Holdings |
| JFE Steel Corporation |
| ArcelorMittal |
| Tata Steel |
| JSW Steel Limited |
| Nippon Steel Corporation |
| Steel Dynamics Inc. |
| NLMK Group |
| thyssenkrupp |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap coaters in India's western industrial corridor anchor regional pricing discipline through captive zinc sourcing from long-standing smelter relationships, insulating project quotes from London Metal Exchange volatility while integrated mills extract premiums through certified carbon documentation.
Pricing Analysis
Input-cost pass-through from zinc concentrate smelter networks determines baseline coating tariffs, with London Metal Exchange fluctuations compressing independent coaters' margins when fixed-price construction contracts lock in quarterly rates. Price differentiation hinges on certification tier—REACH-compliant trivalent passivation commands 15-20 point premiums over hexavalent alternatives—and volume scale, with automotive OEMs negotiating multi-year offtakes below spot-indexed construction procurement. Pricing pressure stems from aluminum substitution in EV battery tray applications, eroding galvanized steel's share in structural lightweighting. Tier-one automotive stampers exhibit lowest price sensitivity, prioritizing documented Scope 3 emissions and alloy traceability over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from automotive contract manufacturers and giga-project construction consortia, while regional distributors serve mid-scale fabrication shops requiring rapid standard-specification fulfillment. Geographic supply concentrates in China, India, and South Korea, with Pohang and Yangtze River Delta complexes anchoring Asia-Pacific coating capacity. Raw material dependencies center on zinc concentrate from Peruvian and Australian smelter networks, aluminum alloying additions, and natural gas for bath heating. Single-source vulnerability in zinc concentrate supply creates exposure to smelter maintenance outages and export restriction risks. Distribution runs through vertically integrated mill-direct relationships for certified grades, with independent coaters relying on spot zinc purchases and regional distributor networks for construction volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as procurement panels consolidate around mills offering blockchain-linked carbon documentation and Zn-Al-Mg alloy certifications for 50-year coastal service life.
For Market Incumbents: Lock in automotive OEM relationships through long-term galvannealed supply agreements with embedded Scope 3 emissions tracking, while retrofitting bath lines for trivalent passivation ahead of REACH enforcement deadlines. Prioritize backward integration into zinc smelting or captive renewable power purchase agreements to defend margin position against London Metal Exchange volatility and MEE effluent compliance cost inflation. For New Entrants and Emerging Players: Regional electrical equipment fabricators in India's Maharashtra and Gujarat clusters present the most penetrable buyer archetype, underserved by certified high-coating-weight suppliers for transmission tower and transformer housing specifications. Target this segment through BIS IS 277 compliance investment and rapid-turnaround distributor partnerships, avoiding direct competition with integrated mills for automotive galvannealed contracts. For Investors and Strategic Acquirers: Valuations sit cheapest among independent coaters with stranded hexavalent passivation assets facing MEE or REACH retrofit burdens, creating distressed entry points for operational turnaround specialists. Long-term viability favors facilities with closed-loop water systems, sludge recovery capabilities, and renewable power sourcing. Monitor zinc-aluminum-magnesium alloy specification penetration in Saudi giga-projects and Southeast Asian port facilities as the inflection signal for premium coating demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Zinc Smelting | Captive concentrate supply insulates margin from London Metal Exchange volatility and Peruvian export restrictions. |
| Trivalent Passivation Line Retrofit | REACH compliance certification unlocks automotive and appliance OEM procurement panels in Ruhr Valley manufacturing clusters. |
| Zn-Al-Mg Alloy Capacity Addition | NEOM and Red Sea Project specifications for 50-year marine service life drive specification upgrades over conventional zinc. |
| Blockchain-Linked Mill Test Certificates | Carbon footprint documentation satisfies tier-one automotive stamper Scope 3 disclosure requirements in Germany and Japan. |
| Closed-Loop Water System Installation | MEE effluent compliance preserves operating licenses for Yangtze River Delta coating facilities facing consolidation pressure. |
Methodological Framework
Direct dialogue with coating line operations managers, automotive Tier 1 procurement directors, construction contractor metallurgical engineers, and MEE regional enforcement officers grounded qualitative assessment of bath chemistry trends and compliance cost structures. Secondary validation drew from customs trade data for zinc concentrate flows, BIS certification registries, SEC 10-K filings from listed steel producers, and REACH substance restriction notifications. Bottom-up capacity modeling across India's western industrial corridor and China's Yangtze and Pearl River deltas triangulated against top-down construction spending and automotive production forecasts.
Segment-level value outputs across the projection horizon reflect disaggregated modeling by coating technology type, end-use durability requirement, and procurement channel economics. The analytical framework applied regression-based intensity factors linking infrastructure investment and vehicle production to galvanized steel consumption, with CAGRs derived from curve-fitting historical coating weight growth against macroeconomic drivers. Industry-specific inputs included zinc price volatility regimes, alloy specification adoption curves in coastal construction, and regulatory compliance cost trajectories under MEE and REACH frameworks.
Underlying measurement precision varies by segment; automotive galvannealed specifications carry tighter precision than commodity construction coatings due to documented OEM contract volumes and IATF quality management system audits. Forecasts reflect assumptions regarding zinc concentrate smelter capacity expansion, dual carbon policy enforcement intensity in China, and EV platform architecture decisions affecting steel-aluminum material selection. Periodic stress-testing of base assumptions against London Metal Exchange price shocks and regulatory timeline accelerations is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Global Flat Steel Market
Metals
High Magnetic Induction Grain-Oriented Silicon Steel Market
Metals
Zinc Plating Market
Metals
Molybdenum Market
Metals
Copper Foil Market
Metals
Copper Chromium Black Market
Metals
Lanthanum Market
Metals
Europe Welding Consumables Market
Metals
India Metal Fabrication Market
Metals
Europe Aluminium Cans Market
Metals
Global Duplex Stainless Steel Market
Metals
Aluminium Rolled Products Market
Metals
Steel Wire Market
Metals
Silver Sulphate Market
Metals
Colloidal Metal Particles Market
Metals
Brazing Strips Market