
 Methyl Gluceth-10 Market | 2026-2036
Methyl Gluceth-10 Market Size, Share, and Industry Trends Forecast 2026-2036
Methyl Gluceth-10 Market Analytics
ISO 16128 natural origin certification is bifurcating supplier eligibility between established glucose-derivative producers and commodity chemical traders. BASF SE leverages its integrated carbohydrate feedstock chain to sustain cost-advantaged methyl gluceth-10 output. Croda International Plc anchors its position through specialty esterification expertise in personal care actives. Evonik Industries AG competes on pharmaceutical-grade purity thresholds that exceed cosmetic specifications.
Methyl gluceth-10 is a methyl glucoside polyether, typically ethoxylated with ten moles of ethylene oxide, yielding a water-soluble humectant with HLB values around 16-17 and reduced skin-irritation potential compared to conventional glycols. Manufacturers produce it through acid-catalyzed glycosidation of glucose followed by base-catalyzed ethoxylation, then purify for residual ethylene oxide limits below 1 ppm for cosmetic use. The end use industry segment shows cosmetics and personal care commanding the largest volume share, while pharmaceutical-grade material captures disproportionate margin pools due to USP monograph compliance costs. Formulation preferences are shifting toward emulsions and serums where methyl gluceth-10 functions as both humectant and co-emulsifier, displacing simpler polyols in premium positioning.
REACH registration through ECHA governs ethoxylated surfactant imports into Europe, while FDA cosmetic ingredient regulations and EPA residual ethylene oxide limits shape US market access requirements. BIS certification for cosmetic raw materials affects Indian import channels, with CDSCO pharmaceutical excipient standards adding a second compliance layer for drug applications. Stakeholders must monitor evolving natural-origin certification thresholds and regional ethylene oxide residue limits as these standards increasingly determine supplier qualification and customer switching costs.
Market Dynamics
ISO 16128 natural origin standards are bifurcating supplier eligibility, forcing glucose-derivative producers to prove feedstock provenance while commodity traders lose qualification access to premium cosmetic channels.
Growth Catalysts
- REACH ethoxylate registration:ECHA compliance requirements for residual ethylene oxide limits below 1 ppm are consolidating import channels toward qualified European manufacturers with established dossiers.
- Serum and emulsion formulation shifts:Personal care brands are specifying methyl gluceth-10 as dual-function humectant-co-emulsifier in water-light textures that command premium positioning.
- Pharmaceutical excipient grade expansion:USP monograph compliance for parenteral and topical drug delivery is opening higher-margin adjacent demand beyond cosmetic applications.
Market Restraints
- Ethylene oxide feedstock volatility:Petrochemical-derived ethylene oxide pricing swings directly compress ethoxylation margins for non-integrated producers lacking captive ethylene supply.
- Carbohydrate feedstock concentration:Corn and wheat glucose supply chains cluster in North American and Black Sea agricultural belts, exposing processors to regional harvest variability and trade policy friction.
- Glycol substitution threat:Propylene glycol and butylene glycol maintain cost advantages in mass-market formulations where natural-origin certification carries no price premium.
Strategic Opportunities
- Indian BIS certification gap:Domestic cosmetic raw material standards remain underdeveloped versus European REACH equivalents, creating first-mover advantage for pre-qualified importers serving local contract manufacturers.
- Biotechnology glucose feedstocks:Cellulosic and enzymatic glucose production from agricultural waste streams are converging with cosmetic natural-origin thresholds, potentially decoupling supply from food-competing carbohydrates.
- Direct-to-brand distribution:Indie beauty brands and clean-label startups are bypassing traditional distributor networks, creating channel access for specialty chemical suppliers with formulation technical service capabilities.
Industry Challenges
- Ethoxylated surfactant toxicology expertise:Regulatory affairs functions capable of navigating ECHA dossier maintenance and 1,4-dioxane impurity management are scarce relative to compliance workload expansion.
- Multi-standard certification timelines:Simultaneous pursuit of ISO 16128 natural origin, COSMOS organic, and USP pharmaceutical grades extends qualification cycles and strains analytical laboratory capacity.
- Legacy glycol formulation lock-in:Established personal care brands face reformulation cost and consumer perception risk when replacing incumbent humectants with methyl gluceth-10 in heritage product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Methyl Gluceth-10 Market |
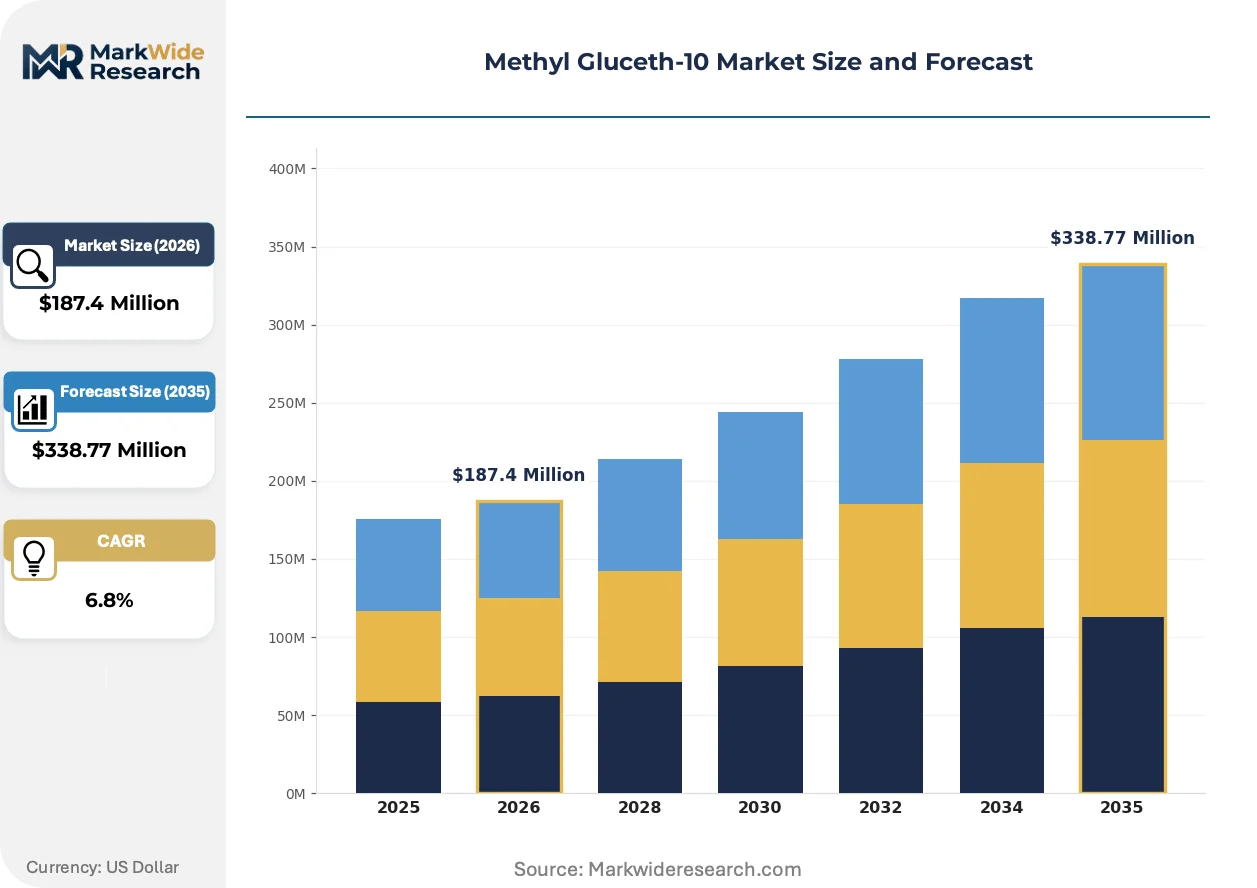
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Creams, Lotions, Gels, Serums End Use Industry: Cosmetics, Personal Care, Pharmaceuticals, Food Formulation: Emulsions, Solutions, Suspensions, Powders Packaging Type: Tubes, Jars, Bottles, Sachets |
| Companies Covered | BASF SE, Croda International Plc, Clariant AG, Dow Chemical Company, Ashland Global Holdings Inc., Lubrizol Corporation, Evonik Industries AG, Stepan Company, Kao Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Methyl Gluceth-10 Market Evolving Landscape
Formulation science and procurement behavior are diverging from conventional polyol specifications toward performance-validated, certification-backed ingredient selection that rewards technical differentiation over commodity supply.
Next-generation ethoxylation catalysts with narrower polydispersity are yielding methyl gluceth-10 with tighter molecular weight distribution and enhanced skin-feel profiles. Premium skincare brands in Germany and France are specifying these grades for sensorial differentiation in facial serums. The technology is displacing conventional acid-catalyzed ethoxylation in high-margin cosmetic applications where batch-to-batch consistency commands price premiums.
EU F-Gas Regulation phase-down schedules are indirectly pressuring ethylene oxide production energy intensity, as steam crackers face carbon cost exposure and renewable power integration requirements. Ethoxylated surfactant manufacturers serving European cosmetic markets are responding with Scope 3 emissions disclosure and renewable energy certificates to maintain ECHA registration competitiveness. Pharmaceutical-grade producers with existing carbon footprint documentation capture disproportionate qualification advantage under emerging CSRD supply chain reporting mandates.
Ingredient procurement teams at multinational personal care brands are consolidating supplier panels from twelve-plus vendors to three-to-four strategic partners with integrated technical service. This concentration is compressing spot-market opportunities for commodity traders while rewarding manufacturers with in-house formulation laboratories and regulatory dossier depth. The shift is most pronounced in UK and Nordic markets where clean beauty positioning and supply chain transparency expectations converge.
Methyl Gluceth-10 Market Segmentation
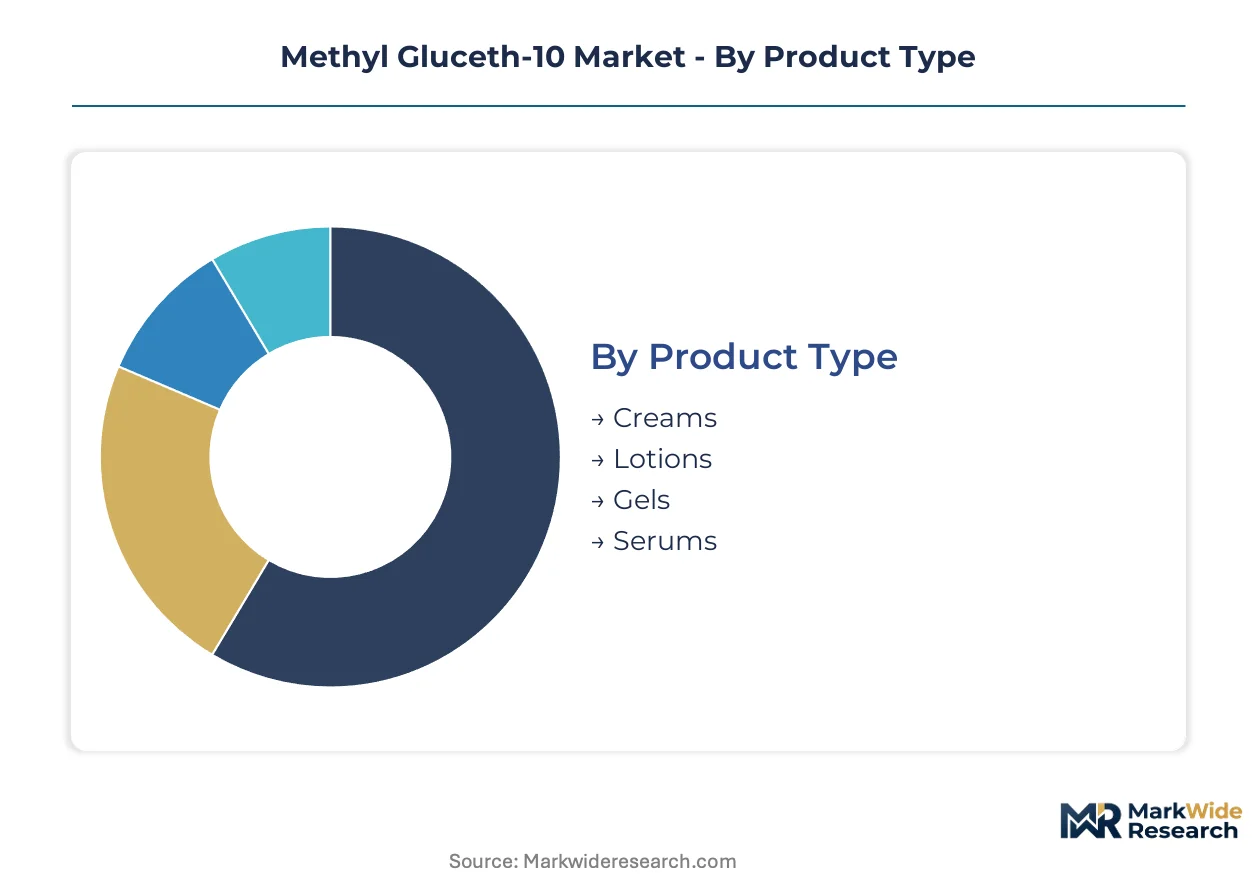
Methyl gluceth-10 formulation specifications diverge sharply across distribution channels. Specialty chemical distributors stock pharmaceutical-grade material with dossier depth, while commodity traders push cosmetic-grade volumes through bulk tanker channels.
Product Type:
Channel concentration varies by viscosity and stability requirements. High-viscosity formats flow through contract manufacturing networks, while water-light textures bypass traditional distribution.
- Serums:Low-viscosity, water-dominant matrices exploit methyl gluceth-10's dual humectant-co-emulsifier functionality. Demand concentrates in German and French premium skincare brands pursuing sensorial differentiation through rapid skin penetration. ISO 16128 natural-origin certification gates access to clean-label channels.
- Creams:Oil-in-water emulsions leverage the ingredient's HLB 16-17 profile for stable lamellar structures. UK and Nordic markets show concentration as heritage brands reformulate heritage lines for natural-origin positioning. Reformulation cost and consumer perception risk constrain switching velocity.
- Lotions:Intermediate viscosity formats balance spreadability with occlusive film formation.
- Gels:Carbomer-thickened systems exploit water-binding capacity without tackiness.
By volume, creams lead. By growth pace, serums are climbing the fastest.
End Use Industry:
Margin tiering separates certification-intensive segments from specification-tolerant commodity applications.
- Cosmetics:Facial skincare and color cosmetics demand ISO 16128-compliant grades with documented glucose feedstock provenance. Germany, France, and the United Kingdom concentrate procurement as clean beauty positioning hardens. ECHA REACH registration and residual ethylene oxide limits below 1 ppm consolidate supplier panels.
- Pharmaceuticals:USP monograph compliance for parenteral and topical delivery commands qualification timelines extending 18-24 months. CDSCO excipient standards in India add secondary compliance layers for drug applications. Carbon footprint documentation under emerging CSRD mandates captures disproportionate advantage.
- Personal Care:Hair care and body wash applications tolerate broader specification ranges.
- Food:Limited use as processing aid in flavor encapsulation systems.
By revenue contribution, cosmetics dominates. By margin expansion, pharmaceuticals shows the steepest trajectory.
Formulation:
Processing complexity determines equipment investment and batch validation requirements across manufacturing footprints.
- Emulsions:Oil-water interfaces exploit methyl gluceth-10's surfactant properties for reduced co-emulsifier loading. Demand clusters in contract manufacturers serving indie beauty brands with rapid formulation turnaround. Next-generation ethoxylation catalysts with narrower polydispersity yield premium grades for sensorial differentiation.
- Solutions:Clear aqueous systems require low-color, low-odor specifications with tight residual ethylene oxide control. Pharmaceutical-grade producers in Europe capture volume as parenteral compatibility testing extends qualification cycles. 1,4-dioxane impurity management separates qualified from commodity supply.
- Suspensions:Insoluble active delivery systems leverage viscosity modification without phase separation.
- Powders:Spray-dried formats for solid dosage and dry shampoo applications.
By installed base, emulsions holds the largest share. By technical upgrade frequency, solutions is gaining share fastest.
Packaging Type:
Fill-finish automation compatibility and shelf-life stability requirements shape procurement specifications.
- Bottles:PET and glass formats for serum and lotion applications with pump or dropper closures. German and French brands specify airless systems to prevent oxidation of natural-origin actives. Direct-to-brand distribution channels bypass traditional distributor markups for volume commitments.
- Tubes:Laminate and aluminum formats for creams and gels with controlled rheology. UK contract manufacturers consolidate supplier panels from twelve-plus vendors to three-to-four strategic partners with integrated technical service.
- Jars:Wide-mouth containers for high-viscosity cream formats.
- Sachets:Single-use foil pouches for sampling and travel retail.
By unit volume, tubes leads. By premium positioning velocity, bottles is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical tanker terminals anchor European ethoxylated surfactant distribution, while the Rhine corridor feeds glucose derivative processors into Germany's personal care manufacturing belt. This infrastructure underwrites methyl gluceth-10 supply security for formulation houses serving premium cosmetic brands.
Germany
Facial serum demand from Berlin and Hamburg indie beauty brands drives specification tightening for HLB 16-17 grades. ECHA REACH registration dossiers for residual ethylene oxide below 1 ppm consolidate supplier access to clean-label channels. The North Rhine-Westphalia cluster around Düsseldorf concentrates contract manufacturers reformulating heritage cream lines for ISO 16128 compliance.
France
Paris-based luxury skincare houses specify next-generation ethoxylation catalyst grades for sensorial differentiation in water-light textures. ANSM cosmetic ingredient oversight intersects with EU F-Gas Regulation carbon cost exposure for ethylene oxide crackers. The Lyon chemical corridor hosts pharmaceutical-grade producers capturing CSRD supply chain reporting advantages.
United Kingdom
London and Southeast England procurement teams consolidate supplier panels from twelve-plus vendors to three-to-four strategic partners with integrated technical service. UK REACH divergence from EU REACH creates parallel registration burdens for ethoxylated surfactant importers. Manchester contract manufacturers serve Nordic clean beauty brands demanding Scope 3 emissions disclosure.
India
Mumbai and Pune personal care contract manufacturers expand methyl gluceth-10 use in affordable serum formats for domestic middle-class consumers. BIS cosmetic raw material standards remain underdeveloped versus European equivalents, creating first-mover advantage for pre-qualified importers. CDSCO pharmaceutical excipient standards add compliance layers for drug applications targeting export markets.
United States
New Jersey and Pennsylvania pharmaceutical excipient demand for parenteral delivery systems commands USP monograph compliance timelines extending 18-24 months. FDA cosmetic ingredient regulations and EPA residual ethylene oxide limits shape market access requirements. The Gulf Coast ethylene oxide production corridor exposes non-integrated processors to petrochemical feedstock volatility.
Methyl Gluceth-10 Market Competitive Landscape
Listed leaders compete with private specialists across certification depth and feedstock integration. The vendor base concentrates around three-to-four strategic partners per major procurement region, compressing spot-market opportunities for commodity traders. Strategic archetypes separate integrated glucose-derivative producers, specialty esterification houses, and pharmaceutical-grade purity specialists. Dominant competitive moves include backward integration into carbohydrate feedstocks and geographic expansion through direct-to-brand distribution channels bypassing traditional distributor markups.
Within the integrated producer tier, BASF SE and Croda International Plc exemplify divergent strategic positions. BASF anchors cost-advantaged output through captive carbohydrate supply chains. Croda occupies a specialty position through esterification expertise in personal care actives. Evonik Industries AG represents the pharmaceutical-grade purity archetype, competing on thresholds exceeding cosmetic specifications. These three entities collectively illustrate how feedstock control, formulation technical service, and regulatory dossier depth separate qualified suppliers from commodity traders losing access to premium channels.
| Leading Market Players |
|---|
| BASF SE |
| Croda International Plc |
| Clariant AG |
| Dow Chemical Company |
| Ashland Global Holdings Inc. |
| Lubrizol Corporation |
| Evonik Industries AG |
| Stepan Company |
| Kao Corporation |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between glucose-derivative producers and ethoxylation specialists lock in both supply access and price visibility across the analysis window. BASF SE and Croda International Plc leverage these structures to buffer European formulators against ethylene oxide feedstock volatility while securing ISO 16128-qualified volumes for premium cosmetic channels.
Pricing Analysis
Certification level creates the primary spread between pharmaceutical-grade USP monograph material and cosmetic-grade ISO 16128-compliant supply. Three-tier pricing structure across premium, standard, and economy levels separates qualified dossier holders from commodity traders, with carbon footprint documentation under CSRD mandates capturing additional premium capture. Cost compression in standard cosmetic grades is intensifying because propylene glycol substitution threats constrain pass-through power for non-integrated producers. Mass-market personal care brands exhibit highest price sensitivity, while pharmaceutical excipient buyers tolerate extended qualification timelines for assured purity thresholds.
Supply Chain Analysis
Inventory positions at Rotterdam chemical tanker terminals currently run six-to-eight weeks leaner than historical averages for ethoxylated surfactant feedstocks. Supply concentrates in Germany, France, and the United States for qualified methyl gluceth-10 production, with glucose feedstocks drawing from North American and Black Sea agricultural belts. Ethylene oxide, carbohydrate derivatives, and catalytic ethoxylation reagents constitute the critical input trinity. Single-source vulnerability runs through the Rhine corridor logistics chokepoint connecting glucose processors to ethoxylation capacity. Distribution runs through specialty chemical distributors with dossier depth for pharmaceutical channels, while cosmetic-grade volumes bypass traditional markups via direct-to-brand arrangements with indie beauty startups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as multinational personal care brands consolidate supplier panels from twelve-plus vendors to three-to-four strategic partners, fragmenting spot-market access for commodity traders while rewarding integrated technical service providers.
For Market Incumbents: Secure backward integration into carbohydrate feedstocks to defend margin position against ethylene oxide volatility and propylene glycol substitution threats. Deepen ECHA REACH dossier maintenance capabilities to exploit regulatory affairs scarcity as compliance workload expands across residual ethylene oxide and 1,4-dioxane impurity management. For New Entrants and Emerging Players: Differentiate on biotechnology glucose feedstocks from agricultural waste streams to meet emerging natural-origin thresholds without food-competing carbohydrate exposure. Target Indian contract manufacturers in Mumbai and Pune as the most penetrable geography given underdeveloped BIS standards versus European equivalents, deploying direct-to-brand technical service capabilities to bypass legacy distributor networks. For Investors and Strategic Acquirers: The market sits at a certification-intensification phase that favors pharmaceutical-grade purity specialists with existing USP monograph compliance and carbon footprint documentation. Long-term viability over the next decade hinges on decoupling from petrochemical ethylene oxide through cellulosic glucose innovation and renewable energy integration. Watch ECHA 1,4-dioxane impurity threshold revisions as the signal for accelerated supplier consolidation and qualification cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbohydrate Feedstocks | BASF SE's captive glucose supply chains neutralize Black Sea harvest variability and trade policy friction. |
| Pharmaceutical-Grade USP Monograph Investment | Evonik Industries AG captures disproportionate margin pools through parenteral compatibility qualification timelines. |
| Direct-to-Brand Distribution Channel Development | Specialty esterification houses bypass twelve-point distributor markups to serve Berlin and Hamburg indie beauty brands. |
| Next-Generation Ethoxylation Catalyst Deployment | Narrower polydispersity grades command sensorial premiums in Paris-based luxury skincare water-light textures. |
| CSRD Supply Chain Carbon Documentation | Pharmaceutical-grade producers with Scope 3 disclosure capture qualification advantage under emerging EU mandates. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with personal care formulators, pharmaceutical excipient procurement leads, ethoxylation plant managers, and regulatory affairs specialists at ECHA-registered entities. Secondary validation drew from ECHA REACH registration dossiers, FDA cosmetic ingredient guidance documents, customs trade data for ethoxylated surfactant flows, and SEC 10-K filings of listed chemical producers. Bottom-up volume triangulation across serum, cream, and lotion formulation specifications converged with top-down value estimates from pharmaceutical-grade margin tiering.
Across the analysis window, the forecasting framework modeled grade tier segmentation separating cosmetic ISO 16128-compliant material from pharmaceutical USP monograph supply, end-use industry divergence between personal care and drug delivery applications, and regional production hub concentration in the North Rhine-Westphalia and Lyon chemical corridors. CAGRs were derived from ethoxylation capacity expansion announcements, glucose feedstock cost curve trajectories, and formulation substitution elasticity estimates for glycol displacement in premium positioning channels.
Material uncertainties — ethylene oxide feedstock volatility, EU F-Gas Regulation carbon cost exposure, and 1,4-dioxane impurity threshold revisions — sit outside the modeled envelope. Forecasts reflect assumptions about certification timeline stability and natural-origin standard convergence. Revision becomes warranted when biotechnology glucose cost parity crosses thresholds that trigger accelerated feedstock switching.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Ferrous Oxalate Market
Bulk Chemicals
Global Basic Chemicals Market
Bulk Chemicals
Global Acrylate Monomers Market
Bulk Chemicals
Global Lithium Derivatives Market
Bulk Chemicals
North America Hydrochloric Acid Market
Bulk Chemicals
Europe Titanium Dioxide Market
Bulk Chemicals
Asia-Pacific Quicklime Market
Bulk Chemicals
Muconic Acid Market
Bulk Chemicals
Sulfamic Acid Market
Bulk Chemicals
Electronic Batio3 Powder Market
Bulk Chemicals
Brassylic Acid Market
Bulk Chemicals
Isoprene Monomer Market
Bulk Chemicals
Tertiary Butylhydroquinone Market
Bulk Chemicals
Furfural Derivatives Market
Bulk Chemicals
Europe Lithium Chloride Market
Bulk Chemicals
Castor Wax Market