
 Global High Purity Titanium Powder Market | 2026-2036
Global High Purity Titanium Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Global High Purity Titanium Powder Market Analysis
Titanium is broadening its displacement of nickel-based superalloys in turbine blade and combustion chamber applications, reducing component weight while maintaining creep resistance at elevated temperatures. OSAKA Titanium Technologies leverages captive sponge-to-powder integration to secure feedstock consistency for semiconductor sputtering targets. Toho Titanium anchors Japan's domestic aerospace supply chain through long-term offtake agreements with engine OEMs. AP&C specializes in plasma atomization systems that produce spherical powder morphologies optimized for electron beam melting processes.
High purity titanium powder denotes refined titanium metal with purity grades from 4N through 7N, produced via hydride-dehydride, gas atomization, or plasma rotating electrode processes yielding controlled particle size distributions between 15 and 150 micrometers. The material serves primarily as feedstock for additive manufacturing, physical vapor deposition targets, and biomedical implants requiring biocompatibility certification. Aerospace applications dominate volume consumption, though medical grade 5N and 6N powders command premium pricing due to batch-level impurity documentation requirements. Powder form factors lead granular and flake alternatives in additive manufacturing uptake, while pelletized feedstock retains relevance in chemical vapor deposition systems.
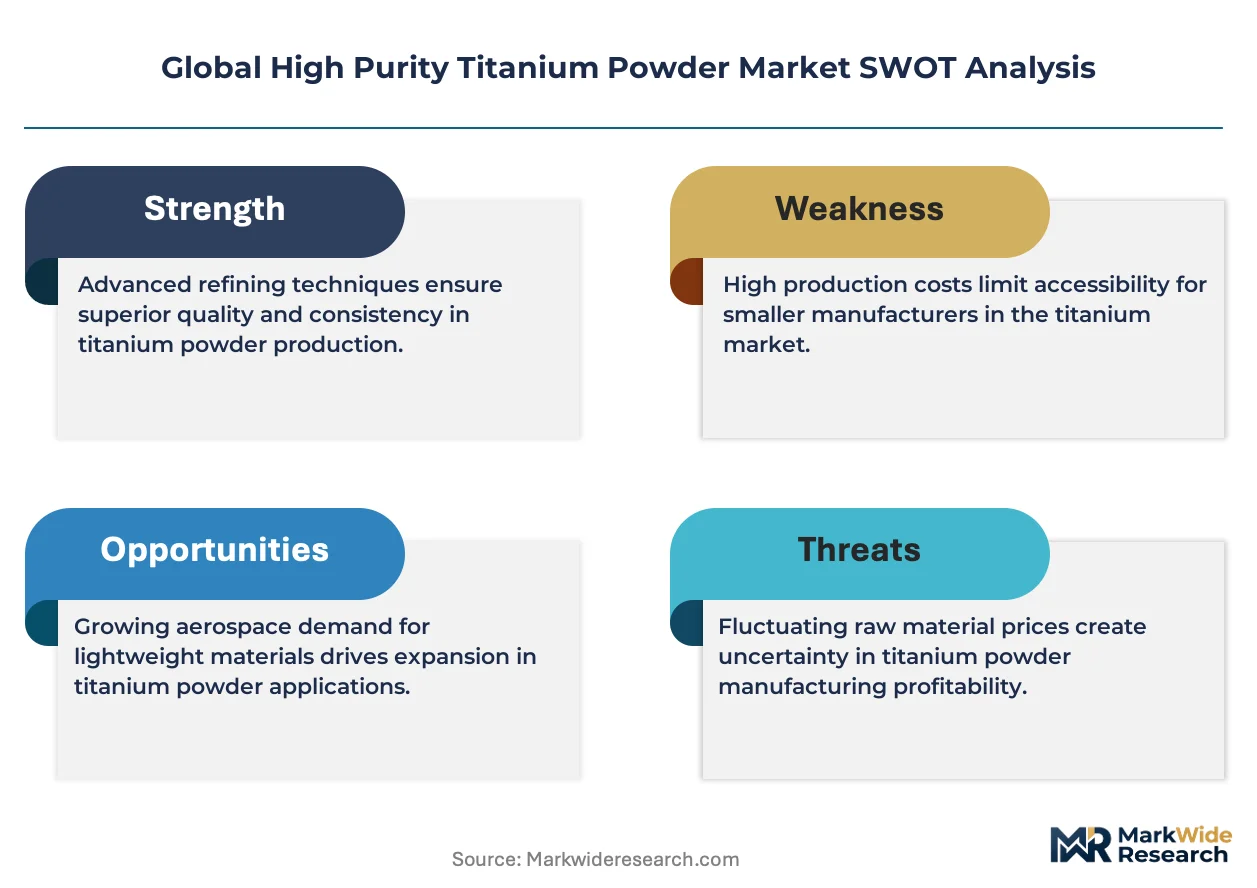
FDA 21 CFR Part 820 quality system regulations govern medical device manufacturers sourcing implant-grade titanium powder, mandating supplier qualification protocols that elevate barrier-to-entry for non-ISO 13485 certified producers. REACH registration and RoHS substance restrictions within Europe compel full material disclosure across titanium supply chains, favoring producers with in-house analytical laboratories capable of generating extended safety data sheets. ECHA's evolving nanoform classification criteria may reclassify ultrafine titanium powder fractions, triggering additional hazard communication obligations. Stakeholders must evaluate certification breadth against end-user qualification timelines, as dual-use aerospace-medical producers face overlapping but non-identical audit requirements that strain quality management resources.
Market Dynamics
Aerospace additive manufacturing is consolidating titanium powder demand around plasma atomization technologies that guarantee spherical particle morphology for electron beam melting processes.
Growth Catalysts
- EU F-Gas Regulation:Tightening material traceability standards compel European suppliers to upgrade analytical capabilities, filtering out non-compliant producers and tightening supply-side discipline.
- Semiconductor sputtering targets:Japanese electronics manufacturers source captive sponge-to-powder supply chains for 5N and 6N purity grades used in physical vapor deposition systems.
- Gas atomization:This production method yields controlled particle size distributions between 15 and 150 micrometers, enabling direct feedstock qualification for laser powder bed fusion equipment without secondary sizing.
Market Restraints
- Titanium sponge concentration:Feedstock supply clusters in Japan and Ukraine, exposing downstream powder producers to geopolitical disruption and transport bottlenecks.
- REACH nanoform classification:ECHA's evolving criteria for ultrafine titanium powder fractions threaten to trigger additional hazard communication obligations and extended safety data sheet requirements.
- Nickel-based superalloy substitution ceiling:Creep resistance requirements in the hottest turbine sections limit titanium displacement despite weight advantages in cooler compressor stages.
Strategic Opportunities
- India's PLI scheme:Production-linked incentives for aerospace and defense manufacturing create localized demand for certified titanium powder feedstock serving domestic additive manufacturing facilities.
- Biomedical implant grade expansion:FDA 21 CFR Part 820 quality system regulations elevate barrier-to-entry for non-ISO 13485 certified producers, concentrating margin in qualified supply chains.
- Hydride-dehydride process optimization:Convergence with in-line spectroscopic monitoring enables real-time purity verification, compressing batch release timelines for medical device manufacturers.
Industry Challenges
- Dual-use audit fatigue:Producers serving both aerospace and medical end-uses face overlapping but non-identical ISO 9001 and ISO 13485 requirements that strain quality management resources.
- Plasma atomization capex intensity:Inert gas recirculation systems and electrode maintenance infrastructure demand sustained capital deployment before achieving economies of scale.
- RoHS substance disclosure:Full material certification across extended supply chains requires in-house analytical laboratories capable of generating documentation for every batch.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global High Purity Titanium Powder Market |
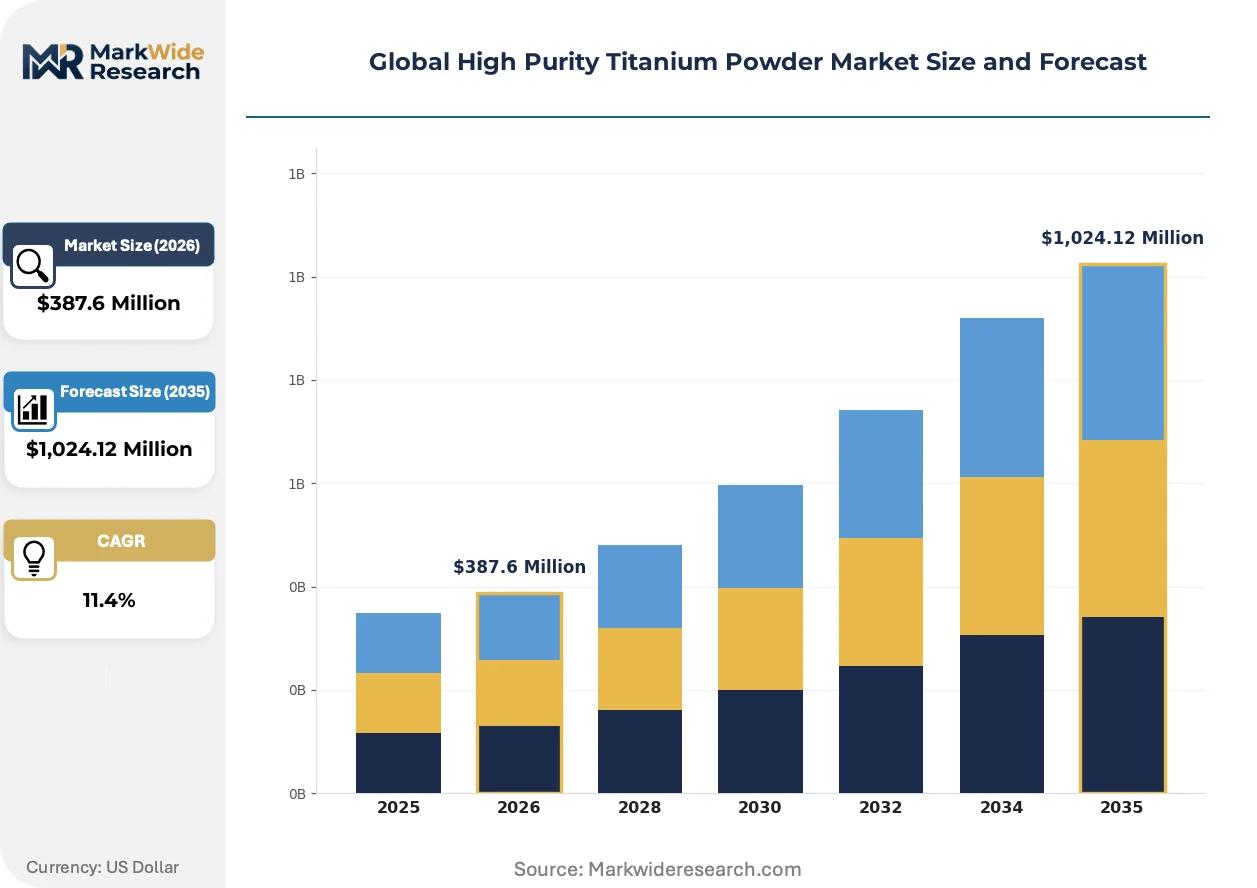
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,024.12 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 7N, 6N, 5N, 4N Application: Aerospace, Medical, Electronics, Automotive Form: Powder, Granule, Flake, Pellet End User: Aerospace Manufacturers, Healthcare Providers, Electronics Firms, Automotive Suppliers |
| Companies Covered | OSAKA Titanium Technologies, Toho Titanium, AP&C, ADMA Products, Global Titanium, Sandvik, Tekna, 6K Additive, IperionX, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global High Purity Titanium Powder Market Emerging Trajectories
Plasma atomization systems are compressing the qualification timeline for additive manufacturing feedstock by delivering inherently spherical morphologies that reduce post-processing requirements.
Plasma rotating electrode process technology is unifying aerospace and medical powder specifications by producing identical particle geometries across 4N through 6N purity grades. Engine OEMs and implant manufacturers now source from common production lines, collapsing the historical separation between these qualification regimes. This convergence is unifying supplier audit protocols and reducing duplicate certification costs for dual-use producers.
REACH registration and RoHS substance restrictions within Europe compel full material disclosure across titanium supply chains. ECHA's evolving nanoform classification criteria threaten to reclassify ultrafine powder fractions, triggering additional hazard communication obligations. Medical device manufacturers in Germany and France are responding by consolidating procurement around producers with captive analytical laboratories capable of generating extended safety data sheets.
Buyer concentration among tier-one aerospace OEMs is compressing supplier qualification timelines and consolidating procurement around long-term offtake agreements. Japanese engine manufacturers now lock in multi-year sponge-to-powder supply contracts that bypass spot market exposure. This pattern is most visible in Nagoya and Tokyo industrial clusters, where integrated titanium producers anchor domestic supply security through backward integration into feedstock production.
Global High Purity Titanium Powder Market Segmentation
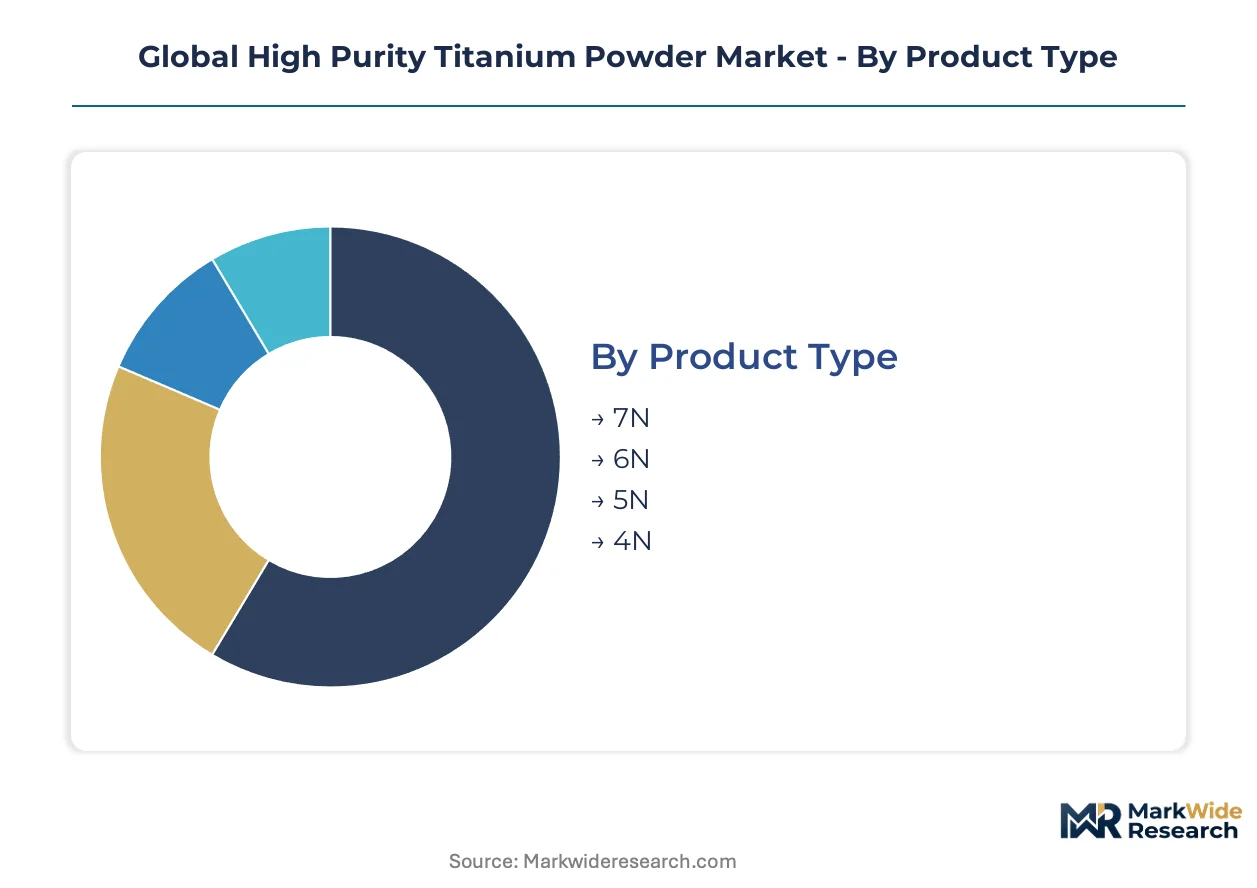
Segmentation by purity grade and application dictates qualification protocols, pricing tiers, and supply chain configuration across the high purity titanium powder market. Manufacturers align production assets to specific purity thresholds, as 4N through 7N grades serve fundamentally different end-use requirements with non-interchangeable certification standards.
Product Type:
Upgrade cycles in semiconductor and medical implant applications are compressing qualification timelines for higher purity grades, forcing producers to reconfigure hydride-dehydride and atomization systems for sequential purity upgrades.
- 7N:Ultra-high purity titanium with metallic impurity levels below 0.0001%, produced through multiple vacuum distillation cycles following initial sponge reduction. Semiconductor sputtering target manufacturers in Japan source captive 7N supply chains for advanced node physical vapor deposition systems, where trace contamination degrades thin-film uniformity.
- 6N:Purity grade commanding premium positioning in biomedical implant applications, where batch-level impurity documentation satisfies FDA 21 CFR Part 820 and ISO 13485 audit requirements. German and French medical device manufacturers consolidate procurement around producers with in-house glow discharge mass spectrometry capabilities.
- 5N:Workhorse purity grade bridging aerospace additive manufacturing and electronics applications, produced via plasma atomization with spherical morphology optimization for electron beam melting.
- 4N:Entry-level high purity specification serving automotive and industrial chemical applications where biocompatibility certification is not required, enabling faster batch release and lower analytical overhead.
Volume placements concentrate in 5N; the faster expansion belongs to 6N.
Application:
Application segmentation maps directly to margin structure, with medical and aerospace commanding qualification premiums while electronics and automotive compete on scale economies.
- Aerospace:Dominant volume consumption channel where titanium displaces nickel-based superalloys in compressor stages and structural brackets, reducing component weight while maintaining fatigue resistance. Engine OEMs in Nagoya and Seattle lock in multi-year offtake agreements that bypass spot market exposure.
- Medical:Implant-grade applications demanding 5N and 6N purity with full material traceability from sponge to finished powder, governed by FDA quality system regulations and EMA MDR compliance. Swiss and German orthopedic manufacturers require ISO 13485 certification as a non-negotiable supplier qualification threshold.
- Electronics:Physical vapor deposition target production serving semiconductor fabrication, where OSAKA Titanium Technologies leverages captive sponge-to-powder integration for sputtering target consistency.
- Automotive:Emerging demand center for additive manufacturing of lightweight structural components, though creep resistance limitations restrict titanium to non-critical chassis applications.
Revenue concentration sits with aerospace; medical is climbing the fastest.
Form:
Form factor selection determines feedstock compatibility with specific additive manufacturing and deposition technologies, creating technology-lock-in effects that resist substitution.
- Powder:Primary form factor for laser powder bed fusion and electron beam melting, with particle size distributions between 15 and 150 micrometers enabling direct machine qualification without secondary sizing. Plasma atomization systems optimize spherical morphology for powder flowability in Tokyo and Montreal production facilities.
- Granule:Intermediate form serving chemical vapor deposition systems where controlled surface area supports reaction kinetics, particularly in German industrial chemical applications.
- Flake:Specialized morphology for physical vapor deposition targets requiring planar surface geometry, produced through hydride-dehydride processing with controlled fracture mechanics.
- Pellet:Retained relevance in electron beam evaporation systems where consolidated feedstock reduces contamination risk during high-temperature deposition.
Procurement is shifting toward powder; pellet retains niche stability.
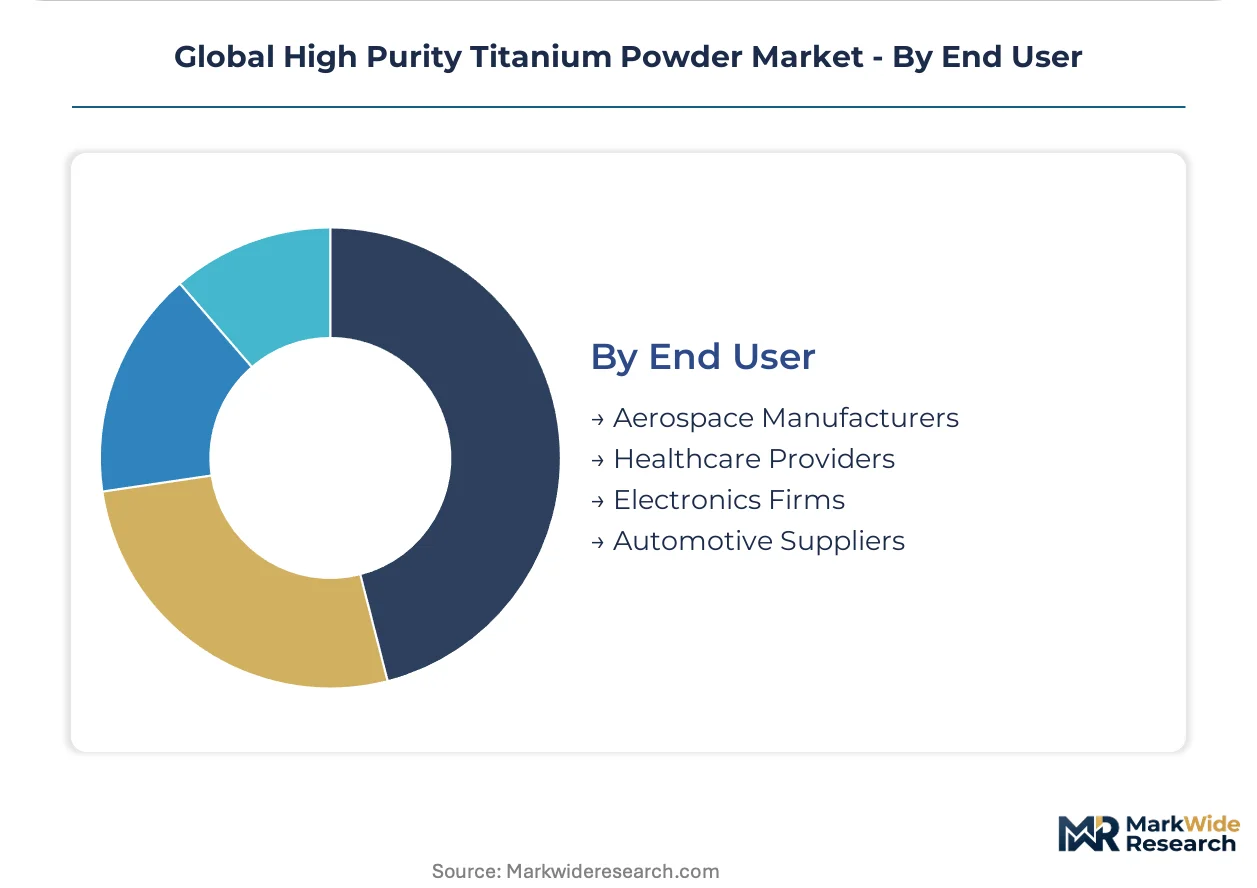
End User:
End user concentration among tier-one OEMs is collapsing supplier bases and extending qualification timelines, favoring producers with dual-use aerospace-medical certification breadth.
- Aerospace Manufacturers:Boeing, Airbus, and Safran anchor demand through structured supplier development programs that mandate plasma atomization capability and inert gas recirculation infrastructure.
- Healthcare Providers:Stryker, Zimmer Biomet, and DePuy Synthes drive medical grade specifications, requiring batch-level impurity certificates and REACH-compliant extended safety data sheets.
- Electronics Firms:Tokyo Electron and Applied Materials source 6N and 7N grades for sputtering target fabrication, with Japanese domestic supply chains preferred for supply security.
- Automotive Suppliers:BMW and Mercedes-Benz additive manufacturing centers pilot titanium powder for luxury vehicle structural components, though volume scaling awaits cost reduction.
Aerospace manufacturers command placement scale; healthcare providers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese titanium sponge producers command integrated supply chains that feed precision electronics and medical implant sectors, while aerospace additive manufacturing concentrates procurement among tier-one OEMs in Seattle and Nagoya. Regulatory divergence between FDA quality systems and ECHA nanoform classifications fragments supplier qualification protocols across major demand centers.
United States
FAA certification requirements for additive manufacturing feedstock and FDA 21 CFR Part 820 quality system regulations govern dual-use aerospace-medical suppliers. The Pacific Northwest hosts plasma atomization facilities serving Boeing's structured supplier development programs, while Greater Boston anchors biomedical implant powder qualification for Stryker and Zimmer Biomet.
Japan
Domestic titanium sponge producers maintain captive sponge-to-powder integration for semiconductor sputtering targets and aerospace engine components. METI industrial policy reinforces supply security through backward integration into feedstock production. The Nagoya-Tokyo industrial corridor locks in multi-year offtake agreements between OSAKA Titanium Technologies and engine OEMs.
Germany
EMA MDR compliance and REACH nanoform classification criteria compel full material disclosure from titanium powder suppliers. Bavaria and Baden-Württemberg concentrate orthopedic implant manufacturing, where German device manufacturers require ISO 13485 certification and batch-level impurity documentation from qualified producers.
China
MIIT industrial standards and dual carbon goals shape domestic titanium powder capacity expansion for aerospace and electronics applications. The Yangtze River Delta and Pearl River Delta clusters host additive manufacturing facilities serving commercial aviation programs, though 5N and 6N purity grades remain import-dependent for semiconductor applications.
India
The PLI scheme for aerospace and defense manufacturing creates localized demand for certified titanium powder feedstock. Karnataka and Maharashtra are piloting domestic additive manufacturing facilities that require qualified powder supply chains, though sponge feedstock dependence on Japanese and Ukrainian sources exposes producers to transport bottlenecks.
Global High Purity Titanium Powder Market Vendor Landscape
Capacity expansion dominates the current landscape as producers scale plasma atomization infrastructure to meet electron beam melting feedstock requirements. The vendor base stratifies between integrated sponge-to-powder operators and specialized atomization technology providers. Three archetypes define competitive positioning: captive feedstock integrators, equipment-technology licensors, and purity-grade specialists. M&A activity and long-term offtake agreements represent the primary competitive moves, with tier-one aerospace OEMs consolidating procurement around qualified dual-use suppliers.
Among Japanese integrated producers, OSAKA Titanium Technologies and Toho Titanium exemplify captive sponge-to-powder operators that anchor domestic supply security through backward integration into feedstock production. AP&C represents the equipment-technology archetype, occupying a position as a plasma atomization specialist serving spherical powder demand from additive manufacturing end-users. These three entities illustrate how geographic concentration in Japanese titanium sponge production translates into downstream powder market influence.
| Leading Market Players |
|---|
| OSAKA Titanium Technologies |
| Toho Titanium |
| AP&C |
| ADMA Products |
| Global Titanium |
| Sandvik |
| Tekna |
| 6K Additive |
| IperionX |
| Others |
Supply Flow & Price Mechanics
Tier-one aerospace OEMs and Japanese semiconductor manufacturers concentrate procurement power, forcing contract-based long-term offtake agreements that compress spot market liquidity and anchor pricing to qualification breadth rather than commodity benchmarks.
Pricing Analysis
Volume concentrates in 5N aerospace additive manufacturing feedstock while margins concentrate in 6N and 7N medical and electronics grades. Pricing stratifies across premium, standard, and economy tiers based on certification level and batch-level impurity documentation depth. Cost compression in 4N industrial grades is intensifying because gas atomization capacity expansion outpaces qualification-constrained medical grade supply. Automotive additive manufacturing pilots exhibit highest price sensitivity; Japanese semiconductor sputtering target manufacturers exhibit lowest.
Supply Chain Analysis
ISO 13485 and AS9100 certification gating fragments supplier bases and extends qualification timelines, concentrating viable supply among dual-use producers with captive analytical laboratories. Sponge feedstock clusters in Japan and Ukraine, with plasma atomization capacity expanding in Canada and the United States. Downstream powder production rests on titanium sponge, inert gas recirculation systems, and glow discharge mass spectrometry equipment. Single-source vulnerability in Ukrainian sponge supply exposes European and Indian additive manufacturers to transport disruption. Distribution runs through direct long-term contracts rather than spot market intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from REACH nanoform reclassification and dual-use audit fatigue will eliminate non-integrated producers lacking captive sponge supply or in-house analytical capabilities.
For Market Incumbents: Hedge against Ukrainian sponge supply disruption by securing alternative feedstock offtake from Japanese producers or advancing hydride-dehydride process optimization with in-line spectroscopic monitoring. Reinforce medical grade positioning through ISO 13485 certification investment before ECHA nanoform criteria harden, as non-compliant producers face extended safety data sheet obligations that strain quality management resources. For New Entrants and Emerging Players: Begin with India's PLI scheme aerospace and defense manufacturing incentives, where localized additive manufacturing facility buildout creates certified powder demand without entrenched incumbent relationships. Target automotive structural component pilots at BMW and Mercedes-Benz additive manufacturing centers as the most penetrable volume segment, leveraging 4N grade lower qualification barriers and faster batch release protocols. For Investors and Strategic Acquirers: The window for entry favors plasma atomization technology licensors with spherical powder process IP and established electron beam melting feedstock qualification. Long-term viability centers on dual-use aerospace-medical certification breadth that collapses duplicate audit costs. Watch ECHA nanoform classification finalization as the inflection signal triggering hazard communication obligation compliance investment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Plasma Atomization Capacity Expansion | Spherical powder morphology secures electron beam melting qualification from Boeing and Safran supplier programs. |
| Captive Sponge-to-Powder Integration | OSAKA Titanium Technologies and Toho Titanium anchor Japanese supply security through backward feedstock control. |
| ISO 13485 Certification Investment | FDA 21 CFR Part 820 compliance elevates barrier-to-entry for Stryker and Zimmer Biomet implant powder supply. |
| India PLI Scheme Localization | Karnataka and Maharashtra additive manufacturing facilities create qualified powder demand serving domestic aerospace programs. |
| In-Line Spectroscopic Monitoring Deployment | Real-time purity verification compresses batch release timelines for German and Swiss medical device manufacturers. |
Methodological Framework
Document review covered trade customs data, SEC filings from titanium producers, ECHA regulatory guidance documents, and FDA quality system regulations, complemented by interviews with plasma atomization equipment specialists, aerospace procurement directors at tier-one OEMs, biomedical engineers at orthopedic implant manufacturers, and semiconductor sputtering target fabrication leads. Secondary validation drew from METI industrial policy white papers, REACH registration databases, and additive manufacturing equipment capex disclosures. Bottom-up segment sizing triangulated against top-down purity grade demand aggregation.
Segment-level projections across purity grades, application verticals, and form factors generated volume and value trajectories over the projection horizon. The analytical framework modeled electron beam melting adoption rates, semiconductor node advancement pacing, and medical implant procedure growth as industry-specific demand drivers. CAGRs derived from regression analysis against historical sponge-to-powder conversion ratios and qualification timeline compression patterns.
Underlying measurement precision varies by segment; 5N aerospace additive manufacturing carries tighter precision than emerging automotive applications due to established OEM reporting transparency. Forecasts reflect assumptions about ECHA regulatory timeline adherence and Japanese sponge producer capacity maintenance. A model refresh is warranted upon material change in Ukraine-Russia conflict status affecting sponge feedstock transport corridors.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Platinum Group Metals Market
Metals
GCC Aluminium Cans Market
Metals
Aluminium Rolled Products Market
Metals
Metallurgical Coal Market
Metals
Huntite Market
Metals
Russia Metal Fabrication Market
Metals
Galvanized Steel Market
Metals
Wear Steel Plate Market
Metals
Beryllium Copper for Industrial Equipment Market
Metals
Aluminum Fluoride Market
Metals
Bismuth Oxide Market
Metals
Silver-Platinum Paste Market
Metals
Europe Aluminium Powder Market
Metals
Global Stretch Spring Wire Market
Metals
Weathering Steel Market
Metals
Copper Foil Market