
 Titanium Mill Products Market | 2026-2036
Titanium Mill Products Market Size, Share, and Industry Trends Forecast 2026-2036
Titanium Mill Products Market Analysis
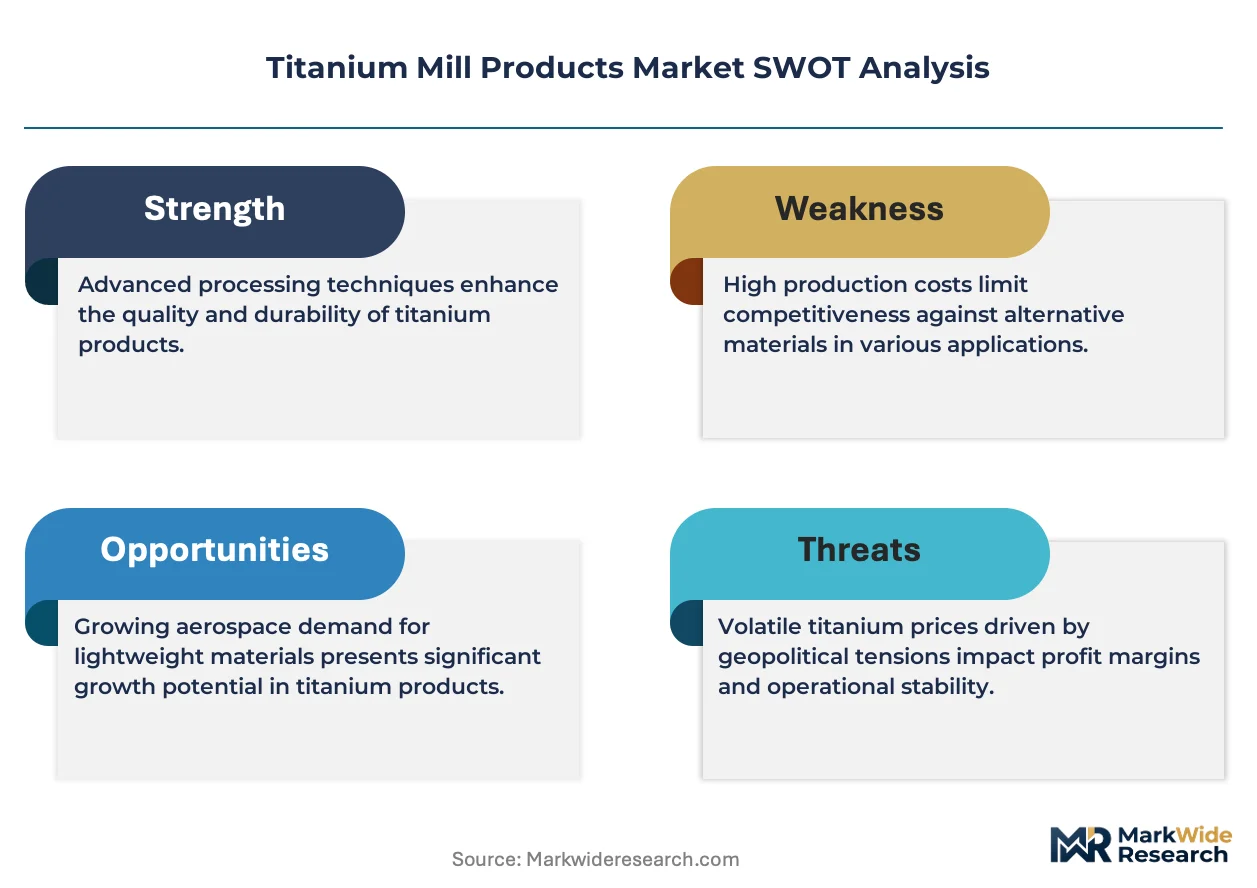
Asset-light leasing structures for titanium sponge conversion capacity are reshaping competitive entry in mill products. VSMPO-AVISMA Corporation leverages captive vertical integration from sponge to finished bar, sustaining margin capture across the value chain. ATI Inc. anchors its position through aerospace-grade plate specialization, while TIMET competes on TIMETAL alloy portfolios for engine rotating components.
Titanium mill products encompass wrought and semi-finished forms—bars, sheets, plates, and tubes—produced from ingot via forging, rolling, or extrusion, with typical aerospace grades meeting AMS 4928 or B265 specifications for strength-to-density ratios exceeding most structural alloys. These materials serve primarily as feedstock for components requiring corrosion resistance and elevated temperature performance. Plate and sheet categories dominate value pools given their penetration in airframe skin and pressure vessel applications, while tube demand for heat exchangers represents the fastest-growing structural segment amid chemical processing capacity expansion. Powder metallurgy forms are gaining traction for near-net-shape medical device implants, though wrought products still occupy the majority of aerospace procurement volumes.
FAA airworthiness directives and AMS material specifications govern U.S. aerospace titanium qualification pathways, while REACH and EU Green Deal carbon-border mechanisms are reshaping European import requirements for mill product sourcing. China's GB/T 3620 standards and dual carbon targets from MEE are tightening domestic smelter emissions benchmarks, indirectly constraining sponge availability for export markets. Stakeholders must monitor evolving alloy qualification timelines and regional carbon accounting rules to secure long-term supply agreements.
Market Dynamics
Aerospace OEMs are consolidating titanium procurement around single-source mill product agreements to secure long-term sponge-to-bar traceability amid volatile energy costs and carbon-border compliance requirements.
Growth Catalysts
- FAA Airworthiness Directives:Updated AMS material specifications for next-generation airframes are mandating higher strength-to-density ratios, pulling titanium alloys into structural applications previously served by aluminum-lithium.
- China's Dual Carbon Goals:MEE emissions benchmarks are constraining domestic sponge smelter output, redirecting procurement toward qualified international mill product suppliers with verified low-carbon production pathways.
- Heat Exchanger Fabrication:Chemical processing capacity expansion across Middle Eastern and Southeast Asian petrochemical clusters is accelerating tube demand for corrosion-resistant titanium seamless products.
Market Restraints
- Sponge Supply Concentration:Over 60% of titanium sponge production clusters in Russia and China, creating geopolitical exposure for Western mill product converters dependent on feedstock imports.
- Kroll Process Energy Intensity:Chloride-route sponge production requires 35-50 MWh per metric ton, rendering titanium mill products vulnerable to electricity price spikes in European and Japanese manufacturing bases.
- Carbon Fiber Substitution:Advanced thermoplastic composites are displacing titanium in non-rotating airframe structures where temperature thresholds permit polymer matrix performance.
Strategic Opportunities
- India Defense Modernization:Indigenous fighter aircraft programs and naval shipbuilding are creating qualified domestic demand for aerospace-grade plate and bar products currently imported from Russia and Europe.
- Additive Manufacturing Feedstock:Plasma rotating electrode process powder derived from mill product offcuts is opening medical implant and aerospace repair applications with near-net-shape geometries.
- EU Carbon Border Adjustment Mechanism:CBAM phase-in for aluminum and steel precursors is incentivizing European OEMs to source titanium mill products with embedded emissions certifications ahead of full mechanism activation.
Industry Challenges
- AMS Qualification Timelines:New alloy variants require 18-36 months of statistical process control documentation before aerospace OEMs release them for production contracts, compressing product development ROI windows.
- Sponge-to-Ingot Traceability Systems:Blockchain-enabled provenance tracking demanded by defense contractors is forcing mill product suppliers to retrofit legacy ERP systems with granular batch-level data capture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Titanium Mill Products Market |
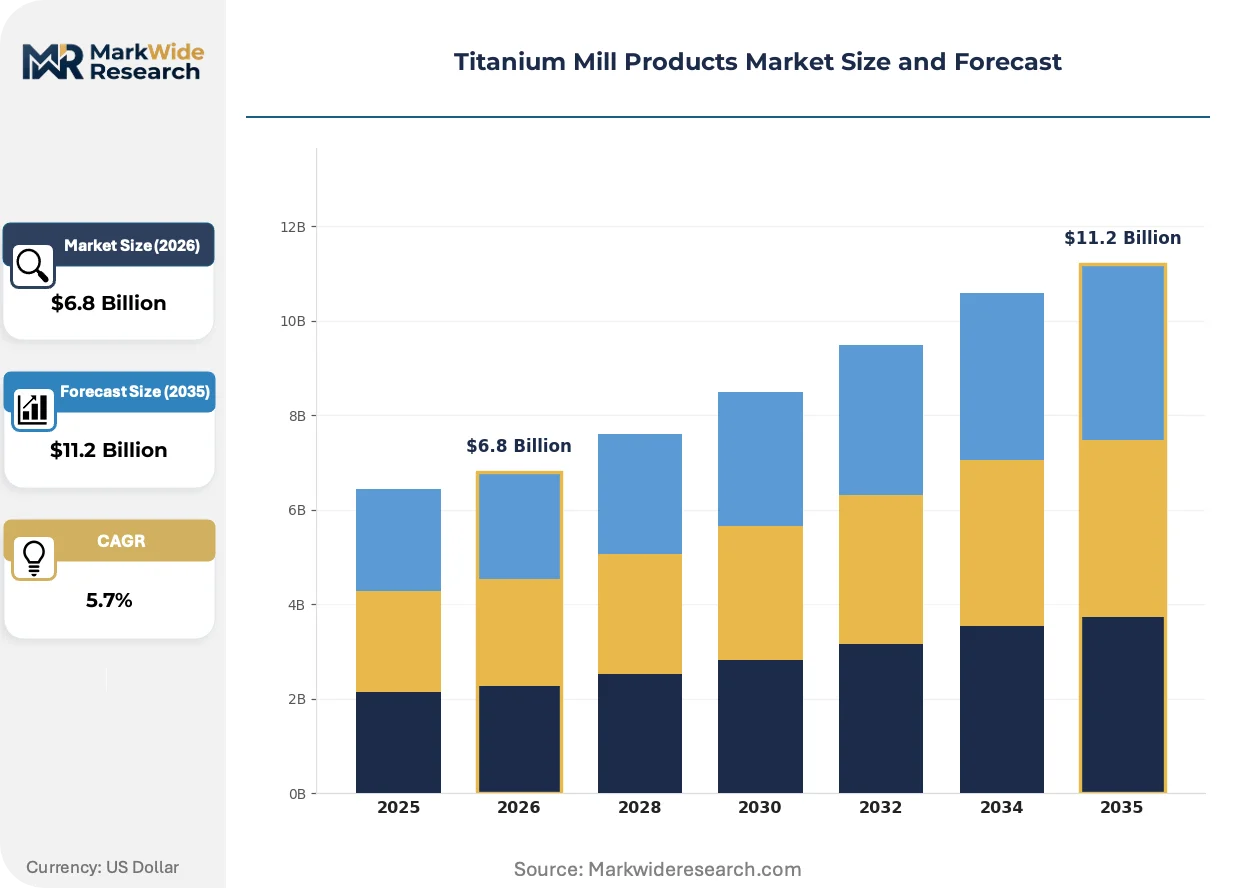
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bars, Sheets, Plates, Tubes End User: Aerospace, Medical Devices, Automotive, Chemical Processing Application: Fabrication, Coatings, Structural Components, Heat Exchangers Form: Forged, Cast, Powder, Wrought |
| Companies Covered | VSMPO-AVISMA Corporation, ATI Inc., TIMET, Baoji Titanium Industry Co., Ltd., Western Superconducting Technologies Co., Ltd., OSAKA Titanium Technologies Co., Ltd., Toho Titanium Co., Ltd., Kobe Steel Ltd., Reliance Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Titanium Mill Products Market Emerging Trajectories
Digital thread integration across sponge conversion and mill finishing operations is compressing quality assurance cycles while enabling real-time carbon intensity tracking for scope 3 emissions reporting.
Electron beam cold hearth remelting is collapsing the defect tolerance window for aerospace-grade ingots by eliminating high-density inclusions that persist in vacuum arc remelted stock. Engine manufacturers are specifying EBCHM material for rotating components where fatigue initiation sites carry catastrophic risk. This metallurgical advance is collapsing the premium pricing spread between prime aerospace grades and commercial-quality mill products as yield rates converge.
REACH authorization requirements for nickel compounds used in titanium alloy production are forcing European mill product suppliers to reformulate master alloy additions and re-qualify ingot chemistries with ECHA-registered alternatives. The regulatory friction is most acute for TIMETAL 834 and similar high-temperature alloys where nickel stabilizes the ordered alpha-two phase. German and French aerospace suppliers are accelerating qualification of reduced-nickel variants to preempt supply interruption.
Long-term offtake contracting is displacing spot market purchasing as OEMs prioritize supply security over price optimization in titanium mill products. Airframers are signing 7-10 year take-or-pay agreements directly with mill product converters, bypassing traditional distributor intermediaries. This behavioral shift is most visible in United States defense procurement, where DFARS compliance and domestic source requirements favor direct mill relationships over multi-metal stockists.
Titanium Mill Products Market Segmentation
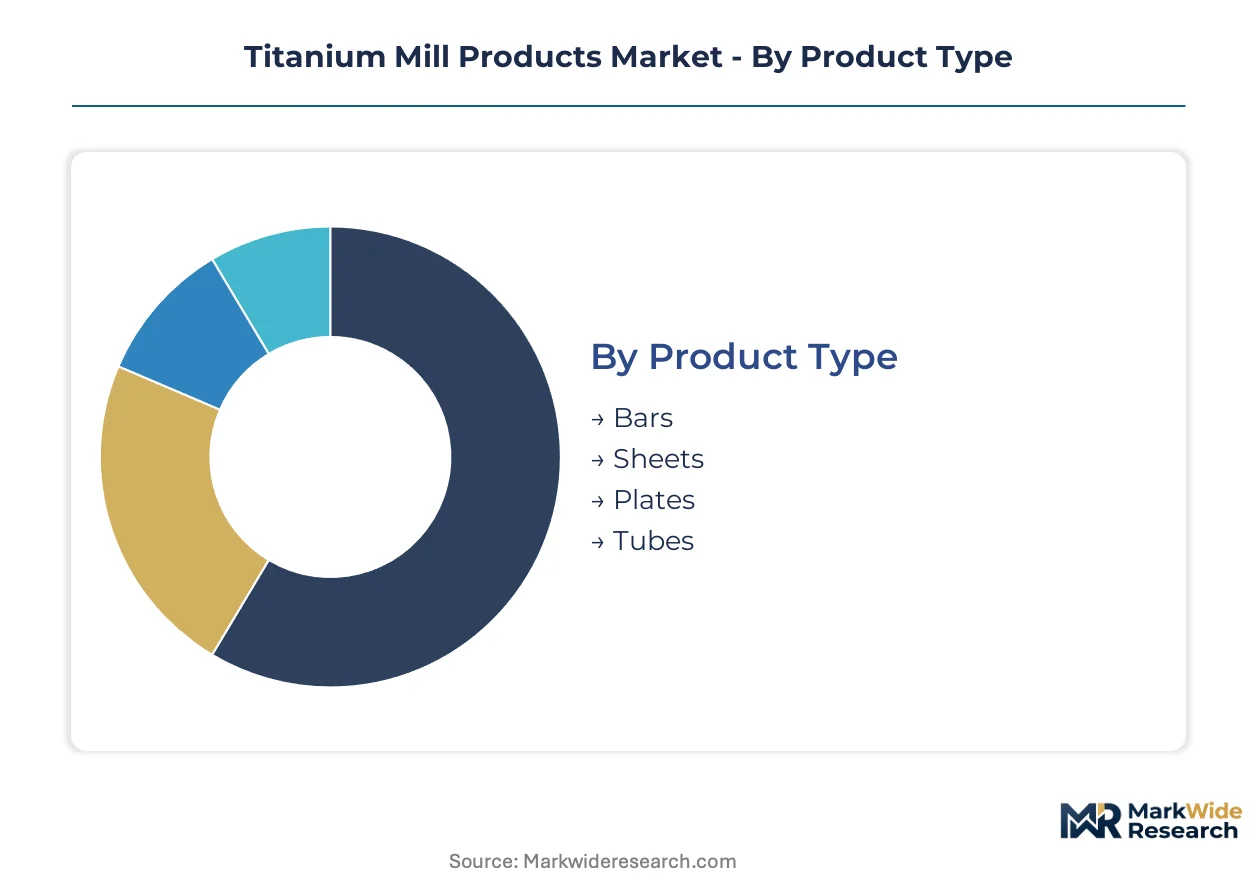
Product form and end-use specifications dictate fundamentally different production economics in titanium mill products. Cycle times, qualification burdens, and margin profiles vary dramatically across segments, forcing converters to prioritize capacity allocation against contracted backlogs rather than spot opportunities.
Product Type:
Inventory velocity separates commodity mill products from engineered specialties, with standard sheet turning 6-8 times annually versus aerospace plate at 2-3 turns due to AMS qualification holds.
- Plates:Thick-section rolled products meeting AMS 4928 and B265 specifications for airframe skin and pressure vessel applications. Boeing and Airbus long-term offtake agreements in the United States concentrate demand for widths exceeding 60 inches, though mill capacity constraints extend lead times to 26-32 weeks.
- Sheets:Thin-gauge cold-rolled products serving chemical processing and architectural cladding where surface finish and flatness tolerance drive specification. Japanese heat exchanger fabricators in Osaka and Yokohama clusters are expanding orders for Grade 2 sheet amid petrochemical capacity additions.
- Bars:Round and rectangular wrought sections for machining into fasteners, fittings, and structural connectors. Bar stock carries shorter qualification cycles than plate, enabling faster response to spot demand from medical device OEMs.
- Tubes:Seamless and welded tubular products for corrosion-resistant piping and heat transfer equipment. Tube demand is expanding most quickly in Middle Eastern petrochemical complexes where chloride resistance specifications favor titanium over stainless alternatives.
Plates dominate installed base. Tubes are where expansion concentrates.
End User:
Customer concentration and contract duration create tiered margin structures, with defense-aerospace procurement locking in decade-long pricing while medical spot orders float with sponge volatility.
- Aerospace:Airframe OEMs and Tier 1 suppliers consuming 70%+ of aerospace-grade plate and bar output. FAA airworthiness directives and DFARS domestic source requirements in the United States enforce qualified supplier lists that exclude non-compliant converters.
- Chemical Processing:Petrochemical and chlor-alkali plant operators specifying seamless tube and welded pipe for heat exchangers and reactor vessels. Saudi Aramco and SABIC maintenance schedules in the Eastern Province drive predictable replacement demand cycles.
- Medical Devices:Orthopedic implant manufacturers and surgical instrument fabricators requiring biocompatible Grade 5 ELI bar and wire. FDA 510(k) clearance pathways and ISO 5832-3 compliance extend qualification timelines beyond industrial applications.
- Automotive:Exhaust system and suspension component prototypes from European premium OEMs, with BMW and Porsche evaluating titanium spring wire for mass reduction. Volume constraints and cost premiums limit penetration to motorsport and limited-production models.
Aerospace commands the deepest contract backlogs. Chemical processing offers the most predictable replacement cycles.
Application:
Functional requirements determine alloy selection and processing route, with structural applications demanding statistical process control documentation that coating and fabrication segments bypass.
- Structural Components:Load-bearing airframe and engine parts requiring forged or rolled mill products with documented mechanical property distributions. Fatigue-critical rotating components specify EBCHM remelted ingot feedstock to eliminate high-density inclusions.
- Heat Exchangers:Tube-and-shell and plate-type exchangers for corrosive process streams, where thermal conductivity and chloride pitting resistance outweigh strength requirements. Fabricators in Singapore and Rotterdam specify welded tube bundles with 25-year design life.
- Fabrication:Welded assemblies and formed subcomponents requiring bend-qualified sheet and plate with controlled grain structure. ASME Section VIII pressure vessel codes govern allowable stress ratings for fabricated titanium equipment.
- Coatings:Thermal spray feedstock and PVD target materials in wire and powder form, representing low-volume but high-margin specialty demand from semiconductor and decorative applications.
Structural components absorb the highest unit value per kilogram. Heat exchangers are climbing the fastest in tonnage terms.
Form:
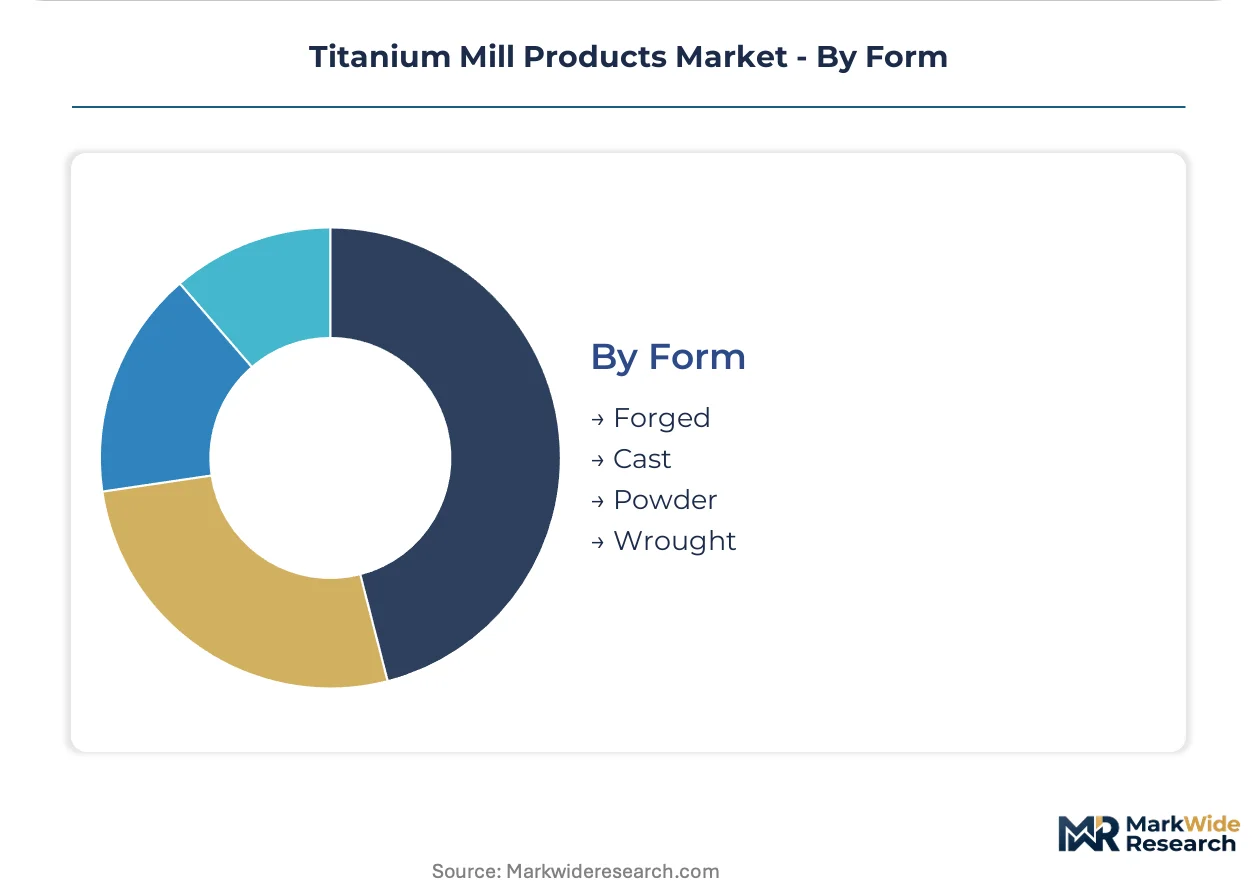
Processing intensity and yield loss create steep cost gradients, with wrought products commanding premiums over cast alternatives due to thermomechanical work input and defect elimination.
- Wrought:Forged, rolled, or extruded products with refined grain structure and directional mechanical properties. Wrought forms occupy the majority of aerospace procurement, with TIMET and ATI specializing in aerospace-grade wrought bar and plate.
- Forged:Hammer or press-forged components with closed-die precision for critical rotating parts. Jet engine disk forgings require 3:1 minimum forging reduction ratios to ensure homogeneity.
- Powder:Plasma rotating electrode process (PREP) and gas atomized powders for additive manufacturing feedstock and near-net-shape medical implants. Powder metallurgy forms are gaining traction for complex geometries where machining waste exceeds 70%.
- Cast:Investment cast and sand cast shapes for chemical pump housings and valve bodies where geometric complexity exceeds forging practicality. Cast titanium remains limited by alpha case formation and hot isostatic pressing requirements.
Wrought forms anchor production volume. Powder is where technology investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances are reshaping titanium mill product flows as Western aerospace OEMs diversify sponge sourcing away from concentrated supply zones. Regional production capabilities and qualification standards now determine competitive access more than raw material proximity.
United States
Defense procurement and commercial aircraft backlogs sustain mill product demand through Boeing and Lockheed Martin supply chains. FAA airworthiness directives and DFARS domestic source requirements enforce qualified supplier lists that exclude non-compliant foreign converters. The Seattle-Tacoma aerospace cluster concentrates plate and bar consumption for 737 MAX and 777X programs.
China
Dual carbon goals from MEE are constraining domestic sponge smelter output and redirecting procurement toward verified low-carbon production pathways. GB/T 3620 standards govern alloy specifications for indigenous COMAC C919 airframe programs. The Baoji titanium industrial base in Shaanxi Province hosts integrated sponge-to-mill-product operations serving domestic chemical processing expansion.
Japan
Heat exchanger fabricators in Osaka and Yokohama clusters are expanding orders for Grade 2 sheet amid regional petrochemical capacity additions. METI industrial policy supports advanced melting technology development for aerospace-grade ingot production. JIS standards alignment with AMS specifications enables dual-qualified export positioning for Japanese mill product suppliers.
Germany
EU Carbon Border Adjustment Mechanism phase-in is incentivizing European OEMs to source titanium mill products with embedded emissions certifications ahead of full mechanism activation. ECHA REACH authorization requirements for nickel compounds are forcing reformulation of high-temperature alloy chemistries. The Hamburg-Bremen port complex handles import logistics for aerospace-grade plate distributed to Airbus Hamburg assembly operations.
Saudi Arabia
SABIC and Saudi Aramco maintenance schedules in the Eastern Province drive predictable replacement demand cycles for corrosion-resistant seamless tube. The country's national industrial development program is evaluating domestic mill product conversion partnerships to reduce import dependency. Jubail Industrial City hosts expanding petrochemical infrastructure requiring titanium heat exchanger bundles with 25-year design life specifications.
Titanium Mill Products Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in sponge conversion and alloy formulation. The vendor base organizes around three structural tiers: vertically integrated Russian and Chinese producers with captive sponge supply; Western aerospace-grade specialists with EBCHM remelting capabilities; and regional distributors serving spot chemical processing demand. Consolidation pressure concentrates in the middle tier as qualification burdens and carbon traceability requirements raise capital barriers. Dominant competitive moves include long-term offtake contracting with OEMs and backward integration into sponge sourcing.
Within the vertically integrated tier, VSMPO-AVISMA Corporation exemplifies captive control from sponge through finished bar production. ATI Inc. and TIMET occupy positions among Western aerospace-grade specialists, with the former anchoring plate specialization and the latter representing TIMETAL alloy portfolio capabilities. These three entities collectively illustrate the strategic archetypes competing for qualified supplier status under tightening emissions and traceability standards.
| Leading Market Players |
|---|
| VSMPO-AVISMA Corporation |
| ATI Inc. |
| TIMET |
| Baoji Titanium Industry Co., Ltd. |
| Western Superconducting Technologies Co., Ltd. |
| OSAKA Titanium Technologies Co., Ltd. |
| Toho Titanium Co., Ltd. |
| Kobe Steel Ltd. |
| Reliance Inc. |
| Others |
Supply Flow & Price Mechanics
Sponge supply concentration in Russia and China determines both pricing tier spreads and supply chain shape, forcing Western aerospace OEMs to pay premiums for qualified low-carbon production pathways while accepting extended lead times for DFARS-compliant domestic sourcing.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing, with aerospace-grade plate commanding spreads over commercial sheet based on AMS qualification documentation and EBCHM remelting certification. Price differentiation hinges on ingot traceability granularity and carbon intensity certification tier, with EU CBAM-compliant products capturing premiums ahead of full mechanism activation. Pricing pressure stems from Kroll process energy intensity exposing European converters to electricity cost spikes. Chemical processing buyers exhibit highest price sensitivity, while defense-aerospace procurement locks in decade-long pricing with limited elasticity.
Supply Chain Analysis
Titanium sponge feedstock draws from concentrated smelting capacity in Russia, China, and Japan, with chloride-route production resting on petroleum coke, chlorine, and magnesium reductant inputs. Single-source vulnerability pervades Western converter operations dependent on imported sponge from geopolitically exposed zones. Distribution runs through direct mill-to-OEM long-term agreements displacing traditional multi-metal stockists, particularly in United States defense procurement channels where DFARS compliance mandates qualified supplier relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment defensive moat, where AMS qualification timelines and DFARS domestic source requirements create structural barriers that protect incumbent positions against price-based competition.
For Market Incumbents: Build certification-depth moats by accelerating EBCHM capacity additions in United States manufacturing bases and securing blockchain-enabled sponge-to-bar traceability systems ahead of defense contractor mandates. Carbon intensity verification infrastructure represents the critical lever against emerging low-carbon entrants from Chinese state-backed operations. Sponge supply disruption from MEE emissions constraints in China poses the primary external threat requiring backward integration hedging.
For New Entrants and Emerging Players: Mid-market chemical processing tube demand in Saudi Arabia and India represents the most penetrable entry point, where corrosion-resistant specifications favor titanium over stainless alternatives but AMS qualification burdens remain absent. Medical device powder metallurgy for orthopedic implants offers secondary white-space, with PREP-derived feedstock enabling near-net-shape geometries that bypass wrought product yield losses. Qualification partnerships with established heat exchanger fabricators provide the essential go-to-market pathway.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors aerospace-grade specialists with captive EBCHM capabilities and existing OEM offtake relationships. Long-term viability centers on exposure to defense procurement backlogs and commercial aircraft replacement cycles rather than spot chemical processing demand. Watch for CBAM implementation acceleration as the inflection signal that revalues low-carbon production assets.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sponge Sourcing | Captive titanium sponge supply from Australian or Saudi feedstock secures margin capture against Russian-Chinese concentration risk. |
| EBCHM Remelting Capacity Expansion | Electron beam cold hearth installations at United States mills meet Boeing and Lockheed Martin fatigue-critical specifications. |
| Carbon Intensity Certification Program | Scope 3 emissions documentation aligns with EU CBAM phase-in requirements for Airbus Hamburg assembly supply. |
| Long-term Supply Agreement | Seven-to-ten year take-or-pay contracts with COMAC or defense primes lock in volume visibility through cycle volatility. |
| Additive Manufacturing Feedstock Development | PREP powder from mill product offcuts opens medical implant and aerospace repair applications with minimal machining waste. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with titanium mill product procurement managers at aerospace Tier 1 suppliers, chemical processing plant engineers, and defense contractor materials qualification leads; and secondary validation through FAA airworthiness directive filings, AMS specification databases, customs trade flows, and SEC 10-K disclosures from publicly traded converters. Bottom-up segment sizing across product form, end-use, and regional demand clusters was triangulated against top-down value chain analysis.
Forecast inputs considered alloy qualification timeline trajectories, sponge smelter capacity utilization across Russia and China, and aerospace OEM delivery schedules throughout the projection horizon. Segmentation dimensions modeled include product form category, end-use industry vertical, application functional requirement, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand projections and supply-side capacity expansion announcements.
Macroeconomic conditions sit as an overlay; deviation in electricity pricing volatility, defense procurement appropriations, or petrochemical capital expenditure cycles would shift the trajectory. Material shifts in MEE emissions enforcement intensity or CBAM activation timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Medium Carbon Steel Market
Metals
Tungsten Metal Powder Market
Metals
Copper Foil Market
Metals
Asia-Pacific Aluminum Casting Market
Metals
Global Oxygen-Free Copper Market
Metals
Metal Injection Molding (Mim) Powders Market
Metals
Aluminium Collars Market
Metals
Beryllium Copper for Industrial Equipment Market
Metals
Palladium Market
Metals
Liquid Metal Thermal Pad Market
Metals
Beryllium Copper Billet Market
Metals
High Carbon Bearing Steel Market
Metals
Flat-Rolled Stainless Steel Market
Metals
Merchant Bar Quality (MBQ) Steel Market
Metals
Aluminium Rolled Products Market
Metals
North America Grain Oriented Electrical Steel Market