
 Silicon Anode Binder Polymers for Lithium-Ion Batteries Market | 2026-2036
Silicon Anode Binder Polymers for Lithium-Ion Batteries Market Size, Share, and Industry Trends Forecast 2026-2036
Silicon Anode Binder Polymers for Lithium-Ion Batteries Market Insights
Korean petrochemical producers is recalibrating capacity toward battery-grade polymer lines as silicon-anode adoption accelerates. BASF leverages its global polymer R&D footprint to anchor specialty binder supply for European cell makers. Zeon Corporation dominates styrene-butadiene rubber formulations for high-silicon-loading electrodes. Kumho Petrochemical extends its synthetic rubber expertise into customized anode binders for Korean battery manufacturers.
Silicon anode binder polymers are adhesive formulations that mechanically stabilize silicon-based active material particles during extreme volumetric expansion and contraction cycles exceeding 300%, with elastic modulus and tensile recovery parameters determining cycle life. These polymers function as critical interface layers that maintain electronic conductivity and prevent electrode pulverization in next-generation lithium-ion cells targeting energy densities above 400 Wh per kilogram. Polyacrylic acid variants lead current commercial adoption due to their carboxyl-rich backbone enabling strong hydrogen bonding with silicon oxide surfaces, while sodium alginate represents the fastest-growing chemistry as seaweed-derived alternatives gain traction in sustainability-focused supply chains. Electric vehicle battery applications command the dominant margin pool as automotive OEMs specify silicon-anode cells for premium platform ranges, whereas consumer electronics provides a mature, volume-stable baseline with less stringent binder performance thresholds.
China's SAMR enforces GB standards for lithium-ion cell safety that directly specify mechanical integrity testing of silicon-dominant anodes, while REACH in Europe mandates disclosure of polymer additive compositions affecting binder import compliance. Japan's METI coordinates national battery roadmap targets that incentivize domestic polymer innovation for silicon anode architectures. Stakeholders must monitor how solid-state battery timelines and dry electrode processing trends reshape binder application methods and material specifications.
Market Dynamics
Silicon-anode binder demand concentrates where cathode and anode supply chains co-locate, with East Asian manufacturing corridors capturing the bulk of polymer procurement as cell energy density targets tighten across automotive platforms.
Growth Catalysts
- Automotive OEM Range Targets:Electric vehicle battery makers in South Korea and Japan are scaling silicon-anode trials to deliver premium platform ranges above 500 kilometers per charge.
- China's Safety Certification Push:NMPA and SAMR enforcement of stricter GB standards for lithium-ion cell mechanical integrity directly favors advanced polymer binders over conventional formulations.
- Seaweed-Derived Chemistry Scale-Up:Sodium alginate binders are gaining procurement traction in sustainability-focused supply chains as cathode-anode co-location accelerates material circularity mandates.
Market Restraints
- Petrochemical Feedstock Volatility:Styrene-butadiene rubber formulations remain exposed to butadiene price swings that compress binder margin structures.
- Korean Supply Concentration:Synthetic rubber expertise for customized anode binders clusters among Korean petrochemical producers, creating single-source vulnerability for European cell makers.
- Solid-State Timeline Uncertainty:Dry electrode processing trends threaten to displace conventional binder application methods before polymer R&D amortization cycles complete.
Strategic Opportunities
- European REACH Compliance Services:Binder additive disclosure mandates create white space for technical documentation and reformulation consulting for import-dependent cell manufacturers.
- Japan METI Roadmap Alignment:National battery innovation targets incentivize domestic polymer development for silicon anode architectures, opening procurement channels for specialty chemical partners.
- Dry Electrode Binder Integration:Convergence of solid-state battery timelines with solvent-free electrode processing requires new polymer architectures for powder-to-electrode adhesion.
Industry Challenges
- Electrochemist Talent Scarcity:The intersection of polymer science and silicon surface chemistry demands specialized formulation expertise that outpaces university pipeline output.
- Dual Certification Timelines:Simultaneous compliance with China's GB standards and Europe's REACH disclosure requirements extends product qualification cycles for multinational suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silicon Anode Binder Polymers for Lithium-Ion Batteries Market |
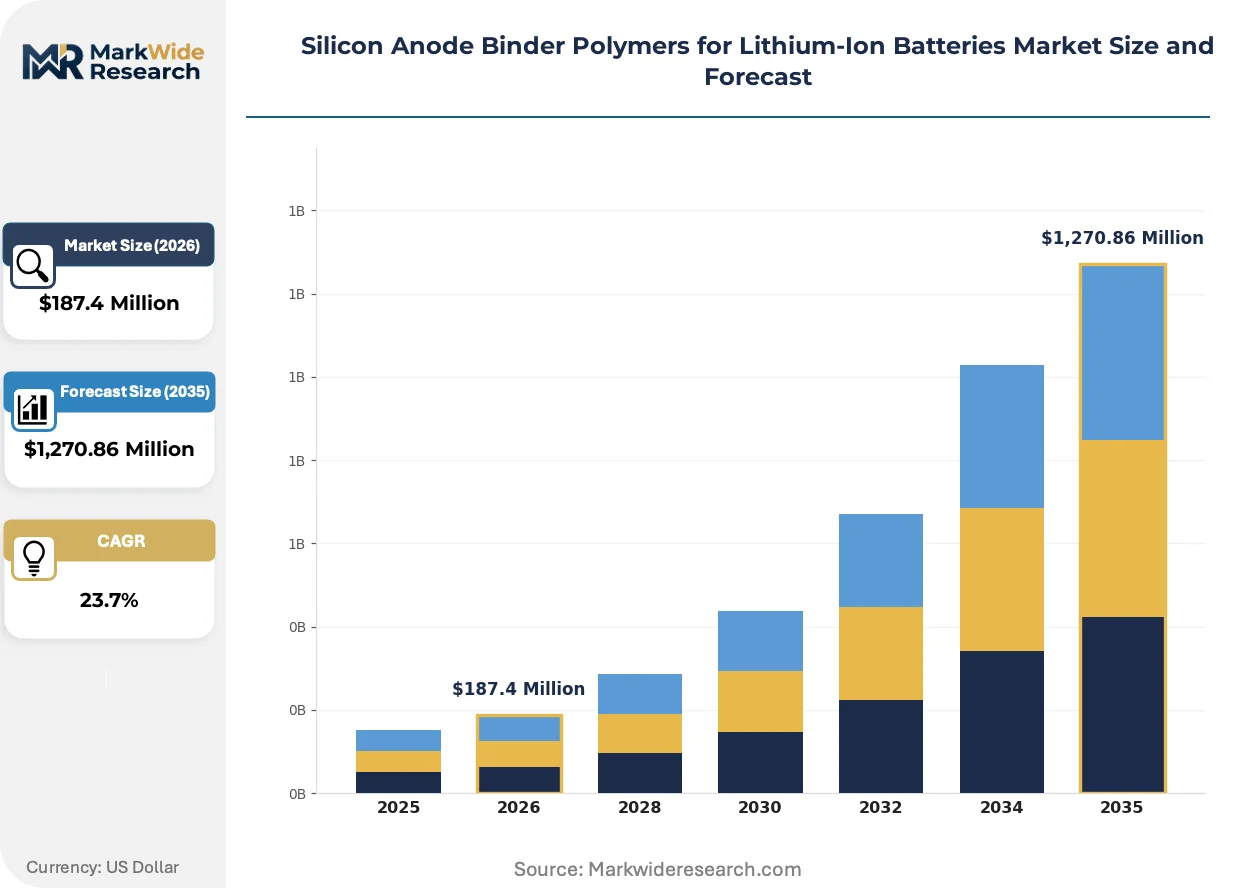
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $1,270.86 Million |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Polymer Type: Polyacrylic Acid, Carboxymethyl Cellulose, Styrene-Butadiene Rubber, Polyvinylidene Fluoride, Sodium Alginate Battery Application: Consumer Electronics, Electric Vehicles, Grid Storage, Power Tools, Aerospace Energy Storage Manufacturing Process: Solution Casting, Electrospinning, Spray Coating, Freeze Drying, Roll-to-Roll Processing End User Type: Battery Manufacturers, Specialty Chemical Suppliers, Research Institutions, Automotive Tier-1s, Electronics OEMs |
| Companies Covered | BASF, Ashland, Zeon Corporation, LG Chem, Nippon Shokubai, Kumho Petrochemical, Enovix, Group14 Technologies, Resonac, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silicon Anode Binder Polymers for Lithium-Ion Batteries Market Trends and Innovations
Polymer architecture evolution is compressing qualification timelines as binder suppliers race to match silicon loading increases in next-generation anode designs. Three developments are restructuring competitive positioning.
Carboxyl-rich polyacrylic acid variants are integrating into high-silicon-loading electrodes as the dominant commercial chemistry for hydrogen bonding with silicon oxide surfaces. Korean battery manufacturers are adopting these formulations at accelerated pace for 2025 platform launches. This chemistry is integrating mechanical stabilization standards that exceed 300% volumetric expansion tolerance, compressing the performance gap between pilot and production-scale cells.
REACH in Europe mandates granular disclosure of polymer additive compositions affecting binder import compliance timelines for non-European suppliers. The regulation's industrial consequence is a restructuring of technical documentation requirements across the supply base. Automotive cell makers in Germany and Hungary are responding by qualifying regional polymer R&D partners to reduce cross-border certification friction.
Buyers are consolidating procurement around cathode-anode co-located manufacturing corridors to compress logistics costs and align binder viscosity specifications with just-in-time electrode coating schedules. The spot-market polymer channel serving dispersed consumer electronics cell makers is losing share to direct mill agreements. This concentration is most visible in China's Jiangsu and Guangdong provinces where integrated gigafactory complexes now specify captive binder supply terms.
Silicon Anode Binder Polymers for Lithium-Ion Batteries Market Segmentation
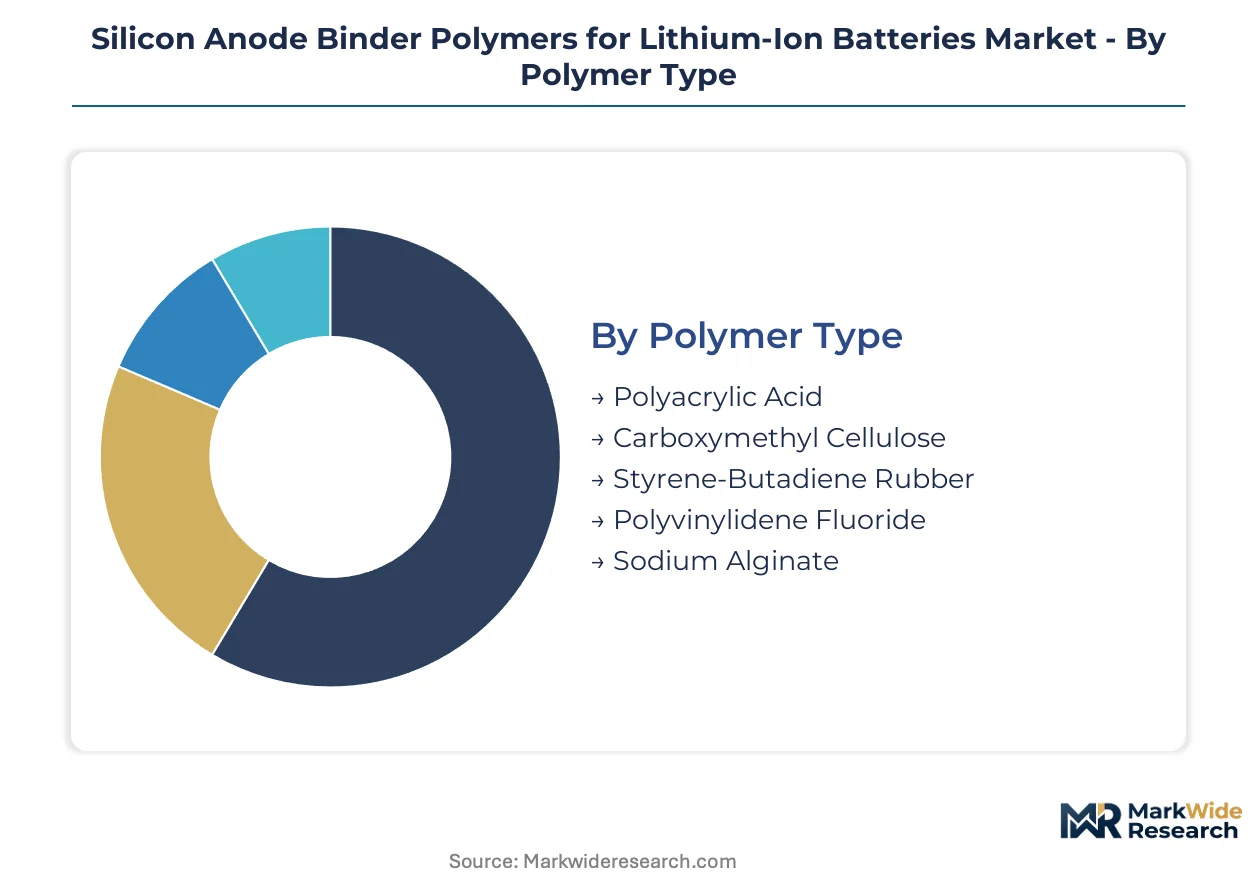
Silicon anode binder polymers exhibit divergent performance profiles across polymer architectures and battery applications. Segmentation reveals where formulation customization commands premium pricing versus where standardized chemistries dominate procurement volumes.
Polymer Type:
Customization intensity spans from commodity-compatible formulations to engineered specialty polymers with application-specific functionalization.
- Polyacrylic Acid:Carboxyl-rich backbone enables robust hydrogen bonding with silicon oxide surfaces, delivering mechanical stabilization through 300% volumetric expansion cycles. Korean battery manufacturers specify these formulations for premium electric vehicle platforms where cycle life targets exceed 1,000 charge-discharge cycles.
- Sodium Alginate:Seaweed-derived biopolymer with tunable ionic crosslinking density attracts sustainability-mandated procurement from European automotive OEMs. Supply chains in China's Jiangsu province are integrating sodium alginate into circularity-certified binder portfolios.
- Styrene-Butadiene Rubber:Korean petrochemical producers leverage synthetic rubber expertise for high-volume electrode coating operations.
- Carboxymethyl Cellulose:Water-processable thickener dominates cost-sensitive consumer electronics cell manufacturing.
- Polyvinylidene Fluoride:Fluorinated binder chemistry serves niche applications demanding extreme electrochemical stability.
Most installed capacity flows through Polyacrylic Acid. Expansion is steepest in Sodium Alginate.
Battery Application:
Performance thresholds and qualification timelines segment demand across mobility, stationary, and portable power sectors.
- Electric Vehicles:Automotive OEMs specify silicon-anode cells for platform ranges above 500 kilometers, driving binder qualification cycles that exceed 18 months. China's NMPA safety certifications and Europe's REACH disclosure mandates create dual compliance burdens for suppliers targeting this segment.
- Consumer Electronics:Mature volume baseline with standardized binder specifications and compressed procurement cycles. Electronics OEMs in Japan prioritize supply security over formulation innovation for smartphone and laptop battery applications.
- Grid Storage:Long-duration cycling requirements favor high-elasticity polymer architectures with 15-20 year service life targets.
- Power Tools:High-discharge-rate applications demand binders with rapid ion transport characteristics.
- Aerospace Energy Storage:Extreme temperature tolerance specifications restrict qualified supplier pools.
Revenue concentration peaks in Electric Vehicles. Volume stability characterizes Consumer Electronics.
Manufacturing Process:
Process selection determines binder morphology, electrode coating uniformity, and capital equipment requirements.
- Solution Casting:Dominant commercial method for high-throughput electrode production with established viscosity control protocols. Roll-to-roll coating lines in South Korea and China rely on solution-cast binders for gigafactory-scale output.
- Roll-to-Roll Processing:Continuous electrode manufacturing integrates binder application with calendering and drying stages. Japanese equipment suppliers are advancing roll-to-roll precision for sub-10-micron coating tolerances.
- Electrospinning:Produces nanofiber binder architectures for ultra-high silicon loading electrodes.
- Spray Coating:Enables rapid prototyping and small-batch formulation testing.
- Freeze Drying:Preserves porous binder structures for solid-state battery interface engineering.
Production scale concentrates in Solution Casting. Technical development investment flows toward Roll-to-Roll Processing.
End User Type:
Procurement authority and formulation expertise distribute across integrated cell makers and specialized chemical suppliers.
- Battery Manufacturers:Direct specification of binder chemistries for captive electrode production lines. Korean and Chinese cell makers are internalizing polymer formulation capabilities to compress qualification timelines.
- Specialty Chemical Suppliers:Technical service relationships with automotive Tier-1s drive customized binder development programs. BASF and Zeon Corporation anchor European and Japanese supply positions through R&D partnerships.
- Research Institutions:Early-stage polymer screening and silicon surface chemistry investigation.
- Automotive Tier-1s:Cell procurement specifications increasingly include binder traceability requirements.
- Electronics OEMs:Volume purchasing power concentrates demand for standardized polymer grades.
Procurement volume aggregates through Battery Manufacturers. Technical specification influence is expanding among Specialty Chemical Suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's binder procurement volumes outpace South Korean adoption rates by a factor of three, yet Japanese polymer innovation cycles remain the tightest in East Asia.
China
Jiangsu and Guangdong province gigafactories are specifying captive polyacrylic acid supply terms as integrated cathode-anode complexes reach operational scale. SAMR enforcement of GB standards for lithium-ion cell mechanical integrity directly favors advanced polymer binders over conventional formulations. The Yangtze River Delta manufacturing corridor now hosts the densest concentration of solution-cast electrode coating lines globally.
South Korea
Seoul Capital Area battery manufacturers are scaling silicon-anode trials for 2025 electric vehicle platform launches targeting ranges above 500 kilometers. MFDS coordinates with national battery roadmap initiatives to accelerate domestic polymer qualification timelines. Busan-Ulsan petrochemical producers are recalibrating capacity toward battery-grade styrene-butadiene rubber lines.
Japan
METI national battery innovation targets incentivize domestic polymer development for silicon anode architectures with cycle life exceeding 1,000 charge-discharge cycles. Kansai region specialty chemical suppliers anchor R&D partnerships with automotive Tier-1s. Nagoya equipment manufacturers are advancing roll-to-roll precision for sub-10-micron coating tolerances.
Germany
Automotive cell makers in Bavaria and Lower Saxony are qualifying regional polymer R&D partners to reduce REACH cross-border certification friction. ECHA disclosure mandates for polymer additive compositions extend import compliance timelines for non-European suppliers. The Stuttgart industrial cluster is consolidating procurement around cathode-anode co-located manufacturing to compress logistics costs.
United States
Pacific Northwest research institutions are screening early-stage polymer architectures for solid-state battery interface engineering. EPA regulations on solvent emissions from electrode coating operations are accelerating interest in dry electrode processing trends. The Greater Boston corridor hosts specialized electrochemist talent pools addressing formulation expertise gaps at the polymer-silicon surface chemistry intersection.
Silicon Anode Binder Polymers for Lithium-Ion Batteries Market Competitive Landscape
Korean petrochemical producers anchor one tier; German and Japanese specialty chemical specialists hold premium formulation positions. The market structure consolidates around three strategic archetypes: synthetic rubber fabricators leveraging feedstock integration, diversified chemical conglomerates with global R&D footprints, and battery-integrated polymer developers compressing qualification timelines. Capacity expansion and strategic partnerships represent the dominant competitive moves as silicon loading targets tighten across automotive platforms.
Within the synthetic rubber specialist tier, Kumho Petrochemical and Zeon Corporation exemplify Korean producers extending petrochemical expertise into customized anode binders. BASF occupies a position among diversified chemical conglomerates leveraging global polymer R&D infrastructure. These three companies represent distinct geographic and structural archetypes: Korean feedstock-integrated fabrication, Japanese high-performance formulation, and European REACH-compliant technical service.
| Leading Market Players |
|---|
| BASF |
| Ashland |
| Zeon Corporation |
| LG Chem |
| Nippon Shokubai |
| Kumho Petrochemical |
| Enovix |
| Group14 Technologies |
| Resonac |
| Others |
Pricing and Supply Chain Analysis
Automotive OEM procurement consolidation around cathode-anode co-located manufacturing corridors is compressing spot-market polymer channels and forcing suppliers toward direct mill agreements with captive volume commitments. This buyer-side concentration shifts pricing power toward Korean and Chinese cell makers while squeezing margin structures for non-integrated specialty chemical suppliers.
Pricing Analysis
Distributor margins in the polymer binder channel have compressed to single-digit percentages as battery manufacturers internalize formulation specification authority. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and silicon loading performance, with automotive EV platforms commanding 40-60% premiums over consumer electronics grades. Pricing pressure stems from butadiene feedstock volatility in styrene-butadiene rubber formulations. Consumer electronics OEMs exhibit highest price sensitivity, while automotive Tier-1s prioritize cycle life guarantees over unit cost.
Supply Chain Analysis
Regional distribution centers in Busan, Ulsan, and the Yangtze River Delta operate hub-and-spoke patterns feeding just-in-time electrode coating lines. Manufacturing concentrates in China, South Korea, and Japan, with Jiangsu province hosting the densest solution-cast capacity globally. Raw material flows draw from petrochemical feedstocks, seaweed harvesting operations for sodium alginate, and acrylic acid monomer streams. Single-source vulnerability clusters among Korean synthetic rubber producers serving European cell makers. Distribution runs through direct mill agreements with integrated gigafactory complexes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicon anode binder polymers function as a stable compounder anchored by irreversible automotive electrification mandates that lock in decade-long procurement cycles for qualified suppliers.
For Market Incumbents: Cement supply security through backward integration into acrylic acid monomer production and captive seaweed processing for sodium alginate portfolios. Solid-state battery timelines threaten conventional solvent-based binder application methods before R&D amortization completes, demanding accelerated dry-electrode polymer architecture development. Capacity addition in China's Jiangsu province aligns with cathode-anode co-location trends. For New Entrants and Emerging Players: Enter via European REACH compliance documentation services, where additive disclosure mandates create white space for technical consulting and reformulation support. The most penetrable segment sits with import-dependent German and Hungarian cell makers seeking regional polymer R&D partners. A go-to-market angle anchored in GB standard pre-certification for China's SAMR requirements opens procurement channels with multinational battery manufacturers. For Investors and Strategic Acquirers: Asymmetric upside sits with specialty chemical developers possessing dry-electrode polymer architectures compatible with solid-state battery interfaces. Long-term viability favors acquisition targets with demonstrated silicon loading performance above 300% volumetric expansion tolerance and established automotive OEM qualification relationships. The signal to watch is dry electrode processing equipment orders from Japanese roll-to-roll precision manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Acid Monomer | Korean petrochemical producers secure feedstock control against butadiene price volatility. |
| Seaweed Processing Capacity Buildout | Sodium alginate suppliers in China's Jiangsu province meet circularity certification mandates from European automotive OEMs. |
| Dry Electrode Polymer R&D Partnership | Japanese specialty chemical firms align with METI national battery innovation targets for solid-state architectures. |
| REACH Compliance Documentation Services | Technical consulting firms reduce cross-border certification friction for non-European binder suppliers. |
| Automotive OEM Direct Qualification Programs | Specialty chemical suppliers compress 18-month qualification cycles through captive R&D partnerships with Tier-1s. |
Research Methodology
Direct dialogue with polymer R&D directors, battery manufacturer procurement leads, electrode coating line engineers, and petrochemical plant managers grounded the qualitative foundation. Secondary validation drew from customs and trade data, Korean and Chinese chemical industry association reports, SEC filings from diversified chemical conglomerates, and SAMR GB standard documentation. Bottom-up and top-down triangulation cross-checked binder volume assumptions against cathode-anode capacity expansion announcements.
Bottom-up modeling segmented demand across polymer architecture, battery application, manufacturing process, and end-user type, with value outputs reconciled against top-down macroeconomic drivers. The analytical framework projected silicon loading penetration rates, automotive platform energy density targets, and regulatory certification timelines across the analysis window. CAGRs derived from regression analysis of historical polymer procurement patterns correlated with lithium-ion cell production capacity.
Inputs from primary stakeholder interviews and disclosed regulatory filings were available through the study window; gaps in solid-state battery commercialization timelines and dry electrode processing adoption rates introduce uncertainty bands around outer-year projections. Forecasts reflect documented assumptions regarding automotive OEM range targets and polymer qualification cycle durations. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polyolefin (PO) Market
Polymers & Resins
C9 Resin Market
Polymers & Resins
Global Bio Polyamide Market
Polymers & Resins
GCC Vinyl Flooring Market
Polymers & Resins
Polymer Filler Market
Polymers & Resins
Global Injection Molding Plastic Market
Polymers & Resins
Highly Reactive Polyisobutylene (HR-PIB) Market
Polymers & Resins
Water Soluble Polymers Market
Polymers & Resins
Nonchlorinated Polyolefins Market
Polymers & Resins
Italy Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Liquid Polybutadiene [LPBD] Market
Polymers & Resins
Global Thermally Conductive Plastics Market
Polymers & Resins
North America Plastic Compounding Market
Polymers & Resins
Global Alkyd Resin Market
Polymers & Resins
Neoprene Market
Polymers & Resins
Medical Styrenic Polymers Market