
 Aluminium Chloride Market | 2026-2036
Aluminium Chloride Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminium Chloride Market Analysis
ISO 9001 certification is reorganizing supplier eligibility for municipal water treatment contracts, pushing smaller traders toward tolling arrangements with qualified manufacturers. BASF SE leverages backward integration into chlor-alkali feedstock to control input costs across European supply chains. Gujarat Alkalies and Chemicals Ltd anchors western India production through captive caustic soda and chlorine supply at its Dahej complex. Solvay S.A. differentiates via pharmaceutical-grade anhydrous material serving European drug precursor markets.
Aluminium chloride is an inorganic compound with formula AlCl₃, existing as white or pale yellow solid with hygroscopic properties and sublimation point near 178 degrees Celsius; manufacturers produce it via direct chlorination of aluminium metal or reaction of aluminium oxide with carbon and chlorine in exothermic processes. The compound functions primarily as a Lewis acid catalyst in Friedel-Crafts reactions and as a coagulating agent in potable and wastewater clarification systems. Powder and granulate formats dominate industrial chemical manufacturing where precise dosing and storage stability matter, while liquid and solution forms lead water treatment applications because of ease of handling and rapid dispersion in flocculation basins. Municipalities represent the most concentrated end-user pool, though research institutions command premium pricing for ultra-high-purity batches.
EPA Office of Water enforces Maximum Contaminant Level Goals that constrain residual aluminium in finished drinking water, compelling coagulant suppliers to refine product grades. ECHA administers REACH registration dossiers that govern import and manufacture thresholds across European Economic Area member states. China's MEE implements discharge permits for industrial wastewater that specify allowable metal concentrations, shaping local formulation demand. Stakeholders must track evolving purity standards and certification reciprocity agreements to secure long-term offtake contracts without geographic blind spots.
Market Dynamics
Municipal water utilities are consolidating supplier bases around ISO 9001 certification, forcing material flows through qualified tolling networks and compressing margins for unqualified traders.
Growth Catalysts
- EPA drinking water standards:Maximum Contaminant Level Goals for residual aluminium compel utilities to upgrade coagulant specifications, expanding procurement of high-purity material.
- Friedel-Crafts catalysis:Pharmaceutical and fine chemical manufacturers rely on anhydrous aluminium chloride for acylation and alkylation reactions, sustaining steady industrial offtake.
- China municipal wastewater expansion:Provincial governments under MEE discharge permit mandates are building tertiary treatment capacity, anchoring regional volume demand.
Market Restraints
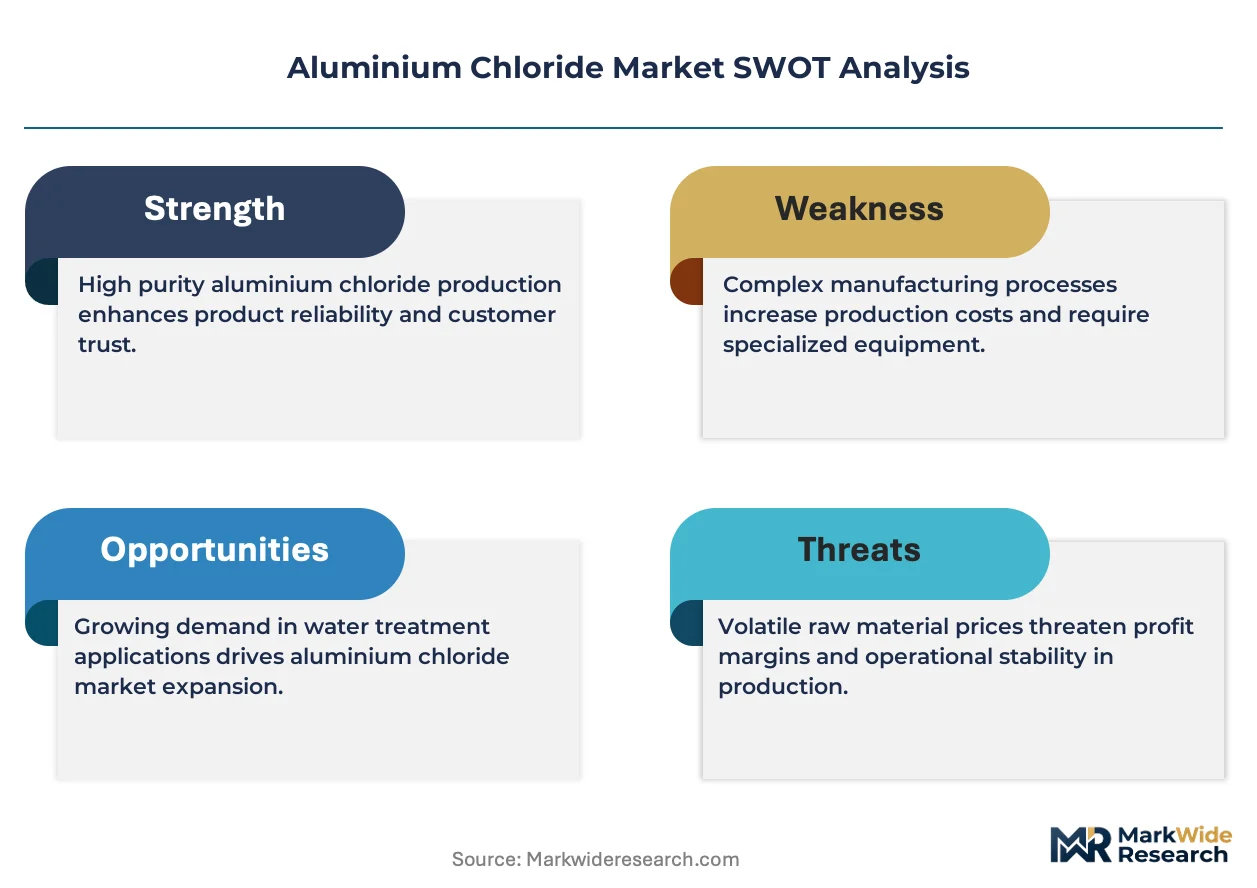
- Chlor-alkali feedstock volatility:Caustic soda and chlorine prices fluctuate with energy costs, squeezing conversion margins for non-integrated producers.
- REACH registration friction:ECHA dossier requirements impose compliance costs and timeline risks for European market entrants without existing registrations.
- Polyaluminium chloride substitution:Pre-hydrolyzed coagulants offer easier handling and lower dosing requirements in some water treatment applications.
Strategic Opportunities
- Pharmaceutical-grade anhydrous material:European drug precursor markets command premium pricing for ultra-high-purity batches with dedicated supply chains.
- India water infrastructure buildout:Smart Cities Mission and AMRUT 2.0 schemes are expanding municipal treatment capacity in tier-2 urban centers.
- Digital dosing systems:Integration with automated flocculation control platforms creates service revenue streams beyond commodity chemical sales.
Industry Challenges
- ISO 9001 certification timelines:Municipal contract eligibility now requires documented quality systems, extending supplier onboarding cycles by 12-18 months.
- Hygroscopic material handling:Anhydrous product requires moisture-controlled storage and specialized transport equipment, complicating logistics for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminium Chloride Market |
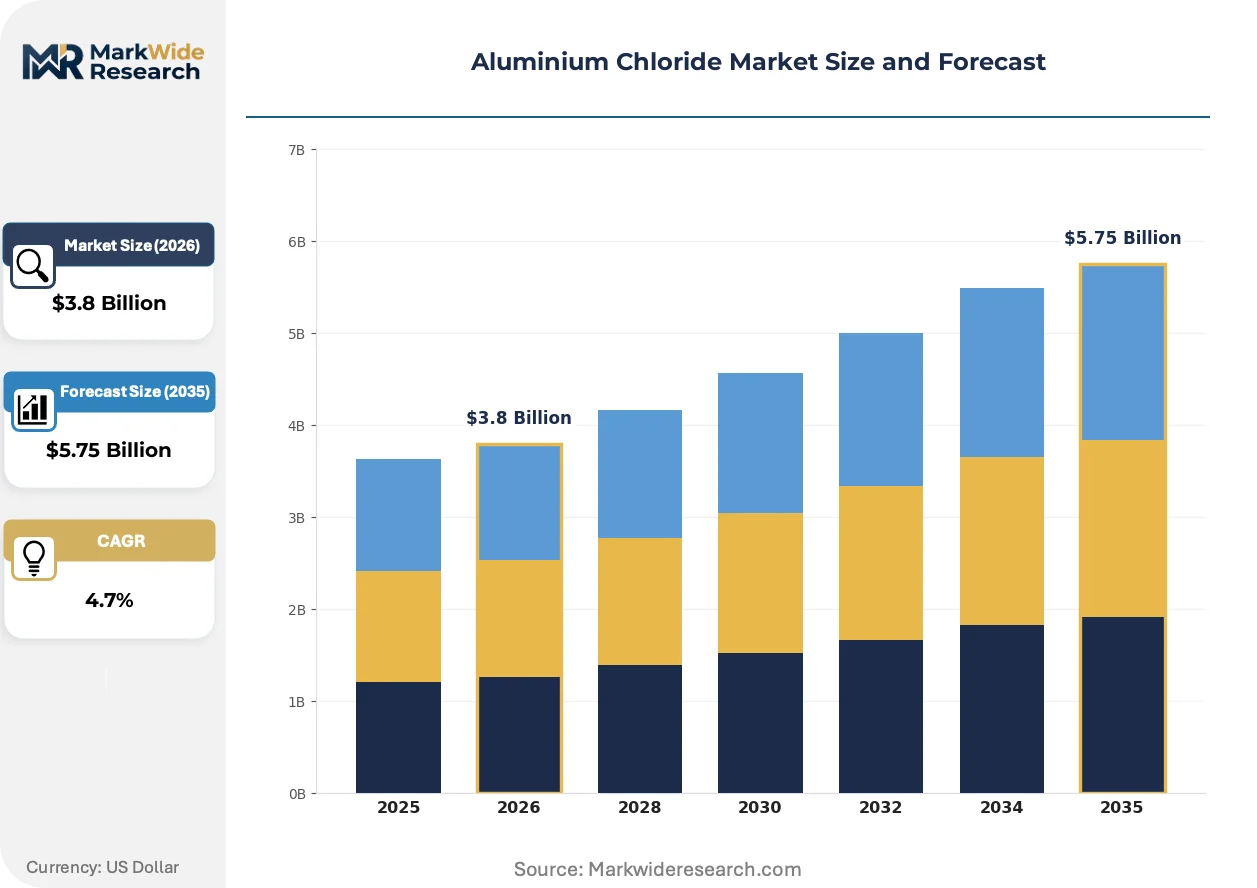
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Granulate, Solution Application: Water Treatment, Chemical Manufacturing, Pharmaceuticals, Cosmetics End User: Municipalities, Industrials, Research Institutions, Laboratories Packaging Type: Drums, Bags, Containers, Bulk |
| Companies Covered | BASF SE, Gujarat Alkalies and Chemicals Ltd, Solvay S.A., Aditya Birla Chemicals, DCM Shriram, Nippon Light Metal Co., Ltd., Gujarat Fluorochemicals, Kanto Denka Kogyo Co., Ltd., Dongying City Longxing Chemical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminium Chloride Market Emerging Trajectories
Process intensification and regulatory digitization are compressing traditional supply arrangements, while buyer consolidation is rewriting procurement terms across municipal and industrial segments.
Membrane bioreactor pre-treatment systems are displacing conventional coagulation-flocculation trains in advanced wastewater reuse schemes. Singapore's NEWater facilities and California's indirect potable reuse plants have adopted ceramic ultrafiltration with reduced chemical dependency. This architecture is displacing bulk coagulant volumes in high-specification applications while creating demand for precision-dosed specialty grades.
China's MEE is tightening industrial wastewater discharge permits with real-time monitoring mandates. Facilities must now report metal concentrations continuously rather than through periodic sampling. Chemical manufacturers in the Yangtze River Delta are responding by reformulating process streams and investing in closed-loop brine recovery systems to meet the new thresholds.
Consolidated procurement through regional water authority frameworks is compressing supplier lists in the United Kingdom and Netherlands. Single-source contracts covering multiple treatment works are replacing plant-level purchasing decisions. This concentration is visible most acutely in England, where Ofwat-regulated water companies have reduced active chemical suppliers by 40 percent since 2019.
Aluminium Chloride Market Segmentation
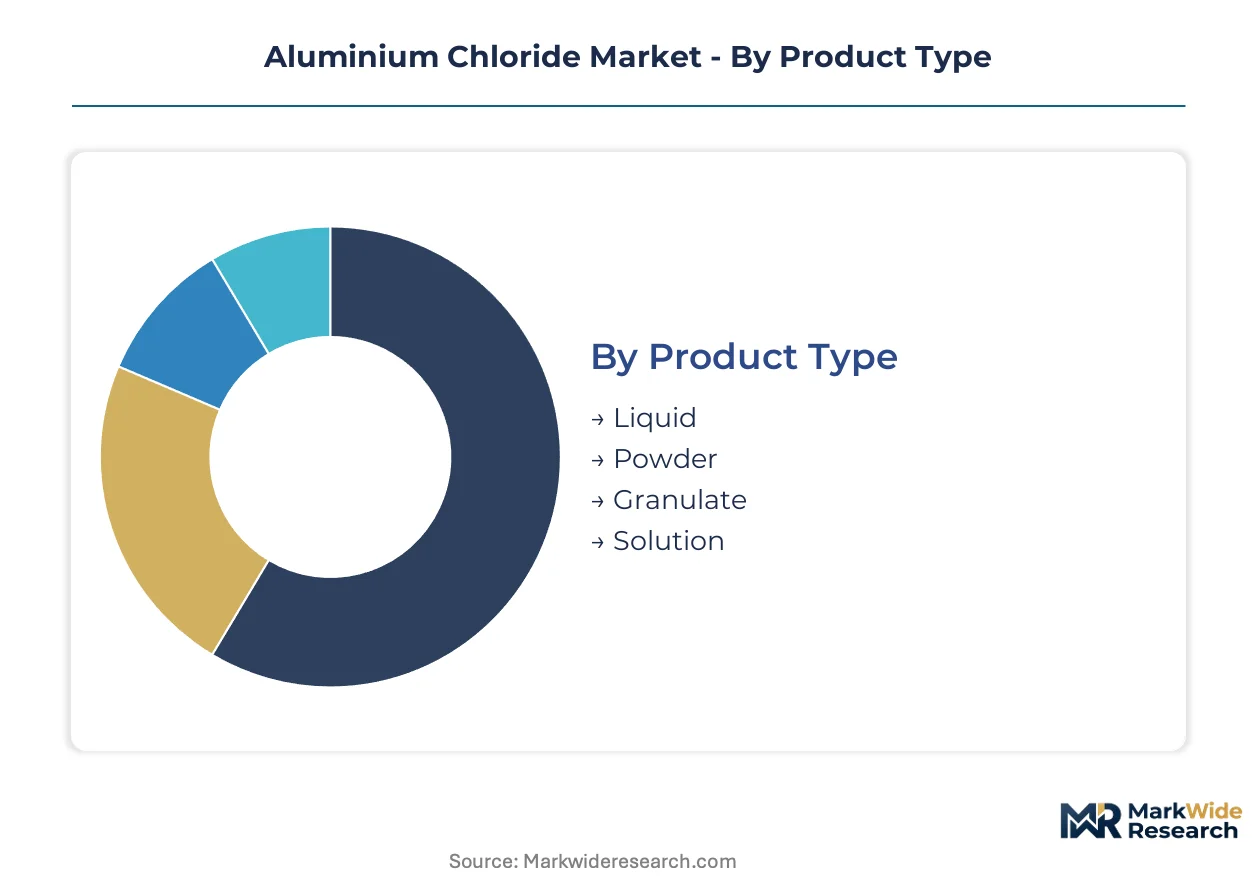
Aluminium chloride procurement patterns diverge sharply across product formats and end-use specifications. Water treatment utilities prioritize handling convenience and rapid dispersion, while chemical manufacturers demand precise stoichiometry and storage stability.
Product Type:
Powder and granulate formats dominate export-oriented supply chains serving chemical manufacturing hubs, whereas liquid and solution forms concentrate in domestic municipal water treatment markets.
- Liquid:Pre-dissolved aqueous solutions enable rapid dispersion in flocculation basins without on-site dissolution equipment. Municipal water utilities across China, India, and the United States favor this format for dosing precision and reduced operator exposure. EPA Maximum Contaminant Level Goals for residual aluminium intensify demand for standardized concentration grades.
- Powder:Fine particulate material offers extended shelf stability and flexible reconstitution ratios for industrial chemical synthesis. Pharmaceutical and fine chemical manufacturers in Germany, Switzerland, and Japan specify anhydrous powder for Friedel-Crafts catalysis with tight moisture specifications.
- Granulate:Free-flowing crystalline form reduces dust generation during handling and supports automated feeding systems. Regional chemical distributors in India and Southeast Asia stock granulate for mid-scale industrial accounts.
- Solution:Dilute aqueous preparations serve small-scale water treatment facilities and mobile treatment units. Rural municipalities in Brazil and South Africa procure solution formats to bypass capital-intensive dissolution infrastructure.
Liquid commands the established base. The steepest expansion runs through powder.
Application:
Water treatment applications generate the highest volume throughput, while pharmaceutical and cosmetic segments extract premium pricing through purity-driven procurement.
- Water Treatment:Coagulation and flocculation processes in potable and wastewater clarification consume bulk volumes. China's MEE discharge permit mandates and EPA drinking water standards compel utilities to upgrade from commodity grades to certified coagulant specifications. Municipal procurement consolidation favors suppliers with documented quality systems.
- Chemical Manufacturing:Lewis acid catalysis in Friedel-Crafts acylation and alkylation reactions sustains steady industrial offtake. European fine chemical producers specify anhydrous material with sub-ppm iron content for electronic-grade intermediate synthesis.
- Pharmaceuticals:Drug precursor synthesis and active pharmaceutical ingredient manufacturing require pharmaceutical-grade anhydrous batches. Swissmedic and EMA guidelines on residual catalyst levels shape purity specifications for European drug manufacturers.
- Cosmetics:Antiperspirant active production and personal care formulation utilize reagent-grade material. ANVISA and Health Canada cosmetic ingredient regulations govern impurity thresholds for topical applications.
Water Treatment anchors volume demand. Pharmaceuticals delivers the steepest margin expansion.
End User:
Procurement scale separates concentrated municipal buyers from fragmented industrial accounts, with research institutions commanding the smallest volumes at highest unit prices.
- Municipalities:Regional water authorities and municipal utilities purchase bulk coagulant under multi-year framework agreements. Ofwat-regulated water companies in England and Dutch regional water boards have compressed supplier lists by 40 percent since 2019.
- Industrials:Chemical manufacturers, metal finishers, and food processors procure variable grades based on process requirements. Yangtze River Delta chemical clusters under China's MEE real-time monitoring mandates are reformulating process streams.
- Research Institutions:Universities and national laboratories source ultra-high-purity batches for analytical standards and reaction mechanism studies. Limited volumes trade at 3-5x industrial grade pricing.
- Laboratories:Quality control and analytical testing operations consume reagent-grade material in gram-to-kilogram quantities. ISO 17025 accreditation requirements shape supplier qualification protocols.
Municipalities dominate procurement tonnage. Industrials exhibit the most volatile demand swings.
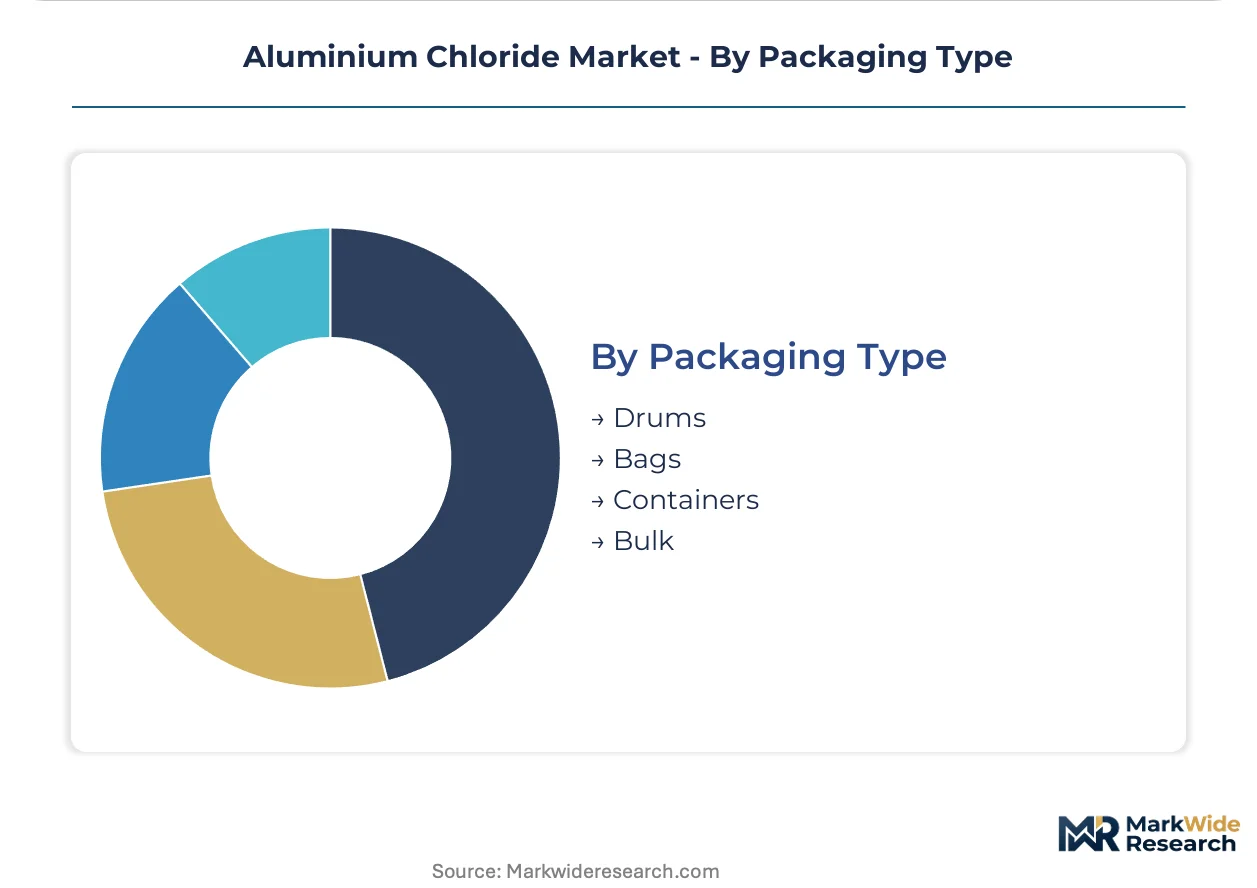
Packaging Type:
Logistics economics favor bulk delivery for high-volume municipal contracts, while drum and bag formats serve dispersed industrial and laboratory accounts.
- Drums:Steel and polyethylene drums protect hygroscopic anhydrous material from moisture ingress during transport. Pharmaceutical and fine chemical manufacturers in Japan and South Korea specify nitrogen-purged drums for sensitive applications.
- Bags:Multi-layer laminated bags with moisture barriers serve mid-scale industrial users. Indian chemical distributors package granulate in 25-kg bags for tier-2 urban manufacturing clusters.
- Containers:Intermediate bulk containers enable pump-off delivery for liquid formulations. California and Singapore water reuse facilities deploy containerized dosing systems.
- Bulk:Tanker truck and railcar delivery minimizes unit logistics costs for high-volume municipal offtake. China's provincial wastewater expansion projects anchor regional bulk procurement.
Bulk captures the municipal anchor. Drums deliver the most stable pricing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical handling infrastructure underwrites Europe's import gateway for chlor-alkali feedstocks, while China's Yangtze River Delta pipeline networks anchor Asia's production concentration.
United States
EPA drinking water standards and Maximum Contaminant Level Goals for residual aluminium compel municipal utilities to upgrade coagulant specifications. California's indirect potable reuse plants and Singapore-modeled facilities in Texas are adopting advanced treatment trains. The Gulf Coast petrochemical corridor sustains chlor-alkali integration for domestic chemical-grade production.
China
MEE discharge permit mandates with real-time monitoring requirements are reformulating industrial process streams across chemical clusters. Yangtze River Delta manufacturers are investing in closed-loop brine recovery systems to meet tightened metal concentration thresholds. Provincial wastewater expansion projects in Jiangsu and Zhejiang anchor bulk coagulant procurement volumes.
Germany
ECHA REACH registration dossiers govern import thresholds and impose compliance timelines for market entrants. The Rhine-Ruhr chemical corridor maintains integrated chlor-alkali production serving pharmaceutical-grade anhydrous demand. BASF SE's Ludwigshafen complex exemplifies backward integration into feedstock control.
India
Smart Cities Mission and AMRUT 2.0 schemes are expanding municipal treatment capacity in tier-2 urban centers beyond metro cores. BIS quality certification requirements are reorganizing supplier eligibility for government contracts. Gujarat's Dahej chemical complex anchors western India production through captive caustic soda and chlorine supply.
Japan
METI industrial standards and JIS specifications govern reagent-grade material for pharmaceutical and electronic applications. Kanto and Kansai manufacturing belts sustain precision chemical synthesis demand. Nippon Light Metal and Kanto Denka Kogyo occupy positions within the domestic specialty chemicals tier.
Aluminium Chloride Market Vendor Landscape
Listed leaders compete with private specialists across certification and integration dimensions. The vendor base stratifies around three tiers: integrated chlor-alkali producers with captive feedstock, tolling-dependent traders seeking ISO 9001 qualification, and pharmaceutical-grade specialists commanding premium positioning. Strategic moves concentrate on backward integration into chlorine supply and tolling network expansion to secure municipal contract eligibility.
Among European-based chemical conglomerates, BASF SE and Solvay S.A. exemplify divergent specialization strategies—BASF leveraging upstream chlor-alkali control while Solvay occupies the pharmaceutical-grade anhydrous niche. Gujarat Alkalies and Chemicals Ltd represents the integrated Asian producer archetype with captive feedstock infrastructure. These three anchors illustrate how geographic feedstock access and certification tier determine competitive positioning.
| Leading Market Players |
|---|
| BASF SE |
| Gujarat Alkalies and Chemicals Ltd |
| Solvay S.A. |
| Aditya Birla Chemicals |
| DCM Shriram |
| Nippon Light Metal Co., Ltd. |
| Gujarat Fluorochemicals |
| Kanto Denka Kogyo Co., Ltd. |
| Dongying City Longxing Chemical Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Forty-five to sixty days of inventory cover separates qualified tolling networks from spot-market traders, compressing pricing power toward ISO-certified manufacturers with documented quality systems. Municipal procurement consolidation across England and the Netherlands has shifted volume discounts toward framework-contract holders with captive chlor-alkali feedstock.
Pricing Analysis
Three-tier pricing structure across pharmaceutical-grade, certified coagulant, and commodity industrial levels governs contract negotiations. Price differentiation rests on ISO 9001 certification status and captive chlorine supply integration. Cost compression in the commodity tier is intensifying because polyaluminium chloride substitution erodes volume offtake. Municipal utilities exhibit the highest price sensitivity, while pharmaceutical manufacturers accept premium positioning for sub-ppm iron specifications.
Supply Chain Analysis
Strategic stockpiling of anhydrous material dominates pharmaceutical-grade procurement, whereas just-in-time liquid delivery serves municipal water utilities with predictable dosing schedules. Supply concentrates in China, Germany, and India, with the Yangtze River Delta and Gujarat's Dahej complex anchoring Asian production. Raw material flows draw from chlor-alkali caustic soda, chlorine gas, and aluminium metal feedstock. Single-source vulnerability runs through European REACH-registered import channels. Distribution runs through regional tolling networks for municipal contracts and direct mill-to-plant arrangements for chemical manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across certification tiers creates white-space opportunities as municipal procurement consolidation displaces unqualified traders. Smart Cities Mission infrastructure buildout in tier-2 Indian urban centers generates niche entry points for compliant suppliers.
For Market Incumbents: Shield municipal contract positions by accelerating ISO 9001 certification timelines for tolling partners before procurement windows close. Deepen backward integration into chlorine supply to offset caustic soda price volatility squeezing non-integrated competitors. Polyaluminium chloride substitution threat demands premium-grade differentiation through pharmaceutical-tier positioning.
For New Entrants and Emerging Players: Anchor in India's AMRUT 2.0 tier-2 expansion corridors where incumbent supplier lists remain open. Digital dosing system integration offers service-revenue attachment beyond commodity sales. Target pharmaceutical-grade anhydrous niches in European drug precursor markets where certification barriers limit competition.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because municipal procurement frameworks are compressing supplier counts toward integrated chlor-alkali producers. Acquisition targets with captive feedstock infrastructure and existing REACH dossiers command defensive positioning value. Monitor China's MEE real-time discharge monitoring rollout as inflection signal for reformulation demand shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chlor-Alkali Feedstock | BASF SE's Ludwigshafen complex demonstrates margin protection through captive chlorine and caustic soda supply. |
| ISO 9001 Certification Investment | Municipal water authorities in England reduced active chemical suppliers by 40 percent since 2019, favoring documented quality systems. |
| Pharmaceutical-Grade Capacity Expansion | Solvay S.A. commands premium positioning in European drug precursor markets through ultra-high-purity anhydrous production. |
| Digital Dosing System Integration | Automated flocculation control platforms in California and Singapore create recurring service revenue beyond commodity chemical sales. |
| Regional Tolling Network Expansion | Gujarat Alkalies and Chemicals Ltd leverages Dahej complex infrastructure to supply western India municipal expansion projects. |
Methodological Framework
Operator-level perspectives from water treatment plant managers, municipal procurement officers, chlor-alkali production directors, and pharmaceutical chemical synthesis leads anchored the qualitative base. Primary interview findings triangulated against customs trade data, SEC 10-K filings from listed chemical producers, ECHA REACH registration dossiers, and China MEE discharge permit records. Bottom-up volume estimates from end-use application splits reconciled with top-down market sizing across grade tiers and regional production hubs.
Sensitivity analysis across feedstock price scenarios and regulatory compliance timelines shaped the projection framework. Segmentation modeling incorporated product format, application end-use, purity grade tier, packaging type, and regional regulatory cluster dimensions. CAGRs derived from weighted average of historical volume trends and forward-looking capacity expansion announcements. Chlor-alkali margin compression indices and municipal wastewater capital expenditure pipelines served as industry-specific forecast inputs throughout the modeling period.
Decision-makers should treat outputs as directional under stable chlor-alkali feedstock pricing and unchanged REACH registration requirements; material deviation would warrant model refresh. Forecasts reflect assumptions about continued municipal procurement consolidation and sustained pharmaceutical-grade premium positioning. Revision becomes warranted when polyaluminium chloride substitution rates or China's MEE enforcement intensity crosses thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Brazil Methanol Market
Chemicals
Zinc Chemicals Market
Chemicals
Hydrogen Chloride Market
Chemicals
Sodium Azide Market
Chemicals
Benzhydrol Market
Chemicals
Electronic Grade Hydrofluoric Acid Market
Chemicals
South Korea Methanol Market
Chemicals
Sodium Methoxide Market
Chemicals
Global Syringaldehyde Market
Chemicals
Global P-Phenylenediamine Market
Chemicals
Nonaisoprenol Market
Chemicals
SLS and LABSA Market
Chemicals
Heptaldehyde Market
Chemicals
Catechol Market
Chemicals
North America Methanol Market
Chemicals
Di Nitro Toluene Market