
 United States Aluminum Extrusion Market | 2026-2036
United States Aluminum Extrusion Market Size, Share, and Industry Trends Forecast 2026-2036
United States Aluminum Extrusion Market Intelligence
IRA domestic content rules is decoupling low-cost import dependence from project eligibility for federal tax credits. Hydro Extrusion USA, LLC leverages its vertically integrated billet supply to secure qualification under Buy America provisions. Bonnell Aluminum sustains cost competitiveness through captive recycling and regional mill network density. Western Extrusions Corp. anchors its position in precision tubing for medical and semiconductor equipment end-uses.
United States aluminum extrusion refers to the forced compression of aluminum alloy billets through hardened steel dies to produce continuous profiles with specific cross-sectional geometries, typically achieving tolerances of ±0.005 inches in precision grades and serving as lightweight structural members across transportation and building systems. The process yields shapes, sheets, bars, and tubes with strength-to-weight ratios superior to steel at one-third the density, making extrusion indispensable for crash-management structures and thermal management components. Structural applications within the construction and automotive end-user segments command the deepest margin pools due to engineering certification requirements and long-term supply agreements, while thermal break technology is displacing conventional framing in high-performance building envelopes. Aerospace-grade shapes and tubes remain concentrated among a qualified supplier base with NADCAP and AS9100 certifications, limiting competitive entry despite premium pricing.
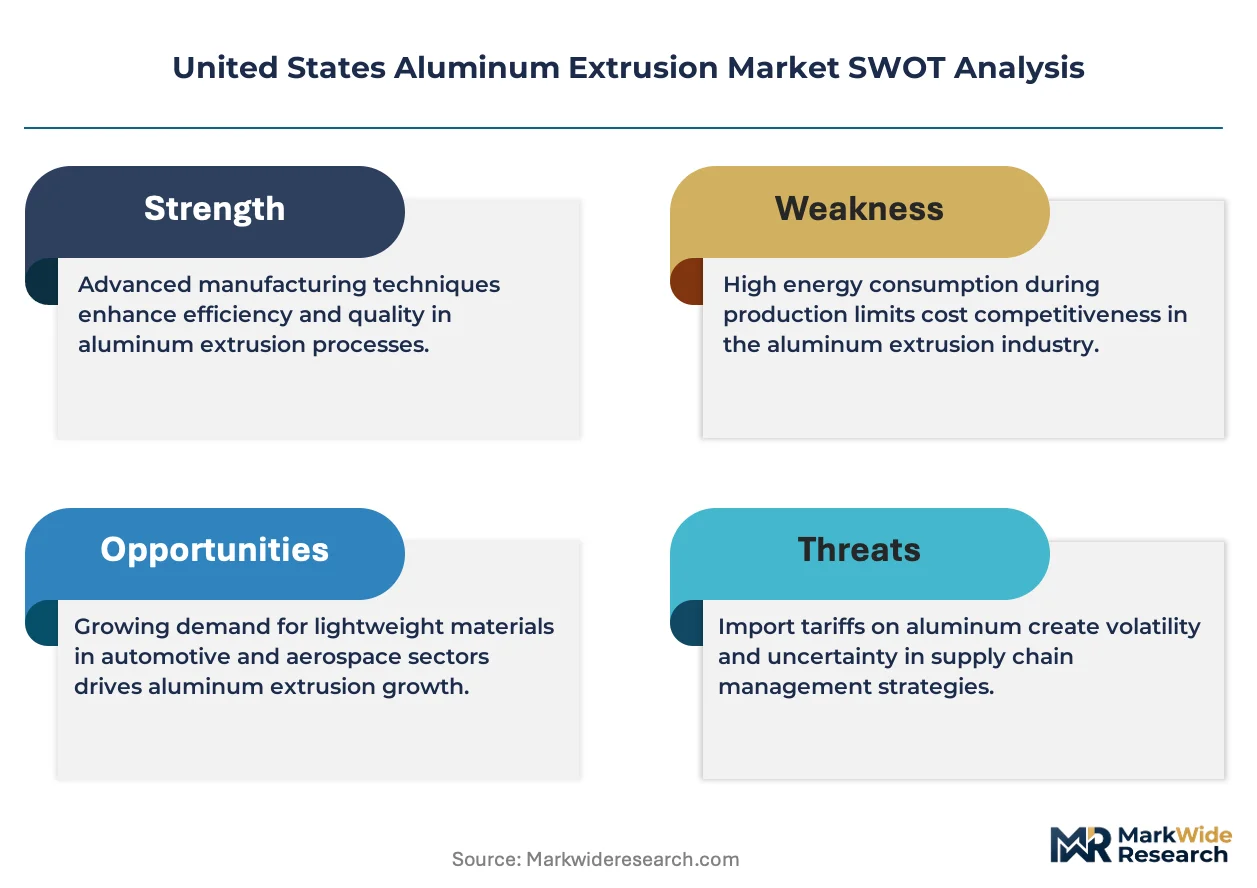
FAA airworthiness directives, EPA automotive emissions thresholds, and OSHA workplace exposure limits collectively elevate compliance costs and qualify the supplier base for safety-critical and environmentally regulated applications. NHTSA crashworthiness standards explicitly incentivize aluminum-intensive vehicle architectures, directly translating regulatory stringency into extrusion volume commitments from Detroit Three and transplant automakers. Stakeholders must monitor pending revisions to Buy America thresholds and alloy-specific tariff classifications, as these will determine whether domestic melting and casting capacity expansion outpaces import substitution.
Market Dynamics
IRA domestic content thresholds are forcing extruders to requalify supply chains around domestic melting and casting capacity, compressing the qualification window for imported billet while automakers accelerate aluminum-intensive platform commitments under NHTSA fuel economy mandates.
Growth Catalysts
- Automotive Lightweighting Mandates:NHTSA crashworthiness standards explicitly reward aluminum-intensive vehicle architectures, locking Detroit Three and transplant OEMs into multi-year extrusion volume commitments for crash-management structures and battery enclosures.
- Buy America Provisions:The Inflation Reduction Act's domestic content rules tie federal tax credit eligibility to domestic melting and casting, redirecting procurement toward qualified domestic billet suppliers and reshaping competitive positioning.
- Thermal Break Technology:Polyamide thermal barrier systems are displacing conventional aluminum framing in high-performance building envelopes across the Great Lakes manufacturing corridor, driven by ASHRAE 90.1 energy code adoption.
Market Restraints
- Primary Aluminum Price Volatility:London Metal Exchange price swings and Midwest premium spikes compress margin predictability for non-integrated extruders lacking captive smelting or long-term tolling arrangements.
- Qualified Supplier Concentration:Aerospace-grade shapes remain captive to NADCAP and AS9100 certified facilities concentrated in California, Texas, and Ohio, limiting competitive entry despite premium pricing availability.
- Steel Substitution Threat:Advanced high-strength steel grades and carbon fiber reinforced polymers compete for mass-critical automotive applications where aluminum's 33% density advantage does not justify cost premiums.
Strategic Opportunities
- Semiconductor Equipment Precision Tubing:Vacuum chamber and gas delivery systems for domestic fab construction under the CHIPS Act create demand for ultra-high-purity extrusions with sub-micron surface finish requirements.
- Gulf Coast Petrochemical Cluster Expansion:Process heat exchanger and pressure vessel applications around Houston and Corpus Christi offer white space for corrosion-resistant alloy extrusions in sour gas handling equipment.
- Closed-Loop Recycling Integration:Captive remelt and direct-chill casting capabilities can secure scrap price arbitrage and carbon intensity advantages under emerging EPA greenhouse gas reporting frameworks for Scope 3 emissions.
Industry Challenges
- Die Design and Maintenance Expertise Gap:H13 steel die engineering and nitriding process control require specialized tooling knowledge that retiring workforce cohorts are not fully transferring to replacement hires.
- Multi-Axis CNC Fabrication Capex Burden:Post-extrusion precision machining for medical device and semiconductor end-uses demands five-axis machining centers and CMM inspection equipment exceeding $2 million per cell.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Aluminum Extrusion Market |
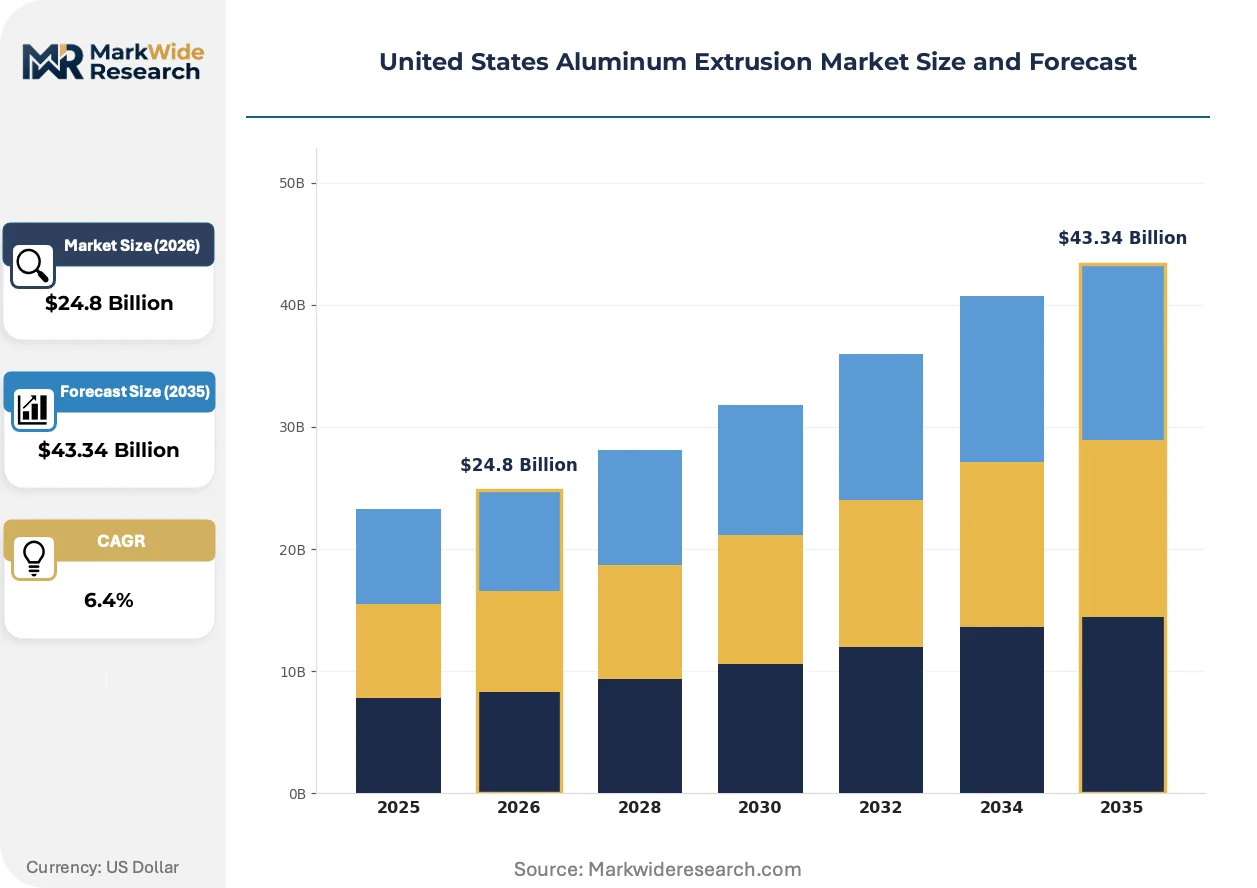
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $43.34 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shapes, Sheets, Bars, Tubes End User: Construction, Automotive, Aerospace, Consumer Goods Application: Structural, Thermal Break, Decorative, Electrical Technology: Extrusion Press, Hydrostatic Extrusion, Hot Extrusion, Cold Extrusion |
| Companies Covered | Universal Alloy Corp., UACJ Automotive Whitehall Industries, Inc., Hydro Extrusion USA, LLC, Erbsloeh Aluminum Solutions, Inc., Bonnell Aluminum, Western Extrusions Corp., Hydro Extrusion Portland, Inc., Tower Extrusions, Ltd., Crystal Finishing Systems, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Aluminum Extrusion Market Strategic Shifts & Innovations
Extrusion process intelligence and alloy formulation advances are compressing development cycles while regulatory carbon accounting and end-use certification requirements reshape how value is captured across the supply chain.
Hybrid aluminum-lithium alloys with scandium micro-additions are modularizing structural member design for electric vehicle battery trays and aerospace floor beams. Tier 1 suppliers to Rivian and Lucid Motors have adopted these alloys at pilot scale since 2023. The technology is modularizing what were previously welded assemblies into single-extrusion components, reducing part count and joint fatigue risk.
The EPA's proposed greenhouse gas emissions standards for light-duty vehicles through 2032 are accelerating aluminum content targets at Ford, General Motors, and Stellantis. These mandates translate directly into extrusion volume commitments for body-in-white and closure panel applications. The Detroit Three are responding by pre-qualifying domestic billet sources and locking in multi-year offtake agreements with qualified extruders.
Consolidated procurement desks at national homebuilders and multi-family developers are compressing supplier qualification cycles and demanding mill-direct volume pricing previously reserved for distributor channels. Lennar, D.R. Horton, and PulteGroup have centralized fenestration and structural framing procurement, displacing regional distributor relationships. This concentration is most visible in the Sun Belt residential construction markets where build-to-rent projects specify thermal break extrusions at volume scale.
United States Aluminum Extrusion Market Segmentation
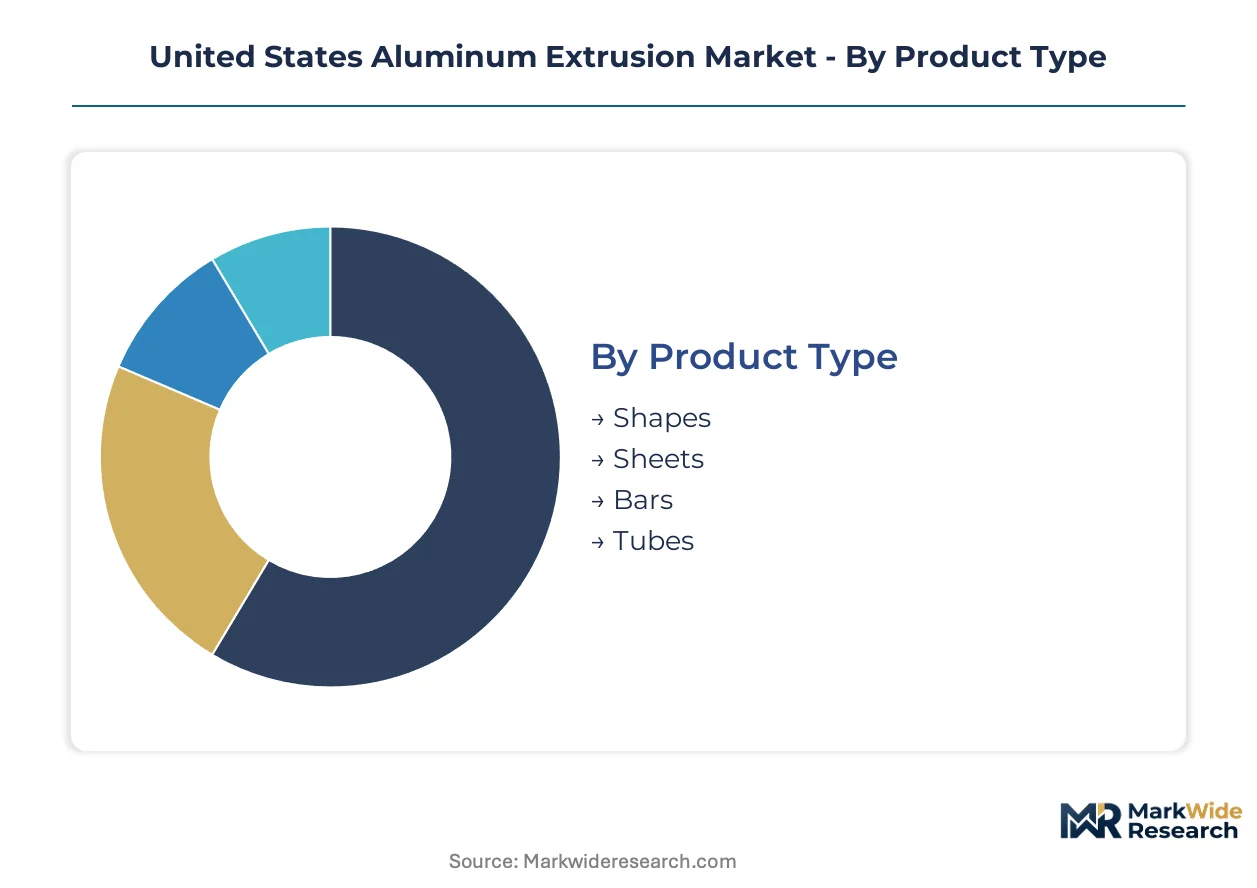
Segmentation in the United States aluminum extrusion market reveals how certification requirements and performance specifications fragment procurement across end-use verticals. Each dimension carries distinct margin profiles and technical barriers that determine competitive positioning.
Product Type:
NADCAP and AS9100 certifications govern aerospace-grade tubes and shapes, while ASTM B221 and ASTM B429 standards apply to structural extrusions for construction and automotive applications.
- Shapes:Complex cross-sectional profiles including I-beams, channels, and angles achieve ±0.005 inch tolerances in precision grades. Demand concentrates in automotive crash-management structures across Michigan and Ohio under NHTSA crashworthiness mandates.
- Tubes:Seamless and porthole extrusions serve vacuum chamber systems for semiconductor fabrication and medical gas delivery equipment. The CHIPS Act domestic fab construction around Phoenix and Austin is accelerating orders for ultra-high-purity 6061 and 6063 alloys with sub-micron surface finishes.
- Sheets:Wide-format extruded plate serves thermal management substrates and electrical busbar applications. Data center power distribution projects in Northern Virginia and Dallas-Fort Worth specify these grades.
- Bars:Solid round, square, and hexagonal stock supply CNC machining operations for industrial equipment and consumer hardware. Regional service centers in Chicago and Los Angeles inventory these for just-in-time delivery.
Leading the category by volume: Shapes. Growing fastest: Tubes.
End User:
Customer concentration and contract duration vary sharply across verticals, with automotive and aerospace locking in multi-year offtake agreements while construction remains project-tender driven.
- Automotive:OEM direct procurement of body-in-white and battery enclosure extrusions operates on three-to-five-year platform cycles. The Detroit Three have pre-qualified domestic billet sources to secure IRA tax credit eligibility.
- Construction:Thermal break window and curtain wall systems dominate commercial building specifications in the Great Lakes corridor. ASHRAE 90.1 energy code adoption is displacing conventional framing.
- Aerospace:Boeing and Lockheed Martin supply chains require NADCAP heat treatment and AS9100 quality systems. Qualified facilities concentrate in California, Texas, and Ohio.
- Consumer Goods:Furniture, sporting equipment, and appliance manufacturers source standard 6063 and 6061 grades through distributor channels with shorter lead times.
Highest margin concentration: Aerospace. Expanding most quickly: Automotive.
Application:
Performance tier and pricing stratification follow functional requirements, with structural and thermal break applications commanding engineering certification premiums over decorative and electrical grades.
- Structural:Load-bearing members for building frames and vehicle chassis require weldability certification and fatigue testing. Gulf Coast petrochemical projects around Houston specify corrosion-resistant 5xxx and 7xxx series alloys.
- Thermal Break:Polyamide-insulated profiles achieve U-factors below 0.30 for high-performance building envelopes. National homebuilder consolidation is compressing supplier qualification cycles.
- Decorative:Anodized and powder-coated finishes serve architectural trim and consumer product aesthetics. Color matching and lot consistency drive supplier selection.
- Electrical:Busbar and heat sink extrusions prioritize electrical conductivity and thermal dissipation. Data center and EV charging infrastructure projects specify these grades.
Deepest margin pool: Structural. Gaining share fastest: Thermal Break.
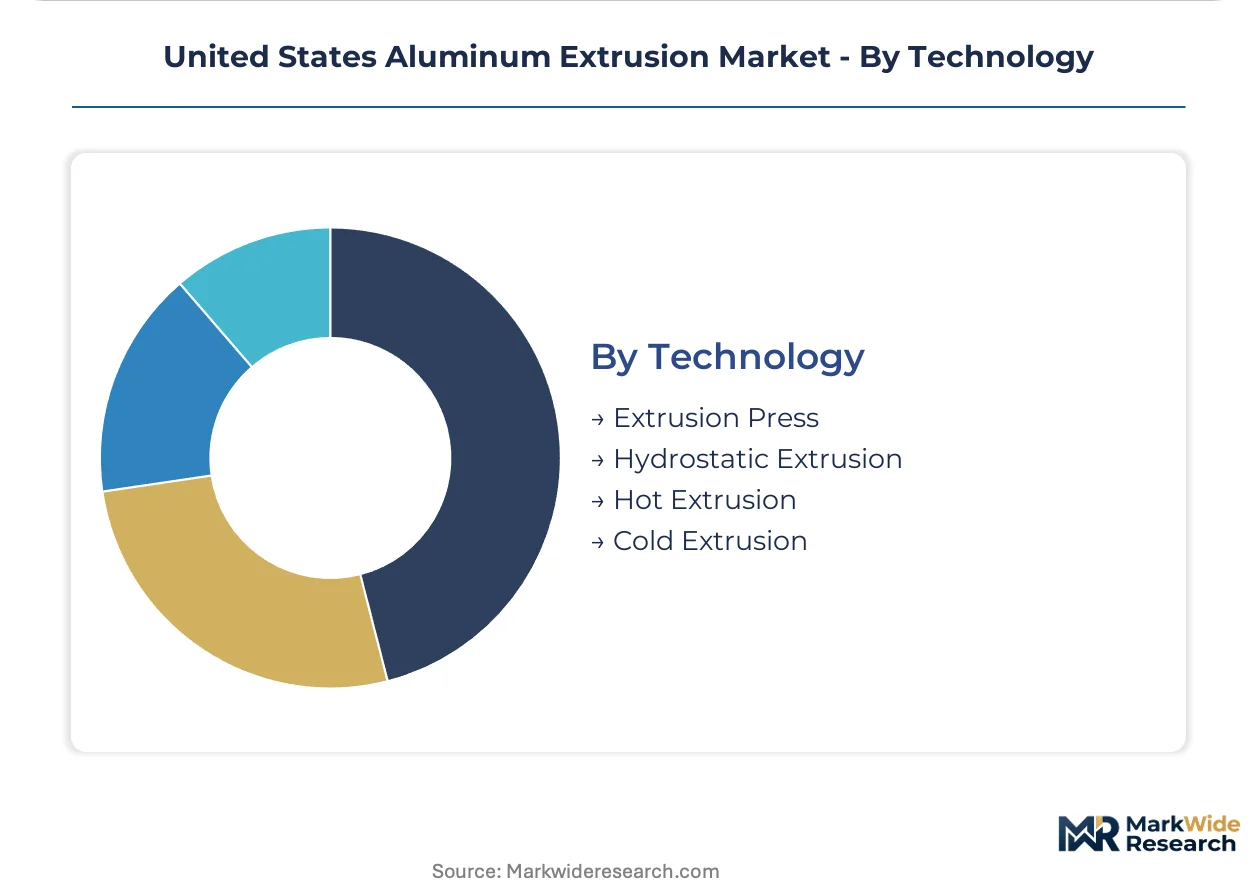
Technology:
Capital intensity and throughput economics separate process categories, with conventional extrusion press operations achieving scale advantages while specialized methods capture premium niches.
- Extrusion Press:Direct and indirect press configurations dominate commercial production with outputs exceeding 50 million pounds annually at integrated facilities. Bonnell Aluminum and Hydro Extrusion USA operate the largest installed bases.
- Hot Extrusion:Elevated billet temperatures above 350°C enable complex shape formation in 2xxx, 6xxx, and 7xxx alloys. Automotive structural components rely on this method.
- Hydrostatic Extrusion:Fluid pressure transmission eliminates friction and enables extreme reduction ratios for aerospace-grade tubes. Limited qualified capacity exists domestically.
- Cold Extrusion:Near-net-shape forming at ambient temperatures serves high-volume fastener and precision component applications with superior surface finishes.
Widest deployment: Extrusion Press. Steepest expansion trajectory: Hydrostatic Extrusion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal Opportunity Zones and state-level manufacturing tax credits are concentrating extrusion capacity in the Great Lakes corridor and Gulf Coast petrochemical belt, with IRA domestic content rules reinforcing geographic clustering around qualified billet supply.
Great Lakes Manufacturing Corridor
Automotive lightweighting programs at Ford, General Motors, and Stellantis drive structural extrusion demand for body-in-white and battery enclosures across Michigan and Ohio. NHTSA crashworthiness standards lock OEMs into multi-year volume commitments with qualified suppliers. Detroit and Toledo anchor the highest-density extrusion consumption zone, with Tier 1 fabricators co-locating near final assembly plants.
Gulf Coast Petrochemical Cluster
Process heat exchanger and pressure vessel applications around Houston and Corpus Christi create demand for corrosion-resistant 5xxx and 7xxx series alloys in sour gas handling equipment. OSHA process safety management requirements elevate qualification barriers for offshore-capable suppliers. The Port of Houston facilitates direct billet import for non-integrated extruders serving energy sector contracts.
Southwest Border Region
Maquiladora automotive assembly in Nuevo León and Chihuahua pulls precision extrusions from El Paso and McAllen facilities seeking tariff-advantaged cross-border logistics. CBP rules of origin enforcement determines eligibility for USMCA duty treatment. Laredo and Eagle Pass service corridors concentrate customs-bonded warehousing for just-in-time delivery to Monterrey assembly plants.
Pacific Northwest
Aerospace-qualified extrusions for Boeing Commercial Airplanes concentrate around Seattle-Tacoma with NADCAP heat treatment and AS9100 certification requirements limiting supplier entry. FAA airworthiness directives govern material traceability from melt to finished section. Auburn and Kent host the densest concentration of hydrostatic extrusion capacity for extreme-reduction-ratio aerospace tubing.
Southeast Growth Belt
Mercedes-Benz, BMW, and Hyundai-Kia transplant assembly in Alabama, Georgia, and Tennessee generates structural extrusion demand independent of Detroit Three supply chains. State-level megasite incentives attract downstream fabrication investments. Chattanooga and Montgomery emerge as secondary extrusion consumption nodes as OEMs diversify geographic risk.
United States Aluminum Extrusion Market Key Industry Players
Vertically integrated domestic producers anchor the qualified-supplier tier; regional specialists with captive recycling hold cost-competitive positions in construction-grade segments. Market structure bifurcates between NADCAP-certified aerospace facilities and high-volume automotive suppliers pre-qualified under IRA domestic content rules. Three archetypes dominate: integrated primary-to-extrusion operators, regional multi-press fabricators with remelt capabilities, and precision-tubing specialists serving semiconductor and medical end-uses. Capacity expansion and strategic M&A around billet supply security represent the dominant competitive moves as extruders secure qualification under Buy America thresholds.
Among the integrated operators, Hydro Extrusion USA, LLC exemplifies the vertically integrated archetype with captive billet supply securing IRA tax credit eligibility, while Bonnell Aluminum represents the regional fabricator model with dense mill networks and closed-loop recycling economics. Western Extrusions Corp. occupies the precision-specialist position in ultra-high-purity tubing for semiconductor and medical equipment applications. These three entities collectively illustrate how qualification requirements and supply chain configuration determine competitive positioning across end-use verticals.
| Leading Market Players |
|---|
| Universal Alloy Corp. |
| UACJ Automotive Whitehall Industries, Inc. |
| Hydro Extrusion USA, LLC |
| Erbsloeh Aluminum Solutions, Inc. |
| Bonnell Aluminum |
| Western Extrusions Corp. |
| Hydro Extrusion Portland, Inc. |
| Tower Extrusions, Ltd. |
| Crystal Finishing Systems, Inc. |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up regional fabricators anchor mid-market pricing discipline through dense mill networks and captive remelt economics, while sovereign-backed primary producers like Hydro leverage upstream billet control to capture IRA-compliant premiums. This ownership fragmentation produces divergent supply behaviors: family-owned specialists prioritize long-term contract coverage over spot volatility, whereas integrated operators extract margin from domestic content qualification thresholds.
Pricing Analysis
Premium pricing for sub-four-week lead times separates automotive platform suppliers from spot-market construction buyers. Contract-based long-term offtake agreements dominate OEM procurement, with price differentiation resting on NADCAP certification tier and volume scale commitments. Pricing pressure stems from LME volatility and Midwest premium spikes compressing non-integrated extruder margins. National homebuilders exhibit acute price sensitivity through consolidated procurement desks, while aerospace-qualified suppliers command insensitivity due to limited source availability.
Supply Chain Analysis
Direct-to-OEM channels handle Detroit Three and transplant automaker demand through qualified supplier programs, while mill-direct relationships serve consolidated national builders. Domestic supply concentrates in Michigan, Ohio, and Texas, with Canadian billet imports feeding non-integrated Great Lakes fabricators. Raw material dependencies encompass primary aluminum ingot, magnesium micro-additions, and H13 tool steel for die fabrication. Tariff exposure on imported billet from Canada and Mexico creates qualification risk under evolving USMCA rules of origin enforcement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from IRA domestic content rules is forcing sub-scale extruders without captive billet supply toward exit or acquisition, concentrating viable competitors around integrated operators and precision specialists.
For Market Incumbents: Extend backward integration into direct-chill casting capacity to secure scrap arbitrage and carbon intensity advantages under emerging EPA Scope 3 frameworks. Deepen regional mill network density in the Southeast Growth Belt to capture Mercedes-Benz, BMW, and Hyundai-Kia transplant demand independent of Detroit Three cycles. Defend against steel substitution threats by co-developing hybrid aluminum-lithium alloys with scandium micro-additions for battery tray applications. For New Entrants and Emerging Players: Hydrostatic extrusion technology for aerospace-grade tubes with sub-micron surface finishes offers the most penetrable white space, given NADCAP-qualified domestic capacity scarcity. Target semiconductor equipment precision tubing demand from CHIPS Act fab construction around Phoenix and Austin, where ultra-high-purity 6061 and 6063 alloys command qualification premiums. Pursue toll-processing partnerships with established heat-treatment facilities to bypass AS9100 certification timelines. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional multi-press fabricators with remelt capabilities in the Gulf Coast petrochemical corridor, where sour gas handling equipment demand outpaces qualified corrosion-resistant alloy supply. Long-term viability hinges on domestic melting and casting capacity positioning under Buy America threshold evolution. Monitor pending revisions to alloy-specific tariff classifications as the inflection signal determining whether capacity expansion outpaces import substitution.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Billet Casting | Captive supply secures IRA tax credit eligibility for Detroit Three platform awards. |
| NADCAP Heat Treatment Certification | AS9100 quality systems unlock Boeing and Lockheed Martin supply chain access. |
| Closed-Loop Recycling Integration | Direct-chill remelt capabilities capture scrap price arbitrage under EPA carbon reporting. |
| Precision Tubing Capacity Expansion | Sub-micron surface finish equipment serves CHIPS Act vacuum chamber demand. |
| Southeast Mill Network Density | Regional proximity to transplant OEMs diversifies revenue beyond Detroit Three exposure. |
Research Approach
Trade association filings, SEC 10-K disclosures, and USGS mineral commodity summaries formed the secondary backbone, cross-referenced against primary interviews with extrusion plant managers, OEM platform engineers, and national homebuilder procurement directors. Bottom-up volume modeling triangulated against top-down aluminum consumption estimates from the Aluminum Association and Department of Commerce trade statistics. Conversations with NADCAP-certified heat treatment operators and semiconductor equipment OEMs validated precision tubing demand assumptions.
Historical trendline analysis of automotive aluminum content per vehicle and construction fenestration specifications established baseline growth trajectories across the projection horizon. Segmentation modeling incorporated product type complexity, end-user contract duration, application performance tier, and regional manufacturing cluster concentration. CAGRs derived from elasticity-adjusted demand curves responding to NHTSA fuel economy mandates and ASHRAE 90.1 energy code adoption patterns. Forecast inputs included Detroit Three platform cycle commitments and CHIPS Act fab construction timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under LME price volatility and Midwest premium spike scenarios. Projections reflect assumptions regarding IRA domestic content threshold stability and USMCA rules of origin enforcement consistency. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
North America Electrical Steel Market
Metals
Aluminium Conductors Market
Metals
Russia Metal Fabrication Market
Metals
Stainless Steel Market
Metals
Steel Long Products Market
Metals
Reconditioned Steel Drums Market
Metals
Trivalent Chromium Finishing Market
Metals
Aluminum Slugs Market
Metals
Recycled Metal Market
Metals
Global Ultra Fine Copper Powder Market
Metals
Bismuth Oxide Market
Metals
Osmium Market
Metals
Cold Drawn Wire Market
Metals
Colloidal Metal Particles Market
Metals
Industrial Silver Market
Metals
Iron Ore Market