
 High Potency API Contract Manufacturing Market | 2026-2036
High Potency API Contract Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
High Potency API Contract Manufacturing Market Intelligence
Buyer concentration among large pharmaceutical companies is shifting as mid-size biotech firms and virtual drug developers fragment the demand base for outsourced high potency API manufacturing. Lonza sustains technology leadership in antibody-drug conjugate payloads through integrated development-to-manufacturing platforms. Piramal Pharma Solutions anchors geographic dominance with multi-site high-containment facilities across North America and Europe. Catalent, Inc. differentiates through end-to-end service bundling that spans clinical supply through commercial launch.
High potency API contract manufacturing encompasses the outsourced production of active pharmaceutical ingredients with occupational exposure limits below ten micrograms per cubic meter, requiring isolator technology, single-use systems, and dedicated HVAC with pressure cascades to protect operators and prevent cross-contamination. The primary purpose is enabling pharmaceutical innovators to access specialized containment infrastructure without capital-intensive facility construction. Injectable formulations lead the product type segment due to the prevalence of oncology biologics and complex parenteral delivery requirements. Oral solid dosage forms represent the fastest-expanding category as oral targeted therapies with potent mechanisms gain priority in neurology and cardiovascular pipelines. Contract research organizations constitute a concentrated margin pool within end users, driven by their need for flexible, small-batch manufacturing during early-phase development.
FDA's current good manufacturing practice enforcement for potent compounds, EMA's guideline on setting health-based exposure limits for cross-contamination, and ISO 14644 cleanroom classification standards collectively shape facility investment thresholds and market access barriers for contract manufacturers. India's CDSCO alignment with ICH Q3C and Q3D guidelines is accelerating domestic facility upgrades to serve export markets. Stakeholders must monitor regulatory divergence between containment expectations in the United States and Europe versus emerging standard-setting in Asian manufacturing hubs.
Market Dynamics
Oncology biotech firms are fragmenting demand for high-containment manufacturing capacity, forcing contract manufacturers to reconfigure facility footprints for smaller batch sizes and faster changeover cycles.
Growth Catalysts
- EMA cross-contamination guidelines:Tightened health-based exposure limits are compelling pharmaceutical innovators to outsource rather than retrofit legacy facilities.
- Antibody-drug conjugate pipelines:ADC payloads with occupational exposure limits below one microgram per cubic meter require isolator technology that virtual drug developers cannot self-fund.
- Switzerland:Basel-region cluster investments in multi-purpose high-containment suites are attracting early-phase oncology programs from US and European sponsors.
Market Restraints
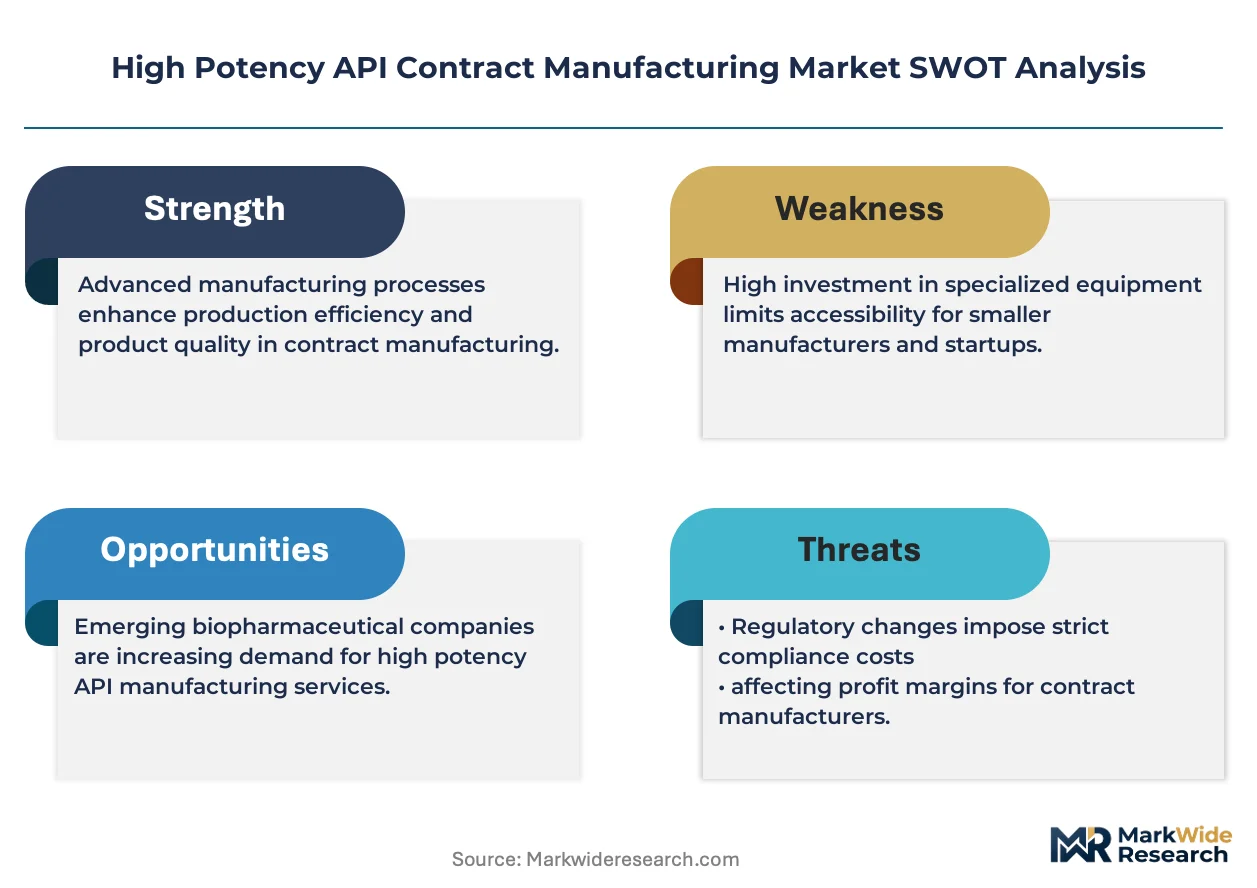
- Stainless steel equipment lead times:Specialized containment vessels and isolator systems face eighteen-to-twenty-four month procurement cycles from limited qualified fabricators.
- Specialized HVAC engineering talent:Pressure cascade design and unidirectional airflow validation expertise concentrates among a handful of European and North American engineering consultancies.
- Single-use system resin supply:Fluoropolymer film and connector supply chains for disposable containment technologies face concentration risk from Japanese and German material suppliers.
Strategic Opportunities
- India CDSCO alignment with ICH Q3C:Domestic facility upgrades to international containment standards are opening export pathways for Indian contract manufacturers.
- Oral solid dosage expansion:Neurology and cardiovascular pipelines with potent small molecules are creating demand for high-containment oral dose manufacturing previously concentrated in injectables.
- Continuous processing convergence with isolator technology:Integrated flow chemistry and containment platforms promise smaller physical footprints and faster batch release cycles.
Industry Challenges
- Containment validation timelines:Media fill studies and operator protection factor testing for new isolator installations extend facility qualification periods.
- Legacy quality management system integration:Paper-based batch records and standalone environmental monitoring systems in acquired facilities require digitization to meet sponsor audit expectations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Potency API Contract Manufacturing Market |
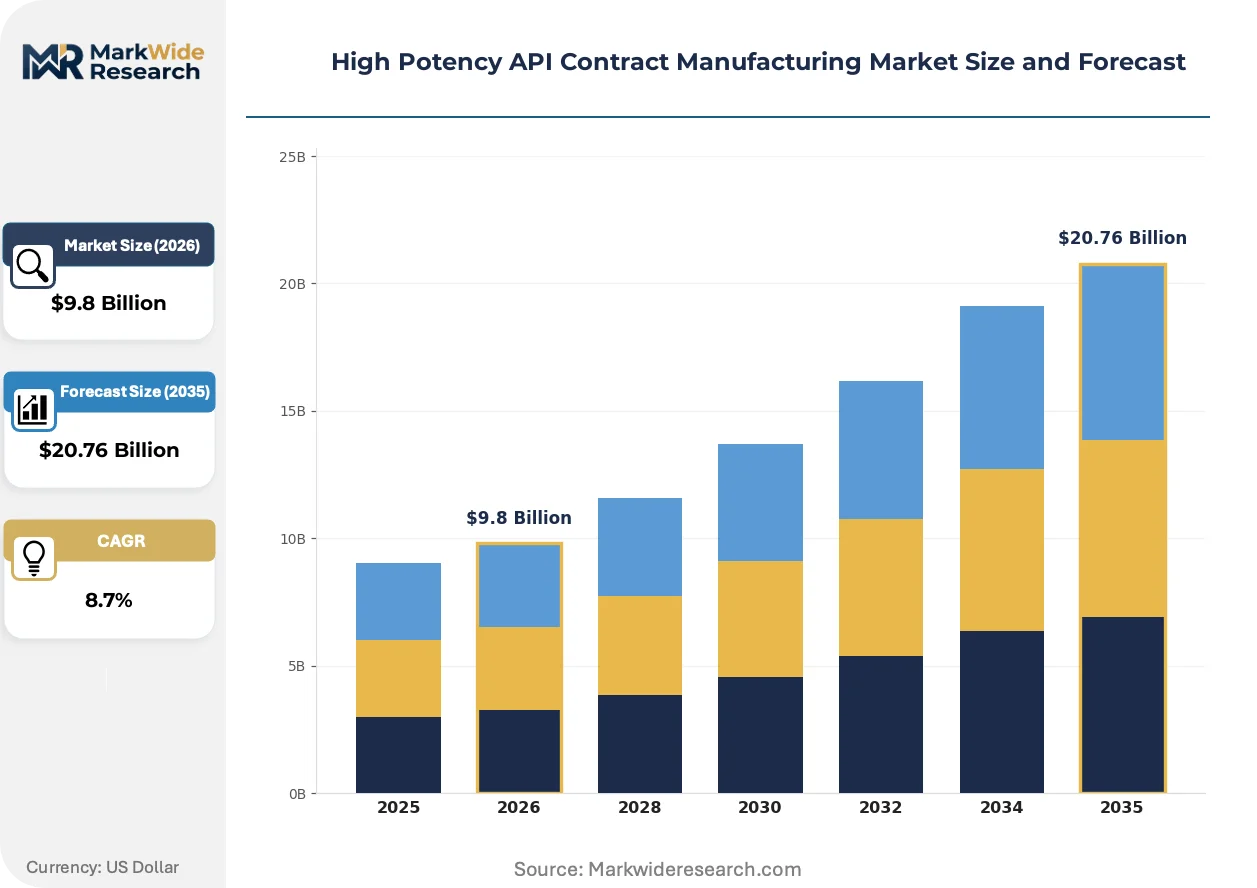
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $20.76 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectables, Oral Solid Dosage, Topical Formulations, Others Delivery Mode: IV Administration, Subcutaneous, Transdermal, Oral End User: Pharmaceutical Companies, Biotech Firms, Research Institutions, Contract Research Organizations Therapy Area: Oncology, Neurology, Cardiovascular, Infectious Diseases |
| Companies Covered | VxP Pharma, Inc., Gentec Pharmaceutical Group, Piramal Pharma Solutions, CordenPharma International, AbbVie, Lonza, Pfizer CentreOne, Curia Global, Inc., Catalent, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Potency API Contract Manufacturing Market Strategic Shifts & Innovations
Contract manufacturing for highly potent compounds is pivoting from fixed stainless steel infrastructure toward modular, single-use containment architectures that compress facility reconfiguration costs.
Isolator technology with integrated vaporized hydrogen peroxide decontamination is absorbing capital investment previously directed toward traditional cleanroom suites. Mid-size biotech sponsors are specifying closed-system isolators for Phase I campaigns that previously required dedicated suites. This shift is compressing the minimum viable facility scale for commercial high-potency API production.
FDA's intensified current good manufacturing practice enforcement for potent compounds is extending inspection scopes to contract manufacturer containment validation protocols. Facility qualification documentation now faces deeper scrutiny of operator protection factor testing methodologies. CDMOs with pre-validated isolator platforms are shortening sponsor technology transfer timelines.
Virtual drug developers are unbundling clinical supply from commercial manufacturing commitments, compressing traditional multi-year sole-source arrangements. Early-phase sponsors are awarding parallel development contracts to multiple CDMOs to de-risk supply continuity. This pattern is most visible in US and Swiss oncology pipelines where asset volatility and funding uncertainty dominate sponsor decision-making.
High Potency API Contract Manufacturing Market Segmentation
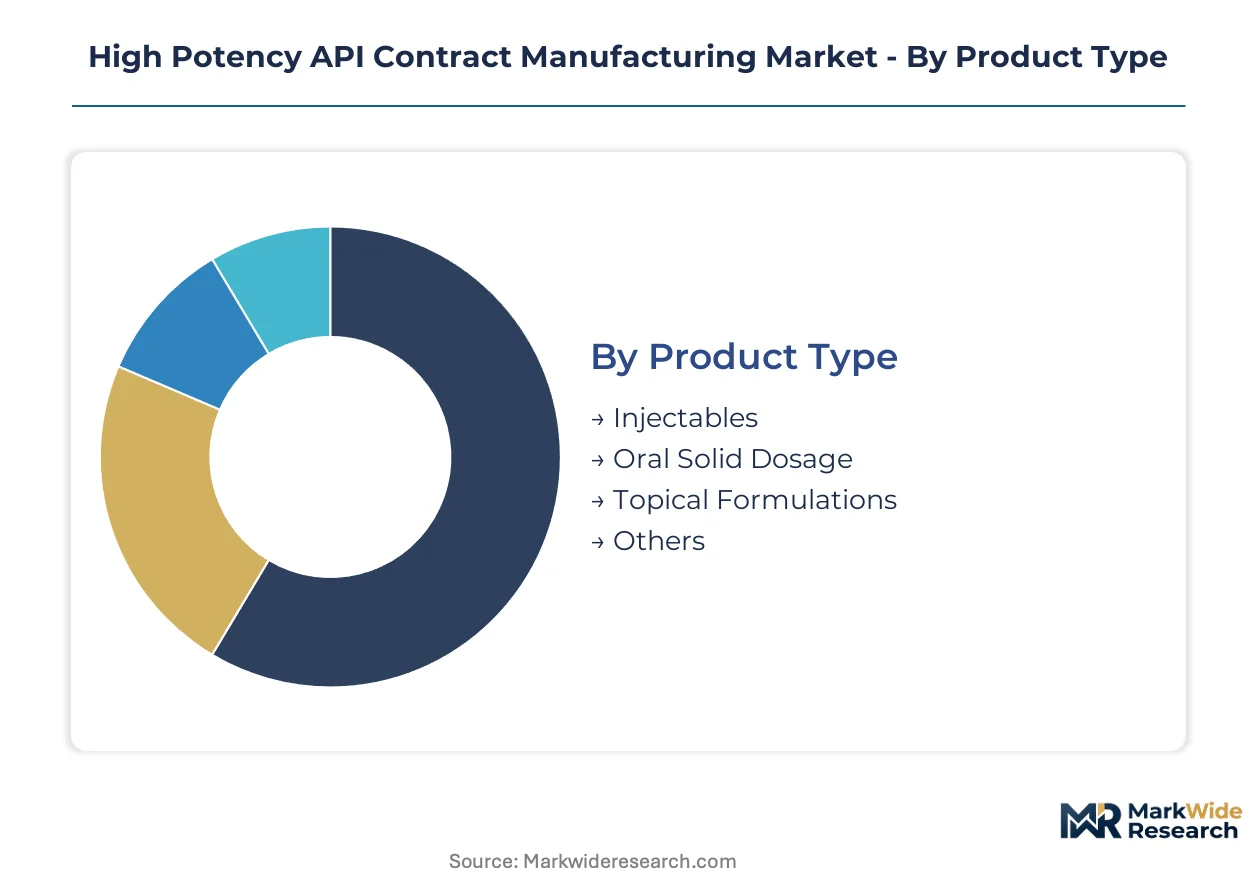
High potency API contract manufacturing demands segment-specific containment architectures. Each product format and delivery pathway imposes distinct engineering requirements that shape facility investment and operational economics.
Product Type:
Capital intensity peaks with injectable formats requiring isolator-integrated aseptic processing, while oral solid investments concentrate in high-containment granulation and compression suites.
- Injectables:Liquid and lyophilized formulations for oncology biologics demand closed-system filling lines with restricted access barrier systems. Demand clusters around Basel-region CDMOs serving US and European sponsors with ADC payload programs. Specialized containment vessels for cytotoxic compounds face eighteen-to-twenty-four month procurement cycles.
- Oral Solid Dosage:High-potency tablets and capsules require contained powder handling with continuous liner systems and dedicated HVAC pressure cascades. Neurology and cardiovascular pipelines with potent small molecules are driving capacity expansion in India and Switzerland. This segment is expanding most quickly as oral targeted therapies displace injectable first-line regimens.
- Topical Formulations:Transdermal patches and semisolid preparations employ localized exhaust ventilation and compounding isolators for corticosteroid and hormone APIs.
- Others:Inhalation powders and ophthalmic solutions utilize specialized containment for potent actives with narrow therapeutic indices.
Most installed capacity flows through injectables. Expansion is steepest in oral solid dosage.
Delivery Mode:
Route of administration dictates containment complexity, with parenteral pathways requiring the most rigorous operator protection engineering.
- IV Administration:Intravenous delivery of high potency compounds mandates terminal sterilization and closed-system transfer devices. Oncology biotech firms specify isolator-based filling for Phase I cytotoxic programs.
- Subcutaneous:Prefilled syringes and auto-injector presentations for antibody-drug conjugates combine device assembly with potent API containment. Switzerland's multi-purpose high-containment suites attract early-phase subcutaneous formulation work.
- Transdermal:Patch manufacturing employs solvent-based adhesive coating with contained drying and slitting operations for potent hormones and analgesics.
- Oral:Conventional tablet and capsule delivery leverages high-containment oral dose suites with wash-in-place capabilities for potent small molecules.
IV administration commands the highest containment capital per dose unit. Subcutaneous delivery is gaining share fastest as patient self-administration preferences reshape oncology dosing regimens.
End User:
Customer scale and outsourcing maturity determine contract structure, with large pharmaceutical sponsors demanding integrated services and virtual developers seeking flexible, small-batch capacity.
- Pharmaceutical Companies:Big pharma sponsors pursue multi-year sole-source arrangements for commercial supply, though early-phase unbundling is compressing traditional commitments. CDMOs with pre-validated isolator platforms shorten technology transfer timelines.
- Biotech Firms:Mid-size oncology developers fragment demand with parallel development contracts awarded to multiple CDMOs. Asset volatility and funding uncertainty dominate sponsor decision-making in US and Swiss pipelines.
- Research Institutions:Academic and government laboratories require contained manufacturing for investigational new drug-enabling toxicology batches.
- Contract Research Organizations:CROs constitute a concentrated margin pool within end users, driven by flexible small-batch manufacturing needs during early-phase development.
Pharmaceutical companies anchor committed revenue. Biotech firms are expanding fastest as virtual drug developers proliferate.
Therapy Area:
Clinical indication shapes potency classification and regulatory scrutiny, with oncology commanding the most stringent containment standards.
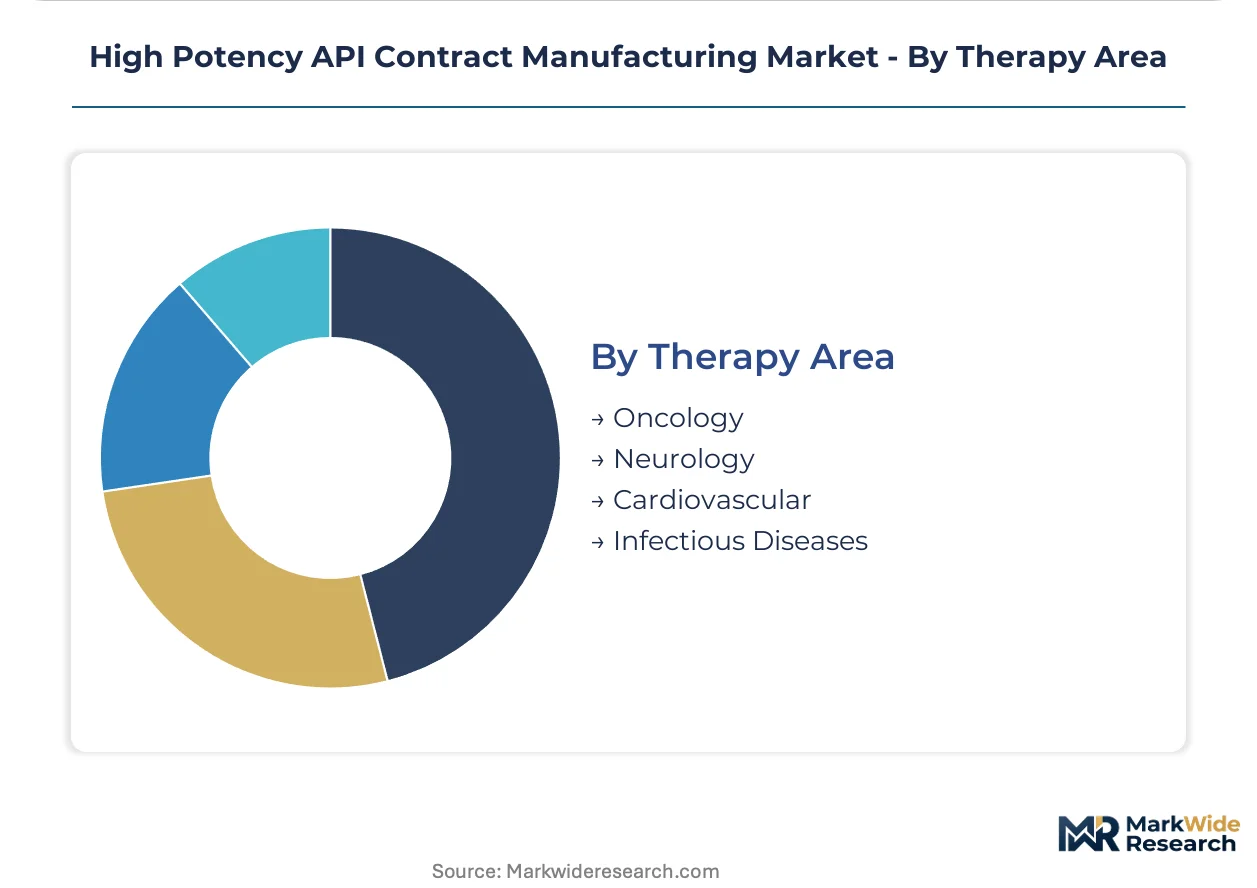
- Oncology:Cytotoxic chemotherapeutics and ADC payloads with occupational exposure limits below one microgram per cubic meter require isolator technology that virtual drug developers cannot self-fund. FDA intensified cGMP enforcement extends inspection scopes to containment validation protocols.
- Neurology:Potent CNS-targeted small molecules for Parkinson's and Alzheimer's disease are creating demand for high-containment oral dose manufacturing previously concentrated in injectables.
- Cardiovascular:Anticoagulant and antihypertensive APIs with steep dose-response curves necessitate contained handling during scale-up.
- Infectious Diseases:Antiviral and antibiotic manufacturing employs containment for potent intermediates and final API isolation.
Oncology dominates committed capacity. Neurology is climbing the fastest as oral CNS therapies advance through Phase II pipelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Switzerland's Basel-region containment clusters attract more early-phase oncology programs than India's export-oriented upgrades, though both geographies are expanding high-potency capacity at accelerated rates. Facility investment patterns diverge between established European hubs and emerging Asian manufacturing centers.
United States
FDA intensified cGMP enforcement for potent compounds drives sponsor outsourcing to contract manufacturers with pre-validated isolator platforms. The agency's extended inspection scopes now scrutinize operator protection factor testing methodologies. Massachusetts and North Carolina biotech corridors concentrate demand for Phase I cytotoxic manufacturing.
Switzerland
Swissmedic alignment with EMA cross-contamination guidelines positions Basel-region CDMOs as preferred partners for ADC payload programs. Multi-purpose high-containment suites attract virtual drug developers seeking flexible small-batch capacity. The country's pharmaceutical engineering talent pool supports faster facility qualification timelines.
India
CDSCO adoption of ICH Q3C and Q3D guidelines accelerates domestic facility upgrades for export market access. Hyderabad and Ahmedabad manufacturing clusters invest in isolator technology to serve US and European sponsor audits. Contract manufacturers leverage cost structures unavailable in Western European facilities.
Germany
EMA health-based exposure limit enforcement compels pharmaceutical innovators to outsource rather than retrofit legacy manufacturing sites. Bavaria and North Rhine-Westphalia host specialized engineering consultancies for pressure cascade design validation. German fabricators face eighteen-to-twenty-four month order backlogs for containment vessels.
United Kingdom
MHRA post-Brexit regulatory autonomy maintains alignment with EMA containment expectations while streamlining domestic approval pathways. The Golden Triangle research cluster generates demand for contained toxicology batch manufacturing. UK-based CDMOs specialize in early-phase clinical supply for virtual biotech sponsors.
High Potency API Contract Manufacturing Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across fragmented demand tiers. The vendor base organizes around three strategic archetypes: integrated development-to-manufacturing platforms, multi-site geographic networks, and end-to-end service bundlers. Consolidation pressure intensifies as mid-size biotech sponsors unbundle clinical from commercial commitments. Dominant competitive moves include isolator technology pre-validation and parallel development contract structures.
Within the integrated platform tier, Lonza and Catalent, Inc. exemplify divergent scale strategies, while Piramal Pharma Solutions anchors geographic coverage archetypes. These entities occupy positions spanning technology leadership, multi-continental facility footprints, and service bundling depth. Their competitive positioning reflects sponsor demands for faster technology transfer and reduced supply continuity risk.
| Leading Market Players |
|---|
| VxP Pharma, Inc. |
| Gentec Pharmaceutical Group |
| Piramal Pharma Solutions |
| CordenPharma International |
| AbbVie |
| Lonza |
| Pfizer CentreOne |
| Curia Global, Inc. |
| Catalent, Inc. |
| Others |
Cost & Logistics Intelligence
Biotech procurement teams mandating isolator-integrated aseptic processing for Phase I cytotoxic programs are forcing contract manufacturers to absorb eighteen-to-twenty-four month equipment lead times into quoted rates, compressing margins on early-phase contracts while elevating price floors for validated capacity.
Pricing Analysis
Capacity additions in India are reshaping price floors for standard containment services as CDSCO-aligned facilities undercut Western European rates by leveraging domestic engineering labor pools. Contract manufacturers employ three-tier pricing structure across premium isolator-validated, standard contained-suite, and economy shared-facility levels. Price differentiation hinges on FDA pre-validation status and single-use system integration depth. Cost compression in early-phase segments is intensifying because virtual drug developers unbundle clinical from commercial commitments. Virtual biotech sponsors exhibit highest price sensitivity; large pharmaceutical companies prioritize supply continuity over rate negotiation.
Supply Chain Analysis
Dual-sourcing requirements for fluoropolymer film and vaporized hydrogen peroxide decontamination systems are compelling sponsors to qualify Japanese and German material suppliers in parallel, extending procurement cycles. Manufacturing equipment concentrates in Germany, Switzerland, and the United States, with specialized containment vessel fabricators facing order backlogs. Raw material dependencies include fluoropolymer resins, stainless steel alloys, and single-use connector assemblies. Single-source vulnerability from concentrated Japanese fluoropolymer supply creates exposure. Distribution runs through direct CDMO-sponsor contracts with minimal intermediary involvement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EMA health-based exposure limit enforcement and FDA intensified cGMP scrutiny for potent compounds are structurally expanding outsourced demand beyond available validated capacity.
For Market Incumbents: Anchor market position through backward integration into isolator technology pre-validation and captive engineering talent development in Basel-region clusters. Acquire specialized HVAC consultancies in Germany to compress facility qualification timelines. Threat of mid-size biotech parallel contracting demands faster technology transfer capabilities as a defensive lever. For New Entrants and Emerging Players: Launch via flexible small-batch isolator platforms targeting oral solid dosage expansion in neurology and cardiovascular pipelines. White-space concentrates in high-containment oral dose manufacturing previously dedicated to injectables, with India offering lowest barrier to export market entry. Go-to-market angle emphasizes CDSCO-aligned pre-validation for US sponsor audits. For Investors and Strategic Acquirers: Asymmetric upside sits with Indian contract manufacturers completing ICH Q3C facility upgrades for export pathway access. Long-term viability centers on isolator technology differentiation rather than commodity containment capacity. Target acquisition archetype: mid-tier CDMOs with validated ADC payload experience but underdigitized quality management systems. Signal to watch is FDA inspection citation rates for operator protection factor testing methodologies as inflection indicator for competitive sorting.| Strategic Initiative | Industry Significance |
|---|---|
| Isolator Technology Pre-Validation | CDMOs with pre-validated platforms shorten sponsor technology transfer timelines for ADC payloads. |
| Backward Integration into Single-Use Systems | Captive fluoropolymer film supply reduces procurement vulnerability to Japanese supplier concentration. |
| Continuous Processing Convergence | Integrated flow chemistry and containment platforms promise smaller physical footprints for commercial production. |
| Digital Quality Management System Overhaul | Paper-based batch record digitization meets sponsor audit expectations for legacy facility acquisitions. |
| Multi-Site Geographic Network Expansion | CDMOs with Basel-region and Indian facilities capture both early-phase and cost-optimized commercial demand. |
Research Approach
Multiple input streams — primary interviews with drug development executives, regulatory affairs leads, and CDMO operations directors; secondary validation through FDA 483 inspection databases, EMA guideline publications, and ClinicalTrials.gov ADC program tracking; plus customs data on pharmaceutical equipment imports — were reconciled through bottom-up facility capacity enumeration and top-down sponsor outsourcing spend analysis.
Data-stream reconciliation across containment technology deployment metrics, therapy area pipeline tracking, and regional regulatory alignment scoring informed the analytical framework across the analysis window. Segmentation dimensions modeled include product format, delivery mode, end-user scale, and therapy area potency classification. CAGRs were derived from facility investment run-rates and sponsor outsourcing commitment patterns. Forecast inputs incorporated isolator installation lead times and CDSCO inspection readiness timelines for Indian facility upgrades.
Forecast precision tightens around the base case; tail outcomes carry wider variance under scenarios of prolonged FDA inspection backlogs or fluoropolymer supply disruption. Forecasts reflect documented assumptions regarding EMA guideline implementation timelines and virtual biotech funding continuity. Deviation in Swissmedic-FDA regulatory divergence on containment validation protocols would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Narcotic Analgesics Market
Pharmaceuticals
Global Anticoccidial Drugs Market
Pharmaceuticals
Cryptococcosis Therapeutics Market
Pharmaceuticals
Oral Vaccines Market
Pharmaceuticals
United Kingdom (UK) Diabetes Drugs Market
Pharmaceuticals
Europe Laxative Market
Pharmaceuticals
Global Cardiovascular Drugs Market
Pharmaceuticals
Triamcinolone Ointment Chlorofluorocarbons Market
Pharmaceuticals
North America Travel Vaccines Market
Pharmaceuticals
Middle East and Africa Obsessive-Compulsive Disorder (OCD) Drugs Market
Pharmaceuticals
Europe Meglitinide Market
Pharmaceuticals
Bacterial Vaginosis Treatment Market
Pharmaceuticals
Global Colorectal Cancer Therapeutics Market
Pharmaceuticals
Europe Small Molecule Sterile Injectable Drugs Market
Pharmaceuticals
Oral Anti-Diabetic Drugs Market
Pharmaceuticals
Antiepileptic Drugs (AED) Market