
 Cryptococcosis Therapeutics Market | 2026-2036
Cryptococcosis Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Cryptococcosis Therapeutics Market Outlook
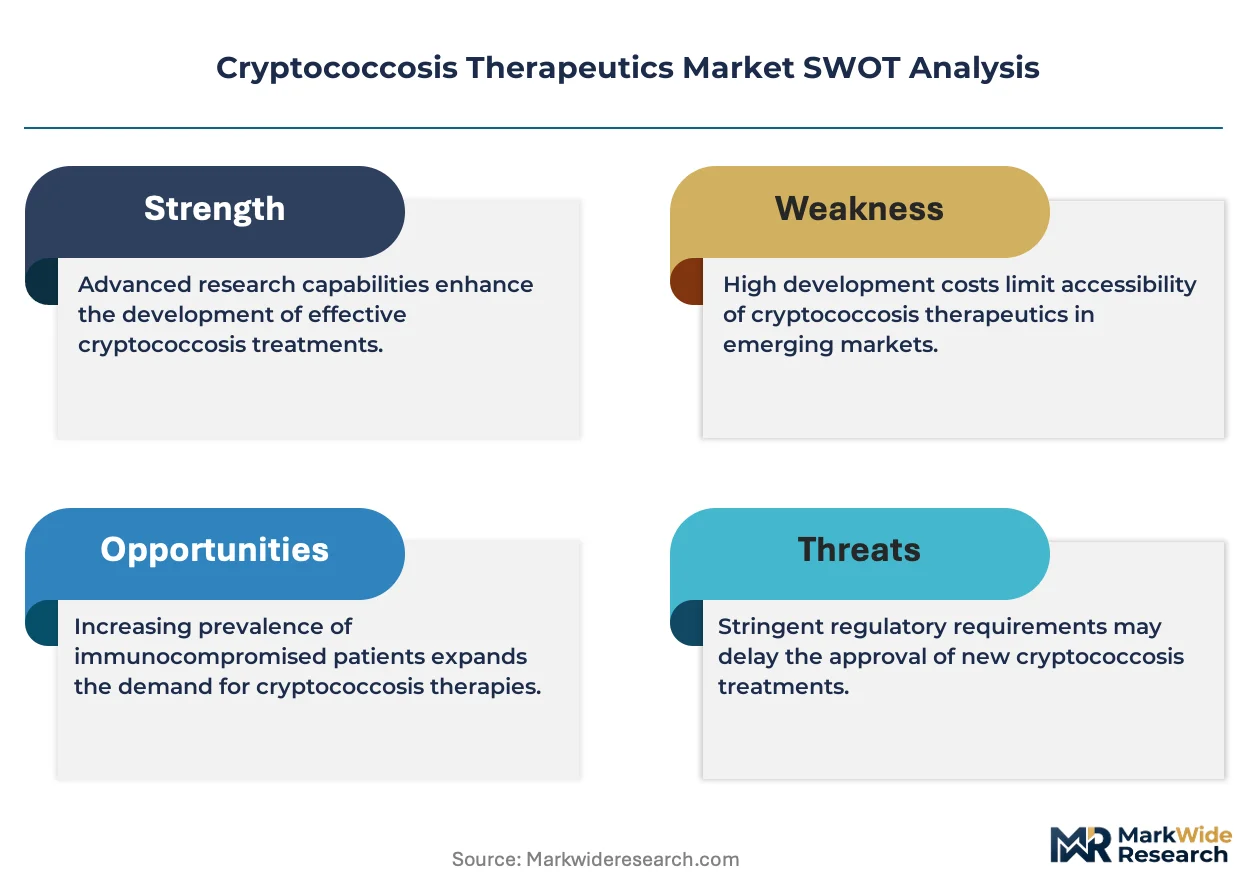
Orphan drug incentives is repositioning the cost-of-entry calculus for cryptococcosis drug developers. Pfizer Inc leverages its manufacturing scale to sustain broad distribution of amphotericin B formulations across endemic regions. Gilead Sciences, Inc. anchors its position through deep specialization in antiviral-adjacent antifungal portfolios serving immunocompromised populations. Bristol-Myers Squibb Company competes by extending its oncology-immunology infrastructure into opportunistic infection co-therapies.
Cryptococcosis therapeutics comprise antifungal agents targeting Cryptococcus neoformans and Cryptococcus gattii, with amphotericin B formulations requiring liposomal encapsulation to reduce renal toxicity while maintaining cerebrospinal fluid penetration. These drugs serve the primary purpose of reducing mortality in HIV-associated meningitis and solid organ transplant recipients with disseminated infection. Amphotericin B and flucytosine dominate current hospital formularies as first-line induction therapy, while voriconazole occupies a narrower niche in salvage settings where azole resistance emerges. Intravenous delivery mode commands the highest clinical reliance in acute CNS presentations, though oral step-down protocols are expanding the addressable homecare segment.
FDA orphan drug designations and WHO Essential Medicines List inclusion shape manufacturer prioritization and pricing flexibility for cryptococcosis therapies. EMA's guidance on antifungal breakpoints and FDA's bioequivalence standards for liposomal formulations govern product approval pathways and generic substitution timelines. National regulators in Brazil and South Africa influence access patterns through public procurement tenders and local production incentives. Stakeholders must monitor evolving resistance surveillance data and regulatory harmonization efforts between FDA and EMA to anticipate portfolio rebalancing requirements.
Market Dynamics
Hospital formulary consolidation around liposomal amphotericin B is compressing generic substitution windows while WHO prequalification requirements reshape manufacturing investment priorities across endemic regions.
Growth Catalysts
- Orphan Drug Incentives:FDA tax credits and market exclusivity provisions are accelerating development timelines for novel antifungal formulations targeting HIV-associated cryptococcal meningitis.
- Immunocompromised Patient Volumes:Solid organ transplant centers and oncology units are expanding prophylactic prescribing protocols for high-risk Cryptococcus exposure.
- WHO Essential Medicines List Inclusion:Amphotericin B and flucytosine placement drives national procurement tenders and public health program prioritization in endemic countries.
Market Restraints
- Input Cost Volatility:Phospholipid supply for liposomal encapsulation concentrates among European specialty chemical suppliers, exposing manufacturers to raw material price swings.
- Regulatory Friction:EMA bioequivalence standards for liposomal generics extend approval timelines and limit rapid substitution of originator formulations.
- Technical Limitation:Cerebrospinal fluid penetration requirements for CNS cryptococcosis restrict viable molecular targets and narrow the development pipeline.
Strategic Opportunities
- Underpenetrated Geography:Brazil's Sistema Único de Saúde procurement channels remain underserved by liposomal formulation suppliers despite high endemic burden.
- Technology Convergence:Nanoparticle drug delivery systems combined with therapeutic drug monitoring platforms enable personalized dosing in transplant recipients.
- Distribution Innovation:Direct hospital contracting models bypass wholesale markup layers in South Africa's public sector tender system.
Industry Challenges
- Specialized Manufacturing Talent:Liposomal formulation expertise resides within a limited pool of pharmaceutical scientists, constraining capacity expansion at contract development organizations.
- Cold Chain Infrastructure:Amphotericin B temperature stability requirements complicate last-mile distribution to rural HIV clinics in tropical climates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cryptococcosis Therapeutics Market |
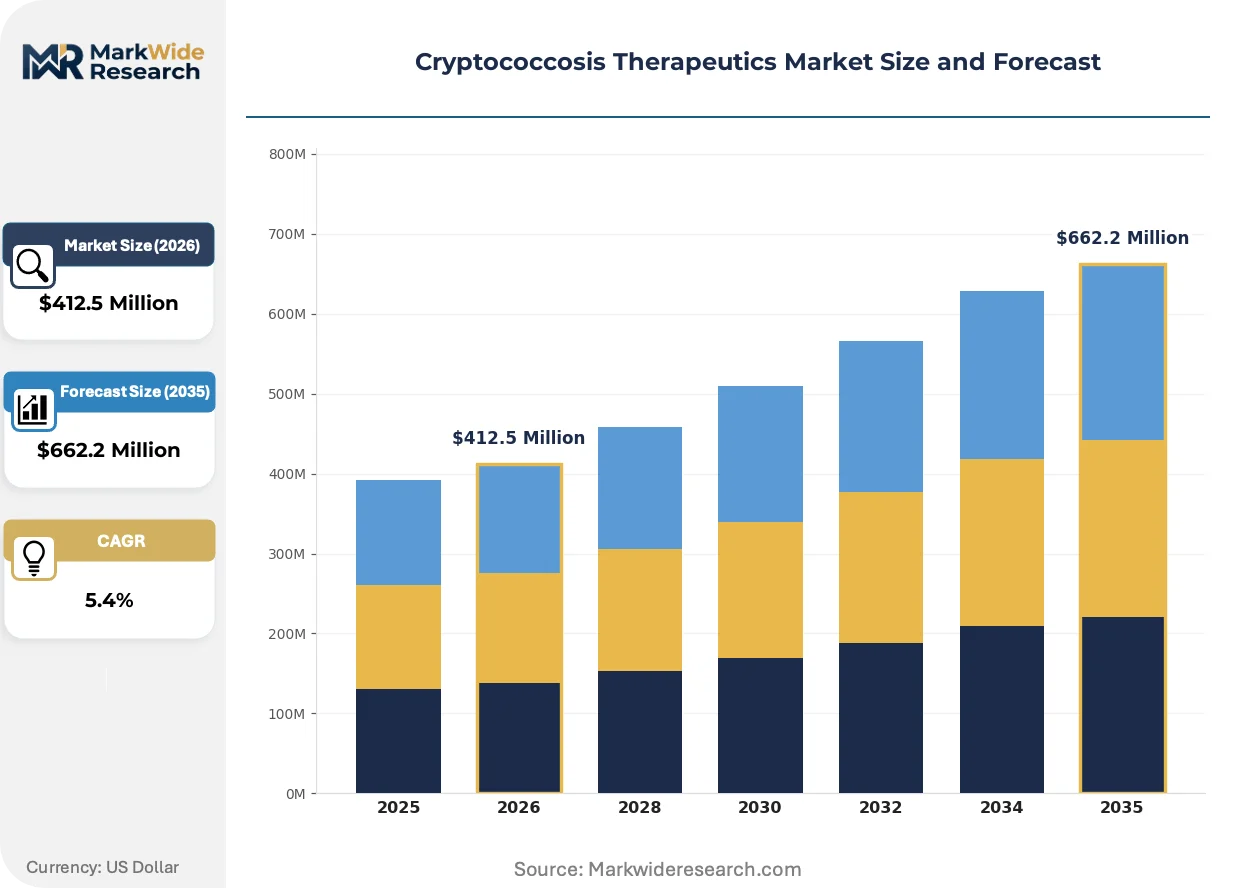
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $662.2 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flucytosine, Amphotericin B, Itraconazole, Voriconazole Therapy Area: Fungal Infections, Immunocompromised Patients, Central Nervous System Infections, Opportunistic Pathogens Delivery Mode: Intravenous, Oral, Topical, Inhalation End User: Hospitals, Rehabilitation Centers, Homecare Settings, Research Institutions |
| Companies Covered | Pfizer Inc, Bristol-Myers Squibb Company, Astellas Pharma Inc, Glenmark Pharmaceuticals, Novartis AG, Merck & Co., Inc., Gilead Sciences, Inc., Sigmapharm Laboratories LLC, Janssen Biotech Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cryptococcosis Therapeutics Market Strategic Shifts
Antifungal resistance surveillance networks and point-of-care diagnostic integration are compressing treatment initiation windows and reshaping how hospitals manage cryptococcal meningitis protocols.
Long-acting injectable formulations of liposomal amphotericin B are rewriting induction therapy administration patterns. Transplant centers in the United States are piloting single-dose regimens to reduce nephrotoxicity monitoring burdens. This compression of hospital length-of-stay is enabling step-down to oral azole maintenance earlier in the care pathway.
EMA's revised antifungal breakpoints guidance is forcing susceptibility testing standardization across European reference laboratories. Clinical microbiology departments must retool automated platforms to report interpretive categories aligned with the new epidemiological cutoff values. Generic manufacturers face extended validation timelines as they demonstrate equivalence against the updated reference standards.
Consolidated purchasing by integrated delivery networks is concentrating procurement authority within centralized pharmacy committees. Academic medical centers are displacing independent hospital formularies with system-wide therapeutic interchange policies. This behavioral shift is most pronounced in the United States, where transplant center networks negotiate exclusive supply agreements spanning multiple states.
Cryptococcosis Therapeutics Market Segmentation
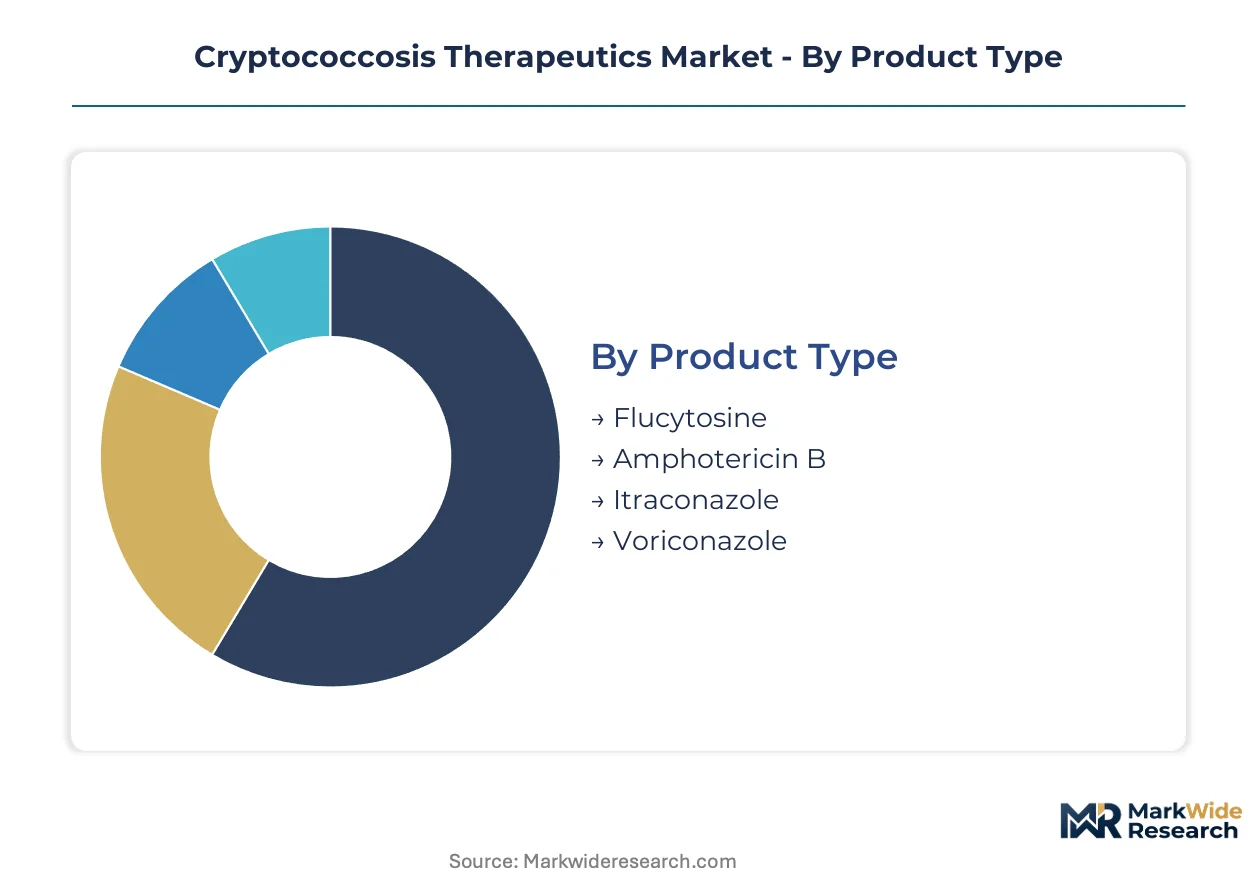
Segmentation in cryptococcosis therapeutics reveals how formulation technology and care setting economics determine competitive positioning. Manufacturers configure portfolios around liposomal encapsulation capabilities and distribution reach into transplant center networks rather than pursuing uniform coverage across all patient pathways.
Product Type:
Standalone antifungal agents dominate hospital formularies while combination protocols embed multiple products into standardized induction regimens.
- Amphotericin B:Liposomal encapsulation reduces nephrotoxicity while maintaining cerebrospinal fluid penetration critical for CNS infections. Demand concentrates in United States transplant centers where nephrology monitoring infrastructure supports high-dose induction protocols.
- Flucytosine:This pyrimidine analog requires therapeutic drug monitoring due to narrow therapeutic index and bone marrow suppression risk. Procurement volumes track HIV clinic networks in South Africa where public sector tenders prioritize fixed-dose combination access.
- Voriconazole:Triazole salvage therapy for azole-resistant Cryptococcus strains with variable CNS penetration.
- Itraconazole:Oral azole maintenance option with bioavailability challenges requiring acid-dependent absorption.
Volume placements concentrate in Amphotericin B; the faster expansion belongs to liposomal formulation variants.
Therapy Area:
Cost tier separation emerges between acute life-threatening presentations requiring hospitalization and chronic prophylaxis managed through outpatient protocols.
- Central Nervous System Infections:Cryptococcal meningitis demands liposomal amphotericin B plus flucytosine induction with 14-day hospital monitoring. United States academic medical centers anchor prescription volumes through dedicated neuro-ID consultation services.
- Immunocompromised Patients:Prophylactic prescribing in solid organ transplant recipients drives maintenance azole demand. Brazil's Sistema Único de Saúde procurement channels show underpenetration despite high endemic burden.
- Fungal Infections:Broad diagnostic category capturing pulmonary and disseminated cryptococcosis presentations.
- Opportunistic Pathogens:Co-infection management protocols in advanced HIV disease combining antifungal with antiretroviral therapy.
Revenue concentration sits with CNS infections; prophylactic segments in transplant populations are climbing the fastest.
Delivery Mode:
Application context dictates route selection—acute CNS disease requires parenteral penetration while step-down protocols shift economic value toward oral alternatives.
- Intravenous:Liposomal amphotericin B infusion requires specialized pharmacy compounding and nephrotoxicity monitoring protocols. United States hospital systems with integrated transplant networks capture the highest utilization rates through centralized purchasing agreements.
- Oral:Fluconazole and itraconazole maintenance therapy enables early hospital discharge and homecare cost reduction. South Africa's public sector tender system favors oral step-down to extend limited liposomal supply across larger patient populations.
- Topical:Limited utility in cutaneous cryptococcosis presentations without systemic dissemination.
- Inhalation:Investigational delivery route for pulmonary cryptococcosis prophylaxis in high-risk transplant recipients.
Clinical reliance clusters in intravenous delivery; oral protocols are gaining share fastest through integrated discharge planning.
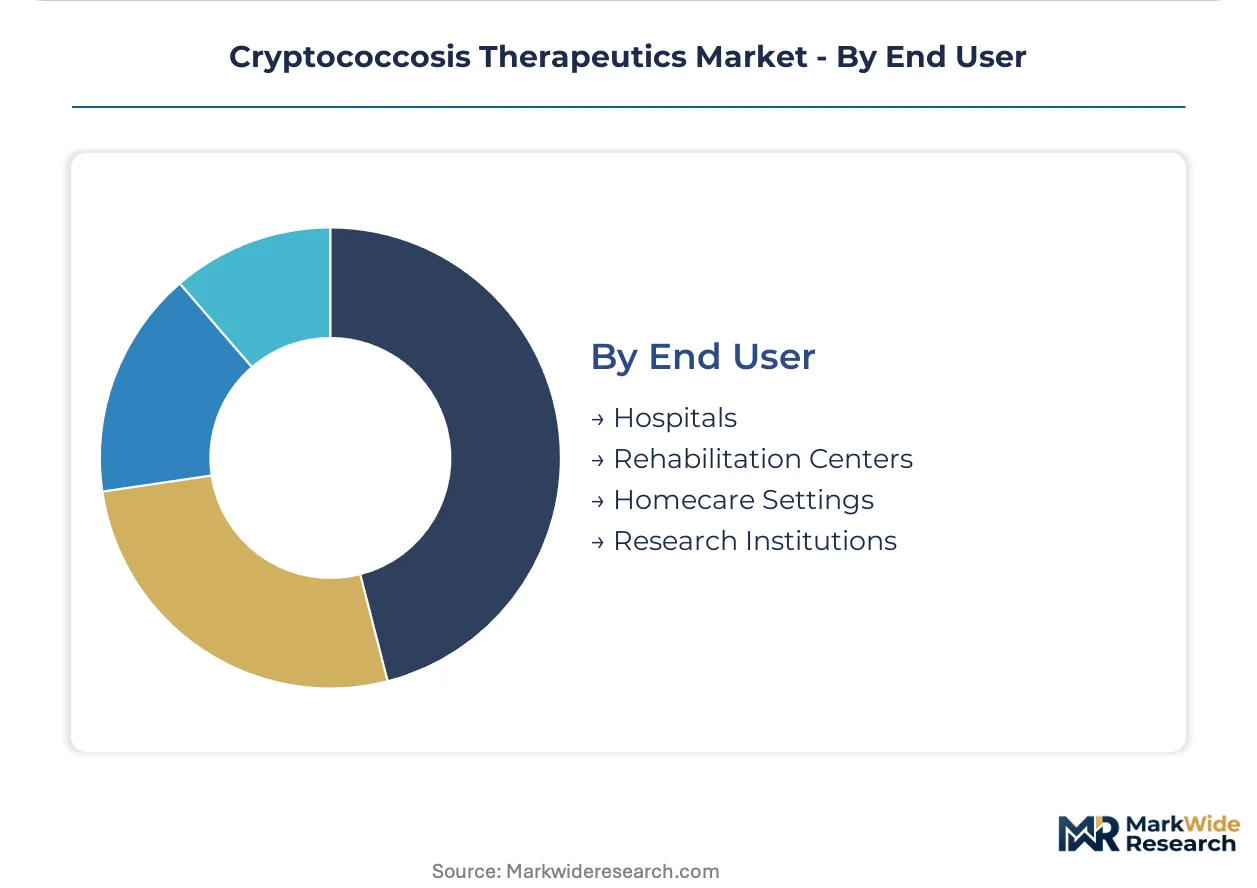
End User:
Customer type determines procurement authority concentration—consolidated health systems negotiate exclusive supply agreements while fragmented homecare segments resist price standardization.
- Hospitals:Academic medical centers and transplant hospitals control formulary placement through pharmacy and therapeutics committees. United States integrated delivery networks spanning multiple states concentrate procurement authority within centralized committees.
- Homecare Settings:Oral azole maintenance and infusion nursing services for ambulatory liposomal administration. Brazil's expanding private insurance coverage is creating reimbursement pathways for home-based antifungal therapy.
- Rehabilitation Centers:Extended care facilities managing recovery from disseminated cryptococcosis in immunocompromised patients.
- Research Institutions:Clinical trial sites investigating novel antifungal combinations and resistance surveillance protocols.
Procurement volume anchors in hospitals; homecare infrastructure is expanding most quickly through step-down protocol adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free Trade Zone incentives in Dubai's Jebel Ali cluster concentrate pharmaceutical distribution infrastructure serving endemic markets across the Middle East and Africa corridor.
United States
Academic medical centers in Boston and transplant networks in Houston drive liposomal amphotericin B procurement volumes. FDA orphan drug tax credits accelerate novel antifungal development timelines for HIV-associated meningitis indications. The Southeast corridor from Atlanta to Miami anchors specialty pharmacy distribution into Caribbean endemic zones.
Brazil
Sistema Único de Saúde procurement channels in São Paulo and Minas Gerais show persistent underpenetration by liposomal formulation suppliers. ANVISA's bioequivalence standards for complex generics extend approval timelines for local manufacturers. The São Paulo metropolitan cluster concentrates infectious disease research institutions piloting resistance surveillance networks.
South Africa
Public sector tenders in Gauteng and KwaZulu-Natal prioritize oral step-down protocols to extend limited liposomal supply across larger HIV-positive populations. The national pharmaceutical regulator enforces cold chain standards for amphotericin B distribution to rural clinics. Cape Town's clinical trial infrastructure supports pediatric cryptococcal meningitis studies.
Germany
EMA antifungal breakpoint guidance emanating from Amsterdam drives susceptibility testing standardization across German reference laboratories. Baden-Württemberg's specialty chemical suppliers concentrate phospholipid production for liposomal encapsulation. The Rhine-Ruhr industrial corridor hosts contract manufacturing organizations with sterile formulation capabilities.
India
CDSCO fast-track pathways for WHO-prequalified essential medicines attract generic flucytosine manufacturers to Hyderabad and Ahmedabad clusters. Maharashtra's transplant centers in Mumbai expand prophylactic prescribing protocols for solid organ recipients. The Delhi-NCR corridor concentrates regulatory consulting services navigating FDA and EMA parallel submission requirements.
Cryptococcosis Therapeutics Market Competitive Environment
United States producers anchor one tier; European specialists hold formulation technology advantages in liposomal encapsulation. The vendor base concentrates around three strategic archetypes: diversified pharmaceutical conglomerates with manufacturing scale, mid-cap antifungal specialists with therapeutic area focus, and generic houses with cost-optimized production. Competitive moves center on exclusive hospital contracting and WHO prequalification pursuit.
Within the diversified pharmaceutical tier, Pfizer Inc and Bristol-Myers Squibb Company occupy positions leveraging oncology-immunology infrastructure for opportunistic infection co-therapies. Gilead Sciences, Inc. exemplifies the antiviral-adjacent specialization archetype serving immunocompromised populations. These three entities represent the dominant competitive anchors against which mid-cap specialists and emerging generic houses calibrate positioning.
| Leading Market Players |
|---|
| Pfizer Inc |
| Bristol-Myers Squibb Company |
| Astellas Pharma Inc |
| Glenmark Pharmaceuticals |
| Novartis AG |
| Merck & Co., Inc. |
| Gilead Sciences, Inc. |
| Sigmapharm Laboratories LLC |
| Janssen Biotech Inc. |
| Others |
Value Chain & Pricing Dynamics
Liposomal encapsulation technology migration from conventional amphotericin B formulations is simultaneously compressing production cost curves and concentrating manufacturing capability among European specialty chemical suppliers with phospholipid synthesis expertise. This dual shift grants pricing power to holders of sterile formulation infrastructure while exposing buyers to input cost volatility from limited-source phospholipid feedstocks.
Pricing Analysis
Short lead-time premiums for liposomal amphotericin B concentrate in United States transplant centers facing urgent CNS meningitis protocols, while spot inventory discounts emerge in South African public tenders with extended procurement cycles. A three-tier pricing structure separates originator liposomal formulations from authorized generics and conventional amphotericin B. Cost compression in the generic tier is intensifying because of EMA bioequivalence validation timelines. Hospital pharmacy committees show highest price sensitivity; academic medical centers with integrated delivery network coverage demonstrate lowest sensitivity due to bundled contracting.
Supply Chain Analysis
Phospholipid supply for liposomal encapsulation rests on German and Dutch specialty chemical producers with hydrogenated soybean phosphatidylcholine synthesis capabilities. Key inputs include phospholipids, cholesterol for membrane stabilization, and sterile filtration equipment. Single-source vulnerability concentrates in European phospholipid manufacturers facing energy cost volatility. Distribution runs through hospital-centric specialty pharmacy channels in the United States and public sector tender systems in endemic countries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Long-acting injectable formulations are displacing conventional multi-dose induction regimens, compressing hospital length-of-stay and rewriting procurement volume calculations across transplant networks.
For Market Incumbents: Lock in exclusive supply agreements with United States integrated delivery networks spanning multiple transplant centers to forestall generic substitution. Secure captive phospholipid supply through backward integration into European specialty chemical producers or long-term offtake contracts. The threat of EMA bioequivalence standard revisions demands preemptive validation investment against updated reference standards.
For New Entrants and Emerging Players: Launch via direct hospital contracting models in Brazil's Sistema Único de Saúde procurement channels, bypassing wholesale markup layers that disadvantage multinational distributors. Target underpenetrated liposomal formulation access in São Paulo and Minas Gerais public health systems. The most penetrable segment lies in oral step-down protocols for HIV clinic networks seeking to extend limited liposomal supply.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified pharmaceutical conglomerates seeking oncology-immunology infrastructure extension into opportunistic infection co-therapies. Long-term viability hinges on WHO prequalification attainment enabling access to endemic market procurement tenders. Watch antifungal resistance surveillance data from European reference laboratories as inflection indicator for pipeline rebalancing requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Pursuit | Unlocks public sector procurement tenders in South Africa and Brazil's national health systems. |
| Phospholipid Supply Agreement | Secures feedstock access from Baden-Württemberg specialty chemical suppliers against input volatility. |
| Long-Acting Injectable Development | Reduces nephrotoxicity monitoring burdens in United States transplant center protocols. |
| Direct Hospital Contracting | Bypasses wholesale layers in South Africa's public sector tender distribution structure. |
| Resistance Surveillance Integration | Aligns susceptibility testing with EMA breakpoint guidance across German reference laboratories. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with hospital formulary directors, transplant center pharmacy leads, infectious disease specialists, and procurement managers at integrated delivery networks. FDA orphan drug designations, EMA antifungal breakpoint guidance documents, WHO Essential Medicines List placement records, and national tender databases in Brazil and South Africa provided validation anchors. Bottom-up prescription volume modeling and top-down market sizing triangulated across these streams.
Reconciliation of hospital procurement data, manufacturer shipment records, and patient registry volumes established the analytical framework across the projection horizon. Segmentation dimensions encompassed formulation type, therapy area, delivery mode, and end-user setting, with regional regulatory clusters as an additional industry-specific layer. CAGRs derived from trend extrapolation of immunocompromised patient volumes and formulary placement trajectories, incorporating WHO prequalification timeline assumptions and resistance surveillance network expansion rates.
The model assumes a particular technology adoption path for long-acting injectable formulations; alternative pathways for nanoparticle delivery systems would alter the outlook for hospital length-of-stay compression and step-down protocol timing. Forecasts reflect assumptions about regulatory harmonization between FDA and EMA, phospholipid supply stability, and cold chain infrastructure expansion in tropical climates. A small set of triggers—antifungal resistance breakpoint revisions, orphan drug incentive policy shifts, and phospholipid supply disruptions—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Lifestyle Drugs Market
Pharmaceuticals
Systemic Antibiotics Market
Pharmaceuticals
Fucosidosis Therapeutics Market
Pharmaceuticals
MRI Contrast Media Agents Market
Pharmaceuticals
Authorized Generics Market
Pharmaceuticals
Liquid Filled Hard Capsules Market
Pharmaceuticals
Soft Capsules Drugs Market
Pharmaceuticals
Anti-Inflammatory Analgesic and Antipyretic Drugs Market
Pharmaceuticals
Optic Nerve Disorders Drugs Market
Pharmaceuticals
Global Postpartum Depression Drugs Market
Pharmaceuticals
US Plasma Fractionation Market
Pharmaceuticals
Cough Oral Solution Market
Pharmaceuticals
Global Rabies Vaccine Market
Pharmaceuticals
Asia-Pacific Biguanide Market
Pharmaceuticals
Tapentadol Market
Pharmaceuticals
Global Cyclosporine Market