
 API Contract Manufacturing Market | 2026-2036
API Contract Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
API Contract Manufacturing Market Analysis
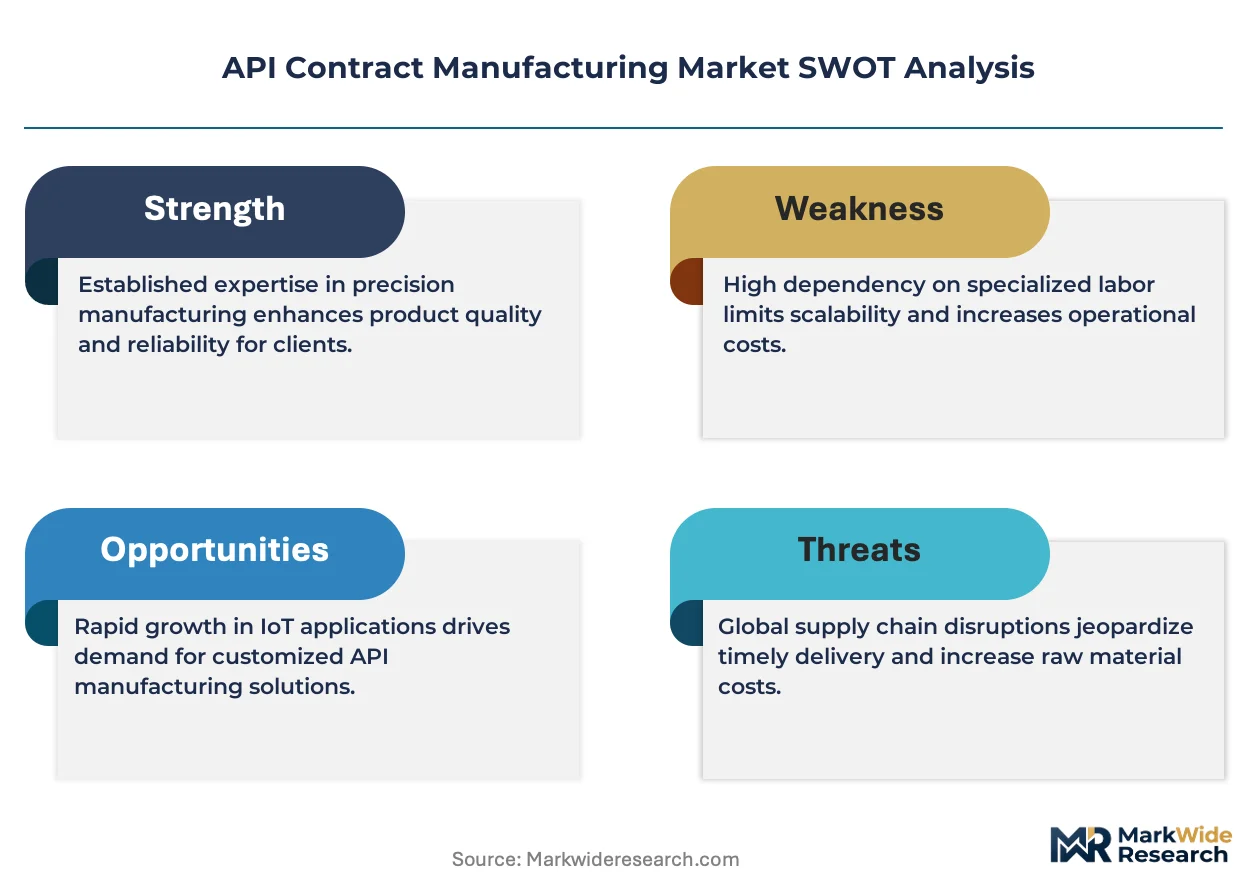
Biologics-grade raw materials are replacing traditional small-molecule feedstocks in high-value API programs, and this material transition is expanding the addressable margin pool for contract manufacturers serving oncology and immunology developers. Lonza leverages its microbial fermentation infrastructure to anchor peptide API supply for European biotech clients. Catalent sustains competitive positioning through integrated development-to-commercial pathways across North American and Asian facilities. WuXi AppTec dominates synthetic chemistry scale-up with multi-ton reactor capacity and aggressive capacity additions in China.
API contract manufacturing encompasses the outsourced production of pharmacologically active substances through chemical synthesis, bioprocessing, or extraction, with purity specifications typically exceeding 99.5% and stringent impurity profiling under ICH Q3A/Q3B guidelines. The primary purpose is to enable pharmaceutical innovators to access specialized manufacturing capabilities without capital-intensive facility investments. Synthesis services capture the largest revenue share due to the complexity and regulatory burden of multi-step chemical routes for novel molecules. Specialty APIs represent the fastest-expanding product category, driven by orphan drug designations and targeted therapy pipelines. The hybrid delivery model is gaining traction as sponsors seek geographic redundancy without fully abandoning oversight proximity.
The FDA enforces current good manufacturing practice standards through pre-approval inspections and warning letter mechanisms that directly determine market access for API suppliers to the United States. EMA's REACH compliance requirements and the EU's F-Gas Regulation constrain solvent selection and environmental discharge profiles for European-bound production. India's CDSCO aligns increasingly with ICH guidelines, reducing dual-registration burdens for export-oriented contract manufacturers. Stakeholders must monitor evolving bioequivalence standards for complex generics and assess whether captive manufacturing investments or external partnerships better match pipeline risk profiles.
Market Dynamics
Biotech pipeline complexity and the FDA's intensifying quality management mandates are forcing pharmaceutical innovators to externalize manufacturing capabilities rather than build captive capacity, restructuring how API production capacity is allocated across chemical synthesis and bioprocessing modalities.
Growth Catalysts
- Orphan drug designations:Rare disease pipelines require specialized high-potency containment that contract manufacturers alone can provision at viable scale, pulling volume toward outsourced partners.
- ICH Q3A/Q3B guidelines:Harmonized impurity profiling standards reduce dual-registration burdens for export-oriented facilities, accelerating cross-border supply relationships.
- India's regulatory alignment:CDSCO's convergence with Western inspection protocols positions Indian contract manufacturers for expanded US and EU-bound API supply.
Market Restraints
- Specialized solvent supply:REACH and EU F-Gas Regulation constrain halogenated solvent availability, elevating raw material costs for European-bound synthetic routes.
- Single-source bioreactor dependency:Stainless steel fermentation train concentration in select Asian manufacturing clusters creates geographic vulnerability for peptide API supply.
- Peptide synthesis yield ceilings:Solid-phase chemistry step efficiencies plateau beyond 30-40 residues, limiting economic viability for longer-chain biologics.
Strategic Opportunities
- Hybrid delivery models:Sponsors seek dual-continent manufacturing redundancy without full oversight abandonment, creating service tier demand for qualified contract partners.
- Continuous flow chemistry:Microreactor technology convergence with process analytical technology enables real-time quality assurance, compressing batch release timelines.
- Complex generic bioequivalence:Evolving FDA standards for long-acting injectables and inhalation products open specialized analytical services to contract manufacturers.
Industry Challenges
- High-containment engineering talent:Potent compound handling expertise scarcity constrains capacity expansion for oncology-focused API programs.
- Multi-year qualification timelines:FDA pre-approval inspection cycles and warning letter remediation extend sponsor onboarding to 18-36 months.
- Legacy quality management system integration:Paper-based batch records and electronic data capture harmonization create compliance friction during technology transfers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | API Contract Manufacturing Market |
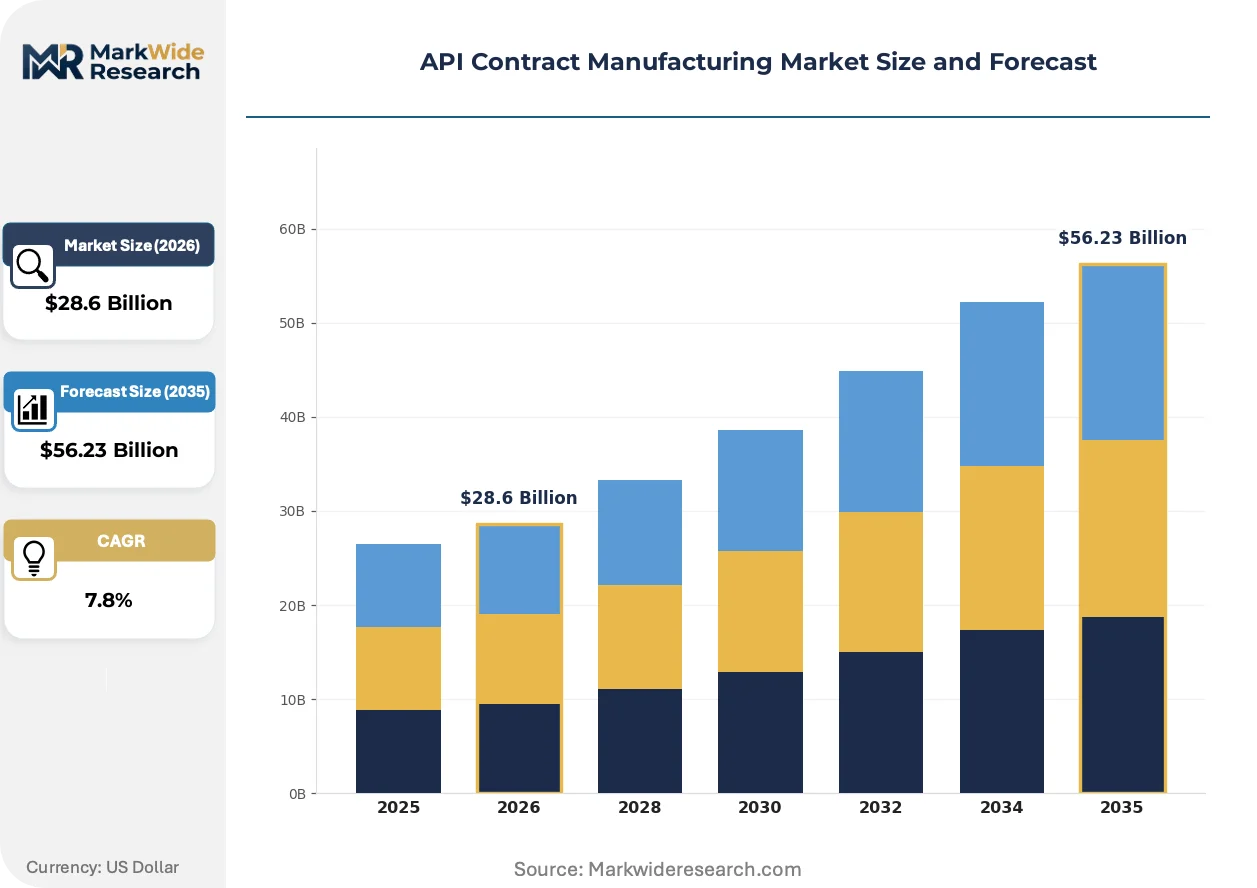
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $56.23 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Synthesis, Formulation, Packaging, Quality Control End User: Pharmaceutical Companies, Biotech Firms, Research Institutions, Contract Research Organizations Product Type: Active Pharmaceutical Ingredients, Intermediates, Generics, Specialty APIs Delivery Model: On-site Production, Off-site Production, Hybrid Model, Emergency Supply |
| Companies Covered | Lonza, Catalent, Piramal Pharma Solutions, Alcami Corporation, Sandoz AG, CordenPharma International, Pfizer CentreOne, WuXi AppTec, Evonik Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
API Contract Manufacturing Market Emerging Trajectories
Continuous processing technologies and real-time release testing are compressing traditional batch manufacturing paradigms, while regulatory data integrity mandates and sponsor risk-mitigation strategies reshape facility investment and partnership structures across the API supply base.
Single-use bioreactor systems is expanding into microbial fermentation for peptide APIs, displacing stainless steel infrastructure in facilities serving mid-scale biotech sponsors. Lonza and comparable European contract manufacturers are adopting disposable stirred-tank configurations for campaigns under 2,000 liters. This technology is expanding into geographic markets where capital deployment speed outweighs per-unit cost optimization.
EMA's F-Gas Regulation and REACH solvent restrictions are constraining halogenated reagent selection for European-bound API synthesis, forcing process chemistry redesign toward aqueous and bio-based alternatives. Multi-step synthetic routes for small-molecule oncology candidates face reformulation pressure. Contract manufacturers with green chemistry capabilities are capturing preference from sponsors with EU commercialization strategies.
Sponsor quality agreements now specify geographic redundancy clauses requiring dual-continent manufacturing capabilities, unbundling traditional single-source relationships. Biotech innovators with US commercialization plans are disqualifying sole-source Asian suppliers. This pattern concentrates procurement leverage with contract manufacturers possessing validated facilities across North American and European jurisdictions.
API Contract Manufacturing Market Segmentation
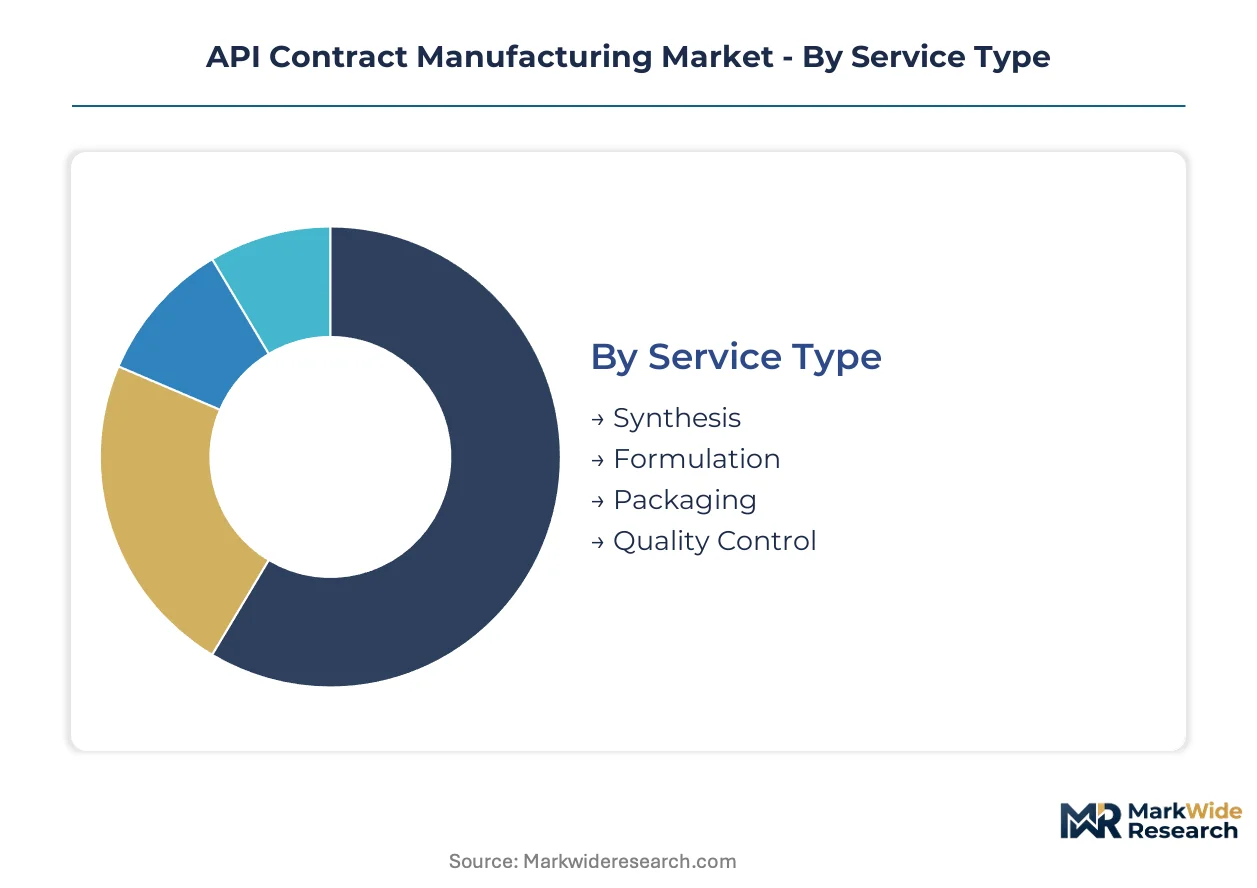
API contract manufacturing segmentation reveals how sponsors allocate production risk across chemical complexity, regulatory jurisdiction, and supply chain redundancy. Each category maps distinct capability requirements to vendor selection criteria.
Service Type:
Chemical synthesis demands the deepest process knowledge, while packaging and quality control offer standardization economies that reshape margin structures.
- Synthesis:Multi-step chemical routes for novel molecules require specialized reactor configurations and impurity profiling under ICH Q3A/Q3B guidelines. Demand concentrates with oncology and immunology developers in Switzerland and Germany, where containment infrastructure investments justify premium pricing for high-potency compounds.
- Formulation:Conversion of APIs into dosage forms demands excipient compatibility testing and stability validation. Sponsors in India and the United States prioritize partners with integrated development-to-commercial pathways to compress technology transfer timelines.
- Packaging:Primary and secondary packaging services include serialization for track-and-trace compliance. European-bound production faces EMA F-Gas Regulation constraints on sterilization processes.
- Quality Control:Analytical method development and batch release testing anchor regulatory submissions. CDSCO-aligned Indian laboratories gain preference for US-bound API programs seeking dual-inspection efficiency.
Leading the category by volume: Synthesis. Growing fastest: Quality Control.
End User:
Biotech firms externalize manufacturing most aggressively, while pharmaceutical companies balance captive capacity against partnership flexibility.
- Pharmaceutical Companies:Large innovators maintain selective outsourcing for capacity peaks and specialized chemistries. Patent cliff pressures in the United States drive complex generic sourcing toward Indian contract manufacturers with FDA establishment experience.
- Biotech Firms:Venture-backed developers lack capital for facility construction, making outsourced API production structural rather than tactical. Peptide and oligonucleotide pipelines in Massachusetts and California concentrate demand with microbial fermentation specialists.
- Research Institutions:Academic medical centers require gram-to-kilogram scale production for investigator-initiated trials. Limited commercial volumes restrict contract manufacturer interest to premium service tiers.
- Contract Research Organizations:CROs extend into manufacturing through captive API capabilities or preferred vendor networks. Sponsor quality agreements increasingly disqualify this channel for commercial-stage supply.
Dominating procurement volume: Pharmaceutical Companies. Expanding most quickly: Biotech Firms.
Product Type:
Specialty APIs command development premiums, while intermediates and generics compete on scale economies and regulatory filing efficiency.
- Active Pharmaceutical Ingredients:Pharmacologically active substances with purity specifications exceeding 99.5% anchor all downstream value. FDA pre-approval inspection cycles of 18-36 months concentrate supply relationships with established vendors in Ireland and Singapore.
- Intermediates:Penultimate synthetic stages enable sponsors to reserve final API conversion for captive facilities or higher-margin jurisdictions. Chinese manufacturers dominate bulk intermediate supply for cost-sensitive programs.
- Generics:Post-patent API production requires bioequivalence documentation and ANDA filing support. India's CDSCO-aligned manufacturers capture volume through cost efficiency and USFDA inspection history.
- Specialty APIs:High-potency compounds for oncology and rare diseases demand contained handling infrastructure. Orphan drug designations in the European Union and United States pull volume toward qualified European contract manufacturers.
Highest revenue concentration: Active Pharmaceutical Ingredients. Steepest expansion trajectory: Specialty APIs.
Delivery Model:
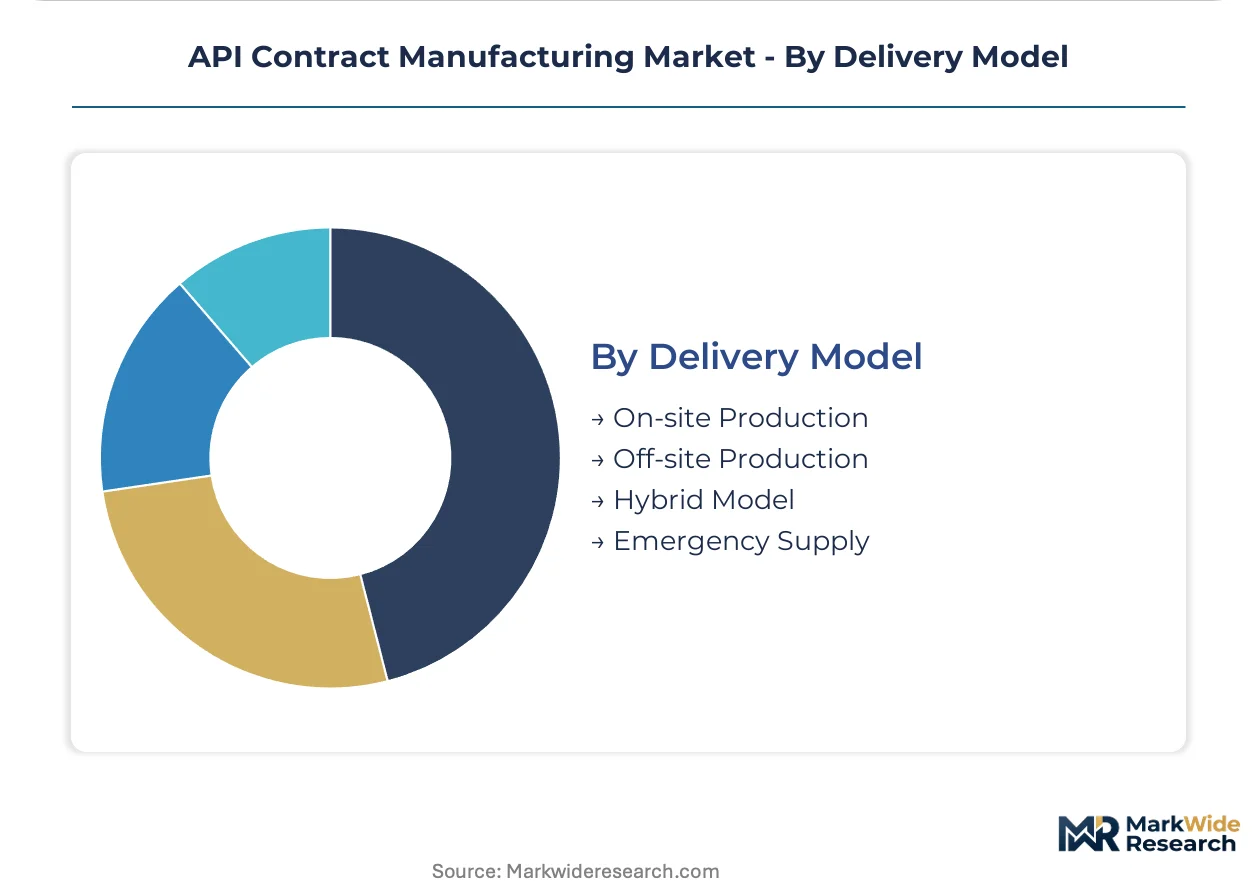
Geographic proximity preferences clash with cost optimization, producing hybrid configurations that split production across regulatory jurisdictions.
- On-site Production:Sponsor personnel maintain direct oversight at contract manufacturer facilities. US-based biotechs favor this model for first-in-human API batches requiring rapid specification adjustments.
- Off-site Production:Full outsourcing to distant manufacturing clusters minimizes labor and environmental compliance costs. Indian and Chinese facilities serve this demand for commercial-stage supply with established specifications.
- Hybrid Model:Split manufacturing across continents satisfies sponsor quality agreements requiring geographic redundancy. European contract manufacturers with Asian partnerships capture preference for US commercialization strategies.
- Emergency Supply:Surge capacity activation for stock-out remediation or pandemic response. Limited qualified inventory constrains this channel to pre-negotiated framework agreements.
Prevailing by transaction volume: Off-site Production. Gaining share fastest: Hybrid Model.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bharat-Netherlands Pharmaceutical Special Economic Zone in Gujarat anchors concentrated API manufacturing investment through tax holidays and duty exemptions for export-oriented units.
United States
FDA pre-approval inspection cycles and warning letter enforcement drive sponsor demand for qualified domestic capacity. The IRA's domestic production incentives favor reshoring of high-potency oncology API synthesis. Greater Boston's biotech corridor concentrates peptide development programs requiring specialized containment infrastructure.
India
CDSCO's alignment with ICH Q3A/Q3B guidelines reduces dual-registration burdens for export manufacturers. PLI scheme incentives for active pharmaceutical ingredients attract greenfield fermentation capacity. Hyderabad and Visakhapatnam clusters dominate synthetic chemistry scale-up for US-bound generic APIs.
Switzerland
Swissmedic's stringent GMP standards and proximity to Basel-based pharma innovators sustain premium pricing for biologics-grade production. Containment infrastructure investments target orphan drug and high-potency oncology pipelines. Visp and Basel regions anchor microbial fermentation capacity for European biotech sponsors.
China
NMPA's convergence with ICH quality standards facilitates parallel filing for domestic and export markets. Dual carbon goals and environmental compliance upgrades reshape solvent-intensive synthetic routes. Yangtze River Delta clusters concentrate multi-ton reactor capacity for intermediate and API commercial supply.
Singapore
EMA-equivalent inspection protocols and trade agreement access position the city-state as a dual-continent supply hub. Biologics manufacturing incentives under the Economic Development Board attract continuous processing technology investments. Tuas Biomedical Park anchors integrated development-to-commercial pathways for Asia-Pacific biotech sponsors.
API Contract Manufacturing Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with synthesis services concentrating around established containment infrastructure while quality control and analytical services fragment across regional laboratories. The vendor base organizes into three archetypes: integrated development-to-commercial platforms, fermentation-specialized biologics manufacturers, and synthetic chemistry scale-up operators. M&A activity targets contiguous capability gaps, while capacity expansion focuses on single-use bioreactor deployment and high-containment suite additions.
Within the integrated platform tier, Lonza and Catalent exemplify the development-to-commercial pathway model that compresses technology transfer timelines for biotech sponsors. WuXi AppTec occupies a position at the scale-driven end of synthetic chemistry manufacturing, anchoring multi-ton reactor capacity serving commercial-stage programs. These three entities represent distinct competitive vectors—bioprocessing integration, North American regulatory proximity, and Asian manufacturing scale—that structure procurement decisions across sponsor quality agreements.
| Leading Market Players |
|---|
| Lonza |
| Catalent |
| Piramal Pharma Solutions |
| Alcami Corporation |
| Sandoz AG |
| CordenPharma International |
| Pfizer CentreOne |
| WuXi AppTec |
| Evonik Industries AG |
| Others |
Supply Flow & Price Mechanics
Single-use bioreactor adoption in peptide API production simultaneously compresses capital deployment timelines and concentrates supply relationships with contract manufacturers possessing validated disposable infrastructure. This technology shift redraws cost economics around campaign flexibility rather than per-unit optimization, anchoring pricing power with European and North American facilities serving biotech sponsors.
Pricing Analysis
Volume-margins split sharply between commercial-stage generics and development-stage specialty APIs. Three-tier pricing structure across premium containment-grade, standard GMP-certified, and economy intermediate supply tiers reflects certification depth and inspection history. Pricing pressure stems from Indian CDSCO-aligned manufacturers capturing share in US-bound generic programs through cost efficiency. Small-molecule oncology developers show lowest price sensitivity; commodity intermediate buyers exhibit highest.
Supply Chain Analysis
Freight cost volatility for temperature-controlled biologics shipments is reshaping geographic sourcing decisions for US and EU sponsors. API supply concentrates in India, China, and Switzerland, with Hyderabad and Basel anchoring distinct capability clusters. Raw material dependencies span biologics-grade media, halogenated solvents under REACH pressure, and high-potency containment equipment. Single-source fermentation train vulnerability in Asian clusters poses structural risk. Distribution runs through qualified contract manufacturer networks with FDA establishment history.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
API contract manufacturing operates as a supply-constrained market where high-containment engineering talent scarcity props pricing for oncology-focused programs. Capacity bottlenecks in qualified containment infrastructure sustain margin premiums for incumbent specialists.
For Market Incumbents: Lock in sponsor relationships through multi-year quality agreements specifying geographic redundancy clauses. Expand high-containment suite capacity in Switzerland and Singapore to capture orphan drug pipeline volume. Defend against emerging single-use bioreactor specialists by anchoring stainless steel fermentation expertise for commercial-scale peptide supply. For New Entrants and Emerging Players: Capture white-space in complex generic bioequivalence services for long-acting injectables, where FDA standards evolution outpaces incumbent analytical capacity. Target mid-scale biotech sponsors in Massachusetts and California requiring rapid campaign turnaround. Lead with continuous flow chemistry capabilities as differentiation against batch-oriented established vendors. For Investors and Strategic Acquirers: Exit pathways concentrate in platform acquisitions by large pharma seeking captive API supply security. Five-to-ten year viability favors contract manufacturers with dual-continent validated facilities and CDSCO-FDA inspection alignment. Watch for ICH Q3A/Q3B guideline expansion into new molecular modalities as inflection signal for analytical services demand.| Strategic Initiative | Industry Significance |
|---|---|
| High-Containment Capacity Expansion | Orphan drug designations in the EU and US pull volume toward qualified European facilities with proven containment infrastructure. |
| Continuous Flow Chemistry Adoption | Microreactor convergence with process analytical technology compresses batch release timelines for sponsor programs. |
| Geographic Redundancy Partnerships | Dual-continent manufacturing capabilities satisfy sponsor quality agreements requiring validated facilities across jurisdictions. |
| CDSCO Regulatory Alignment Investment | Indian manufacturers with converged Western inspection protocols capture expanded US and EU-bound API supply relationships. |
| Green Chemistry Process Redesign | REACH and EU F-Gas Regulation compliance positions contract manufacturers for preference from EU commercialization sponsors. |
Methodological Framework
FDA warning letter databases, EMA inspection outcome records, and CDSCO registration filings formed the secondary backbone for supply-side validation. Primary interviews with regulatory affairs directors at contract manufacturers, procurement leads at biotech sponsors, and containment engineering specialists informed demand-side triangulation. Bottom-up capacity assessments and top-down pipeline value projections were reconciled across the analysis window.
Historical trendline analysis of sponsor outsourcing ratios and facility qualification timelines anchored the analytical framework. Segmentation modeling spanned service type, product category, delivery model, and regional regulatory cluster dimensions. CAGRs were derived from capacity expansion announcements, sponsor pipeline disclosures, and inspection cycle duration patterns. Forecast inputs incorporated ICH guideline evolution trajectories and dual-registration burden reduction metrics.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA inspection resource allocation and REACH solvent restriction enforcement. Forecasts reflect documented assumptions around sponsor externalization rates and regulatory convergence timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Corticosteroids Market
Pharmaceuticals
Global Onychomycosis Treatment Market
Pharmaceuticals
Global Autogenous Vaccines Market
Pharmaceuticals
Metformin HCL Drugs Market
Pharmaceuticals
Intravenous Pegloticase Market
Pharmaceuticals
Advanced Parenteral Drug Market
Pharmaceuticals
Smart Pills Market
Pharmaceuticals
Xerostomia Therapeutics Market
Pharmaceuticals
Adamantane Antiviral Drugs Market
Pharmaceuticals
Hepatitis Therapeutics Market
Pharmaceuticals
Anticholinergic Drugs Market
Pharmaceuticals
Asia-Pacific Aneurysmal Subarachnoid Hemorrhage Drugs Market
Pharmaceuticals
US Pharmacy Market
Pharmaceuticals
Antiretroviral (ARV) Agents Market
Pharmaceuticals
Pharmacovigilance (PV) Market
Pharmaceuticals
Ebola Drug and Vaccine Market