
 Hydrogen Breath Test Analyzer Market | 2026-2036
Hydrogen Breath Test Analyzer Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrogen Breath Test Analyzer Market Outlook
The gap between premium laboratory analyzers and portable point-of-care units is expanding as clinical workflows fragment across centralized and decentralized settings. QuinTron Instrument Company leverages its installed base in hospital reference labs to sustain recurring consumable revenue. MD Diagnostics anchors European distribution through specialized gastroenterology channels. Commonwealth Diagnostics International competes on cost structures for outpatient clinic penetration.
A hydrogen breath test analyzer quantifies hydrogen and methane concentrations in expired breath, typically achieving detection thresholds below 10 parts per million using electrochemical or solid-state sensor arrays to diagnose carbohydrate malabsorption and bacterial overgrowth. Portable analyzers with Bluetooth connectivity and cloud-based reporting now dominate new unit shipments as ambulatory care shifts toward home-based and clinic-based testing. Laboratory analyzers employing infrared spectroscopy retain margin pools in research institutions where multi-gas quantification protocols remain essential. Electrochemical sensors lead technology adoption due to lower power requirements and reduced calibration frequency.
The FDA regulates hydrogen breath test analyzers as Class II medical devices under 21 CFR 862, requiring 510(k) premarket notification for electrochemical and chromatography-based systems. ISO 13485 quality management standards govern manufacturing processes for devices distributed across European Economic Area markets under MDR compliance obligations. Japan's PMDA enforces JIS T 0601-1 electrical safety standards for clinical measurement equipment. Stakeholders must monitor evolving reimbursement codes for functional gastrointestinal disorder diagnostics and sensor material biocompatibility requirements.
Market Dynamics
Electrochemical sensor miniaturization is compressing unit economics and fragmenting clinical workflows between centralized laboratories and ambulatory point-of-care settings, forcing vendors to recalibrate service models and pricing architectures simultaneously.
Growth Catalysts
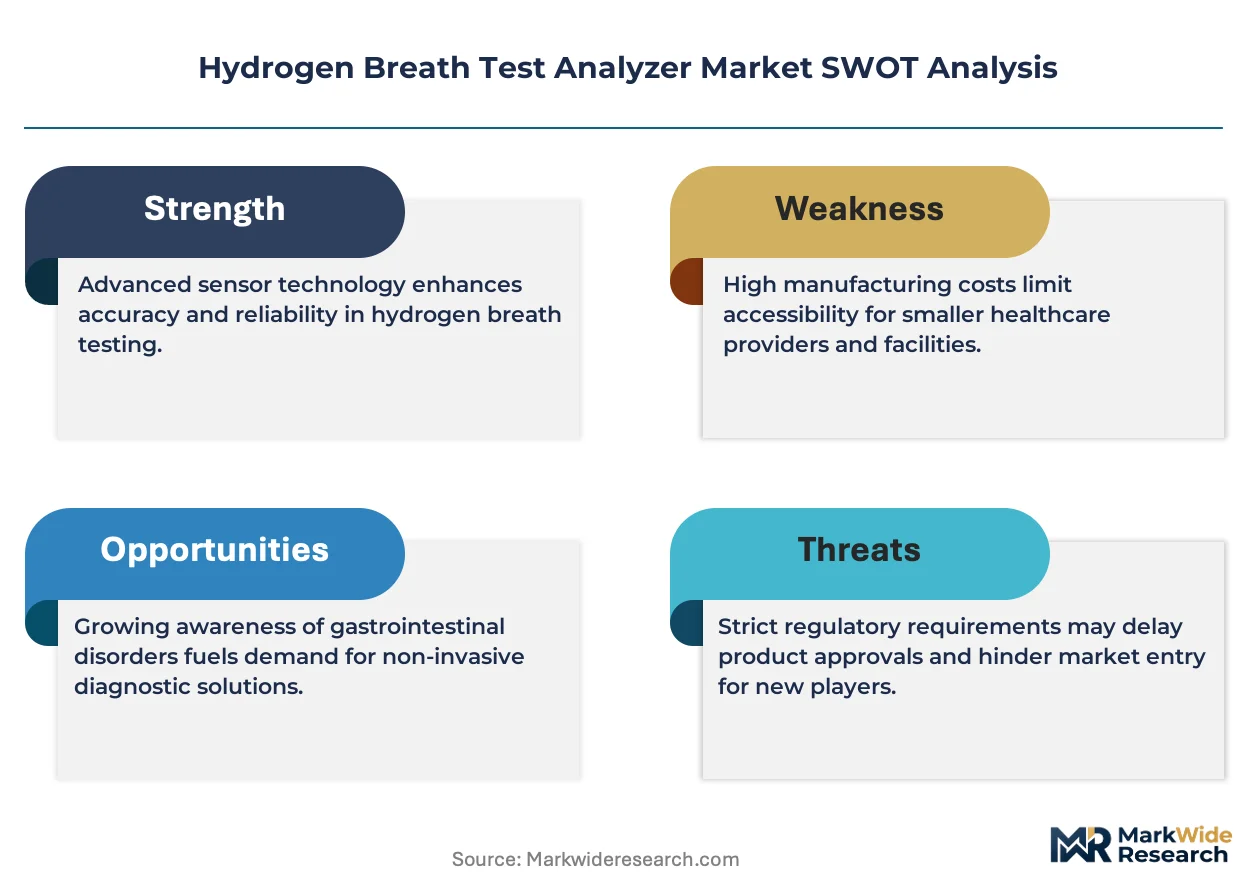
- Functional GI Disorder Diagnostics:Irritable bowel syndrome and small intestinal bacterial overgrowth detection protocols in US diagnostic laboratories are expanding test volumes as gastroenterology practices integrate breath-based carbohydrate malabsorption screening into standard care pathways.
- MDR Compliance Pathways:European Medical Device Regulation harmonization is accelerating device registration timelines for electrochemical analyzers, enabling faster market access across Germany, France, and Italy through unified conformity assessment procedures.
- Cloud-Connected Sensor Arrays:Bluetooth-enabled portable units with real-time data transmission to electronic health record systems are penetrating outpatient clinics and home-based testing environments, reducing dependency on centralized laboratory infrastructure.
Market Restraints
- Palladium Catalyst Supply Concentration:Electrochemical sensor manufacturing depends on palladium electrode materials sourced primarily from Russian and South African mining operations, exposing production costs to geopolitical supply disruptions and commodity price volatility.
- Reimbursement Code Fragmentation:US Centers for Medicare and Medicaid Services maintains non-uniform coverage determinations for hydrogen breath testing across state Medicaid programs, creating payment uncertainty that constrains capital equipment procurement in smaller clinical practices.
- Infrared Spectroscopy Substitution:Laboratory-grade multi-gas analyzers employing nondispersive infrared technology retain performance advantages for research protocols requiring simultaneous methane, hydrogen, and carbon dioxide quantification, limiting electrochemical penetration in academic medical centers.
Strategic Opportunities
- Japanese Home Care Expansion:METI's promotion of decentralized preventive healthcare under the Society 5.0 framework is creating regulatory tailwinds for portable breath analyzers in Tokyo and Osaka metropolitan home care networks.
- Pediatric Malabsorption Screening:Lactose and fructose intolerance detection in pediatric gastroenterology practices represents an underdeveloped application segment with distinct sensor calibration requirements and caregiver-friendly interface demands.
- Telemedicine Integration:Remote patient monitoring platforms are incorporating home-based breath testing modules, enabling asynchronous specialist consultation models that bypass traditional clinic-based diagnostic bottlenecks.
Industry Challenges
- Electrochemical Calibration Expertise:Sensor drift management and periodic recalibration protocols require specialized biomedical engineering competencies that remain scarce in distributed clinical settings, complicating device reliability assurance.
- Legacy Health Record Integration:Proprietary data formats from cloud-connected analyzers face interoperability friction with hospital information systems built on HL7 v2 standards, necessitating costly middleware development for enterprise deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrogen Breath Test Analyzer Market |
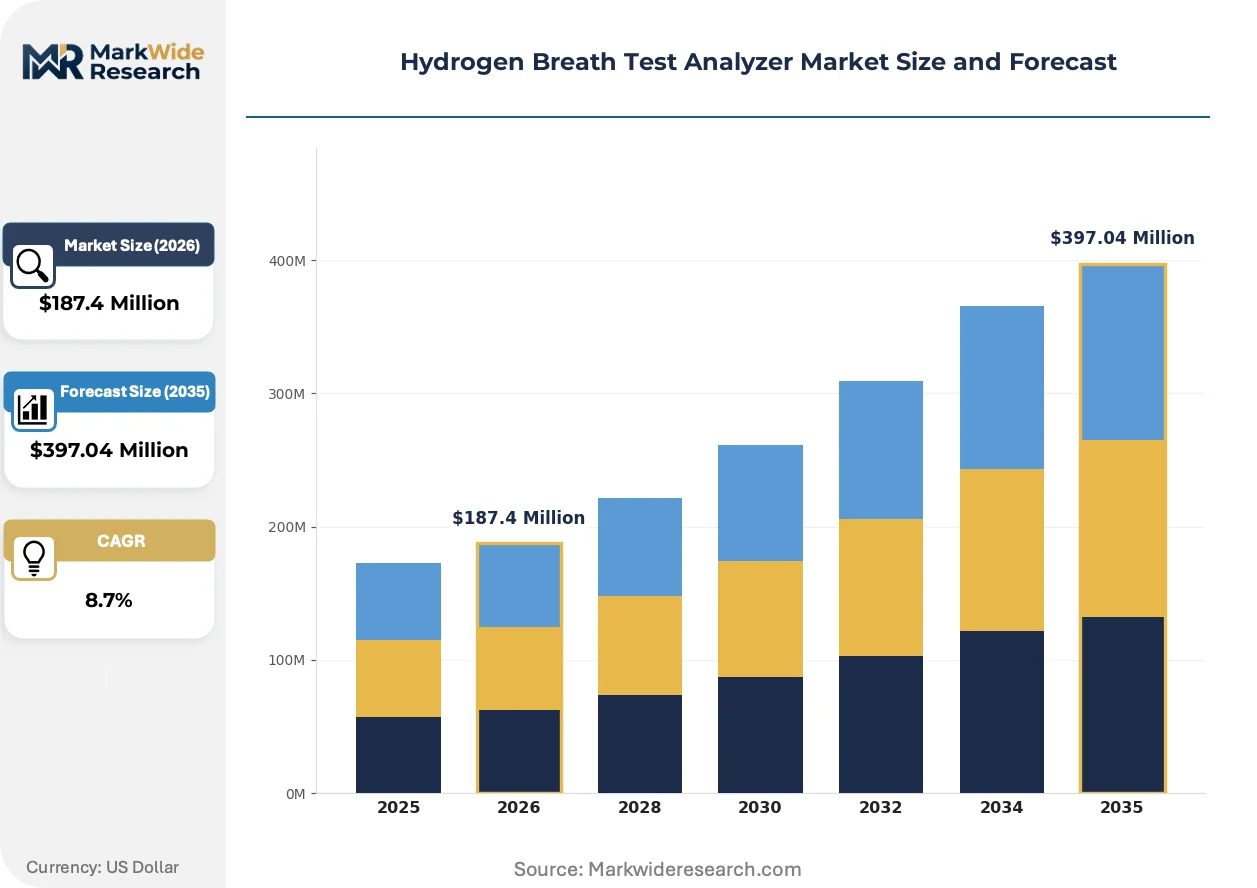
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Analyzers, Laboratory Analyzers, Handheld Devices, Software Solutions End User: Hospitals, Clinics, Diagnostic Laboratories, Research Institutions Technology: Electrochemical Sensors, Infrared Spectroscopy, Chromatography, Mass Spectrometry Application: Digestive Disorders, Food Intolerance Testing, Aerobic Metabolism, Clinical Research |
| Companies Covered | QuinTron Instrument Company, Inc., MD Diagnostics Ltd., LABORIE, Bedfont Scientific Ltd., FAN GmbH, Commonwealth Diagnostics International, CooperSurgical Inc., Fisher Scientific, coVita LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrogen Breath Test Analyzer Market Strategic Shifts
Sensor fusion architectures and algorithmic breath pattern recognition are converging to expand diagnostic specificity beyond binary malabsorption detection, reshaping competitive differentiation around software-enabled clinical decision support rather than hardware sensitivity alone.
Solid-state metal-oxide semiconductor sensors are overtaking traditional electrochemical cells in next-generation portable units. Outpatient gastroenterology clinics in Germany and the Netherlands are adopting these devices for same-day diagnostic workflows. The technology is overtaking laboratory-dependent testing models by enabling real-time results without sample transport logistics or batch processing delays.
Japan's PMDA has streamlined electrical safety certification under revised JIS T 0601-1 implementation guidelines for clinical measurement equipment. Domestic manufacturers now face reduced documentation burdens for software-as-medical-device components embedded in breath analyzers. Tokyo-based distributors are accelerating import partnerships with European sensor technology providers to capitalize on regulatory alignment.
Direct-to-consumer testing platforms are disintermediating traditional physician-referral channels for functional gut disorder screening. Subscription-based breath test kits with mail-in cartridge return systems are capturing symptom-driven demand in US and UK metropolitan markets. California and London health technology startups are building proprietary patient databases to support predictive algorithm development for personalized dietary intervention recommendations.
Hydrogen Breath Test Analyzer Market Segmentation
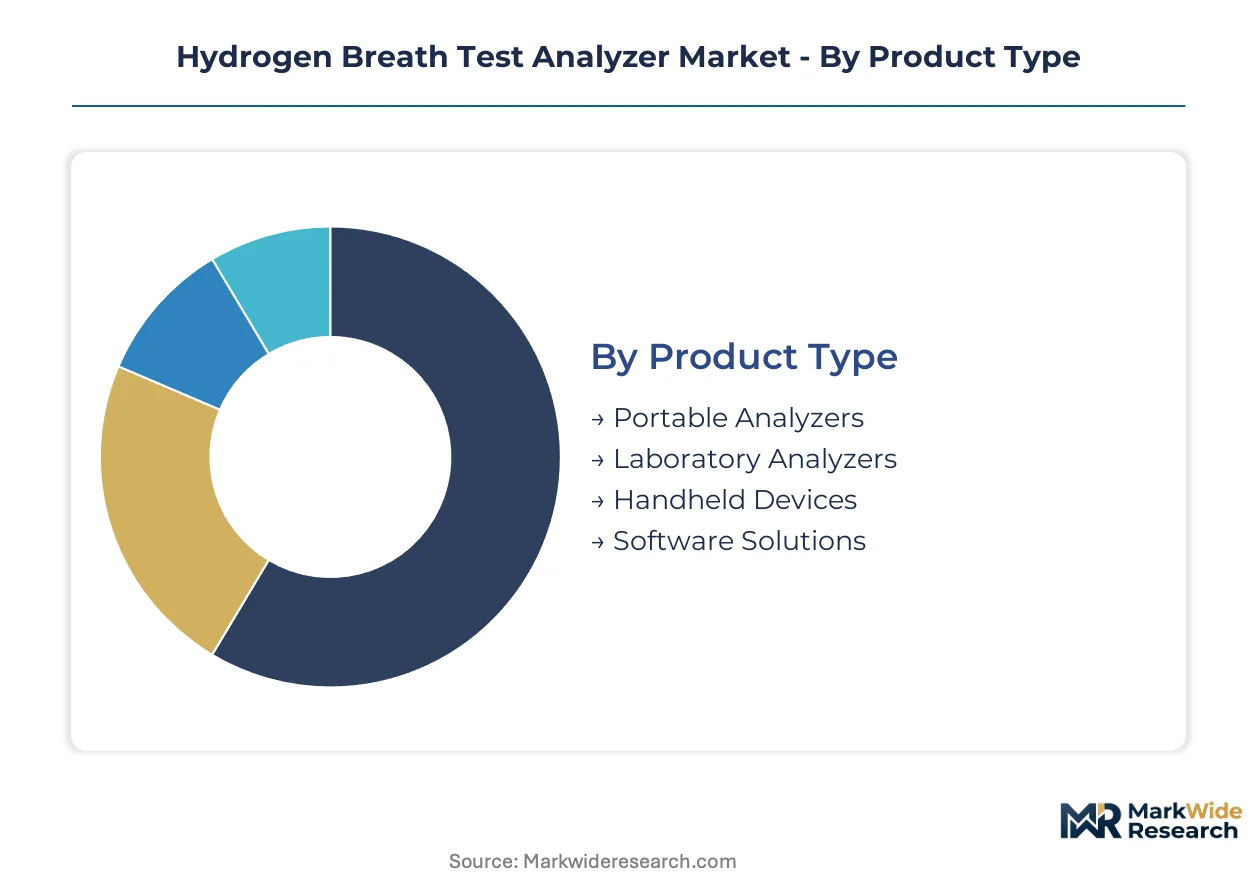
Segmentation in the hydrogen breath test analyzer market reveals how clinical workflows fragment between centralized laboratory infrastructure and distributed point-of-care environments. Product architecture, sensor technology, and end-user setting together determine procurement priorities and service model requirements.
Product Type:
Portable analyzers embed into ambulatory workflows as standalone units, while laboratory systems integrate with broader diagnostic platforms and health information networks.
- Portable Analyzers:Battery-operated units with solid-state sensor arrays achieve detection thresholds below 10 parts per million without external power infrastructure. Outpatient gastroenterology clinics in Germany and the Netherlands deploy these for same-day diagnostic workflows, eliminating sample transport logistics and batch processing delays that constrain laboratory-dependent models.
- Laboratory Analyzers:Multi-gas quantification systems employing nondispersive infrared spectroscopy or chromatography support simultaneous methane, hydrogen, and carbon dioxide measurement for research protocols. Academic medical centers retain these for functional gut disorder studies requiring granular metabolic profiling, though electrochemical alternatives erode share in routine diagnostic applications.
- Handheld Devices:Smartphone-connected breath collectors with disposable cartridge interfaces target home-based testing environments.
- Software Solutions:Cloud-based data interpretation platforms with algorithmic pattern recognition integrate sensor outputs into electronic health record systems.
Portable analyzers lead volumes today; software solutions are gaining share fastest as telemedicine platforms disintermediate traditional clinic-based diagnostic channels.
End User:
Procurement patterns diverge sharply between capital-intensive hospital systems and volume-driven outpatient operators with constrained equipment budgets.
- Diagnostic Laboratories:High-throughput facilities in the United States process hydrogen breath test panels for irritable bowel syndrome and small intestinal bacterial overgrowth screening under established reimbursement codes. These operators prioritize analyzer uptime guarantees and consumable supply security over upfront capital expenditure minimization.
- Hospitals:Integrated delivery networks consolidate breath testing within gastroenterology departments, leveraging existing biomedical engineering staff for sensor calibration and drift management. Hospital procurement committees evaluate total cost of ownership across 7-10 year equipment lifecycles, including middleware integration with HL7 v2-based health information systems.
- Clinics:Independent gastroenterology practices favor lease-based acquisition models to preserve working capital.
- Research Institutions:Academic centers demand multi-gas quantification capabilities and raw data export functionality for protocol customization.
Diagnostic laboratories lead volumes today; clinics are expanding most quickly as decentralized preventive healthcare models gain regulatory support.
Technology:
Sensor architecture determines power requirements, calibration frequency, and compatibility with portable versus stationary form factors.
- Electrochemical Sensors:Palladium electrode cells operate at reduced power with extended calibration intervals, enabling battery-powered deployment. These sensors dominate new unit shipments as manufacturers miniaturize form factors for ambulatory and home-based testing environments, though supply concentration in Russian and South African mining operations exposes production costs to commodity volatility.
- Infrared Spectroscopy:Nondispersive infrared systems retain performance advantages for simultaneous multi-gas detection in research settings. Academic medical centers specify these for metabolic studies requiring carbon dioxide co-measurement, constraining electrochemical penetration where protocol complexity outweighs portability benefits.
- Chromatography:Gas separation techniques support reference-standard calibration for regulatory compliance.
- Mass Spectrometry:High-resolution isotope detection enables advanced metabolic research applications with premium instrumentation costs.
Electrochemical sensors lead volumes today; solid-state metal-oxide semiconductor variants are climbing the fastest as next-generation portable units enter European outpatient markets.
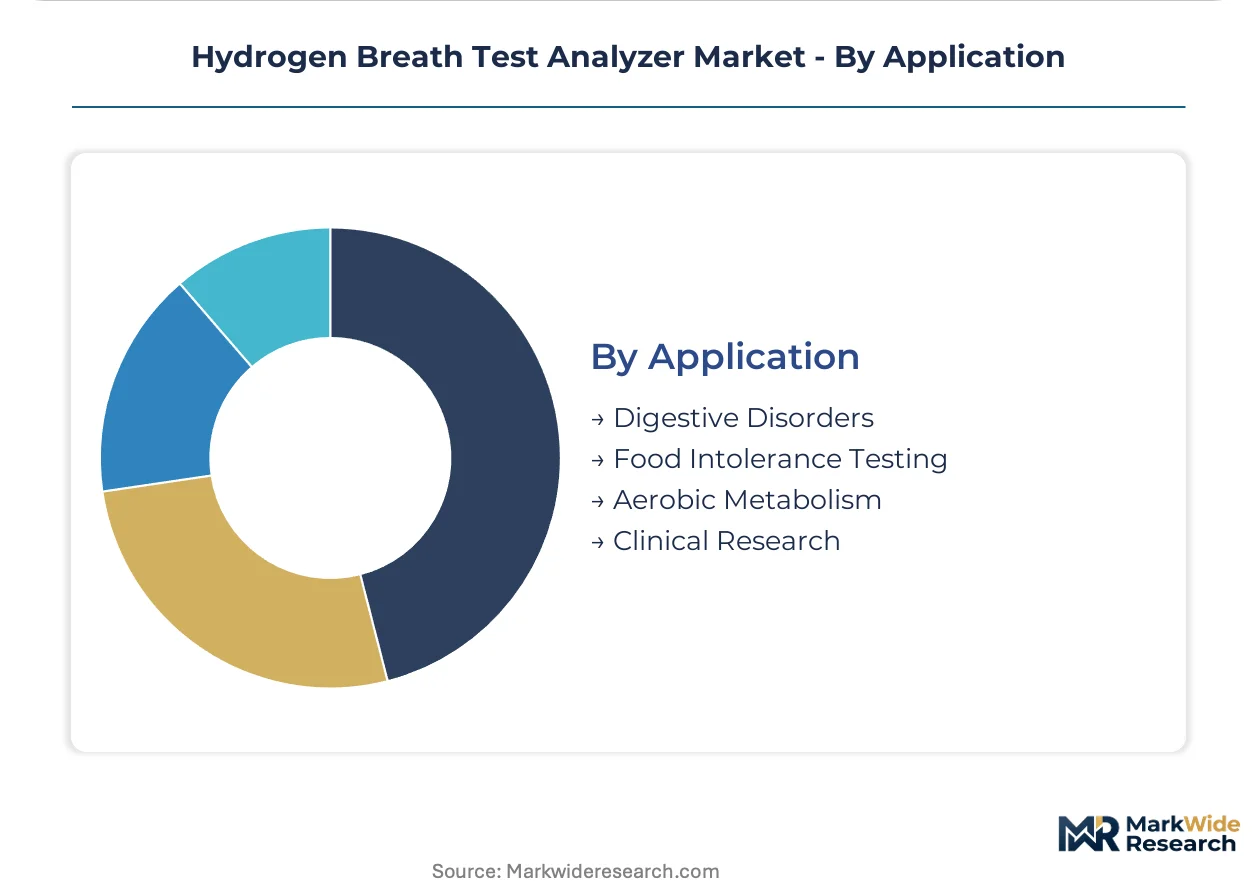
Application:
Clinical utility concentrates in functional gastrointestinal disorder detection, with emerging expansion into metabolic fitness and direct-to-consumer wellness segments.
- Digestive Disorders:Hydrogen and methane breath testing for small intestinal bacterial overgrowth and carbohydrate malabsorption constitutes the core clinical application. US gastroenterology practices integrate these protocols into standard irritable bowel syndrome evaluation pathways, driving test volume expansion as diagnostic specificity improves through algorithmic breath pattern recognition.
- Food Intolerance Testing:Lactose and fructose intolerance detection in pediatric populations represents an underdeveloped segment with distinct sensor calibration requirements. Caregiver-friendly interface demands and smaller breath sample volumes create product design constraints that differentiate pediatric-focused systems from adult-oriented platforms.
- Aerobic Metabolism:Fitness and weight management applications employ breath hydrogen as a metabolic fuel utilization indicator.
- Clinical Research:Pharmaceutical trials for functional gut disorder therapeutics utilize standardized breath testing endpoints.
Digestive disorders lead volumes today; food intolerance testing shows the steepest expansion trajectory as pediatric gastroenterology practices formalize malabsorption screening protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized biomedical engineering talent pools in gastroenterology device manufacturing anchor geographic concentration for hydrogen breath test analyzer production and adoption.
United States
Diagnostic laboratories in Massachusetts and California process high-throughput hydrogen breath test panels for irritable bowel syndrome screening under established CPT reimbursement codes. The FDA's 510(k) premarket notification pathway under 21 CFR 862 accelerates electrochemical analyzer clearances for outpatient clinic deployment. Boston's medical device cluster hosts reference labs integrating cloud-connected sensor arrays with Epic Systems EHR infrastructure.
Germany
Outpatient gastroenterology practices in Bavaria and North Rhine-Westphalia adopt solid-state metal-oxide semiconductor analyzers for same-day diagnostic workflows. EMDR harmonization through unified conformity assessment procedures enables faster device registration across German, French, and Italian markets. Munich's precision sensor manufacturing corridor supplies miniaturized electrochemical cells to portable unit assemblers.
Japan
Home care networks in Tokyo and Osaka metropolitan areas deploy Bluetooth-enabled breath analyzers under METI's Society 5.0 decentralized healthcare framework. PMDA's streamlined JIS T 0601-1 electrical safety certification reduces documentation burdens for software-as-medical-device components. Osaka's medical electronics district accelerates import partnerships with European sensor technology providers.
United Kingdom
Direct-to-consumer testing platforms in London and Manchester capture symptom-driven demand through subscription-based breath test kits with mail-in cartridge return systems. MHRA alignment with MDR post-Brexit transition maintains CE marking recognition for EU-manufactured analyzers. Cambridge's health technology startup cluster builds proprietary patient databases for predictive dietary intervention algorithms.
Netherlands
Outpatient clinics in Amsterdam and Rotterdam integrate portable analyzers with real-time data transmission to electronic health record systems. Dutch healthcare insurance reimbursement frameworks for functional gastrointestinal disorder diagnostics stabilize procurement budgets for independent gastroenterology practices. Eindhoven's sensor technology ecosystem supplies solid-state metal-oxide semiconductor components to next-generation portable unit manufacturers.
Hydrogen Breath Test Analyzer Market Competitive Environment
Top-tier vendors anchor hospital reference laboratory installations, while mid-tier specialists penetrate outpatient clinic and home-based testing environments. The vendor base stratifies across three tiers: premium laboratory system providers, portable point-of-care specialists, and direct-to-consumer platform operators. Two dominant strategic archetypes emerge: installed-base defenders leveraging recurring consumable revenue, and cloud-native disrupters bypassing traditional physician-referral channels. Competitive moves concentrate on sensor technology licensing partnerships and middleware development for health record interoperability.
Among North American-installed base defenders, QuinTron Instrument Company, Inc. exemplifies the recurring revenue archetype through hospital laboratory relationships, while Commonwealth Diagnostics International occupies a position exemplifying cost-structured outpatient clinic penetration. MD Diagnostics Ltd. represents the European distribution specialist archetype anchoring gastroenterology channel partnerships across Germany, France, and Italy.
| Leading Market Players |
|---|
| QuinTron Instrument Company, Inc. |
| MD Diagnostics Ltd. |
| LABORIE |
| Bedfont Scientific Ltd. |
| FAN GmbH |
| Commonwealth Diagnostics International |
| CooperSurgical Inc. |
| Fisher Scientific |
| coVita LLC |
| Others |
Value Chain & Pricing Dynamics
ISO 13485 quality management certification gates qualified supply access for electrochemical sensor manufacturers, separating premium-tier laboratory analyzer vendors from economy-grade portable unit assemblers and compressing margin pools for non-compliant entrants. Buyers in hospital procurement committees leverage this certification divide to negotiate service bundling terms that shift total cost of ownership calculations toward consumable lock-in rather than upfront equipment expenditure.
Pricing Analysis
Bundled consumable-service contracts dominate hospital laboratory procurement, while unbundled per-test pricing prevails in outpatient clinic and direct-to-consumer channels. Three-tier pricing structure across premium, standard, and economy levels separates infrared spectroscopy laboratory systems from electrochemical portable units and handheld smartphone-connected collectors. Pricing pressure stems from palladium electrode material cost volatility sourced from Russian and South African mining operations. Diagnostic laboratories exhibit lowest price sensitivity due to established CPT reimbursement codes, while independent gastroenterology practices in the United States and Germany face acute capital constraint.
Supply Chain Analysis
Direct-to-hospital sales channels handle high-throughput diagnostic laboratory demand, while specialized gastroenterology distributors serve fragmented outpatient clinic networks across Germany, France, and Italy. Electrochemical sensor manufacturing draws from palladium electrode materials, solid-state metal-oxide semiconductor substrates, and Bluetooth connectivity modules concentrated in South Korean and Japanese electronics corridors. Single-source vulnerability in palladium catalyst supply exposes production schedules to geopolitical disruption. Distribution runs through regional medical device distributors with ISO 13485 certification and MDR compliance capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on electrochemical sensor miniaturization cost curves and the premium-tier shift toward software-enabled algorithmic breath pattern recognition that commands higher per-test pricing.
For Market Incumbents: Hedge against solid-state metal-oxide semiconductor substitution by deepening captive supply relationships with Munich and Eindhoven precision sensor manufacturers. Secure palladium electrode inventory buffers against Russian supply disruption. Reinforce hospital reference laboratory installed bases through exclusive consumable supply agreements that raise switching costs for QuinTron and MD Diagnostics accounts. For New Entrants and Emerging Players: Direct-to-consumer telemedicine platforms represent the most penetrable white-space channel, bypassing traditional physician-referral bottlenecks through subscription-based breath test kit models. Target pediatric food intolerance screening in United States metropolitan markets where caregiver-friendly interface demands remain underserved. Pursue FDA 510(k) clearance for Bluetooth-enabled portable units with cloud-based EHR integration as the primary go-to-market validation. For Investors and Strategic Acquirers: Roll-up economics work for regional diagnostic laboratory networks because fragmented outpatient gastroenterology practices lack scale to negotiate favorable consumable pricing. Five-to-ten year viability hinges on reimbursement code expansion for functional gastrointestinal disorder diagnostics. Monitor CMS National Coverage Determination proceedings for hydrogen breath testing as the inflection signal for capital equipment procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerates electrochemical analyzer clearance for outpatient clinic deployment under 21 CFR 862. |
| CE Marking Pathway | Enables unified MDR conformity assessment across German, French, and Italian distribution channels. |
| Hospital System Partnership | Secures reference laboratory installed base with Epic Systems EHR middleware integration. |
| Software Companion Development | Supports algorithmic breath pattern recognition for irritable bowel syndrome diagnostic specificity. |
| Reimbursement Strategy | Aligns CPT code expansion with gastroenterology practice test volume growth targets. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with biomedical engineers at hospital purchasing committees, GPO contracts managers, and regulatory affairs leads at electrochemical sensor manufacturers with secondary validation against FDA 510(k) filings, CMS reimbursement databases, and ISO 13485 certification registries. Bottom-up unit shipment estimates from portable and laboratory analyzer categories were cross-checked against top-down addressable market calculations for functional gastrointestinal disorder diagnostics.
Segment-weighting approaches distributed value across product type, end user, technology, and application dimensions, with electrochemical sensor adoption curves and solid-state metal-oxide semiconductor penetration rates serving as primary forecast inputs. CAGRs were derived from installed base growth projections and consumable revenue per analyzer lifecycle assumptions across the projection horizon.
The model assumes a particular technology adoption path; alternative pathways for infrared spectroscopy retention in academic medical centers would alter the outlook for electrochemical portable unit share gains. Forecasts reflect base-case assumptions regarding MDR harmonization timelines and palladium supply stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Asia-Pacific Womens Health Diagnostics Market
Diagnostics
Global Urinalysis Market
Diagnostics
H. Pylori Breath Test Kit Market
Diagnostics
Sperm Density Testing Market
Diagnostics
Respiratory Pathogen Testing Kits Market
Diagnostics
Rapid Oral Fluid Screening Device Market
Diagnostics
Global Syphilis Immunoassay Diagnostics Market
Diagnostics
LDL Test Market
Diagnostics
Epilepsy Diagnosis and Treatment Market
Diagnostics
Fructosamine Reagents Market
Diagnostics
Global Hemoglobin A1c Testing Devices Market
Diagnostics
Global Phytopathological Disease Diagnostics Market
Diagnostics
Middle East and Africa in-Vitro Diagnostics Market
Diagnostics
North America Thyroid Cancer Diagnostics Market
Diagnostics
Cushing's Syndrome Diagnostics and Therapeutics Market
Diagnostics
Global Lyme Disease Diagnostic Market