
 Europe Meglitinide Market | 2026-2036
Europe Meglitinide Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Meglitinide Market Foresight
Endocrinology specialist shortages across Southern and Eastern Europe are reorganizing patient referral flows toward centralized diabetes centers. Novo Nordisk leverages its insulin-centric portfolio to cross-sell meglitinide formulations through integrated care networks. Novartis sustains competitive presence via established cardiovascular-metabolic therapeutic franchises. Glenmark anchors generic repaglinide supply across price-sensitive Central European markets.
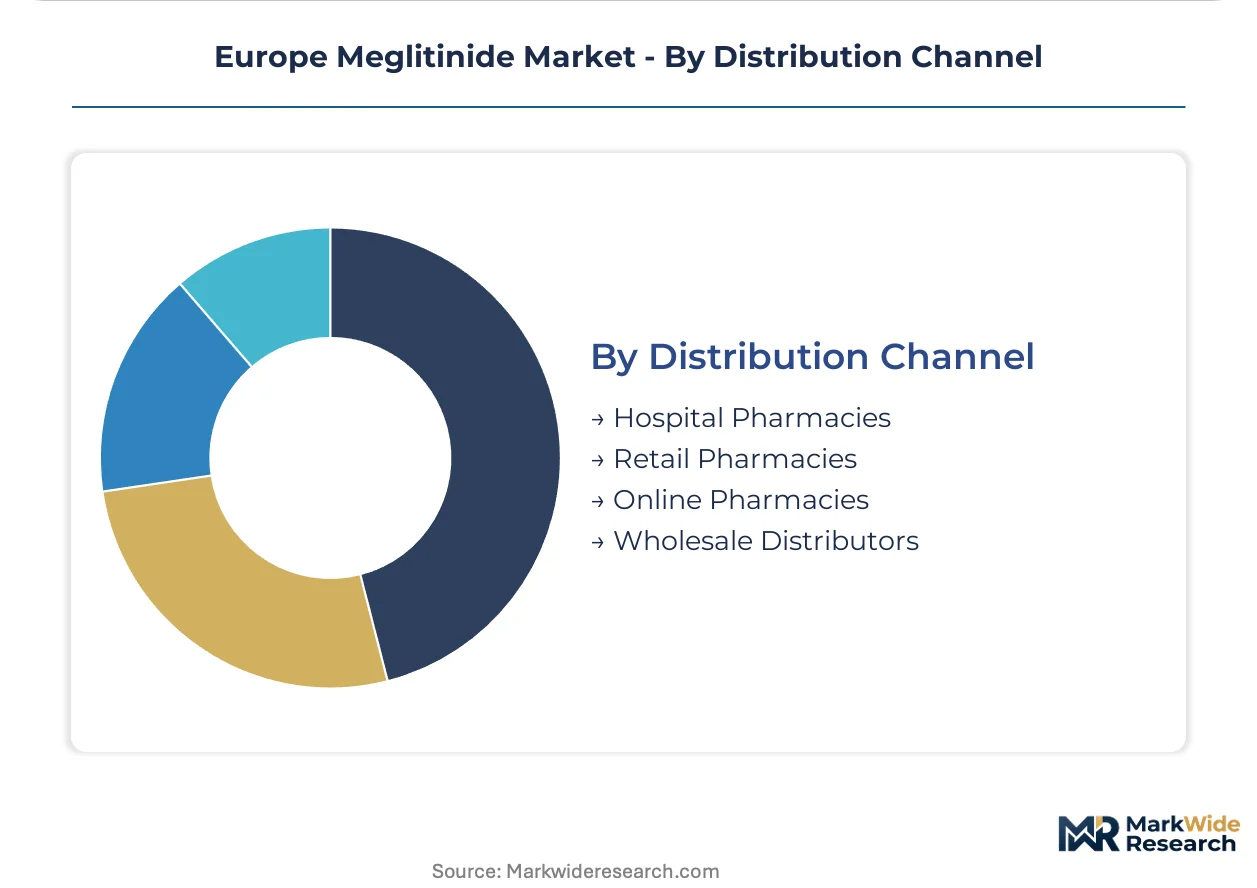
Meglitinides constitute a class of non-sulfonylurea insulin secretagogues with rapid onset and short duration of action, binding to SUR1 subunits of pancreatic beta-cell KATP channels to stimulate prandial glucose-dependent insulin release. The primary commercial purpose centers on postprandial glycemic control in type 2 diabetes patients with erratic meal timing or sulfonylurea intolerance. Repaglinide dominates product type revenue due to broader prescriber familiarity and reimbursement depth across EU member states, while nateglinide occupies a narrower niche favoring milder glucose excursions. Online pharmacies represent the fastest-growing distribution channel, though hospital pharmacies still capture the deepest volume pools through tender-based procurement.
EMA centralized marketing authorization procedures and the EU Falsified Medicines Directive shape product serialization requirements and batch traceability standards across the value chain. REACH compliance for active pharmaceutical ingredient impurities and national health technology assessments in France, Germany, and Italy govern pricing and market access timelines. Stakeholders must monitor biosimilar insulin pricing pressure and SGLT2 inhibitor guideline elevation, as these forces redirect payer budgets and clinician prescribing hierarchies within the oral antidiabetic space.
Market Dynamics
EMA pharmacovigilance frameworks and the EU Medical Device Regulation are compressing product registration timelines while elevating batch traceability requirements across meglitinide supply chains. Hospital pharmacy tender systems in Germany, France, and Italy now embed serialization compliance as a gatekeeper criterion for contract awards.
Growth Catalysts
- EU Falsified Medicines Directive:Mandatory serialization infrastructure investments are locking in compliant suppliers and raising barriers for marginal competitors, consolidating procurement flows toward certified manufacturers.
- Centralized diabetes centers:Endocrinology specialist shortages across Southern and Eastern Europe are reorganizing patient referral flows toward high-volume treatment hubs with standardized prescribing protocols.
- Repaglinide familiarity:Broader prescriber experience with this specific molecule drives deeper reimbursement negotiations and faster formulary inclusion across EU member states.
Market Restraints
- SGLT2 inhibitor elevation:Cardiovascular outcome data from empagliflozin and dapagliflozin trials are redirecting payer budgets and clinician hierarchies away from prandial insulin secretagogues.
- Active pharmaceutical ingredient concentration:Repaglinide API synthesis depends on a limited supplier base concentrated in India and China, exposing European formulators to shipping disruptions and customs delays.
- REACH compliance costs:ECHA impurity profiling requirements for nateglinide intermediates are extending quality validation cycles and raising manufacturing overhead for smaller generic entrants.
Strategic Opportunities
- Online pharmacy channels:E-prescription harmonization under the EU Cross-Border Healthcare Directive is enabling direct-to-patient fulfillment models that bypass traditional wholesale markups.
- Poland and Romania:Underpenetrated diabetes care infrastructure in these markets offers first-mover positioning for integrated care networks combining diagnostics, prescribing, and adherence monitoring.
- Fixed-dose combinations:Convergence of meglitinide pharmacology with SGLT2 inhibitor mechanisms presents formulation innovation pathways for differentiated patent-protected positioning.
Industry Challenges
- Pharmacovigilance staffing:EMA periodic safety update report requirements demand specialized medical writing capabilities that contract research organizations struggle to staff at competitive rates.
- Legacy ERP integration:Batch traceability systems must interface with hospital pharmacy inventory platforms that run on incompatible software architectures, raising implementation timelines and validation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Meglitinide Market |
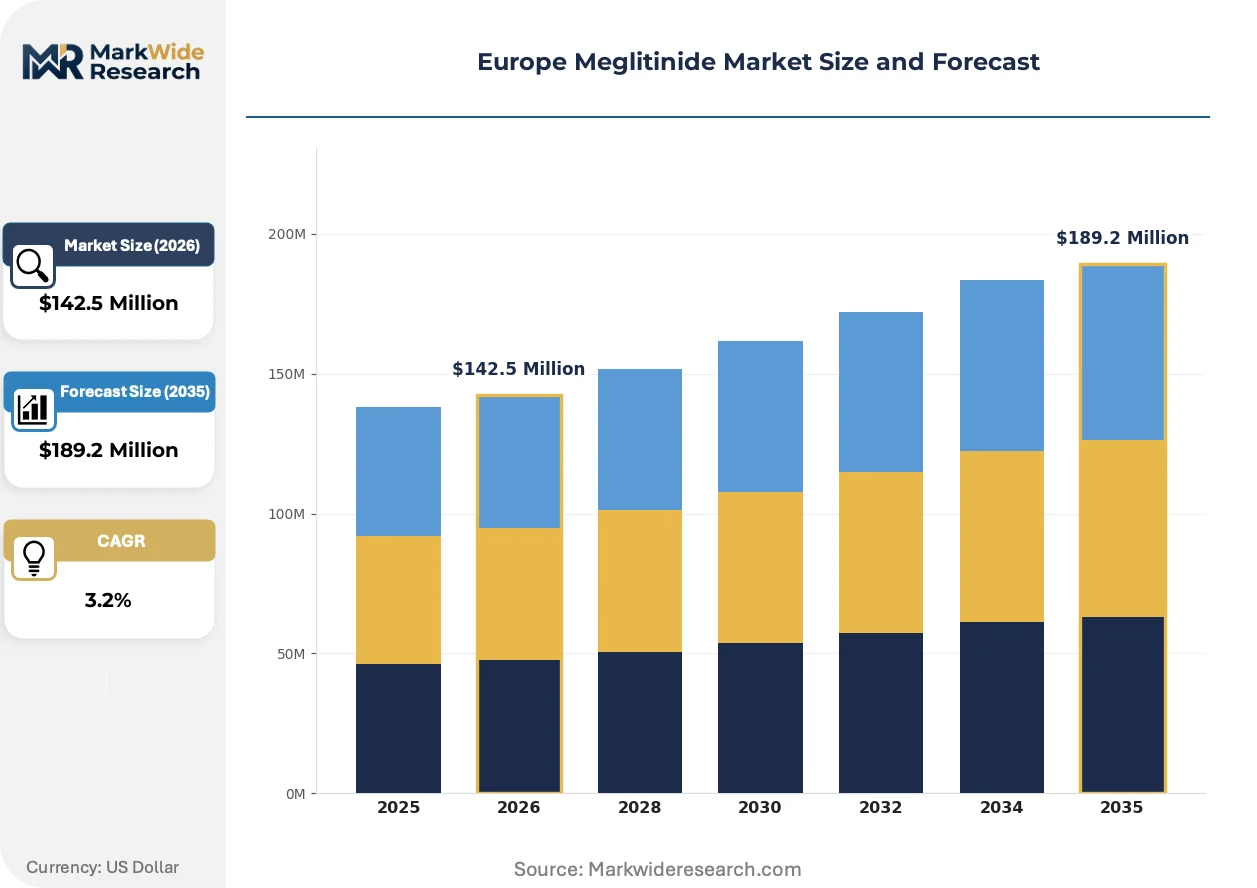
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $189.2 Million |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Repaglinide, Nateglinide, Mitiglinide, Others Therapy Area: Type 2 Diabetes, Prediabetes, Gestational Diabetes, Latent Autoimmune Diabetes, Others End User: Specialty Clinics, Outpatient Clinics, Diabetes Centers, Pharmacy Chains Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Wholesale Distributors |
| Companies Covered | Novo Nordisk, Novartis, Glenmark, Boehringer Ingelheim, Biocon, Kissei Pharmaceuticals, Fresenius Kabi AG, Teva Pharmaceutical Industries Ltd, Sanofi, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Meglitinide Market Shifts & Advancements
Digital therapeutics and connected delivery devices are reshaping how prandial glucose control is monitored and reimbursed across European diabetes care networks. Three intersecting developments are altering competitive positioning.
Connected pen injector systems with dose-capture sensors are fragmenting the traditional boundary between drug and device reimbursement categories. Specialty diabetes clinics in Germany and the Netherlands are piloting these platforms for repaglinide patients with erratic meal timing. The technology is fragmenting procurement decisions across pharmacy, medical device, and digital health budget silos, complicating vendor access strategies.
EMA centralized marketing authorization procedures now require pediatric investigation plans for all new diabetes therapies, extending development timelines by two to four years. This regulatory expansion affects meglitinide line extensions and fixed-dose combination filings most acutely. Manufacturers are responding by prioritizing adult-only indications and deferring pediatric submissions to preserve cash flow.
Hospital pharmacy consortia in France and Italy are consolidating tender volumes into multi-year framework agreements that lock in pricing and freeze out secondary suppliers. This buyer concentration is displacing spot-market transactions and raising qualification barriers for generic entrants. The shift is most visible in Lombardy and Île-de-France, where regional health authorities now manage procurement for dozens of facilities through single negotiation desks.
Europe Meglitinide Market Segmentation
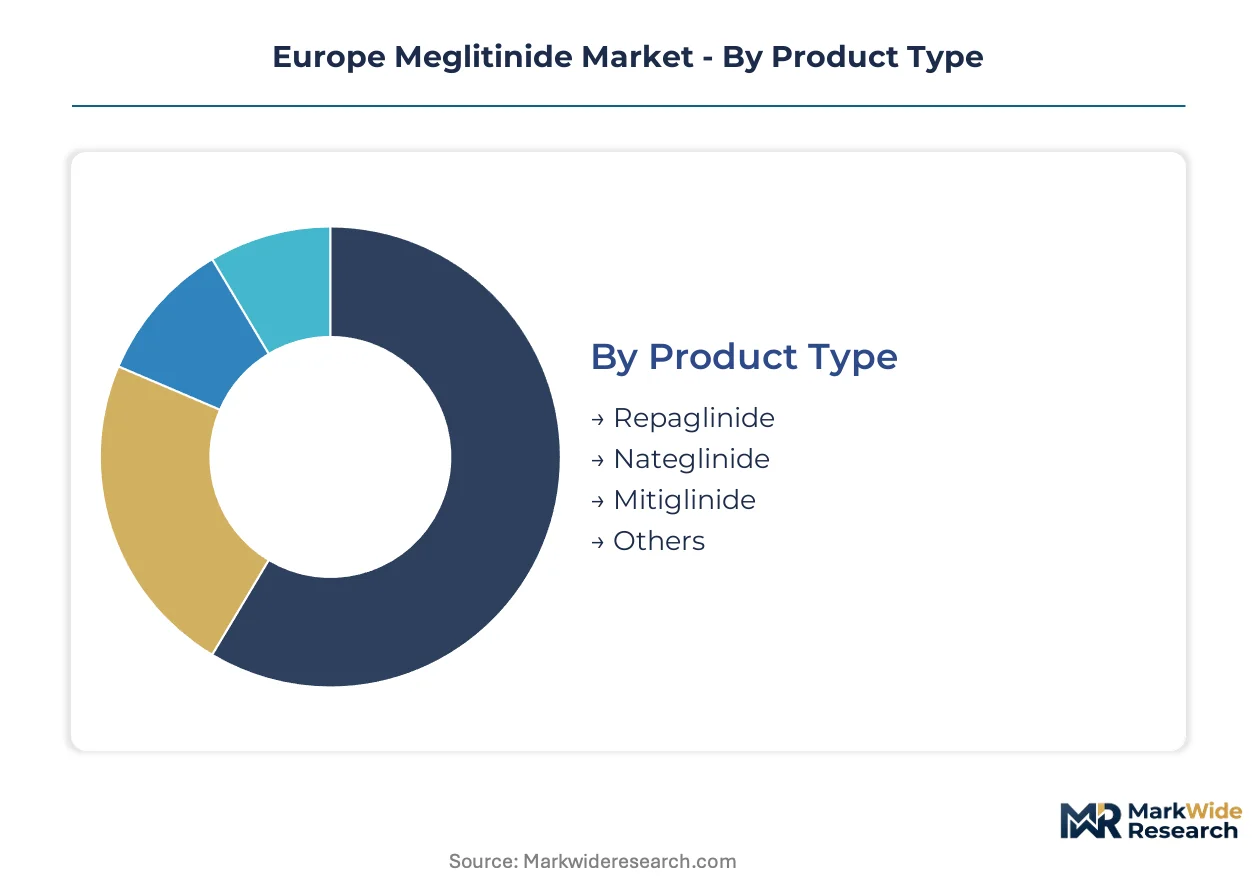
Channel dynamics across Europe's meglitinide market determine which formulations reach patients and how procurement economics unfold. Segmentation reveals where tender systems, reimbursement depth, and prescriber familiarity concentrate commercial opportunity.
Product Type:
Hospital pharmacy tender systems in Germany, France, and Italy filter product availability through reimbursement familiarity and batch traceability compliance, channeling volume toward established molecules while constraining newer entrants.
- Repaglinide:A carbamoylmethyl benzoic acid derivative with rapid onset and short duration, binding SUR1 subunits to stimulate prandial insulin release. Demand concentrates in German and Italian hospital pharmacies where prescriber familiarity drives deeper formulary inclusion and tender contract awards.
- Nateglinide:A D-phenylalanine derivative with faster onset but shorter glucose-lowering effect than repaglinide, favoring patients with milder postprandial excursions. French and Dutch specialty clinics favor this profile for elderly populations with irregular meal patterns, though reimbursement depth lags repaglinide across most EU markets.
- Mitiglinide:A potassium channel blocker with shorter half-life than repaglinide, available in limited European markets through Japanese originator licensing.
- Others:Experimental secretagogues and regional formulations lacking centralized EMA authorization, circulating primarily in non-hospital retail channels.
Repaglinide dominates installed base. Nateglinide is where expansion concentrates among patients with sulfonylurea intolerance.
Therapy Area:
Cost tier stratification across European healthcare systems allocates meglitinides to patient populations where prandial control justifies premium pricing over sulfonylurea alternatives.
- Type 2 Diabetes:The core addressable population with residual beta-cell function requiring prandial glucose control. Hospital pharmacies in Lombardy and Île-de-France capture the deepest volume pools through regional tender consolidation.
- Prediabetes:An emerging off-label use concentrated in German preventive care networks, though reimbursement remains fragmented across statutory health insurance funds.
- Gestational Diabetes:Limited adoption due to teratogenicity concerns and insulin preference in obstetric protocols; niche presence in French maternal-fetal medicine centers.
- Latent Autoimmune Diabetes:Rare application where rapid insulin secretagogue action bridges diagnostic uncertainty; confined to academic medical centers in Belgium and the Netherlands.
- Others:Cystic fibrosis-related diabetes and steroid-induced hyperglycemia represent experimental territories without established reimbursement pathways.
Type 2 Diabetes anchors revenue concentration. Prediabetes represents the steepest expansion trajectory as preventive pharmacology gains traction.
End User:
Volume flows toward settings where endocrinology specialist density enables complex prescribing decisions and integrated care protocols.
- Specialty Clinics:Concentrated in German metropolitan regions and Dutch academic networks, these settings manage polypharmacy in patients with erratic meal timing.
- Outpatient Clinics:Polish and Romanian primary care settings with limited specialist access, where meglitinides compete against sulfonylureas on price.
- Diabetes Centers:High-volume hubs in Southern and Eastern Europe reorganizing patient referral flows amid specialist shortages; standardized protocols favor repaglinide familiarity.
- Pharmacy Chains:Spanish and Portuguese retail networks with limited prescriber influence, capturing residual demand from stabilized patients.
Diabetes Centers dominate installed base. Specialty Clinics are where expansion concentrates as integrated care networks deepen.
Distribution Channel:
Margin structure varies sharply across channels, with hospital tenders compressing prices while online fulfillment captures premium convenience pricing.
- Hospital Pharmacies:Tender-based procurement systems in Germany, France, and Italy embed serialization compliance as contract gatekeepers, consolidating flows toward certified manufacturers.
- Retail Pharmacies:Community-based dispensing in Spain, Portugal, and Greece with higher per-unit margins but fragmented volume.
- Online Pharmacies:E-prescription harmonization under the EU Cross-Border Healthcare Directive enables direct-to-patient fulfillment bypassing wholesale markups.
- Wholesale Distributors:Secondary sourcing for rural and peripheral markets with higher logistics overhead and inventory carrying costs.
Hospital Pharmacies dominate installed base. Online Pharmacies are where expansion concentrates as digital health infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EMA pharmacovigilance frameworks govern the dominant Western European geography, compressing product registration timelines while elevating batch traceability requirements across meglitinide supply chains. Hospital pharmacy tender systems in Germany, France, and Italy embed serialization compliance as gatekeeper criteria for contract awards.
Germany
Hospital pharmacy procurement concentrates volume in metropolitan regions with standardized prescribing protocols. Statutory health insurance funds under the G-BA framework negotiate reimbursement depth for repaglinide formulations. The Rhine-Ruhr and Bavarian hospital consortia consolidate tender volumes into multi-year framework agreements that freeze out secondary suppliers.
France
Regional health authorities in Île-de-France manage procurement for dozens of facilities through single negotiation desks. ANSM pharmacovigilance reporting requirements extend quality validation cycles for nateglinide intermediates. The Paris basin diabetes centers reorganize patient referral flows amid endocrinology specialist shortages.
Italy
Lombardy regional health authorities capture the deepest meglitinide volume pools through tender-based procurement systems. AIFA pricing negotiations favor established molecules with broader prescriber familiarity. The Milan-Turin corridor anchors specialty clinic density for complex polypharmacy management.
Poland
Underpenetrated diabetes care infrastructure offers first-mover positioning for integrated care networks. The national health fund reimbursement pathways remain fragmented across voivodeship boundaries. The Warsaw-Łódź corridor concentrates emerging diabetes center capacity with standardized protocols.
Netherlands
Dutch academic networks pilot connected pen injector systems for repaglinide patients with erratic meal timing. The Health and Youth Care Inspectorate governs digital therapeutics reimbursement categories. The Randstad cluster fragments procurement decisions across pharmacy, medical device, and digital health budget silos.
Europe Meglitinide Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with hospital pharmacy tender systems filtering availability through reimbursement familiarity and batch traceability compliance. The structure channels volume toward established molecules while constraining newer entrants. Three archetypes dominate: insulin-centric portfolio cross-sellers, cardiovascular-metabolic franchise holders, and generic API suppliers for price-sensitive markets. Competitive moves concentrate on fixed-dose combination development and integrated care network partnerships.
Within the integrated leader tier, Novo Nordisk and Novartis exemplify divergent strategic positioning. Novo Nordisk leverages its insulin-centric portfolio to cross-sell meglitinide formulations through established care networks. Novartis sustains competitive presence via its cardiovascular-metabolic therapeutic franchises. Among generic specialists, Glenmark anchors supply across Central European markets where price sensitivity governs procurement decisions.
| Leading Market Players |
|---|
| Novo Nordisk |
| Novartis |
| Glenmark |
| Boehringer Ingelheim |
| Biocon |
| Kissei Pharmaceuticals |
| Fresenius Kabi AG |
| Teva Pharmaceutical Industries Ltd |
| Sanofi |
| Others |
Supply & Pricing Matrix
Hospital pharmacy tender consolidation in Germany, France, and Italy creates scale economies that compress unit economics while elevating qualification barriers for secondary suppliers, establishing price floors that reflect serialization compliance costs rather than manufacturing input alone.
Pricing Analysis
Price spreads between Western and Central European markets reflect reimbursement depth disparities across statutory health insurance frameworks. Pricing stratifies across premium, standard, and economy tiers based on EMA centralized authorization status and batch traceability certification levels. Cost compression in the generic tier intensifies because Glenmark and Teva compete for Central European hospital contracts. Outpatient clinics in Poland and Romania exhibit highest price sensitivity, while German diabetes centers prioritize formulary familiarity over unit cost.
Supply Chain Analysis
Container availability constraints on India-Europe and China-Europe trade lanes extend API delivery timelines for repaglinide intermediates, forcing European formulators to carry elevated safety stock. Active pharmaceutical ingredient production concentrates in India and China, with formulation and packaging anchored in Germany and Italy. Repaglinide synthesis draws from specialized benzoic acid derivatives and chiral amine precursors subject to REACH impurity profiling. Single-source vulnerability in Indian API suppliers exposes the value chain to customs delays and export license disruptions. Distribution runs through hospital pharmacy consortia in metropolitan regions, bypassing traditional wholesale tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe meglitinide market is experiencing high-growth disruption as EMA pediatric investigation plan requirements extend development timelines for line extensions, favoring incumbents with established adult-only indications and freezing out capital-constrained entrants.
For Market Incumbents: Compound formulary lock-in through multi-year hospital pharmacy framework agreements that embed serialization compliance as non-negotiable contract terms. Deepen backward integration into repaglinide API supply through captive manufacturing partnerships in India, insulating against shipping disruptions and customs delays that threaten tender fulfillment.
For New Entrants and Emerging Players: Lead with online pharmacy channel specialization under EU Cross-Border Healthcare Directive harmonization, targeting stabilized type 2 diabetes patients in Spain and Portugal where retail pharmacy influence remains limited. Poland and Romania offer the most penetrable geography given underdeveloped diabetes center infrastructure and fragmented national health fund reimbursement pathways.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors generic API suppliers with REACH-compliant manufacturing footprints and established hospital pharmacy tender relationships. Long-term viability hinges on fixed-dose combination development capabilities that merge meglitinide pharmacology with SGLT2 inhibitor mechanisms. Monitor EMA pediatric investigation plan waiver approvals as the critical signal for pipeline acceleration versus regulatory capital trap.
| Strategic Initiative | Industry Significance |
|---|---|
| Fixed-Dose Combination Development | Convergence of meglitinide and SGLT2 inhibitor mechanisms enables patent-protected positioning beyond generic competition. |
| Hospital System Partnership | Multi-year framework agreements with Rhine-Ruhr and Lombardy consortia lock in volume and freeze secondary suppliers. |
| CE Marking Pathway | Connected pen injector systems require MDR compliance to access German and Dutch digital therapeutics reimbursement categories. |
| Backward Integration | Captive repaglinide API production in India reduces exposure to shipping disruptions and customs delays on critical trade lanes. |
| Reimbursement Strategy | G-BA and AIFA negotiations favor molecules with broader prescriber familiarity, accelerating formulary inclusion timelines. |
Research Methodology
A standing panel of formulary directors, hospital procurement managers, regulatory affairs leads, and payer access specialists provided ongoing calibration across primary interview rounds. Secondary validation drew from EMA centralized marketing authorization procedures, EU Falsified Medicines Directive implementation reports, hospital pharmacy tender databases, and national health technology assessment filings in France, Germany, and Italy. Bottom-up prescription volume modeling and top-down pharmaceutical expenditure analysis were triangulated against statutory health insurance reimbursement data.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. The analytical framework modeled segmentation across product type, therapy area, end user setting, and distribution channel, with regional regulatory clusters as a cross-cutting dimension. CAGRs were derived from trend extrapolation of tender award volumes and reimbursement negotiation outcomes, incorporating SGLT2 inhibitor substitution rates and biosimilar insulin pricing pressure as demand-side modifiers.
Underlying assumptions cover EMA pharmacovigilance framework stability and REACH compliance cost trajectories, with deviation risk concentrated in API supplier export license disruptions and pediatric investigation plan requirement expansions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Autism Spectrum Disorder Therapeutics Market
Pharmaceuticals
Middle East and Africa Glucagon-Like Peptide-1 (GLP-1) Agonists Market
Pharmaceuticals
Asia-Pacific Fatty Bases for Suppositories Market
Pharmaceuticals
Global Bronchodilators Market
Pharmaceuticals
Global Diphtheria Vaccine Market
Pharmaceuticals
Global Bacterial Vaccines Market
Pharmaceuticals
Global Human Growth Hormone (HGH) Market
Pharmaceuticals
North America Dipeptide Peptidase 4 (Dpp-4) Inhibitors Market
Pharmaceuticals
Buprenorphine and Naloxone Market
Pharmaceuticals
Penicillin Market
Pharmaceuticals
Africa Generic Pharmaceutical Market
Pharmaceuticals
Global Eylea Market
Pharmaceuticals
Global Ceftiofur Market
Pharmaceuticals
Italy OTC Drugs Market
Pharmaceuticals
Betahistine Mesilate Market
Pharmaceuticals
Trulicity Market