
 Healthcare Personal Protection Equipment Market | 2026-2036
Healthcare Personal Protection Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Personal Protection Equipment Market Foresight
Nitrile is displacing natural latex across examination and surgical glove lines, a shift that is realigning raw-material sourcing and unit economics for manufacturers worldwide. 3M leverages its polymer science portfolio to secure captive nitrile supply chains across North American production hubs. Kimberly-Clark Corporation anchors hospital contracting relationships through bundled gown-glove-drape programs that lock in multi-year procurement cycles. DuPont de Nemours, Inc. differentiates via advanced nonwoven laminates that exceed ASTM F1670 blood-borne pathogen penetration standards.
Healthcare personal protection equipment encompasses garments, barriers, and respiratory devices engineered to block biological, chemical, and particulate hazards in clinical environments, typically constructed from spunbond-meltblown-spunbond polypropylene composites or nitrile-butadiene rubber with defined AQL defect thresholds and fluid-resistance ratings. Its primary purpose is to break transmission chains between healthcare workers, patients, and contaminated surfaces during invasive procedures, diagnostic testing, and routine bedside care. Gloves generate the largest revenue pool within product type segments due to per-procedure disposability and universal clinical application, while infection control leads application segments as hospitals implement zero-tolerance protocols for catheter-associated and surgical site infections. Material-grade nitrile commands expanding share as latex allergy prevalence and FDA powder-ban enforcement reshape formulary decisions.
FDA liquid-barrier classification rules, OSHA bloodborne pathogen standards, and CDC isolation precaution guidelines collectively mandate minimum performance benchmarks that determine market access for domestic suppliers and importers alike. The EU MDR and REACH chemical restrictions add compliance layers for European market entry, particularly for phthalate-plasticized PVC alternatives. Stakeholders must monitor evolving ASTM and ISO test-method harmonization, as divergent regional certification requirements threaten to fragment product platforms and inflate qualification costs for manufacturers serving multiple jurisdictions.
Market Dynamics
FDA enforcement of liquid-barrier performance standards is compressing material transition timelines, forcing manufacturers to abandon latex lines and retool nitrile-butadiene rubber capacity ahead of scheduled formulary reviews.
Growth Catalysts
- OSHA Bloodborne Pathogen Standard:Mandatory exposure control plans in US dental and surgical suites sustain per-procedure glove consumption rates that outpace population-adjusted healthcare growth.
- Tertiary Hospital Consolidation:Merged US health systems centralize procurement through multi-year bundled contracts, locking in volume commitments that stabilize manufacturer capacity planning.
- Nitrile-Butadiene Rubber:Synthetic polymer advances eliminate protein allergen risks while matching latex tactile sensitivity, enabling universal formulary adoption across pediatric and immunocompromised patient settings.
Market Restraints
- Acrylonitrile Price Volatility:Petrochemical feedstock fluctuations for nitrile monomer production compress gross margins during crude oil price spikes.
- Malaysian Rubber Concentration:Legacy natural latex processing infrastructure remains concentrated in Southeast Asian plantation economies, creating geographic supply vulnerability during monsoon disruptions.
- ASTM F1670 Certification Burden:Blood-borne pathogen penetration testing requirements add twelve-to-eighteen month qualification timelines for new laminate entrants.
Strategic Opportunities
- India PLI Scheme:Production-linked incentives for medical textiles attract greenfield nonwoven investments serving domestic hospital procurement and export markets.
- EU MDR Harmonization:Consolidated device regulations create pathway for single-certification access across twenty-seven member states, reducing duplicate testing costs.
- Telehealth-Home Care Convergence:Remote patient monitoring expansion generates demand for consumer-grade protective kits in home infusion and wound care settings.
Industry Challenges
- Polymer Science Talent Scarcity:Formulation chemists with nitrile compounding expertise command premium compensation, constraining R&D expansion at mid-tier manufacturers.
- Legacy ERP Integration:Batch record systems for FDA 21 CFR Part 11 compliance require costly middleware upgrades to interface with modern manufacturing execution platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Personal Protection Equipment Market |
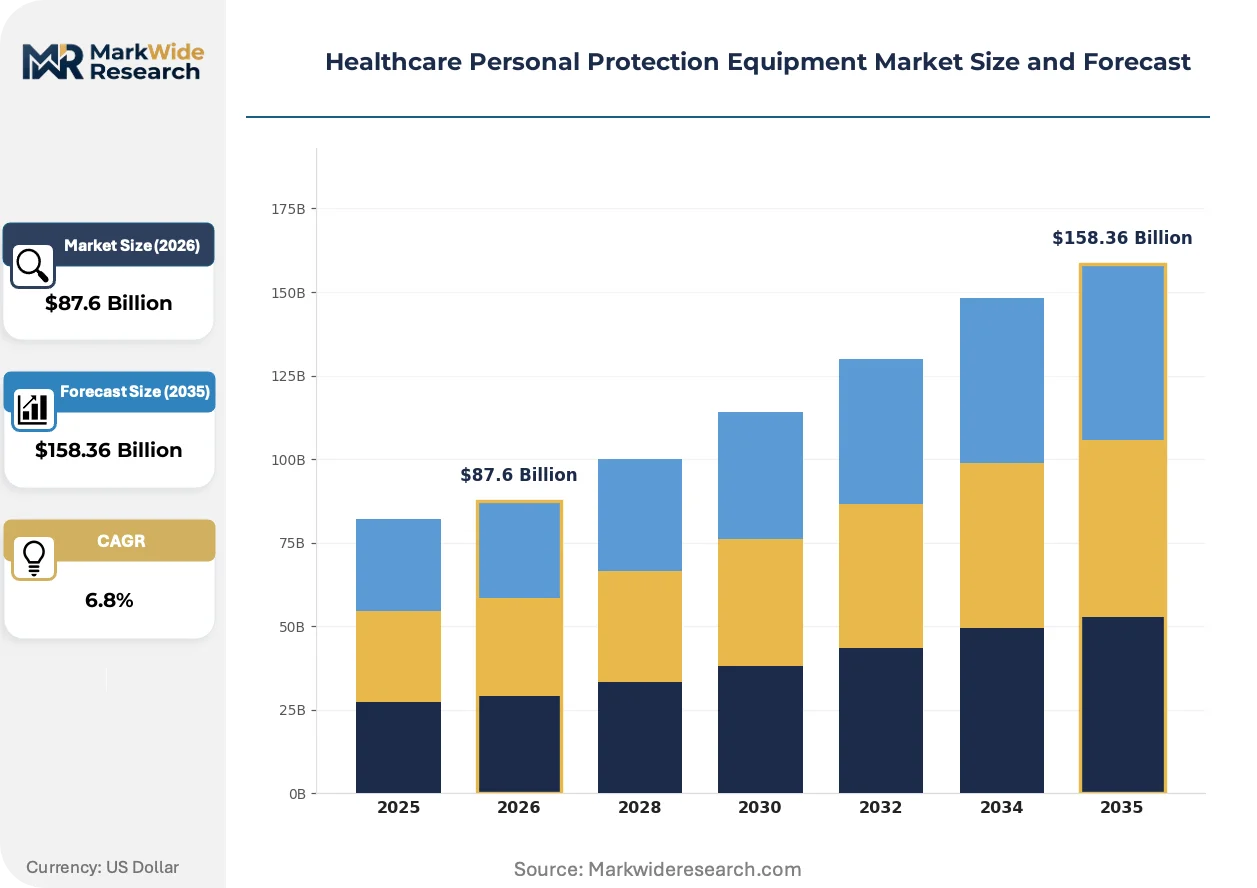
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $158.36 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gloves, Masks, Face Shields, Gowns End User: Hospitals, Clinics, Laboratories, Outpatient Facilities Application: Infection Control, Surgical Procedures, Laboratory Work, Patient Care Material: Latex, Nitrile, Polypropylene, PVC |
| Companies Covered | 3M, Honeywell International Inc., Ansell Ltd., DuPont de Nemours, Inc., Alpha Pro Tech, Ltd, Kimberly-Clark Corporation, Cardinal Health, Medline Industries, LP, Top Glove Corporation Bhd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Personal Protection Equipment Market Shifts & Advancements
Material science advances and procurement digitization are compressing product lifecycles while elevating performance thresholds for market access.
Smart polymer coatings with embedded color-change indicators are decentralizing contamination detection from centralized laboratory testing to point-of-use visual verification. US surgical suites adopt these materials at accelerated rates for orthopedic implant procedures. The technology is decentralizing quality assurance workflows and reducing reliance on post-procedure environmental monitoring.
REACH chemical restrictions on phthalate plasticizers in PVC alternatives are forcing compound reformulation across European supply chains. Industrial consequence includes accelerated migration to TPE and TPU elastomers for examination glove lines. German and French distributors now require full material disclosure documentation before contract renewal.
Hospital system e-procurement platforms are consolidating supplier rosters through reverse auction mechanisms that compress contract negotiation cycles. Group purchasing organizations displace direct manufacturer relationships for routine SKU replenishment. This pattern is most visible in United States consolidated delivery networks where annual vendor rationalization reviews eliminate non-strategic suppliers.
Healthcare Personal Protection Equipment Market Segmentation
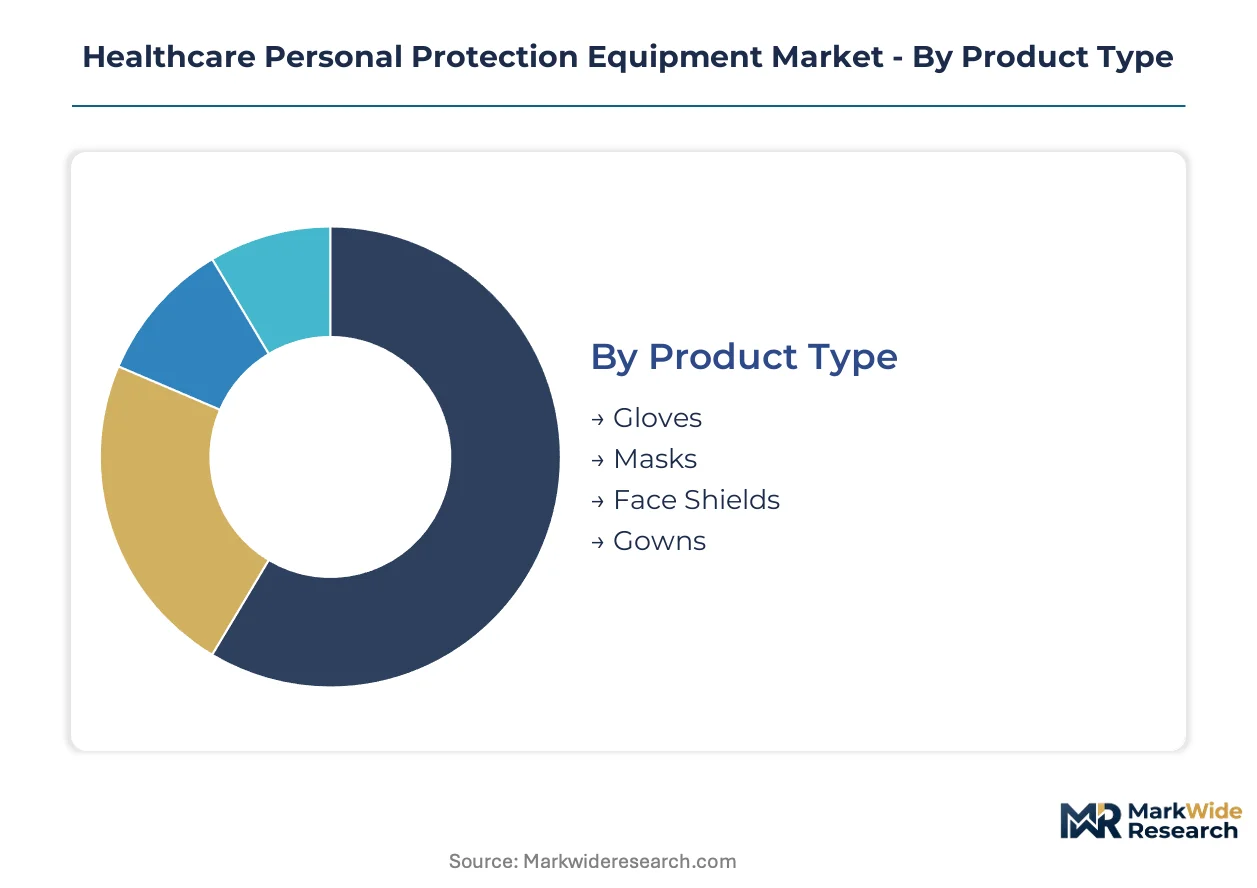
Healthcare personal protection equipment segments diverge sharply in certification intensity and procurement economics. FDA liquid-barrier classifications, ASTM penetration standards, and OSHA exposure limits create tiered compliance burdens that reshape manufacturer portfolios and hospital formulary decisions.
Product Type:
FDA 510(k) clearance requirements vary substantially across this category, with surgical gowns facing ASTM F1670 blood-borne pathogen testing and gloves requiring biocompatibility ISO 10993 evaluation.
- Gloves:Nitrile-butadiene rubber formulations dominate hospital procurement, replacing natural latex in tertiary surgical suites due to FDA powder-ban enforcement and protein allergen elimination. United States hospital systems now specify nitrile for 90% of examination and surgical applications, locking in multi-year supply contracts with domestic compounders.
- Gowns:Spunbond-meltblown-spunbond polypropylene laminates with taped seams command premium positioning in orthopedic and cardiovascular operating rooms. ASTM F1671 viral penetration testing adds twelve-month qualification timelines that filter out mid-tier Asian suppliers from US group purchasing organization rosters.
- Masks:N95 respirators and surgical masks require NIOSH certification or FDA 510(k) clearance respectively, with fluid resistance ratings determining ICU versus general ward deployment.
- Face Shields:PET or polycarbonate barriers with anti-fog coatings serve splash protection protocols in dental and emergency department settings, typically procured as disposable units.
Gloves sit at the top of the volume ranking, with gowns climbing the fastest as zero-tolerance surgical site infection protocols expand procedure-specific barrier requirements.
End User:
Procurement scale and specification complexity separate institutional buyers, with consolidated health systems leveraging volume concentration for price-tier advantages.
- Hospitals:Tertiary medical centers in the United States centralize purchasing through integrated delivery networks, bundling glove-gown-drape contracts across 200-plus bed facilities. Federal stockpiling programs for national strategic reserves add non-cyclical demand spikes that strain nitrile supply chains.
- Clinics:Federally qualified health centers and ambulatory surgery centers operate on tighter inventory cycles, favoring just-in-time distributor relationships over direct manufacturer contracts.
- Laboratories:CLIA-certified diagnostic facilities require chemical resistance specifications for chemotherapy drug handling, driving demand for thick-gauge nitrile and double-gloving protocols.
- Outpatient Facilities:Endoscopy centers and dialysis clinics prioritize cost-efficient standard-grade PPE with shorter shelf-life requirements.
Hospitals anchor procurement volume, while laboratories are gaining share fastest as molecular diagnostics and biopharma testing expand headcount.
Application:
Risk stratification determines barrier performance tiers, with sterile surgical applications demanding the most rigorous material validation.
- Infection Control:Isolation precautions for multidrug-resistant organisms require contact-droplet-airborne PPE combinations, with CDC guideline updates triggering immediate formulary revisions across US acute care networks.
- Surgical Procedures:Sterile field maintenance mandates AQL 1.5 defect thresholds for gloves and sealed-seam gowns, with orthopedic implant protocols specifying synthetic polymer alternatives to minimize particulate shedding.
- Laboratory Work:BSL-2 and BSL-3 containment protocols drive demand for puncture-resistant materials and integrated face protection systems.
- Patient Care:Routine bedside nursing consumes standard examination gloves and isolation gowns at per-shift replacement rates.
Infection control holds the volume lead, with surgical procedures expanding most quickly as robotic and minimally invasive techniques multiply instrument changeover cycles.
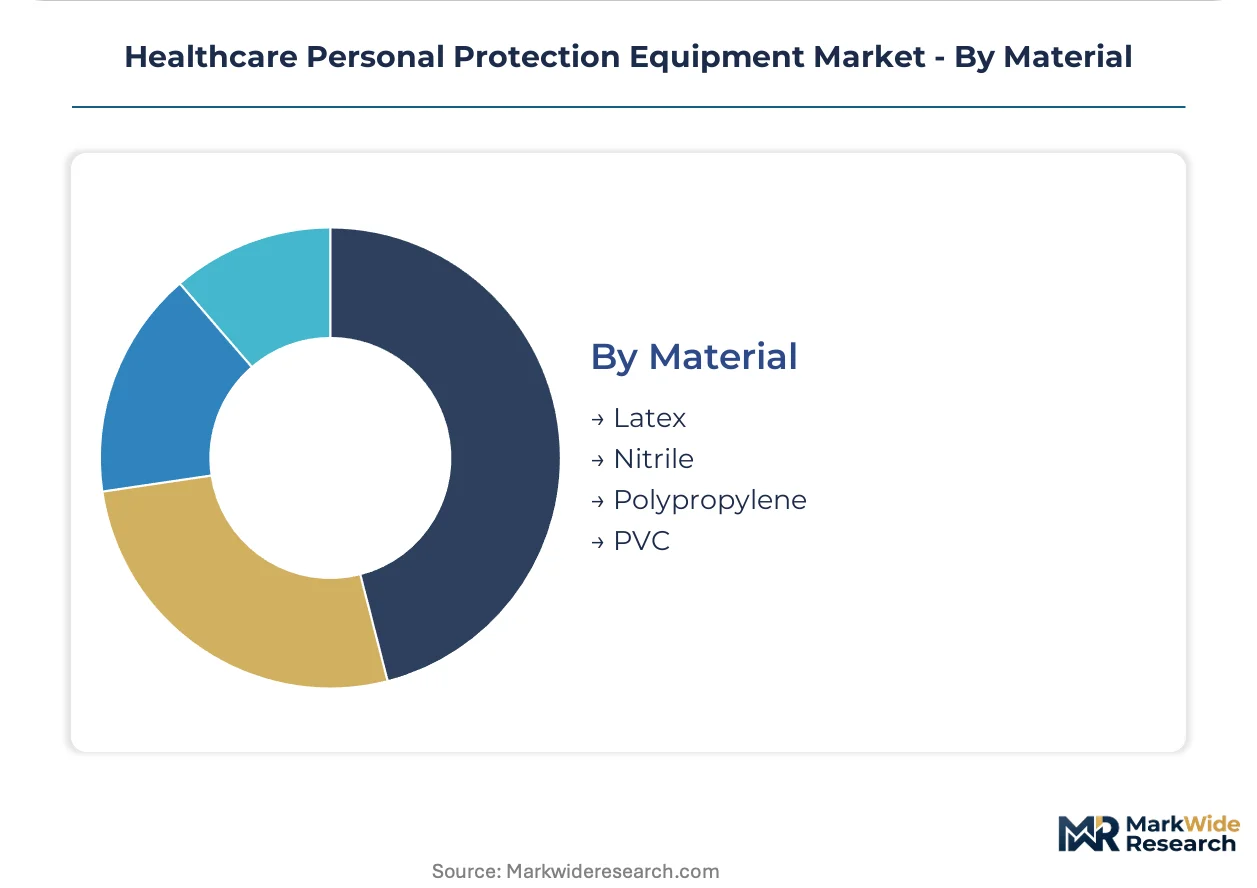
Material:
Regulatory chemistry restrictions and allergen profiles are reconstituting raw-material sourcing strategies across manufacturing footprints.
- Nitrile:Acrylonitrile-butadiene copolymers deliver latex-equivalent tactile sensitivity without Type I hypersensitivity risks, capturing universal formulary status in US pediatric and oncology units. 3M and domestic compounders have secured captive butadiene supply through Gulf Coast petrochemical partnerships.
- Latex:Hevea brasiliensis-derived natural rubber maintains niche positioning in microsurgical applications requiring maximum tactile precision, though FDA powder prohibitions have collapsed hospital demand.
- Polypropylene:Spunbond and meltblown nonwovens form the substrate for surgical gowns and drapes, with basis weight and hydrostatic head measurements determining AAMI Level 1-4 barrier classifications.
- PVC:Plasticized polyvinyl chloride alternatives face REACH chemical restrictions in European markets, forcing compound reformulation or abandonment.
Nitrile dominates volume rankings, with polypropylene gaining share fastest as advanced laminate structures penetrate higher-acuity surgical segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gulf Coast petrochemical corridors anchor nitrile-butadiene rubber production for healthcare glove manufacturing. Hospital consolidation and federal stockpiling programs concentrate procurement power in select markets. Regulatory divergence across FDA, ECHA, and national health agencies fragments certification pathways.
United States
Tertiary hospital networks in Texas and Ohio centralize billion-dollar procurement contracts through integrated delivery networks. OSHA bloodborne pathogen standards mandate exposure control plans that sustain per-procedure glove consumption above population-adjusted healthcare growth. Federal stockpiling programs for national strategic reserves generate non-cyclical demand spikes that strain domestic nitrile supply chains.
Germany
REACH chemical restrictions on phthalate plasticizers force compound reformulation across examination glove lines serving Bavarian and North Rhine-Westphalian hospital systems. ECHA enforcement of substance restrictions accelerates migration to TPE and TPU elastomers. Frankfurt and Düsseldorf-based distributors now require full material disclosure documentation before contract renewal.
China
Yangtze River Delta manufacturing clusters produce spunbond-meltblown-spunbond polypropylene laminates for surgical gown export markets. NMPA device registration requirements and GB standards compliance create dual-track qualification burdens for domestic and international product lines. Zhejiang and Jiangsu province facilities face MEE environmental inspections that tighten emissions controls on nonwoven production.
India
PLI scheme production-linked incentives attract greenfield medical textile investments in Gujarat and Tamil Nadu serving domestic hospital procurement. CDSCO medical device rules harmonize with EU MDR frameworks to streamline export certification. Coimbatore and Ahmedabad industrial corridors expand nonwoven capacity for regional supply chain independence.
Malaysia
Legacy natural latex processing infrastructure remains concentrated in plantation economies vulnerable to monsoon disruptions. Top Glove Corporation Bhd and regional producers face FDA import alerts that reshape export volumes to US markets. Selangor and Perak processing hubs confront labor compliance audits that elevate production costs.
Healthcare Personal Protection Equipment Market Competitive Landscape
Global majors compete with regional champions across material science capabilities and hospital contracting relationships. The vendor base stratifies into three tiers: diversified conglomerates with captive polymer supply, specialized medical textile pure-plays, and regional distributors with local regulatory expertise. Dominant competitive moves include backward integration into nitrile compounding capacity and multi-year bundled contract negotiations with consolidated health systems.
Within the diversified conglomerate tier, 3M and DuPont de Nemours, Inc. occupy positions anchored by polymer science portfolios and advanced nonwoven laminate capabilities. Kimberly-Clark Corporation represents the hospital-contracting archetype through bundled gown-glove-drape programs. Ansell Ltd. exemplifies the specialized medical protection pure-play model with concentrated expertise in hand protection formulations.
| Leading Market Players |
|---|
| 3M |
| Honeywell International Inc. |
| Ansell Ltd. |
| DuPont de Nemours, Inc. |
| Alpha Pro Tech, Ltd |
| Kimberly-Clark Corporation |
| Cardinal Health |
| Medline Industries, LP |
| Top Glove Corporation Bhd |
| Others |
Supply & Pricing Matrix
EU REACH chemical restrictions on phthalate plasticizers gate qualified supply for European hospital procurement, filtering out non-compliant compounders and enabling premium-tier pricing for full-disclosure manufacturers serving German and French distributor networks.
Pricing Analysis
Acrylonitrile feedstock volatility passes through directly to nitrile glove unit economics, compressing margins for non-integrated manufacturers during crude oil price spikes. Pricing stratifies across AAMI Level 4 surgical laminates, Level 2-3 isolation barriers, and standard examination-grade disposables, with FDA 510(k) certification tier commanding substantial premiums. Cost compression in standard-grade nitrile examination lines is intensifying because Malaysian legacy latex producers are retooling capacity to capture formulary share. Federally qualified health centers and ambulatory surgery centers exhibit highest price sensitivity, while tertiary hospital systems lock in multi-year contracts that trade volume commitment for price stability.
Supply Chain Analysis
Dual-sourcing requirements from US group purchasing organizations mandate multi-supplier qualification for critical glove and gown lines, preventing single-source dependency in national strategic reserve stockpiling programs. Manufacturing concentrates in Malaysia for natural latex processing, China for spunbond-meltblown-spunbond polypropylene laminates, and the United States Gulf Coast for nitrile-butadiene rubber compounding. Raw material flows draw from acrylonitrile monomer production, butadiene petrochemical feedstocks, and polypropylene resin pellets. Single-source vulnerability persists in specialty laminate films requiring ASTM F1671 viral penetration certification. Distribution runs through integrated delivery networks and group purchasing organizations that consolidate hospital system procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in healthcare personal protection equipment rests on nitrile formulation expertise and captive petrochemical supply, with premium-tier shift toward synthetic polymer alternatives outpacing commodity latex replacement economics.
For Market Incumbents: Acquire nitrile compounding facilities and captive butadiene supply agreements to secure input cost control against acrylonitrile volatility. Expand AAMI Level 4 laminate capacity in US Gulf Coast corridors to capture orthopedic and cardiovascular surgical suite upgrades. Threat from REACH-compliant TPE and TPU elastomer substitutes in European markets demands accelerated R&D in phthalate-free plasticizer chemistry. For New Entrants and Emerging Players: EU MDR harmonization opens a window for single-certification access across twenty-seven member states, reducing duplicate testing costs for mid-tier manufacturers. Target Indian PLI scheme incentives for greenfield medical textile investments serving domestic hospital procurement and export markets. White space exists in telehealth-home care convergence for consumer-grade protective kits in home infusion settings. Go-to-market angle: direct e-commerce partnerships with remote patient monitoring platform providers. For Investors and Strategic Acquirers: Roll-up economics work for specialized medical textile pure-plays because hospital system consolidation is compressing supplier rosters and elevating scale requirements for group purchasing organization eligibility. Long-term viability centers on backward integration into polymer science capabilities and multi-year bundled contract relationships with integrated delivery networks. Watch for FDA import alert escalations against Southeast Asian producers as inflection indicator for domestic manufacturer volume capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nitrile Compounding | Captive butadiene supply from Gulf Coast petrochemical partnerships insulates margins from acrylonitrile volatility. |
| AAMI Level 4 Laminate Capacity Expansion | Taped-seam gowns for orthopedic implant protocols command premium positioning above standard isolation barriers. |
| EU MDR Single-Certification Pathway | Consolidated device regulations streamline market access across German, French, and Italian hospital networks. |
| Hospital System Bundled Contract Negotiation | Multi-year glove-gown-drape commitments with integrated delivery networks stabilize capacity planning visibility. |
| Smart Polymer Coating Development | Embedded color-change contamination indicators decentralize quality assurance to point-of-use visual verification. |
Research Methodology
Coverage spans the United States, Germany, China, India, and Malaysia, with primary inputs from each region validating supply chain and procurement dynamics. The approach combines structured interviews with hospital procurement managers, group purchasing organization contract specialists, biomedical engineers, nitrile compounding plant managers, and regulatory affairs leads with secondary validation from FDA 510(k) filings, ECHA substance restriction databases, CDSCO medical device registrations, and NMPA compliance disclosures. Bottom-up facility capacity assessments and top-down hospital expenditure triangulation anchor volume and value estimates.
Granularity-level modeling distinguishes nitrile, latex, polypropylene, and PVC material tiers; gloves, gowns, masks, and face shields product categories; and hospital, clinic, laboratory, and outpatient facility end-user segments across the projection horizon. CAGRs derive from procedure volume growth adjusted for per-procedure PPE consumption intensity, with infection control protocol expansion and surgical site infection prevention mandates as key healthcare-specific inputs. Regional regulatory cluster modeling captures FDA, ECHA, and CDSCO compliance pathway divergence.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden OSHA guideline revisions, monsoon disruptions to Malaysian latex processing, or geopolitical trade restrictions on acrylonitrile feedstock flows. Forecasts reflect documented assumptions regarding hospital consolidation velocity and federal stockpiling program scale. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Equipment
Medical Chairs Market
Healthcare Equipment
Global Hospital Asset Management Market
Healthcare Equipment
Patient Recliner Market
Healthcare Equipment
North America Nurse Call Systems Market
Healthcare Equipment
Emergency Hospital Beds Market
Healthcare Equipment
Patient Infotainment Terminals Market
Healthcare Equipment
Patient Recliner Chair Market
Healthcare Equipment
Medical Cold Storage Market
Healthcare Equipment
Healthcare Cold Chain Monitoring Market
Healthcare Equipment
India Healthcare Machine Vision System Market
Healthcare Equipment
Physiotherapy Equipment Market
Healthcare Equipment
North America Healthcare Machine Vision System Market
Healthcare Equipment
Veterinary Furniture Market
Healthcare Equipment
Specialty Medical Chairs Market
Healthcare Equipment
Microbiological Safety Cabinets Market
Healthcare Equipment
Middle East and Africa Hospital Furniture Market