
 Middle East and Africa Obsessive-Compulsive Disorder (OCD) Drugs Market | 2026-2036
Middle East and Africa Obsessive-Compulsive Disorder (OCD) Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Obsessive-Compulsive Disorder (OCD) Drugs Market Foresight
Outpatient clinics is decoupling from hospital-centric prescribing patterns as telepsychiatry platforms expand across the Gulf Cooperation Council states. Novartis leverages its established neuroscience portfolio to sustain formulary access in Egyptian and South African public health systems. Pfizer competes through primary care detailing networks that anchor SSRI volume in Nigerian and Kenyan urban markets.
Middle East and Africa Obsessive-Compulsive Disorder (OCD) Drugs comprise psychopharmaceutical formulations—primarily selective serotonin reuptake inhibitors, serotonin-norepinephrine reuptake inhibitors, and adjunctive antipsychotics—manufactured through active pharmaceutical ingredient synthesis, tablet compression, and enteric coating processes designed to modulate serotonergic neurotransmission in cortico-striato-thalamo-cortical circuits. These agents serve the primary commercial purpose of reducing obsessional ideation and compulsive ritual frequency in diagnosed patient populations. The SSRI category dominates current value flows due to established efficacy profiles and favorable tolerability versus tricyclic alternatives, while the intravenous administration route represents a faster-growing structural pocket as hospital-based acute OCD protocols gain adoption in South Africa and the UAE. Long-term treatment duration segments concentrate margin pools because chronic maintenance prescribing generates recurring reimbursement cycles under Saudi Arabia's Council of Health Insurance mandates.
South Africa's Medicines Control Council, Saudi Arabia's Food and Drug Authority, and the UAE's Ministry of Health and Prevention collectively shape market access through bioequivalence requirements, import licensing, and national formulary inclusion criteria that determine which manufacturers can supply reimbursed channels. The EU's F-Gas Regulation indirectly influences regional supply security by constraining propellant availability for certain inhalation-delivery development programs. Stakeholders must monitor how Gulf state mental health insurance parity legislation alters patient co-payment structures and generic substitution incentives.
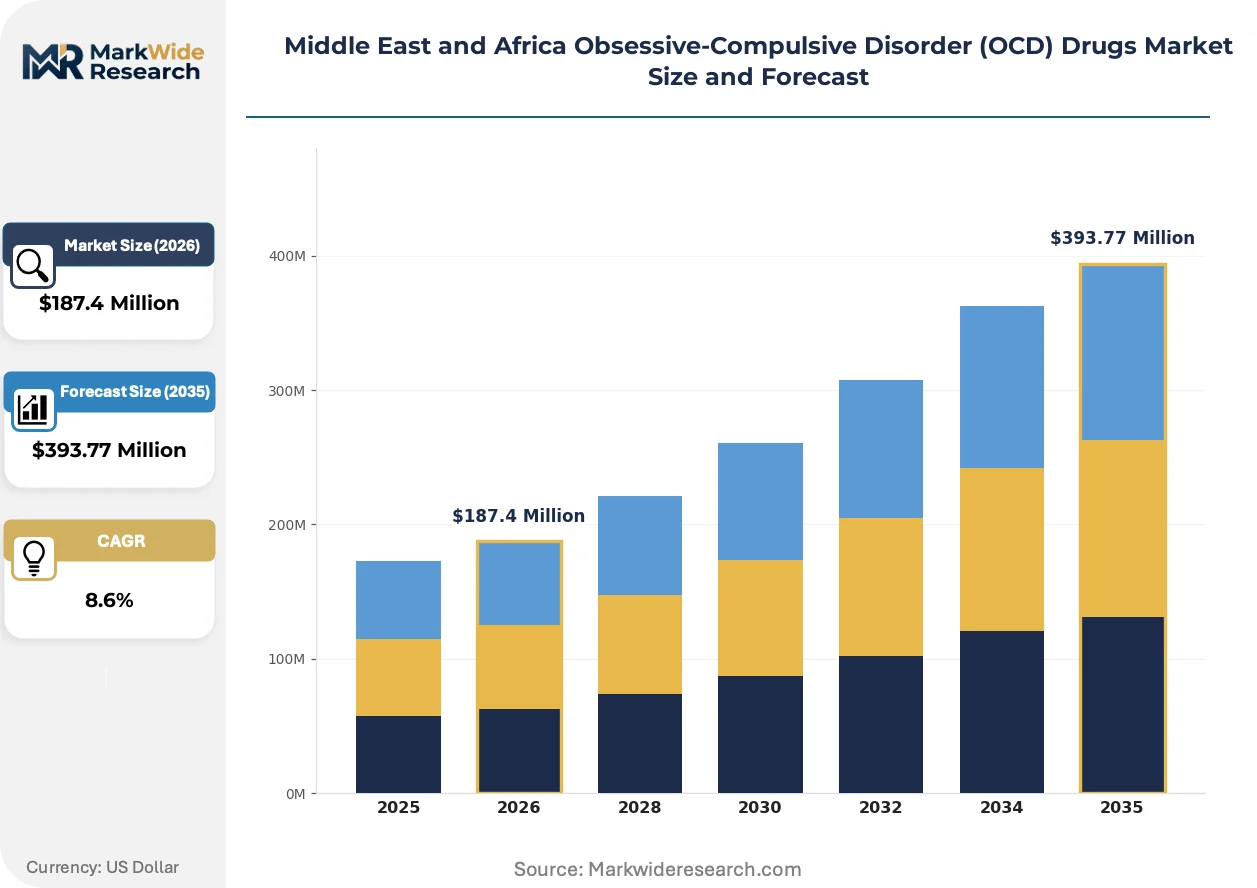
Market Dynamics
Telepsychiatry platform deployment across Gulf Cooperation Council states is decoupling OCD treatment from hospital-centric infrastructure, redistributing prescribing authority toward outpatient networks and primary care physicians.
Growth Catalysts
- Saudi Arabia's Council of Health Insurance mandates:Mental health pharmacotherapy inclusion in government insurance schemes eliminates patient co-payment barriers for SSRI maintenance therapy.
- SSRI tolerability profiles:Favorable side-effect matrices versus tricyclic antidepressants accelerate primary care physician confidence in first-line prescribing across Egyptian and Nigerian urban markets.
- South African hospital networks:Acute OCD protocol adoption in Johannesburg and Cape Town tertiary centers drives intravenous administration route demand.
Market Restraints
- API import dependency:Active pharmaceutical ingredient supply concentrates on Indian and Chinese manufacturers, exposing formulation plants in the UAE and Saudi Arabia to shipping disruption and currency fluctuation.
- Bioequivalence study costs:South Africa's Medicines Control Council requirements for generic registration impose capital barriers on regional manufacturers lacking dedicated clinical trial infrastructure.
- Psychiatrist workforce scarcity:Sub-Saharan African markets face diagnostic bottleneck as OCD recognition requires specialist assessment unavailable outside Lagos, Nairobi, and Johannesburg metropolitan clusters.
Strategic Opportunities
- Kenyan primary care networks:Underpenetrated upcountry regions present volume expansion potential for SSRI detailing programs targeting general practitioner education.
- Telepsychiatry-SSRI integration:Remote diagnostic platforms combined with e-prescription systems enable asynchronous care models reducing specialist appointment backlogs in the UAE.
- Egyptian public health formulary expansion:Ministry of Health and Population initiatives to decentralize mental health services create procurement openings for established neuropsychiatric portfolios.
Industry Challenges
- Specialist psychiatric nursing shortage:Hospital-based acute OCD protocols in South Africa and the UAE require trained infusion staff currently concentrated in tertiary academic centers.
- Multinational licensing complexity:Product registration harmonization gaps between Saudi Arabia's Food and Drug Authority and the UAE's Ministry of Health and Prevention force duplicate dossier submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Obsessive-Compulsive Disorder (OCD) Drugs Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $393.77 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Type: SSRIs, SNRIs, Tricyclic Antidepressants, Antipsychotics Administration Route: Oral, Intravenous, Transdermal, Inhalation End User: Hospitals, Outpatient Clinics, Homecare, Rehabilitation Centers Treatment Duration: Short-term, Long-term, Maintenance Therapy, Acute Treatment |
| Companies Covered | Novartis, AstraZeneca, Pfizer, Hikma Pharmaceuticals, Merck & Co., GlaxoSmithKline, Sanofi, Eva Pharma, H. Lundbeck, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Obsessive-Compulsive Disorder (OCD) Drugs Market Shifts & Advancements
Digital therapeutic platforms and pharmacogenomic testing are converging to personalize SSRI selection, shifting prescribing decisions from empirical trial toward biomarker-informed protocols.
Pharmacogenomic screening for CYP2D6 and CYP2C19 polymorphisms is modularizing SSRI prescribing workflows in South African private hospital chains. Psychiatrists at Netcare and Life Healthcare facilities increasingly order pre-treatment metabolic panels to predict fluoxetine and sertraline clearance rates. This capability compresses the therapeutic adjustment window and reduces adverse event discontinuation.
Saudi Arabia's Food and Drug Authority implemented expedited review pathways for mental health products in 2023, compressing registration timelines for novel formulations. Multinational suppliers now prioritize Riyadh and Jeddah for first-launch sequencing within the Middle East region. Generic substitution guidelines accompanying these reforms are reshaping procurement negotiations with the Ministry of Health.
Patient advocacy networks in the UAE and Qatar are demanding direct-to-consumer pharmacy channels for maintenance SSRI refills, bypassing psychiatrist revisit requirements for stable chronic cases. Community pharmacy chains in Dubai and Abu Dhabi are piloting subscription delivery models with remote prescriber oversight. This behavioral shift concentrates volume in retail channels previously excluded from psychiatric medication distribution.
Middle East and Africa Obsessive-Compulsive Disorder (OCD) Drugs Market Segmentation
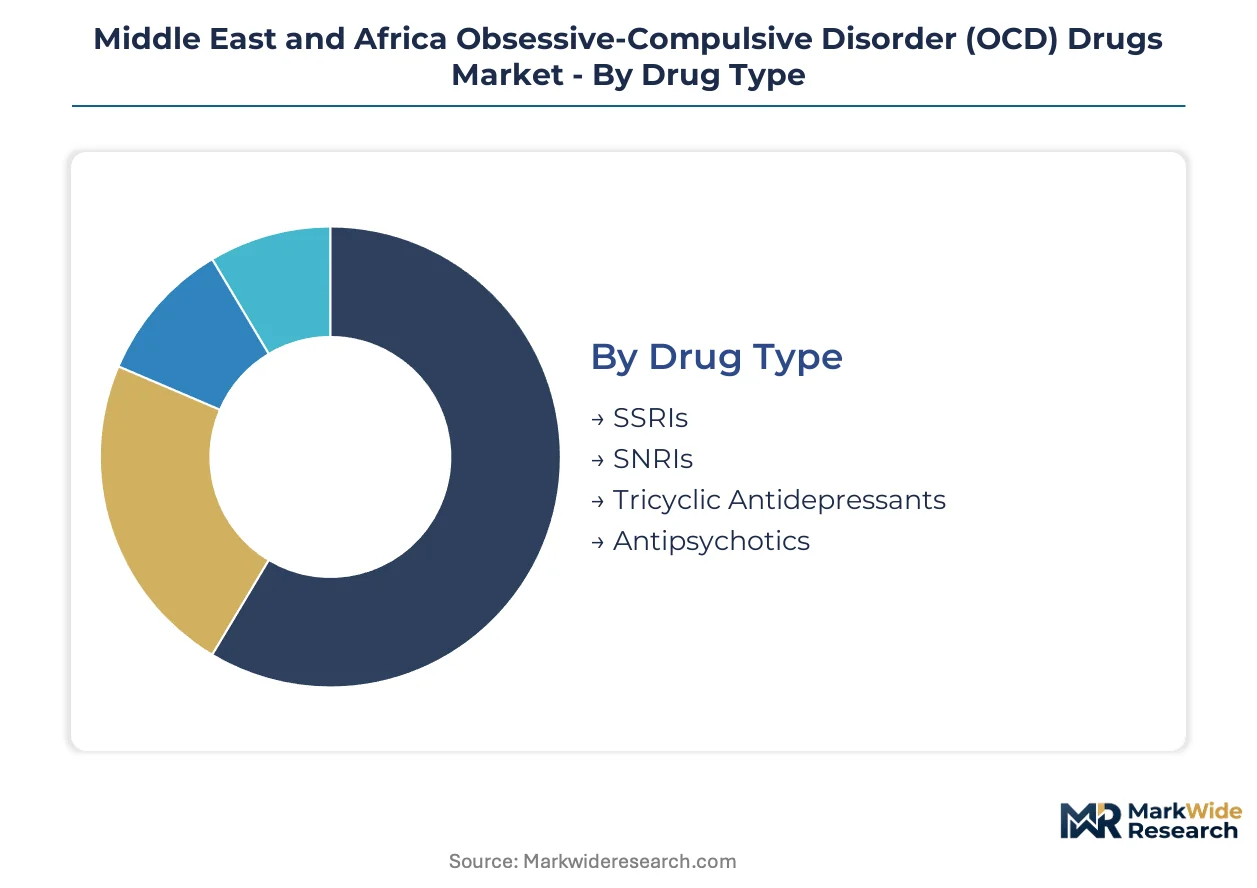
Segmentation in the Middle East and Africa OCD drugs market reveals how prescribing authority, reimbursement structures, and patient acuity intersect to determine commercial access. Manufacturers must align formulation development with the specific requirements of hospital protocols, outpatient networks, and emerging homecare channels across Gulf and sub-Saharan markets.
Drug Type:
Standardization dominates at the API level, yet finished dose differentiation creates tiered positioning across public and private reimbursement channels.
- SSRIs:Fluoxetine, sertraline, and escitalopram formulations constitute the clinical and commercial backbone, with established efficacy in cortico-striato-thalamo-cortical circuit modulation. Saudi Arabia's Council of Health Insurance mandates now cover SSRI maintenance therapy, eliminating prior co-payment barriers that constrained adherence in Riyadh and Jeddah metropolitan clusters.
- SNRIs:Venlafaxine and duloxetine serve treatment-resistant populations and comorbid anxiety presentations, commanding premium positioning in South African private hospital chains. Netcare and Life Healthcare facilities in Johannesburg increasingly prescribe SNRIs as second-line options where SSRI monotherapy fails, though public sector formulary inclusion remains limited.
- Tricyclic Antidepressants:Clomipramine retains niche utilization for severe, refractory OCD cases in Egyptian tertiary centers despite tolerability limitations.
- Antipsychotics:Aripiprazole and risperidone function as adjunctive augmentation agents in acute protocols at Cape Town academic hospitals.
Leading the category by volume: SSRIs. Growing fastest: SNRIs.
Administration Route:
Route selection tracks infrastructure availability, with oral dominance giving way to acute-care alternatives where specialist nursing capacity permits.
- Oral:Tablet and capsule formulations anchor maintenance prescribing across outpatient networks, with enteric-coated variants reducing gastrointestinal discontinuation. Primary care physicians in Lagos and Nairobi urban clusters increasingly initiate oral SSRI therapy as telepsychiatry platforms extend diagnostic reach beyond specialist centers.
- Intravenous:Hospital-based acute OCD protocols in Johannesburg and Cape Town tertiary centers drive demand for parenteral formulations, requiring trained infusion staff concentrated in academic medical centers. The UAE's Ministry of Health and Prevention has approved expedited licensing for intravenous psychotropic imports to address this emerging channel.
- Transdermal:Patch delivery systems remain investigational in the region, with limited commercial availability through South African private pharmacy chains.
- Inhalation:Development programs face supply constraints from EU F-Gas Regulation propellant restrictions, delaying regional launch timelines for aerosolized delivery concepts.
Oral administration captures the largest patient volume. Intravenous delivery is climbing the fastest as acute protocols expand.
End User:
Patient acuity and reimbursement eligibility determine channel selection, with government insurance reforms redistributing volume toward outpatient settings.
- Hospitals:Tertiary academic centers in Johannesburg, Cape Town, and Riyadh manage severe, treatment-resistant cases requiring multimodal intervention and inpatient stabilization.
- Outpatient Clinics:Telepsychiatry platform deployment across Gulf Cooperation Council states is decoupling prescribing from hospital infrastructure, redistributing SSRI initiation authority to primary care networks in Dubai and Abu Dhabi.
- Homecare:Stable maintenance patients in Saudi Arabia and the UAE are accessing remote prescriber oversight with pharmacy subscription delivery, bypassing traditional revisit requirements.
- Rehabilitation Centers:Integrated mental health facilities in Kenya and Nigeria combine pharmacotherapy with behavioral intervention for complex presentations.
Outpatient clinics now lead hospital channels by prescription volume. Homecare is gaining share fastest through subscription models.
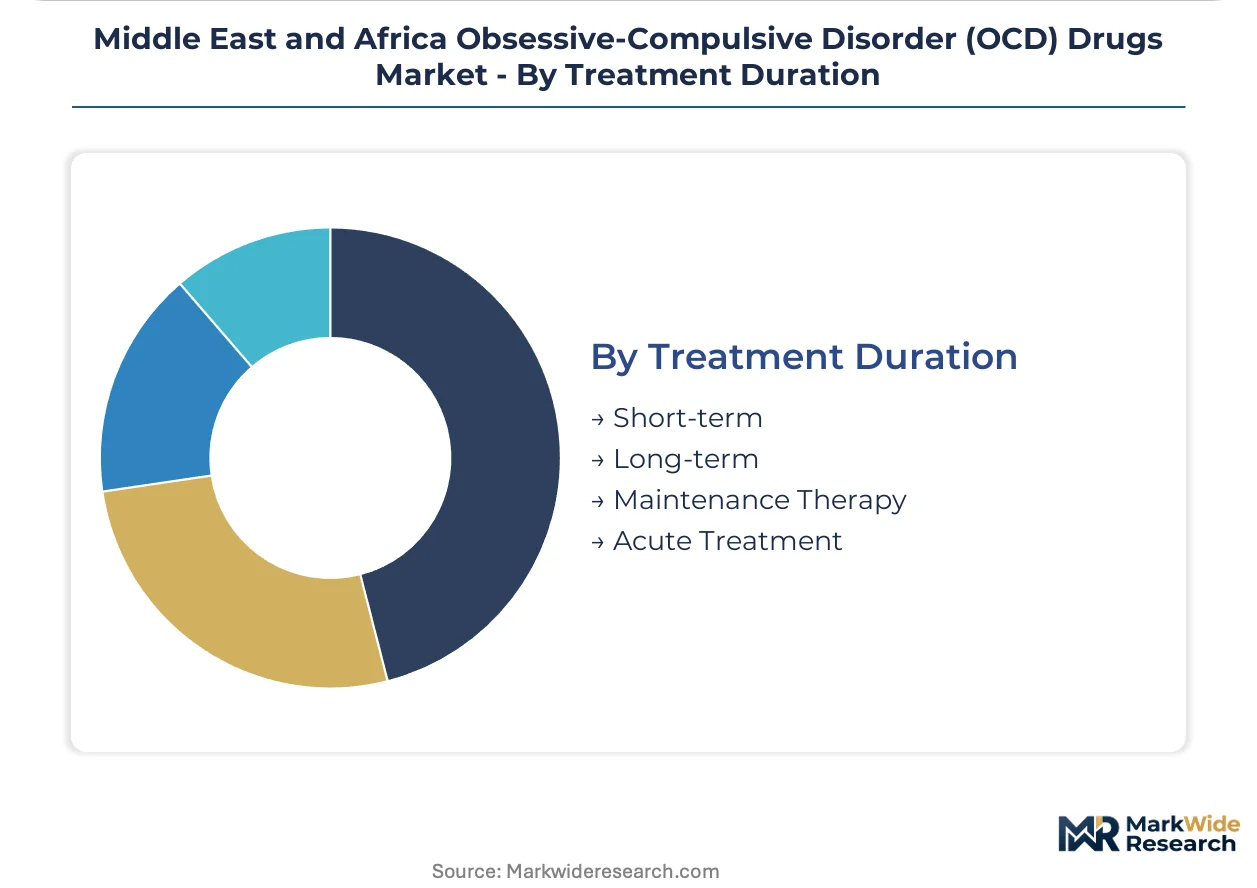
Treatment Duration:
Duration segmentation aligns with chronic disease management economics, where recurring reimbursement cycles concentrate manufacturer margin pools.
- Short-term:Acute crisis intervention spans 8-12 weeks in Johannesburg and Cape Town emergency psychiatric services, typically bridging to maintenance protocols.
- Long-term:Extended pharmacotherapy beyond 12 months generates recurring revenue under Saudi Arabia's Council of Health Insurance mandates, with automatic refill authorization for stable patients.
- Maintenance Therapy:Chronic prescribing dominates commercial value, with Egyptian Ministry of Health and Population initiatives expanding decentralized mental health service procurement.
- Acute Treatment:Hospital-based protocols for severe exacerbations require intravenous augmentation and intensive nursing oversight in South African tertiary networks.
Maintenance therapy leads by value contribution. Acute treatment is expanding most quickly through protocol adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Formulation capacity concentrates in the UAE and Saudi Arabia while patient demand spreads across Gulf and sub-Saharan markets. Egyptian and South African manufacturers import active pharmaceutical ingredients from Indian and Chinese suppliers, creating supply chain exposure. Telepsychiatry platforms now redistribute prescribing authority toward outpatient networks in metropolitan clusters.
Saudi Arabia
Riyadh and Jeddah metropolitan clusters drive SSRI maintenance therapy volume under Council of Health Insurance mandates. The country's Food and Drug Authority implemented expedited review pathways for mental health products in 2023, compressing registration timelines. Eastern Province hospital networks are adopting acute OCD protocols requiring intravenous augmentation.
United Arab Emirates
Dubai and Abu Dhabi outpatient clinics now exceed hospital channels by prescription volume through telepsychiatry platform deployment. The Ministry of Health and Prevention approved expedited licensing for intravenous psychotropic imports to address emerging acute-care demand. Community pharmacy chains in these emirates pilot subscription delivery models with remote prescriber oversight.
South Africa
Johannesburg and Cape Town tertiary centers anchor intravenous administration route adoption for hospital-based acute OCD protocols. The Medicines Control Council harmonization with ICH guidelines streamlines product registration for multinational suppliers. Netcare and Life Healthcare private hospital chains increasingly prescribe SNRIs as second-line options.
Egypt
Cairo metropolitan cluster concentrates diagnostic capacity and specialist psychiatric assessment for severe refractory cases. The Ministry of Health and Population initiatives to decentralize mental health services create procurement openings for neuropsychiatric portfolios. Egyptian tertiary centers retain niche clomipramine utilization despite tolerability limitations versus SSRI alternatives.
Middle East and Africa Obsessive-Compulsive Disorder (OCD) Drugs Market Competitive Landscape
Top-tier vendors anchor formulary access in government insurance channels, while regional manufacturers compete on generic substitution and import licensing agility. The market structures around three strategic archetypes: multinational neuroscience portfolios, regional generic specialists, and hospital-network captive suppliers. Competitive moves concentrate on regulatory dossier harmonization across Gulf Cooperation Council jurisdictions and telepsychiatry platform partnerships for e-prescription integration.
Among multinational neuroscience portfolios, Novartis and Pfizer occupy positions exemplifying divergent channel strategies. Novartis leverages established portfolio relationships to sustain formulary access in Egyptian and South African public health systems. Pfizer competes through primary care detailing networks that anchor SSRI volume in Nigerian and Kenyan urban markets. Hikma Pharmaceuticals represents the regional generic specialist archetype, navigating bioequivalence requirements and import licensing frameworks.
| Leading Market Players |
|---|
| Novartis |
| AstraZeneca |
| Pfizer |
| Hikma Pharmaceuticals |
| Merck & Co. |
| GlaxoSmithKline |
| Sanofi |
| Eva Pharma |
| H. Lundbeck |
| Others |
Supply & Pricing Matrix
Government insurance procurement pools in Saudi Arabia and the UAE anchor volume-based contract pricing for SSRI maintenance therapy, concentrating purchasing power among formulary gatekeepers and compressing margins for non-preferred suppliers.
Pricing Analysis
Cost-down pressure on generic SSRI suppliers accelerates because Saudi Arabia's Council of Health Insurance mandates have expanded covered patient pools while tightening reimbursement ceilings. Pricing stratifies across premium branded, standard authorized generic, and economy unbranded tiers, with differentiation driven by bioequivalence certification tier and Ministry of Health formulary inclusion status. Egyptian and Nigerian urban markets exhibit highest price sensitivity among primary care physicians initiating first-line therapy, whereas South African private hospital chains retain tolerance for premium SNRI positioning.
Supply Chain Analysis
Direct-to-hospital channels handle acute intravenous psychotropic demand in Johannesburg and Cape Town tertiary centers, while retail pharmacy networks distribute oral maintenance formulations across Gulf Cooperation Council states. Active pharmaceutical ingredient supply draws from Indian and Chinese manufacturers, with formulation finishing concentrated in the UAE and Saudi Arabia. Sertraline base, fluoxetine hydrochloride, and escitalopram oxalate constitute critical input dependencies. Single-source vulnerability in API supply exposes regional plants to shipping disruption and currency fluctuation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
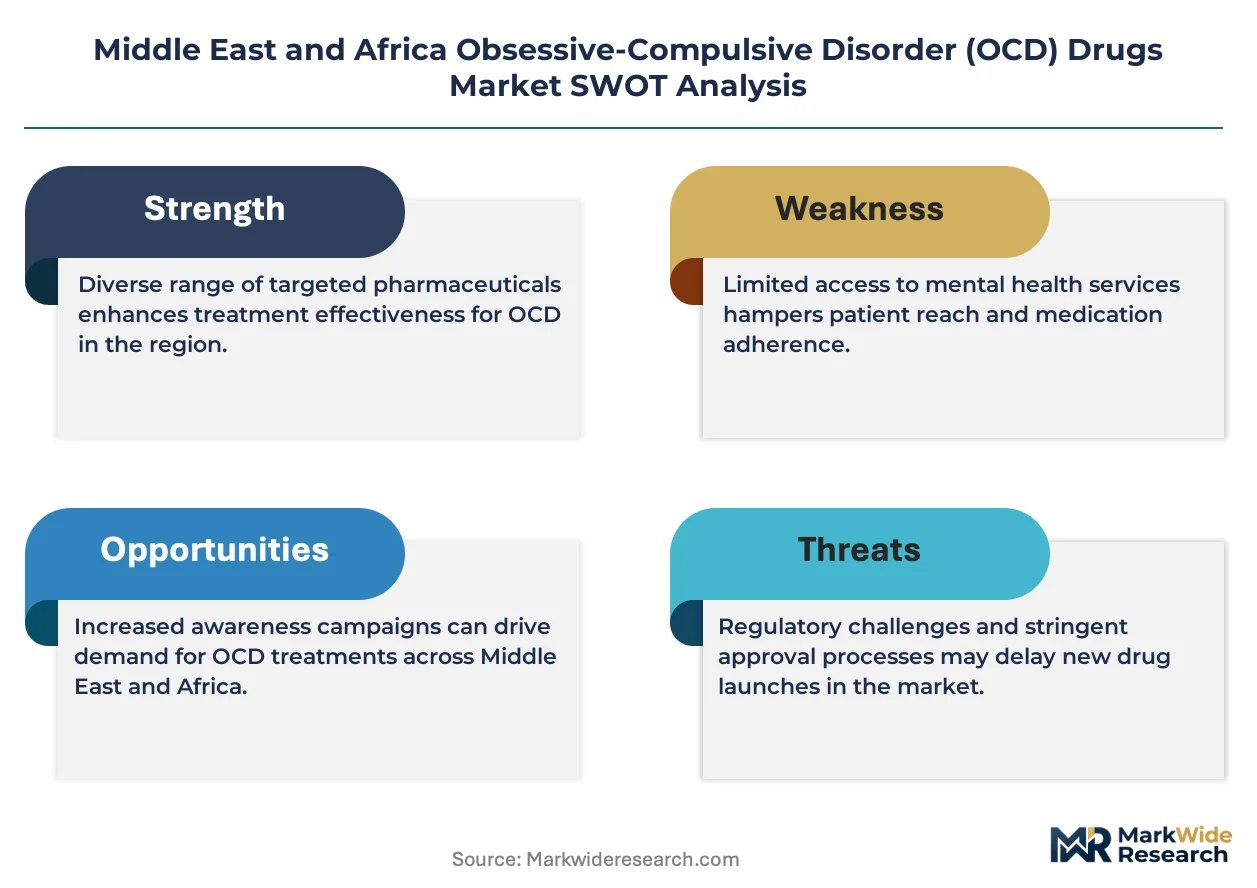
South Africa's Medicines Control Council bioequivalence requirements and Saudi Arabia's Food and Drug Authority registration pathways create a cost-of-compliance moat that favors established manufacturers with dedicated clinical infrastructure over opportunistic traders.
For Market Incumbents: Deepen formulary anchoring in Egyptian public health systems through Ministry of Health and Population decentralization initiatives, while securing intravenous psychotropic supply agreements with Johannesburg and Cape Town tertiary networks. Generic substitution guidelines in Gulf Cooperation Council states threaten branded SSRI volume, making bioequivalence certification investment and local manufacturing partnerships essential defensive levers. For New Entrants and Emerging Players: Pharmacogenomic testing platforms offer technology-first entry into South African private hospital chains where Netcare and Life Healthcare facilities increasingly demand CYP2D6 and CYP2C19 metabolic panels. Kenyan primary care networks present the most penetrable geography for SSRI detailing programs targeting general practitioner education, with telepsychiatry-SSRI integration as the optimal go-to-market angle. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional generic specialists with established Saudi Food and Drug Authority and UAE Ministry of Health and Prevention import licensing in place. Long-term viability hinges on Gulf state mental health insurance parity legislation sustaining reimbursement expansion. Monitor patient advocacy network demands for direct-to-consumer pharmacy channels as an inflection signal for retail channel volume concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Telepsychiatry Platform Integration | Remote diagnostic deployment across Dubai and Abu Dhabi outpatient networks redistributes prescribing authority from hospital infrastructure. |
| Pharmacogenomic Testing Partnership | CYP2D6 and CYP2C19 metabolic panel adoption at Netcare and Life Healthcare facilities personalizes SSRI selection protocols. |
| Expedited Regulatory Pathway Navigation | Saudi Food and Drug Authority mental health product fast-track compresses registration timelines for novel formulations. |
| API Supply Diversification | Indian and Chinese manufacturer relationships reduce single-source exposure for UAE and Saudi formulation plants. |
| Subscription Delivery Model Pilot | Community pharmacy chains in Dubai and Abu Dhabi test remote prescriber oversight for stable maintenance patient refills. |
Research Methodology
Independent corroboration across regulatory affairs leads at Saudi Arabia's Food and Drug Authority, formulary directors at UAE Ministry of Health and Prevention, and hospital procurement managers at South African tertiary centers underwrites the qualitative findings. Primary interviews with drug development executives at multinational neuroscience portfolios, payer access specialists at Gulf state insurance councils, and primary care physicians in Lagos and Nairobi urban clusters combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Bottom-up patient flow modeling and top-down reimbursement expenditure analysis triangulate volume estimates.
Rate-of-change decomposition across the projection horizon segments the market by drug type, administration route, end user channel, and treatment duration, with regional regulatory cluster as an additional modeled dimension. CAGRs derive from fitted growth curves applied to base-year observed volumes, adjusted for Saudi Council of Health Insurance mandate expansion rates and South African Medicines Control Council registration throughput. Forecast inputs include telepsychiatry platform deployment trajectories and pharmacogenomic testing adoption curves in private hospital chains.
Several conditions sit outside the modeled scope, including potential psychiatrist workforce expansion in sub-Saharan Africa, EU F-Gas Regulation propellant restriction modifications, and Gulf state currency peg adjustments. Forecasts reflect assumptions about sustained government insurance reimbursement commitment and stable API import logistics. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Nicotine Replacement Product Market
Pharmaceuticals
Asia Pacific Multiple Sclerosis Drugs Market
Pharmaceuticals
Calcineurin Inhibitor Drugs Market
Pharmaceuticals
Aripiprazole Market
Pharmaceuticals
Hyperphosphatemia Market
Pharmaceuticals
Mucosolvan (Ambroxol) Market
Pharmaceuticals
Oxycodone Market
Pharmaceuticals
Cervical Cancer Vaccine Market
Pharmaceuticals
Non-Alcoholic Steatohepatitis (NASH) Therapeutics and Diagnostics Market
Pharmaceuticals
Amylin Analogs Market
Pharmaceuticals
Trisenox Market
Pharmaceuticals
Sitagliptin Market
Pharmaceuticals
Galculus Bovis and Metronidazole Market
Pharmaceuticals
Global Self-Administered Drugs Market
Pharmaceuticals
Global Acetazolamide Market
Pharmaceuticals
Sildenafil Drug Market