
 Europe Small Molecule Sterile Injectable Drugs Market | 2026-2036
Europe Small Molecule Sterile Injectable Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Small Molecule Sterile Injectable Drugs Market Foresight
Hospital procurement channels across Europe is fragmenting as centralized tendering gives way to regional purchasing alliances and direct manufacturer contracts. Fresenius Kabi anchors its position through captive fill-finish capacity and vertical control over active pharmaceutical ingredient sourcing. Hikma Pharmaceuticals competes aggressively on cost-engineered generics, while Sanofi differentiates through proprietary delivery technologies and established hospital formularies.
Europe small molecule sterile injectable drugs comprise low-molecular-weight chemical entities formulated as pyrogen-free solutions, suspensions, or lyophilized powders for parenteral administration, typically requiring terminal sterilization or aseptic processing under ISO 5 conditions to ensure sterility assurance levels of 10^-6. These formulations serve critical therapeutic functions where oral bioavailability proves inadequate, such as in oncology, infectious diseases, and emergency anesthesia. Small molecule APIs retain the dominant revenue share within product type segmentation, though generics manufacturing is expanding fastest as patent cliffs deepen and biosimilar competition remains limited to biologics. Intravenous delivery mode still occupies the largest volume position, yet subcutaneous formulations are gaining structural importance as self-administration protocols shift site-of-care economics toward outpatient and home care settings.
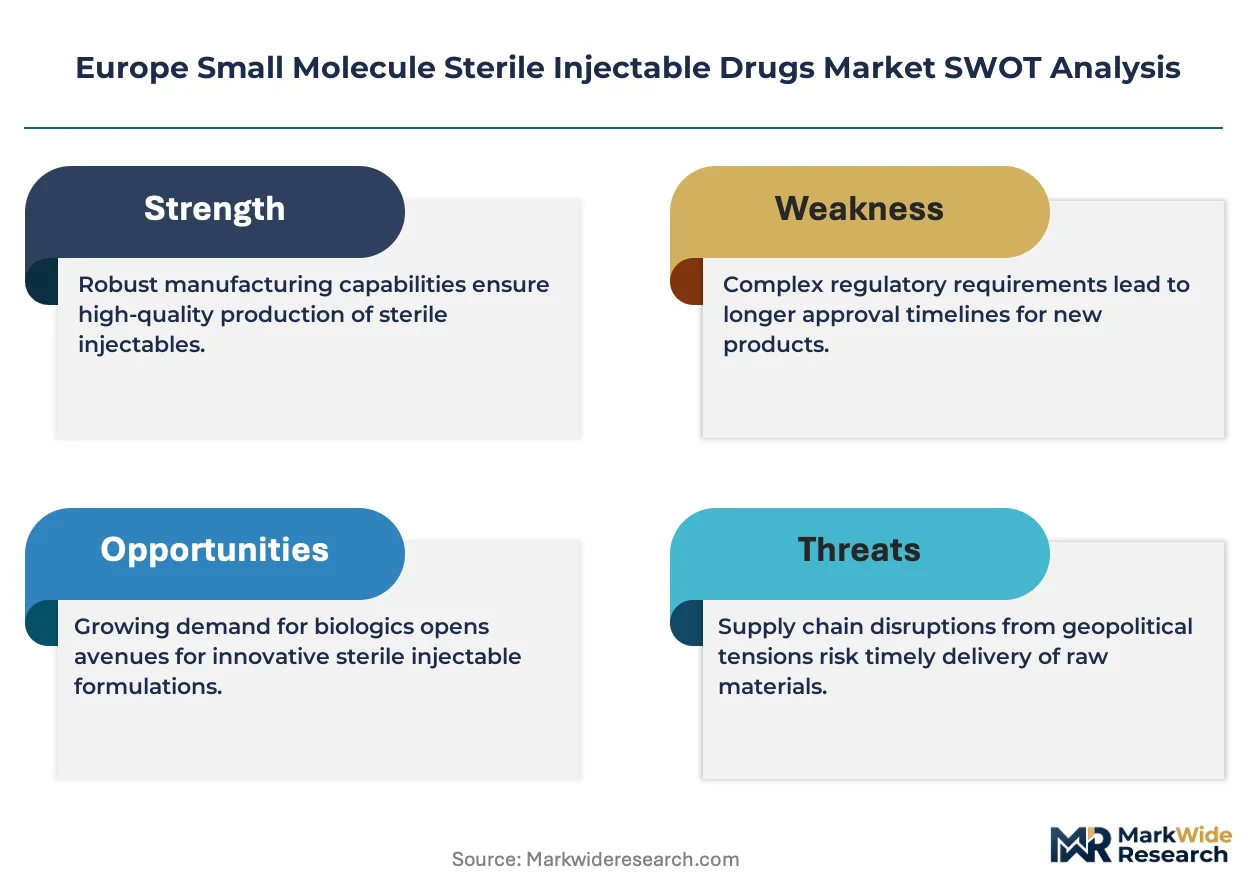
EMA's centralized marketing authorization procedure governs pan-European access, while national competent authorities in Germany, France, and Italy enforce batch release and GMP compliance through pharmacovigilance inspections. The EU's revised Annex 1 on sterile medicinal products mandates enhanced contamination control strategies, forcing manufacturers to upgrade isolator technology and real-time environmental monitoring systems. Stakeholders must weigh capital deployment toward modular aseptic filling lines against the risk of stranded assets if regulatory stringency tightens further on single-use technologies.
Market Dynamics
The EU's revised Annex 1 on sterile medicinal products is compressing manufacturing economics across Europe, forcing asset-heavy upgrades to isolator technology and real-time environmental monitoring while regional procurement alliances fragment traditional hospital tendering channels.
Growth Catalysts
- Oncology Unit Expansion:Hospital-based cancer centers across Germany and Italy are expanding ready-to-administer sterile injectable protocols, reducing pharmacy compounding burden and medication error risk.
- EMA Centralized Authorization:The centralized marketing authorization procedure accelerates pan-European market access, compressing time-to-revenue for manufacturers with compliant dossiers.
- Subcutaneous Formulation Shift:Self-administration protocols are displacing intravenous delivery in select therapeutic areas, opening outpatient and home care revenue streams.
Market Restraints
- API Supply Concentration:Active pharmaceutical ingredient sourcing concentrates in Asian manufacturing clusters, exposing European fill-finish operations to geopolitical and logistics disruption.
- Annex 1 Compliance Costs:The EU's contamination control mandate requires isolator upgrades and continuous particulate monitoring, straining mid-cap manufacturer balance sheets.
- Biosimilar Competition:Biologic alternatives in oncology and immunology are capturing patient volume previously served by small molecule cytotoxics.
Strategic Opportunities
- Poland and Czech Republic:Central European hospital networks remain underpenetrated by ready-to-use sterile injectables, offering first-mover expansion potential for compliant manufacturers.
- Modular Aseptic Lines:Flexible filling technologies enable rapid product changeover, allowing contract manufacturers to capture fragmented biotech client demand without dedicated assets.
- Green Chemistry Incentives:The EU Green Deal's pharmaceutical manufacturing sustainability mandates create competitive differentiation for solvent-reduction and waste-minimization technologies.
Industry Challenges
- Aseptic Processing Expertise Gap:Qualified personnel in isolator operation and environmental monitoring remain scarce across Rhineland and northern Italy manufacturing corridors.
- Legacy System Integration:Real-time monitoring platforms must interface with established manufacturing execution systems, creating validation complexity and timeline risk.
- Single-Use Technology Stranding:Capital deployed toward disposable fluid path technologies faces regulatory uncertainty as EMA evaluates extractables and leachables data requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Small Molecule Sterile Injectable Drugs Market |
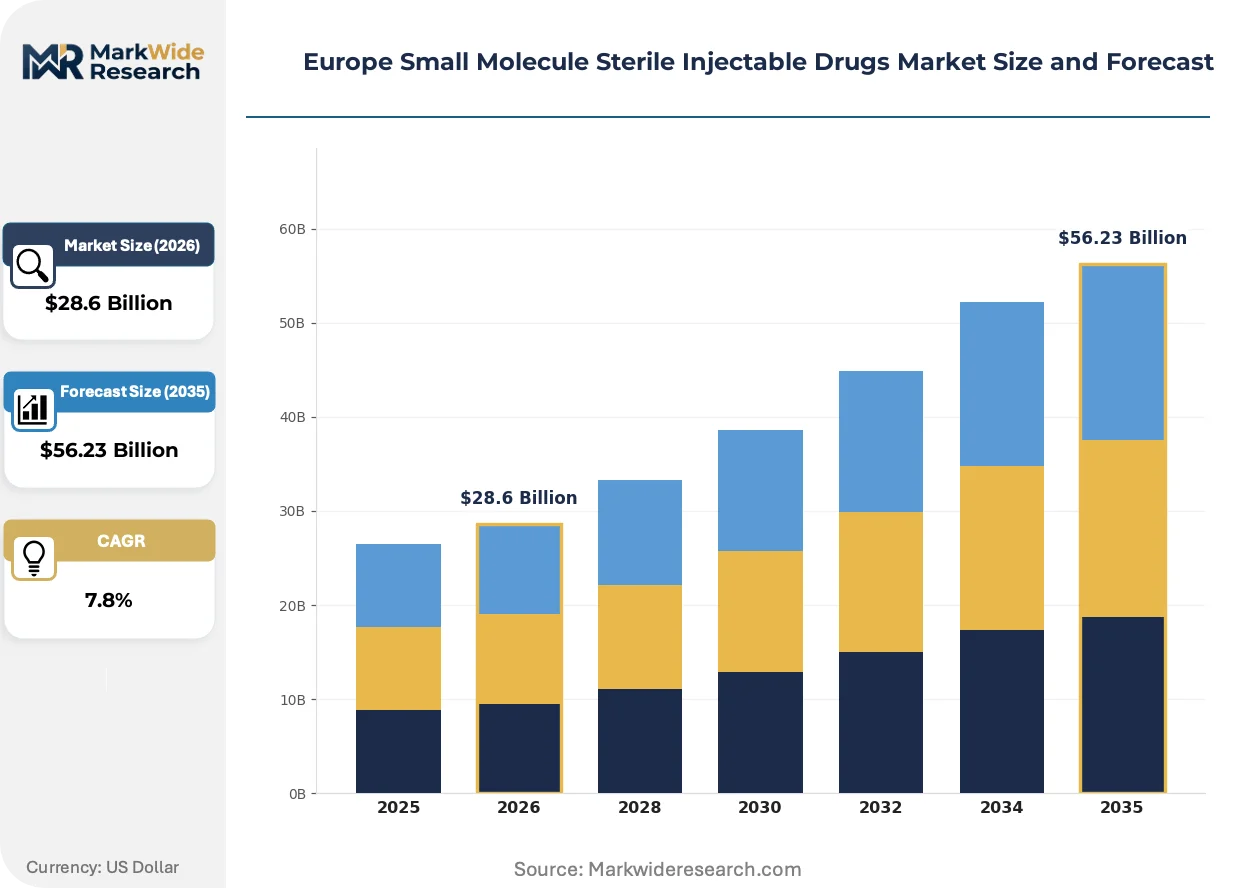
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $56.23 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Small Molecule APIs, Biosimilars, Generics Therapy Area: Oncology, Infectious Diseases, Autoimmune Disorders, Pain Management Delivery Mode: Subcutaneous, Intravenous, Intramuscular, Intraosseous End User: Hospitals, Clinics, Home Care, Specialty Pharmacies |
| Companies Covered | Gilead Sciences, Bristol-Myers Squibb Company, Fresenius Kabi, Cenexi, Merck Sharp & Dohme, Sanofi, Hikma Pharmaceuticals, Unither Pharmaceuticals, AstraZeneca, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Small Molecule Sterile Injectable Drugs Market Shifts & Advancements
Digital integration across manufacturing execution and quality systems is compressing batch release timelines while regulatory stringency around contamination control accelerates technology refresh cycles.
Closed isolator systems with integrated vaporized hydrogen peroxide decontamination are digitizing aseptic processing workflows across German and Italian manufacturing sites. Fresenius Kabi and specialized CMOs are adopting these platforms to reduce human intervention and environmental monitoring burden. The technology is digitizing compliance documentation, enabling real-time batch record review and compressing release timelines from weeks to days.
EMA's Annex 1 revision mandates enhanced contamination control strategies with specific requirements for barrier technology and continuous monitoring. Manufacturers must upgrade isolator infrastructure or risk inspection findings and supply interruptions. Oncology and anti-infective sterile injectables face the steepest compliance burden given their therapeutic criticality and volume concentration in European hospital formularies.
Hospital purchasing alliances in France and Spain are consolidating procurement authority previously dispersed across individual institutions. Regional tendering coalitions are displacing national framework agreements, fragmenting vendor access and compressing contract durations. Northern Italy's contract manufacturing corridor experiences the most acute pricing pressure as these alliances leverage volume concentration for preferential terms.
Europe Small Molecule Sterile Injectable Drugs Market Segmentation
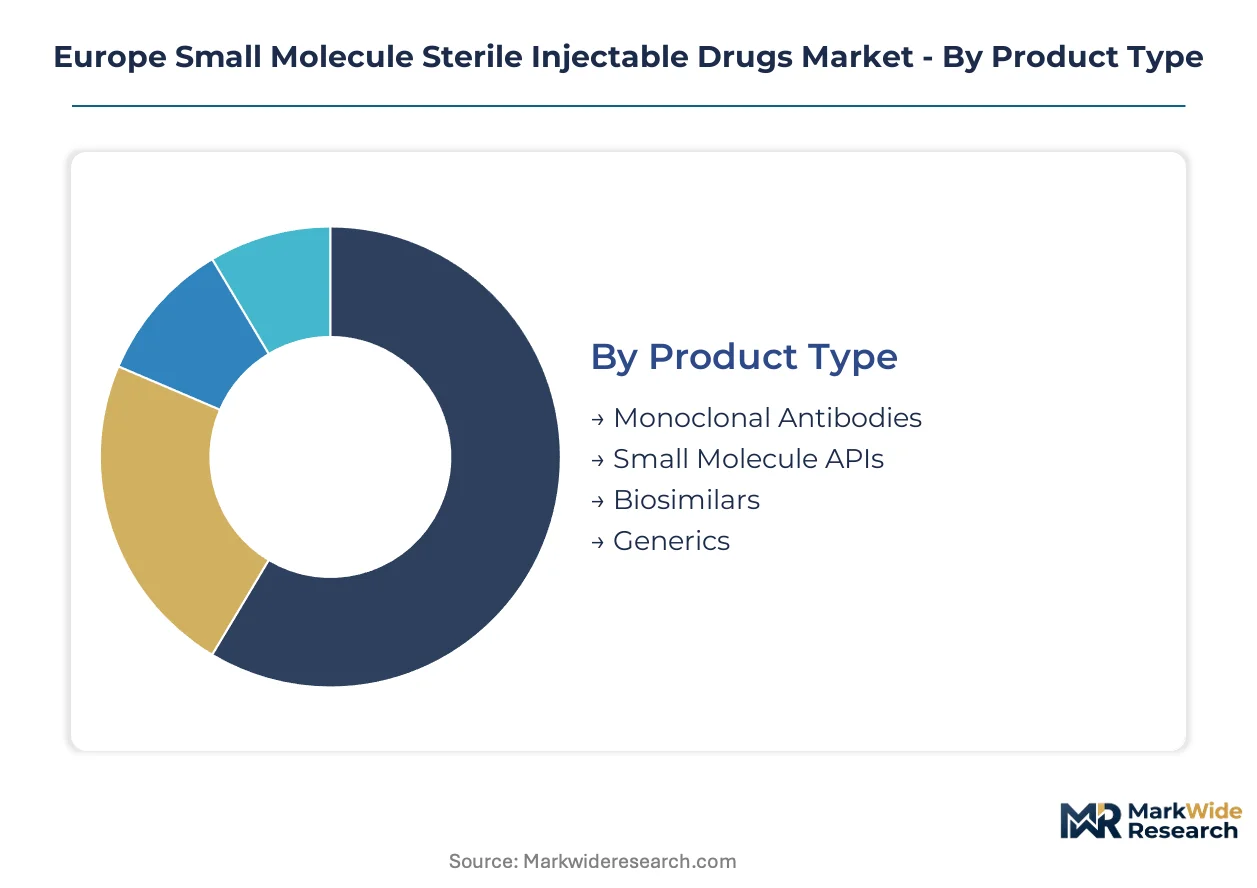
Segmentation in Europe's small molecule sterile injectable drugs market reveals distinct procurement patterns and margin structures across therapeutic applications and delivery technologies. Hospital formularies, EMA authorization pathways, and Annex 1 compliance requirements create divergent competitive dynamics within each category.
Product Type:
After-sales service intensity varies sharply across product types, with complex biologics demanding cold chain validation and batch-specific pharmacovigilance support that small molecule APIs rarely require.
- Small Molecule APIs:Low-molecular-weight chemical entities formulated as pyrogen-free solutions or lyophilized powders for parenteral administration. Demand concentrates in Germany's Rhineland pharmaceutical cluster, where Fresenius Kabi and specialized CMOs maintain captive fill-finish capacity and backward integration into active pharmaceutical ingredient sourcing.
- Generics:Cost-engineered formulations of off-patent small molecules, typically requiring terminal sterilization or aseptic processing under ISO 5 conditions. Procurement is fragmenting across regional purchasing alliances in France and Spain, compressing contract durations and pricing power for manufacturers lacking scale.
- Monoclonal Antibodies:Large protein therapeutics requiring sophisticated cold chain infrastructure and specialized handling protocols.
- Biosimilars:Follow-on biologics with abbreviated approval pathways but complex immunogenicity monitoring requirements.
By volume, Small Molecule APIs leads. By growth pace, Generics is expanding most quickly as patent cliffs deepen and hospital procurement shifts toward cost containment.
Therapy Area:
Margin structures align with therapeutic criticality, where oncology formulations command premium pricing supported by hospital formulary stickiness and limited substitution flexibility.
- Oncology:Cytotoxic and cytostatic agents for cancer treatment, including alkylating agents, antimetabolites, and mitotic inhibitors. Hospital-based cancer centers across Germany and Italy are expanding ready-to-administer protocols, reducing pharmacy compounding burden while tightening sterility assurance requirements under EMA's Annex 1 revision.
- Infectious Diseases:Antibacterial, antiviral, and antifungal sterile injectables for severe or resistant infections. Northern Italy's contract manufacturing corridor experiences acute capacity pressure as these products face the steepest compliance burden given their therapeutic criticality and volume concentration in European hospital formularies.
- Autoimmune Disorders:Immunomodulatory agents for rheumatoid arthritis, multiple sclerosis, and inflammatory bowel disease.
- Pain Management:Opioid and non-opioid analgesics for acute and chronic pain control.
By revenue concentration, Oncology dominates. By patient volume expansion, Infectious Diseases is gaining share fastest amid antimicrobial resistance protocols.
Delivery Mode:
Supply concentration patterns reflect manufacturing complexity, with intravenous formulations requiring bulk aseptic filling capacity that subcutaneous alternatives can bypass through prefilled syringe technologies.
- Intravenous:Direct vascular administration requiring infusion-compatible formulations with specific osmolality and pH parameters. Germany's hospital networks maintain the largest installed base of infusion pump infrastructure, anchoring demand for IV-compatible presentations despite the shift toward outpatient care.
- Subcutaneous:Tissue-layer injection enabling self-administration and home care displacement of hospital-based treatment. Self-administration protocols are opening outpatient and home care revenue streams across France and the United Kingdom, restructuring site-of-care economics for manufacturers with compliant device-drug combinations.
- Intramuscular:Deep tissue injection for depot formulations and rapid absorption requirements.
- Intraosseous:Emergency vascular access through bone marrow cavity for critical care scenarios.
By current volume, Intravenous retains the largest position. By structural shift magnitude, Subcutaneous shows the steepest expansion trajectory as home care protocols proliferate.
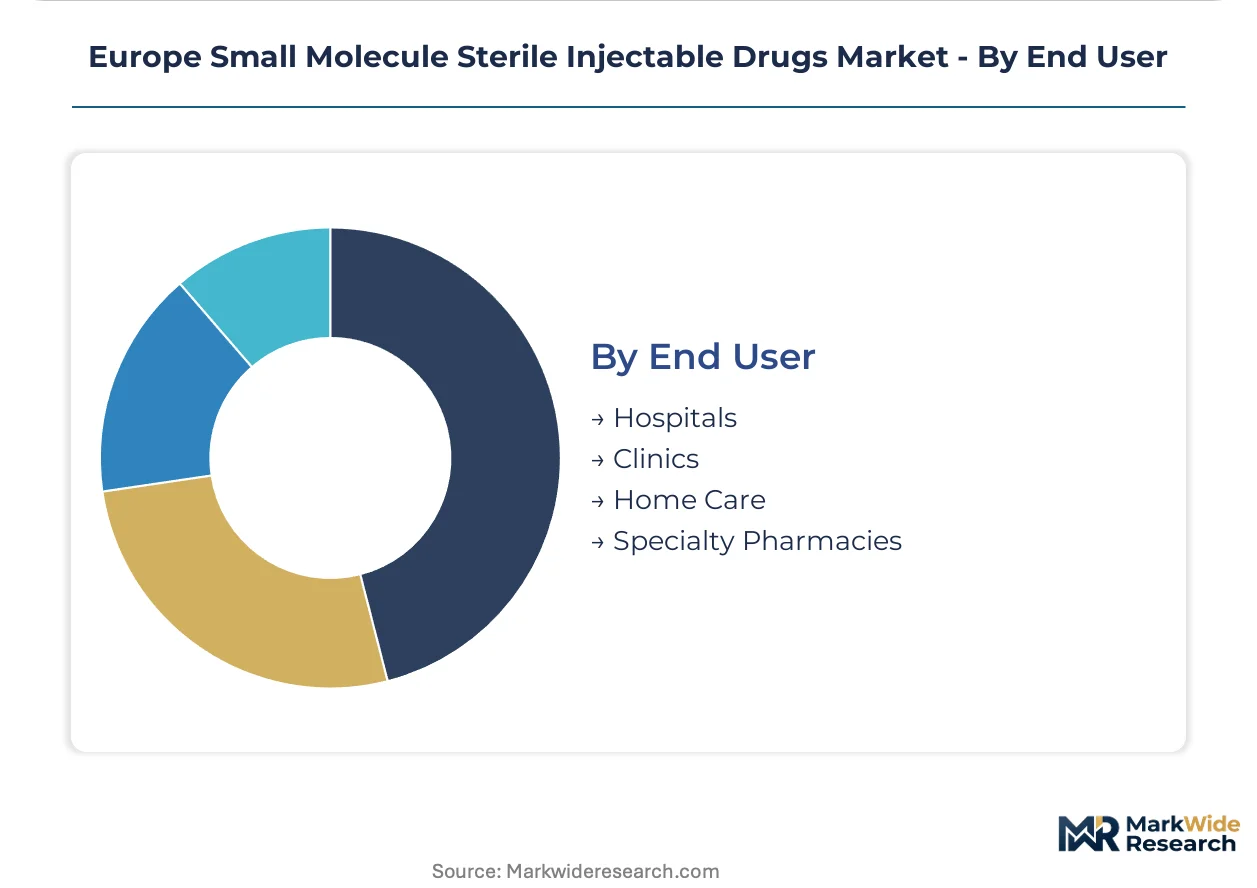
End User:
Customer type determines regulatory interface intensity, with hospital pharmacies subject to national competent authority inspections that home care channels largely avoid.
- Hospitals:Institutional purchasers with centralized pharmacy operations and formulary committees governing product selection. Poland and Czech Republic hospital networks remain underpenetrated by ready-to-use sterile injectables, offering first-mover expansion potential for manufacturers with EMA-compliant dossiers and modular aseptic filling flexibility.
- Home Care:Patient-directed administration with nursing support or self-injection protocols. The EU Green Deal's pharmaceutical manufacturing sustainability mandates create competitive differentiation for solvent-reduction technologies serving this channel's waste minimization requirements.
- Clinics:Outpatient facilities with limited compounding capacity favoring ready-to-administer presentations.
- Specialty Pharmacies:Distribution channels with cold chain expertise and patient support programs for complex therapies.
By procurement authority concentration, Hospitals dominates. By channel growth acceleration, Home Care is climbing the fastest as subcutaneous formulations enable site-of-care migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube waterway corridor underwrites Central Europe's dominance in sterile injectable distribution, connecting Bavarian manufacturing clusters to North Sea ports and Black Sea markets.
Germany
Hospital-based oncology units in Rhineland and Bavaria are expanding ready-to-administer protocols. EMA's centralized marketing authorization procedure accelerates dossier approval for manufacturers with compliant isolator infrastructure. Frankfurt's logistics hub anchors cold chain distribution for temperature-sensitive cytotoxics moving eastward.
Italy
Northern Italy's contract manufacturing corridor faces acute capacity pressure from infectious disease sterile injectables demand. ANSM enforces batch release compliance alongside EMA's Annex 1 contamination control mandates. Milan's pharmaceutical cluster concentrates fill-finish operations serving French and Spanish procurement alliances.
France
Regional hospital purchasing alliances are consolidating procurement authority previously held by individual institutions. The EU Green Deal's pharmaceutical sustainability mandates drive solvent-reduction investments among Paris-region manufacturers. Lyon biotech corridor hosts specialized CMOs targeting subcutaneous formulation shifts.
United Kingdom
Home care protocols for self-administered injectables are restructuring site-of-care economics across NHS trusts. MHRA operates parallel recognition procedures with EMA while maintaining sovereign batch release authority. London's research triangle attracts biotech clients seeking modular aseptic filling partnerships.
Poland
Hospital networks in Warsaw and Krakow remain underpenetrated by ready-to-use sterile injectables. The country's national pharmaceutical regulator enforces GMP compliance through pharmacovigilance inspections aligned with EU directives. Silesian manufacturing zones offer expansion capacity for compliant fill-finish operators.
Europe Small Molecule Sterile Injectable Drugs Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic archetypes: vertically integrated pharmaceutical conglomerates with captive API-to-finish control, cost-engineered generic specialists competing on tender pricing, and flexible contract manufacturers capturing fragmented biotech demand through modular asset deployment. Dominant competitive moves include backward integration into active pharmaceutical ingredient sourcing and strategic partnerships with regional hospital purchasing alliances.
Among Germany-based integrated operators, Fresenius Kabi exemplifies the captive capacity archetype through Rhineland manufacturing concentration. Hikma Pharmaceuticals occupies a position within the cost-competitive generic tier, while Sanofi anchors the proprietary delivery technology segment. Cenexi and Unither Pharmaceuticals represent the contract manufacturing specialization vector, serving biotech clients requiring rapid product changeover capabilities without dedicated asset commitment.
| Leading Market Players |
|---|
| Gilead Sciences |
| Bristol-Myers Squibb Company |
| Fresenius Kabi |
| Cenexi |
| Merck Sharp & Dohme |
| Sanofi |
| Hikma Pharmaceuticals |
| Unither Pharmaceuticals |
| AstraZeneca |
| Others |
Supply & Pricing Matrix
API manufacturing concentration in India and China feeds margin compression downstream, where European fill-finish operators absorb cost volatility while hospital purchasing alliances extract volume discounts. The pricing structure stratifies across three tiers: premium proprietary formulations, standard authorized generics, and economy tender-driven commodities.
Pricing Analysis
Volume-discount tiering structures dominate procurement across German and French hospital networks, with regional purchasing alliances consolidating demand to extract preferential terms. Price differentiation rests on Annex 1 compliance certification and captive API sourcing, where backward-integrated manufacturers command premium positioning. Cost compression in the generics tier is intensifying as Polish and Czech procurement channels mature, with tender-driven pricing eroding margins for non-integrated suppliers. Hospital pharmacy directors exhibit the sharpest price sensitivity, while oncology formularies retain substitution flexibility constraints that protect premium tiers.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard across Italian and Spanish hospital procurement, straining mid-cap manufacturer working capital cycles. Active pharmaceutical ingredient sourcing draws from India, China, and Switzerland, with fill-finish operations concentrated in Germany's Rhineland and northern Italy's contract manufacturing corridor. Single-source vulnerability in isolator technology suppliers creates bottleneck risk as Annex 1 compliance drives simultaneous upgrade cycles. Distribution runs through temperature-controlled logistics networks anchored at Frankfurt and Milan, with final-mile delivery to hospital pharmacies governed by national competent authority batch release protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's small molecule sterile injectable market sits in early-cycle expansion, with Poland and Czech Republic hospital networks offering penetration runway as ready-to-use protocols displace compounding workflows.
For Market Incumbents: Entrench formulary position through isolator infrastructure upgrades that lock in Annex 1 compliance ahead of inspection backlogs. Deepen backward integration into API sourcing to offset Asian supply chain volatility, while securing multi-year direct contracts with Rhineland and Bavarian oncology centers to bypass fragmenting tender channels. For New Entrants and Emerging Players: Build out modular aseptic filling capacity in Silesian manufacturing zones to serve biotech clients requiring rapid product changeover without dedicated asset commitment. Poland's underpenetrated hospital networks offer first-mover access for EMA-compliant dossiers, with subcutaneous formulation partnerships providing the strongest go-to-market angle for home care channel expansion. For Investors and Strategic Acquirers: Capital is best deployed toward contract manufacturing specialists with isolator technology and established EMA inspection track records, positioned to capture biotech outsourcing demand across the analysis window. Watch for inflection in EMA extractables and leachables guidance on single-use technologies, which would strand capital in disposable fluid path systems and favor stainless steel isolator investments.| Strategic Initiative | Industry Significance |
|---|---|
| Isolator Technology Upgrade | Annex 1 compliance mandates barrier systems with vaporized hydrogen peroxide decontamination, reducing human intervention and inspection risk. |
| Backward API Integration | Captive sourcing from Rhineland chemical clusters insulates fill-finish operations from India-China supply disruption and tariff exposure. |
| Modular Aseptic Line Deployment | Flexible filling platforms enable rapid product changeover, allowing CMOs to serve fragmented biotech demand without dedicated assets. |
| Regional Purchasing Alliance Partnership | Direct contracts with French and Spanish hospital coalitions secure volume commitments outside national tender frameworks. |
| Subcutaneous Formulation Development | Self-administration protocols shift site-of-care economics toward outpatient and home care, opening reimbursement-advantaged revenue streams. |
Research Methodology
Initial hypotheses were tested against primary input from hospital pharmacy directors, regulatory affairs leads at EMA-compliant manufacturers, formulary committee members, and procurement managers at regional purchasing alliances, then refined through secondary validation against EMA submission databases, national competent authority inspection records, ClinicalTrials.gov protocols, and hospital procurement tender documents. Bottom-up demand modeling across therapy areas and delivery modes was triangulated with top-down market sizing from trade flow analysis and industry association disclosures.
Demand-supply-balance framing anchored the analytical framework, with segmentation dimensions spanning product type, therapy area, delivery mode, and end-user channel modeled across the projection horizon. CAGRs were derived from growth driver elasticity analysis and patent cliff timing, with inputs including oncology protocol expansion rates, isolator capacity utilization across German and Italian manufacturing corridors, and subcutaneous formulation adoption curves in NHS trusts.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Asian API suppliers or accelerated EMA stringency on single-use technologies would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Pneumococcal Vaccines Market
Pharmaceuticals
Middle East and Africa Obsessive-Compulsive Disorder (OCD) Drugs Market
Pharmaceuticals
Latin America Biguanide Market
Pharmaceuticals
Bevacizumab Market
Pharmaceuticals
Adenosine Market
Pharmaceuticals
Anthrax Treatment Market
Pharmaceuticals
Posaconazole Market
Pharmaceuticals
Systemic Antibiotics Market
Pharmaceuticals
Anticholinergic Drugs Market
Pharmaceuticals
Global Urothelial Cancer Drugs Market
Pharmaceuticals
Sleeping Medications Market
Pharmaceuticals
Urticaria Drugs Market
Pharmaceuticals
Global Zika Vaccines Market
Pharmaceuticals
Quinolones Market
Pharmaceuticals
Nesiritide Market
Pharmaceuticals
Botulinum Toxin Market