
 Europe Laxative Market | 2026-2036
Europe Laxative Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Laxative Market Foresight
European pharmaceutical manufacturing is repositioning toward higher-margin specialty digestive health products. Bayer AG leverages its consumer health division to sustain broad retail penetration across German-speaking markets. Sanofi S.A. anchors its position through pharmacy-centric distribution and clinician endorsement programs. GlaxoSmithKline plc competes via differentiated fiber supplement formulations targeting chronic constipation management.
Laxatives comprise pharmacological agents that promote bowel evacuation through osmotic water retention, stool softening, or intestinal motility stimulation, with active ingredients ranging from macrogol polymers to bisacodyl and senna glycosides. These products serve therapeutic and preventive roles in managing opioid-induced constipation, irritable bowel syndrome with constipation, and age-related colonic hypomotility. Osmotic laxatives lead volume consumption due to favorable tolerability profiles and EMA-preferred first-line status in chronic use guidelines. Tablet formulations dominate pharmacy channel flows, while liquid and powder formats capture expanding homecare segments driven by dysphagia prevalence and dosing flexibility preferences.
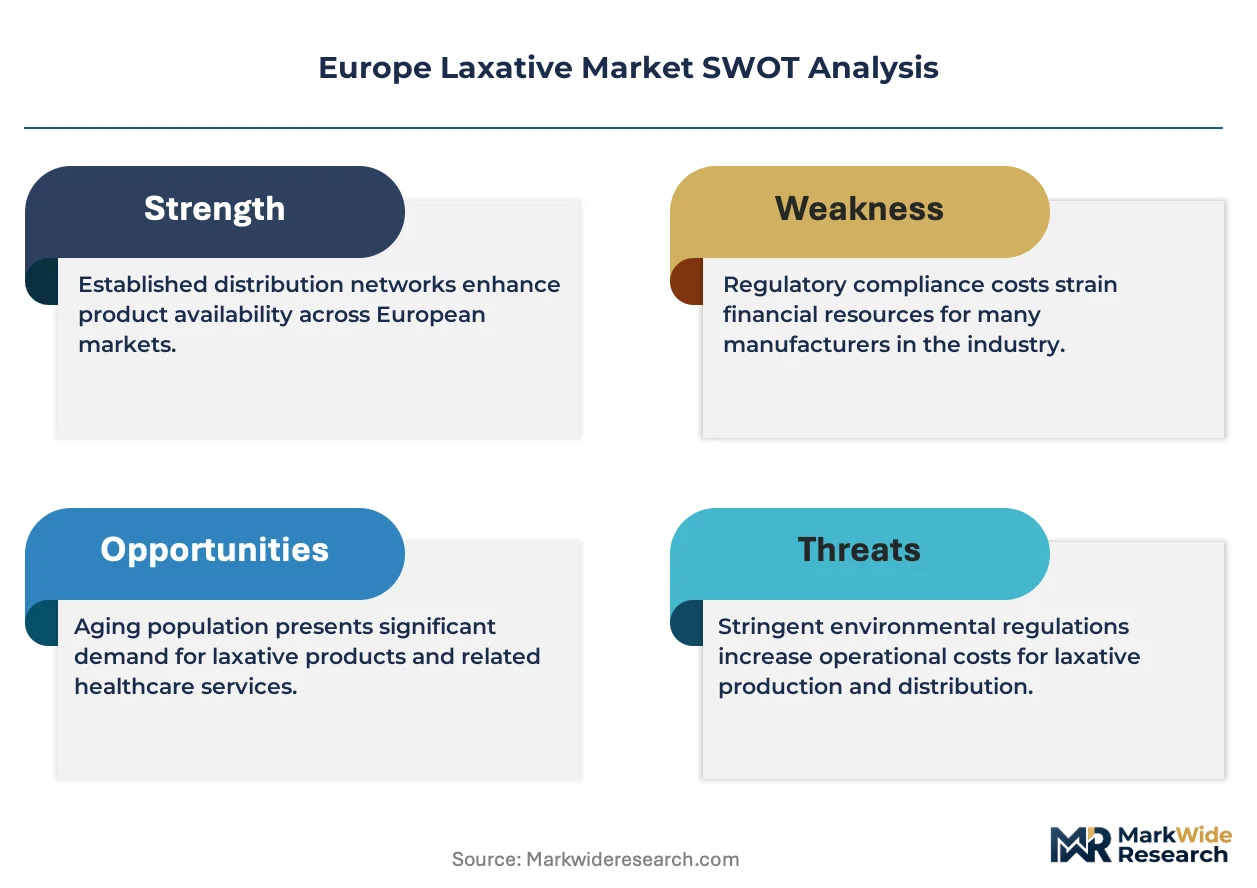
EMA oversight of OTC reclassification pathways, coupled with national regulators like Germany's BfArM and France's ANSM, shapes product labeling, indication breadth, and advertising boundaries for non-prescription laxatives. REACH compliance for excipient sourcing and the EU Medical Device Regulation borderline classifications for certain delivery mechanisms further constrain formulation and packaging decisions. Stakeholders must monitor evolving pharmacovigilance signal detection requirements and pre-emptive pricing negotiations with national reimbursement authorities.
Market Dynamics
EMA pharmacovigilance requirements for OTC reclassification are compressing formulation timelines and forcing manufacturers toward chronic-use safety profiles that satisfy BfArM and ANSM scrutiny.
Growth Catalysts
- Geriatric institutionalization:Nursing home and long-term care facility admissions across Germany, France, and Italy generate sustained demand for predictable bowel management protocols.
- REACH-compliant macrogol sourcing:Polymer supply chain standardization under ECHA oversight reduces excipient variability and accelerates batch release timelines.
- Opioid-induced constipation protocols:Palliative care guidelines in the United Kingdom and Netherlands embed osmotic laxatives as first-line adjunct therapy.
Market Restraints
- API concentration in India and China:Bisacodyl and senna glycoside active pharmaceutical ingredient supply depends on Asian contract manufacturers, exposing European formulators to freight cost volatility and customs delays.
- EU Medical Device Regulation borderline ambiguity:Certain rectal delivery mechanisms face reclassification scrutiny, extending compliance timelines and freezing pipeline investments.
- Herbal substitute competition:Fiber supplements and probiotic alternatives capture preventive-use occasions, narrowing the addressable therapeutic window for pharmacological laxatives.
Strategic Opportunities
- Poland and Romania retail pharmacy expansion:Underpenetrated Eastern European markets offer volume growth through pharmacy chain consolidation and clinician education programs.
- Dual carbon goal alignment:Sustainable packaging mandates under the EU Green Deal create premium positioning for biodegradable sachet and blister formats.
- Homecare liquid format penetration:Dysphagia-prevalent aging populations in Spain and Belgium shift consumption toward flexible-dose liquid and powder formulations.
Industry Challenges
- Pharmacovigilance signal detection staffing:EMA's strengthened adverse event reporting requirements demand specialized safety science personnel that mid-tier manufacturers struggle to recruit.
- Legacy ERP integration with track-and-trace systems:Falsified Medicines Directive serialization mandates force costly upgrades to manufacturing execution software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Laxative Market |
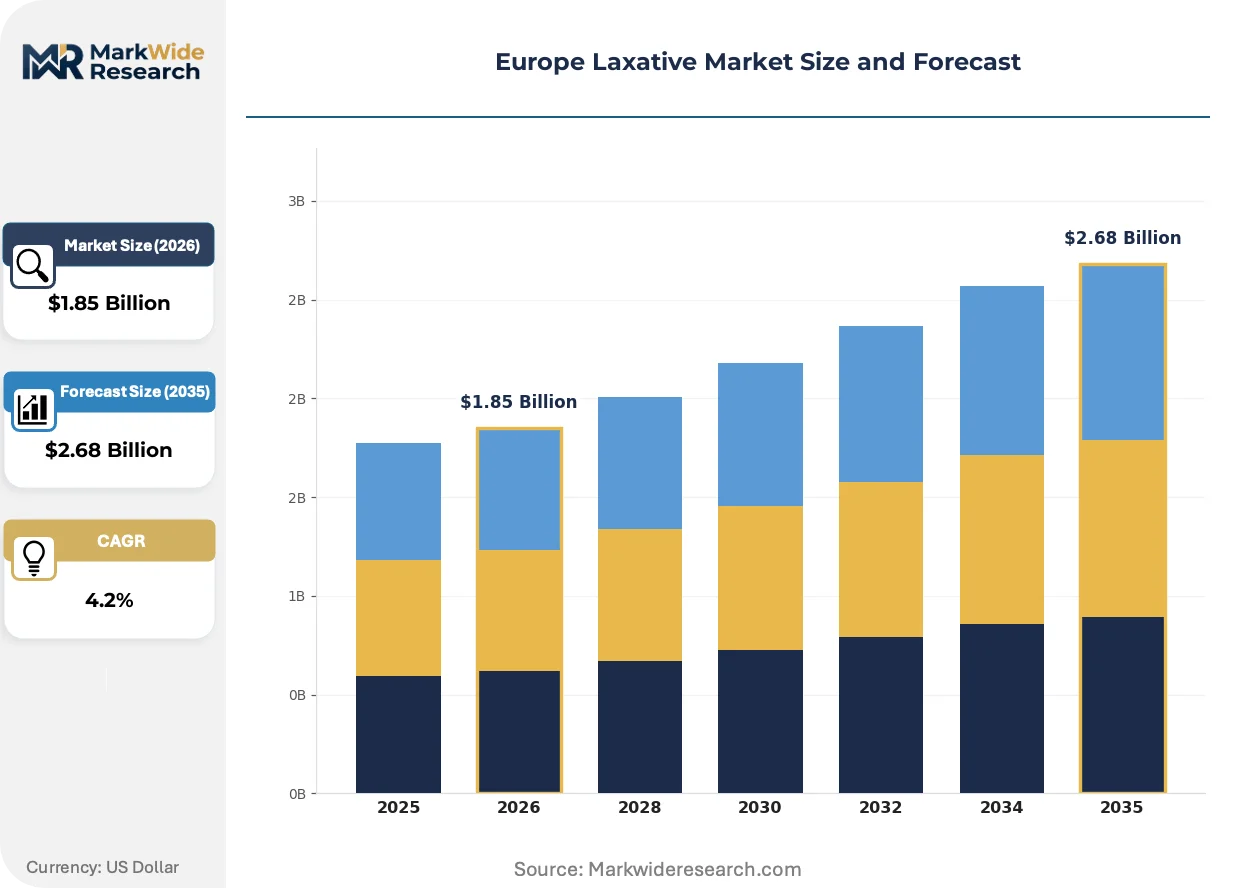
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.68 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stool Softener, Fiber Supplement, Osmotic Laxative, Stimulant Laxative Form: Tablet, Liquid, Powder, Suppository End User: Hospitals, Pharmacies, Homecare, Clinics Distribution Channel: Online Retail, Drugstores, Supermarkets, Health Stores |
| Companies Covered | Bayer AG, GlaxoSmithKline plc, Sanofi S.A., AstraZeneca, Teva Pharmaceutical Industries Ltd., Novartis AG, Boehringer Ingelheim GmbH, Takeda Pharmaceutical Company Limited, F. Hoffmann-La Roche Ltd., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Laxative Market Shifts & Advancements
Formulation science and distribution architecture are converging to reshape how European consumers access and adhere to constipation therapies, with technology and regulation acting as twin accelerants.
Macrogol polymer engineering with controlled-release kinetics is electrifying the chronic constipation segment. German and French gastroenterology practices are adopting these formulations for IBS-C patients who failed first-line fiber therapy. The technology is compressing the trial-and-error treatment cycle that previously delayed effective symptom control.
EMA's strengthened OTC reclassification pathways are forcing manufacturers to generate real-world evidence before pharmacy-only status expires. France's ANSM now requires 12-month post-marketing surveillance for bisacodyl switches, extending investment recovery timelines. Osmotic laxative categories face the tightest evidentiary scrutiny due to their chronic-use positioning.
Spanish and Italian pharmacy chains are consolidating procurement through central buying cooperatives, displacing the traditional wholesaler-dominant model. Independent pharmacies in Portugal are responding by joining franchise networks that negotiate volume terms collectively. Channel concentration is most visible in Iberia, where three cooperatives now control over half of laxative shelf placement decisions.
Europe Laxative Market Segmentation
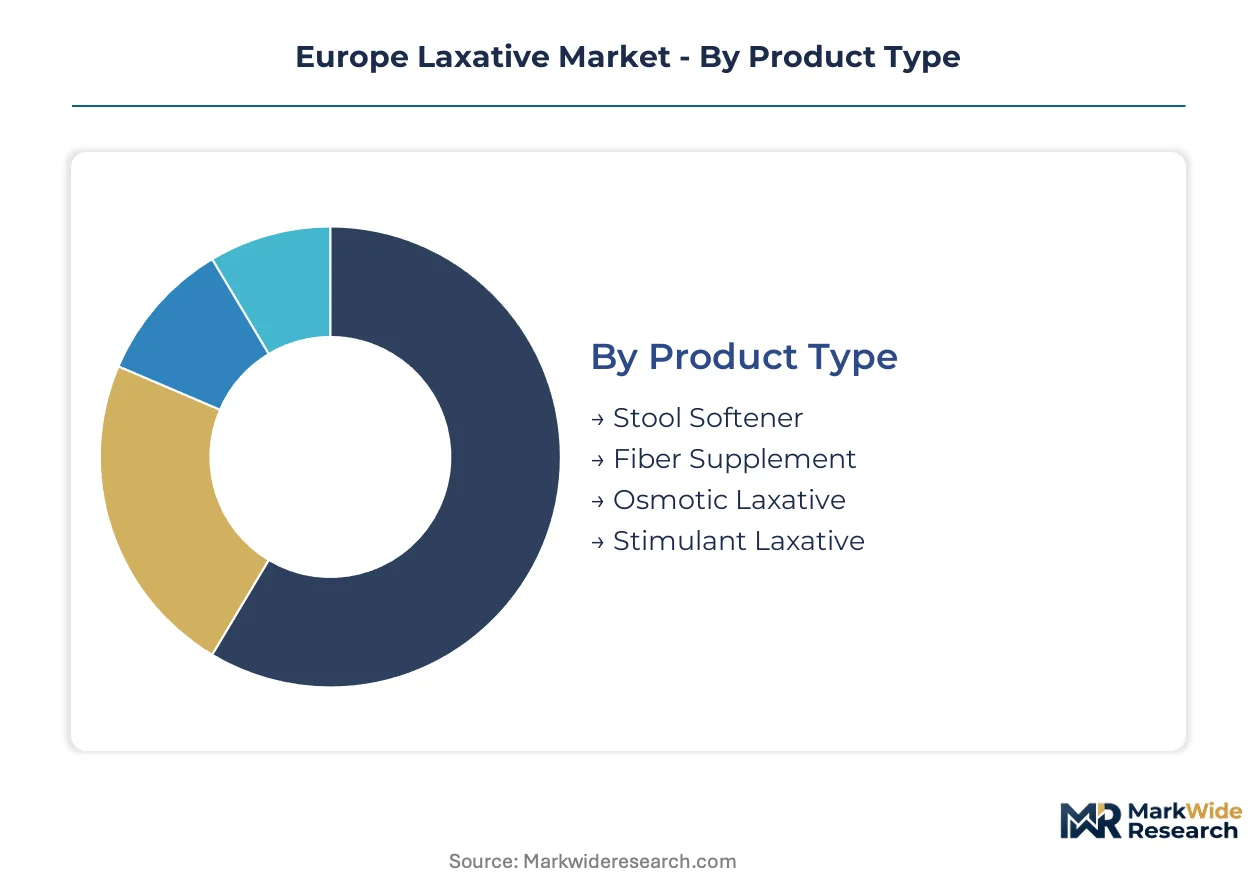
Laxative segmentation in Europe reflects divergent clinical protocols, patient compliance preferences, and channel access patterns. Manufacturers calibrate portfolio depth across each axis to match reimbursement pathways and EMA labeling constraints. The analysis below maps four structural dimensions governing commercial positioning.
Product Type:
Customization versus standardization varies sharply across pharmacological mechanisms, with chronic-use safety profiles demanding formulation precision while acute therapies tolerate commodity sourcing.
- Osmotic Laxative:Macrogol-based formulations retain water in the intestinal lumen through osmotic pressure, producing predictable bowel evacuation without cramping. German nursing homes and French palliative care units specify these agents in standardized protocols for opioid-induced constipation, driving volume concentration in institutional procurement. EMA guidelines designate osmotics as first-line for chronic use, compressing competitor entry timelines.
- Stimulant Laxative:Bisacodyl and senna glycosides trigger colonic motility through direct neural stimulation. Pharmacy dispensing in Italy and Spain favors these for acute constipation episodes where rapid onset outweighs tolerability concerns. ANSM scrutiny of chronic safety signals constrains indication expansion.
- Stool Softener:Docusate sodium reduces stool surface tension to ease passage without stimulating peristalsis. Pediatric and post-surgical applications in Belgian and Dutch hospitals specify these for gentle bowel management.
- Fiber Supplement:Psyllium and methylcellulose bulk-forming agents supplement dietary intake for preventive use. Health store and supermarket channels in the United Kingdom capture wellness-oriented consumers seeking non-pharmacological alternatives.
Most installed capacity flows through Osmotic Laxative. Expansion is steepest in Fiber Supplement.
Form:
Patient capability constraints and dosing precision requirements segment format adoption across acute care and domiciliary settings.
- Tablet:Compressed dosages dominate pharmacy fulfillment for ambulatory patients with intact swallowing function. German and Austrian pharmacy chains stock extended-release bisacodyl tablets as standard constipation therapy.
- Liquid:Flexible volumetric dosing serves dysphagia-prevalent geriatric populations and pediatric titration protocols. Spanish homecare nursing services specify macrogol solutions for precise electrolyte-balanced administration.
- Powder:Reconstitutable sachets combine portability with dose customization. French and Italian consumers favor these for travel and intermittent use occasions.
- Suppository:Rectal delivery bypasses gastrointestinal absorption for rapid local action. Hospital emergency departments in the United Kingdom and Netherlands stock these for fecal impaction management.
Tablet commands current volume leadership. Liquid formats are climbing the fastest as homecare penetration deepens.
End User:
Care setting determines product sophistication, with institutional procurement emphasizing protocol adherence and cost predictability.
- Homecare:Self-administered therapies purchased through retail channels or reimbursed domiciliary prescriptions. Aging-in-place policies across France, Germany, and the United Kingdom shift bowel management from institutional to residential settings.
- Hospitals:Acute care facilities standardize on osmotic protocols for post-operative ileus and medication-induced constipation. British NHS trusts and German Klinikum networks negotiate centralized purchasing agreements.
- Pharmacies:Community dispensaries provide pharmacist-guided selection between OTC and pharmacy-only categories. French officines and German Apotheken maintain category expertise that steers patient choices.
- Clinics:Outpatient gastroenterology practices prescribe specialized formulations for IBS-C and chronic idiopathic constipation. Italian and Spanish specialist centers drive adoption of controlled-release macrogol engineering.
Pharmacies handle the greatest transaction volume. Homecare is gaining share fastest as policy favors deinstitutionalization.
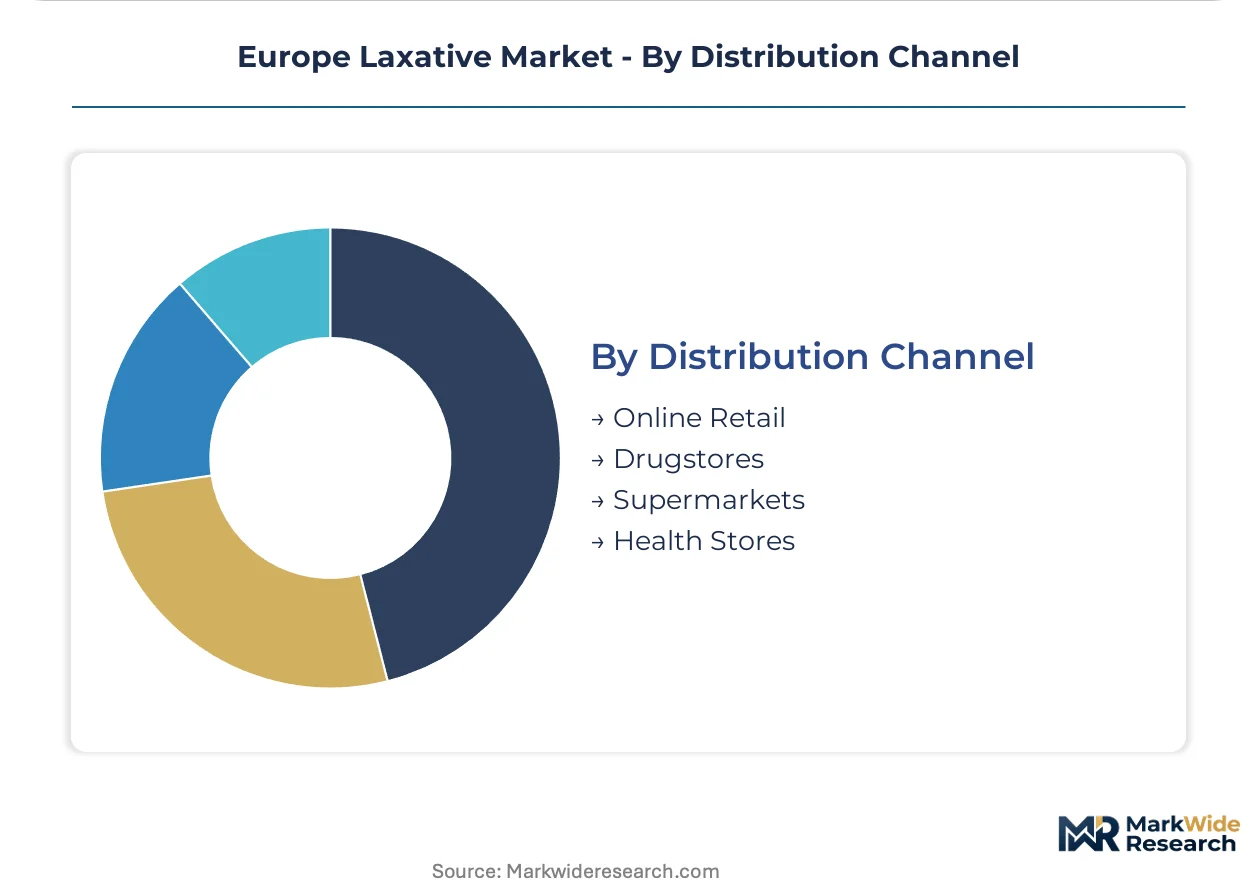
Distribution Channel:
Channel concentration reflects regulatory boundaries between pharmacy-only and general retail sale categories.
- Drugstores:Pharmacy-affiliated retail captures prescription and pharmacy-only OTC laxatives. German dm-drogerie and French Para pharmacies dominate shelf placement for fiber supplements and docusate products.
- Online Retail:E-commerce platforms aggregate subscription and replenishment purchasing. United Kingdom and Dutch consumers increasingly source macrogol powders through pharmacy-integrated digital channels.
- Supermarkets:Mass merchandisers stock general sale fiber supplements and stimulant laxatives. Tesco, Carrefour, and REWE chains in their respective markets compete on price for bulk psyllium.
- Health Stores:Specialized wellness retailers emphasize natural and organic positioning. Holland & Barrett in the United Kingdom and DIO pharmacies in Italy curate probiotic-fiber combination products.
Drugstores retain the deepest category penetration. Online Retail is expanding most quickly as serialization compliance enables legitimate digital dispensing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as formulators migrate production toward jurisdictions with streamlined EMA compliance pathways and favorable BfArM inspection schedules. Cost-of-compliance gaps between Western and Central European facilities are compressing as REACH enforcement harmonizes, yet legacy capacity advantages persist in established clusters.
Germany
Nursing home procurement standardization and Klinikum network centralization drive institutional demand for macrogol protocols. BfArM pharmacovigilance requirements for OTC switches enforce 18-month post-market surveillance, extending investment recovery timelines. The Rhine-Main manufacturing corridor hosts concentrated formulation capacity serving German-speaking markets.
France
ANSM's 12-month surveillance mandate for bisacodyl reclassifications constrains indication expansion for stimulant categories. Pharmacy chain consolidation through central buying cooperatives displaces traditional wholesaler relationships. The Lyon pharmaceutical cluster specializes in controlled-release polymer engineering for IBS-C applications.
United Kingdom
NHS trust centralized purchasing agreements standardize osmotic laxative protocols for opioid-induced constipation in palliative care. Falsified Medicines Directive serialization mandates force ERP upgrades among mid-tier manufacturers. Greater London anchors distribution architecture for pharmacy-integrated digital channels.
Italy
Specialist gastroenterology centers in Lombardy and Emilia-Romagna drive adoption of next-generation macrogol formulations for chronic idiopathic constipation. Independent pharmacy franchise networks negotiate collective volume terms against cooperative buying pressure. The Milan-Turin corridor concentrates clinical trial infrastructure for EMA real-world evidence generation.
Spain
Homecare nursing services in Madrid and Barcelona specify liquid macrogol formats for dysphagia-prevalent aging populations. Iberian pharmacy cooperative consolidation leaves three buyers controlling majority shelf placement decisions. The Barcelona pharmaceutical hub specializes in flexible-dose powder sachet manufacturing for travel and intermittent use segments.
Europe Laxative Market Competitive Landscape
German producers anchor one tier; French and British specialists hold differentiated positions through pharmacy-centric distribution and clinician endorsement programs. The vendor base stratifies across three tiers: diversified pharmaceutical conglomerates with consumer health divisions, mid-cap regional formulators with EMA-preferred chronic-use profiles, and niche natural health players competing on fiber supplement positioning. Consolidation pressure intensifies as serialization compliance costs and pharmacovigilance staffing requirements disadvantage sub-scale operators. Dominant competitive moves include portfolio diversification into combination digestive health products and strategic partnerships with centralized pharmacy buying cooperatives.
Within the diversified pharmaceutical tier, Bayer AG and Sanofi S.A. exemplify archetype positioning through consumer health infrastructure and pharmacy channel anchoring. GlaxoSmithKline plc occupies a position emphasizing differentiated formulation science in fiber supplement categories. These three entities represent contrasting strategic postures: German-headquartered conglomerate diversification, French S.A. structure pharmacy integration, and British plc specialty focus on chronic condition management.
| Leading Market Players |
|---|
| Bayer AG |
| GlaxoSmithKline plc |
| Sanofi S.A. |
| AstraZeneca |
| Teva Pharmaceutical Industries Ltd. |
| Novartis AG |
| Boehringer Ingelheim GmbH |
| Takeda Pharmaceutical Company Limited |
| F. Hoffmann-La Roche Ltd. |
| Others |
Supply & Pricing Matrix
Polyethylene glycol spot prices on the Rotterdam exchange cascade through European laxative manufacturing into three distinct pricing tiers serving institutional buyers, retail pharmacies, and direct-to-consumer channels. Raw material volatility compresses margins for macrogol-dependent osmotic formulations while REACH-compliant excipient sourcing adds certification premiums that concentrate pricing power among integrated German and French producers.
Pricing Analysis
Retailer markup layers separate pharmacy-dispensed macrogol solutions from supermarket fiber supplements and health store probiotic alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects EMA chronic-use certification status, BfArM inspection history, and volume commitment scale. Pricing pressure stems from Indian and Chinese API freight cost volatility exposing European formulators to margin compression. Institutional procurement teams at German Klinikum networks exhibit lowest price sensitivity due to protocol standardization mandates, while independent Spanish pharmacies face highest sensitivity from cooperative buying consolidation.
Supply Chain Analysis
Regional distribution centers in the Rhine-Main corridor and Lyon pharmaceutical cluster anchor hub-and-spoke patterns serving German, French, and Benelux markets. API manufacturing concentrates in India and China for bisacodyl and senna glycosides, with polymer engineering centered in Germany and France. Raw material dependencies include macrogol polymers, electrolyte balancing agents, and film-coating excipients. Single-source vulnerability from Asian contract manufacturers exposes batch release timelines to customs delays. Distribution runs through pharmacy-affiliated wholesalers in Western Europe and cooperative buying networks in Iberia and Italy.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe Laxative Market functions as a regulatory compounder where EMA pharmacovigilance requirements for OTC reclassification continuously elevate compliance barriers that favor scaled incumbents with dedicated safety science infrastructure.
For Market Incumbents: Deploy pharmacovigilance signal detection capabilities as a competitive moat. Consolidate manufacturing footprint in BfArM-preferred Rhine-Main and Lyon clusters to streamline inspection schedules. Acquire mid-tier formulators lacking EMA real-world evidence generation capacity before ANSM surveillance mandates tighten. Channel control through centralized pharmacy cooperatives in Spain and Italy defends shelf placement against fiber supplement substitutes. For New Entrants and Emerging Players: Underserved dysphagia-prevalent homecare segments in Belgium and Spain offer white-space entry through flexible-dose liquid macrogol formats. Eastern European pharmacy chain consolidation in Poland and Romania presents volume growth through clinician education programs bypassing cooperative buying gatekeepers. Target gastroenterology clinic networks in Lombardy and Emilia-Romagna with controlled-release polymer engineering for IBS-C applications. Go-to-market angle emphasizes EMA-preferred chronic-use status against commodity stimulant laxatives. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap formulators possessing EMA-compliant chronic-use portfolios and underutilized capacity in Central European jurisdictions. Long-term viability hinges on serialization compliance infrastructure and REACH-certified excipient sourcing relationships. Acquisition target archetype: regional specialists with BfArM inspection history and pharmacy cooperative contracts in Iberia or Italy. Signal to watch: ANSM adverse event reporting thresholds for bisacodyl reclassifications that would trigger portfolio rationalization among sub-scale competitors.| Strategic Initiative | Industry Significance |
|---|---|
| EMA Real-World Evidence Generation | Post-marketing surveillance capabilities satisfy ANSM and BfArM OTC reclassification pathways. |
| Pharmacy Cooperative Partnership | Centralized buying agreements in Spain and Italy secure shelf placement against wholesale displacement. |
| Controlled-Release Polymer Engineering | German and French gastroenterology practices adopt next-generation macrogol for IBS-C protocols. |
| REACH-Compliant Excipient Sourcing | ECHA-standardized polymer supply chains reduce batch variability and accelerate release timelines. |
| Homecare Liquid Format Expansion | Spanish and Belgian nursing services specify flexible-dose solutions for dysphagia management. |
Research Methodology
Bottom-up end-user modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with regulatory affairs leads at EMA-notified bodies, pharmacy procurement managers at German Apotheken and French officines, formulary directors at NHS trusts, and gastroenterology clinic administrators in Lombardy and Emilia-Romagna combined with secondary validation. Secondary sources include EMA submission databases, ANSM pharmacovigilance bulletins, BfArM inspection reports, ClinicalTrials.gov entries for macrogol formulations, and pharmacy cooperative procurement disclosures. Triangulation between demand-side protocol adoption and supply-side manufacturing capacity produces volume estimates.
Input-output matrix framing connects macrogol polymer consumption to finished laxative production across osmotic, stimulant, stool softener, and fiber supplement categories. Segmentation dimensions span pharmacological mechanism, dosage form, care setting, and distribution channel. CAGRs derive from patient population projections, institutionalization rates, and policy-driven homecare shifts. Industry-specific forecast inputs include EMA OTC reclassification timelines and REACH enforcement harmonization across member states.
Inputs from EMA and national regulatory databases were available through the study window; gaps in real-time pharmacy inventory data introduce uncertainty bands around channel share estimates. Forecasts reflect documented assumptions regarding geriatric institutionalization trajectories and opioid prescribing patterns. Adverse event reporting threshold changes or API supply disruptions could materially revise projections. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Lithuania Pharmaceutical Market
Pharmaceuticals
Belgium Pharmaceutical Market
Pharmaceuticals
Gastrointestinal Diseases Drug Development Market
Pharmaceuticals
Roflumilast API Market
Pharmaceuticals
Hydroxyzine Market
Pharmaceuticals
Global Non-Alcoholic Fatty Liver Disease (NAFLD) Drug Market
Pharmaceuticals
US Sex Reassignment Hormone Therapy Market
Pharmaceuticals
Europe Anesthesia Drugs Market
Pharmaceuticals
Global Androgen Deprivation Therapy Market
Pharmaceuticals
Antidepressant Drugs Market
Pharmaceuticals
Global Diphtheria Vaccine Market
Pharmaceuticals
Global Pharmaceuticals Market
Pharmaceuticals
Russia Diabetes Drugs Market
Pharmaceuticals
Global Immune Checkpoint Inhibitors Market
Pharmaceuticals
Oral Anticoagulant Market
Pharmaceuticals
Global Hepatitis B Vaccines Market