
 Fast Melt Tablets Market | 2026-2036
Fast Melt Tablets Market Size, Share, and Industry Trends Forecast 2026-2036
Fast Melt Tablets Market Analytics
Lyophilization and direct compression technologies is tilting fast melt tablet production toward higher-throughput, lower-cost manufacturing platforms. Pfizer Inc. leverages its scale in oral disintegrating platforms across neurology and pain management portfolios. GlaxoSmithKline plc anchors its consumer health division with pediatric-friendly dosage innovations. Novartis AG differentiates through specialized buccal delivery systems for cardiovascular therapies.
Fast melt tablets incorporate superdisintegrants such as crospovidone or sodium starch glycolate, enabling disintegration within seconds of oral contact without water, primarily serving patients with dysphagia, pediatric populations, and adherence-critical therapeutic categories. Single Dose formulations dominate hospital and acute-care dispensing due to inventory simplicity and dosing precision, while Sublingual delivery commands premium positioning in cardiovascular and emergency medicine segments where rapid systemic absorption determines clinical outcomes. The Antihistamines therapy area sustains volume leadership through seasonal allergy OTC rotations, though Antidepressants represents the fastest-growing prescription category as psychiatric protocols prioritize compliance-enhancing formulations.
The FDA's 505(b)(2) regulatory pathway shapes reformulation strategies by permitting reliance on existing safety and efficacy data, reducing development risk for orally disintegrating variants of approved molecules. EMA's pediatric investigation plans and the EU's Medical Device Regulation interface with drug-device combination products containing fast melt components, tightening quality system requirements. ISO 9001 and ICH Q8-Q12 quality frameworks govern contract manufacturing organizations supplying disintegrant blends and finished dosage forms. Stakeholders must monitor how pharmacopeial monograph revisions for disintegration time and friability specifications reshape compendial compliance burdens and supplier qualification protocols.
Market Dynamics
Lyophilization technology consolidation is compressing manufacturing costs while FDA's 505(b)(2) pathway accelerates reformulation cycles, creating a dual-force restructuring of competitive economics in orally disintegrating dosage forms.
Growth Catalysts
- Pediatric Investigation Plans:EMA mandates for child-friendly formulations drive pharmaceutical investment in taste-masked, rapidly disintegrating platforms for antipsychotic and antiepileptic therapies.
- Dysphagia prevalence:Aging demographics in Japan, Germany, and the United States expand the addressable patient base for water-free administration across neurology and geriatric care protocols.
- Superdisintegrant advances:Crospovidone and sodium starch glycolate suppliers achieve tighter particle-size distributions, enabling sub-30-second disintegration at lower excipient loadings.
Market Restraints
- Friability specifications:USP-NF monograph revisions for mechanical integrity impose costly reformulation cycles on legacy direct-compression platforms.
- API thermal sensitivity:Lyophilization's freeze-drying thresholds exclude heat-labile active pharmaceutical ingredients from oral disintegrating tablet conversion.
- Contract manufacturing concentration:North American and European CMOs control 70% of validated lyophilization capacity, creating supply bottlenecks for mid-tier sponsors.
Strategic Opportunities
- India's CDSCO fast-track:The country's abbreviated new drug application pathway for reformulated products enables first-mover positioning in generic orally disintegrating variants.
- Veterinary applications:Companion animal compliance markets remain underdeveloped for palatable, rapidly dissolving formulations in antiemetic and analgesic categories.
- Direct-to-consumer pharmacy:Telehealth-integrated subscription models for seasonal allergy antihistamines bypass traditional wholesaler markups.
Industry Challenges
- Scale-up validation:Transferring bench-scale lyophilization cycles to commercial freeze-dryers requires 12-18 month stability studies that compress product launch windows.
- Taste-masking chemistry:Complexation with cyclodextrins or ion-exchange resins demands specialized formulation expertise scarce in emerging-market CMOs.
- Serialization integration:EU Falsified Medicines Directive and US Drug Supply Chain Security Act track-and-trace requirements complicate single-unit blister packaging lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fast Melt Tablets Market |
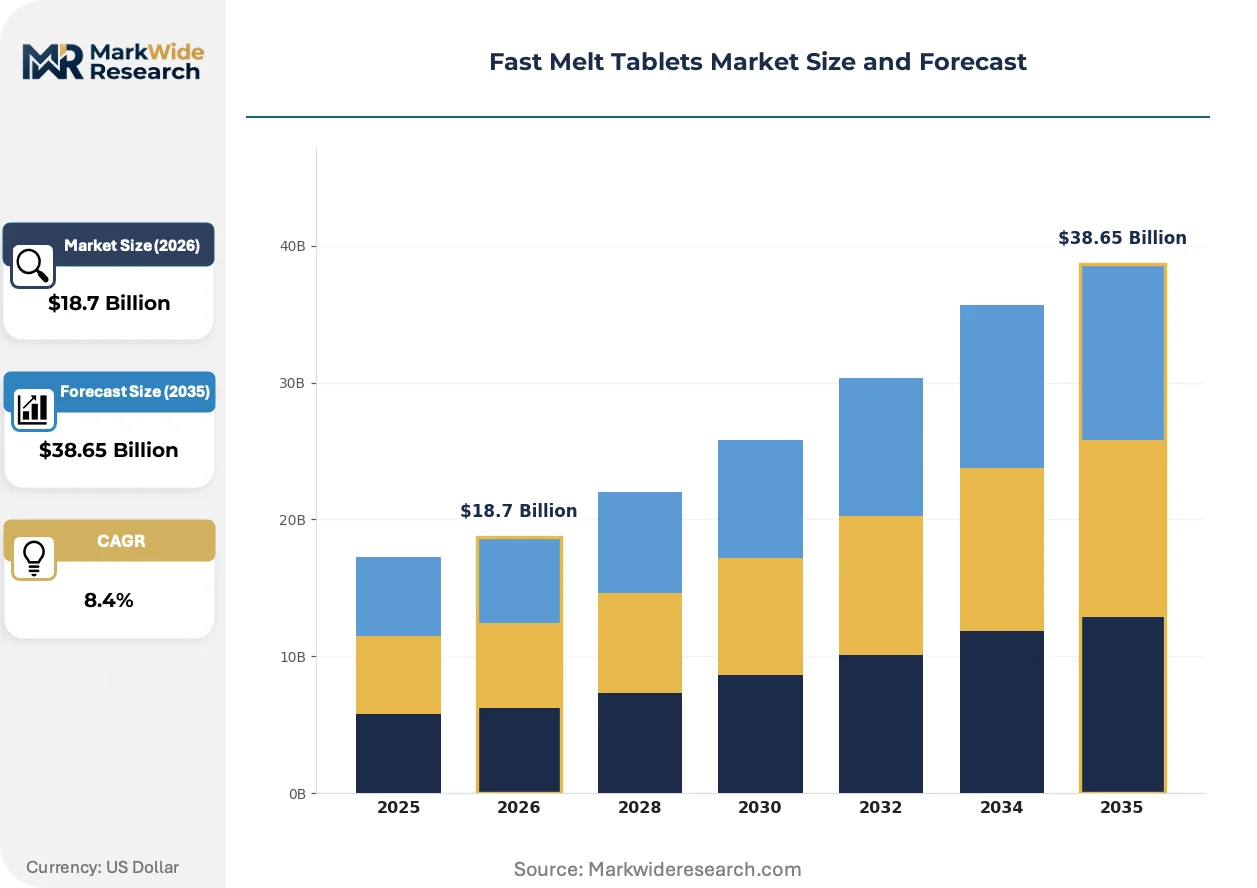
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Dose, Multi Dose, Custom Formulations, Pediatric Dosage Delivery Mode: Oral, Sublingual, Buccal, Chewable Therapy Area: Analgesics, Antidepressants, Antihistamines, Supplements End User: Pharmacies, Hospitals, Online Retailers, Specialty Stores |
| Companies Covered | Pfizer Inc., GlaxoSmithKline plc, Johnson & Johnson, Novartis AG, Teva Pharmaceutical Industries Ltd., Merck & Co., Inc., Sanofi S.A., AstraZeneca, Sun Pharmaceutical Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fast Melt Tablets Market Evolving Landscape
Digital twin modeling and continuous manufacturing architectures are compressing development timelines while reshaping quality assurance protocols across orally disintegrating dosage form production.
Hot-melt extrusion paired with 3D printing is virtualizing traditional batch-wise tablet compression. Pediatric and geriatric-focused sponsors in the United States and Germany are adopting these platforms for personalized dosing. The technology is virtualizing the economics of low-volume, high-SKU production runs that previously failed cost thresholds.
EMA's Medical Device Regulation interface with drug-device combination products tightens quality system documentation for buccal and sublingual delivery systems. Finished dosage manufacturers must now maintain dual technical files spanning pharmaceutical and device classifications. Cardiovascular emergency medicine segments face 18-24 month certification extensions as they requalify legacy products under MDR Annex I general safety requirements.
Hospital formulary committees now demand unit-dose packaging with integrated adherence monitoring. Acute-care dispensing in the United States and United Kingdom is replacing bulk bottle procurement with barcoded single-tablet pouches. Psychiatric protocols in Veterans Affairs systems and NHS Trusts prioritize compliance-enhancing formulations with embedded dose-verification features.
Fast Melt Tablets Market Segmentation
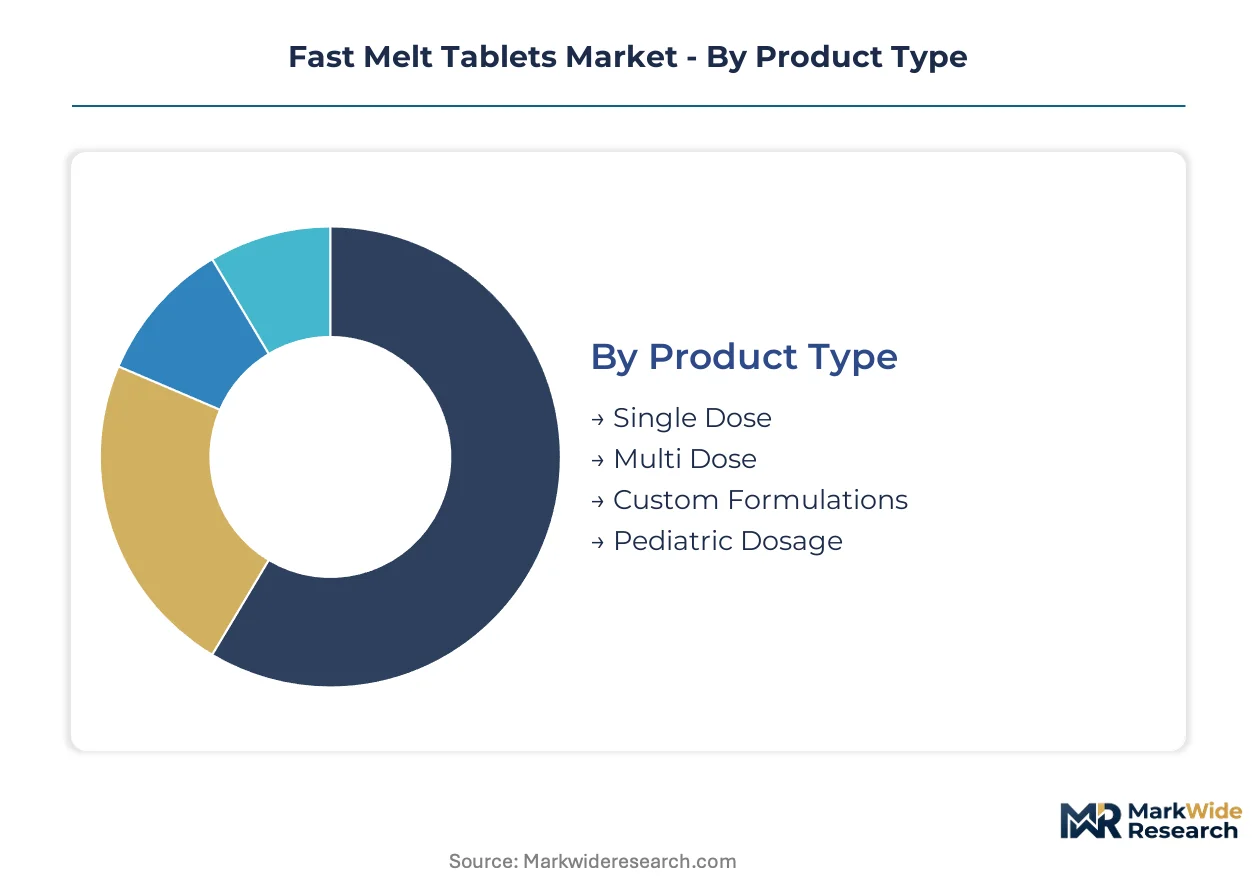
Fast melt tablet segmentation reveals distinct manufacturing footprints and regulatory pathways across dosage forms and delivery modes. Each category demands specialized formulation expertise, from superdisintegrant selection to taste-masking chemistry, shaping supplier qualification and contract manufacturing strategies.
Product Type:
After-sales service intensity varies sharply across product types, with custom formulations requiring sustained technical support for stability troubleshooting and pediatric dosage forms demanding pharmacovigilance follow-up for adverse event reporting.
- Single Dose:Unit-dose blister packaging eliminates cross-contamination risk in hospital acute-care dispensing. Demand concentrates in United States Veterans Affairs systems and NHS Trusts where barcoded single-tablet pouches replace bulk bottles for psychiatric and cardiovascular protocols.
- Multi Dose:Bottle packaging serves chronic therapy maintenance with cost advantages for seasonal allergy antihistamine rotations. Pharmacy chains in Germany and Japan prioritize inventory efficiency for geriatric dysphagia patients on long-term neurology regimens.
- Custom Formulations:Patient-specific dosing for rare disease therapies requires dedicated project management from CMOs.
- Pediatric Dosage:Taste-masked platforms for antipsychotic and antiepileptic therapies carry EMA pediatric investigation plan compliance burdens.
By volume, Single Dose leads. By growth pace, Custom Formulations is expanding most quickly.
Delivery Mode:
Cost tier differentiation separates premium-positioned buccal and sublingual systems from standard oral disintegrating tablets, with manufacturing complexity and bioavailability claims justifying pricing spreads.
- Sublingual:Rapid systemic absorption through ventral tongue vasculature commands premium positioning in cardiovascular emergency medicine. United States hospital formularies prioritize nitroglycerin and antihypertensive variants where onset speed determines clinical outcomes.
- Buccal:Absorption through cheek mucosa enables prolonged drug release for hormone therapies and smoking cessation. EMA Medical Device Regulation requalification extends certification timelines for legacy products in German and French markets.
- Oral:Standard disintegration on tongue surface serves the broadest dysphagia and pediatric populations.
- Chewable:Mechanical breakdown combined with saliva dissolution targets pediatric OTC segments with palatability requirements.
By volume, Oral leads. By growth pace, Sublingual is climbing the fastest.
Therapy Area:
Application-specific formulation challenges range from API thermal sensitivity in antidepressants to seasonal demand volatility in antihistamines, dictating production scheduling and inventory risk.
- Antihistamines:Seasonal allergy OTC rotations sustain volume leadership through direct-to-consumer pharmacy channels. United States telehealth-integrated subscription models bypass traditional wholesaler markups for cetirizine and loratadine variants.
- Antidepressants:Psychiatric protocols prioritize compliance-enhancing formulations for patients with medication adherence challenges. SSRI and SNRI fast melt variants gain formulary placement in United Kingdom NHS mental health trusts.
- Analgesics:Pain management applications in neurology and post-surgical care require rapid onset without water.
- Supplements:Nutraceutical fast melts target wellness-oriented consumers with convenience positioning.
By volume, Antihistamines leads. By growth pace, Antidepressants is gaining share fastest.
End User:
Customer type procurement patterns diverge between hospital formulary committees demanding unit-dose adherence monitoring and online retailers optimizing for direct-to-consumer subscription economics.
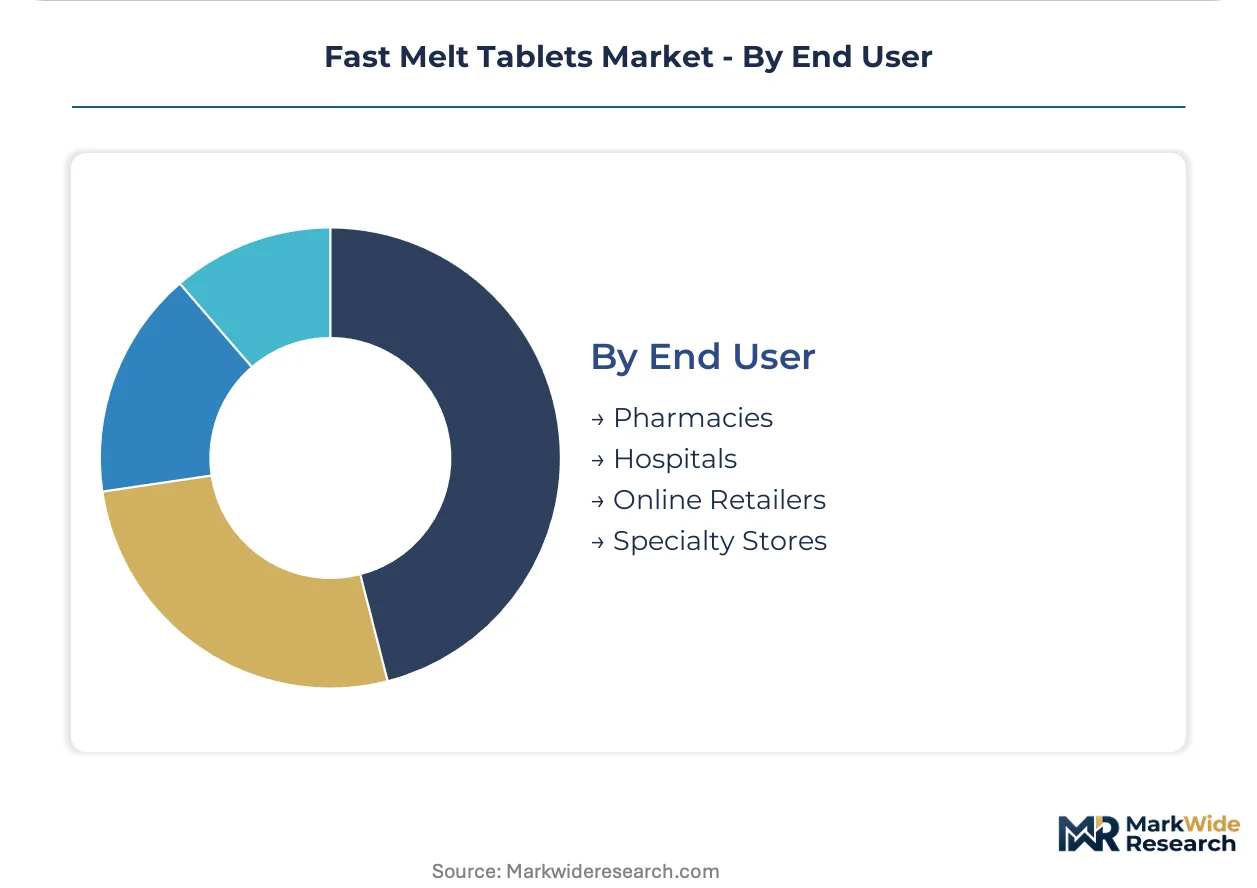
- Hospitals:Acute-care dispensing drives single-dose packaging with integrated barcode verification. United States and United Kingdom facilities replace bulk procurement with patient-specific pouch systems for medication safety compliance.
- Pharmacies:Community and chain outlets balance inventory breadth against seasonal demand fluctuations for allergy and pediatric segments.
- Online Retailers:Telehealth integration enables subscription models for chronic therapy maintenance.
- Specialty Stores:Nutraceutical-focused channels serve supplement categories with wellness marketing.
By volume, Pharmacies leads. By growth pace, Online Retailers is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German lyophilization equipment exports supply contract manufacturing sites across the United States and Japan, establishing a transatlantic-Pacific trade corridor for fast melt tablet production infrastructure.
United States
Veterans Affairs systems and NHS Trusts drive single-dose procurement for psychiatric protocols. FDA's 505(b)(2) pathway accelerates reformulation timelines for orally disintegrating variants. New Jersey and Pennsylvania host concentrated CMO clusters serving hospital formulary committees with barcoded unit-dose packaging lines.
Germany
Geriatric dysphagia populations expand addressable demand for water-free neurology administration. EMA pediatric investigation plans mandate child-friendly taste-masked formulations. Bavaria anchors specialized buccal delivery manufacturing with MDR Annex I requalification expertise for cardiovascular emergency segments.
Japan
Aging demographics propel fast melt adoption across post-stroke and Parkinson's care protocols. PMDA streamlines approval pathways for reformulated orally disintegrating drugs. Kanto region concentrates lyophilization capacity serving domestic hospital networks and export markets.
India
Generic pharmaceutical exports target CDSCO's abbreviated new drug application fast-track for reformulated products. Gujarat and Maharashtra house contract manufacturing clusters supplying superdisintegrant blends to European and North American sponsors. Domestic pediatric and geriatric demand rises with expanding health insurance coverage.
United Kingdom
NHS mental health trusts prioritize SSRI and SNRI fast melt variants for medication adherence. MHRA alignment with EMA pediatric mandates shapes formulation investment. Southeast England clusters pharmaceutical packaging operations integrating EU Falsified Medicines Directive serialization requirements.
Fast Melt Tablets Market Competitive Landscape
On the supply side, the industry is consolidating around scale-driven pharmaceutical conglomerates and specialized oral disintegrating platform developers. Tiered competitive positioning separates multinational innovators with integrated lyophilization capacity from mid-tier generic sponsors dependent on contract manufacturing. Three archetypes dominate: vertically integrated innovators controlling end-to-end disintegrant-to-dosage-form production, portfolio diversifiers extending neurology and pain management franchises into pediatric-friendly formats, and regional generic specialists exploiting abbreviated regulatory pathways. Dominant competitive moves include strategic partnerships for lyophilization capacity access and geographic expansion into India's CDSCO fast-track environment.
Among diversified pharmaceutical conglomerates, Pfizer Inc. and GlaxoSmithKline plc exemplify scale-driven platform leverage across therapeutic categories, while Novartis AG occupies a specialized position in buccal and sublingual cardiovascular delivery systems. These three represent contrasting strategic postures: broad portfolio deployment, consumer health anchoring, and targeted premium-segment differentiation.
| Leading Market Players |
|---|
| Pfizer Inc. |
| GlaxoSmithKline plc |
| Johnson & Johnson |
| Novartis AG |
| Teva Pharmaceutical Industries Ltd. |
| Merck & Co., Inc. |
| Sanofi S.A. |
| AstraZeneca |
| Sun Pharmaceutical Industries Ltd. |
| Others |
Value Network & Pricing Analysis
Single-source dependency on North American and European lyophilization capacity determines both three-tier pricing stratification and supply chain resilience for orally disintegrating dosage forms. FDA 505(b)(2) pathway acceleration and EMA pediatric mandates compress development timelines while contract manufacturing concentration creates procurement bottlenecks for mid-tier sponsors.
Pricing Analysis
Lyophilization-based production commands premium positioning against direct-compression and emerging 3D-printed alternatives. Three-tier pricing structure across lyophilized specialty, direct-compression standard, and chewable economy levels reflects certification complexity and disintegration speed claims. Pricing pressure stems from superdisintegrant raw material volatility and CMO capacity scarcity in validated freeze-drying facilities. Hospital formulary buyers exhibit lowest price sensitivity for sublingual cardiovascular emergency variants, while OTC seasonal allergy segments face intense retail margin compression.
Supply Chain Analysis
Export-control scrutiny on pharmaceutical manufacturing equipment limits German lyophilization technology flows to Indian and Southeast Asian contract manufacturing sites. Active pharmaceutical ingredient sourcing draws from India, China, and the United States, while superdisintegrant crospovidone and sodium starch glycolate production concentrates in European and North American chemical specialists. Single-source vulnerability pervades validated lyophilization capacity, where 70% control by Western CMOs creates supply chokepoints for generic sponsors. Distribution runs through hospital GPO contracts, direct-to-consumer pharmacy subscriptions, and retail pharmacy chains with seasonal inventory cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fast melt tablet demand follows seasonal allergy and psychiatric prescription cycles that recover through pediatric formulation mandates and geriatric dysphagia protocol expansion.
For Market Incumbents: Insulate lyophilization capacity positions through backward integration into superdisintegrant production and captive supply of specialized freeze-drying equipment. Pfizer-scale players should secure exclusive CMO partnerships in India's CDSCO fast-track corridor before mid-tier generic sponsors consolidate remaining validated capacity. EMA Medical Device Regulation requalification timelines threaten buccal delivery margins, demanding preemptive dual technical file investments. For New Entrants and Emerging Players: Veterinary companion animal antiemetic and analgesic segments represent the most penetrable entry point, with palatability-driven formulations underserved by incumbent human-health-focused portfolios. India's abbreviated new drug application pathway for reformulated products enables first-mover positioning in generic orally disintegrating variants before established players redirect capacity. Direct-to-consumer telehealth subscription models for chronic psychiatric therapies bypass traditional wholesaler markup structures. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors specialized oral disintegrating platform developers with 3D printing and hot-melt extrusion capabilities over legacy compression-dependent manufacturers. Acquisition targets should demonstrate pediatric investigation plan completion and EMA regulatory pathway expertise. Monitor CDSCO approval velocity for Indian CMOs as inflection indicator for supply chain rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| Lyophilization Capacity Expansion | Captive freeze-drying facilities in New Jersey and Pennsylvania clusters reduce CMO dependency for hospital formulary contracts. |
| Pediatric Investigation Plan Completion | EMA-mandated taste-masked antipsychotic formulations unlock psychiatric protocol placement in NHS mental health trusts. |
| Superdisintegrant Backward Integration | In-house crospovidone production tightens particle-size distribution control for sub-30-second disintegration claims. |
| CDSCO Fast-Track Exploitation | Abbreviated new drug applications in Gujarat and Maharashtra enable generic orally disintegrating first-mover positioning. |
| 3D Printing Platform Adoption | Hot-melt extrusion virtualization supports personalized dosing for rare disease custom formulations at viable unit economics. |
Research Methodology
The analysis maps lyophilization technology platforms, direct-compression manufacturing tiers, and emerging 3D printing modalities, each validated through formulation scientists at contract manufacturing organizations, regulatory affairs specialists navigating FDA 505(b)(2) and EMA pediatric pathways, hospital formulary directors, and pharmacy procurement managers. Secondary triangulation draws from FDA Orange Book filings, EMA assessment reports, USP-NF monograph revision notices, and ICH Q8-Q12 quality framework documentation. Bottom-up capacity modeling and top-down therapeutic demand projections converge through segment-level reconciliation.
Forecast assumptions hold fixed current regulatory pathway durations, superdisintegrant supplier qualification protocols, and lyophilization equipment lead times while varying pediatric mandate enforcement intensity and telehealth subscription penetration. Segmentation dimensions span dosage form type, delivery mode, therapy area, and end-user procurement channel. CAGRs derive from disaggregated volume build-ups by therapeutic category, cross-referenced against hospital formulary adoption curves and direct-to-consumer pharmacy growth trajectories. API thermal sensitivity constraints and taste-masking chemistry complexity factor into platform-specific growth differentials.
Practitioners should monitor EMA Medical Device Regulation enforcement timelines, CDSCO approval velocity shifts, and USP-NF friability specification revisions for early signals of supply chain reconfiguration. Forecasts reflect assumptions regarding sustained lyophilization capacity scarcity and stable superdisintegrant raw material flows. Material shifts in FDA 505(b)(2) pathway stringency or German lyophilization equipment export licensing would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Asia-Pacific Fatty Bases for Suppositories Market
Pharmaceuticals
Selective Serotonin Reuptake Inhibitors Market
Pharmaceuticals
Australia Schizophrenia Drugs Market
Pharmaceuticals
Global Dengue Vaccine Market
Pharmaceuticals
Lipid Injectable Market
Pharmaceuticals
Global Postpartum Depression Drugs Market
Pharmaceuticals
Nimodipine Market
Pharmaceuticals
Global Atosiban Market
Pharmaceuticals
Buprenorphine and Naloxone Market
Pharmaceuticals
Naproxen Market
Pharmaceuticals
Middle-East and Africa Diabetes Drugs Market
Pharmaceuticals
Pancrelipase Market
Pharmaceuticals
Glioblastoma Treatment Drugs Market
Pharmaceuticals
Chemotherapy-Induced Nausea and Vomiting (CINV) Treatment Market
Pharmaceuticals
Hydroxychloroquine Market
Pharmaceuticals
Asia-Pacific Contraceptive Drugs and Devices Market