
 Bacterial Vaginosis Treatment Market | 2026-2036
Bacterial Vaginosis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Bacterial Vaginosis Treatment Market Outlook
EU MDR requirements for antimicrobial susceptibility labeling is restructuring how manufacturers validate clinical endpoints for vaginal therapeutics. Pfizer Inc leverages its established infectious disease infrastructure to sustain commercial reach across European hospital formularies. Bayer AG anchors its position through gynecological health franchises with deep pharmacy channel relationships. Teva Pharmaceutical Industries Ltd competes on generic metronidazole and clindamycin portfolios, extending cost-accessible options into retail networks.
Bacterial vaginosis treatment encompasses pharmaceutical and biological interventions targeting Gardnerella vaginalis and polymicrobial anaerobic overgrowth, with metronidazole, clindamycin, and tinidazole constituting first-line antibiotic regimens administered orally or intravaginally. These therapies restore acidic vaginal pH and lactobacillus dominance, preventing obstetric complications and HIV susceptibility associated with persistent dysbiosis. Antibiotics occupy the dominant revenue position due to established efficacy protocols and broad prescriber familiarity, while Probiotics represents the fastest-expanding category as live biotherapeutic products advance through regulatory pipelines. Home Care settings capture growing volume as self-administered intravaginal gels and tablets reduce clinic dependency for recurrent cases.
FDA, EMA, and WHO prequalification standards govern clinical trial design, manufacturing quality, and antimicrobial stewardship labeling for vaginal infection therapies across developed and emerging markets. These frameworks elevate barriers for novel microbiome modulators while accelerating biosimilar scrutiny of established antibiotic formulations. Stakeholders must monitor evolving pharmacovigilance requirements for live biotherapeutic products and antimicrobial resistance surveillance mandates that will reshape portfolio prioritization and geographic market entry sequencing.
Market Dynamics
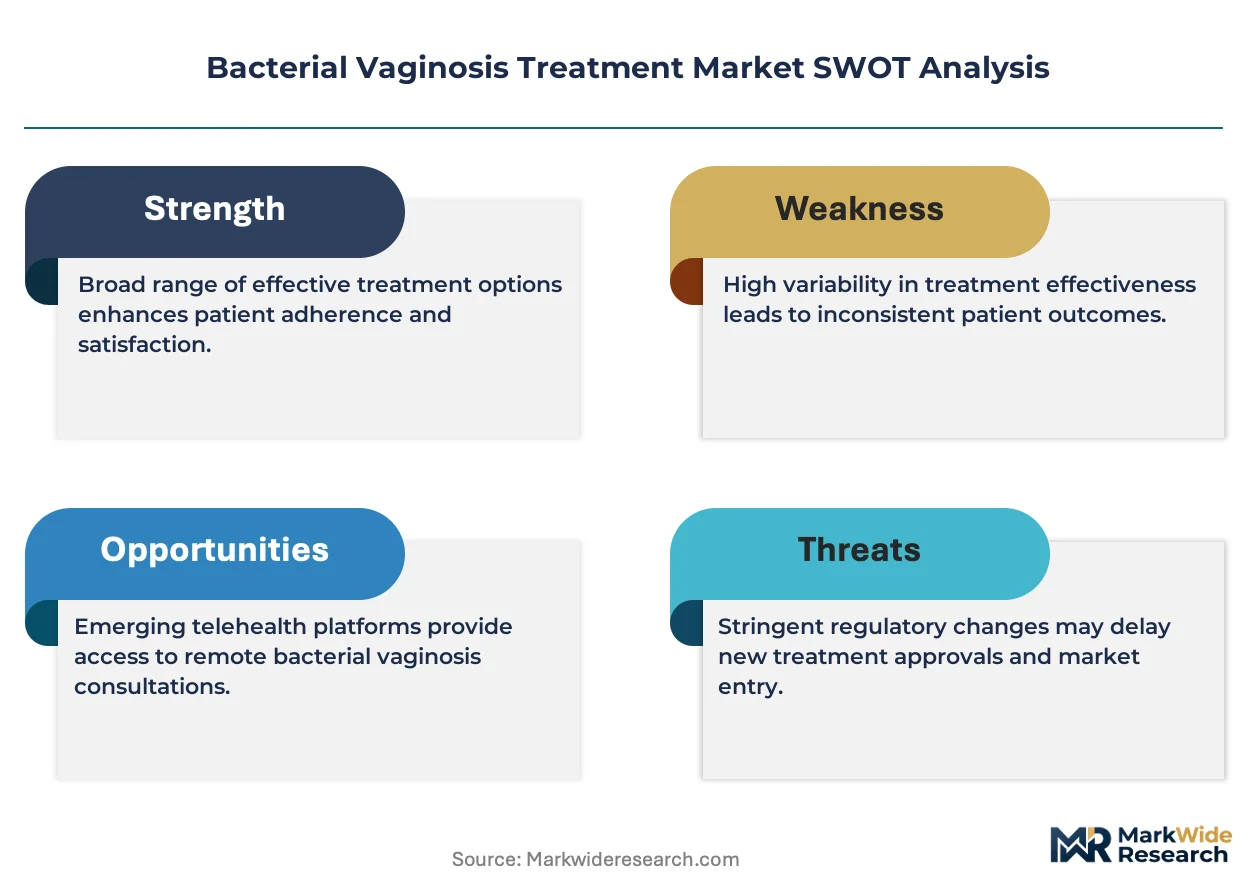
Microbiome-modulating therapies are absorbing capital and regulatory attention, compressing development timelines for antibiotic alternatives while FDA and EMA frameworks diverge on live biotherapeutic product approval pathways.
Growth Catalysts
- Point-of-care testing expansion:Gynecological practices in the United States deploy rapid molecular diagnostics, reducing time-to-treatment for recurrent infections.
- EMA MDR antimicrobial labeling:European manufacturers accelerate clinical endpoint validation for vaginal therapeutics, creating first-mover advantages in biosimilar scrutiny.
- Recurrent infection protocols:Commercial payer coverage expansion drives prescription therapy access for patients with multiple episodes annually.
Market Restraints
- Antimicrobial resistance surveillance:WHO prequalification standards mandate enhanced pharmacovigilance, elevating compliance costs for generic metronidazole formulations.
- Active pharmaceutical ingredient concentration:Clindamycin and tinidazole precursor supply chains cluster in specific manufacturing regions, exposing formulation continuity risks.
- Live biotherapeutic stability:Cold-chain requirements for probiotic-based treatments limit distribution reach into tropical climates without infrastructure investment.
Strategic Opportunities
- Home care self-administration:Intravaginal gel and tablet formats reduce clinic dependency, opening retail pharmacy channels for maintenance therapy regimens.
- FDA breakthrough therapy designation:Microbiome modulators targeting Gardnerella vaginalis biofilms receive accelerated review timelines, compressing competitive entry windows.
- Telehealth integration:Remote diagnosis platforms connect patients to prescription therapies without physical examination, expanding access in rural United States counties.
Industry Challenges
- Clinical trial recruitment:Vaginal microbiome studies require specialized investigator networks, constraining enrollment velocity for Phase III endpoints.
- Lactobacillus strain IP:Patent thickets around proprietary probiotic isolates complicate licensing negotiations for developers entering the live biotherapeutic segment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bacterial Vaginosis Treatment Market |
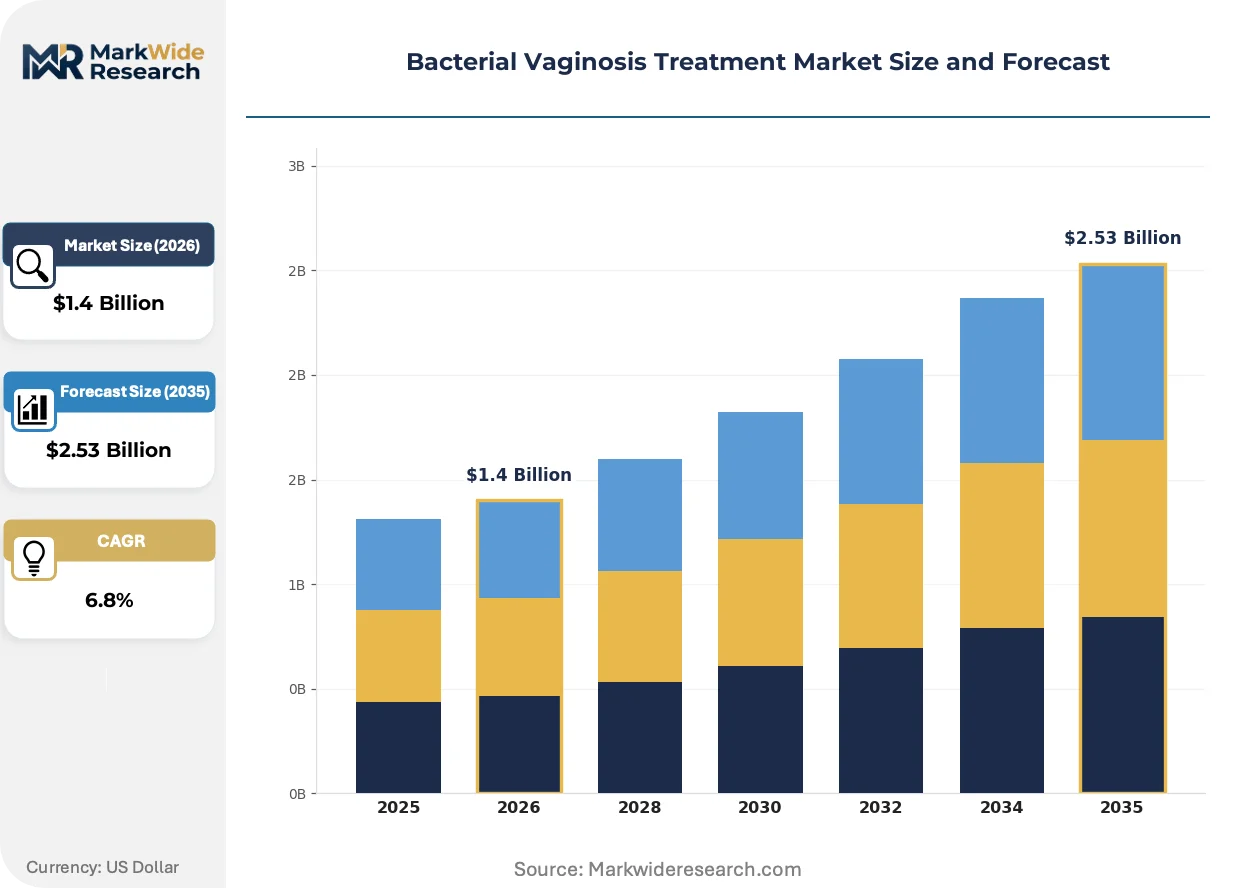
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Probiotics, Hormonal Therapies, Antifungal Agents End User: Hospitals, Clinics, Pharmacies, Home Care Form: Tablets, Creams, Gels, Solutions Distribution Channel: Online Pharmacy, Retail Pharmacy, Hospital Pharmacy, Others |
| Companies Covered | Pfizer Inc, Bayer AG, Novartis AG, AbbVie Inc, Merck & Co., Inc., Teva Pharmaceutical Industries Ltd, Sanofi, GlaxoSmithKline plc, Bausch Health Companies Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bacterial Vaginosis Treatment Market Strategic Shifts
Live biotherapeutic products are absorbing regulatory and commercial momentum, shifting competitive focus from antibiotic efficacy comparisons to microbiome restoration claims and maintenance dosing models.
Phage therapy directed at Gardnerella vaginalis biofilms is absorbing preclinical investment from microbiome-focused biotech firms, with early-stage candidates targeting persistent dysbiosis unresponsive to standard antibiotics. Academic medical centers in the United States and Germany sponsor investigator-initiated trials evaluating bacteriophage cocktails as adjunctive therapy. This modality is absorbing development resources that previously flowed into next-generation nitroimidazole derivatives, compressing the antibiotic innovation pipeline.
EU MDR requirements for antimicrobial susceptibility labeling are restructuring clinical endpoint validation for vaginal therapeutics, forcing manufacturers to generate resistance surveillance data as a condition of market authorization. EMA guidance on microbiome-modulating therapies demands longitudinal safety follow-up beyond traditional antibiotic approval timelines. European hospital formularies are responding by tightening formulary inclusion criteria for new entrants, favoring products with demonstrated resistance mitigation profiles.
Patients with recurrent bacterial vaginosis are compressing treatment-seeking intervals, demanding maintenance therapy options that extend beyond acute infection management. Retail pharmacies in the United States report rising inquiries for prescription probiotic co-therapies prescribed alongside standard antibiotics. This behavioral shift is most pronounced among commercially insured women aged 25-40, who prioritize recurrence prevention over single-episode cure rates.
Bacterial Vaginosis Treatment Market Segmentation
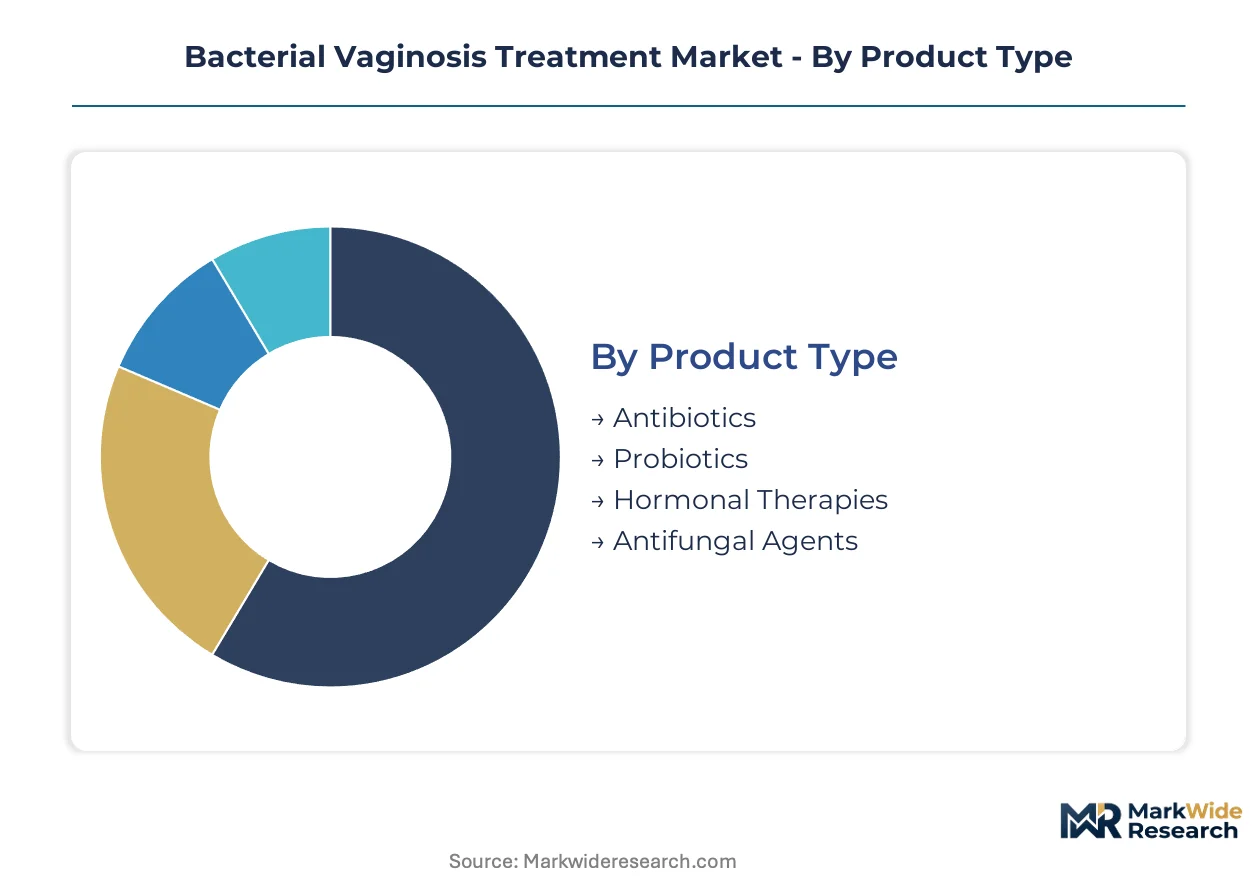
Treatment modality selection in bacterial vaginosis hinges on infection severity, recurrence history, and patient-administration preferences. Segmentation reveals where pharmaceutical investment concentrates versus where biological alternatives are gaining regulatory traction.
Product Type:
Supply concentration for active pharmaceutical ingredients clusters around established nitroimidazole and lincosamide production corridors, while live biotherapeutic manufacturing requires specialized fermentation capacity that remains geographically sparse.
- Antibiotics:Metronidazole, clindamycin, and tinidazole formulations dominate prescription volumes through oral and intravaginal routes. United States gynecological practices favor single-dose oral regimens for initial episodes, though intravaginal formulations capture maintenance protocols.
- Probiotics:Live biotherapeutic products deliver Lactobacillus strains to restore acidic vaginal pH and suppress Gardnerella vaginalis overgrowth. FDA breakthrough therapy designations for biofilm-targeting candidates are accelerating clinical timelines for developers with proprietary strain libraries.
- Hormonal Therapies:Estrogen-modulating approaches address atrophic vaginitis overlap presentations in perimenopausal patients.
- Antifungal Agents:Azole derivatives serve mixed-infection presentations where Candida co-pathogenesis complicates diagnosis.
Antibiotics absorb the bulk of installed capacity; probiotics are expanding most quickly.
End User:
Site-of-care economics vary sharply by reimbursement structure, with commercial payer coverage for recurrent protocols shifting volume toward outpatient settings.
- Hospitals:Emergency departments and obstetric units manage severe presentations and pregnancy-associated cases requiring parenteral therapy. EMA MDR antimicrobial labeling requirements are tightening formulary inclusion criteria for European hospital systems.
- Clinics:Gynecological and primary care practices deploy point-of-care molecular diagnostics to reduce time-to-treatment. Rapid nucleic acid amplification tests for Gardnerella vaginalis are compressing diagnostic windows in United States metropolitan markets.
- Pharmacies:Retail channels dispense generic metronidazole and clindamycin formulations with high prescriber familiarity.
- Home Care:Self-administered intravaginal gels and tablets reduce clinic dependency for patients with multiple annual episodes. Telehealth platforms in rural United States counties now enable remote prescription authorization for maintenance regimens.
Clinics command the largest patient throughput; home care is climbing the fastest as self-administration formats mature.
Form:
Manufacturing complexity scales with delivery system sophistication, with semi-solid formulations requiring specialized stability testing beyond standard tablet dissolution profiles.
- Tablets:Oral metronidazole and tinidazole offer systemic distribution for disseminated infection or patient preference. United States formularies prioritize single-dose 2g regimens for compliance optimization in mobile populations.
- Creams:Clindamycin phosphate creams provide localized anaerobic suppression with minimal systemic absorption. Patients with gastrointestinal intolerance to oral antibiotics drive demand in pharmacy channels.
- Gels:Intravaginal metronidazole gel delivers targeted pH restoration with reduced systemic exposure.
- Solutions:Rinse formulations serve adjunctive hygiene protocols alongside primary antibiotic therapy.
Tablets retain the largest manufacturing footprint; gels are gaining share fastest through retail pharmacy expansion.
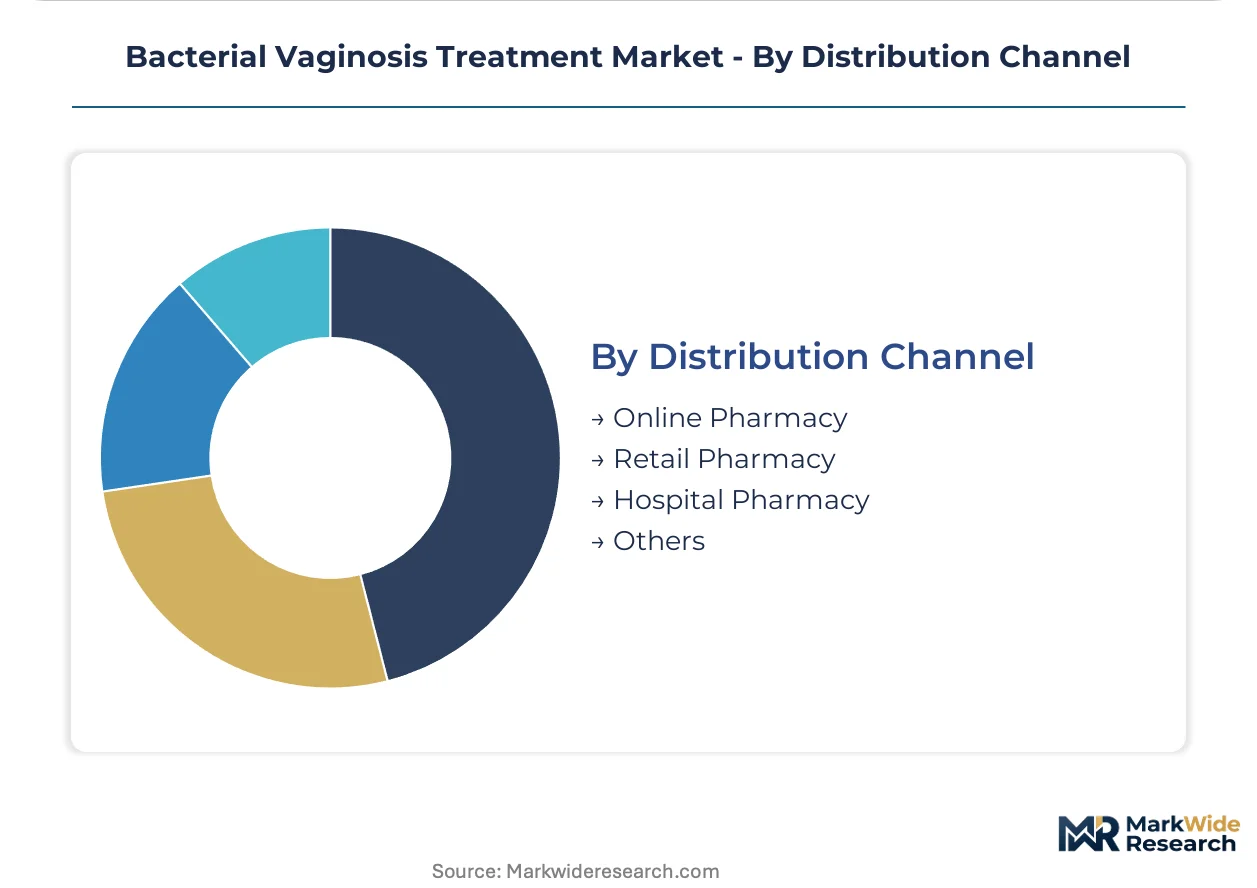
Distribution Channel:
Cold-chain requirements for live biotherapeutic products are segmenting logistics capabilities, with temperature-controlled networks concentrating in developed markets.
- Online Pharmacy:Digital platforms enable discreet procurement for recurrent infection maintenance therapies. United States telehealth-integrated pharmacies are capturing prescription volume from patients in pharmacy deserts.
- Retail Pharmacy:Chain and independent pharmacies anchor generic antibiotic accessibility with immediate fulfillment. Pharmacy benefit manager formulary tiers determine patient out-of-pocket exposure for branded alternatives.
- Hospital Pharmacy:Inpatient formularies stock parenteral formulations and combination therapies for severe presentations.
- Others:Specialty distributors serve clinical trial supply chains and direct-to-practice biotherapeutic delivery.
Retail pharmacy commands the deepest penetration; online pharmacy is expanding most quickly through telehealth integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's biotech corridor concentrates live biotherapeutic development for bacterial vaginosis, with Massachusetts General Hospital and Harvard-affiliated labs driving early-stage Gardnerella vaginalis research. This geographic pattern repeats across specific national markets where regulatory pathways and reimbursement structures determine commercial viability.
United States
Commercial payer coverage expansion for recurrent infection protocols drives prescription therapy access in metropolitan gynecological practices. FDA breakthrough therapy designations for microbiome modulators accelerate clinical timelines for biofilm-targeting candidates. Research Triangle Park in North Carolina hosts contract research organizations specializing in vaginal microbiome study design.
Germany
EMA MDR antimicrobial susceptibility labeling requirements restructure clinical endpoint validation for vaginal therapeutics entering European hospital formularies. German hospital systems tighten inclusion criteria to favor products with demonstrated resistance mitigation profiles. The Frankfurt-Rhine-Main corridor concentrates pharmaceutical distribution infrastructure for temperature-controlled biotherapeutic logistics.
United Kingdom
NHS England commissioning frameworks for sexual health services shape procurement patterns for point-of-care molecular diagnostics. MHRA post-Brexit regulatory autonomy creates divergence from EMA timelines for live biotherapeutic product approvals. London's Imperial College and University College Hospital networks anchor investigator-initiated trials for phage therapy adjuncts.
India
CDSCO streamlined approval pathways for generic metronidazole and clindamycin formulations support cost-accessible manufacturing for export markets. Domestic pharmacy retail expansion in tier-2 cities extends antibiotic availability beyond metropolitan centers. Hyderabad's active pharmaceutical ingredient cluster supplies nitroimidazole precursors to formulation facilities across South Asia.
Japan
PMDA consultation procedures for microbiome-modulating therapies demand extended safety follow-up beyond traditional antibiotic approval timelines. Aging demographic profiles elevate perimenopausal bacterial vaginosis presentations requiring hormonal co-therapy considerations. Osaka's pharmaceutical manufacturing belt specializes in intravaginal gel formulation technologies for regional distribution.
Bacterial Vaginosis Treatment Market Competitive Environment
The competitive structure tilts toward diversified pharmaceutical conglomerates with established infectious disease infrastructure. Market concentration reflects high regulatory barriers for novel microbiome modulators and the capital intensity of live biotherapeutic manufacturing. Two strategic archetypes dominate: legacy antibiotic manufacturers defending generic portfolios against biosimilar scrutiny, and biotechnology specialists pursuing FDA breakthrough designations for biofilm-disrupting candidates. Competitive moves center on portfolio diversification into maintenance therapy regimens and strategic partnerships with telehealth platforms for remote prescription authorization.
Among established pharmaceutical conglomerates, Pfizer Inc and Bayer AG exemplify divergent positioning archetypes. Pfizer leverages its infectious disease commercial infrastructure to sustain hospital formulary presence across European markets. Bayer anchors its position through gynecological health franchises with established pharmacy channel relationships. Teva Pharmaceutical Industries Ltd occupies a distinct tier, competing on cost-accessible generic metronidazole and clindamycin portfolios extended into retail networks. These three entities collectively illustrate how scale, therapeutic focus, and geographic footprint stratify competitive positioning without requiring identical strategic postures.
| Leading Market Players |
|---|
| Pfizer Inc |
| Bayer AG |
| Novartis AG |
| AbbVie Inc |
| Merck & Co., Inc. |
| Teva Pharmaceutical Industries Ltd |
| Sanofi |
| GlaxoSmithKline plc |
| Bausch Health Companies Inc |
| Others |
Value Chain & Pricing Dynamics
FDA antimicrobial stewardship labeling mandates gate qualified supply access and premium-tier pricing for microbiome-modulating therapies, compressing margins for generic antibiotic manufacturers while rewarding developers with validated resistance-mitigation profiles. Cold-chain infrastructure requirements for live biotherapeutic products segment distribution economics, concentrating premium pricing power among manufacturers with captive logistics networks in temperate climate zones.
Pricing Analysis
Outcome-based pricing anchors premium tiers for biofilm-targeting microbiome modulators with FDA breakthrough therapy designations, while generic metronidazole and clindamycin formulations compete on per-unit transactional models in retail pharmacy channels. Price differentiation separates resistance-validated biotherapeutics from commodity antibiotics, with certification tier and geographic delivery cost as secondary drivers. Cost compression in oral antibiotic generics intensifies due to WHO prequalification compliance burdens. Uninsured and underinsured patients exhibit highest price sensitivity, while commercially insured women aged 25-40 prioritize recurrence prevention over out-of-pocket exposure.
Supply Chain Analysis
Active pharmaceutical ingredient supply rests on manufacturing corridors in India, China, and the United States for nitroimidazole and lincosamide precursors. Raw material dependencies include clindamycin fermentation feedstocks, tinidazole chemical intermediates, and specialized Lactobacillus strain libraries for probiotic formulations. Single-source vulnerability concentrates around cold-chain logistics providers for temperature-sensitive biotherapeutics. Distribution runs through hospital formularies for parenteral therapies, retail pharmacy networks for oral generics, and specialty distributors for clinical trial supplies and direct-to-practice biotherapeutic delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bacterial vaginosis treatment market sits in a technology-transition phase where live biotherapeutic products displace legacy antibiotic regimens for recurrent infection management. Microbiome-modulating therapies with biofilm-disruption mechanisms are capturing development capital and regulatory priority, compressing competitive timelines for traditional antimicrobial developers.
For Market Incumbents: Deepen backward integration into Lactobacillus strain fermentation capacity to secure supply autonomy for live biotherapeutic pipelines. Incumbent antibiotic manufacturers must accelerate resistance surveillance data generation to defend formulary positions against EMA MDR antimicrobial labeling requirements. Generic portfolio defenders should invest in telehealth platform partnerships to capture remote prescription authorization volume shifting from clinic-based settings.
For New Entrants and Emerging Players: Telehealth-integrated pharmacy channels offer the most penetrable entry vector for maintenance therapy regimens targeting rural United States counties with limited gynecological practice density. New entrants should prioritize home care self-administration formats—intravaginal gels and tablets—to bypass hospital formulary gatekeeping. A direct-to-patient go-to-market angle through digital health platforms enables discreet procurement for recurrent infection populations.
For Investors and Strategic Acquirers: FDA breakthrough therapy designation awards for Gardnerella vaginalis biofilm candidates are the leading indicator that microbiome modulators will command premium valuation multiples over generic antibiotic assets. Long-term viability over the next decade hinges on proprietary strain IP and validated maintenance dosing models. Acquisition targets should display investigator-initiated trial sponsorships at academic medical centers and partnerships with contract research organizations specializing in vaginal microbiome study design.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Phase III enrollment for biofilm-targeting candidates accelerates FDA breakthrough pathway timelines. |
| Regulatory Approval Pathway | EMA MDR antimicrobial labeling compliance opens European hospital formulary access for resistance-validated products. |
| Manufacturing Scale-Up | Fermentation capacity expansion for proprietary Lactobacillus strains secures supply for maintenance therapy demand. |
| Pipeline Diversification | Phage therapy adjunct programs capture preclinical investment from microbiome-focused biotechnology firms. |
| Strategic Partnership | Telehealth platform alliances enable remote prescription authorization in pharmacy desert geographies. |
Study Parameters
Independent corroboration across regulatory filings, clinical trial registries, and formulary databases underwrites the qualitative findings in this study. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and payer access specialists informed competitive positioning assessments. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up treatment modality demand estimates triangulated against top-down pharmaceutical revenue segmentation.
Rate-of-change decomposition across product type, end user, administration form, and regional regulatory cluster dimensions structured the analytical framework. CAGRs were derived from modeled adoption curves for microbiome-modulating therapies and erosion patterns in generic antibiotic volumes. Forecast inputs incorporated point-of-care diagnostic deployment rates, commercial payer coverage expansion for recurrent protocols, and cold-chain infrastructure development in target markets.
Caveats apply where antimicrobial resistance surveillance mandates, live biotherapeutic stability failures, or telehealth reimbursement policy reversals could materially shift the outlook. Forecasts reflect assumptions about regulatory pathway timelines and prescriber behavior adoption curves. A small set of named triggers—FDA breakthrough therapy award velocity, EMA MDR compliance cost escalation, and WHO prequalification standard revisions—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Herbal Drugs Market
Pharmaceuticals
Sleeping Medications Market
Pharmaceuticals
Glioblastoma Treatment Drugs Market
Pharmaceuticals
Global Muscle Relaxant Drugs Market
Pharmaceuticals
Antimetabolite Drugs Market
Pharmaceuticals
Global Liraglutide Market
Pharmaceuticals
Global Basal Insulin Market
Pharmaceuticals
Adapalene Products Market
Pharmaceuticals
Lamotrigine API Market
Pharmaceuticals
Global Hemostasis and Tissue Sealing Agents Market
Pharmaceuticals
Global Psoriasis Drugs Market
Pharmaceuticals
Intravenous Solution Compounders Market
Pharmaceuticals
Global Eylea Market
Pharmaceuticals
Global Loperamide Hcl Market
Pharmaceuticals
Asia Pacific SGLT2 Inhibitors Market
Pharmaceuticals
Retinal Drugs and Biologics Market