
 Hemp Seeds Market | 2026-2036
Hemp Seeds Market Size, Share, and Industry Trends Forecast 2026-2036
Hemp Seeds Market Intelligence
Subscription-based replenishment programs for shelled hemp seeds is pivoting how brands secure recurring revenue. Manitoba Harvest leverages direct-to-consumer auto-ship models to sustain repeat purchase rates in North America. Canah International anchors European supply through Romanian cultivation networks. Yunnan HuaFang Industrial Hemp Co. Ltd. dominates Chinese domestic processing with state-backed agricultural licenses.
Hemp seeds are the edible fruits of Cannabis sativa varieties bred below 0.3% THC, containing approximately 25% protein and 35% oil by weight with a complete amino acid profile and optimal omega-6 to omega-3 ratio near 3:1. They serve as functional food ingredients, animal feed components, and cosmetic oil feedstocks across industrial formulations. Shelled seeds command premium positioning in health stores and specialty shops where consumers pay for convenience and digestibility. Whole seeds retain cost advantages in industrial oil extraction and bulk feed applications where hull fiber adds value. Protein powder represents the fastest-growing product type as sports nutrition brands reformulate with plant-based alternatives.
EFSA novel food approvals govern hemp seed ingredient entry into European food and beverage applications, while FDA GRAS self-determination shapes U.S. market access without pre-market authorization. China's SAMR enforces GB standards for industrial hemp processing that separate food-grade from fiber-grade cultivars. Stakeholders must monitor evolving THC threshold harmonization between jurisdictions to avoid cross-border shipment seizures and reformulation costs.
Market Dynamics
Protein powder manufacturers in North America and Europe are pulling shelled hemp seeds into plant-based formulations at accelerating rates, compressing traditional soy and pea protein market positions while forcing cultivators to secure food-grade certifications ahead of ingredient procurement cycles.
Growth Catalysts
- Sports Nutrition Reformulation:Plant-based protein brands are substituting hemp seed protein for whey concentrates in recovery formulations, creating ingredient demand that outpaces supply contract availability in Canada and Germany.
- EFSA Novel Food Pathway:The European Food Safety Authority's streamlined authorization for hemp seed ingredients is reducing time-to-market for functional food entrants, particularly in protein-fortified bakery applications.
- Shelled Seed Convenience Premium:Health food retailers are allocating expanded shelf space to ready-to-eat hemp hearts, with consumer willingness-to-pay premiums for digestibility driving margin expansion across specialty distribution channels.
Market Restraints
- THC Threshold Harmonization Gaps:Divergent maximum THC limits between the USDA's 0.3% standard and China's GB cultivar classifications are creating cross-border shipment risks and forcing redundant testing protocols.
- Romanian Cultivation Concentration:European supply chains depend heavily on Canah International's Romanian growing networks, exposing buyers to single-source geographic concentration during adverse weather cycles.
- Pea Protein Substitution Threat:Established pea protein isolates maintain cost advantages in mass-market sports nutrition, limiting hemp protein penetration in price-sensitive contract manufacturing segments.
Strategic Opportunities
- Cosmetic Oil Feedstock Expansion:Personal care formulators in France and Switzerland are sourcing hemp seed oil for omega-rich skincare lines, opening premium pricing tiers outside traditional food applications.
- Chinese State-Backed Licensing:Yunnan Province's agricultural licensing framework is creating captive supply zones for domestic processors, with export potential to ASEAN markets under developing trade agreements.
- Direct-to-Consumer Subscription Channels:Auto-ship replenishment models are capturing lifetime value through recurring shelled seed purchases, reducing customer acquisition costs versus retail intermediation.
Industry Challenges
- Food-Grade Certification Timelines:EFSA novel food approvals require 18-24 month safety dossier reviews, delaying product launches and tying up R&D capital without revenue certainty.
- Hull Fiber Valorization Complexity:Whole seed processors must develop separate revenue streams for hull byproducts in animal feed, requiring additional capital equipment for fractionation that many mid-scale operators lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hemp Seeds Market |
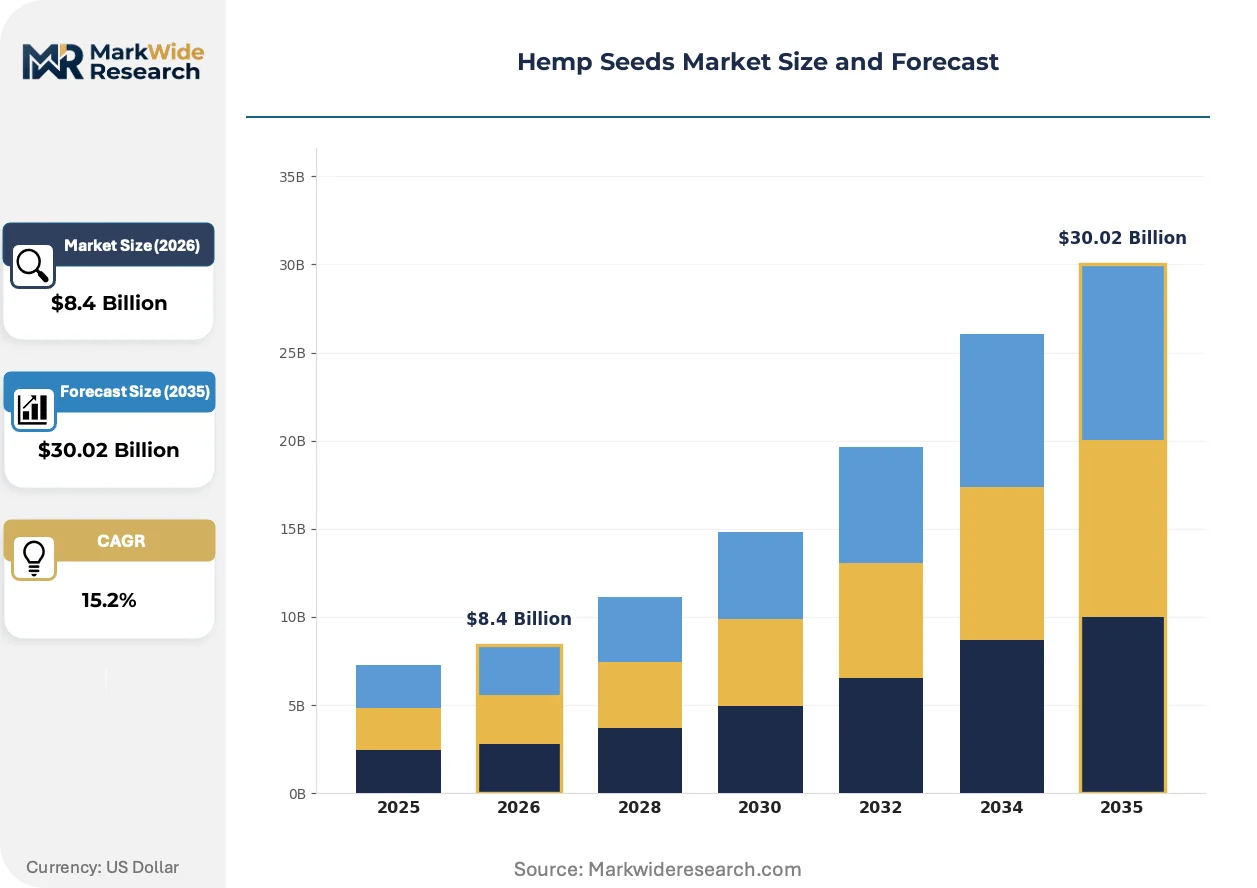
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $30.02 Billion |
| CAGR (2026 – 2036) | 15.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Seeds, Shelled Seeds, Oil, Protein Powder Grade: Food Grade, Feed Grade, Organic, Non-Organic Application: Food & Beverage, Nutraceuticals, Cosmetics, Industrial Distribution Channel: Online Retail, Supermarkets, Health Stores, Specialty Shops |
| Companies Covered | Manitoba Harvest, Green Source Organics, Harvest Hemp Foods, North American Hemp and Grain Co., Canah International, Hempflax BV, Yunnan HuaFang Industrial Hemp Co. Ltd., BAFA neu GmbH, Liaoning Qiaopai Biotech Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hemp Seeds Market Strategic Shifts & Innovations
Processing technology is fragmenting traditional oil extraction economics while regulatory clarity in major jurisdictions is enabling ingredient standardization that supports scale manufacturing.
Supercritical CO2 extraction systems are modularizing hemp seed oil production by enabling small-batch processors to achieve pharmaceutical-grade purity without industrial solvent infrastructure. Mid-scale Canadian processors are adopting these units to serve cosmetic and nutraceutical contracts that previously required tolling agreements with large refiners. This technology compression is lowering capital barriers for regional supply autonomy.
REACH registration requirements for hemp-derived ingredients in the European Union are forcing ingredient suppliers to consolidate toxicology data and submit joint dossiers through substance information exchange forums. The regulation is accelerating industry collaboration among competing processors while excluding non-compliant imports from German and Dutch formulation facilities. Protein powder manufacturers are responding by dual-sourcing from REACH-registered and pending-registration suppliers to hedge approval delays.
Ingredient buyers in North American sports nutrition are consolidating supplier relationships around vertically integrated cultivator-processors who control seed genetics through oil extraction. This procurement concentration is displacing spot-market purchasing and forcing traditional commodity traders to offer technical services and formulation support to retain accounts. The shift is most visible in contract manufacturing agreements for private-label protein blends where traceability certifications have become table stakes.
Hemp Seeds Market Segmentation
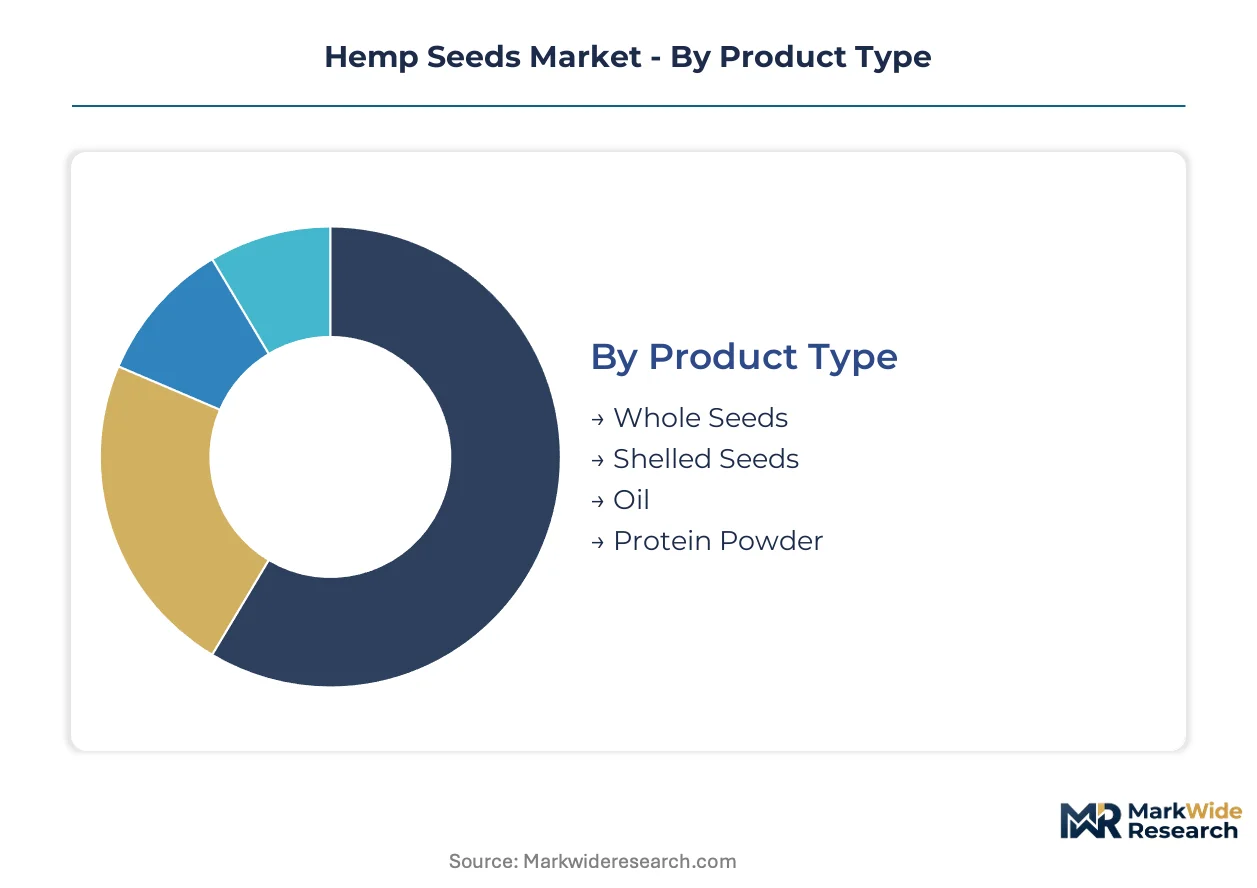
Hemp seed segmentation tracks how protein concentration, hull removal, and regulatory certification split buyers across price tiers and end-use applications. Each dimension reveals distinct procurement patterns and margin structures that processors exploit through targeted cultivation and processing investments.
Product Type:
Buyers in this category separate by convenience threshold and protein extraction intent rather than raw botanical characteristics alone.
- Shelled Seeds:Hulled kernels containing approximately 33% protein and 50% oil by weight with enhanced digestibility and ready-to-eat positioning. Demand concentrates in North American health stores and direct-to-consumer channels where Manitoba Harvest and similar operators capture recurring auto-ship subscriptions driven by sports nutrition formulation requirements.
- Protein Powder:Defatted meal processed to 50-70% protein concentration with complete amino acid profiles including high arginine content. Formulators in Germany and Canada are pulling this segment into plant-based recovery products, compressing soy and pea protein positions in premium sports nutrition contracts.
- Whole Seeds:Intact fruits with hull fiber retained, optimizing oil extraction yields and bulk feed economics. Industrial processors in China leverage Yunnan HuaFang's state-backed licenses for fiber-grade cultivar separation.
- Oil:Cold-pressed or supercritical CO2 extracted lipid fractions with omega-6 to omega-3 ratios near 3:1. Cosmetic laboratories in France and Switzerland source pharmaceutical-grade output for omega-rich skincare formulations.
Volume sits with whole seeds for industrial extraction; growth tilts toward protein powder in sports nutrition reformulation.
Grade:
Certification tier determines which regulatory pathway governs market access and which buyer segments remain addressable.
- Organic:Cultivated without synthetic pesticides or fertilizers under USDA NOP or EU 2018/848 standards, commanding shelf space premiums in German and Canadian retail. EFSA novel food authorization timelines stretch procurement cycles for organic-certified ingredients entering European protein-fortified bakery applications.
- Food Grade:Meets THC thresholds below 0.3% with microbiological and heavy metal specifications for human consumption. FDA GRAS self-determination enables U.S. market entry without pre-market authorization, accelerating brand launches versus EFSA's 18-24 month dossier reviews.
- Non-Organic:Conventional cultivation with standard agricultural inputs, serving price-sensitive feed and industrial oil markets where hull fiber valorization matters more than certification premiums.
- Feed Grade:Tolerates higher fiber content and broader THC variance for animal nutrition applications, with China's GB standards enforcing strict cultivar separation from food-grade channels.
Supply concentrates in food-grade organic for North American health retail; expansion runs through feed-grade for European aquaculture and poultry integration.
Application:
End-use divergence separates buyers by formulation complexity and regulatory scrutiny intensity.
- Food & Beverage:Protein fortification in bakery, dairy alternatives, and functional snacks with EFSA novel food governance in Europe and FDA GRAS pathways in the U.S. German manufacturers lead hemp seed integration into bread and muesli products.
- Nutraceuticals:Capsule and tablet formulations emphasizing omega fatty acid profiles and complete plant proteins for sports recovery segments.
- Cosmetics:Emollient and anti-inflammatory applications in French and Swiss premium skincare lines, with supercritical CO2 extraction enabling pharmaceutical-grade purity for dermal absorption claims.
- Industrial:Lubricants, paints, and biofuel feedstocks utilizing cold-pressed oil fractions outside food-grade specifications.
Revenue pools deepest in food and beverage; nutraceuticals are climbing the fastest on sports nutrition reformulation.
Distribution Channel:
Channel selection reflects customer lifetime value strategies versus transaction efficiency priorities.
- Online Retail:Direct-to-consumer auto-ship models capture recurring shelled seed purchases with reduced customer acquisition costs, exemplified by North American subscription programs locking in repeat rates.
- Health Stores:Specialty retail with trained staff explaining digestibility advantages of shelled seeds over whole alternatives, supporting premium pricing in urban Canadian and German markets.
- Supermarkets:Mass-market penetration requiring price-competitive positioning against established nut and seed categories, limiting organic and shelled variants to affluent postal codes.
- Specialty Shops:Independent retailers serving ethnic and alternative diet communities with bulk whole seed offerings for oil extraction and traditional food preparation.
Margin protection favors online retail with subscription lock-in; physical expansion tilts toward health stores for education-dependent premium conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada cultivates the majority of raw hemp seed output while the United States absorbs the largest share of shelled seed consumption through direct-to-consumer channels. This production-consumption divide shapes cross-border trade flows and certification requirements.
Canada
Manitoba and Saskatchewan host the dominant cultivation belts for food-grade hemp varieties. Health Canada oversees cultivar registration under the Industrial Hemp Regulations with strict THC monitoring protocols. Winnipeg anchors processing infrastructure where vertically integrated operators control genetics through oil extraction.
United States
Sports nutrition brands in Colorado and California drive shelled seed demand for protein fortification. The FDA permits GRAS self-determination for hemp ingredients without pre-market authorization, accelerating brand launches versus European timelines. Boulder and Denver clusters concentrate specialty food manufacturers sourcing organic-certified inputs.
Germany
Bakery and functional food manufacturers in Bavaria and North Rhine-Westphalia integrate hemp seeds into bread and muesli applications. EFSA novel food authorization governs ingredient entry with 18-24 month safety dossier reviews. Hamburg serves as the primary import gateway for Romanian and Canadian supply.
Romania
Canah International's cultivation networks in the Danube Delta and Transylvania regions supply European organic and conventional grades. EU 2018/848 organic standards apply alongside national agricultural licensing. Cluj-Napoca hosts processing facilities fractionating seeds for oil and protein separation.
China
Yunnan Province's state-backed agricultural licensing creates captive supply zones for domestic processors. SAMR enforces GB standards separating food-grade from fiber-grade cultivars with strict THC thresholds. Kunming anchors industrial processing for both domestic consumption and developing ASEAN export channels.
Hemp Seeds Market Key Industry Players
Capital-heavy producers compete with asset-light designers across distinct processing tiers. The market structure tilts toward vertical integration among mid-scale operators who control cultivation through extraction, while commodity traders struggle to retain accounts without technical services. Three archetypes dominate: vertically integrated cultivator-processors, regional tolling specialists, and ingredient traders offering formulation support. Competitive moves concentrate on backward integration into seed genetics and geographic expansion through EFSA registration hedging.
Among North American vertically integrated operators, Manitoba Harvest exemplifies the direct-to-consumer subscription model capturing recurring shelled seed purchases. Canah International occupies the European supply anchor position through Romanian cultivation networks. Yunnan HuaFang Industrial Hemp Co. Ltd. represents the state-licensed Chinese processor archetype with domestic market dominance.
| Leading Market Players |
|---|
| Manitoba Harvest |
| Green Source Organics |
| Harvest Hemp Foods |
| North American Hemp and Grain Co. |
| Canah International |
| Hempflax BV |
| Yunnan HuaFang Industrial Hemp Co. Ltd. |
| BAFA neu GmbH |
| Liaoning Qiaopai Biotech Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Sports nutrition contract manufacturers in North America and Europe command pricing leverage through consolidated procurement relationships with vertically integrated cultivator-processors, shifting transaction structures away from commodity spot markets toward technical service bundles and traceability premiums.
Pricing Analysis
Margin tightening in shelled seed tiers reflects procurement consolidation around Manitoba Harvest and similar operators who bundle formulation support with ingredient supply. Three-tier pricing structure across organic-certified, food-grade conventional, and feed-grade levels separates buyers by EFSA authorization status and THC testing protocols. Cost-down pressure on whole seed fractions accelerates as Chinese processors exploit state-licensed Yunnan supply for industrial oil extraction. Mass-market sports nutrition brands exhibit highest price sensitivity, while cosmetic laboratories in France and Switzerland accept pharmaceutical-grade premiums for supercritical CO2 extracted oils.
Supply Chain Analysis
Dual-sourcing requirements from German and Canadian formulators mandate qualification of both Romanian and North American suppliers to hedge EFSA approval delays and weather-related crop failures. Raw material flows draw from Canadian prairie cultivation belts, Romanian Danube Delta networks, and Yunnan state-licensed zones. Supply chain risk centers on single-source geographic concentration in Romanian organic networks controlled by Canah International. Distribution runs through direct-to-consumer auto-ship channels capturing recurring shelled seed purchases alongside health store intermediation for education-dependent premium conversion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supercritical CO2 extraction technology is displacing traditional solvent-based oil processing, enabling mid-scale processors to achieve pharmaceutical-grade purity without industrial infrastructure investments and fragmenting historical tolling relationships with large refiners.
For Market Incumbents: To counter pea protein substitution threats in mass-market sports nutrition, backward integration into proprietary seed genetics secures differentiated amino acid profiles for recovery formulations. EFSA novel food dossier pre-submission for organic-certified ingredients locks in 18-24 month approval timelines ahead of competitor entries. Captive supply contracts with Romanian cultivation networks hedge geographic concentration risks from Canah International's dominant position. For New Entrants and Emerging Players: Begin with cosmetic oil feedstock supply to French and Swiss skincare laboratories where pharmaceutical-grade purity commands premium pricing outside commoditized food channels. ASEAN export channels from Yunnan Province offer underpenetrated white-space as Chinese state-backed licensing creates captive supply zones with developing trade agreement access. Technical service partnerships with mid-scale Canadian processors lacking supercritical CO2 capabilities provide tolling revenue without cultivation capital requirements. For Investors and Strategic Acquirers: The window for entry favors vertically integrated cultivator-processors controlling genetics through extraction in Manitoba and Saskatchewan. Long-term viability rests on regulatory harmonization momentum across USDA, EFSA, and SAMR jurisdictions. Watch THC threshold alignment between China's GB standards and Western 0.3% limits as the signal for cross-border shipment friction reduction and inventory pooling opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Novel Food Dossier Submission | Accelerates European market entry for protein-fortified bakery applications against 18-24 month review timelines. |
| Supercritical CO2 Extraction Adoption | Enables mid-scale Canadian processors to serve cosmetic contracts without tolling agreements with large refiners. |
| Romanian Cultivation Network Expansion | Diversifies European supply beyond Canah International's concentrated Danube Delta and Transylvania growing regions. |
| Direct-to-Consumer Subscription Launch | Captures lifetime value through auto-ship replenishment models exemplified by Manitoba Harvest's recurring purchase programs. |
| Yunnan State-Backed Licensing Pursuit | Secures captive supply zones under SAMR GB standards with developing ASEAN export channel potential. |
Research Approach
Multi-period observation of EFSA novel food approval timelines, THC threshold harmonization developments, and sports nutrition reformulation patterns anchored the trend analysis, supplemented by interviews with hemp seed processors, functional food formulators, cosmetic laboratory procurement managers, and agricultural licensing officials. Secondary validation drew from Health Canada Industrial Hemp Regulations filings, FDA GRAS notification databases, SAMR GB standard publications, and EU 2018/848 organic certification records. Bottom-up cultivation volume estimates triangulated against top-down ingredient demand projections from protein powder manufacturers.
Segment-weighting across product type, grade certification, application, and distribution channel dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from elasticity-adjusted demand curves incorporating sports nutrition substitution rates and cosmetic oil feedstock expansion trajectories. Cultivar registration volumes under Health Canada oversight, EFSA safety dossier submission counts, and supercritical CO2 extraction unit installations served as industry-specific forecast inputs.
Regulatory approval delays, THC threshold divergence between jurisdictions, and pea protein cost competitiveness are the dominant revision risks that would necessitate forecast adjustment. A model refresh is warranted upon material change in EFSA novel food authorization timelines or SAMR GB standard harmonization with Western THC limits.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Cowpeas Market
Seeds
Organic Seed Market
Seeds
Cotton Seed Treatment Market
Seeds
Global Sports Turf Seed Market
Seeds
Africa Grain Seed Market
Seeds
Carrot Seed Oil Market
Seeds
Global Wheat Seed Market
Seeds
Tomato Seed Market
Seeds
Pigeon Pea Market
Seeds
Seed Health Market
Seeds
Genetically Modified Seeds Market
Seeds
Mexico Vegetable Seed Market
Seeds
Tallow Tree Seed Market
Seeds
Dodder Seed Market
Seeds
Europe Quinoa Seed Market
Seeds
China Seed Market