
 Africa Grain Seed Market | 2026-2036
Africa Grain Seed Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Grain Seed Market Outlook
Seed bundling with agronomic advisory services is expanding as the dominant commercial configuration across African distribution channels. Bayer AG leverages its breeding pipeline to anchor premium hybrid maize portfolios in Southern Africa. Corteva Agriscience sustains competitive intensity through trait integration and farmer-facing digital platforms. Seed Co Limited dominates certified seed supply corridors in Zimbabwe, Zambia, and Malawi through established breeder-to-field networks.
Africa grain seed comprises genetically improved and open-pollinated varieties selected for yield stability, drought tolerance, and disease resistance, with germination rates typically benchmarked above 85% under controlled conditions and genetic purity standards enforced through field inspection protocols. Its primary commercial purpose is to replace farm-saved grain with certified planting material that closes yield gaps across rainfed and irrigated production systems. Maize occupies the largest volume share as the staple carbohydrate across Eastern and Southern Africa, while soybean seed demand accelerates fastest on the back of poultry feed industrialization and edible oil processing investments. Smallholder agriculture remains the deepest addressable pool, though commercial farming commands disproportionate margin capture through volume contracting and input credit bundling.
Kenya's Seed and Plant Varieties Act, South Africa's Plant Improvement Act, and Ethiopia's national seed quality standards collectively shape variety release timelines, certification costs, and cross-border seed movement across the continent. Regulatory divergence between COMESA harmonization frameworks and national seed laws creates compliance complexity for suppliers operating in multiple jurisdictions. Stakeholders must monitor the pace of regional variety registration reciprocity and the political durability of input subsidy programs as determinants of market access and portfolio prioritization.
Market Dynamics
Certified hybrid seed penetration is displacing farm-saved grain across Africa's commercial farming corridors, tightening germination benchmarks and compressing variety release timelines as national seed authorities enforce genetic purity protocols.
Growth Catalysts
- Ethiopia's input subsidy expansion:Federal programs covering certified seed costs for smallholders are accelerating certified variety adoption in highland maize belts.
- Poultry feed industrialization:Soybean seed demand is pulling hybrid development investment from processors building crushing capacity near Lagos and Nairobi.
- COMESA variety registration reciprocity:Cross-border seed movement simplification is reducing certification duplication costs for suppliers operating in multiple East African jurisdictions.
Market Restraints
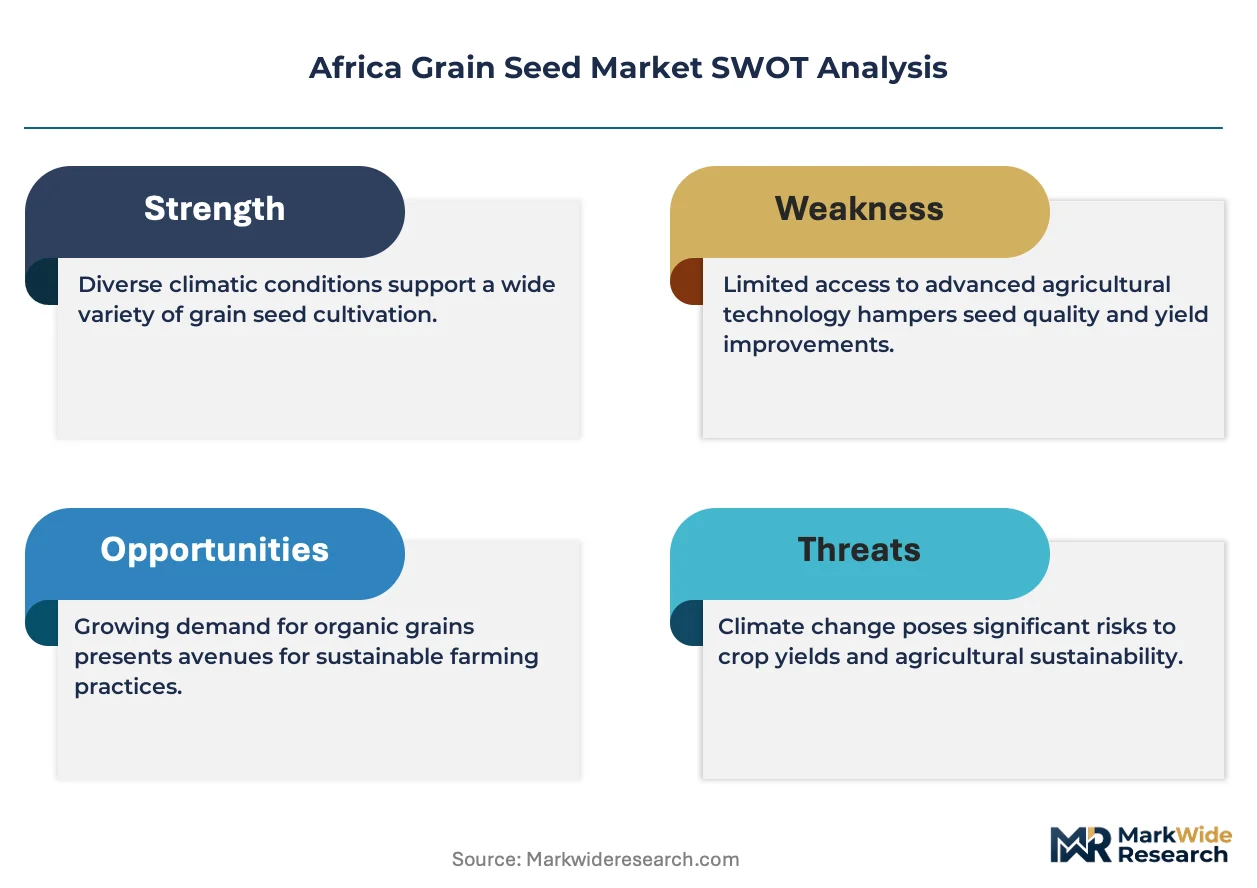
- Parent seed import dependency:Southern African breeding programs rely on temperate-zone germplasm, exposing cost structures to currency volatility and phytosanitary clearance delays.
- Rainfed production concentration:Yield instability in drought-prone Sahelian zones depresses certified seed return-on-investment calculations for risk-averse smallholders.
- Counterfeit seed infiltration:Informal channels in Nigeria and Kenya distribute mislabeled grain as certified planting material, eroding trust in formal distribution networks.
Strategic Opportunities
- DRC underpenetration:Eastern Congo's cassava-to-maize dietary transition creates demand for early-maturing hybrid varieties with limited local supply competition.
- Digital advisory bundling:Mobile-platform agronomic services bundled with seed purchases are opening credit-scoring channels for input financing in Tanzania.
- South Africa's drought-tolerance premiums:Water-scarcity breeding targets command price premiums in irrigation-restricted Western Cape wheat systems.
Industry Challenges
- Field inspection capacity:National seed certification agencies in Malawi and Zambia lack trained personnel to execute genetic purity verification protocols within planting windows.
- Trait licensing complexity:Proprietary biotechnology stacks require multi-jurisdictional royalty negotiations, delaying commercialization of insect-resistant hybrids.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Grain Seed Market |
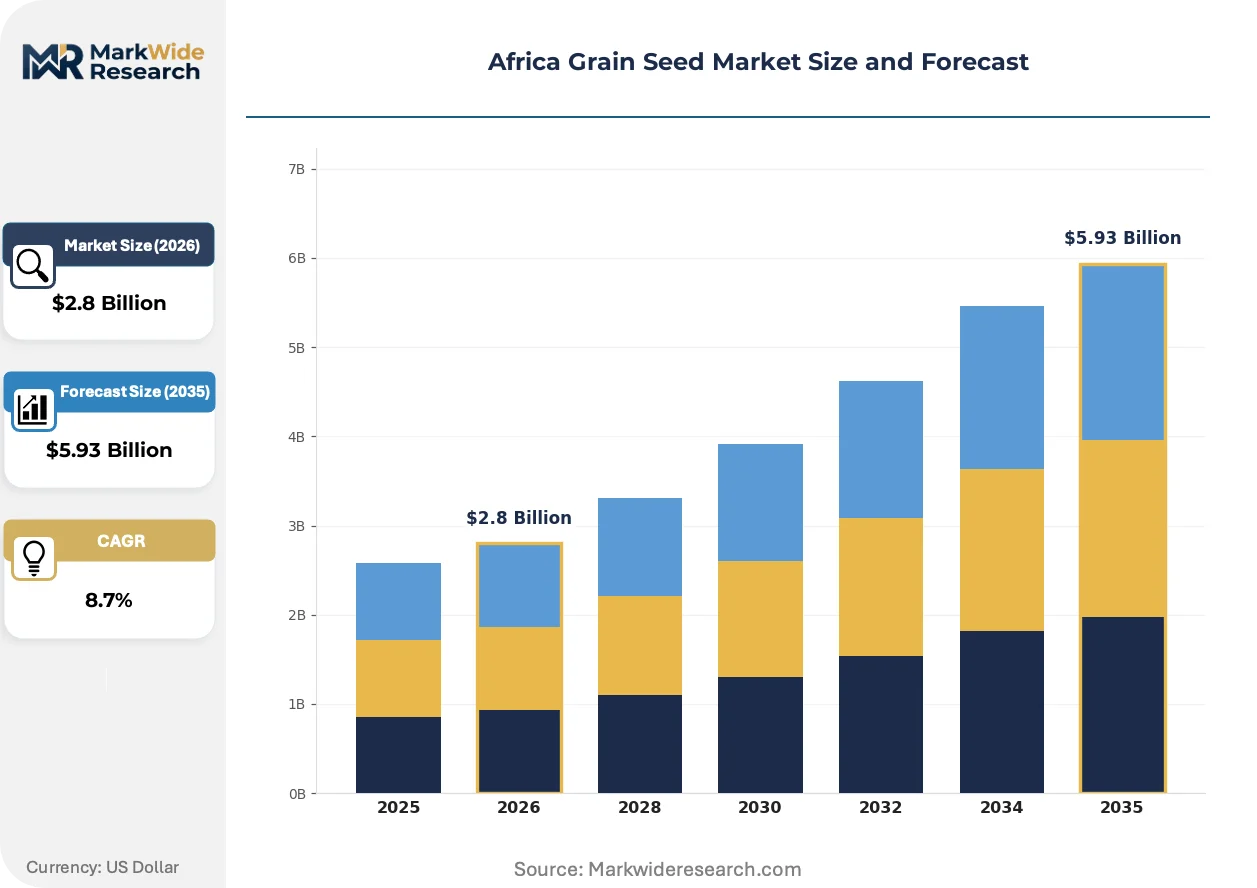
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Maize, Soybean, Wheat, Rice Application: Crop Production, Commercial Farming, Smallholder Agriculture, Research Distribution Channel: Direct Sales, Retailers, E-commerce, Cooperatives End User: Agricultural Enterprises, Farmers, Research Institutions, Agronomy Firms |
| Companies Covered | Bayer AG, Corteva Agriscience, Groupe Limagrain, Seed Co Limited, Syngenta Group, Advanta Seeds - UPL, BASF SE, Capstone Seeds, Zambia Seed Company Limited (Zamseed), Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Grain Seed Market Strategic Shifts
Genomic selection tools and climate-adaptive breeding pipelines are compressing variety development cycles while digital distribution platforms reconfigure how seed reaches smallholder fields.
Marker-assisted breeding is converging with rapid generation advance protocols in East African maize programs. National agricultural research institutes in Kenya and Ethiopia are adopting genomic selection to shorten breeding cycles from eight to four years. This compression is enabling faster deployment of drought-tolerant hybrids before climate stress patterns shift.
Kenya's Seed and Plant Varieties Act amendments are tightening distinctness-uniformity-stability testing requirements for new variety release. The regulatory tightening is extending commercialization timelines by 12-18 months for non-hybrid crops. Suppliers are responding by concentrating portfolio investment in hybrid maize and soybean where regulatory pathways remain streamlined.
Farmer-facing digital platforms are displacing traditional agro-dealer credit relationships in Southern Africa. Corteva's agronomic advisory apps and Bayer's weather-indexed insurance bundles are capturing smallholder loyalty through yield-guarantee mechanisms. Zimbabwe and Zambia show the fastest platform adoption where mobile penetration exceeds 75% and banking infrastructure remains sparse.
Africa Grain Seed Market Segmentation
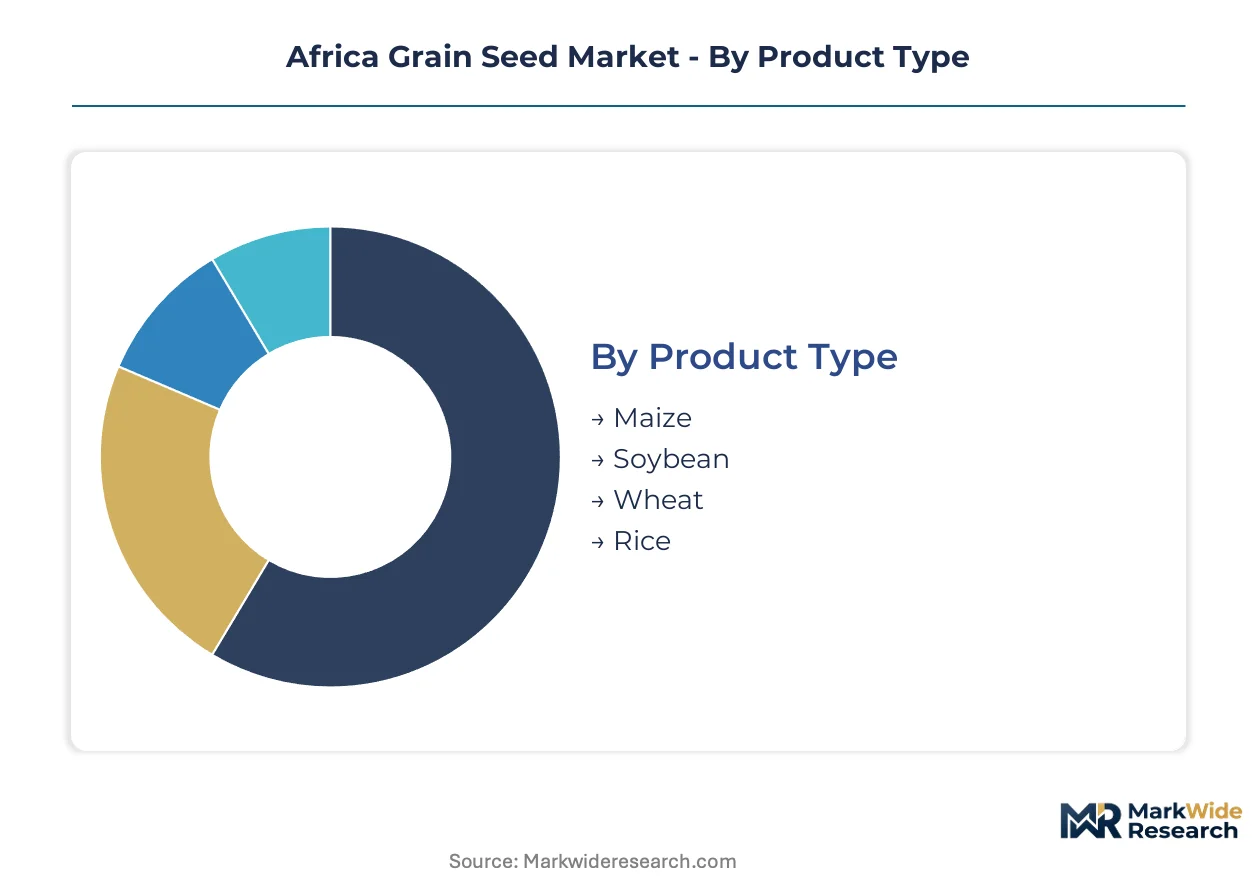
Segmentation across product type, application, channel, and end user reveals how certified hybrid adoption varies by farming scale and infrastructure access. These divides shape pricing power, distribution investments, and regulatory compliance burdens for suppliers operating across multiple African jurisdictions.
Product Type:
Replacement cycles for certified seed accelerate where yield gaps between farm-saved grain and hybrid varieties exceed 40 percent, driving upgrade decisions across commercial farming corridors.
- Maize:Drought-tolerant hybrids with stacked insect resistance dominate breeding pipelines. Demand concentrates in Ethiopia's highland belts and Nigeria's northern guinea savanna, where federal subsidy programs cover certified seed costs for smallholders transitioning from open-pollinated varieties.
- Soybean:Determinate growth habit varieties with pod-shatter resistance anchor commercial portfolios. Poultry feed industrialization near Lagos and Nairobi pulls hybrid development investment from processors building crushing capacity, with seed demand climbing fastest where contract farming schemes guarantee offtake.
- Wheat:Heat-tolerant spring wheat varieties address irrigation-restricted systems. Kenya's Rift Valley and South Africa's Western Cape drive certified seed procurement for winter wheat rotations.
- Rice:Upland NERICA hybrids and lowland inbred varieties serve distinct agro-ecologies. Nigeria's fadama irrigation schemes and Madagascar's highland perimeters anchor demand.
Maize sits at the top of the volume ranking, with soybean climbing the fastest.
Application:
Cost tier differentiation separates input-intensive commercial operations from risk-averse smallholder systems with limited working capital for certified seed purchases.
- Commercial Farming:Large-scale operations with irrigation infrastructure and mechanized planting demand high-germination hybrid maize with trait packages. South Africa's Western Cape and Zambia's Copperbelt anchor volume contracting, where seed suppliers bundle input credit with yield-guarantee mechanisms.
- Smallholder Agriculture:Rainfed producers with sub-hectare holdings prioritize price-accessible open-pollinated varieties. Ethiopia's federal subsidy programs and Tanzania's voucher schemes reduce out-of-pocket costs, though counterfeit seed infiltration in informal channels erodes trust.
- Crop Production:Broad-acre grain operations with storage and handling infrastructure source certified varieties through direct supplier relationships. Zimbabwe's contract maize schemes illustrate this channel's concentration.
- Research:National agricultural research institutes and CGIAR centers maintain breeder seed stocks for variety development pipelines. Kenya's KALRO and Ethiopia's EIAR anchor demand for foundation seed with genetic purity certification.
Commercial farming captures disproportionate margin share, with smallholder agriculture expanding most quickly on subsidy expansion.
Distribution Channel:
Customer type and mobile penetration patterns determine whether digital platforms or traditional agro-dealer networks dominate last-mile seed delivery.
- Direct Sales:Volume contracting between seed companies and commercial farming operations bypasses retail markups. Bayer and Corteva anchor premium hybrid portfolios through this channel in Southern Africa.
- Retailers:Agro-dealer networks with certified stockist status dominate smallholder access in Malawi and Zambia. Stockouts during planting windows and counterfeit infiltration constrain reliability.
- E-commerce:Mobile-platform ordering with doorstep delivery is gaining traction where banking infrastructure remains sparse. Zimbabwe and Zambia show fastest adoption with mobile penetration exceeding 75 percent.
- Cooperatives:Bulk procurement aggregations reduce per-unit seed costs for smallholder groups. Ethiopia's cooperative unions and Kenya's farmer service centers illustrate this channel's reach.
Retailers maintain the deepest penetration footprint, with e-commerce gaining share fastest on platform investment.
End User:
Supply concentration among national research institutes and multinational breeding programs shapes variety availability for distinct user categories with divergent technical requirements.
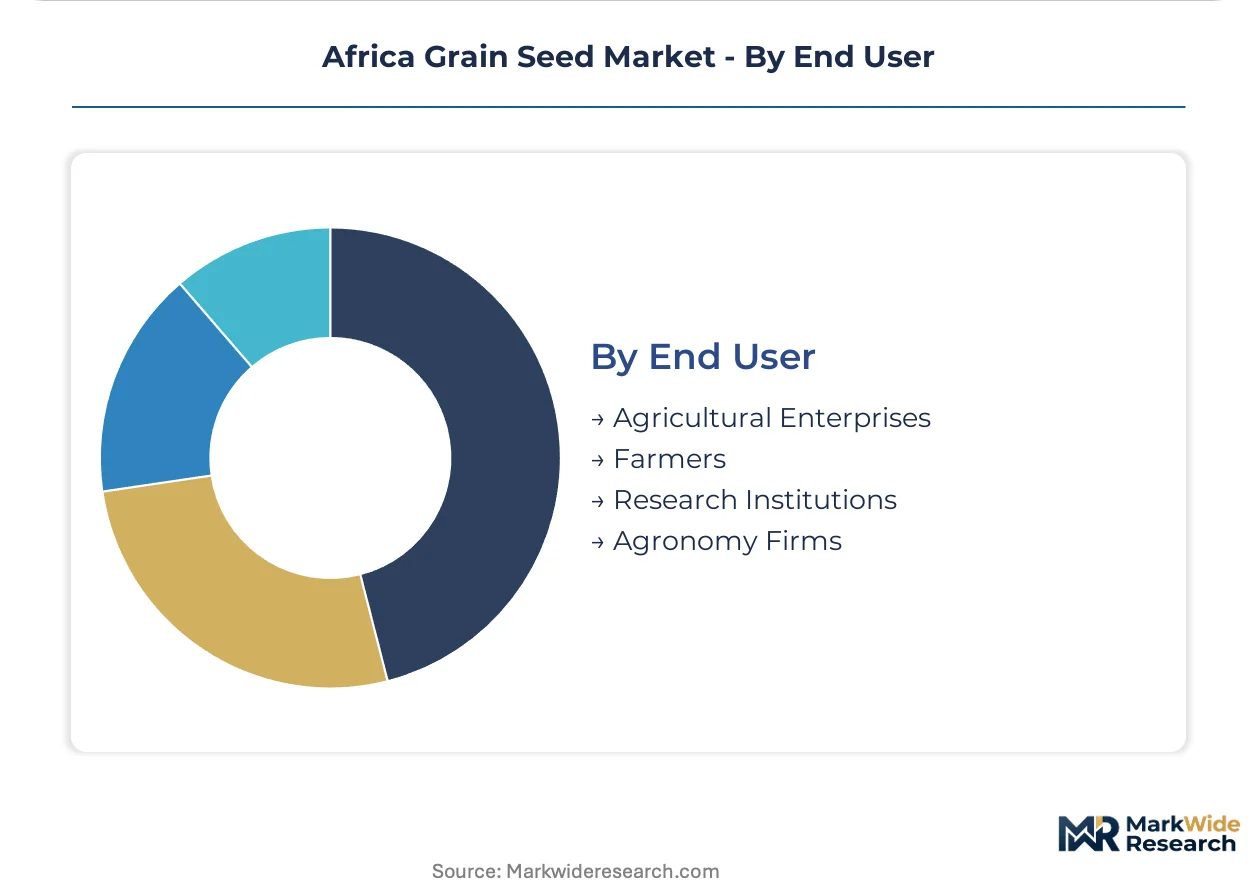
- Farmers:Individual producers with heterogeneous risk profiles and land tenure systems constitute the deepest addressable pool. Nigeria, Ethiopia, and South Africa concentrate absolute demand.
- Agricultural Enterprises:Vertically integrated operations with captive processing and offtake infrastructure source certified seed through multi-year supply agreements. Poultry integrators in Nigeria and oilseed processors in Kenya anchor soybean seed procurement.
- Research Institutions:National variety release authorities and international breeding programs demand foundation seed with documented pedigree and genetic purity certification. Kenya's Seed and Plant Varieties Act compliance requirements shape procurement specifications.
- Agronomy Firms:Technical service providers bundle seed recommendations with soil testing and crop protection advisory. Tanzania's emerging digital advisory platforms illustrate this category's growth.
Farmers represent the largest user category by volume, with agricultural enterprises expanding most quickly on industrialization investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial seed breeding in Africa traces its modern lineage to colonial-era research stations in Kenya and Zimbabwe, where hybrid maize development programs established the germplasm foundations that now supply certified varieties across Eastern and Southern Africa.
Nigeria
Federal input subsidy programs covering certified seed costs for smallholders drive hybrid maize adoption in the northern guinea savanna. The National Agricultural Seeds Council enforces seed quality standards through field inspection protocols. Lagos anchors poultry feed industrialization, pulling soybean seed demand from processors building crushing capacity.
Ethiopia
Highland maize belts expand irrigated acreage through federal programs subsidizing certified variety costs for rainfed producers. The Ethiopian Institute of Agricultural Research sets national seed quality standards governing variety release timelines. The Rift Valley corridor concentrates commercial wheat seed procurement for winter rotations.
South Africa
The Western Cape's irrigation-restricted wheat systems command price premiums for drought-tolerance breeding targets. The Plant Improvement Act governs variety registration and genetic purity certification requirements. The Copperbelt region anchors volume contracting between seed suppliers and large-scale commercial operations.
Kenya
Mobile-platform agronomic services bundled with seed purchases open credit-scoring channels for input financing among smallholders. The Seed and Plant Varieties Act amendments tighten distinctness-uniformity-stability testing requirements for new variety release. Nairobi anchors breeder-to-field networks supplying certified hybrid corridors.
Zimbabwe
Contract maize schemes illustrate direct supplier relationships with broad-acre grain operations maintaining storage infrastructure. National seed certification agencies enforce germination rate benchmarks above 85 percent under controlled conditions. Mobile penetration exceeding 75 percent enables fastest platform adoption for digital advisory bundling.
Africa Grain Seed Market Competitive Environment
Premium-margin players sit above commodity-margin players across trait integration and breeding pipeline depth, with multinational breeding programs commanding price premiums for stacked insect resistance and drought tolerance. The vendor base fragments across national research institutes, regional seed companies, and integrated multinational portfolios. Three strategic archetypes dominate: germplasm owners with proprietary biotechnology stacks, regional specialists with established distribution networks, and national champions with government contract relationships. Capacity expansion and trait licensing constitute the dominant competitive moves reshaping market access.
Within the germplasm-owner tier, Bayer AG and Corteva Agriscience occupy positions anchoring premium hybrid portfolios across Southern Africa. Seed Co Limited exemplifies the regional specialist archetype, with its name signaling concentrated presence in Zimbabwe, Zambia, and Malawi supply corridors. These three entities represent distinct strategic positions: multinational breeding depth, trait integration platforms, and established breeder-to-field networks respectively.
| Leading Market Players |
|---|
| Bayer AG |
| Corteva Agriscience |
| Groupe Limagrain |
| Seed Co Limited |
| Syngenta Group |
| Advanta Seeds - UPL |
| BASF SE |
| Capstone Seeds |
| Zambia Seed Company Limited (Zamseed) |
| Others |
Value Chain & Pricing Dynamics
Skilled breeder-scientist concentrations in Kenya's Rift Valley and Ethiopia's highland research stations anchor labor-cost differentials that widen pricing spreads between premium hybrid portfolios and commodity open-pollinated varieties. These talent clusters enable multinational programs to command germplasm premiums while regional seed companies compete on distribution proximity.
Pricing Analysis
Volume-contracting with input-credit bundling anchors pricing structures across Southern African commercial farming corridors. Price differentiation separates trait-integrated hybrids with stacked insect resistance from single-trait certified varieties and farm-saved grain substitutes. Pricing pressure intensifies in Nigeria's northern guinea savanna as counterfeit seed infiltration erodes formal-channel trust and compresses margin capture. Smallholder agriculture exhibits acute price sensitivity to upfront seed costs, while commercial farming operations prioritize yield-guarantee mechanisms over unit pricing.
Supply Chain Analysis
Kenya's Seed and Plant Varieties Act amendments and Ethiopia's national seed quality standards are reshaping parent-seed sourcing requirements for regional breeding programs. Supply concentrates in South Africa's Western Cape winter wheat systems, Zambia's Copperbelt hybrid maize corridors, and Zimbabwe's contract farming networks. Breeding pipelines draw from temperate-zone germplasm repositories, exposing cost structures to currency volatility and phytosanitary clearance delays. Single-source vulnerability runs through parent-seed import dependencies for drought-tolerance traits. Distribution runs through agro-dealer networks with certified stockist status, though mobile-platform ordering gains share where banking infrastructure remains sparse.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified hybrid penetration is accelerating toward late-cycle quality concentration as poultry feed industrialization and irrigation expansion pull demand toward premium germplasm specifications. The market rewards breeding depth and regulatory navigation capability over pure distribution scale.
For Market Incumbents: Deploy field inspection capacity expansion to defend genetic purity certification moats against counterfeit infiltration in Nigeria and Kenya. Deepen backward integration into rapid generation advance protocols to compress variety development cycles before climate stress patterns shift. Channel control through digital advisory bundling captures smallholder loyalty where mobile penetration exceeds threshold levels. For New Entrants and Emerging Players: Capture Eastern Congo's cassava-to-maize dietary transition with early-maturing hybrid varieties before established breeder-to-field networks extend reach. Target Tanzania's emerging digital advisory platforms for credit-scoring channel entry. White-space concentration in DRC's underpenetrated highland belts offers limited local supply competition for agile entrants with rapid variety registration capability. For Investors and Strategic Acquirers: Regional seed companies with established COMESA variety registration reciprocity are the most active acquirer targets in this space for multinational breeding programs seeking distribution footprint. Long-term viability hinges on regulatory durability of input subsidy programs and pace of genomic selection adoption. Watch Ethiopia's federal subsidy expansion pace as the inflection signal for certified seed penetration acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Trait Licensing Agreement | Proprietary biotechnology stacks require multi-jurisdictional royalty negotiations before insect-resistant hybrid commercialization. |
| Digital Platform Integration | Mobile agronomic advisory bundling with seed purchases opens credit-scoring channels in Tanzania's sparse banking infrastructure. |
| Backward Integration into Parent Seed | In-house germplasm development reduces exposure to temperate-zone import dependency and currency volatility. |
| Regional Variety Registration Expansion | COMESA harmonization reciprocity reduces certification duplication costs for East African multi-jurisdiction operations. |
| Cooperative Channel Partnership | Bulk procurement aggregations through Ethiopia's cooperative unions reduce per-unit seed costs for smallholder groups. |
Study Parameters
Direct dialogue with breeder program directors, national seed certification agency inspectors, agro-dealer network managers, and poultry feed procurement officers grounded qualitative findings in operational realities across the value chain. Secondary validation drew from Kenya Seed and Plant Varieties Act regulatory filings, COMESA harmonization framework documentation, Ethiopian Institute of Agricultural Research variety release records, and national agricultural input subsidy program disclosures. Bottom-up and top-down triangulation cross-checked volume estimates against certified seed distribution data and commercial farming acreage expansion.
Bottom-up modeling anchored forecasts in segment-level penetration rates for certified hybrid versus farm-saved grain substitution across product type, application, and distribution channel dimensions. Top-down validation referenced macroeconomic drivers including poultry feed industrialization investment, irrigation infrastructure expansion, and mobile platform penetration thresholds. CAGRs were derived from trajectory analysis of certified seed procurement volumes against subsidy program scaling and breeding pipeline deployment timelines. Climate stress pattern shifts and genomic selection adoption curves served as industry-specific forecast sensitivity inputs.
Subsidy program political durability, counterfeit seed enforcement effectiveness, and parent-seed import clearance reliability are the dominant revision risks warranting ongoing scenario assessment. Forecasts reflect assumptions about regulatory reciprocity pace and breeding cycle compression feasibility. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Poppy Seed Market
Seeds
Global Packaged Chia Seeds Market
Seeds
Asia-Pacific Quinoa Seeds Market
Seeds
India Maize Seed Market
Seeds
North America Alfalfa Seed Market
Seeds
South Africa Forage Seed Market
Seeds
Sweet Corn Seeds Market
Seeds
Organic Sesame Seed Market
Seeds
Southeast Asia Vegetable Seed Market
Seeds
China Seed Market
Seeds
Pumpkin Seeds Market
Seeds
Global Grain Seed Market
Seeds
Faba Beans Market
Seeds
Sri Lanka Seed Market
Seeds
Africa Chia Seeds Market
Seeds
Avena Sativa Market