
 Tomato Seed Market | 2026-2036
Tomato Seed Market Size, Share, and Industry Trends Forecast 2026-2036
Tomato Seed Market Intelligence
The R&D-to-scale capability gap between integrated seed conglomerates and regional specialists is unwinding as climate-resilient variety development demands heavier capital deployment. Limagrain leverages its global breeding network to sustain trait pipelines across multiple agroclimatic zones. BASF SE anchors its position through advanced molecular marker platforms that accelerate hybrid development cycles. Syngenta AG competes via integrated crop solution bundles that extend beyond seed into crop protection adjacencies.
Tomato seed comprises the reproductive propagule of Solanum lycopersicum, typically processed to achieve specified germination rates exceeding 85 percent and treated with film coatings containing fungicides or micronutrients to enhance field establishment. Its commercial purpose centers on enabling standardized, high-yielding fruit production for fresh market and processing supply chains. Hybrid seed types dominate value capture due to proprietary trait stacks and farmer willingness to pay for yield consistency, while organic farming applications represent a faster-growing demand pocket where open pollinated and heirloom varieties command premium positioning. Seed priming technology leads operational adoption among large-scale greenhouse operators seeking uniform emergence, whereas pelleting penetration remains concentrated in mechanized transplanting systems.
EU Green Deal sustainability targets and REACH chemical restrictions are reshaping permissible seed coating chemistries, forcing reformulation investments across European supply chains. India's Central Seed Committee and BIS certification requirements govern varietal release and quality standards, creating compliance thresholds that filter market access for imported genetics. Stakeholders must monitor evolving phytosanitary protocols and trait registration timelines as regulatory divergence between jurisdictions complicates variety deployment strategies.
Market Dynamics
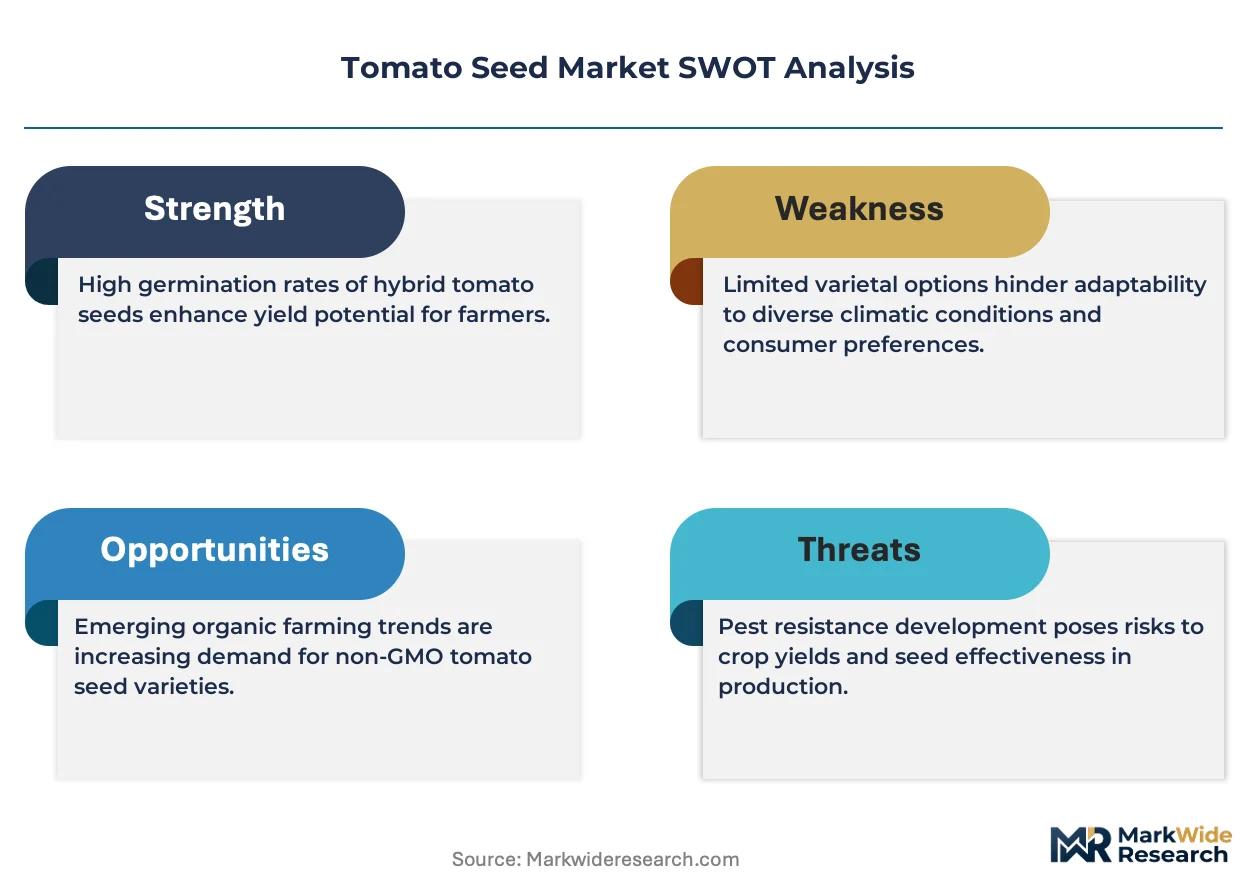
Greenhouse cultivation expansion is compressing breeding timelines and forcing seed developers to prioritize climate-adaptive trait stacks over traditional field-performance metrics.
Growth Catalysts
- Protected Agriculture Subsidies:India's government-backed horticulture programs accelerate farmer uptake of certified hybrid varieties through direct procurement support and protected structure financing.
- EU Green Deal:Sustainability mandates under this framework drive demand for low-chemical-input varieties and reformulated seed coatings that reduce environmental load.
- Seed Priming Technology:Large-scale greenhouse operators deploy advanced priming protocols to achieve emergence uniformity, cutting transplant labor costs and improving stand establishment rates.
Market Restraints
- Parent Line Concentration:Hybrid seed production depends on geographically concentrated cytoplasmic male-sterile line maintenance, creating vulnerability to regional weather shocks and disease outbreaks.
- REACH Chemical Restrictions:ECHA's tightening seed coating chemistry rules force costly reformulation cycles, eroding margins for European supply chain participants.
- Open Pollinated Substitution:Organic certification requirements and heirloom variety preference in premium fresh markets limit hybrid penetration in fastest-growing demand pockets.
Strategic Opportunities
- Mechanized Transplanting Systems:Pelleting technology adoption lags in emerging protected agriculture clusters, creating white space for coating specialists to capture equipment-integrated supply relationships.
- CRISPR Trait Acceleration:Regulatory clarity on gene-edited varieties in select jurisdictions enables compressed development cycles for drought and pest resistance stacks.
- Farmer Producer Organizations:India's FPO aggregation model concentrates seed demand, enabling direct varietal placement and bypassing traditional distributor markups.
Industry Challenges
- Phytosanitary Protocol Divergence:India's BIS certification timelines and Central Seed Committee release procedures create deployment delays that misalign variety introduction with growing season windows.
- Trait Registration Complexity:Stacked genetic modifications face asynchronous approval pathways across export destination markets, complicating variety portfolio planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tomato Seed Market |
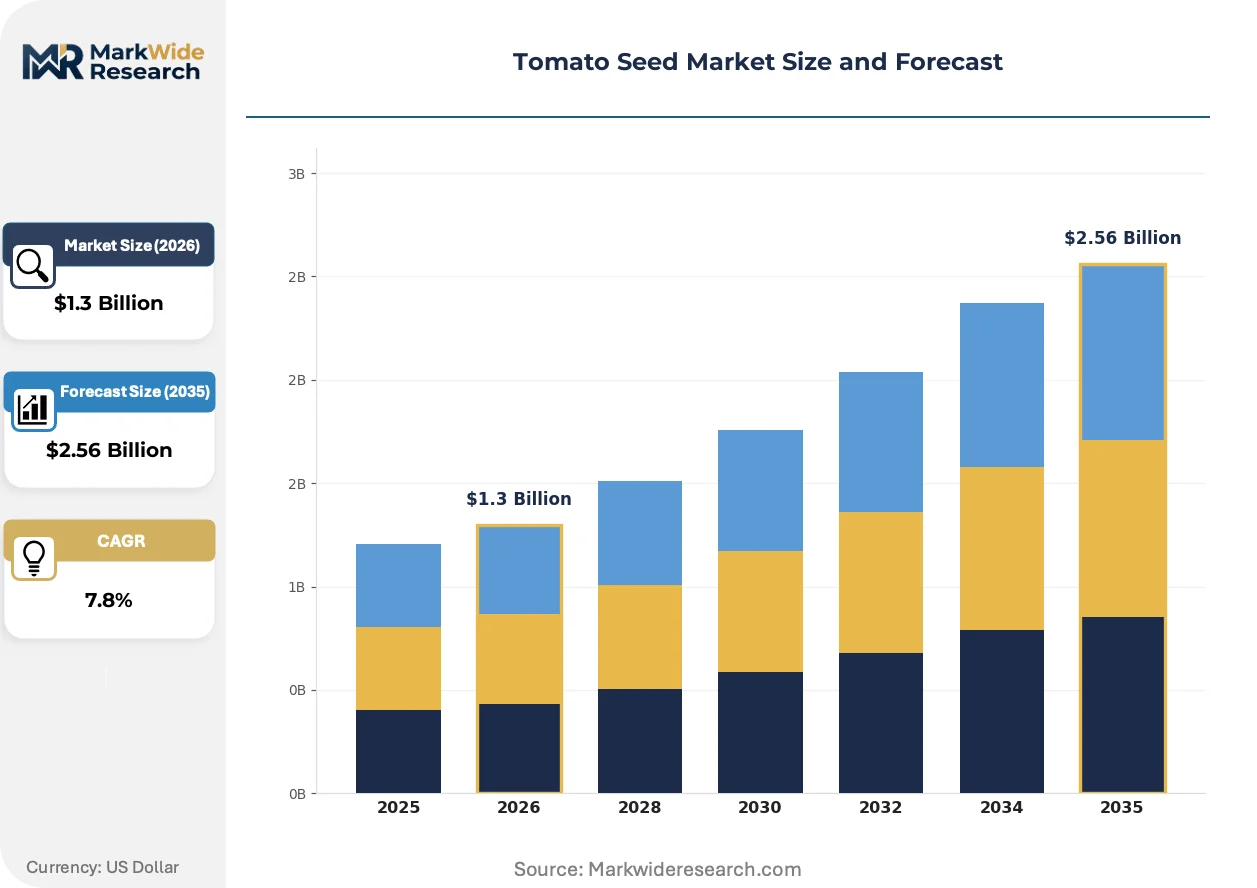
| Market Size in 2026 | $1.3 Billion |
| Market Size in 2035 | $2.56 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Seed Type: Hybrid, Open Pollinated, Heirloom, Genetically Modified End Use Application: Greenhouse Cultivation, Organic Farming, Contract Farming, Home Gardening Technology: Seed Priming, Coating, Pelleting, Micropropagation Customer Type: Seed Companies, Agricultural Cooperatives, Private Farmers, Research Institutions |
| Companies Covered | Limagrain, Rijk Zwaan Zaadteelt en Zaadhandel B.V., BASF SE, Syngenta AG, Sakata Seed Corporation, Bayer AG, Namdhari Seeds Pvt. Ltd., Takii & Co. Ltd., East West Seeds India Pvt. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tomato Seed Market Strategic Shifts & Innovations
Digital phenotyping platforms are compressing generational breeding cycles while molecular marker deployment accelerates trait stacking precision across multiple agroclimatic targets.
Gene editing via CRISPR-Cas9 is displacing transgenic approaches for disease resistance development. Seed developers deploy these tools to introduce targeted pathogen tolerance without foreign DNA insertion, satisfying regulatory pathways in jurisdictions with distinct treatment of edited versus transformed organisms. Commercial greenhouse operators in the Netherlands and Spain prioritize edited varieties for their reduced regulatory burden and faster market access.
REACH authorization requirements are forcing coating chemistry transitions away from neonicotinoid and certain triazole active ingredients. ECHA's substance evaluation program has designated several legacy seed treatment compounds as substances of very high concern, compelling formulators to validate biological and mineral alternatives. European supply chains absorb these compliance costs through reformulation partnerships with specialty chemical providers.
Direct contracting between seed developers and integrated greenhouse operators is shortening traditional distribution hierarchies. Large-scale protected agriculture investors in India and Mexico negotiate exclusive varietal access and technical service bundles, displacing multi-brand distributor relationships. This concentration of procurement decision-making favors breeders with captive greenhouse trial networks and localized agronomic support capabilities.
Tomato Seed Market Segmentation
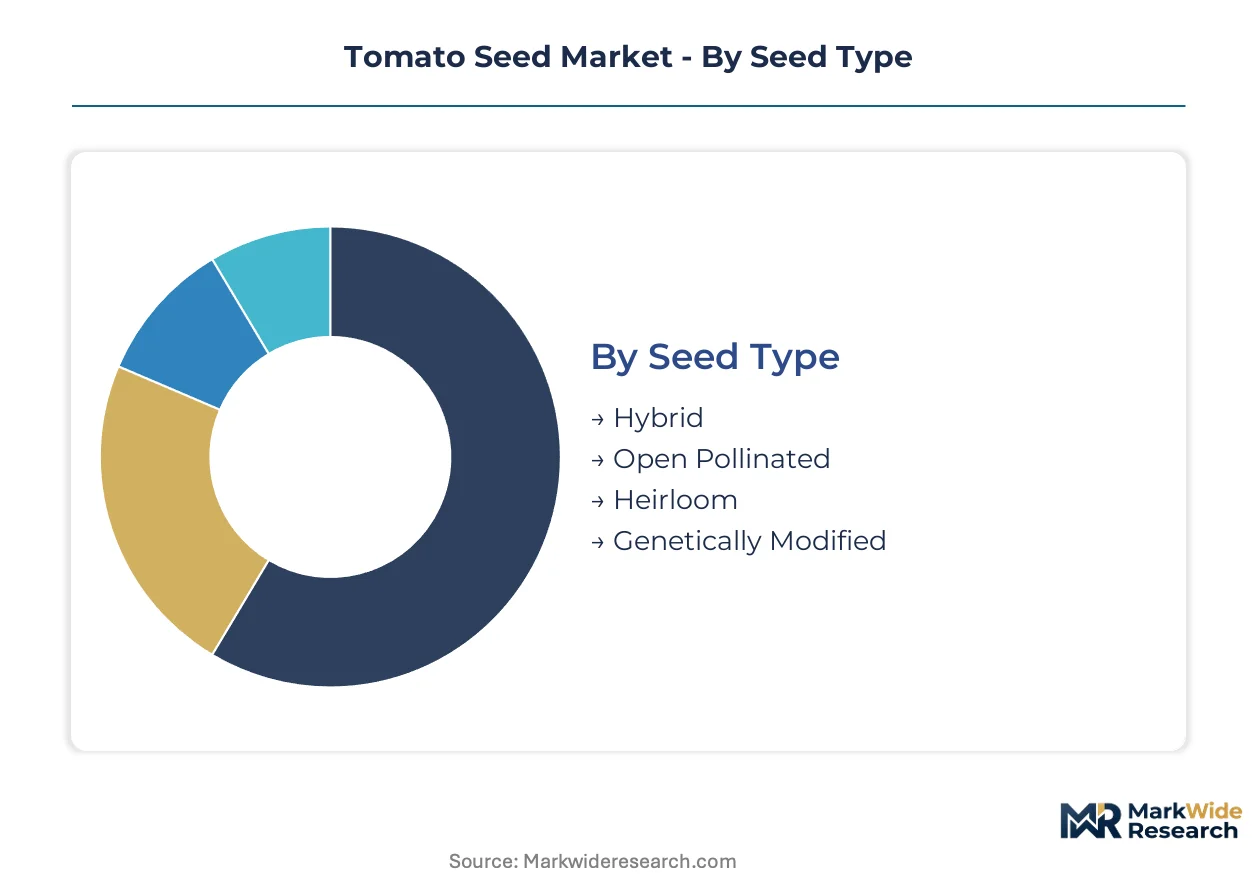
Tomato seed market segmentation reveals how breeding investments, cultivation systems, and procurement channels align to create distinct value pools. Channel dynamics vary sharply between protected agriculture supply chains and open-field distribution networks, with technology adoption further stratifying customer relationships.
Seed Type:
Channel concentration differs markedly: hybrid varieties flow through proprietary distributor networks with technical service bundles, while open pollinated and heirloom seeds reach growers via agricultural retailers and direct-to-farm ecommerce platforms.
- Hybrid:Proprietary F1 crosses combine cytoplasmic male sterility with targeted trait stacks for yield consistency and disease resistance. Demand concentrates in commercial greenhouse clusters across the Netherlands, Spain, and India where payback periods justify premium seed pricing against labor savings.
- Open Pollinated:Self-pollinating varieties maintain genetic stability across generations without hybrid vigor degradation. Organic certification requirements in EU member states and premium fresh market channels in North America drive farmer retention of open pollinated genetics despite lower per-hectare yields.
- Heirloom:Heritage varieties preserved through farmer selection carry distinct flavor profiles and morphological diversity for specialty retail and restaurant supply chains.
- Genetically Modified:Transgenic trait insertion for viral resistance and extended shelf life remains restricted to specific export-oriented production zones with regulatory acceptance.
Hybrid dominates installed base. Heirloom is where expansion concentrates in premium fresh market channels.
End Use Application:
Cost tier stratification separates high-infrastructure protected systems from low-capital entry points, with equipment requirements and financing access determining grower segment participation.
- Greenhouse Cultivation:Controlled environment agriculture demands climate-adaptive hybrid varieties with determinate growth habits optimized for high-density planting. India's protected structure subsidies and Morocco's export-oriented cluster development accelerate certified seed procurement through integrated greenhouse operators.
- Organic Farming:Certification constraints prohibit synthetic seed treatments and genetically modified germplasm, funneling demand toward untreated open pollinated and heirloom varieties. EU Green Deal organic area targets expand the addressable market for untreated seed coatings and biological priming agents.
- Contract Farming:Processor and exporter agreements specify varietal requirements with seed supply bundled into input packages.
- Home Gardening:Small-scale cultivation favors packet-sized quantities of cherry and beefsteak types through retail and digital channels.
Greenhouse Cultivation commands margin concentration. Organic Farming is climbing the fastest among application segments.
Technology:
Customer type determines technology penetration: large-scale greenhouse operators adopt priming and pelleting for mechanized systems, while smallholders rely on basic coated seed through cooperative procurement.
- Seed Priming:Controlled hydration protocols initiate metabolic processes before sowing, compressing emergence windows and improving stand uniformity. Netherlands-based greenhouse operators deploy priming for transplant scheduling precision in year-round production cycles.
- Coating:Film layers deliver fungicides, micronutrients, and rhizobia inoculants to enhance field establishment. REACH chemical restrictions in EU jurisdictions force reformulation toward biological actives and mineral carriers.
- Pelleting:Size-standardized pellets enable mechanical singulation in transplanting equipment, reducing labor dependency.
- Micropropagation:Tissue culture multiplication of disease-free nuclear stock supports rapid varietal scaling for emerging markets.
Coating holds installed base dominance. Pelleting is gaining share fastest as mechanized transplanting spreads.
Customer Type:
Volume concentration varies by procurement scale, with seed companies and cooperatives aggregating demand that individual farmers cannot match, while research institutions anchor pre-commercial variety pipelines.
- Seed Companies:Integrated breeders and licensed distributors capture value through proprietary genetics and technical service relationships. India's Central Seed Committee registration requirements filter market access, favoring established players with regulatory affairs capabilities.
- Agricultural Cooperatives:Aggregated procurement concentrates demand for standardized varieties across member farms. Mexico's protected agriculture cooperatives negotiate direct breeder contracts, bypassing traditional distributor markups.
- Private Farmers:Individual growers select varieties based on local extension recommendations and neighboring plot performance.
- Research Institutions:Public breeding programs and universities maintain germplasm collections and conduct adaptive trials.
Seed Companies dominate volume capture. Agricultural Cooperatives represent the steepest expansion trajectory in emerging protected agriculture clusters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across cultivation systems. Smallholder open-field growers in emerging markets prioritize seed cost over trait sophistication, while integrated greenhouse operators in developed clusters accept premium pricing for emergence uniformity and disease resistance stacks.
India
Protected agriculture subsidies and government-backed horticulture programs drive certified hybrid seed uptake among commercial growers. The Central Seed Committee and BIS certification requirements govern varietal release and quality standards, filtering market access for imported genetics. Maharashtra and Karnataka host concentrated protected structure clusters where Farmer Producer Organizations aggregate demand and negotiate direct breeder contracts.
Netherlands
Year-round greenhouse production cycles generate sustained demand for primed hybrid varieties with determinate growth habits optimized for high-density planting. REACH chemical restrictions and EU Green Deal sustainability mandates force coating chemistry reformulation toward biological actives and mineral carriers. Westland municipality anchors the densest concentration of glasshouse operations, where direct contracting between breeders and integrated operators displaces traditional distributor hierarchies.
Spain
Export-oriented protected agriculture in Almería and Murcia drives procurement of climate-adaptive varieties with stacked disease resistance. ECHA substance evaluation programs designate legacy seed treatment compounds as substances of very high concern, compelling compliance investments across European supply chains. Almería's greenhouse belt concentrates mechanized transplanting systems where pelleting technology adoption reduces labor dependency.
United States
Organic certification requirements and heirloom variety preference in premium fresh market channels sustain demand for open pollinated genetics despite lower per-hectare yields. USDA organic standards prohibit synthetic seed treatments, funneling procurement toward untreated coatings and biological priming agents. California's Central Valley and Florida's winter vegetable districts host distinct production clusters with divergent seed technology penetration.
Mexico
Processor and exporter agreements specify varietal requirements with seed supply bundled into input packages for contract farming arrangements. Phytosanitary protocol divergence complicates variety deployment strategies for stacked genetic modifications facing asynchronous approval pathways. Sinaloa and Baja California greenhouse clusters negotiate exclusive varietal access and technical service bundles with integrated breeders.
Tomato Seed Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with scale advantages in breeding network density and regulatory affairs capabilities determining competitive position. The market structure rewards players with captive greenhouse trial networks and localized agronomic support infrastructure. Three archetypes dominate: global integrated conglomerates with multi-crop trait pipelines, regional specialists with climate-adaptive variety portfolios, and coating technology providers with equipment-integrated supply relationships. Competitive moves concentrate on direct contracting with large-scale protected agriculture investors and reformulation partnerships with specialty chemical providers to address REACH compliance requirements.
Within the integrated conglomerate tier, Limagrain, BASF SE, and Syngenta AG exemplify scale-driven positioning. Limagrain leverages its global breeding network to sustain trait pipelines across multiple agroclimatic zones. BASF SE anchors its position through advanced molecular marker platforms. Syngenta AG competes via integrated crop solution bundles that extend beyond seed into crop protection adjacencies.
| Leading Market Players |
|---|
| Limagrain |
| Rijk Zwaan Zaadteelt en Zaadhandel B.V. |
| BASF SE |
| Syngenta AG |
| Sakata Seed Corporation |
| Bayer AG |
| Namdhari Seeds Pvt. Ltd. |
| Takii & Co. Ltd. |
| East West Seeds India Pvt. Ltd. |
| Others |
Cost & Logistics Intelligence
Biological seed coating actives displacing synthetic chemistries under REACH restrictions simultaneously relocate formulation expertise toward European specialty chemical providers and compress margin structures for legacy coating portfolios. This substitution dynamic concentrates pricing power with reformulation-capable suppliers while forcing breeders to absorb compliance costs or pass through to greenhouse operators.
Pricing Analysis
Technical service contracts and agronomic support bundles drive lifetime value capture beyond the seed unit transaction. Three-tier pricing structure across premium, standard, and economy levels stratifies by trait complexity and germplasm origin, with integrated greenhouse operators in the Netherlands and Spain showing lowest price sensitivity due to labor savings from emergence uniformity. Pricing pressure stems from open pollinated substitution in organic-certified channels where heirloom premiums cannot offset hybrid yield advantages. Smallholder open-field growers in India exhibit highest price sensitivity, prioritizing seed cost per hectare over disease resistance trait density.
Supply Chain Analysis
India and the Netherlands anchor hybrid seed multiplication and greenhouse trial networks respectively. Parent line maintenance draws from geographically concentrated cytoplasmic male-sterile stocks in India, while precision priming technology feeds from Dutch equipment manufacturers and Spanish coating formulators. Single-source vulnerability concentrates in cytoplasmic male-sterile line repositories exposed to regional weather shocks. Distribution runs through proprietary breeder-distributor hierarchies for hybrid varieties, with direct contracting displacing traditional channels among large-scale protected agriculture operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Climate-resilient germplasm development capabilities sit in scarce supply relative to deployment demand, with integrated breeding networks and regulatory affairs infrastructure representing the critical bottleneck assets.
For Market Incumbents: Compound captive greenhouse trial network density across India's protected agriculture clusters to preempt direct contracting losses. Deepen backward integration into seed coating formulation capabilities to capture REACH compliance value rather than outsourcing reformulation costs. Lock in exclusive varietal access agreements with Maharashtra and Karnataka Farmer Producer Organizations before regional specialists consolidate aggregation relationships. For New Entrants and Emerging Players: Lead with pelleting technology integration for mechanized transplanting systems in Mexico's Sinaloa and Baja California greenhouse clusters, where equipment-integrated supply relationships remain underdeveloped. Target organic-certified open pollinated and heirloom segments in North American premium fresh markets, where regulatory barriers filter synthetic-treated competition. Pursue direct-to-farm ecommerce positioning for home gardening packet sales, bypassing distributor markup structures entirely. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors breeders with regulatory affairs scale and captive trial infrastructure. Five-to-ten year viability hinges on CRISPR trait acceleration capabilities and direct contracting relationships with protected agriculture investors. Watch for ECHA substance evaluation program designations as the inflection signal coating chemistry transitions toward biological actives.| Strategic Initiative | Industry Significance |
|---|---|
| Direct Contracting with Greenhouse Operators | Bypasses distributor markups and locks in exclusive varietal access for breeders with trial networks. |
| REACH-Compliant Coating Reformulation | Positions specialty chemical partners to capture value from ECHA-mandated chemistry transitions. |
| CRISPR Trait Development Acceleration | Compresses breeding cycles for drought and disease resistance stacks where regulatory clarity exists. |
| Farmer Producer Organization Aggregation | Concentrates seed demand in India, enabling direct varietal placement and technical service bundling. |
| Seed Priming Technology Deployment | Captures value from greenhouse operators seeking emergence uniformity and transplant scheduling precision. |
Research Approach
Findings reconcile primary fieldwork against secondary review of EU regulatory filings, Indian Central Seed Committee varietal release records, and ECHA substance evaluation documentation. Breeding program directors, protected agriculture greenhouse operators, seed coating formulators, and agricultural cooperative procurement managers provided structured input. Trade data from customs authorities, breeder association membership directories, and greenhouse equipment manufacturer disclosures supplied validation. Bottom-up variety deployment tracking triangulates against top-down cultivation area estimates.
Segmentation dimensions modeled include seed type, cultivation system, treatment technology, and customer procurement scale across the projection horizon. CAGRs derive from varietal adoption curves, protected agriculture infrastructure investment pipelines, and regulatory compliance cost absorption trajectories. Forecast inputs incorporate greenhouse operator direct contracting velocity, Farmer Producer Organization formation rates, and ECHA substance evaluation timelines.
Forecasts assume regulatory continuity in EU REACH authorization pathways and Indian BIS certification procedures; material policy shifts would require re-modeling. Specific risks include asynchronous trait approval across export destinations, cytoplasmic male-sterile line disease outbreaks, and organic certification standard revisions. Recalibration cycles align with material shifts in protected agriculture subsidy programs and ECHA substance evaluation designations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Cover Crop Seed Varieties Market
Seeds
United States Garden Seeds Market
Seeds
Flaxseed (Linseed) Market
Seeds
Hemp Seeds Market
Seeds
Organic Chia Seeds Market
Seeds
North America Seeds Market
Seeds
Flower Seed Market
Seeds
North America Chia Seeds Market
Seeds
E. Angustifolium Market
Seeds
India Forage Seed Market
Seeds
Drought Tolerant Seeds Market
Seeds
Carrot Seed Oil Market
Seeds
Watermelon Seeds Market
Seeds
Europe Cannabis Seeds Market
Seeds
North America Forage Seed Market
Seeds
South America Forage Seed Market