
 North America Hemp Market | 2026-2036
North America Hemp Market Size, Share, and Industry Trends Forecast 2026-2036
North America Hemp Market Intelligence
Extraction technology standardization is narrowing the gap between small-batch processors and industrial-scale operators across the hemp value chain. Curaleaf Holdings leverages its multi-state operational footprint to secure consistent biomass supply. Green Thumb Industries anchors its position through controlled-environment cultivation protocols. Charlotte's Web Holdings differentiates via vertically integrated seed-to-shelf quality systems.
Hemp comprises the Cannabis sativa L. plant containing less than 0.3% delta-9 tetrahydrocannabinol by dry weight, cultivated for fiber, seed, and cannabinoid extraction through retting, decortication, or supercritical CO2 processing. Hemp fiber serves composite manufacturers seeking lower embodied carbon than glass fiber reinforcement. Hemp seeds and hemp oil lead product type revenue pools due to established food-grade certification pathways. Building materials application shows the fastest structural growth as biobased insulation and hempcrete gain code acceptance in residential construction.
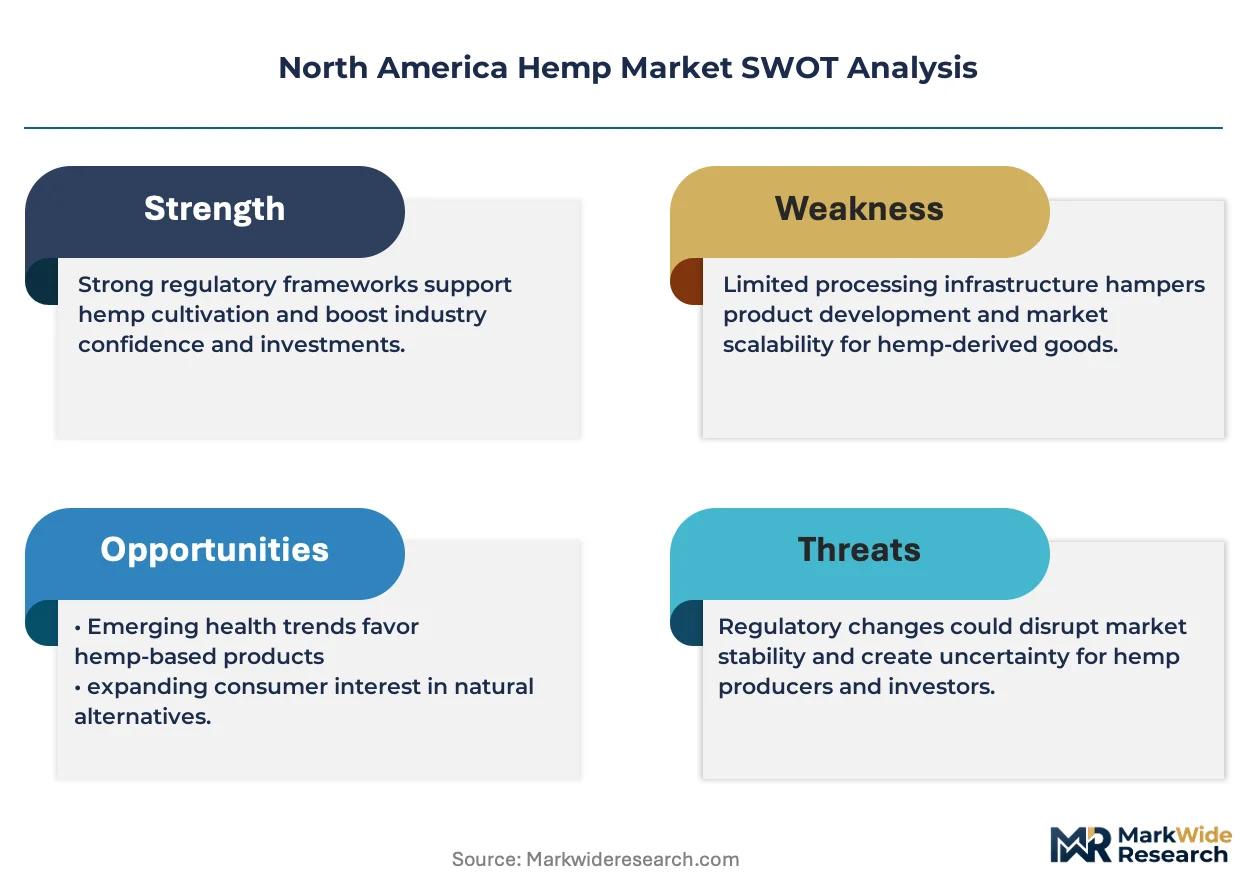
The USDA oversees hemp cultivation licensing under the 2018 Farm Bill, while the FDA regulates cannabinoid-infused food and cosmetic products, creating a bifurcated compliance landscape that elevates testing and documentation costs. State agriculture departments in Colorado, Kentucky, and Oregon impose additional THC testing protocols that shape regional supply availability. Stakeholders must monitor pending FDA rulemaking on cannabidiol dosage and labeling to anticipate channel access shifts.
Market Dynamics
Extraction technology standardization is compressing margins for small-batch hemp processors while amplifying throughput advantages for industrial-scale operators across the North American value chain.
Growth Catalysts
- The 2018 Farm Bill framework:USDA licensing protocols have unlocked interstate commerce for hemp biomass, enabling processors in Kentucky to source fiber from Montana growers without state-by-state permitting barriers.
- Food and beverage reformulation:Plant-based protein demand from manufacturers is pulling hemp seed and hemp oil volumes through established food-grade certification pathways.
- Midwest processing infrastructure clustering:Agronomic expertise and cooperative networks around established hemp-growing regions are reducing per-unit logistics costs for fiber and cannabinoid extraction.
Market Restraints
- THC testing protocol fragmentation:Colorado, Kentucky, and Oregon impose divergent state-level THC thresholds that create compliance friction and limit cross-border shipment flexibility.
- Supercritical CO2 equipment capex intensity:Industrial-scale extraction systems require capital deployment that excludes mid-tier processors from cannabinoid isolation markets.
- Glass fiber substitution economics:Hemp fiber reinforcement faces persistent cost disadvantages against incumbent composite materials in automotive and construction applications.
Strategic Opportunities
- Biobased insulation code acceptance:Residential construction jurisdictions are adopting hempcrete and hemp-wool insulation into building codes, creating material specification pathways previously closed to plant-based alternatives.
- FDA cannabinoid rulemaking completion:Pending dosage and labeling regulations for cannabidiol-infused products will clarify channel access rules for food and cosmetic manufacturers.
- Retting and decortication automation:Convergence of optical sorting and mechanical fiber separation technologies is reducing labor dependency in hemp stalk processing.
Industry Challenges
- Seed genetics standardization gaps:Lack of certified cultivars with consistent cannabinoid and fiber profiles forces processors to manage input variability through batch-level adjustments.
- Dual-use facility compliance complexity:Operators serving both food-grade and cosmetic cannabinoid markets must maintain parallel documentation systems under bifurcated FDA and USDA oversight.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Hemp Market |
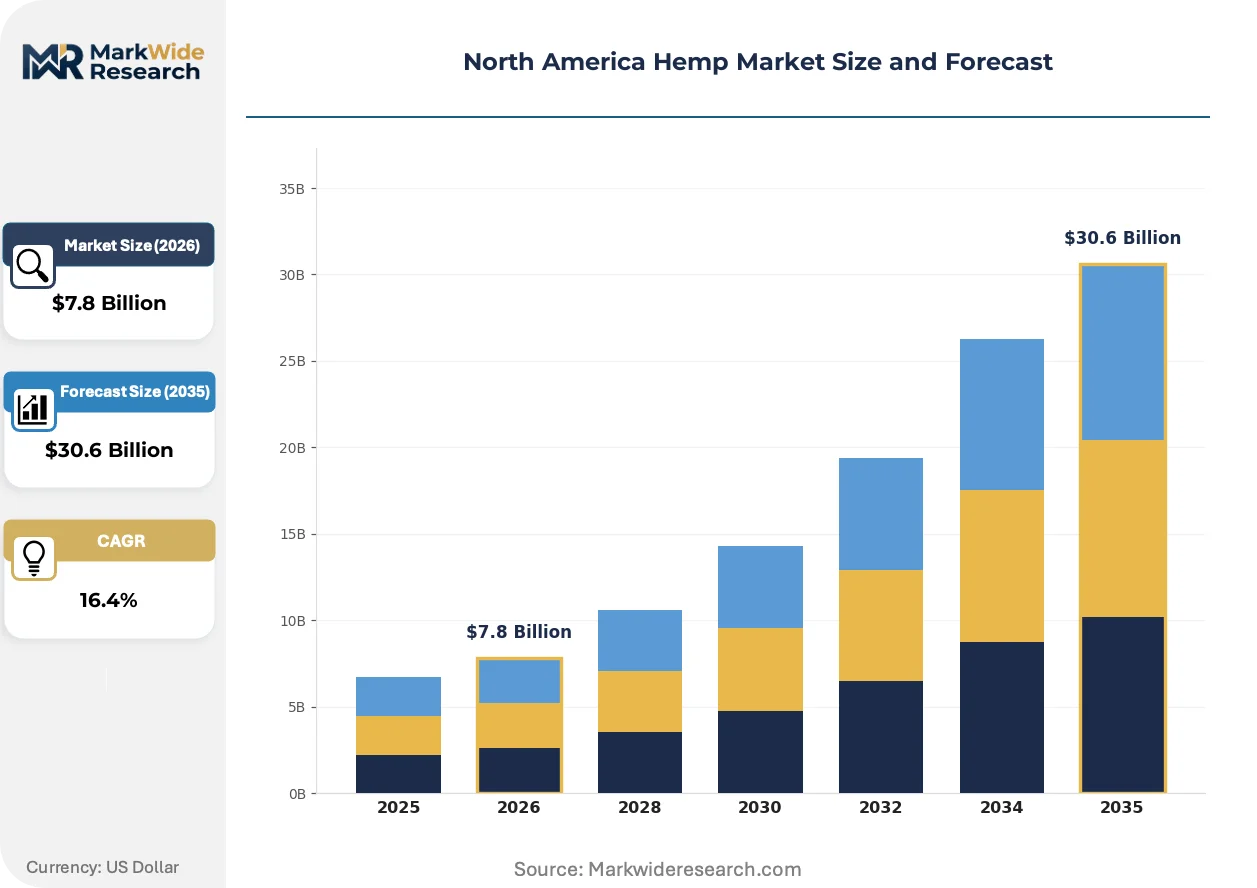
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $30.6 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hemp Seeds, Hemp Oil, Hemp Fiber, Hemp Protein Application: Textiles, Food & Beverages, Cosmetics, Building Materials Distribution Channel: Online Retail, Retail Stores, Wholesale Distributors, Direct Sales End User: Agriculture, Food Industry, Personal Care, Construction |
| Companies Covered | Curaleaf Holdings, Green Thumb Industries, Canopy Growth Corporation, Aurora Cannabis, Fresh Hemp Foods Ltd., Blue Sky Hemp Ventures Ltd., The Cronos Group, Trulieve Cannabis, Charlotte's Web Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Hemp Market Strategic Shifts & Innovations
Automation and regulatory clarification are the twin forces compressing decision timelines across hemp cultivation, processing, and product formulation in North America.
Supercritical CO2 extraction with integrated winterization is collapsing the capability gap between boutique cannabinoid processors and pharmaceutical-grade operators. Food and beverage manufacturers seeking THC-compliant CBD inputs are adopting these systems at accelerated procurement cycles. The technology is collapsing quality assurance timelines from months to weeks for ingredient qualification.
The FDA's pending cannabinoid rulemaking is forcing food and cosmetic manufacturers to build dual-labeling systems ahead of final guidance. Industrial consequence includes frozen new product development pipelines and inventory write-down risks for non-compliant stock. The dietary supplement channel is most affected, with brands diverting R&D spend toward EU Novel Food dossier preparation as a hedge against US regulatory delay.
Buyer concentration among national food manufacturers is compressing supplier qualification timelines from multi-year to single-cycle evaluations. Regional hemp cooperatives that previously sold to fragmented local buyers now face consolidated procurement desks demanding certified seed-to-shelf traceability. This pattern is most visible in the American Midwest, where processor cooperative membership has shifted from farmer-owned to strategic supply agreements with CPG holding companies.
North America Hemp Market Segmentation
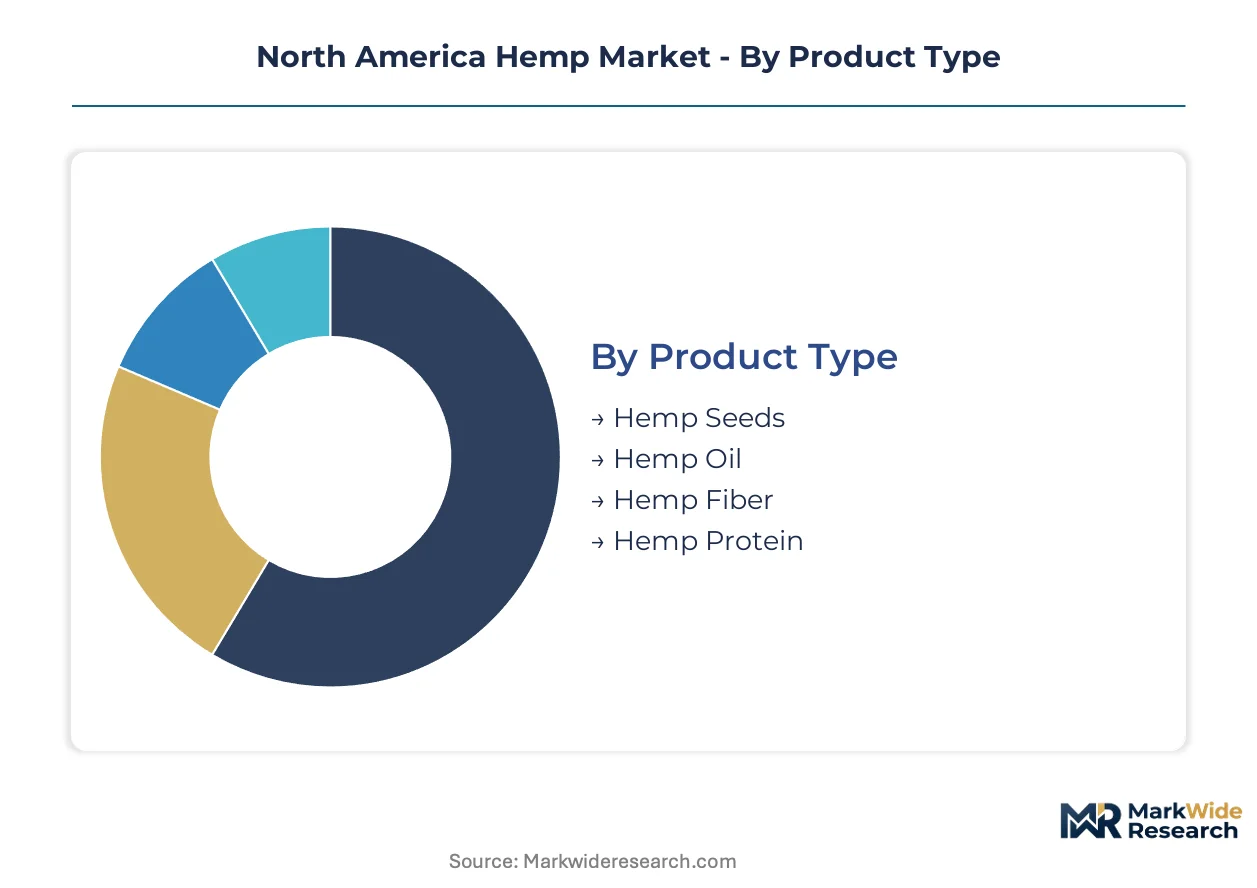
Hemp market segmentation reveals how product specifications, application requirements, and channel economics fragment buyer priorities across the North American value chain. Distinct compliance pathways for food-grade versus industrial applications create non-overlapping procurement criteria that shape supplier positioning.
Product Type:
Cost tier differentiation separates commodity-grade outputs from certified organic and pharmaceutical-grade specifications.
- Hemp Seeds:Whole and hulled seeds carry food-grade certification pathways including USDA Organic and Non-GMO Project verification. Food and beverage manufacturers in the American Midwest source these through established cooperative networks that manage THC compliance documentation.
- Hemp Oil:Cold-pressed and refined oil variants serve cosmetic formulators and dietary supplement brands with divergent fatty acid profile requirements. The FDA's pending cannabinoid rulemaking is freezing new product development pipelines for infused formulations.
- Hemp Fiber:Bast and hurd fractions supply composite manufacturers and construction material producers with distinct length and cellulose specifications.
- Hemp Protein:Concentrated protein powder isolates target sports nutrition and plant-based meat alternative applications with amino acid completeness claims.
Hemp seeds hold installed capacity. Hemp protein is rotating up the share rankings.
Application:
End-use specifications determine whether processors pursue food-grade, cosmetic, or industrial compliance certifications.
- Textiles:Fiber length and tensile strength requirements from apparel and technical fabric manufacturers drive decortication equipment selection. Kentucky and Oregon processing facilities serve regional textile clusters with varying retting protocol standards.
- Food & Beverages:THC threshold compliance and GRAS self-determination documentation dominate procurement criteria for ingredient buyers. National CPG manufacturers compress supplier qualification timelines through consolidated procurement desks.
- Cosmetics:INCI nomenclature compliance and EU Novel Food dossier preparation absorb R&D expenditure for brands hedging against US regulatory delay.
- Building Materials:Hempcrete and biobased insulation specifications are gaining residential code acceptance in multiple jurisdictions. This application climbs the fastest as carbon accounting drives material substitution decisions.
Food and beverages hold installed capacity. Building materials is rotating up the share rankings.
Distribution Channel:
Channel selection reflects buyer scale, documentation requirements, and geographic proximity to processing infrastructure.
- Online Retail:Direct-to-consumer platforms serve supplement and cosmetic brands with batch-level certificate of analysis requirements. These channels concentrate demand from coast-adjacent metropolitan markets with established cannabinoid product familiarity.
- Retail Stores:Natural products and specialty grocery chains demand shelf-stable packaging and uniform labeling compliant with pending FDA guidance.
- Wholesale Distributors:Ingredient brokers manage THC testing documentation across state lines for food manufacturers lacking in-house compliance infrastructure.
- Direct Sales:Processor cooperatives in the American Midwest maintain strategic supply agreements with CPG holding companies that bypass traditional distribution markups.
Wholesale distributors hold installed capacity. Direct sales is rotating up the share rankings.
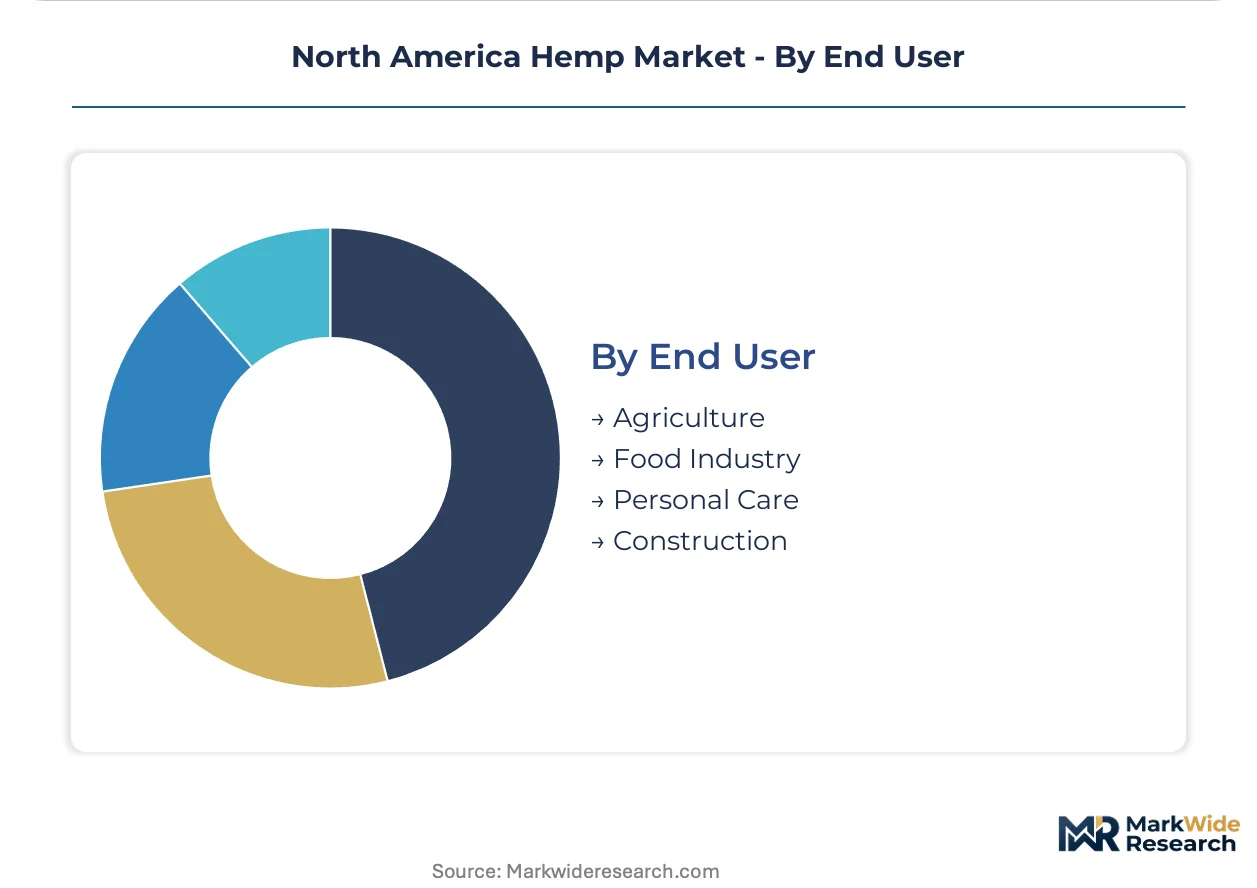
End User:
Customer type determines whether hemp inputs enter regulated food systems, unregulated industrial supply chains, or export-oriented cosmetic channels.
- Agriculture:Seed and fiber producers supply certified cultivars to licensed growers under USDA Farm Bill protocols. Colorado and Kentucky agriculture departments impose additional THC testing that shapes regional supply availability.
- Food Industry:Plant-based protein demand from national manufacturers pulls hemp seed and oil volumes through established certification pathways.
- Personal Care:Cosmetic formulators require INCI-compliant ingredient nomenclature and stability testing documentation for shelf-life claims.
- Construction:Residential builders and insulation contractors specify hempcrete and hemp-wool products as jurisdictions adopt biobased material codes.
Agriculture holds installed capacity. Construction is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food and beverage manufacturers concentrate procurement power in the American Midwest, where hemp processing cooperatives cluster around established agronomic expertise. Construction material buyers in the Mountain West and Pacific Northwest drive specification shifts toward biobased insulation. Canadian prairie provinces anchor fiber production capacity for cross-border textile supply chains.
United States
The American Midwest dominates hemp seed and oil processing, with Kentucky and Colorado agriculture departments imposing additional THC testing protocols that shape regional supply availability. USDA Farm Bill licensing enables interstate commerce, allowing Montana fiber growers to supply Kentucky decortication facilities without state-by-state permitting barriers. Chicago-area food manufacturers compress supplier qualification timelines through consolidated procurement desks demanding certified seed-to-shelf traceability.
Canada
Alberta and Saskatchewan prairie provinces anchor industrial hemp fiber production for North American textile and composite supply chains. Health Canada and the PMRA oversee cultivation licensing with THC threshold compliance frameworks that align with USDA protocols for seamless cross-border shipment. Winnipeg and Regina processing facilities serve as consolidation points for prairie-grown bast fiber destined for automotive composite manufacturers in Ontario and Michigan.
Mexico
Jalisco and Nuevo León states emerge as hemp cultivation zones serving Mexican food and cosmetic manufacturers seeking regional cannabinoid inputs. The country's national agricultural regulator implements THC testing standards that facilitate export-oriented production for US supplement brands. Guadalajara-area processing infrastructure clusters around established agro-industrial expertise from tequila and agricultural export sectors.
North America Hemp Market Key Industry Players
Channel-controlling players compete with product-specialist players across a market structure that fragments between multi-state operators and regional cooperatives. Consolidation pressure concentrates among food-grade processors seeking USDA Organic certification pathways, while fiber specialists maintain cooperative ownership structures. Two strategic archetypes dominate: vertically integrated seed-to-shelf operators and extraction-technology licensors. Competitive moves center on strategic supply agreements with CPG holding companies and automation investments in retting and decortication equipment.
Among North American cannabis-sector operators, Curaleaf Holdings, Green Thumb Industries, and Charlotte's Web Holdings occupy positions representing distinct strategic archetypes. Curaleaf exemplifies the multi-state operational footprint model securing consistent biomass supply across jurisdictions. Green Thumb anchors the controlled-environment cultivation protocol specialization. Charlotte's Web represents vertically integrated quality system differentiation from seed genetics through retail shelf placement. These three sit within a competitive set where geographic coverage and compliance infrastructure determine procurement desk access.
| Leading Market Players |
|---|
| Curaleaf Holdings |
| Green Thumb Industries |
| Canopy Growth Corporation |
| Aurora Cannabis |
| Fresh Hemp Foods Ltd. |
| Blue Sky Hemp Ventures Ltd. |
| The Cronos Group |
| Trulieve Cannabis |
| Charlotte's Web Holdings |
| Others |
Cost & Logistics Intelligence
Kentucky's hemp processing corridor concentrates decortication capacity and supercritical CO2 extraction infrastructure, giving Midwest cooperatives leverage over national CPG procurement desks seeking certified seed-to-shelf traceability. This geographic clustering compresses logistics costs but also concentrates pricing power among established operators with USDA Organic certification pathways.
Pricing Analysis
Cost-plus contracts indexed to USDA hemp spot prices dominate biomass transactions between Montana fiber growers and Kentucky processors, with quality premiums attaching to certified organic and pharmaceutical-grade specifications. Price differentiation rests on THC compliance documentation and food-grade certification tiers, with cold-pressed hemp oil commanding spreads over refined variants due to fatty acid profile verification. Pricing pressure stems from supercritical CO2 equipment capex intensity excluding mid-tier processors, forcing margin compression at the standard grade. National food manufacturers exhibit lowest price sensitivity due to consolidated procurement timelines, while regional cosmetic formulators face highest sensitivity given frozen R&D pipelines pending FDA rulemaking.
Supply Chain Analysis
Export-control restrictions on supercritical CO2 extraction technology limit equipment flows to Canadian and Mexican processing facilities, reinforcing US domestic capacity advantages. Geographic supply concentrates in the United States, Canada, and Mexico, with Alberta prairie provinces anchoring bast fiber production for cross-border textile supply chains. Raw material dependencies include certified seed genetics, food-grade processing equipment, and GRAS self-determination documentation. Single-source vulnerability runs through Midwest cooperative networks serving consolidated CPG procurement desks. Distribution runs through wholesale ingredient brokers managing THC testing documentation across state lines for food manufacturers lacking in-house compliance infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across state-level THC testing protocols and pending FDA cannabinoid rulemaking creates niche entry points for specialists with compliance infrastructure. Food and beverage reformulation toward plant-based proteins is pulling demand through non-overlapping procurement criteria that favor regional cooperatives over national distributors.
For Market Incumbents: Pre-empt margin erosion from extraction technology standardization by securing strategic supply agreements with CPG holding companies before buyer consolidation completes. Invest in automated retting and decortication equipment to defend fiber processing share against glass fiber substitution economics. Kentucky and Colorado operators should deepen backward integration into certified seed genetics to reduce input variability batch-level adjustments. For New Entrants and Emerging Players: Mexican hemp cultivation zones in Jalisco and Nuevo León represent the most penetrable entry point for export-oriented cannabinoid production serving US supplement brands with Health Canada-aligned THC protocols. Building materials applications in the Mountain West offer white-space specification opportunities as jurisdictions adopt hempcrete into residential codes. Go-to-market execution should anchor on direct sales agreements with regional insulation contractors bypassing traditional distribution markups. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated seed-to-shelf operators with captive supply agreements and USDA Organic certification pathways. Long-term viability across the analysis window favors acquisition targets with multi-state licensing footprints and in-house supercritical CO2 processing capacity. Watch for FDA cannabinoid rulemaking completion as the inflection signal unlocking frozen food and cosmetic new product development pipelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Seed Genetics | Reduces input variability for processors facing USDA THC testing protocols. |
| Automation Investment in Retting Equipment | Collapses labor dependency for Kentucky and Oregon fiber facilities serving textile clusters. |
| Strategic Supply Agreement with CPG Holding Companies | Secures channel access ahead of buyer consolidation in the American Midwest. |
| EU Novel Food Dossier Preparation | Hedges US regulatory delay for dietary supplement brands seeking alternative market access. |
| Direct Sales Channel Development | Bypasses wholesale distributor markups for construction material buyers specifying hempcrete. |
Research Approach
Cross-validation between primary interviews with hemp cultivation licensing officers, food-grade processing facility managers, and CPG procurement directors anchors the qualitative findings against secondary sources including USDA Farm Bill implementation records, FDA cannabinoid guidance dockets, and state agriculture department THC testing protocols. Bottom-up triangulation from processor cooperative membership data and top-down validation from trade flow analysis ensure segmentation integrity across product type, application, and distribution channel dimensions.
Calibration against historical Farm Bill implementation cycles and pending regulatory rulemaking timelines shapes the analytical framework across the projection horizon. Segmentation modeling incorporates product grade tier, end-use compliance pathway, regional processing infrastructure density, and buyer consolidation stage. CAGRs derive from biomass volume trajectories, food and beverage reformulation adoption curves, and building materials code acceptance patterns without year-specific anchoring.
Practitioners should monitor FDA cannabinoid dosage and labeling rulemaking, state-level THC threshold harmonization efforts, and supercritical CO2 equipment import policy shifts for early signals of forecast revision. Material shifts in Farm Bill reauthorization provisions or interstate commerce precedent would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
China Compound Feed Market
Agriculture and Agri Products
Uruguay Agricultural Products Market
Agriculture and Agri Products
Greenhouse Market
Agriculture and Agri Products
Flower Pot Market
Agriculture and Agri Products
Canada Bamboos Market
Agriculture and Agri Products
Sugar Cane Market
Agriculture and Agri Products
Alfalfa Pellets Market
Agriculture and Agri Products
Colombia Floriculture Market
Agriculture and Agri Products
Australia Floriculture Market
Agriculture and Agri Products
Africa Rice Market
Agriculture and Agri Products
Plant Antifreeze Market
Agriculture and Agri Products
Lucerne Market
Agriculture and Agri Products
Beet Pulp Market
Agriculture and Agri Products
Netherlands Cashew Market
Agriculture and Agri Products
Agriculture in Egypt Market
Agriculture and Agri Products
Potting Soil Market