
 Global Wheat Seed Market | 2026-2036
Global Wheat Seed Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wheat Seed Market Outlook
OECD Seed Scheme certification is rotating competitive access across the wheat seed value chain, favoring breeders with multi-country varietal portfolios. Groupe Limagrain leverages its integrated research stations across France and India to sustain germplasm leadership in durum and bread wheat. Corteva Agriscience anchors North American hybrid wheat development through proprietary cytoplasmic male sterility platforms. KWS SAAT competes in European winter wheat with a dense network of regional testing stations.
Wheat seed comprises the reproductive grain of Triticum aestivum and related species, selected for genetic purity exceeding 98%, germination rates above 85%, and specific weight thresholds that determine sowing viability and field establishment consistency. Its commercial purpose centers on transferring improved yield potential, disease resistance, and abiotic stress tolerance from breeding programs into agricultural production systems. Hybrid wheat commands premium positioning due to technical complexity in seed production and proprietary parental line control, while open-pollinated varieties dominate volume in developing markets where farmer-saved seed persists. The flour milling end-use segment concentrates margin pools around protein content and gluten strength specifications that contract growers must meet.
The OECD Seed Schemes, EU Seed Marketing Directives, and India's BIS certification requirements collectively govern cross-border seed movement, varietal identity standards, and phytosanitary market access. These frameworks elevate compliance costs for smaller breeders while creating structural advantages for operators with dedicated regulatory affairs capacity across multiple jurisdictions. Stakeholders must monitor evolving national-level restrictions on genome-edited varieties, as divergent classification decisions between major wheat-producing countries will fragment seed trade corridors and reshape breeding investment priorities.
Market Dynamics
Certified seed procurement mandates from commercial flour milling operations are compressing farmer-saved seed volumes and concentrating varietal registration power among breeders with multi-jurisdictional compliance capacity.
Growth Catalysts
- OECD Seed Scheme harmonization:Cross-border varietal recognition protocols reduce re-registration costs for certified seed exporters operating across France, Germany, and Australia.
- Indian state university breeder programs:Accelerated foundation seed multiplication at Punjab Agricultural University and Indian Agricultural Research Institute expands certified seed penetration in Haryana and Uttar Pradesh.
- Hybrid cytoplasmic male sterility platforms:Proprietary CMS systems enable commercial-scale hybrid wheat seed production with controlled pollination and genetic purity enforcement.
Market Restraints
- Parental line supply concentration:Maintainer and restorer germplasm for hybrid systems concentrates among three institutional breeding networks, creating royalty stacking and access bottlenecks.
- EU Seed Marketing Directive varietal registration costs:Distinctness, uniformity, and stability testing protocols impose EUR 80,000-150,000 per candidate variety, excluding smaller public breeding programs.
- Farmer-saved seed persistence:Open-pollinated bread wheat varieties in developing markets sustain 40-60% farm-retention rates, compressing commercial seed addressable volume.
Strategic Opportunities
- India's BIS certification expansion:Mandatory truth-in-labeling for certified seed creates first-mover advantage for breeders with existing Indian field testing infrastructure.
- Genome-edited variety regulatory clarity:Divergent classification pathways between USDA, EFSA, and China's MEE create jurisdiction arbitrage for gene-edited drought-tolerance traits.
- Direct-to-farm digital seed platforms:Agritech marketplaces in Brazil and Argentina bypass cooperative aggregators, capturing margin from disintermediated certified seed distribution.
Industry Challenges
- Seed pathogen certification timelines:Loose smut and common bunt testing protocols add 18-24 months to commercial release schedules, compressing effective patent life for proprietary varieties.
- Parental line IP enforcement complexity:Cytoplasmic male sterility system licensing disputes between public research institutions and commercial breeders delay hybrid platform deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wheat Seed Market |
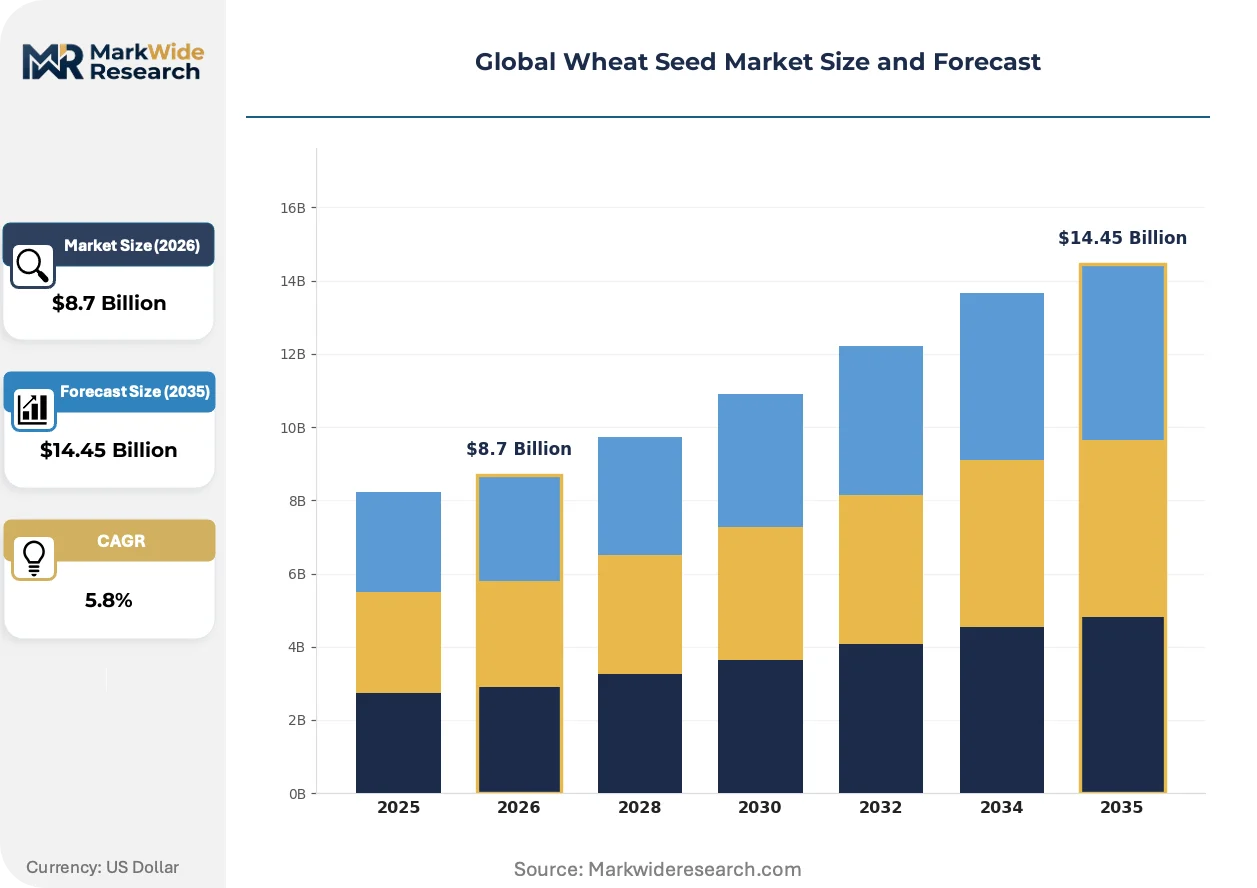
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hybrid, Open-Pollinated, GM, Others End Use: Food Production, Feed, Biofuel, Flour Milling Distribution Channel: Direct Sales, Retail, Online, Wholesale Geographical Focus: North America, Europe, Asia-Pacific, Latin America |
| Companies Covered | Groupe Limagrain, Florimond Desprez, Corteva Agriscience, RAGT Group, BASF SE, Bayer, KWS SAAT, Advanta Seeds, Syngenta Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wheat Seed Market Strategic Shifts
Gene-editing tools and digital phenotyping platforms are compressing varietal development cycles while regulatory fragmentation around edited varieties is reshaping breeding investment geography.
CRISPR-Cas9 and TALEN systems for targeted gluten strength and Fusarium resistance modification are displacing decade-long backcrossing programs at European and North American breeding stations. Commercial seed producers in France and Canada are adopting edited lines for powdery mildew resistance, accelerating variety turnover from 12 years to 7-8 years. This compression is concentrating R&D among entities with stacked molecular breeding and regulatory affairs capabilities.
EU F-Gas Regulation phase-down schedules and REACH chemical authorization restrictions are eliminating several legacy seed treatment actives for bunt and smut control. Seed coating formulators are pivoting to biological alternatives and physical seed disinfection, with treated seed volumes in Germany and Poland shifting toward hot water and electron beam methods. The transition elevates capital requirements for treatment infrastructure and favors integrated seed production facilities over standalone conditioners.
Flour millers in Turkey and Egypt are tightening protein content and falling number specifications in forward purchase contracts, forcing contract growers toward certified varieties with documented gluten strength profiles. This specification creep is displacing informal seed sourcing through local traders and elevating direct breeder-grower contracting with embedded quality testing. The shift is most pronounced in Anatolia and the Nile Delta, where miller consolidation has reduced supplier counts by 30-40% over five years.
Global Wheat Seed Market Segmentation
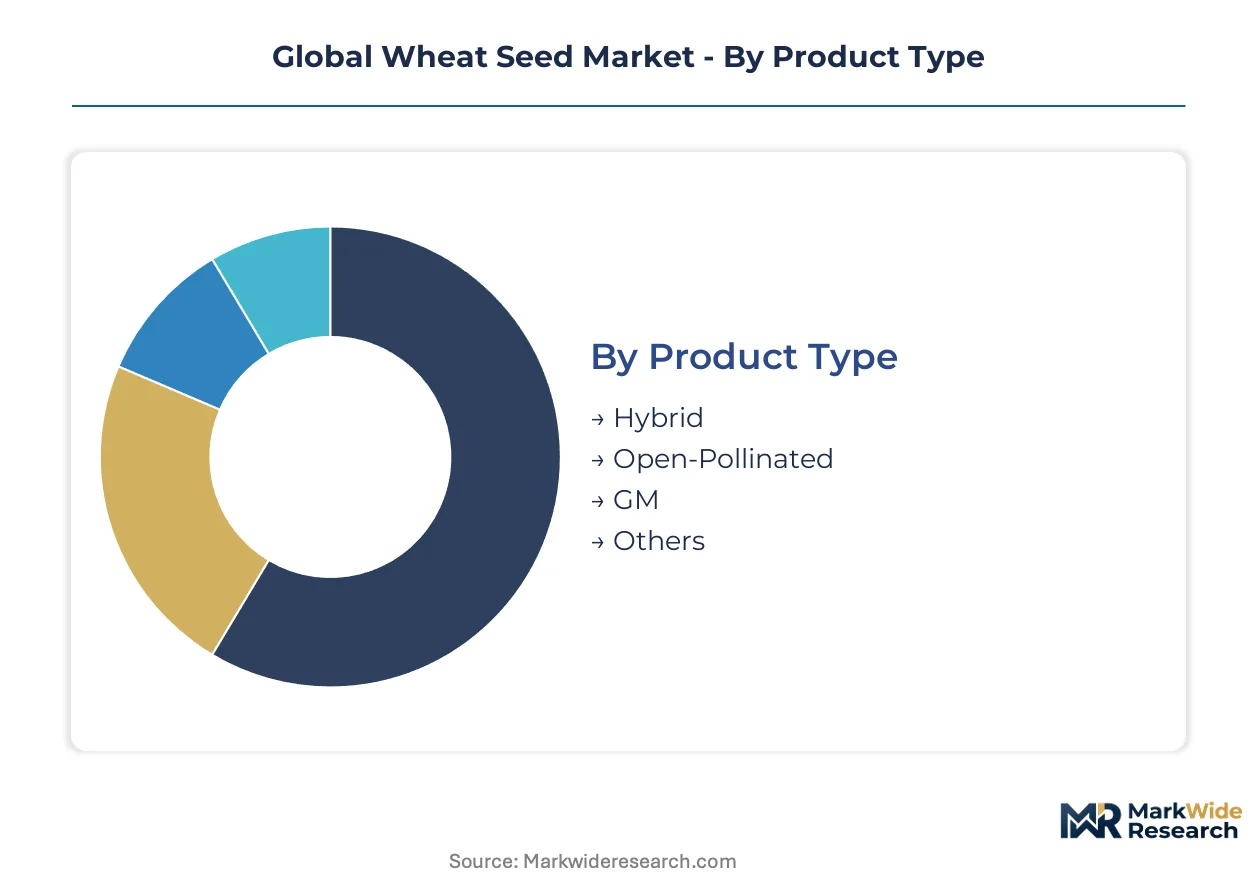
Segmentation in wheat seed markets reveals how technical complexity, regulatory boundaries, and procurement channel power reshape competitive access. Breeders must align R&D portfolios with the specific compliance, pricing, and performance tiers where margin pools concentrate.
Product Type:
Hybrid systems face acute substitution pressure from open-pollinated varieties where farmer-saved seed networks remain entrenched, forcing proprietary platform holders to defend value through yield guarantees and bundled agronomy services.
- Hybrid:Cytoplasmic male sterility systems enable controlled pollination with genetic purity enforcement above 98%. Demand clusters in North American Great Plains contract farming operations where flour millers mandate certified high-performance varieties with documented gluten strength profiles.
- Open-Pollinated:Self-fertile varieties permit farmer seed retention across generations without yield penalty. Penetration concentrates in India's Haryana and Uttar Pradesh state university networks, where accelerated foundation seed multiplication programs expand certified distribution despite 40-60% farm-retention persistence.
- GM:Transgenic trait stacks for herbicide tolerance and Fusarium resistance face fragmented regulatory acceptance across major wheat-producing jurisdictions.
- Others:Genome-edited lines with targeted drought-tolerance modifications occupy classification uncertainty zones between conventional and GM regulatory pathways.
Open-pollinated varieties retain volume leadership across developing markets; hybrid platforms hold the steepest expansion curve where commercial milling procurement mandates compress informal seed sourcing.
End Use:
Cost tier stratification separates specification-intensive milling contracts from commodity feed and biofuel offtake where varietal identity requirements relax.
- Food Production:Direct human consumption varieties face stringent mycotoxin limits and protein content floors. Procurement concentrates in Turkey's Anatolia region and Egypt's Nile Delta, where consolidated millers have reduced supplier counts by 30-40% through embedded quality testing and direct breeder-grower contracting.
- Flour Milling:Specialized varieties with documented falling numbers and gluten strength specifications command premium positioning. Forward purchase contracts in France and Germany now require OECD Seed Scheme certification and varietal identity preservation through chain-of-custody documentation.
- Feed:Lower protein thresholds and relaxed gluten specifications permit broader varietal sourcing from regional testing station networks.
- Biofuel:Starch content optimization for ethanol conversion drives demand for high-yielding feedstock varieties with minimal quality premiums.
Food production retains volume leadership across certified seed markets; flour milling holds the steepest expansion curve as specification creep displaces informal trader networks.
Distribution Channel:
Channel margin capture diverges sharply between cooperative aggregator systems and disintermediated digital platforms, with infrastructure investment requirements determining viable participation.
- Direct Sales:Breeder-to-grower contracting with embedded agronomy advisory and quality testing protocols. Dominates in France, Germany, and Australia where OECD Seed Scheme harmonization reduces cross-border re-registration costs for certified seed exporters.
- Wholesale:Cooperative and dealer network aggregation with volume-based pricing tiers and seasonal credit extension. Concentrates in North American winter wheat belts and European Union member state distribution systems.
- Retail:Independent agro-dealer storefronts with limited technical advisory capacity and generic variety portfolios.
- Online:Agritech marketplaces in Brazil and Argentina bypass cooperative aggregators, capturing margin from disintermediated certified seed distribution through direct-to-farm logistics integration.
Wholesale channels retain volume leadership across established wheat belts; online platforms are gaining share fastest where mobile penetration and logistics fragmentation create digital arbitrage opportunities.
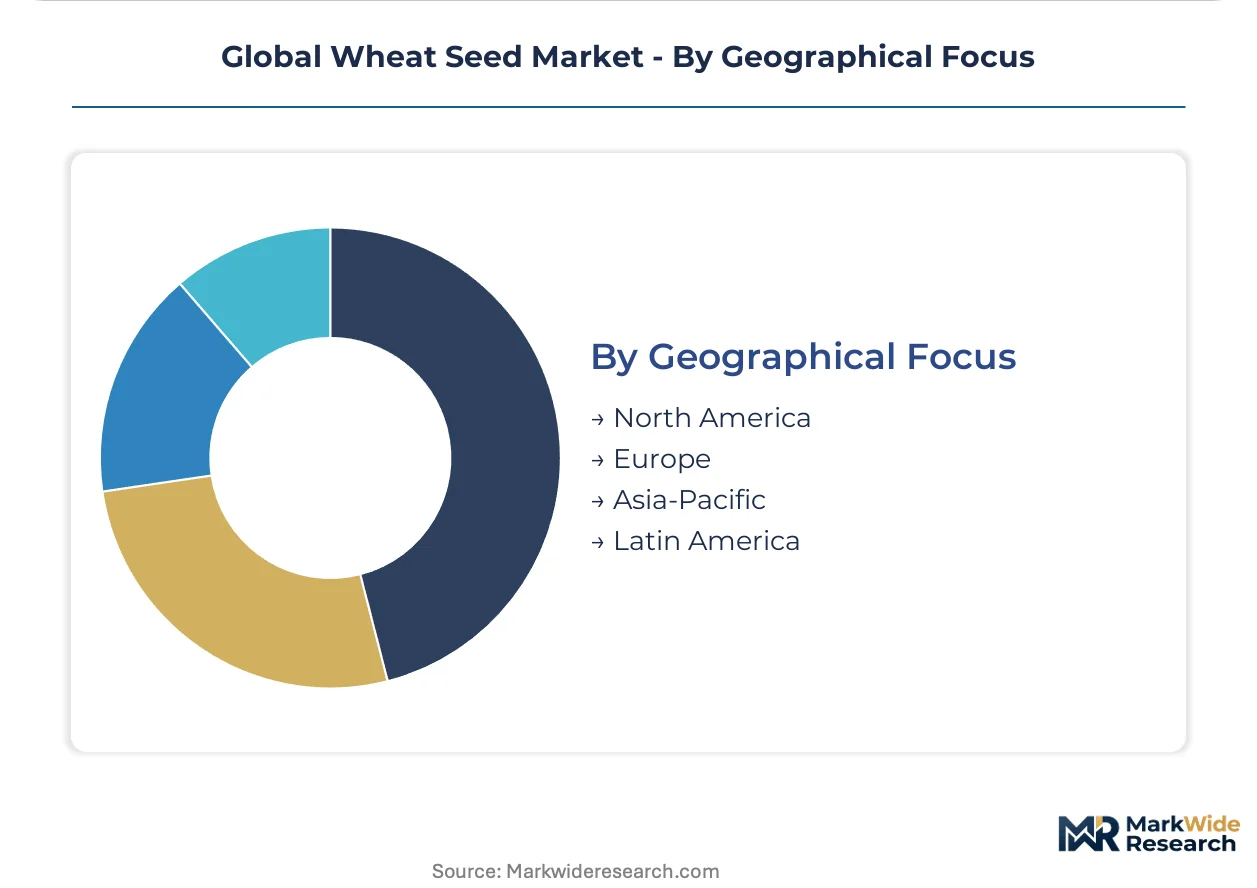
Geographical Focus:
Supply concentration and regulatory capacity determine which geographies sustain premium positioning versus commodity pricing pressure.
- North America:Hybrid wheat development anchors through proprietary cytoplasmic male sterility platforms, with Corteva Agriscience and integrated research stations driving commercial-scale seed production. USDA regulatory clarity on genome-edited varieties attracts breeding investment toward drought-tolerance trait development.
- Europe:EU Seed Marketing Directives and REACH chemical authorization restrictions eliminate legacy seed treatment actives, elevating capital requirements for biological coating and physical disinfection infrastructure. EFSA classification decisions on edited varieties fragment trade corridors with divergent national pathways.
- Asia-Pacific:India's BIS certification expansion and state agricultural university breeder programs accelerate certified seed penetration. China's MEE regulatory stance on gene-edited crops creates uncertainty for cross-border germplasm movement.
- Latin America:Direct-to-farm digital seed platforms in Brazil and Argentina disintermediate cooperative aggregators, with agritech marketplaces capturing margin from streamlined certified seed distribution.
Europe retains volume leadership in high-specification certified seed; Asia-Pacific holds the steepest expansion curve as India's breeder multiplication programs and BIS truth-in-labeling mandates compress farmer-saved seed persistence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's BIS certification mandates and state university breeder programs are accelerating certified seed penetration, while divergent regulatory pathways for genome-edited varieties fragment cross-border germplasm trade corridors.
United States
Commercial flour millers in the Great Plains mandate certified high-performance varieties with documented gluten strength profiles. USDA regulatory clarity on genome-edited drought-tolerance traits attracts breeding investment toward proprietary trait development. Corteva Agriscience anchors hybrid wheat platforms through cytoplasmic male sterility systems in Iowa and Nebraska research stations.
France
Groupe Limagrain leverages integrated research stations across the Auvergne-Rhône-Alpes region for durum and bread wheat germplasm leadership. EU Seed Marketing Directives impose EUR 80,000-150,000 per variety for distinctness, uniformity, and stability testing. The Paris Basin concentrates OECD Seed Scheme-certified seed production for cross-border export to Germany and Australia.
India
Punjab Agricultural University and Indian Agricultural Research Institute accelerate foundation seed multiplication programs in Haryana and Uttar Pradesh. BIS truth-in-labeling mandates for certified seed create first-mover advantage for breeders with existing field testing infrastructure. Farmer-saved seed persistence sustains 40-60% retention rates, compressing commercial addressable volume.
Germany
KWS SAAT competes in European winter wheat through a dense network of regional testing stations across Lower Saxony and Bavaria. EU F-Gas Regulation phase-down eliminates legacy seed treatment actives, elevating capital requirements for biological coating infrastructure. The North German Plain shifts treated seed volumes toward hot water and electron beam disinfection methods.
Australia
OECD Seed Scheme harmonization reduces re-registration costs for certified seed exporters operating across state boundaries. Direct breeder-to-grower contracting with embedded agronomy advisory dominates in New South Wales and Victoria. The Wheatbelt region concentrates premium positioning around protein content specifications for Asian flour milling offtake.
Global Wheat Seed Market Competitive Environment
Player mix skews toward integrated breeding networks with multi-jurisdictional regulatory affairs capacity. Two structural tiers have emerged: proprietary hybrid platform holders with cytoplasmic male sterility control, and open-pollinated variety specialists with dense regional testing infrastructure. Strategic archetypes include germplasm aggregators, regulatory compliance specialists, and direct-to-farm digital distributors. Competitive moves concentrate on M&A for parental line portfolios and capacity expansion in biological seed treatment infrastructure.
Within the integrated breeding network tier, Groupe Limagrain and Corteva Agriscience exemplify divergent geographic anchoring strategies. Limagrain occupies a position bridging French and Indian research infrastructure, while Corteva represents North American hybrid platform development. KWS SAAT sits within the European winter wheat specialization archetype, with regional testing density as its structural differentiator. These three entities illustrate how regulatory affairs capacity across multiple OECD Seed Scheme jurisdictions creates sustainable competitive access.
| Leading Market Players |
|---|
| Groupe Limagrain |
| Florimond Desprez |
| Corteva Agriscience |
| RAGT Group |
| BASF SE |
| Bayer |
| KWS SAAT |
| Advanta Seeds |
| Syngenta Group |
| Others |
Value Chain & Pricing Dynamics
OECD Seed Scheme certification gates both supply qualification and price differentiation simultaneously, creating a bifurcated market where multi-jurisdictional compliance capacity commands premium positioning while non-certified seed trades at commodity discounts.
Pricing Analysis
Certification level creates the primary spread across wheat seed tiers, with OECD Seed Scheme-certified varieties commanding substantial premiums over farm-saved alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects germplasm purity thresholds, with hybrid systems anchored by proprietary cytoplasmic male sterility platforms at the top. Cost compression in open-pollinated segments is intensifying because state university breeder programs in India expand foundation seed volumes. Commercial flour millers exhibit lowest price sensitivity due to forward contract specifications, while smallholder farmers in developing markets retain highest elasticity.
Supply Chain Analysis
Inventory cycles for certified seed extend 18-24 months due to phytosanitary testing protocols, compressing effective commercial windows for proprietary varieties. Production gravity centers on France, Germany, and Australia for OECD Scheme-certified volumes, with India emerging as the fastest-expanding certified seed base. The supply chain draws from parental line germplasm concentrated among institutional breeding networks, creating royalty stacking at hybrid platform entry points. Single-source vulnerability persists in cytoplasmic male sterility system licensing. Distribution runs through cooperative aggregators in established wheat belts, while agritech marketplaces in Brazil and Argentina disintermediate traditional channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wheat seed markets operate as a regulatory entrenchment story, where multi-jurisdictional OECD Seed Scheme compliance capacity creates switching costs that lock in incumbent positioning and fragment competitive access for challengers.
For Market Incumbents: Consolidate parental line portfolios through targeted acquisition of regional breeding stations, particularly in India's Punjab and Haryana corridors where BIS certification expansion accelerates. Deepen backward integration into biological seed treatment infrastructure as EU F-Gas Regulation phase-down eliminates legacy chemical actives. Channel control through embedded agronomy advisory services defends against digital marketplace disintermediation. For New Entrants and Emerging Players: Differentiate on genome-edited drought-tolerance traits where USDA regulatory clarity creates jurisdiction arbitrage against EFSA uncertainty. White-space targets cluster in direct-to-farm digital platforms for Brazil and Argentina, where cooperative aggregator bypass captures margin from logistics fragmentation. India's certified seed penetration gap offers the most penetrable geography, with state university partnership as the viable go-to-market angle. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across biological seed treatment and physical disinfection infrastructure due to REACH chemical authorization restrictions. Long-term viability favors entities with stacked molecular breeding and regulatory affairs capabilities across multiple OECD jurisdictions. Acquisition target archetype: regional testing station networks with existing multi-country varietal portfolios. The signal to watch is divergent national classification decisions on genome-edited varieties, which will fragment trade corridors and reshape breeding investment geography.| Strategic Initiative | Industry Significance |
|---|---|
| Parental Line Portfolio Acquisition | Consolidates cytoplasmic male sterility system control against royalty stacking bottlenecks. |
| Biological Seed Treatment Infrastructure | Positions for EU F-Gas Regulation compliance as chemical actives face phase-down schedules. |
| Direct-to-Farm Digital Platform Launch | Captures margin from disintermediated distribution in Brazil and Argentina logistics corridors. |
| Multi-Jurisdictional Regulatory Affairs Expansion | Enables OECD Seed Scheme certification arbitrage across France, Germany, and Australia. |
| Genome-Edited Trait Pipeline Development | Exploits USDA regulatory clarity for drought-tolerance positioning against EFSA uncertainty. |
Study Parameters
A standing panel of wheat breeding program directors, certified seed production managers, flour miller procurement leads, and regulatory affairs specialists at OECD Seed Scheme authorities provided ongoing calibration across the analysis window. Primary interviews with these stakeholders combined with secondary validation from EU Seed Marketing Directive filings, USDA varietal registration databases, Indian BIS certification records, and customs trade data. Bottom-up volume modeling across product type, end use, and distribution channel segments triangulated against top-down market sizing from breeder revenue disclosures and cooperative aggregator throughput.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including hybrid versus open-pollinated systems, food production versus flour milling end uses, and direct sales versus wholesale versus online channels. CAGRs were derived from trend extrapolation of breeder seed multiplication rates and commercial certified seed penetration curves. Industry-specific forecast inputs incorporated phytosanitary certification timeline compression and farmer-saved seed persistence elasticity by geography.
Material uncertainties — divergent regulatory classification of genome-edited varieties, parental line IP enforcement disputes, and seed pathogen outbreak severity — sit outside the modeled envelope. Forecasts reflect assumptions regarding OECD Seed Scheme harmonization continuity and BIS certification mandate enforcement intensity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
South America Forage Seed Market
Seeds
United States Garden Seeds Market
Seeds
Asia-Pacific Quinoa Seeds Market
Seeds
Psyllium Market
Seeds
Faba Beans Market
Seeds
Agricultural Seeder Market
Seeds
Flax Crop Market
Seeds
Global Packaged Chia Seeds Market
Seeds
Global Sunflower Market
Seeds
Thailand Seed Market
Seeds
Helianthus Annuus (Sunflower) Market
Seeds
Asparagus Seeds Market
Seeds
Global Vegetable Seed Market
Seeds
Global Forage Sorghum Seed Market
Seeds
Apple Seed Oil Market
Seeds
Ghana Seeds Market