
 Carrot Seed Oil Market | 2026-2036
Carrot Seed Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Carrot Seed Oil Market Analytics
Multi-source botanical procurement is decoupling from traditional European distiller networks as supply chains diversify into Eastern European and Indian cultivation zones. Robertet anchors its position through captive farming partnerships in Provence. Kazima Perfumers competes on steam-distillation scale out of Uttar Pradesh. Givaudan leverages R&D intensity in fractionation technology to isolate carrot seed oil's carotol and daucol fractions for fine fragrance applications.
Carrot seed oil is a fixed essential oil extracted from Daucus carota seeds, typically yielding 0.3–0.7% by steam distillation and characterized by high carotol content up to 40% alongside beta-bisabolene and daucene. Its primary commercial purpose centers on skin-rejuvenation formulations, perfumery bases, and therapeutic blends where antioxidant and cytophylactic properties command premium positioning. Organic cold-pressed grades capture the deepest margin pools as cosmetic brands reformulate around preservative-free claims, while conventional refined variants serve volume aromatherapy markets where price elasticity remains higher. Glass bottle packaging for premium cosmetic channels sustains price architecture against plastic container formats dominating supermarket and direct-sales tiers.
REACH in Europe and FDA cosmetic labeling requirements in the United States both tighten traceability and contaminant disclosure for botanical extracts, pushing distillers toward certified organic feedstock and GC-MS batch testing. BIS standards in India govern cold-pressed oil purity grades for export-bound pharmaceutical and cosmetic applications. Stakeholders must monitor how evolving naturals certification frameworks—particularly COSMOS and USDA Organic convergence—reshape supplier qualification criteria and procurement minimums across downstream channels.
Market Dynamics
REACH compliance in Europe is compressing margins for conventional distillers while rewarding certified organic feedstock holders, creating a bifurcation between premium cold-pressed grades and mass-market refined variants.
Growth Catalysts
- Clean-label aromatherapy demand:United States wellness brands are reformulating around single-ingredient transparency, pulling organic carrot seed oil into diffuser and topical blends at accelerated clip.
- COSMOS certification convergence:The harmonization of European organic cosmetic standards is streamlining supplier qualification, reducing audit duplication for Provence-based distillers exporting to German formulators.
- Fractionation technology maturation:Advanced molecular distillation is isolating carotol and daucol fractions for fine fragrance houses, opening high-margin specialty chemical applications beyond traditional essential oil markets.
Market Restraints
- Seed input cost volatility:Daucus carota cultivation remains concentrated in drought-sensitive regions of Uttar Pradesh and Maharashtra, exposing processors to monsoon-dependent yield swings.
- Cold-pressed yield ceilings:Steam distillation caps at 0.3–0.7% extraction efficiency, constraining volume scalability against solvent-extracted botanical alternatives in price-sensitive aromatherapy channels.
- REACH contaminant thresholds:ECHA-mandated heavy metal and pesticide residue limits are disqualifying conventional Indian export batches, forcing costly feedstock switching or certification upgrades.
Strategic Opportunities
- Eastern European cultivation expansion:Bulgaria and Romania offer untapped organic farmland with lower labor costs, enabling backward integration for distillers seeking captive supply outside Indian monsoon zones.
- Pharmaceutical API precursors:Carotol-rich fractions are attracting interest from cytophylactic compound researchers, positioning carrot seed oil as a feedstock for dermatological active ingredients.
- Direct-to-formulator digital channels:B2B platforms are collapsing traditional distributor layers, allowing small-batch distillers to reach clean-label cosmetic startups in California and New York without importer markups.
Industry Challenges
- GC-MS analytical talent scarcity:Batch-level contaminant testing requires specialized chromatography expertise that outstrips current training pipeline output in Indian and Eastern European processing hubs.
- Organic certification timeline compression:Three-year conversion periods for conventional farmland lock prospective suppliers out of premium markets during price spike windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carrot Seed Oil Market |
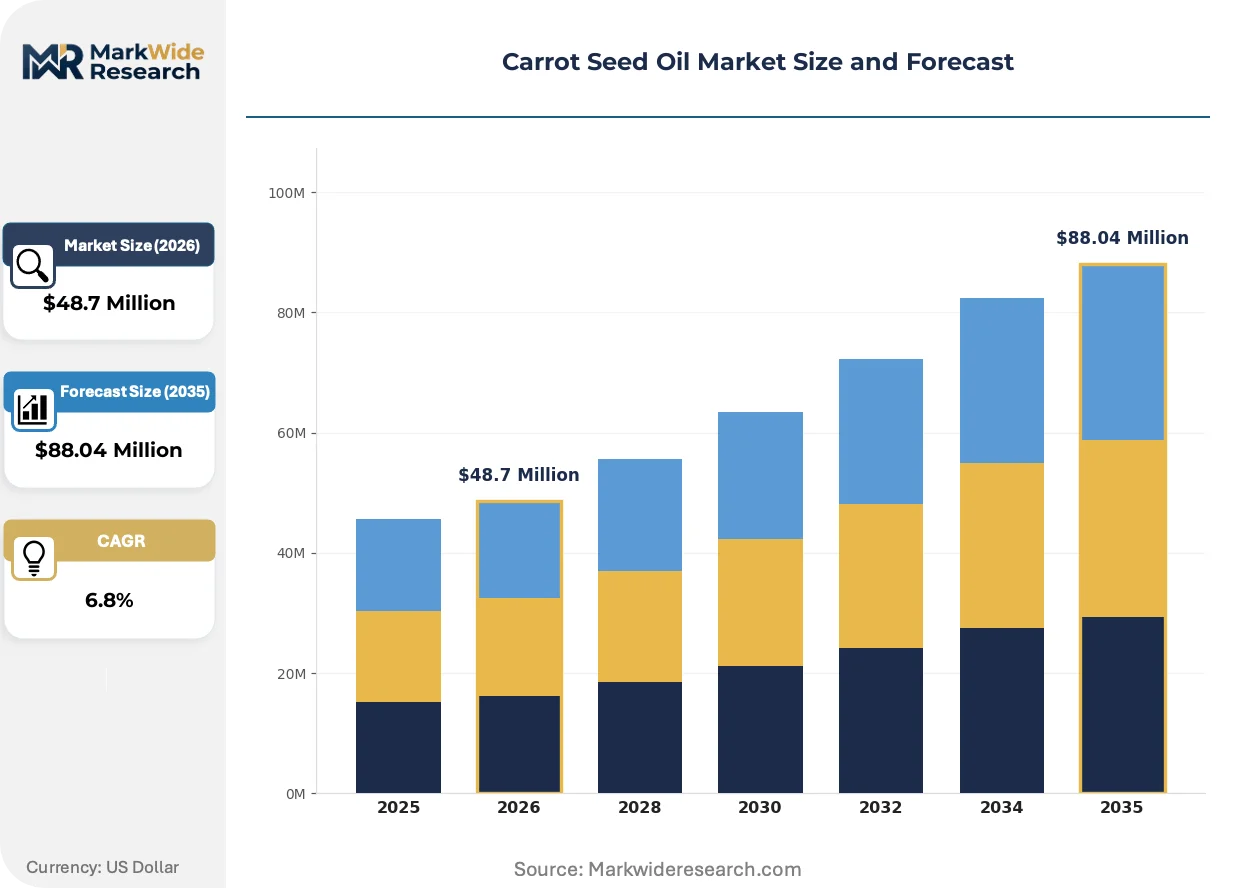
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $88.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Conventional, Cold-Pressed, Refined Application: Cosmetics, Aromatherapy, Pharmaceuticals, Food Packaging Type: Glass Bottles, Plastic Containers, Metal Cans, Bulk Packaging Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | Kazima Perfumers, Kanta Enterprises Private Limited, Robertet, PerfumersWorld, Now Foods, Cathy's Attars, HealthAid Limited, Leven Rose, Givaudan, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carrot Seed Oil Market Evolving Landscape
Supercritical CO2 extraction is disrupting traditional steam distillation economics, while regulatory tightening in Europe and buyer consolidation in North America are rewriting supplier qualification protocols across the value chain.
Supercritical CO2 extraction systems are absorbing capital investment from mid-scale distillers seeking to bypass steam distillation's thermal degradation of heat-sensitive sesquiterpenes. French and German cosmetic formulators are specifying CO2-derived grades for anti-aging serums where carotol integrity commands measurable efficacy claims. This technology is absorbing market share from conventional hydrodistillation in premium segments while compressing price premiums for artisanal small-batch producers unable to finance equipment upgrades.
REACH Annex XVII updates are tightening residual solvent limits for cold-pressed cosmetic-grade oils, forcing Indian exporters toward certified organic feedstock or third-party laboratory partnerships. The industrial consequence is a supplier shakeout among Uttar Pradesh distillers lacking in-house GC-MS capabilities. Aromatherapy brands in Germany and the Netherlands are responding by consolidating purchase orders with Provence-based partners holding captive organic cultivation and integrated testing facilities.
Buyer concentration among clean-label cosmetic conglomerates is shortening supplier payment cycles and demanding blockchain-traceable batch documentation. Small distillers in Bulgaria and Romania are being displaced from premium tiers as formulators in France and California mandate single-origin certificates and real-time harvest monitoring. This pattern is most visible in the United States, where direct-to-consumer skincare brands are bypassing traditional importers to contract directly with Eastern European organic cooperatives, compressing margins for legacy distribution intermediaries in New York and Rotterdam.
Carrot Seed Oil Market Segmentation
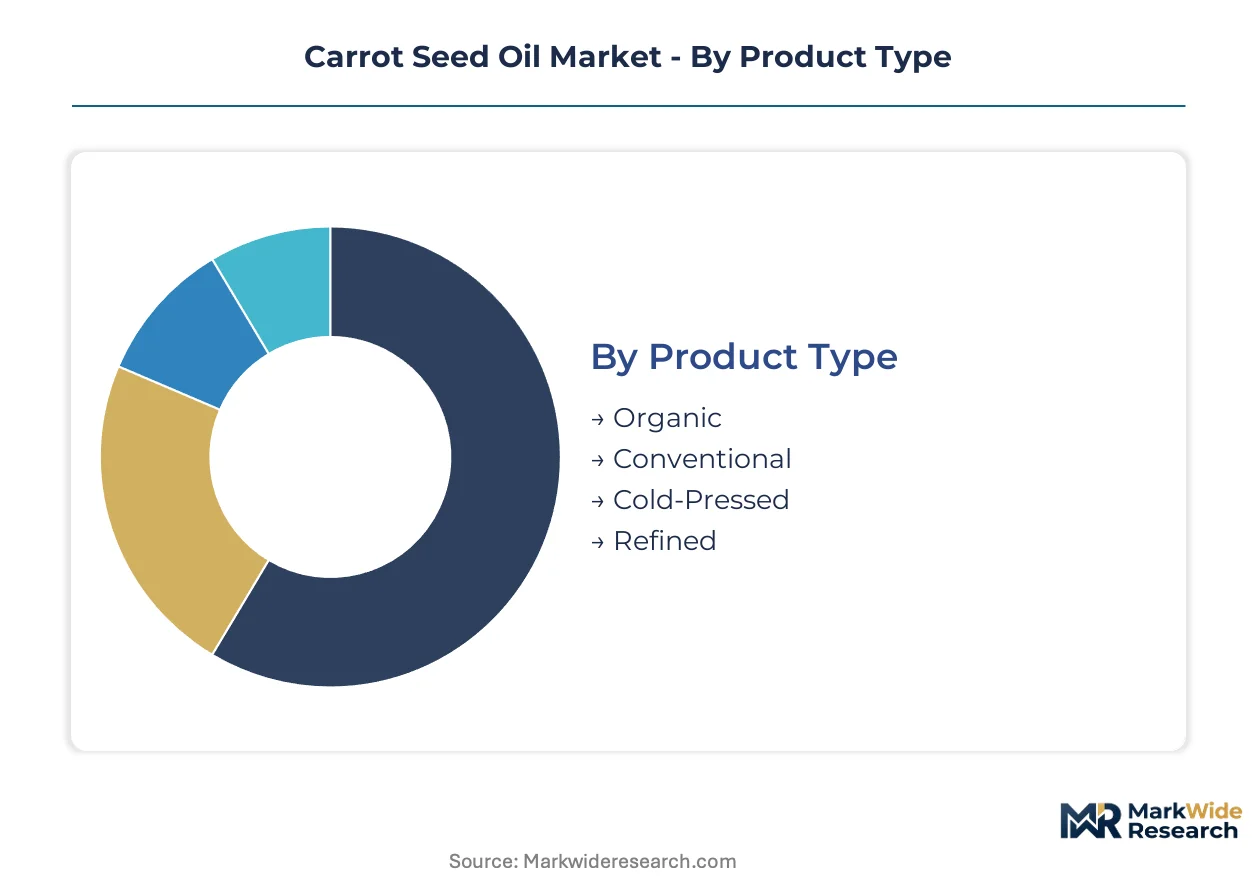
Carrot seed oil's commercial architecture fragments across extraction methods, purity grades, and end-use specifications. Each segment carries distinct margin profiles and regulatory burdens that reshape supplier competitive positioning.
Product Type:
Cultivation concentration in Provence and Uttar Pradesh directly shapes which extraction grades dominate premium versus volume tiers.
- Organic:Certified feedstock from Provence captive farms yields cold-pressed grades with sub-50ppm pesticide thresholds. French and German cosmetic formulators specify organic for anti-aging serums where COSMOS compliance commands shelf placement.
- Cold-Pressed:Mechanical extraction at sub-40°C preserves carotol fractions above 35%, enabling cytophylactic efficacy claims in dermatological applications. REACH Annex XVII solvent limits disqualify conventional alternatives in European premium channels.
- Conventional:Steam-distilled variants from Indian bulk processors serve price-elastic aromatherapy markets with relaxed contaminant specifications.
- Refined:Bleached and deodorized grades neutralize color and odor for fragrance compound dilution where visual clarity outweighs bioactive retention.
Today's leader: Organic. Tomorrow's challenger: Cold-Pressed.
Application:
End-use demand splits sharply between efficacy-driven cosmetic formulations and experiential aromatherapy consumption.
- Cosmetics:Skin-rejuvenation serums and preservative-free moisturizers absorb the highest-grade fractions. California direct-to-consumer brands contract Eastern European cooperatives for single-origin traceability.
- Pharmaceuticals:Carotol-rich isolates attract dermatological API research, though clinical validation timelines constrain near-term volume.
- Aromatherapy:Diffuser blends and massage oils in the United States pull conventional grades through clean-label wellness positioning.
- Food:Flavoring and nutraceutical applications remain marginal due to stringent FSSAI and FDA ingestion safety thresholds.
Cosmetics commands current margin pools. Pharmaceuticals offers the steepest expansion trajectory pending regulatory clearance.
Packaging Type:
Channel economics dictate material selection, with premium cosmetic positioning requiring glass to sustain price architecture.
- Glass Bottles:Amber and cobalt glass blocks UV degradation for retail cosmetic channels where shelf aesthetics validate premium pricing.
- Plastic Containers:PET and HDPE formats dominate supermarket and direct-sales tiers with lower logistics costs.
- Metal Cans:Aluminum and tin-plated steel serve industrial fragrance compound shipments requiring light and oxygen barriers.
- Bulk Packaging:Stainless steel totes and drum formats supply formulators with in-house filling capabilities, bypassing retail packaging markups.
Glass Bottles anchor premium positioning. Bulk Packaging gains share fastest among vertically integrated cosmetic manufacturers.
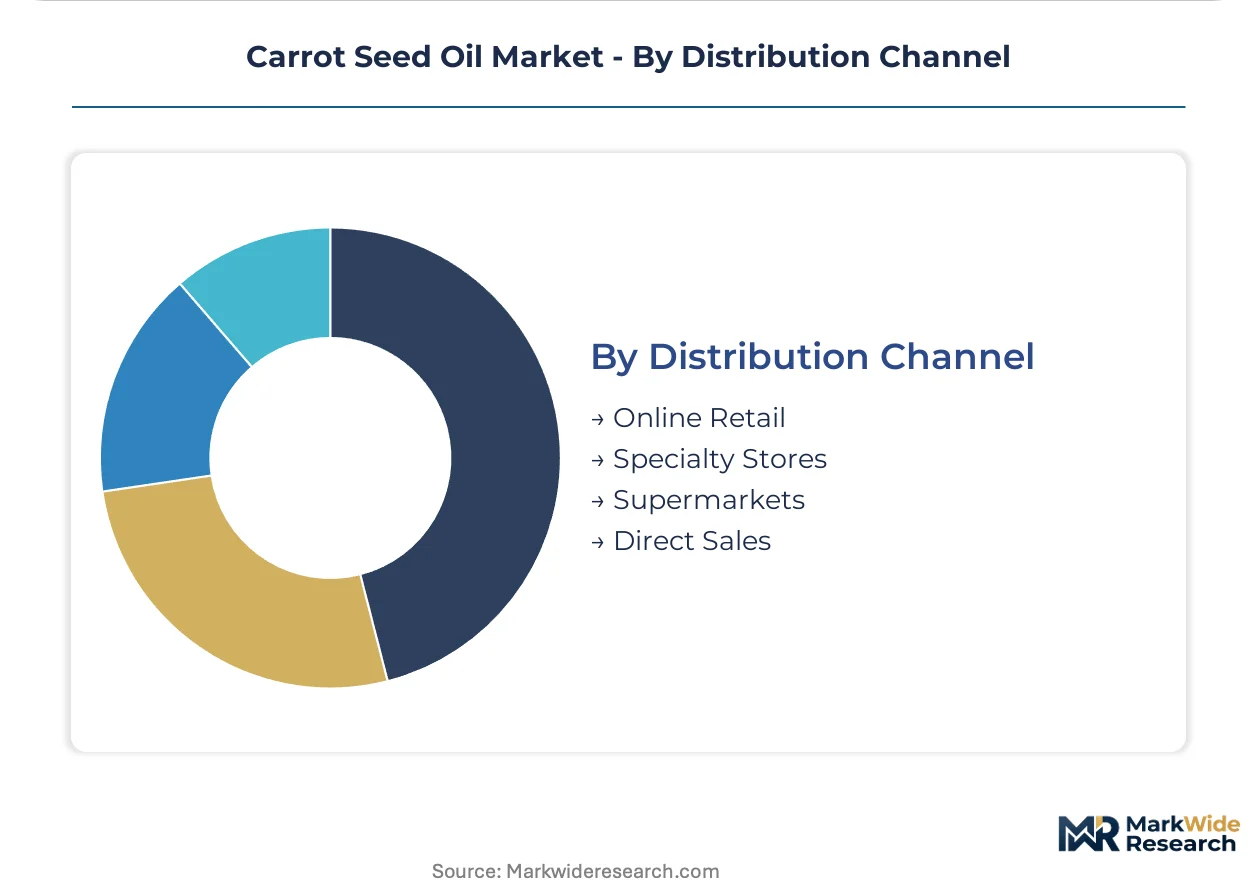
Distribution Channel:
Digital disintermediation is collapsing traditional importer layers for small-batch distillers seeking direct formulator access.
- Online Retail:B2B platforms enable Bulgarian and Romanian cooperatives to reach California and New York cosmetic startups without Rotterdam distributor markups.
- Specialty Stores:Aromatherapy boutiques in Germany and the Netherlands consolidate purchases with Provence partners holding integrated testing facilities.
- Supermarkets:Mass-market wellness chains in the United States stock conventional grades for diffuser oil private labels.
- Direct Sales:Multi-level marketing networks move aromatherapy kits through personal consultant channels with higher customer acquisition costs.
Online Retail is displacing legacy import structures. Specialty Stores defend position through experiential curation and batch traceability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Provence anchors the premium-grade supply base through Robertet's captive organic cultivation partnerships, while Uttar Pradesh bulk processors feed volume aromatherapy channels. Regulatory divergence between ECHA-mandated contaminant limits and FDA cosmetic labeling requirements is fragmenting procurement strategies across formulator networks.
United States
California direct-to-consumer skincare brands and New York wellness startups are contracting Eastern European cooperatives for single-origin traceability. FDA cosmetic labeling requirements mandate batch-level contaminant disclosure, pushing formulators toward certified organic feedstock. Greater Los Angeles houses the densest cluster of clean-label aromatherapy brands reformulating around single-ingredient transparency.
France
Grasse-based fragrance houses and Parisian cosmetic formulators specify cold-pressed grades with carotol content above 35% for anti-aging serum efficacy claims. REACH Annex XVII updates tighten residual solvent limits, disqualifying conventional Indian export batches from premium channels. Provence-Alpes-Côte d'Azur concentrates the highest density of COSMOS-certified organic distillation capacity.
Germany
Natural cosmetics manufacturers in Hamburg and Munich are consolidating purchase orders with integrated testing facilities to reduce audit duplication. ECHA-mandated heavy metal thresholds are compressing margins for conventional distillers while rewarding certified organic feedstock holders. Bavaria's formulator ecosystem is streamlining supplier qualification through harmonized European organic cosmetic standards.
India
Uttar Pradesh steam-distillation processors compete on scale for conventional aromatherapy markets, while Maharashtra cultivators face monsoon-dependent yield volatility. BIS standards govern cold-pressed oil purity grades for export-bound pharmaceutical and cosmetic applications. Mumbai serves as the primary export logistics hub for bulk shipments to European and North American formulators.
Bulgaria
Untapped organic farmland in the Rose Valley and Thracian Plain offers lower labor costs for distillers seeking captive supply outside Indian monsoon zones. The country's national agricultural regulator is aligning certification frameworks with COSMOS convergence timelines. Sofia-based cooperatives are gaining direct access to California cosmetic startups through B2B digital platforms, bypassing Rotterdam distributor markups.
Carrot Seed Oil Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue direct-to-formulator digital channels and Eastern European cultivation expansion. The supplier base stratifies across integrated fragrance houses with captive farming, Indian bulk processors competing on steam-distillation scale, and mid-scale distillers investing in supercritical CO2 extraction. Three archetypes dominate: Provence-based organic specialists, Uttar Pradesh volume players, and technology-forward fractionation houses. Competitive intensity centers on backward integration into seed cultivation and GC-MS testing capability acquisition.
Within the integrated fragrance house tier, Robertet exemplifies the captive supply model through Provence farming partnerships, while Givaudan occupies a position defined by R&D intensity in molecular distillation. Among Indian bulk processors, Kazima Perfumers represents the scale-driven steam-distillation archetype. These three companies anchor the competitive structure without exhausting the vendor landscape.
| Leading Market Players |
|---|
| Kazima Perfumers |
| Kanta Enterprises Private Limited |
| Robertet |
| PerfumersWorld |
| Now Foods |
| Cathy's Attars |
| HealthAid Limited |
| Leven Rose |
| Givaudan |
| Others |
Value Network & Pricing Analysis
Captive farming partnerships in Provence anchor supply positioning for premium cold-pressed grades while compressing procurement costs for integrated fragrance houses. This backward integration into Daucus carota cultivation simultaneously insulates Robertet from Indian monsoon volatility and sustains price premiums against Uttar Pradesh bulk processors.
Pricing Analysis
Seed input cost pass-through from Maharashtra and Uttar Pradesh cultivation zones directly governs margin compression for steam-distilled conventional grades. Pricing stratifies across COSMOS-certified organic, cold-pressed pharmaceutical-grade, and refined fragrance-dilution tiers, with certification level and carotol content as primary differentiation drivers. Cost compression in conventional segments is intensifying as REACH-mandated testing upgrades disqualify uncertified Indian export batches. Aromatherapy brands in Germany exhibit highest price elasticity, while French cosmetic formulators absorb premium positioning for anti-aging serum applications.
Supply Chain Analysis
Freight cost differentials between Mumbai export hubs and direct Sofia-to-Rotterdam routing are reshaping procurement patterns for California cosmetic startups. Supply concentrates in France, India, and Bulgaria, with Daucus carota seeds, amber glass packaging, and GC-MS testing services as critical input dependencies. Single-source vulnerability in Uttar Pradesh monsoon-dependent cultivation exposes processors to yield-driven price spikes. Distribution runs through B2B digital platforms collapsing traditional Rotterdam importer layers for Eastern European cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between Eastern European organic farmland conversion costs and REACH-compliant testing infrastructure investments in Western Europe. The regulatory cost differential creates expansion incentives for Bulgarian and Romanian cultivation against Indian conventional supply.
For Market Incumbents: To counter supercritical CO2 extraction technology disruption from mid-scale French and German competitors, Robertet and Givaudan should deepen captive farming partnerships in Provence while acquiring in-house GC-MS testing capabilities. Certification investment in COSMOS-organic convergence timelines defends shelf placement against emerging Eastern European cooperatives.
For New Entrants and Emerging Players: California direct-to-consumer skincare startups represent an underserved buyer archetype seeking single-origin traceability without Rotterdam distributor markups. Bulgarian organic cooperatives should target this segment through B2B platform direct contracting. Pharmaceutical API precursor applications for carotol-rich fractions offer the most penetrable white-space expansion pending dermatological clinical validation.
For Investors and Strategic Acquirers: Roll-up economics work for mid-scale Eastern European distillers because COSMOS certification convergence compresses audit duplication costs across fragmented Bulgarian and Romanian supplier bases. The five-to-ten-year viability window favors platform consolidation of organic farmland with integrated testing facilities. Watch for FDA cosmetic labeling rulemaking as the inflection signal accelerating certified organic feedstock demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Cultivation | Provence farming partnerships insulate Robertet from Indian monsoon yield volatility. |
| Supercritical CO2 Extraction Scale-Up | French formulators specify CO2-derived grades for carotol integrity in anti-aging serums. |
| GC-MS Testing Capability Acquisition | In-house chromatography facilities satisfy REACH Annex XVII contaminant disclosure mandates. |
| B2B Platform Direct Channel Launch | Sofia cooperatives bypass Rotterdam markups to reach California cosmetic startups. |
| Pharmaceutical API Precursor Development | Carotol-rich fractions attract dermatological active ingredient research investment. |
Research Methodology
Bottom-up cosmetic and pharmaceutical formulation modeling reconciled against top-down Daucus carota cultivation and distillation capacity tracking forms the analytical core. Primary interviews with Provence-based fragrance house procurement directors, Uttar Pradesh steam-distillation plant managers, California clean-label brand formulators, and German natural cosmetics regulatory affairs leads combined with secondary validation from REACH Annex XVII filings, BIS cold-pressed oil standards, USDA Organic certification databases, and customs trade data. Triangulation across supply-side capacity surveys and demand-side procurement pattern analysis ensures segment-level precision.
Historical trendline analysis of extraction technology adoption rates, organic certification conversion timelines, and regional cultivation yield patterns established baseline growth assumptions. Segmentation modeling spans extraction method, purity grade, end-use application, packaging format, and distribution channel dimensions across the projection horizon. CAGRs derive from fitted trend extrapolation adjusted for regulatory threshold tightening and technology substitution effects. Forecast inputs include monsoon precipitation indices for Maharashtra cultivation zones and COSMOS certification audit pipeline data.
Underlying measurement precision varies by segment; organic cold-pressed grades carry tighter precision than conventional steam-distilled volumes due to certified supply chain documentation. Forecasts reflect assumptions about REACH enforcement consistency and FDA cosmetic labeling rulemaking trajectory. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Flaxseed (Linseed) Market
Seeds
Dragon Fruit Seeds Market
Seeds
Asia-Pacific Seed Market
Seeds
Brazil Forage Seed Market
Seeds
Apple Seed Oil Market
Seeds
Sri Lanka Seed Market
Seeds
Europe Grain Seed Market
Seeds
Europe Seed Market
Seeds
Myanmar Maize Seed Market
Seeds
Agricultural Seeder Market
Seeds
Global Sunflower Seed (Seed for Sowing) Market
Seeds
Vietnam Seed Market
Seeds
Global Forage Sorghum Seed Market
Seeds
Buckwheat Market
Seeds
Middle East and Africa Cannabis Seeds Market
Seeds
Nepal Seeds Market