
 United States Crop Protection Chemicals Market | 2026-2036
United States Crop Protection Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
United States Crop Protection Chemicals Market Outlook
Project finance and equipment leasing for precision sprayer fleets is tilting competitive access toward better-capitalized operators. BASF SE leverages its integrated herbicide seed-trait pipeline to sustain pricing power in glyphosate-tolerant systems. Bayer AG anchors its position through digital farming platforms that bundle chemical prescriptions with planting recommendations. FMC Corporation differentiates via its insecticide portfolio weighted toward specialty crops with tighter resistance-management protocols.
United States crop protection chemicals comprise synthetic and biological formulations engineered to control weeds, insects, and fungal pathogens across commercial agriculture, with active ingredients typically synthesized through multi-step organic chemistry and formulated for stability under field conditions. Herbicides command the largest product-type position due to acreage dominance in corn and soybean rotations, while biopesticides represent the fastest-expanding category as resistance-management mandates intensify. Liquid concentrates lead formulation demand because of compatibility with aerial and ground-based precision equipment, though soluble powders retain share in high-value horticultural segments where tank-mix flexibility commands premium positioning.
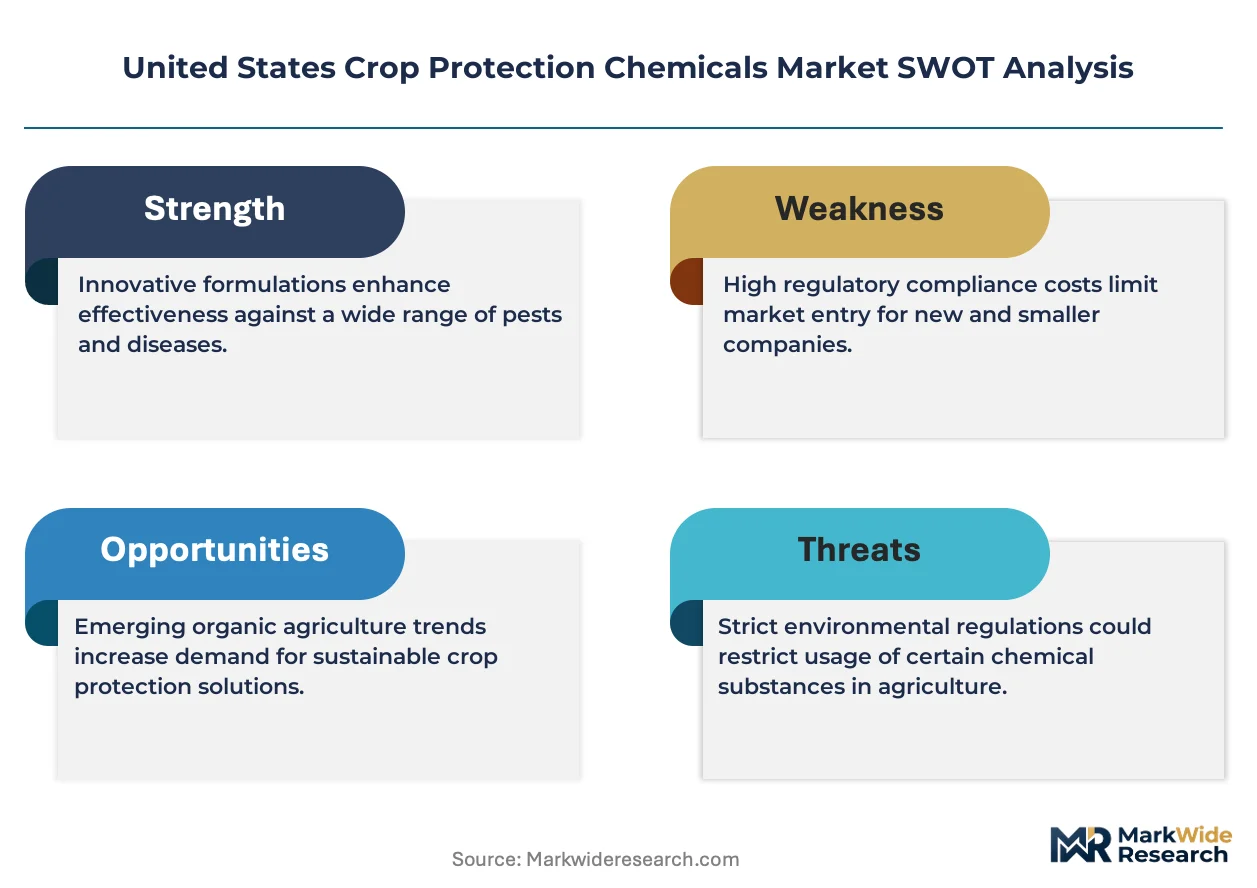
EPA registration requirements under FIFRA govern new active ingredient approvals, while OSHA standards dictate handler exposure limits and PPE mandates across manufacturing and application operations. USDA conservation programs increasingly tie cost-share eligibility to integrated pest management plans that reduce chemical load per acre. Stakeholders must monitor how state-level neonicotinoid restrictions in New York and California propagate through adjacent jurisdictions and reshape product portfolios before federal rulemaking catches pace.
Market Dynamics
Precision agriculture platforms are redirecting chemical demand toward variable-rate application technologies across the Corn Belt, compressing traditional broadcast spraying volumes while elevating data-integrated input specifications.
Growth Catalysts
- Herbicide Resistance Management Mandates:EPA's registration pathway extensions for novel active ingredients push growers toward diversified chemistries. Specialty crop operators in California accelerate tank-mix protocols combining multiple modes of action.
- USDA Conservation Cost-Share Programs:Integrated pest management plan requirements tie eligibility to reduced chemical load per acre. Corn-soybean rotations in Iowa and Illinois expand cover-crop companion spraying windows.
- Biological Formulation Advances:Microbial inoculant stability under field conditions improves shelf-life parity with synthetics. Florida citrus and California almond growers pilot Bacillus-based fungicide rotations.
Market Restraints
- Active Ingredient Import Concentration:Chinese manufacturers supply the majority of glyphosate technical material. Port congestion and tariff exposure in Long Beach and Savannah generate inventory volatility for domestic formulators.
- Neonicotinoid Regulatory Friction:New York and California state-level restrictions propagate through adjacent jurisdictions. Seed treatment applications face re-registration uncertainty across the Pacific Northwest.
- Generic Price Compression:Patent expiration waves for pyrethroid and strobilurin chemistries erode branded premia. Off-patent manufacturers in India and Israel capture volume in commodity row-crop segments.
Strategic Opportunities
- Variable-Rate Application Technology Convergence:Drone-mounted sensors fused with prescription mapping software enable sub-acre chemical targeting. Cotton operations in Texas and Georgia deploy these systems for defoliant timing.
- Specialty Crop Biological Underpenetration:High-value horticulture in Washington's Yakima Valley and Michigan's fruit belt retains synthetic dependency. Microbial biofungicide registration data gaps create first-mover openings for novel strains.
- OSHA Handler Exposure Standard Updates:Revised PPE mandates for mixing and loading operations drive demand for closed-transfer systems. Equipment manufacturers capture retrofit revenue across existing sprayer fleets.
Industry Challenges
- Precision Agriculture Technician Scarcity:Variable-rate system calibration and prescription algorithm management require hybrid agronomy-data science competencies. Land-grant university extension programs in Nebraska and Kansas struggle to graduate sufficient qualified personnel.
- Tank-Mix Compatibility Certification:Adjuvant and biological co-formulation stability testing extends product development timelines. Formulators must validate physical compatibility across water quality variations in the Great Plains versus the Southeast.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Crop Protection Chemicals Market |
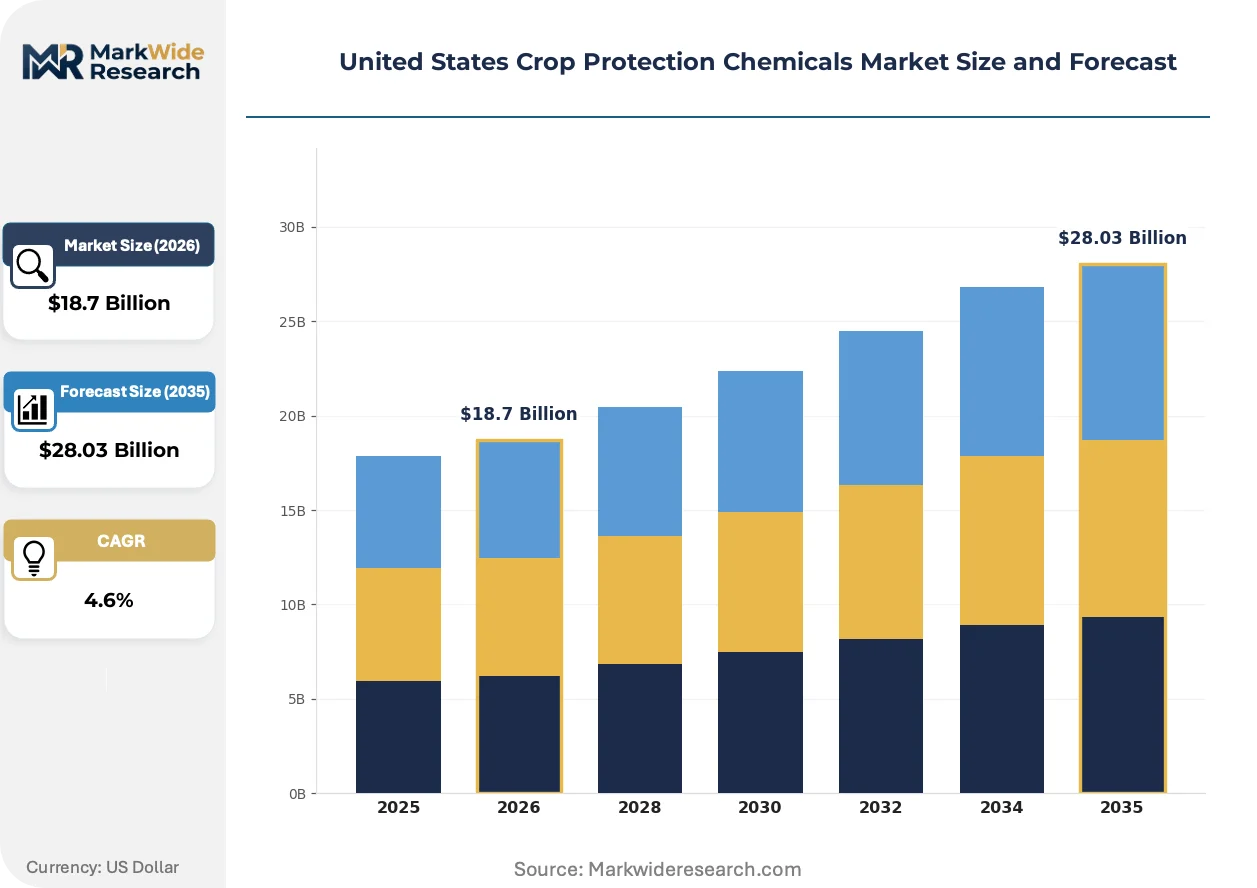
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbicides, Insecticides, Fungicides, Biopesticides Application: Agricultural, Horticultural, Turf, Ornamental Formulation: Granules, Liquid Concentrates, Emulsifiable Concentrates, Soluble Powders End User: Farmers, Agricultural Cooperatives, Retailers, Pesticide Distributors |
| Companies Covered | BASF SE, Bayer AG, Corteva Agriscience, FMC Corporation, Syngenta Group, Adama Agricultural Solutions Ltd., American Vanguard Corporation, Nufarm Ltd, Sumitomo Chemical Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Crop Protection Chemicals Market Strategic Shifts
Digital farming interfaces are bundling chemical prescriptions with real-time weather and soil data, collapsing the traditional separation between input procurement and agronomic advisory services.
RNA interference-based biopesticides are migrating from greenhouse vegetable trials to broad-acre row-crop pilots. Cotton and potato growers in the Texas High Plains evaluate sprayable dsRNA formulations for lepidopteran control. The technology is migrating from high-value protected agriculture toward commodity systems as manufacturing scale reduces per-acre cost premiums.
EPA's Endangered Species Act consultation requirements for new active ingredients extend registration timelines by 18-36 months. Herbicide manufacturers front-load ecological risk assessments to preempt litigation-driven delays. Corn and soybean seed-trait providers accelerate pre-registration partnerships with formulators to secure co-approval pathways.
Input purchasing consolidation among multi-state cooperatives concentrates procurement leverage. CHS and Growmark members negotiate multi-year chemical supply agreements with volume-floor guarantees. The Great Lakes and Northern Plains regions exhibit the most pronounced cooperative purchasing density, displacing independent retail channel share.
United States Crop Protection Chemicals Market Segmentation
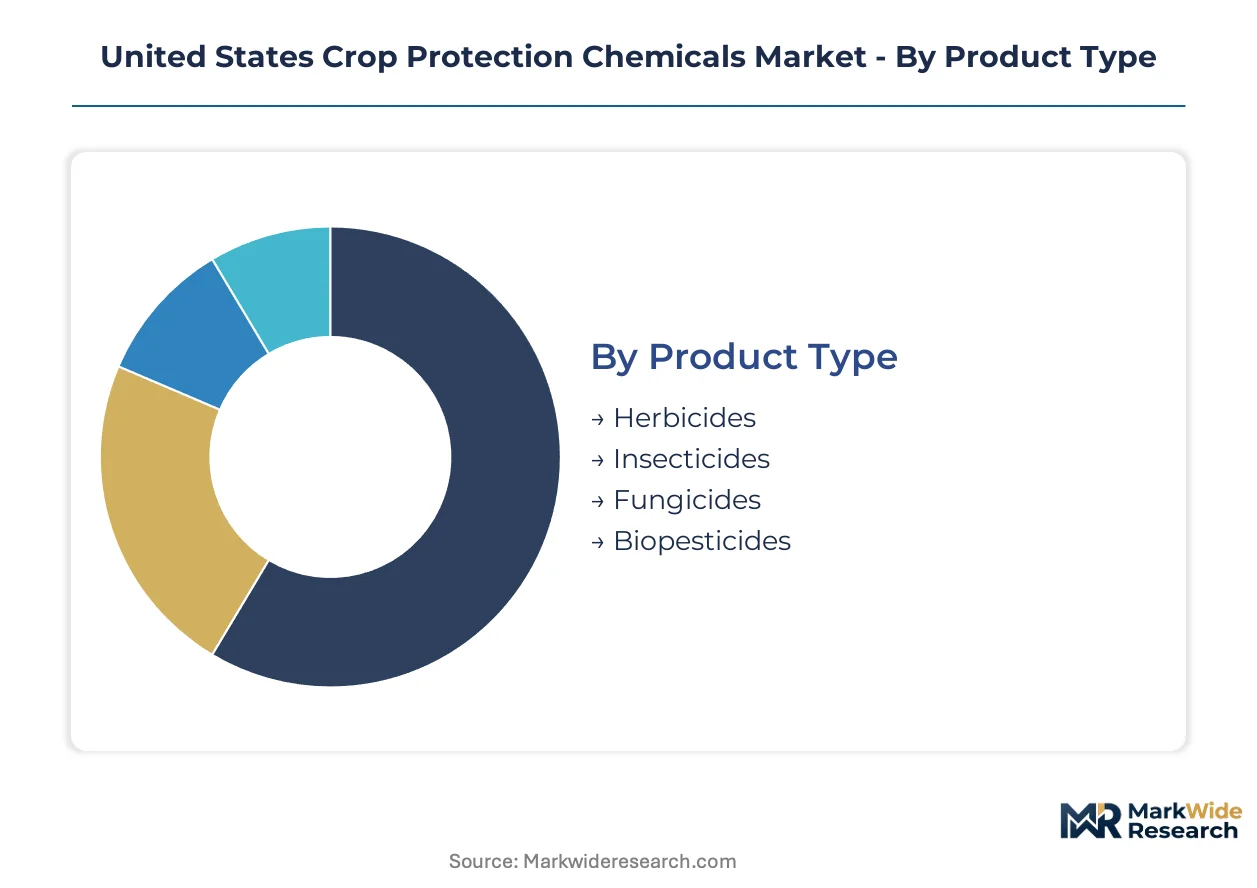
Segmentation in the United States crop protection chemicals market reveals how product chemistry, application method, and buyer structure determine pricing power and channel access. Distinct formulation preferences across the Corn Belt versus California's specialty crop belt fragment manufacturing scale economies.
Product Type:
Cost tier separates synthetic chemistries from biological alternatives, with resistance management protocols reshuffling portfolio priorities across major growing regions.
- Herbicides:Synthetic auxins, ALS inhibitors, and EPSP synthase blockers dominate corn-soybean rotations. Iowa and Illinois growers face waterhemp and Palmer amaranth pressure that accelerates tank-mix complexity and elevates per-acre expenditure.
- Insecticides:Pyrethroids, neonicotinoids, and diamides target lepidopteran and coleopteran pests. Cotton operations in Texas and Georgia deploy these chemistries against bollworm and tarnished plant bug infestations.
- Fungicides:Strobilurin and triazole chemistries protect against rust and blight pathogens. Midwest corn growers apply preventive treatments during grain-fill windows.
- Biopesticides:Microbial and biochemical formulations derived from Bacillus species and plant extracts. Florida citrus and California almond operators pilot these rotations to satisfy export residue standards.
Herbicides hold installed capacity. Biopesticides is rotating up the share rankings.
Application:
Volume concentration varies dramatically by crop value density, with high-acreage row crops enabling broadcast economies and specialty systems demanding precision placement.
- Agricultural:Broad-acre field crops including corn, soybeans, wheat, and cotton. Nebraska and Kansas operations drive bulk procurement through cooperative channels.
- Horticultural:Tree nuts, citrus, vegetables, and berries with stringent residue limits. California's Central Valley and Washington's Yakima Valley dominate expenditure intensity.
- Turf:Golf courses, sports fields, and municipal lawns. Florida and Arizona maintenance contractors specify seasonal pre-emergent programs.
- Ornamental:Nursery stock, greenhouse floriculture, and landscape plantings. Michigan and Oregon production regions concentrate greenhouse fumigant demand.
Agricultural commands procurement volume. Horticultural is climbing the fastest on value-per-acre metrics.
Formulation:
Customer type dictates physical form preference, with mechanized operators favoring liquid handling and smaller-scale growers retaining powder flexibility.
- Liquid Concentrates:Suspension and solution formulations compatible with precision injection systems. Corn Belt aerial applicators and ground rig operators specify these for variable-rate compatibility.
- Emulsifiable Concentrates:Oil-based carriers that disperse in water for foliar penetration. Cotton defoliant applications in the Mississippi Delta rely on this form for uniform canopy coverage.
- Soluble Powders:Dry formulations reconstituted in spray tanks. High-value horticulture in California and Washington retains this format for tank-mix customization.
- Granules:Clay or polymer-based carriers for soil incorporation. Rice production in Arkansas and Louisiana uses these for aquatic weed management.
Liquid concentrates anchor manufacturing throughput. Emulsifiable concentrates is gaining share fastest in specialty crop segments.
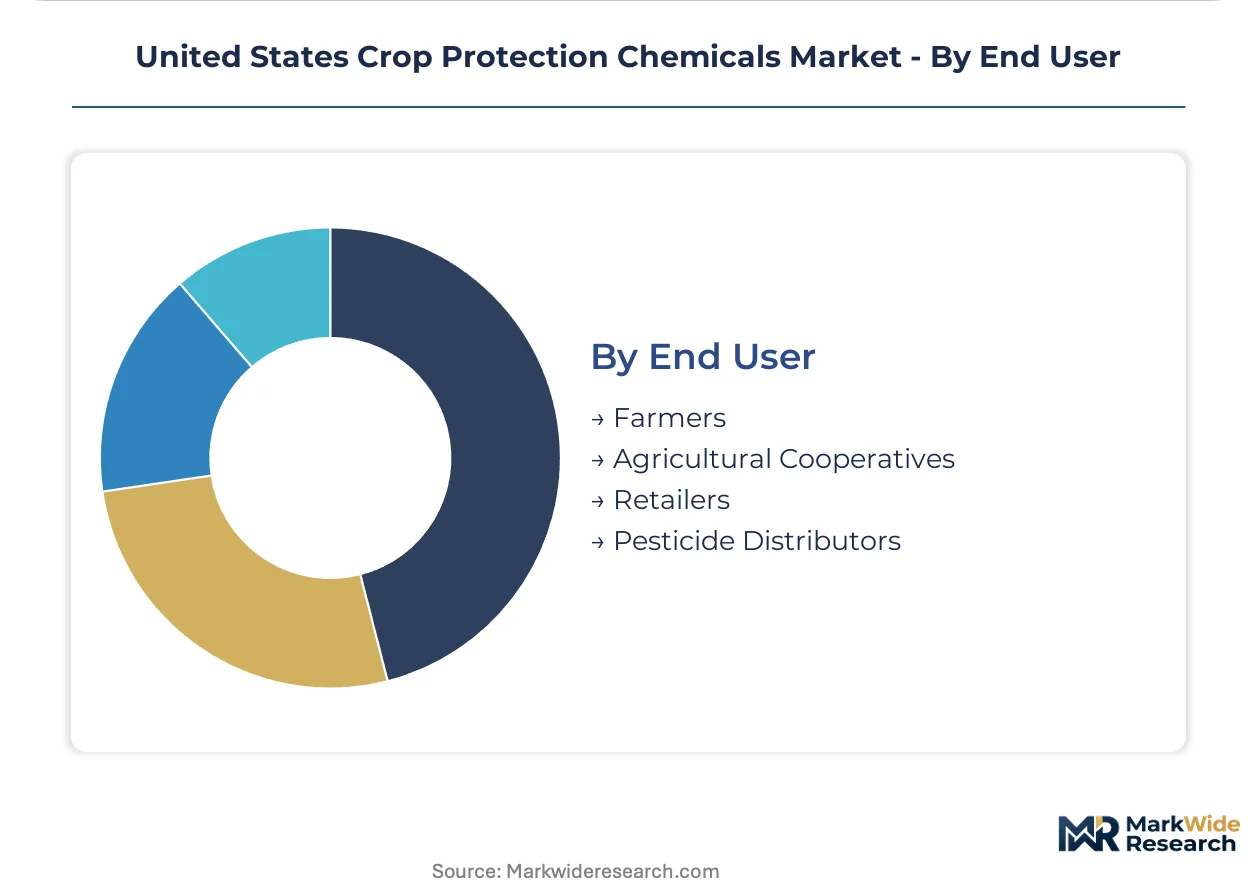
End User:
Margin structure diverges sharply across buyer categories, with cooperatives extracting volume discounts and distributors capturing formulation service premiums.
- Farmers:Owner-operators managing fewer than 2,000 acres who purchase through retail agronomy centers. Illinois and Indiana family operations dominate this tier.
- Agricultural Cooperatives:Member-owned purchasing organizations consolidating chemical procurement. CHS and Growmark members across the Great Lakes negotiate multi-year supply agreements.
- Retailers:Independent and branded farm supply stores providing application services. Northern Plains independents face consolidation pressure from national chains.
- Pesticide Distributors:Wholesale formulators and regional distributors managing inventory and logistics. Savannah and Long Beach port-dependent operations serve Southeast and West Coast markets.
Agricultural cooperatives hold procurement leverage. Farmers is rotating up the influence rankings as direct-to-grower digital platforms expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
USDA conservation cost-share programs tie eligibility to integrated pest management plans, redirecting chemical procurement patterns across major agricultural states. State-level neonicotinoid restrictions in New York and California propagate regulatory friction into adjacent jurisdictions. Corn Belt precision agriculture adoption compresses broadcast spraying volumes while elevating data-integrated input specifications.
California
Specialty crop operators in the Central Valley accelerate tank-mix protocols combining multiple herbicide modes of action. EPA registration pathway extensions for novel active ingredients push growers toward diversified chemistries. Almond and citrus growers in Fresno and Kern counties pilot Bacillus-based fungicide rotations to satisfy export residue standards.
Midwest Corn Belt
Iowa and Illinois corn-soybean rotations expand cover-crop companion spraying windows under conservation program incentives. Waterhemp and Palmer amaranth pressure elevates per-acre herbicide expenditure and tank-mix complexity. CHS and Growmark cooperatives across the Great Lakes negotiate multi-year chemical supply agreements with volume-floor guarantees.
Texas and Southern Plains
Cotton operations deploy variable-rate application systems for defoliant timing using drone-mounted sensors fused with prescription mapping software. Bollworm and tarnished plant bug infestations drive pyrethroid and diamide insecticide demand. Port-dependent distributors in Houston serve Gulf Coast markets facing glyphosate technical material inventory volatility.
Florida
Citrus growers pilot microbial biofungicide rotations as state-level resistance-management mandates intensify. Florida and Arizona turf maintenance contractors specify seasonal pre-emergent programs for golf courses and municipal lawns. Miami-Dade and Polk County horticultural operations retain soluble powder formulations for tank-mix customization flexibility.
Pacific Northwest
Washington's Yakima Valley high-value horticulture retains synthetic dependency due to microbial biofungicide registration data gaps. Seed treatment applications face re-registration uncertainty across Oregon and Idaho. Closed-transfer system retrofits capture equipment manufacturer revenue as OSHA handler exposure standards tighten.
United States Crop Protection Chemicals Market Competitive Environment
On the supply side, the industry is consolidating around integrated seed-trait-chemical platforms that bundle input procurement with agronomic advisory services. Tiered competitive positioning separates global conglomerates with multi-crop portfolios from regional specialists concentrating on resistance-management protocols. Two strategic archetypes dominate: vertically integrated life-science conglomerates controlling proprietary germplasm and trait licensing, and formulation-focused specialists capturing premium positioning in high-value horticultural segments. Dominant competitive moves include pre-registration partnerships between seed-trait providers and formulators to secure co-approval pathways, and project finance structures for precision sprayer fleets that tilt competitive access toward better-capitalized operators.
Within the integrated conglomerate tier, BASF SE and Bayer AG exemplify platform-based competition anchored in digital farming interfaces that collapse traditional separations between input procurement and agronomic advisory. FMC Corporation occupies a specialist position weighted toward insecticide portfolios with tighter resistance-management protocols in specialty crop segments. These three entities represent the competitive spectrum from bundled platform dominance to targeted portfolio differentiation.
| Leading Market Players |
|---|
| BASF SE |
| Bayer AG |
| Corteva Agriscience |
| FMC Corporation |
| Syngenta Group |
| Adama Agricultural Solutions Ltd. |
| American Vanguard Corporation |
| Nufarm Ltd |
| Sumitomo Chemical Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in glyphosate technical manufacturing across Chinese coastal provinces compresses supplier margins while simultaneously elevating pricing volatility for domestic formulators navigating tariff exposure and port congestion cycles.
Pricing Analysis
EPA registration tier and resistance-management protocol adherence create the primary spread between branded premia and generic alternatives. Three-tier pricing structure across novel active ingredients, established proprietary chemistries, and post-patent generics dominates procurement negotiations. Cost compression in pyrethroid and strobilurin segments is intensifying because Indian and Israeli manufacturers capture volume in commodity row-crop applications. Agricultural cooperatives exhibit the highest price sensitivity due to consolidated volume leverage, while specialty crop operators in California's Central Valley show relative insensitivity given export residue standard compliance requirements.
Supply Chain Analysis
Contract manufacturing concentration resides with Chinese agrochemical intermediates producers along the Yangtze River Delta and Shandong Peninsula, supplemented by Indian technical material suppliers in Gujarat and Maharashtra. Active ingredient synthesis draws from imported aniline derivatives, organophosphate precursors, and chlorinated intermediates. Single-source vulnerability concentrates in glyphosate technical supply from Chinese state-affiliated manufacturers. Distribution runs through port-dependent wholesale formulators in Savannah and Long Beach serving regional distributor networks across the Corn Belt and Pacific Coast.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biological formulation substitution threatens synthetic chemistry incumbents as microbial biofungicide stability improvements erode traditional performance gaps in high-value horticultural segments.
For Market Incumbents: Harden resistance-management protocol integration through pre-registration partnerships with seed-trait providers, securing co-approval pathways that lock in herbicide rotation requirements. Deepen backward integration into precision application equipment leasing to capture project finance structures that tilt competitive access toward better-capitalized operators. These moves defend against biological substitute encroachment and generic price erosion simultaneously.
For New Entrants and Emerging Players: Specialty crop biological underpenetration in Washington's Yakima Valley and Michigan's fruit belt represents the most penetrable entry point given microbial biofungicide registration data gaps and synthetic dependency retention. RNA interference-based biopesticide pilots in Texas cotton operations offer a second white-space target as manufacturing scale reduces per-acre cost premiums. A go-to-market angle anchored in export residue standard compliance for almond and citrus growers accelerates adoption velocity.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across precision agriculture platform integration, elevating equipment and data infrastructure requirements relative to traditional chemical manufacturing. Acquisition target archetypes include formulation-focused specialists with tight resistance-management protocols in high-value horticultural segments and regional distributors with captive port access in Savannah or Houston. Watch variable-rate technician graduation rates from land-grant university extension programs as an inflection indicator for precision adoption velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Pre-registration Partnership | Seed-trait providers and formulators secure EPA co-approval pathways, compressing registration timelines for novel herbicide modes of action. |
| Precision Equipment Leasing | Project finance structures for drone-mounted sensor fleets redirect competitive access toward operators with stronger balance sheets. |
| Biological Formulation Scale-up | Bacillus strain manufacturing investments close shelf-life parity gaps with synthetic fungicides in Florida citrus and California almond applications. |
| Cooperative Procurement Consolidation | CHS and Growmark multi-year supply agreements with volume-floor guarantees displace independent retail channel share across the Great Lakes. |
| Closed-transfer System Retrofit | Equipment manufacturers capture recurring revenue as OSHA handler exposure standard updates mandate PPE upgrades across existing sprayer fleets. |
Study Parameters
The analysis maps herbicide, insecticide, fungicide, and biopesticide sub-sectors, each validated through technical R&D directors at major formulators, procurement leads at agricultural cooperatives, distribution channel partners, and EPA regulatory affairs specialists. Primary interview findings triangulate against customs and trade data, SEC 10-K filings, USDA conservation program enrollment records, and EPA registration databases. Bottom-up volume estimates from county-level crop acreage and application rate assumptions reconcile with top-down manufacturer shipment data.
Assumptions held fixed across the modeling period include EPA FIFRA regulatory framework continuity and USDA conservation cost-share program eligibility criteria, while tariff exposure levels and neonicotinoid restriction propagation were varied across sensitivity scenarios. Segmentation dimensions encompass product chemistry tier, application method, formulation type, and end-user buyer structure. CAGRs derive from regression-adjusted trend extrapolation incorporating active ingredient pipeline visibility and precision agriculture adoption curves.
Stress conditions across glyphosate technical import disruption, state-level neonicotinoid restriction expansion, and biological formulation performance breakthroughs were modeled; outcomes outside those bands fall beyond the analytical envelope. Quarterly review of EPA registration timeline announcements, cooperative procurement contract disclosures, and precision agriculture technician graduation rates from Nebraska and Kansas extension programs is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Fosthiazate Market
Crop Protection
Herbicide Safeners Market
Crop Protection
Glufosinate Ammonium Market
Crop Protection
Sustainable Crop Protection Chemicals Market
Crop Protection
US Insecticide Market
Crop Protection
Global Algaecides Market
Crop Protection
Soil Sterilizers Market
Crop Protection
Europe Insecticides Market
Crop Protection
Europe Seed Treatment Market
Crop Protection
Russia Crop Protection Chemicals Market
Crop Protection
Synthetic Pesticide Market
Crop Protection
Global Insecticides Market
Crop Protection
Global Turf Protection Market
Crop Protection
Pre-Emergent Herbicide Market
Crop Protection
Asia-Pacific Acaricides Market
Crop Protection
Fumigation Service Market