
 Seed Health Market | 2026-2036
Seed Health Market Size, Share, and Industry Trends Forecast 2026-2036
Seed Health Market Analytics
The capital-intensity divergence between integrated biotechnology platforms and regional seed distributors is unwinding competitive stability in seed health. Bayer leverages its germplasm library and microbial pipeline to sustain premium positioning across major row-crop geographies. Syngenta anchors its seed health portfolio through integrated crop protection chemistry, while Corteva Agriscience differentiates via CRISPR-edited disease resistance traits and biological seed coatings.
Seed health encompasses the biological condition, pathogen load, and treatment status of propagation material used for crop establishment, measured through germination percentage, vigor indices, and freedom from regulated pests such as Xanthomonas and Pseudomonas syringae. Synthetic and hybrid seed categories dominate commercial volume, though organic seed segments are gaining traction where EU Green Deal targets restrict chemical inputs. Disease resistance traits command premium pricing, while yield enhancement applications face margin compression as generic biologicals proliferate in agricultural farming channels.
The EPA regulates treated seed as pesticide-end-use products under FIFRA, requiring rigorous data on non-target organism effects, while the EU Green Deal's pesticide reduction targets are reshaping product registration pathways through EFSA. Brazil's national agricultural regulator enforces phytosanitary certification for imported germplasm, creating compliance bottlenecks for multinational suppliers. Stakeholders must monitor evolving biologicals registration frameworks and germplasm import protocols to anticipate which seed treatment platforms will retain market access.
Market Dynamics
The EPA's biopesticide registration pathways and the EU Green Deal's pesticide reduction targets are compressing synthetic chemistry margins while accelerating biological seed treatment platforms. This regulatory bifurcation is restructuring R&D allocation across integrated biotechnology firms and regional distributors.
Growth Catalysts
- Biological Registration Pathways:The EPA's streamlined biopesticide approval process under FIFRA is compressing time-to-market for microbial seed treatments. Large-scale agricultural farming operations in Brazil's Cerrado soybean belt are expanding procurement of biological-coated varieties to combat nematode resistance.
- EU Farm to Fork Mandates:The EU Green Deal's pesticide reduction targets are forcing substitution of chemical seed treatments with microbial inoculants and RNA interference technologies. Organic seed segments are gaining traction where certification standards restrict synthetic inputs.
- CRISPR Trait Integration:Gene-edited disease resistance traits are decomposing the traditional separation between germplasm development and seed health management. Corteva Agriscience and academic breeding programs are stacking fungal resistance loci directly into elite hybrid backgrounds.
Market Restraints
- Active Ingredient Concentration:Three multinational suppliers control over 70% of novel fungicide and insecticide active ingredients for seed treatment, creating supply vulnerability for generic formulators.
- Phytosanitary Certification Bottlenecks:Brazil's national agricultural regulator enforces strict germplasm import protocols, delaying commercialization timelines for new trait introductions by 18-24 months.
- Biological Efficacy Variability:Microbial seed coatings exhibit inconsistent field performance across soil temperature and moisture gradients, limiting farmer willingness to pay premium pricing relative to synthetic chemistry benchmarks.
Strategic Opportunities
- Underpenetrated Smallholder Channels:India's fragmented rice-wheat systems represent untapped volume for biological seed treatments, with state agricultural universities serving as distribution anchors for farmer producer organizations.
- Carbon Credit Integration:Biological nitrogen fixation traits in legume and cereal coatings qualify for emerging soil carbon protocols, creating revenue stacking beyond yield protection.
- Seed-Applied Biologicals Convergence:The intersection of precision fermentation and seed coating equipment automation is enabling cost parity between microbial and synthetic treatments at commercial scale.
Industry Challenges
- Microbiome Specialist Scarcity:The talent pipeline for rhizosphere ecology and formulation science lags behind platform expansion, forcing firms to recruit from pharmaceutical fermentation backgrounds.
- Multi-Jurisdiction Registration Burden:Seed treatments face divergent data requirements across EPA, EFSA, and ANVISA frameworks, duplicating toxicology and environmental fate studies.
- Trait-Coating Integration Complexity:Stacking CRISPR-edited resistance with biological coatings requires redesigned quality assurance protocols, extending seed processing timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Seed Health Market |
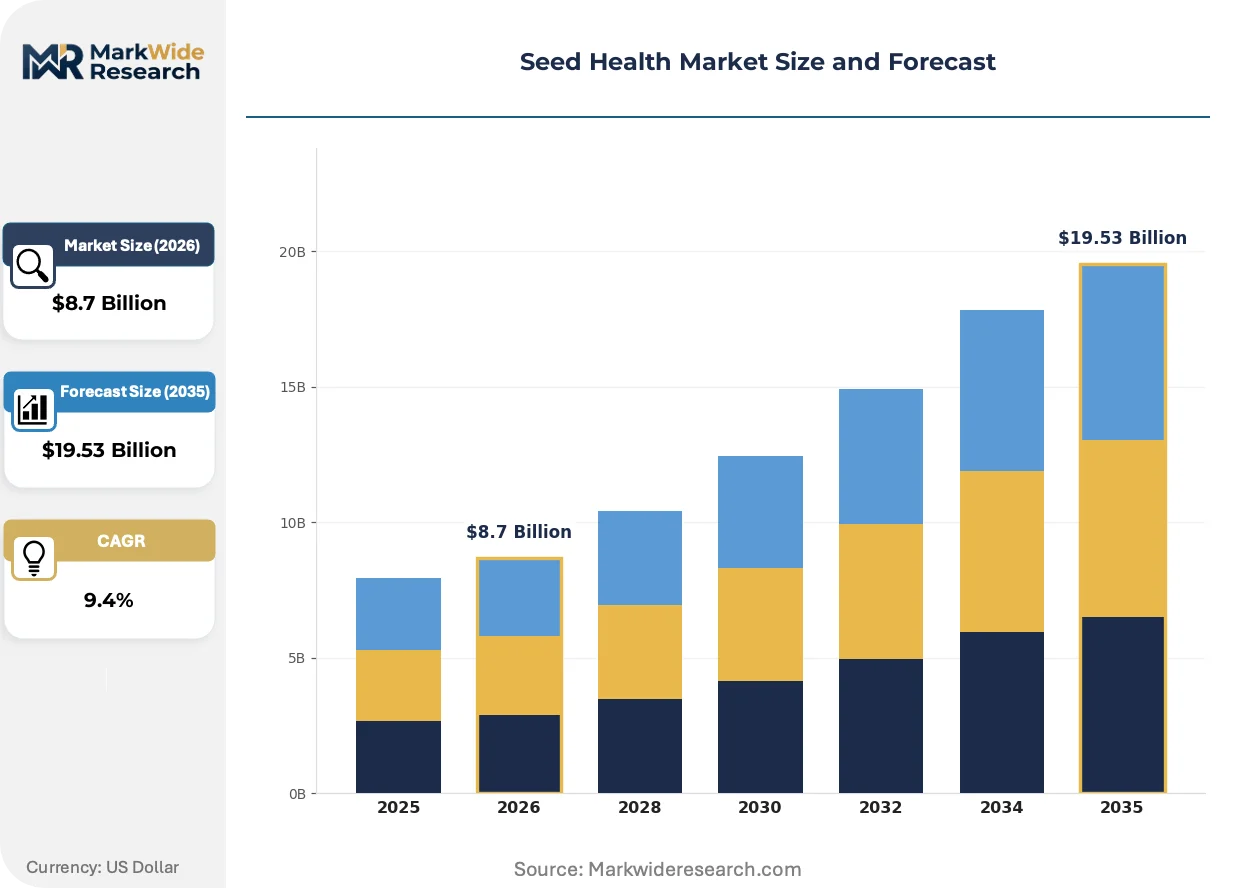
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthetic Seeds, Organic Seeds, Hybrid Seeds, GM Seeds Application: Agricultural Farming, Horticulture, Research & Development, Commercial Production Trait: Disease Resistance, Yield Enhancement, Drought Tolerance, Herbicide Tolerance End Use Industry: Crops, Vegetables, Fruits, Ornamental Plants |
| Companies Covered | Seed Health, Bayer, Syngenta, Corteva Agriscience, Limagrain, KWS SAAT, Land O'Lakes, Sakata Seed, Takii Seed, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Seed Health Market Evolving Landscape
Biological seed treatment platforms are decomposing the traditional segmentation between chemistry-driven protection and genetics-driven resistance. Three convergent developments are restructuring competitive positioning and value capture mechanisms.
RNA interference seed treatments are decomposing the fungicide market for soybean rust and Fusarium control. Brazilian farmers in Mato Grosso and Paraná are adopting dsRNA-coated varieties at twice the rate of North American corn belts, drawn by residue-free export certification. The technology is decomposing premium pricing power for triazole chemistry while forcing incumbents to license or develop parallel RNAi pipelines.
The EU Green Deal's pesticide reduction targets are reshaping product registration through EFSA's hazard-based cut-off criteria. Seed treatment formulators are reformulating away from neonicotinoid and fipronil actives ahead of 2030 withdrawal deadlines, redirecting R&D toward microbial metabolites and peptide-based biofungicides. German and French distributors are consolidating biological-only procurement catalogs, squeezing synthetic chemistry shelf space.
Farmer purchasing for seed health inputs is fragmenting across digital platforms and cooperative bulk-buying arrangements. Traditional ag-retail relationships in Iowa and Illinois are losing share to direct-manufacturer subscription models and regional seed cooperative volume tenders. The shift is most visible in soybean and cotton belts where price transparency apps compress information asymmetries between distributors and growers.
Seed Health Market Segmentation
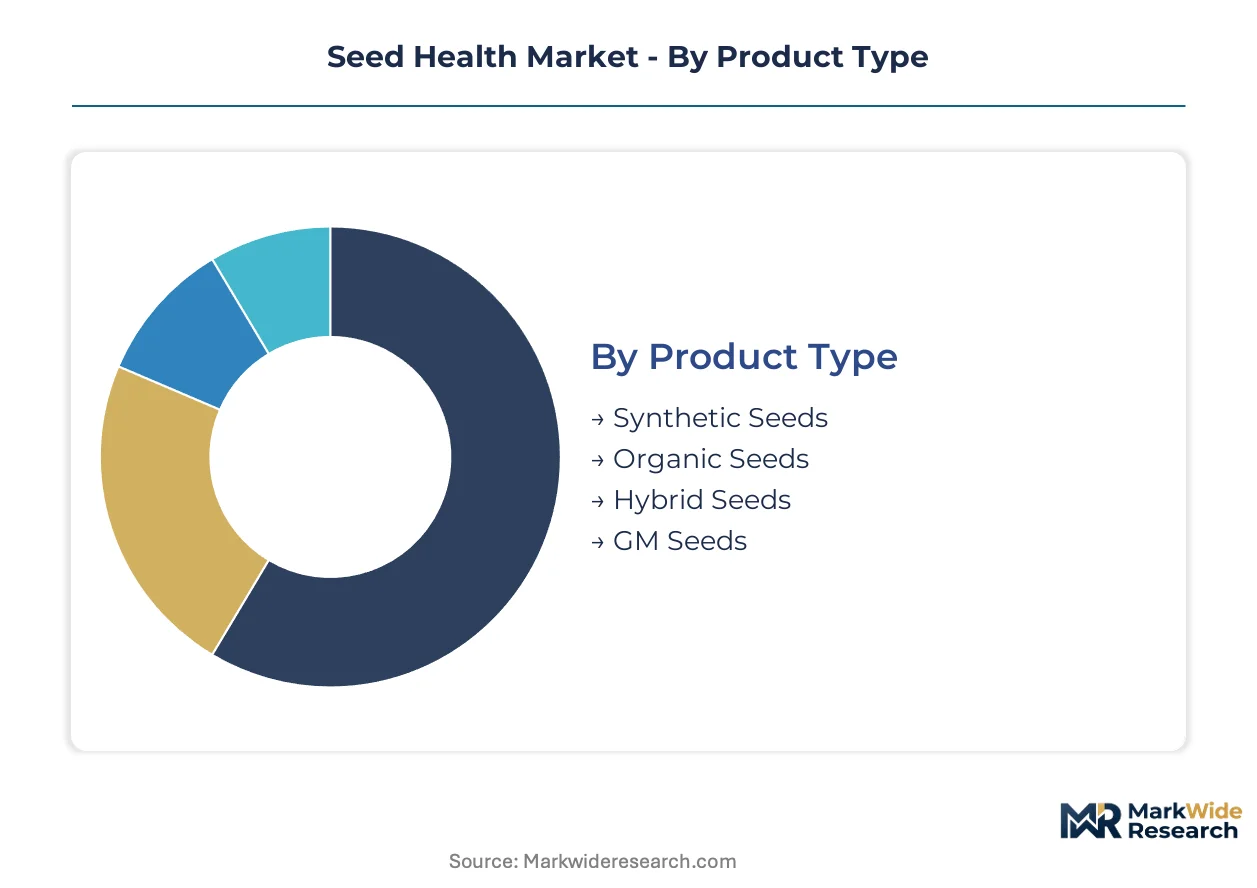
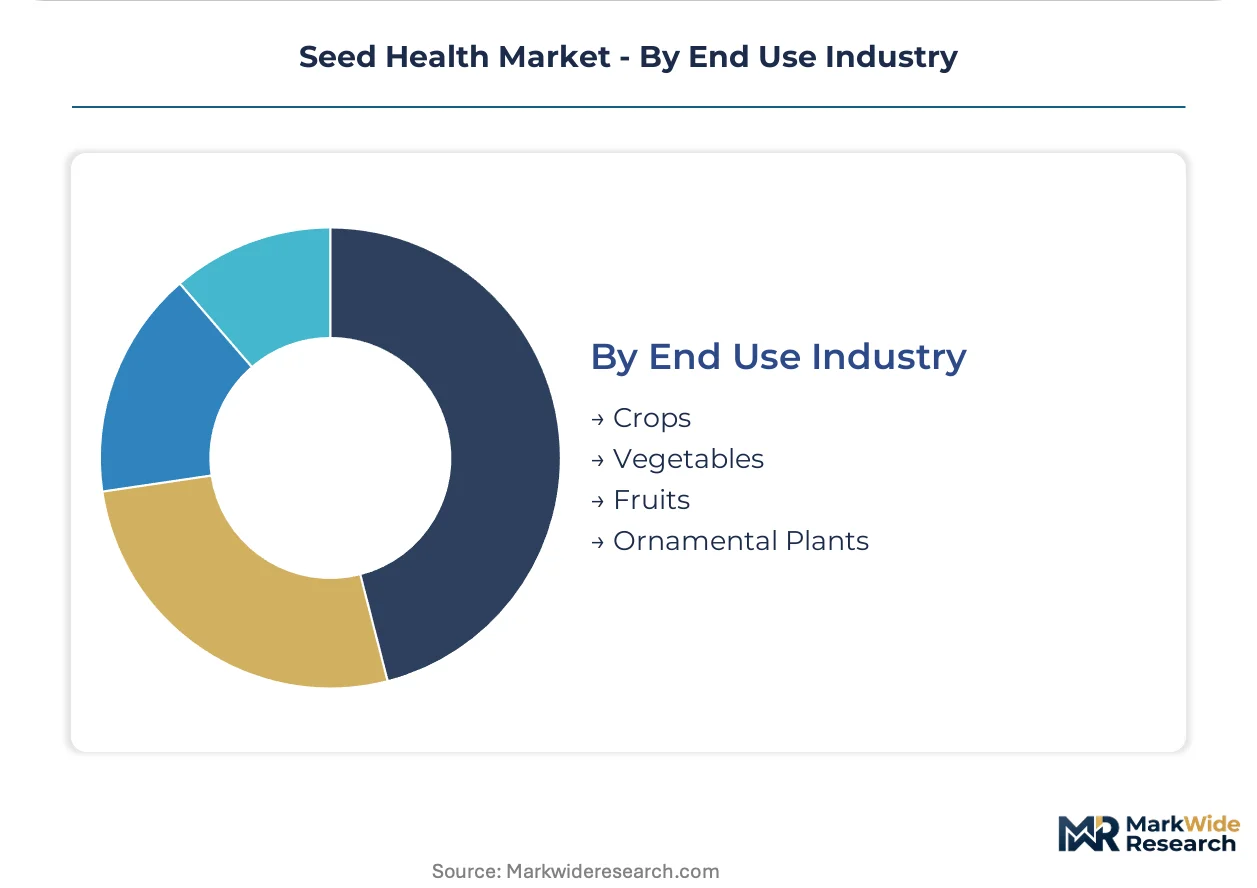
Segmentation in seed health reveals divergent R&D priorities across germplasm types and end-use applications. Trait integration complexity and regulatory pathways vary sharply between commodity row crops and specialty horticulture systems.
Product Type:
Domestic consumption dominates synthetic and hybrid categories, while organic and GM varieties face heavier export orientation due to EU and Asian regulatory fragmentation.
- Synthetic Seeds:Chemically treated propagation material combining fungicides, insecticides, and polymers for field durability. Demand concentrates in Brazil's Cerrado soybean belt where farmers combat nematode resistance through neonicotinoid-coated varieties. ANVISA phytosanitary protocols create 18-24 month commercialization delays for new active ingredient introductions.
- Hybrid Seeds:Cross-pollinated varieties integrating disease resistance loci through conventional breeding programs. Iowa and Illinois corn belts anchor North American procurement, though Brazilian safrinha corn systems are expanding double-crop adoption. Corteva and Bayer germplasm libraries command premium positioning through stacked trait packages.
- Organic Seeds:Certification-compliant propagation material excluding synthetic chemical treatments. EU Green Deal pesticide reduction targets are compressing conventional chemistry shelf space in German and French distribution channels.
- GM Seeds:Transgenic varieties incorporating foreign DNA for herbicide tolerance and insect resistance. Argentine wheat and Paraguay soybean systems represent volume concentration amid EU import restriction complexity.
Hybrid seeds hold the largest share; momentum sits with organic seeds.
Application:
Volume concentration tilts toward large-scale mechanized operations, though research pipelines and commercial propagation facilities command disproportionate margin capture.
- Agricultural Farming:Row-crop and broad-acre systems consuming treated seed at commercial scale. Mato Grosso and Paraná soybean farmers are adopting RNA interference coatings at twice the rate of North American corn belts, drawn by residue-free export certification requirements.
- Commercial Production:Professional nursery and greenhouse propagation facilities requiring certified pathogen-free germplasm. California's Central Valley vegetable transplant industry enforces zero-tolerance protocols for Xanthomonas and Pseudomonas syringae contamination.
- Horticulture:Specialty crop and protected cultivation systems emphasizing vigor indices and germination uniformity. Netherlands glasshouse tomato and pepper sectors drive varietal innovation through seed company partnership programs.
- Research & Development:Academic and corporate breeding pipelines advancing CRISPR-edited disease resistance traits. Corteva's microbial pipeline and university programs are stacking fungal resistance loci directly into elite hybrid backgrounds.
Agricultural farming anchors volume; commercial production shows the steepest expansion trajectory.
Trait:
Cost tier stratification separates premium disease resistance packages from commoditized yield enhancement applications facing biological generic compression.
- Disease Resistance:Genetic and chemical protection against fungal, bacterial, and viral pathogens. Fusarium and soybean rust pressure in Brazil's Cerrado is accelerating CRISPR trait integration and RNA interference coating adoption.
- Yield Enhancement:Growth promotion and stress mitigation technologies. Generic biologicals are proliferating in agricultural farming channels, compressing margin structures for microbial inoculant formulators.
- Drought Tolerance:Water stress adaptation through breeding and seed-applied biologicals. India's fragmented rice-wheat systems represent underpenetrated volume for drought-tolerant variety distribution through state agricultural universities.
- Herbicide Tolerance:Genetic modification enabling broad-spectrum weed control chemistry. US Midwest soybean systems maintain concentration despite EPA regulatory scrutiny on drift and resistance management protocols.
Disease resistance commands premium pricing; drought tolerance is gaining share fastest.
End Use Industry:
Customer type fragmentation distinguishes commodity crop procurement through cooperatives from specialty vegetable contracting with direct manufacturer subscription models.
- Crops:Cereal, oilseed, and fiber production systems at commercial scale. Brazil's national agricultural regulator enforces strict germplasm import protocols, creating compliance bottlenecks for multinational suppliers.
- Vegetables:Brassica, solanaceous, and cucurbit production for fresh and processing markets. California, Spain's Almería, and China's Shandong province anchor global transplant and direct-seed demand.
- Fruits:Tree, vine, and berry propagation requiring certified virus-free rootstock. Washington State apple and Italian table grape nurseries enforce phytosanitary certification standards exceeding minimum regulatory thresholds.
- Ornamental Plants:Floriculture and landscape propagation emphasizing aesthetic uniformity and shelf life. Netherlands Aalsmeer auction systems and Colombia's Bogotá savanna drive varietal turnover through breeder royalty structures.
Crops dominate volume; vegetables show strongest pricing power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil treats seed health as an export-compliance necessity, while the United States approaches it as yield-optimization infrastructure. Germany and France treat biological alternatives as regulatory mandates, whereas India treats them as cost-reduction tools for smallholders.
United States
Iowa and Illinois corn belts drive demand for stacked trait packages integrating CRISPR-edited disease resistance. The EPA's biopesticide registration pathways under FIFRA compress time-to-market for microbial seed treatments. Corteva Agriscience anchors R&D activity in Johnston, Iowa, where germplasm libraries merge with biological coating development.
Brazil
Mato Grosso and Paraná soybean farmers adopt RNA interference coatings at twice North American rates, driven by residue-free export certification requirements. ANVISA enforces strict phytosanitary protocols for imported germplasm, creating 18-24 month commercialization delays. The Cerrado soybean belt concentrates procurement of nematode-resistant treated varieties as chemical resistance intensifies.
Germany
The EU Green Deal's pesticide reduction targets force substitution of chemical seed treatments with microbial inoculants. EFSA's hazard-based cut-off criteria reshape product registration pathways, accelerating biological platform R&D. Bayer leverages its Leverkusen-based microbial pipeline to sustain premium positioning across EU distribution channels.
India
Fragmented rice-wheat systems in Punjab and Haryana represent underpenetrated volume for drought-tolerant biological seed treatments. State agricultural universities serve as distribution anchors for farmer producer organizations. The central government's PLI scheme for agriculture inputs channels investment toward domestic microbial formulation capacity.
China
Shandong province's vegetable transplant industry enforces zero-tolerance protocols for bacterial pathogens in certified germplasm. The Ministry of Agriculture's germplasm import regulations create compliance bottlenecks for multinational suppliers. Yangtze River Delta greenhouse clusters drive demand for vigor-indexed propagation material in protected cultivation systems.
Seed Health Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in seed health. Three multinational suppliers control over 70% of novel fungicide and insecticide active ingredients for seed treatment, creating supply vulnerability for generic formulators. The competitive landscape stratifies into biotechnology-integrated platforms, chemistry-anchored portfolios, and regional germplasm specialists. M&A activity concentrates on microbial pipeline acquisitions, while strategic partnerships target CRISPR trait licensing.
Within the integrated biotechnology tier, Bayer and Syngenta exemplify archetypes combining germplasm libraries with crop protection chemistry. Corteva Agriscience occupies a distinct position through gene-edited disease resistance traits and biological seed coatings. Among regional specialists, KWS SAAT and Sakata Seed represent family-controlled seed houses with concentrated geographic footprints. Land O'Lakes anchors cooperative-owned distribution in North American agricultural channels.
| Leading Market Players |
|---|
| Seed Health |
| Bayer |
| Syngenta |
| Corteva Agriscience |
| Limagrain |
| KWS SAAT |
| Land O'Lakes |
| Sakata Seed |
| Takii Seed |
| Others |
Value Network & Pricing Analysis
ANVISA's phytosanitary certification requirements for imported germplasm simultaneously gate supplier qualification and stratify price tiers, forcing multinational suppliers to absorb compliance costs while regional distributors capture margin through expedited clearance relationships.
Pricing Analysis
Long-term offtake contracts dominate procurement between integrated biotechnology platforms and large-scale agricultural farming operations, while spot purchasing persists among smallholder channels and specialty horticulture buyers. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by trait complexity and certification grade, with CRISPR-edited disease resistance commanding substantial premiums over conventional coated varieties. Price erosion runs through yield enhancement applications as generic biologicals proliferate, compressing margin structures for microbial inoculant formulators. Agricultural farming operations in Brazil's Cerrado exhibit lowest price sensitivity due to export certification requirements, while India's fragmented rice-wheat smallholders drive hardest bargain negotiations.
Supply Chain Analysis
Strategic stockpiling of microbial active ingredients and polymer coating materials characterizes supplier inventory strategy, buffering against fermentation batch variability and seasonal seed processing peaks. Manufacturing concentration centers on Germany, the United States, and Brazil, with Leverkusen and Johnston anchoring R&D-integrated production while Mato Grosso hosts regional formulation facilities. Raw material dependencies include fermentation-derived microbial metabolites, synthetic polymer binders, and CRISPR-edited germplasm foundations. Single-source vulnerability concentrates in novel fungicide active ingredients controlled by three multinational suppliers. Distribution runs through ag-retail cooperatives in North American corn belts and state agricultural university networks in Indian Punjab and Haryana.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Seed health is entering a cyclical recovery phase as biological registration pathways mature and farmer procurement normalizes following EU Green Deal transition turbulence.
For Market Incumbents: Secure microbial pipeline acquisitions ahead of EPA biopesticide approval accelerations, defending against CRISPR trait integration that decomposes traditional chemistry-germplasm boundaries. Prioritize backward integration into precision fermentation capacity to capture cost parity with synthetic treatments. Lock long-term offtake agreements with Brazil's Cerrado cooperatives before ANVISA clearance bottlenecks intensify. For New Entrants and Emerging Players: EPA's streamlined biopesticide fast-track offers regulatory arbitrage against EFSA's hazard-based cut-off criteria, enabling time-to-market compression for microbial seed coating platforms. Target India's fragmented rice-wheat systems through state agricultural university distribution partnerships, exploiting underpenetrated volume for drought-tolerant biological treatments. Pursue direct-manufacturer subscription models displacing traditional ag-retail relationships in soybean and cotton belts. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed microbial formulation specialists lacking germplasm integration, presenting rollup opportunities as biological-chemistry convergence accelerates. Five-to-ten year viability hinges on successful CRISPR trait-coating integration and carbon credit protocol qualification for nitrogen fixation applications. Monitor RNA interference coating adoption rates in Mato Grosso and Paraná as inflection indicator for residue-free export certification demand.| Strategic Initiative | Industry Significance |
|---|---|
| Microbial Pipeline Acquisition | Consolidates fermentation capacity ahead of biological-chemistry cost parity inflection. |
| CRISPR Trait Licensing Agreement | Stacks fungal resistance loci directly into elite hybrid backgrounds bypassing coating dependency. |
| Precision Fermentation Scale-Up | Enables commercial-scale microbial metabolite production rivaling synthetic active ingredient costs. |
| Carbon Credit Protocol Integration | Qualifies biological nitrogen fixation traits for emerging soil carbon revenue stacking beyond yield protection. |
| State University Distribution Partnership | Anchors smallholder channel penetration through farmer producer organization networks in underpenetrated geographies. |
Research Methodology
Operator-level perspectives from seed treatment formulators, germplasm breeding directors, ag-retail procurement managers, and phytosanitary compliance officers anchored the qualitative base. Primary interview insights combined with secondary validation from EPA biopesticide registration databases, ANVISA import protocol filings, EU Green Deal implementation trackers, and SEC 10-K disclosures from integrated biotechnology platforms. Bottom-up volume estimates triangulated against top-down market sizing across product type, application, trait, and end-use industry segmentation dimensions.
Sensitivity analysis tested forecast robustness against regulatory timeline acceleration scenarios and biological efficacy variability assumptions. The analytical framework modeled price-volume dynamics across synthetic, hybrid, organic, and GM seed categories; agricultural farming, commercial production, horticulture, and research applications; disease resistance, yield enhancement, drought tolerance, and herbicide tolerance traits; and crops, vegetables, fruits, and ornamental end-use industries. CAGRs derived from regression-adjusted historical trajectory analysis incorporating input from industry-specific forecast inputs including germplasm import clearance timelines and farmer adoption curve parameters.
Underlying assumptions cover EPA biopesticide approval velocity, EU pesticide reduction target enforcement intensity, and ANVISA phytosanitary protocol stability, with deviation risk concentrated in biological efficacy consistency across soil temperature gradients and CRISPR regulatory classification shifts. Revision becomes warranted when RNA interference coating adoption crosses threshold penetration in residue-sensitive export markets or when carbon credit protocol qualification rates for biological nitrogen fixation diverge materially from baseline expectations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Myanmar Seed Market
Seeds
Watermelon Seeds Market
Seeds
South America Chia Seeds Market
Seeds
Global Rice Seed Market
Seeds
Mustard Seeds Market
Seeds
Philippines Rice Seed Market
Seeds
Myanmar Maize Seed Market
Seeds
China Seed Market
Seeds
Global Seed Market
Seeds
North America Alfalfa Seed Market
Seeds
Asia-Pacific Maize Seed Market
Seeds
Global Alfalfa Seed Market
Seeds
Cover Crop Seed Varieties Market
Seeds
Genetically Modified Seeds Market
Seeds
Native Grass Seeds Market
Seeds
Africa Chia Seeds Market