
 Cowpeas Market | 2026-2036
Cowpeas Market Size, Share, and Industry Trends Forecast 2026-2036
Cowpeas Market Analysis
Multi-source seed procurement is hardening across the cowpeas value chain as buyers diversify germplasm risk. Safal Seeds & Biotech Ltd. leverages its biotech R&D pipeline to develop climate-resilient hybrids. Zenith Hybrid Seeds Pvt. Ltd. anchors its position through geographic dominance in South Asian legume belts. Kenya Seed Company competes via public-sector distribution networks reaching smallholder cooperatives.
Cowpeas are drought-tolerant annual legumes containing protein levels between 23% and 30% by dry weight, primarily cultivated for human consumption, livestock feed, and soil nitrogen fixation through symbiotic rhizobium associations. Whole cowpeas sustain the largest volume share due to staple-food consumption across Sub-Saharan Africa and South Asia. Cowpea flour represents the fastest-growing product type as gluten-free baking and protein-fortified processed foods expand formulation demand. The food industry end-use segment occupies the deepest margin pools, particularly where cowpea protein isolates replace costlier soybean and pea protein in extruded snacks and meat analogs.
Nigeria's Seed Council and Kenya's Plant Health Inspectorate Service enforce germplasm certification and phytosanitary standards that filter informal seed channels and elevate commercial hybrid penetration. The FAO's International Treaty on Plant Genetic Resources for Food and Agriculture shapes cross-border germplasm exchange protocols affecting breeder access to landrace diversity. Stakeholders must monitor varietal registration timelines and climate-adaptation breeding priorities to secure germplasm access ahead of shifting rainfall patterns.
Market Dynamics
Multi-source seed procurement is hardening across the cowpeas value chain as buyers diversify germplasm risk. Climate-resilient breeding programs and national certification frameworks are compressing informal seed channels while elevating commercial hybrid penetration.
Growth Catalysts
- Nigeria's Seed Council certification:National seed certification rules tighten quality benchmarks and filter informal channels, accelerating commercial hybrid adoption in northern corridors.
- Gluten-free baking expansion:Cowpea flour demand accelerates as protein-fortified processed foods displace wheat-based formulations in extruded snacks.
- Symbiotic nitrogen fixation:Soil regeneration mandates in drought-prone regions pull cowpeas into rotational cropping systems for sustainable intensification.
Market Restraints
- Input cost volatility:Fertilizer and irrigation infrastructure costs swing with energy prices, compressing smallholder margins in rainfed production zones.
- Supply concentration risk:Germplasm access narrows as Kenya's Plant Health Inspectorate Service and Nigeria's Seed Council restrict cross-border landrace exchange.
- Protein isolate technical limitation:Cowpea protein extraction yields lag soybean and pea protein efficiency, constraining cost-competitive meat analog formulations.
Strategic Opportunities
- Kenyan smallholder cooperatives:Public-sector distribution networks reach underpenetrated producer clusters, opening captive procurement channels for certified seed.
- Cowpea protein isolate applications:Meat analog and extruded snack sectors offer white space for cost-competitive soybean displacement.
- FAO germplasm treaty protocols:Cross-border landrace access frameworks create regulatory tailwinds for climate-adaptation breeding pipelines.
Industry Challenges
- Phytosanitary certification timelines:Kenya's Plant Health Inspectorate Service and Nigeria's Seed Council extend varietal registration cycles, delaying commercial release of drought-tolerant hybrids.
- Climate-adaptation breeding skill gaps:Molecular marker-assisted selection and rapid generation advancement require specialized personnel scarce in national agricultural research systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cowpeas Market |
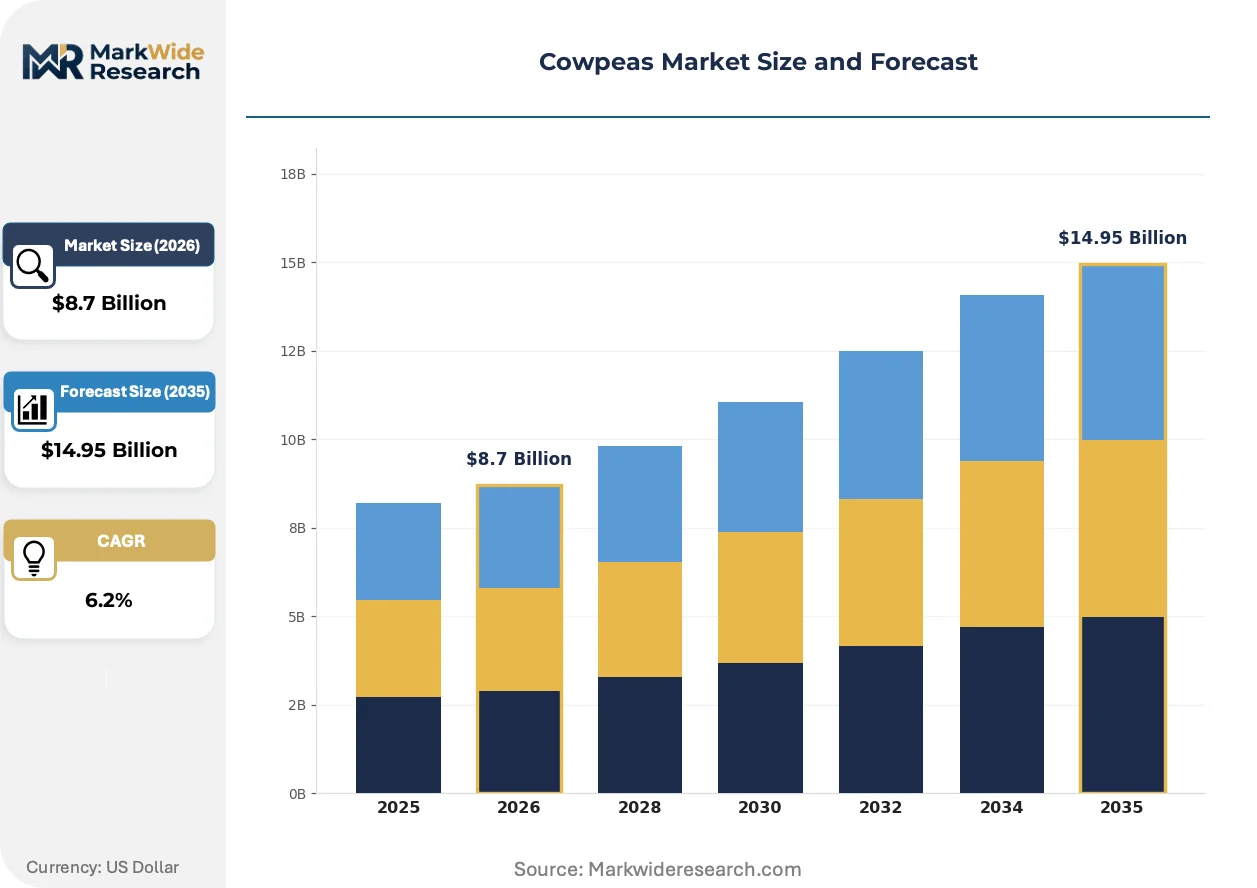
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.95 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Cowpeas, Split Cowpeas, Cowpea Flour, Cowpea Snacks Distribution Channel: Supermarkets, Online Retailers, Farmers' Markets, Wholesale Distributors End User: Food Industry, Animal Feed, Nutraceuticals, Home Cooking Geographical Variety: Black-eyed Peas, Brown Cowpeas, Red Cowpeas, White Cowpeas |
| Companies Covered | Safal Seeds & Biotech Ltd., Zenith Hybrid Seeds Pvt. Ltd., Ajinkya Seeds Pvt. Ltd., Meridian Seeds and Nursery Ltd., SARO Agrosciences Limited, Premier Seed Nigeria Ltd., Kenya Seed Company, Coperaguas Cooperativa Agroindustrial, Gold Agric Nigeria Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cowpeas Market Emerging Trajectories
Decentralized seed multiplication and climate-smart breeding architectures are reshaping how germplasm reaches smallholders. Three intersecting developments are compressing traditional supply hierarchies and opening new value-capture nodes.
Community-based seed production networks are decentralizing certified germplasm access. Farmer field schools and cooperative multiplication plots in Kaduna and Kano corridors bypass centralized distribution bottlenecks. This architecture compresses seed delivery timelines from formal breeding stations to planting rows.
FAO's International Treaty on Plant Genetic Resources for Food and Agriculture is tightening cross-border germplasm exchange protocols. Breeder access to West African and South Asian landrace diversity now requires documented benefit-sharing agreements. Nigerian and Kenyan national gene banks are responding with accelerated in-situ conservation programs.
Food industry buyers in West Africa are consolidating direct procurement relationships with processor cooperatives. Bulk contracting for cowpea flour and protein isolate displaces spot-market purchasing through traditional aggregators. This concentration is most visible in Nigeria's northern processing corridors serving gluten-free baking and protein-fortification demand.
Cowpeas Market Segmentation
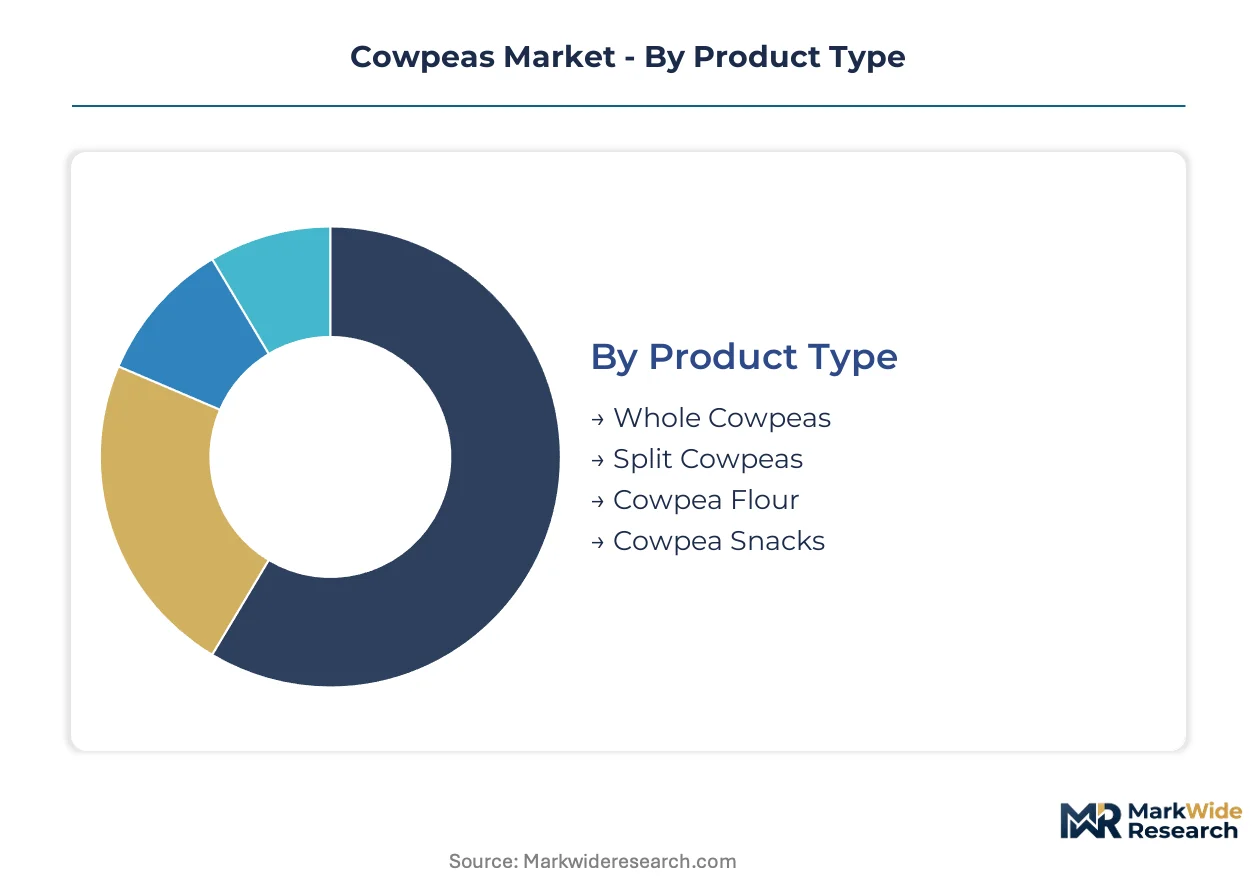
Cowpeas market segmentation reveals how physical form, channel access, and end-use specifications determine value capture across the value chain. Distinct buyer requirements for processing tolerance, protein content, and distribution reliability create tiered pricing structures that reward specialized supply configurations.
Product Type:
Supply concentration in processing infrastructure favors formats with established milling and extrusion capacity, while emerging applications reshape capacity allocation decisions.
- Whole Cowpeas:Unprocessed seeds retain hull integrity and germination viability for direct human consumption and planting stock. Nigerian northern corridors and Kano processing clusters absorb the largest procurement volumes for staple-food distribution. Quality premiums attach to seed size uniformity and weevil-free storage.
- Cowpea Flour:Milled powder with protein content between 23% and 30% by dry weight serves gluten-free baking and protein-fortified extruded snacks. West African food manufacturers in Kaduna and Kano corridors are expanding direct procurement contracts for this format. Technical constraints around extraction yields and color stability limit cost-competitive displacement of soybean and pea protein isolates.
- Split Cowpeas:Dehulled and divided seeds accelerate cooking time for prepared food manufacturers seeking pulse ingredients with reduced hydration requirements.
- Cowpea Snacks:Roasted, fried, or extruded finished products target convenience-food channels with value-added formulation and packaging.
Whole Cowpeas absorb the bulk of installed capacity; Cowpea Flour is expanding most quickly.
Distribution Channel:
Channel selection determines margin retention and quality control exposure, with formal retail and direct procurement compressing traditional aggregator hierarchies.
- Supermarkets:Organized retail chains in Nigerian urban centers enforce standardized packaging, lot traceability, and moisture content specifications. Cold storage requirements and shelf-space fees filter smaller suppliers.
- Wholesale Distributors:Aggregator networks connecting farm-gate production to processor and institutional buyers dominate volume throughput in West African corridors. Price discovery occurs through spot-market negotiations with limited forward contracting.
- Online Retailers:E-commerce platforms serving diaspora populations and urban consumers seeking specialty cowpea varieties bypass physical distribution bottlenecks.
- Farmers' Markets:Direct producer-to-consumer sales preserve landrace diversity and command freshness premiums in localized trade.
Wholesale Distributors channel the greatest volume; Supermarkets capture the steepest margin expansion trajectory.
End User:
Application-specific protein specifications and formulation requirements segment buyers by technical sophistication and procurement scale.
- Food Industry:Processed food manufacturers in Nigeria's northern corridors formulate cowpea flour into gluten-free baked goods, extruded snacks, and meat analogs. Protein isolate applications face technical limitations in extraction efficiency relative to soybean and pea protein competitors.
- Animal Feed:Livestock producers utilize cowpea hay and seed meal for ruminant and poultry rations, leveraging symbiotic nitrogen fixation benefits in rotational cropping systems.
- Home Cooking:Household consumers across Sub-Saharan Africa and South Asia sustain traditional preparation methods for whole and split cowpeas as dietary staples.
- Nutraceuticals:Functional food and supplement formulators target protein isolates and fiber concentrates for specialized health applications.
Food Industry commands the deepest margin pools; Nutraceuticals is climbing the fastest.
Geographical Variety:
Varietal differentiation reflects adaptation to rainfall patterns, pest pressure, and regional culinary preferences that shape seed certification priorities.
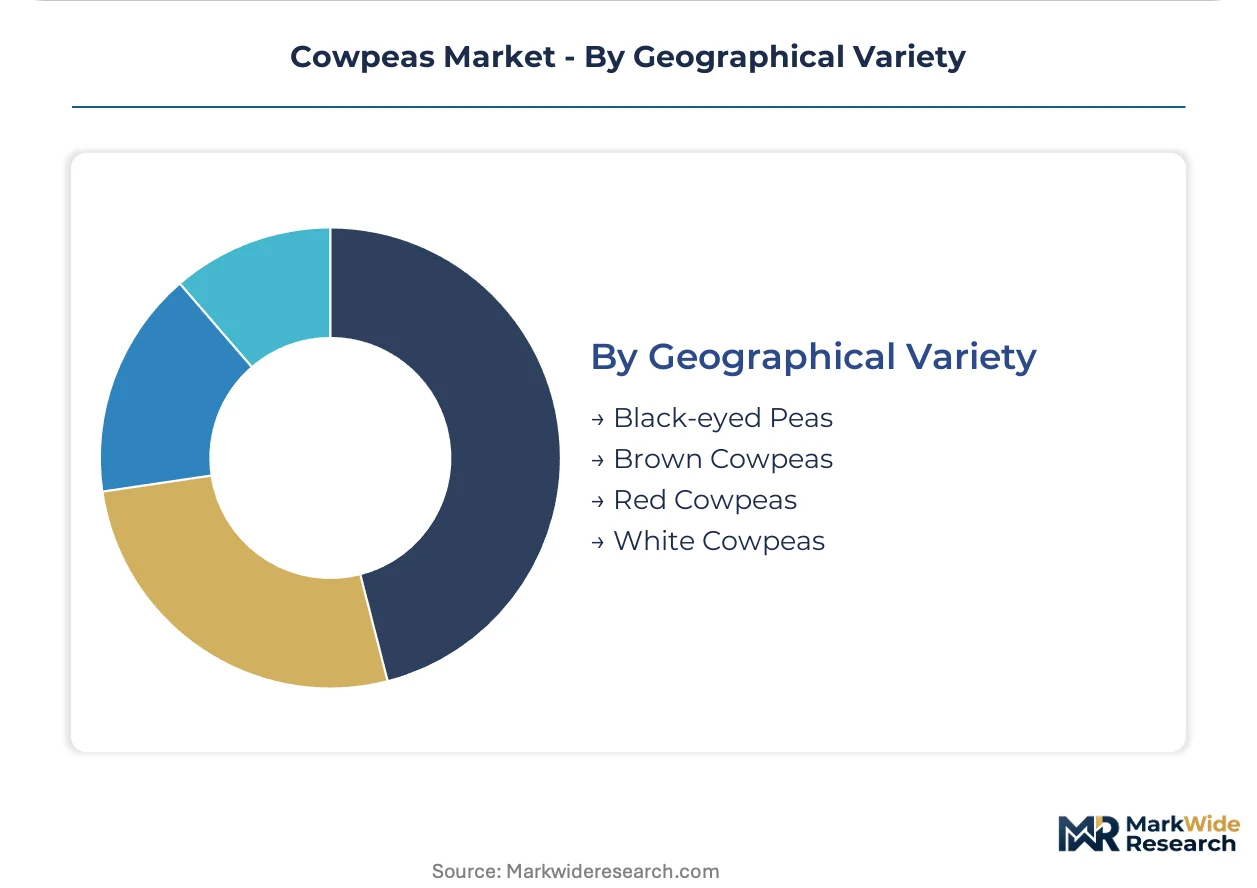
- Black-eyed Peas:Cream-colored seeds with distinctive black hilum markings dominate West African and North American production. Nigeria's Seed Council certification programs prioritize this variety for commercial hybrid penetration in northern corridors.
- Brown Cowpeas:Earth-toned seed coats with intermediate cooking times serve regional markets in East Africa and parts of South Asia where drought tolerance outweighs visual uniformity requirements.
- Red Cowpeas:Pigmented seed varieties with enhanced antioxidant properties target niche nutraceutical and specialty food channels.
- White Cowpeas:Pale seed coats preferred for specific traditional preparations in selected West African and South Asian culinary traditions.
Black-eyed Peas holds the dominant production footprint; Brown Cowpeas is gaining share fastest in drought-adaptation breeding programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nigerian seed corridors anchor the cowpeas trade geography. Kano and Kaduna processing clusters absorb the bulk of West African procurement volume. National certification frameworks in Nigeria and Kenya are compressing informal germplasm channels while accelerating commercial hybrid penetration.
Nigeria
Kano corridor processors are expanding direct procurement contracts for cowpea flour and protein isolates. The country's Seed Council enforces germplasm certification rules that filter informal seed channels and elevate quality benchmarks for commercial hybrids. Northern Kaduna and Kano corridors concentrate the deepest food industry buyer activity for gluten-free baking applications.
Kenya
Smallholder cooperatives in drought-prone zones are pulling cowpeas into rotational cropping systems for nitrogen fixation benefits. The Plant Health Inspectorate Service extends phytosanitary certification timelines that delay commercial release of climate-adapted varieties. Public-sector distribution networks reach underpenetrated producer clusters in the Rift Valley and Eastern regions.
India
South Asian legume belts sustain traditional consumption of whole and split cowpeas as dietary staples. The country's national agricultural research system operates climate-resilient breeding programs targeting rainfall variability. Maharashtra and Karnataka processing corridors are expanding milling capacity for protein-fortified extruded snacks.
Brazil
Coperaguas Cooperativa Agroindustrial exemplifies cooperative-led production models in tropical legume zones. The national agricultural research corporation Embrapa maintains germplasm banks supporting drought-tolerant varietal development. Goiás and Minas Gerais corridors concentrate commercial seed multiplication for domestic and regional export.
United States
Black-eyed pea demand concentrates in Southern culinary markets and diaspora food channels. The USDA maintains germplasm conservation protocols affecting breeder access to African landrace diversity. Texas and Georgia processing clusters serve institutional foodservice and packaged snack formulations.
Cowpeas Market Vendor Landscape
Capacity expansion dominates the current landscape as seed companies harden multi-source germplasm procurement. The vendor base organizes around three tiers: multinational biotech developers with climate-resilient pipelines, regional hybrid specialists with geographic dominance in legume belts, and public-sector distributors reaching smallholder cooperatives. Strategic archetypes include R&D-led biotech innovators, geography-anchored seed multipliers, and cooperative-linked public distributors. Competitive moves concentrate on certified seed capacity expansion and climate-adaptation breeding partnerships.
Within the biotech innovation tier, Safal Seeds & Biotech Ltd. and Zenith Hybrid Seeds Pvt. Ltd. represent contrasting geographic anchoring strategies. Safal occupies a position exemplifying South Asian biotech R&D concentration, while Zenith anchors the regional specialist archetype through dominance in Indian legume production zones. Kenya Seed Company sits within the public-sector distribution archetype, reaching smallholder networks that private competitors cannot access efficiently.
| Leading Market Players |
|---|
| Safal Seeds & Biotech Ltd. |
| Zenith Hybrid Seeds Pvt. Ltd. |
| Ajinkya Seeds Pvt. Ltd. |
| Meridian Seeds and Nursery Ltd. |
| SARO Agrosciences Limited |
| Premier Seed Nigeria Ltd. |
| Kenya Seed Company |
| Coperaguas Cooperativa Agroindustrial |
| Gold Agric Nigeria Ltd. |
| Others |
Supply Flow & Price Mechanics
Food industry buyers in Nigeria's northern Kaduna and Kano corridors concentrate procurement power through direct contracting for cowpea flour and protein isolates, anchoring a contract-based long-term offtake model that rewards certified seed quality and processing tolerance.
Pricing Analysis
Warranty and service bundling remains unbundled in spot-market transactions but attaches to certified seed contracts through germplasm viability guarantees and phytosanitary certification support. Three-tier pricing structure across premium, standard, and economy levels separates breeder-certified hybrids from quality-declared seed and informal landrace channels. Price differentiation hinges on certification tier under Nigeria's Seed Council and Kenya's Plant Health Inspectorate Service protocols, plus volume scale in bulk flour procurement. Cost compression in standard-tier seed is intensifying because fertilizer and irrigation infrastructure costs swing with energy prices. Smallholder cooperatives in Kenya's Rift Valley exhibit highest price sensitivity, while Nigerian food manufacturers sourcing protein isolates show lowest sensitivity due to formulation switching costs.
Supply Chain Analysis
Certification and qualification gating through Nigeria's Seed Council and Kenya's Plant Health Inspectorate Service compresses informal channels while elevating commercial hybrid penetration. Geographic supply concentrates in Nigeria, Kenya, and India, with Brazilian cooperative models expanding in tropical legume zones. Raw material dependencies center on breeder foundation seed, rhizobium inoculants for nitrogen fixation, and milling infrastructure for flour production. Single-source vulnerability in germplasm access narrows as FAO treaty protocols tighten cross-border landrace exchange. Distribution runs through wholesale aggregator networks connecting farm-gate production to processor and institutional buyers, with direct procurement relationships consolidating in Nigerian processing corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cowpeas market is becoming a vertical-integration race as seed companies pursue backward integration into captive germplasm banks and food manufacturers build direct procurement relationships with processor cooperatives.
For Market Incumbents: To counter germplasm access restrictions under tightening FAO treaty protocols, Safal Seeds and Zenith Hybrid Seeds should deepen captive supply of landrace diversity through accelerated in-situ conservation partnerships with Nigerian and Kenyan national gene banks. Incumbents must also expand certified seed multiplication capacity in drought-prone corridors to preempt public-sector distribution networks. For New Entrants and Emerging Players: Launch via community-based seed production networks in underpenetrated Kenyan smallholder cooperatives, bypassing centralized distribution bottlenecks that constrain established competitors. Target cowpea protein isolate applications in meat analog and extruded snack sectors where technical limitations in extraction efficiency have slowed cost-competitive soybean displacement. Penetrate through farmer field school partnerships that embed germplasm access at planting rows. For Investors and Strategic Acquirers: The window for entry favors biotech R&D specialists with climate-resilient breeding pipelines and established varietal registration pathways. Long-term viability rests on molecular marker-assisted selection capabilities and rapid generation advancement infrastructure. Watch for inflection in varietal registration timelines under Nigeria's Seed Council and Kenya's Plant Health Inspectorate Service as signal of regulatory capacity to accelerate drought-tolerant hybrid release.| Strategic Initiative | Industry Significance |
|---|---|
| Climate-Resilient Breeding Partnership | Collaborations with national agricultural research systems accelerate drought-tolerant hybrid development for shifting rainfall patterns. |
| Community-Based Seed Multiplication | Farmer field schools in Kaduna and Kano corridors compress seed delivery timelines from breeding stations to planting rows. |
| Direct Procurement Consolidation | Bulk contracting for cowpea flour displaces spot-market purchasing through traditional aggregator networks in Nigerian processing corridors. |
| In-Situ Conservation Program | National gene bank partnerships secure landrace diversity access ahead of tightening FAO germplasm exchange protocols. |
| Protein Isolate Extraction Scale-Up | Milling capacity expansion in Maharashtra and Karnataka targets protein-fortified extruded snack formulation demand. |
Methodological Framework
Document review covered seed certification regulations, FAO treaty protocols, and national agricultural research system publications, complemented by interviews with breeder program directors, seed company procurement leads, food industry formulation scientists, and smallholder cooperative managers. Secondary validation drew from Nigeria's Seed Council varietal registration databases, Kenya's Plant Health Inspectorate Service phytosanitary records, and FAO germplasm exchange documentation. Bottom-up volume modeling triangulated against top-down demand aggregation from food manufacturer procurement disclosures.
Cross-referencing historical adoption curves against breeder and processor panel input anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product format, distribution channel, end-use application, and geographical variety. CAGRs derived from trend extrapolation adjusted for certification timeline delays and climate-adaptation breeding pipeline acceleration. Industry-specific forecast inputs incorporated symbiotic nitrogen fixation adoption rates in rotational cropping systems and gluten-free baking formulation switching patterns.
Regulatory timeline extensions, rainfall pattern variability, and protein isolate extraction yield breakthroughs are the dominant revision risks to modeled outputs. Forecasts reflect assumptions around Seed Council and Plant Health Inspectorate Service capacity maintenance. A model refresh is warranted upon material change in FAO germplasm treaty enforcement intensity or commercial hybrid registration velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Quinoa Seed Market
Seeds
South America Vegetable Seed Market
Seeds
Okra Seed Market
Seeds
Global Seed Market
Seeds
Vietnam Vegetable Seed Market
Seeds
Africa Grain Seed Market
Seeds
Flaxseed (Linseed) Market
Seeds
North America Tomato Seed Market
Seeds
North America Quinoa Seeds Market
Seeds
Dragon Fruit Seeds Market
Seeds
Asia-Pacific Quinoa Seeds Market
Seeds
South Africa Seed Market
Seeds
Tallow Tree Seed Market
Seeds
South America Chia Seeds Market
Seeds
North America Chia Seeds Market
Seeds
Global Packaged Chia Seeds Market