
 Europe Quinoa Seed Market | 2026-2036
Europe Quinoa Seed Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Quinoa Seed Market Foresight
The EU Green Deal is pivoting agricultural subsidies toward climate-resilient crops, directly expanding the addressable acreage for quinoa cultivation across member states. The British Quinoa Company leverages domestic sourcing to reduce import dependency and strengthen traceability claims. Quinola anchors its portfolio around pre-cooked convenience formats that compete with conventional grain staples. Ekibio specializes in organic certification tiers that differentiate its supply within French retail channels.
Quinoa seed denotes the dried grain of Chenopodium quinoa, a pseudocereal containing approximately 14-18% protein with a complete amino acid profile including lysine, traditionally processed through washing to remove bitter saponins before human consumption. Its primary commercial purpose centers on delivering gluten-free, high-protein ingredients for food manufacturing and direct retail. Organic quinoa occupies the premium tier where margin pools remain deepest due to certification complexity and limited European cultivation. White quinoa leads volume through retail consumer familiarity, while red quinoa gains traction in nutraceutical applications where antioxidant content commands formulation premiums.
EU Green Deal implementation through the Farm to Fork strategy shapes crop rotation incentives, while REACH and EFSA standards govern pesticide residue limits and novel food safety assessments for imported quinoa varieties. CE marking requirements for packaged goods influence labeling and traceability investments across the value chain. Stakeholders must monitor how evolving organic certification harmonization between member states affects cross-border sourcing economics and domestic cultivation subsidies.
Market Dynamics
The EU Green Deal's Farm to Fork strategy is redirecting agricultural subsidies toward climate-resilient crop diversification, fundamentally altering land allocation economics for quinoa cultivation across member states. This policy pivot is compressing the cost gap between imported Andean supply and emerging European domestic production.
Growth Catalysts
- REACH compliance incentives:ECHA pesticide residue standards for imported grains are tightening, creating regulatory headroom for European-grown quinoa with shorter traceability chains and lower chemical input profiles.
- Gluten-free manufacturing demand:Food processors in Germany and France are reformulating bakery and ready-meal portfolios, pulling quinoa protein into ingredient specifications as wheat alternatives face consumer rejection.
- Rotational cropping economics:Quinoa's drought tolerance and low water requirements are absorbing marginal acreage in Spain and Italy where irrigation restrictions under EU water framework directives are rendering traditional cereals unviable.
Market Restraints
- Input cost volatility:Organic certification compliance costs and saponin removal processing equipment represent fixed capital burdens that scale poorly for sub-commercial European harvest volumes.
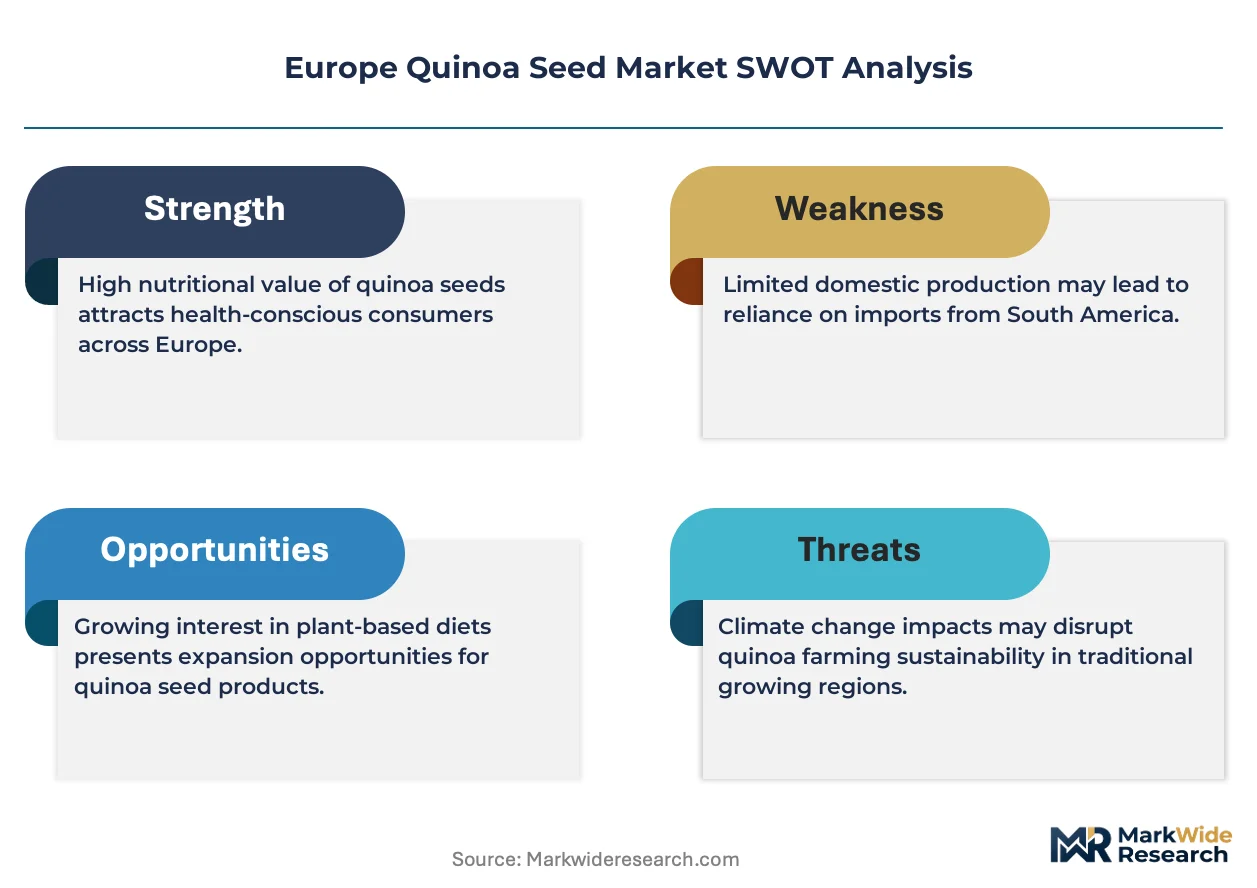
- Supply concentration risk:Over 80 percent of global quinoa seed genetics and breeding stock remains concentrated in Peruvian and Bolivian germplasm banks, creating varietal dependency for European cultivation programs.
- Substitution threat:Teff, amaranth, and buckwheat pseudocereals are competing for the same gluten-free protein positioning in retail and foodservice channels with established supply infrastructure.
Strategic Opportunities
- Eastern European cultivation expansion:Poland and Romania offer underexploited arable land with suitable altitude and temperature profiles for quinoa agronomy, currently absent from commercial seed distribution networks.
- Pre-cooked convenience formats:Shelf-stable microwaveable quinoa pouches are penetrating UK and German retail channels previously dominated by dry grain bulk, capturing time-constrained urban consumers.
- Organic certification harmonization:Proposed EU-wide organic standard alignment would reduce cross-border certification friction for multi-country sourcing operations, lowering compliance overhead for integrated supply chains.
Industry Challenges
- Agronomic expertise scarcity:European extension services and agricultural universities lack quinoa-specific cultivation protocols, forcing early commercial growers to adapt Andean practices without localized research support.
- Processing infrastructure gaps:Industrial-scale saponin removal and sorting equipment is concentrated in South American export hubs, requiring European operators to invest in greenfield facilities or accept higher toll-processing costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Quinoa Seed Market |
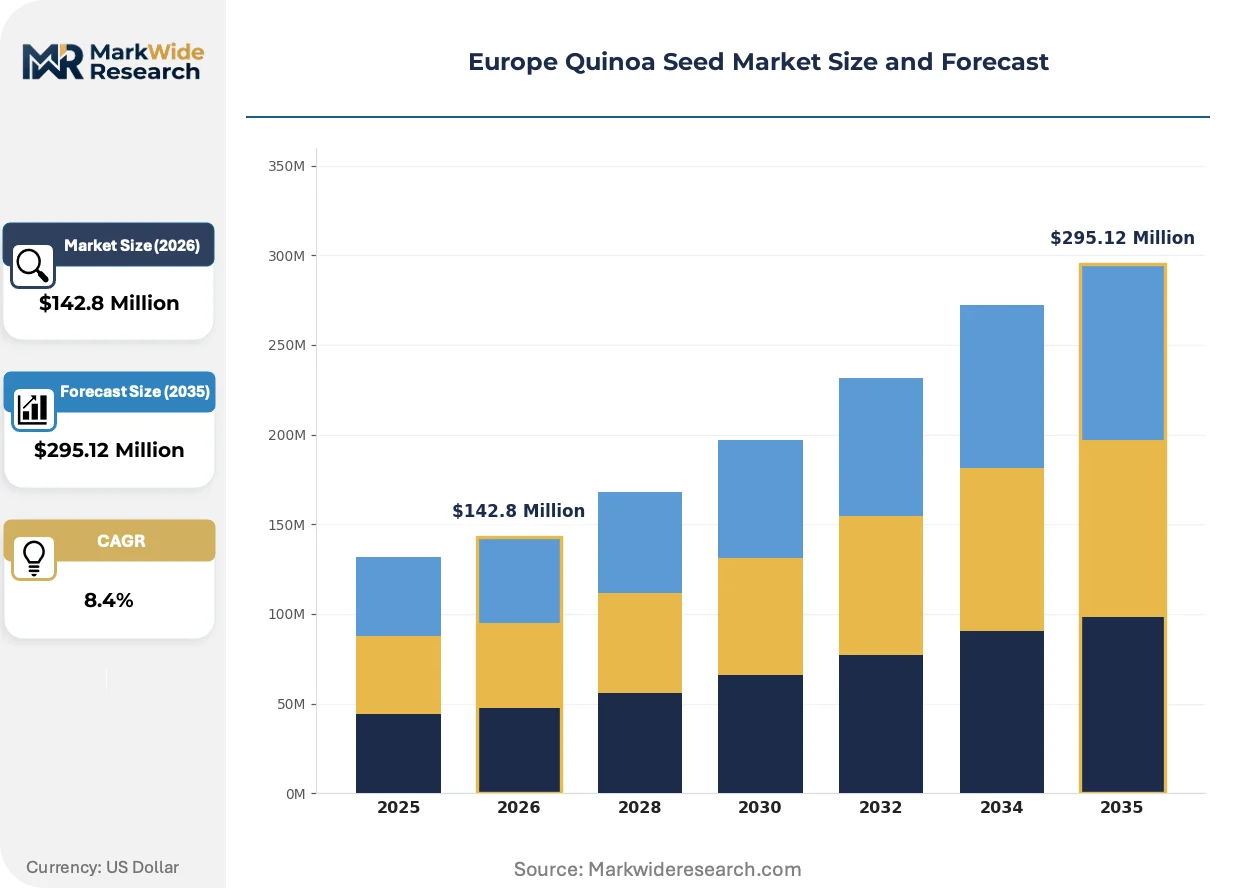
| Market Size in 2026 | $142.8 Million |
| Market Size in 2035 | $295.12 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Quinoa, Non-Organic Quinoa, White Quinoa, Red Quinoa Packaging Type: Bags, Bulk Containers, Pouches, Tins End User: Food Industry, Nutraceuticals, Retail Consumers, Animal Feed Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Distributors |
| Companies Covered | The British Quinoa Company, Agricolor Quinoa, Quinola, Ekibio, Quinoa Marchfeld, Dutch Quinoa Group, Nourish You, pureproducts, Andean Naturals, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Quinoa Seed Market Shifts & Advancements
Mechanical saponin removal technologies and precision breeding programs are converging to reduce processing waste and improve European varietal adaptation. These technical advances are compressing the cost structure gap against incumbent Andean supply while enabling new product format development.
Mechanical abrasion systems for saponin removal are absorbing capital investment previously directed toward water-intensive washing protocols. German and Dutch equipment manufacturers are deploying these systems for contract processors serving domestic organic brands. The technology is absorbing water cost premiums in drought-stressed southern European growing regions where effluent regulations restrict traditional processing methods.
EU Green Deal implementation through the Farm to Fork strategy is mandating 25 percent organic farmland coverage targets by 2030. This regulatory pressure is accelerating quinoa inclusion in crop rotation schemes eligible for ecological focus area subsidies. French and Italian agricultural ministries are responding with varietal trial programs to identify locally adapted cultivars.
Health-conscious retail buyers are consolidating purchasing around certified organic and short-supply-chain claims. German discounters and UK premium multiples are displacing anonymous bulk sourcing with single-origin European quinoa in private label ranges. This preference compression is most visible in urban markets of London, Berlin, and Paris where traceability transparency commands shelf positioning premiums.
Europe Quinoa Seed Market Segmentation
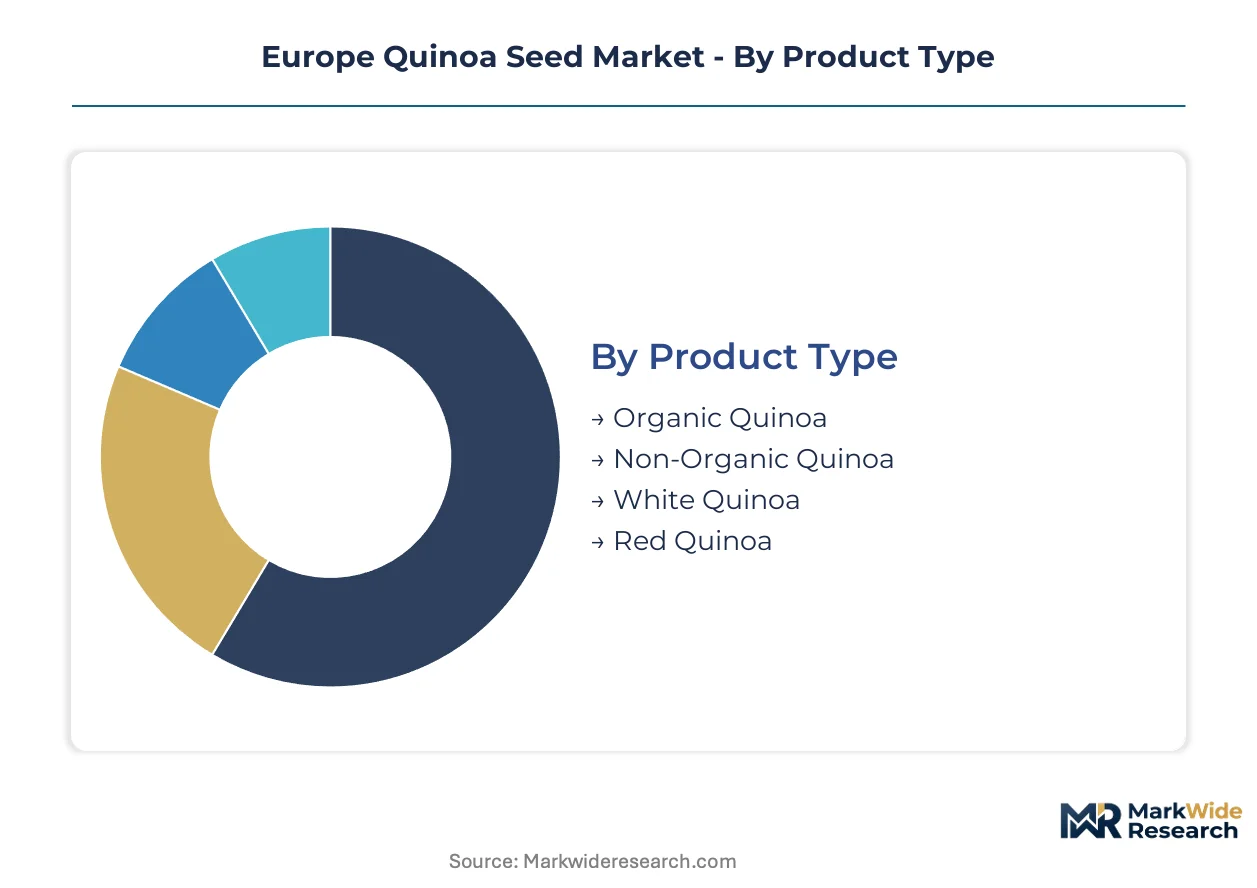
Segmentation in the Europe quinoa seed market reveals how certification tiers, packaging formats, and channel strategies create distinct margin pools. Producers must align supply chain investments with the specific requirements of each segment to capture value.
Product Type:
Supply concentration in organic quinoa channels creates pricing power for certified European growers against bulk Andean imports.
- Organic Quinoa:Certified cultivation under EU organic standards commands premium positioning through restricted pesticide use and full traceability documentation. German and French retailers are consolidating private label ranges around single-origin organic supply, absorbing price premiums for transparency claims.
- White Quinoa:The most established varietal with neutral flavor profile and familiar cooking properties dominates retail shelf space across UK and German supermarkets. Volume concentration in this segment pressures margins through commoditization, though convenience-format innovation sustains differentiation.
- Non-Organic Quinoa:Conventional cultivation with standard pesticide protocols serves price-sensitive food manufacturing and animal feed applications.
- Red Quinoa:Higher anthocyanin content targets nutraceutical formulators and premium foodservice channels in France and Italy.
Today's leader: Organic Quinoa. Tomorrow's challenger: Red Quinoa.
Packaging Type:
Cost tier differentiation separates commodity bulk from value-added convenience formats with divergent capital intensity requirements.
- Pouches:Pre-cooked microwaveable formats capture urban convenience demand in UK and German retail, requiring retort processing investment that barriers smaller suppliers. Time-constrained consumers in London and Berlin are displacing dry grain purchases with shelf-stable ready-to-heat alternatives.
- Bags:Standard dry grain packaging dominates volume through retail and foodservice distribution, with kraft paper and polypropylene variants segmented by sustainability positioning.
- Bulk Containers:Food manufacturers and distributors procure tonnage quantities with minimal processing overhead, concentrating procurement in Rotterdam and Hamburg port zones.
- Tins:Extended shelf-life metal packaging serves emergency food reserves and institutional catering contracts with specific durability requirements.
Pouches are expanding most quickly; bulk containers anchor volume economics.
End User:
Application-driven demand splits between ingredient specifications for food manufacturing and direct retail consumption with opposing quality sensitivities.
- Retail Consumers:Health-conscious households in Germany, France, and the United Kingdom drive gluten-free substitution trends, prioritizing organic certification and origin transparency. German discounters and UK premium multiples are restructuring shelf space around European-sourced quinoa with shortened supply chains.
- Food Industry:Bakery, ready-meal, and snack manufacturers in France and Germany are reformulating wheat-based products, pulling quinoa protein into ingredient specifications with functional binding requirements.
- Nutraceuticals:Red quinoa extracts target antioxidant and protein supplement formulations with pharmaceutical-grade processing standards.
- Animal Feed:High-protein grain substitutes for poultry and aquaculture operations compete on cost with soy and fishmeal alternatives.
Retail Consumers command margin premiums; Food Industry drives volume scaling.
Distribution Channel:
Channel concentration in health food retail and supermarket multiples creates gatekeeper dynamics for new market entrants.
- Supermarkets:German Aldi and Lidl, French Carrefour, and UK Tesco and Sainsbury's control mainstream volume through private label development and promotional pricing cycles. These retailers are displacing anonymous bulk sourcing with European-origin quinoa in sustainability-focused ranges.
- Health Food Stores:Independent and chain specialists in Berlin, Paris, and London curate premium organic assortments with educated staff recommendations supporting higher price points.
- Online Retail:Direct-to-consumer and marketplace platforms enable niche brand discovery with subscription models capturing repeat purchase loyalty.
- Distributors:Foodservice and manufacturing intermediaries consolidate fragmented supply for institutional buyers with volume contracting and logistics integration.
Supermarkets dominate volume capture; Online Retail offers steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized agronomists and food scientists concentrate in Germany, France, and the United Kingdom, anchoring Europe's quinoa cultivation expertise and processing innovation. These talent clusters drive varietal adaptation and supply chain modernization across the continent.
Germany
Health-conscious consumers in Berlin and Hamburg pull organic quinoa into mainstream retail through discounter private label expansion. ECHA REACH compliance incentives favor domestic sourcing with shorter chemical traceability chains. The North Rhine-Westphalia corridor hosts contract processors deploying mechanical saponin removal systems for regional organic brands.
France
French bakery and ready-meal manufacturers reformulate wheat-dependent portfolios, absorbing quinoa protein for gluten-free binding functionality. The EU Green Deal's Farm to Fork ecological focus area subsidies accelerate quinoa inclusion in crop rotation schemes. Auvergne-Rhône-Alpes agricultural stations run varietal trials identifying locally adapted cultivars for commercial scale-up.
United Kingdom
Urban convenience demand in London displaces dry grain purchases with pre-cooked microwaveable formats. British agricultural policy post-Brexit redirects subsidies toward import substitution crops including domestic quinoa. The East Anglia cluster concentrates emerging cultivation operations serving traceability-focused supermarket buyers.
Spain
Drought tolerance requirements absorb marginal acreage in Castile-La Mancha and Andalusia where irrigation restrictions under EU water framework directives render traditional cereals unviable. Spanish organic certification growth aligns with retailer sustainability commitments. Valencia-based cooperatives aggregate smallholder production for export-oriented processing.
Italy
Red quinoa antioxidant properties attract nutraceutical formulators in Milan's pharmaceutical corridor. Italian agricultural ministries respond to EU organic farmland targets with quinoa rotation incentive programs. Emilia-Romagna food processors integrate quinoa protein into functional ingredient specifications for European manufacturers.
Europe Quinoa Seed Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across Europe's quinoa seed landscape. Vertically integrated cultivation-to-retail operators absorb fixed processing infrastructure costs that barrier smaller entrants. The competitive terrain splits between domestic sourcing specialists, Andean import distributors, and convenience-format innovators. Capacity expansion in mechanical saponin removal and strategic partnerships for organic certification harmonization represent dominant competitive vectors.
Among UK-based domestic sourcing specialists, The British Quinoa Company exemplifies the vertically integrated archetype controlling cultivation through retail placement. Quinola occupies a position within the convenience-format tier, anchoring pre-cooked product development. Ekibio represents organic certification specialists differentiating through French retail channel penetration.
| Leading Market Players |
|---|
| The British Quinoa Company |
| Agricolor Quinoa |
| Quinola |
| Ekibio |
| Quinoa Marchfeld |
| Dutch Quinoa Group |
| Nourish You |
| pureproducts |
| Andean Naturals |
| Others |
Supply & Pricing Matrix
Organic certification compliance costs flow from EU regulatory standards through to retail shelf price premiums, compressing margins for uncertified bulk imports while rewarding domestic European growers with shortened traceability chains. Saponin removal processing equipment represents a fixed capital burden that stratifies pricing tiers between commodity grain suppliers and value-added convenience format producers.
Pricing Analysis
Processed-versus-unprocessed quinoa splits pricing architectures across the value chain. Three-tier pricing structure across organic certified, conventional food-grade, and feed-grade levels separates premium transparency claims from commodity positioning. Price differentiation rests on certification tier and geographic origin proximity to end markets. Pricing pressure stems from Andean import competition in conventional segments. Food manufacturers exhibit highest price sensitivity; health-conscious retail consumers absorb organic premiums with lower elasticity.
Supply Chain Analysis
Andean germplasm dependency anchors European cultivation programs in Peruvian and Bolivian breeding stock. Quinoa draws from South American seed genetics, domestic European cultivation expansion, and mechanical saponin removal equipment as critical inputs. Single-source vulnerability concentrates in germplasm access and varietal adaptation knowledge. Distribution runs through Rotterdam and Hamburg port zones for bulk imports, with domestic aggregation cooperatives serving organic retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in mechanical processing automation and organic certification harmonization, compressing cost structures for domestic European supply against incumbent Andean imports.
For Market Incumbents: Cement market position through backward integration into saponin removal processing infrastructure and exclusive varietal breeding partnerships with agricultural research stations. Teff and amaranth substitution threats demand accelerated convenience format innovation. Channel control through supermarket private label exclusivity represents the critical defensive lever. For New Entrants and Emerging Players: Health food store independents offer partnership pathways for unproven European-origin brands seeking credibility transfer. Poland and Romania cultivation expansion presents the most penetrable white-space opportunity. Direct-to-consumer subscription models with single-origin transparency claims provide the strongest go-to-market angle. For Investors and Strategic Acquirers: Consolidation pressure builds where sub-scale domestic processors lack capital for mechanical saponin removal equipment. Long-term viability favors vertically integrated cultivation-to-retail operators with captive organic certification. Acquisition targets cluster around Eastern European aggregators with established grower networks. Watch EU organic farmland coverage targets as the primary inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Mechanical Saponin Removal Capacity Buildout | German equipment manufacturers deploy abrasion systems that absorb water cost premiums in drought-stressed southern European regions. |
| Organic Certification Harmonization | EU-wide standard alignment reduces cross-border friction for multi-country sourcing operations serving supermarket private labels. |
| Eastern European Cultivation Expansion | Polish and Romanian arable land with suitable altitude profiles currently lacks commercial seed distribution infrastructure. |
| Pre-cooked Convenience Format Development | Retort processing investment barriers smaller suppliers while capturing time-constrained urban consumers in London and Berlin. |
| Varietal Breeding Partnership | French and Italian agricultural stations identify locally adapted cultivars eligible for Farm to Fork ecological subsidies. |
Research Methodology
Coverage spans Germany, France, the United Kingdom, Spain, and Italy, with primary inputs from each national market. The research combines interviews with quinoa cultivation specialists, organic certification auditors, supermarket category buyers, food manufacturing procurement leads, and agricultural cooperative managers with secondary validation through EU Farm to Fork strategy documents, EFSA novel food assessments, REACH compliance databases, and national agricultural ministry varietal trial reports. Bottom-up acreage and yield estimates triangulate against top-down retail volume audits.
Rate-of-change decomposition separates volume growth from price trajectory shifts across the projection horizon. The analytical framework models segmentation dimensions including certification tier, packaging format, end-use application, and distribution channel complexity. CAGRs derive from compound growth mechanics applied to baseline market sizing. Industry-specific forecast inputs incorporate EU organic farmland coverage targets and mechanical processing capacity expansion timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to germplasm access restrictions, water framework directive enforcement intensity, and substitution dynamics from competing pseudocereals. Forecasts reflect documented assumptions around subsidy continuity and varietal adaptation success rates. Material deviation in EU Green Deal implementation pace or Andean supply disruption severity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
China Forage Seed Market
Seeds
Wax Gourd Seed Market
Seeds
Chia Seeds Market
Seeds
South America Seed Market
Seeds
Quinoa Seed Market
Seeds
Field Crop Seeds Market
Seeds
Glycine Soja (Soybean) Seed Extract Market
Seeds
Asia-Pacific Maize Seed Market
Seeds
Indonesia Seeds Market
Seeds
Asia-Pacific Quinoa Seeds Market
Seeds
Hemp Seeds Market
Seeds
Crambe Abyssinica Seed Oil Market
Seeds
Spain Forage Seed Market
Seeds
Global Onion Seed Market
Seeds
Psyllium Seed Market
Seeds
Morocco Seed Market