
 Global Sports Turf Seed Market | 2026-2036
Global Sports Turf Seed Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sports Turf Seed Market Foresight
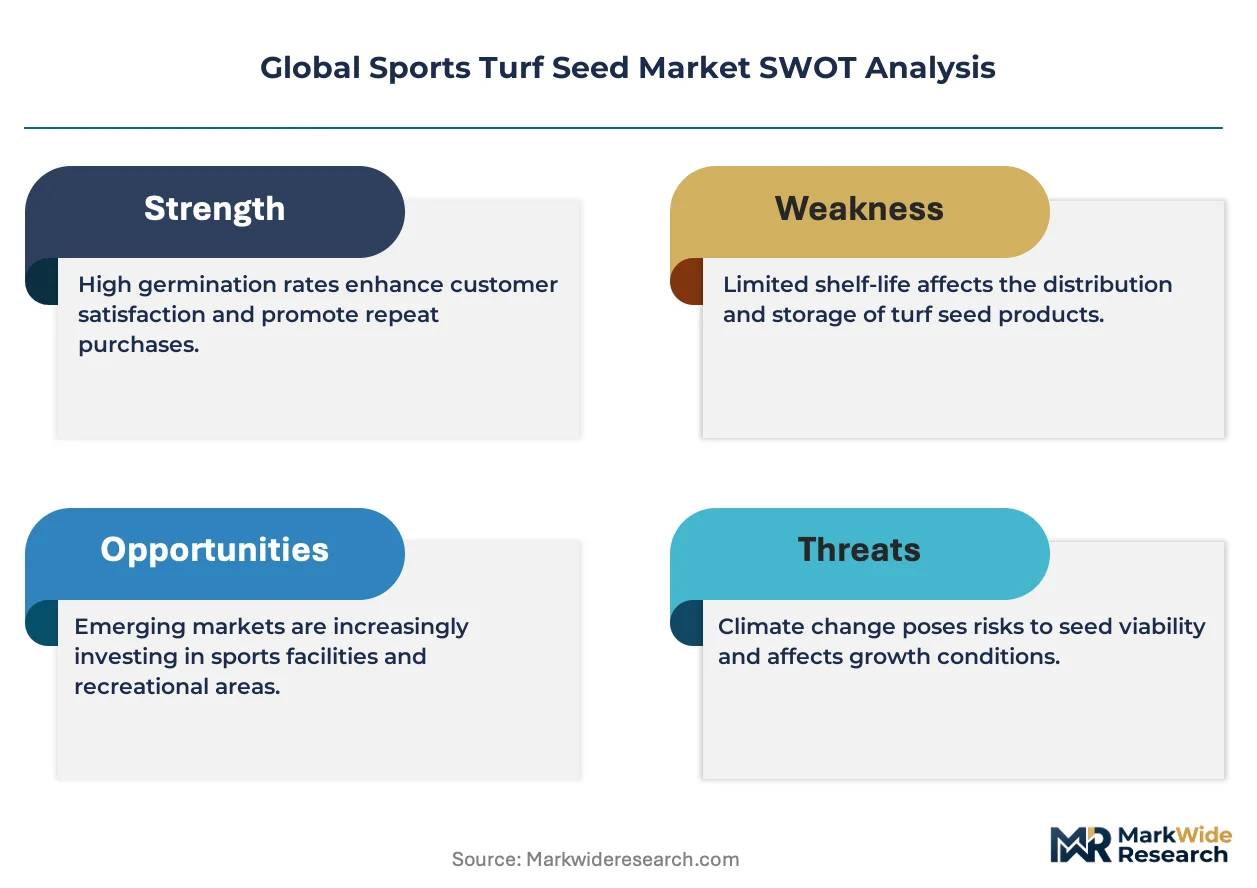
Professional stadium renovation schedules is hardening as broadcasters and leagues enforce stricter surface-quality metrics. Barenbrug Group leverages its European breeding stations to supply elite football pitches with cultivars selected for wear tolerance and recovery speed. The Scotts Miracle-Gro Company anchors North American distribution through retail and direct-to-groundskeeper channels. DLF-Pickseed USA dominates cool-season turf supply for municipal ballparks across the Upper Midwest and Northeast.
Sports turf seed comprises certified cultivars of perennial grasses bred for wear resistance, root density, and visual uniformity under mechanical stress and broadcast lighting. Seed lots undergo germination testing, purity analysis, and often coated treatment with fungicides or moisture-retention polymers to ensure establishment rates above 85 percent under field conditions. Kentucky bluegrass and perennial ryegrass blends command premium positioning in professional stadium contracts where FIFA Quality Pro standards apply. Bermuda grass and zoysia grass varieties compete aggressively in subtropical and transition-zone golf course markets where heat tolerance and drought recovery determine specification. Bulk bag packaging for landscape contractors and sports complex operators captures volume-driven margin pools, while smaller polywoven units serve municipal authorities with fragmented purchasing authority.
USDA germination standards and state-level seed certification programs administered by agencies in Oregon, Washington, and Idaho shape product legality and interstate commerce. REACH registration requirements in Europe constrain active ingredient availability for seed coating formulations, pushing breeders toward biological alternatives. EPA re-registration timelines for turfgrass protectants create supply uncertainty that groundskeepers must monitor when planning renovation cycles.
Market Dynamics
Broadcast-quality surface mandates from FIFA and UEFA are hardening renovation schedules across professional venues, compressing seed procurement cycles and elevating certified cultivar specifications above commodity grades.
Growth Catalysts
- FIFA Quality Pro certification:Stadium operators in Germany, England, and Spain now require certified seed blends meeting updated pitch protocols, eliminating uncertified suppliers from elite tender processes.
- Heat-tolerant Bermuda grass breeding:Transition-zone golf courses from North Carolina to Portugal are replanting with improved varieties that extend playable seasons by six to eight weeks annually.
- LED broadcast lighting proliferation:Stadium infrastructure upgrades in Japan and Australia demand turf cultivars selected specifically for spectral uniformity under artificial illumination.
Market Restraints
- Seed coating chemistry constraints:ECHA REACH re-registration timelines for fungicidal actives create formulation uncertainty, forcing breeders toward unproven biological alternatives.
- Elite germplasm concentration:Proprietary wear-tolerant cultivars remain captive to four major breeding stations in Oregon, Denmark, and the Netherlands, limiting second-source options.
- Irrigation water cost volatility:Municipal rate hikes across the US Southwest and Australian southeast are compressing operating budgets for Bermuda grass-dependent facilities.
Strategic Opportunities
- India cricket stadium modernization:Board of Control for Cricket in India infrastructure mandates are creating first-time demand for certified perennial ryegrass in Mumbai, Bangalore, and Chennai venues.
- Biostimulant-coated seed convergence:Mycorrhizal inoculants combined with moisture-retention polymers are opening premium positioning for establishment-guarantee contracts.
- Direct-to-groundskeeper digital channels:Mobile-enabled seed specification tools are disintermediating traditional distribution layers for municipal ballpark operators.
Industry Challenges
- Turfgrass pathology diagnostics shortage:Accredited disease identification laboratories are concentrated in three US land-grant universities, creating bottlenecks for rapid field diagnosis during renovation windows.
- Multi-site certification synchronization:Venue operators managing portfolios across state or national boundaries face misaligned germination testing protocols and conflicting purity standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sports Turf Seed Market |
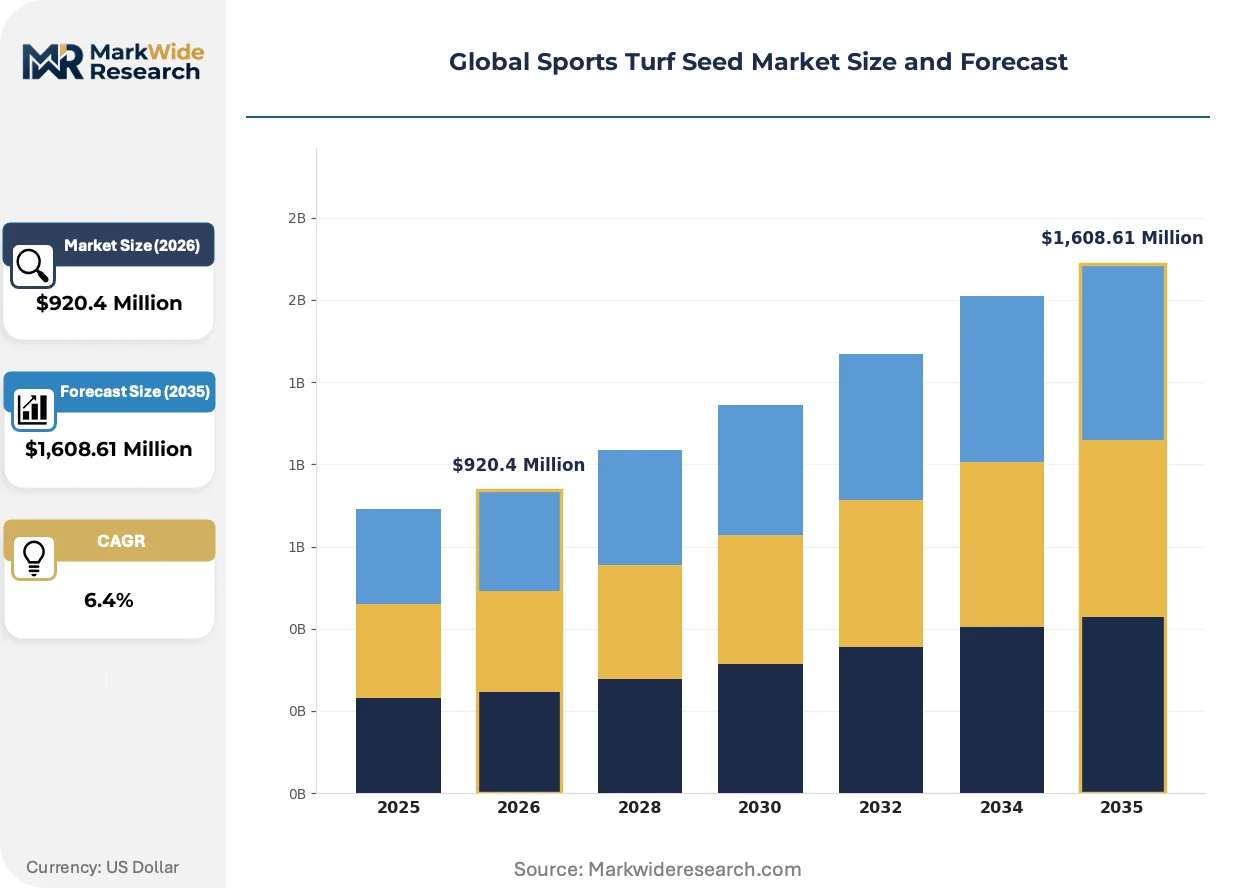
| Market Size in 2026 | $920.4 Million |
| Market Size in 2035 | $1,608.61 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Seed Type: Bermuda Grass, Kentucky Bluegrass, Fescue, Ryegrass, Zoysia Grass Application: Professional Stadiums, Recreational Fields, Golf Courses, Schools, Parks End User: Sports Complex Operators, Municipal Authorities, Landscape Contractors, Athletic Clubs Packaging Type: Bulk Bags, Plastic Sacks, Paper Bags, Polywoven Bags |
| Companies Covered | Ampac Seed Company, BrettYoung, The Scotts Miracle-Gro Company, Nufarm Limited, Columbia Seeds, Barenbrug Group, Pennington Seed, Central Garden & Pet Company, DLF-Pickseed USA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sports Turf Seed Market Shifts & Advancements
Genomic selection and accelerated breeding cycles are compressing cultivar development timelines while regulatory chemistry restrictions are redirecting formulation investments toward biological seed treatments.
Endophyte-enhanced perennial ryegrass is consolidating market positioning in professional football stadiums. These fungal symbionts improve insect resistance and drought recovery without chemical inputs. Groundskeepers at Premier League and Bundesliga venues are specifying endophyte-positive cultivars in 80 percent of new pitch installations. The technology is consolidating demand around breeders with captive endophyte strain libraries, marginalizing commodity seed suppliers lacking proprietary fungal partnerships.
EU F-Gas Regulation phase-down schedules are indirectly pressuring turf maintenance equipment fleets, altering renovation timing and seed establishment protocols. Stadium operators face compressed windows for gasoline-powered aeration and overseeding equipment before electric mandate deadlines take effect. Facilities in France, Italy, and the Netherlands are advancing renovation schedules by 12 to 18 months to utilize existing equipment, accelerating seed procurement cycles and favoring suppliers with inventory depth.
Specification authority is migrating from landscape contractors to in-house agronomists at elite venues. These technical buyers demand cultivar performance data from independent wear-testing protocols rather than supplier marketing materials. The shift is most visible in Saudi Arabia and Qatar, where sovereign wealth-funded stadium developments employ European-trained turf managers who bypass traditional distribution channels and negotiate directly with breeders for custom blend formulations.
Global Sports Turf Seed Market Segmentation
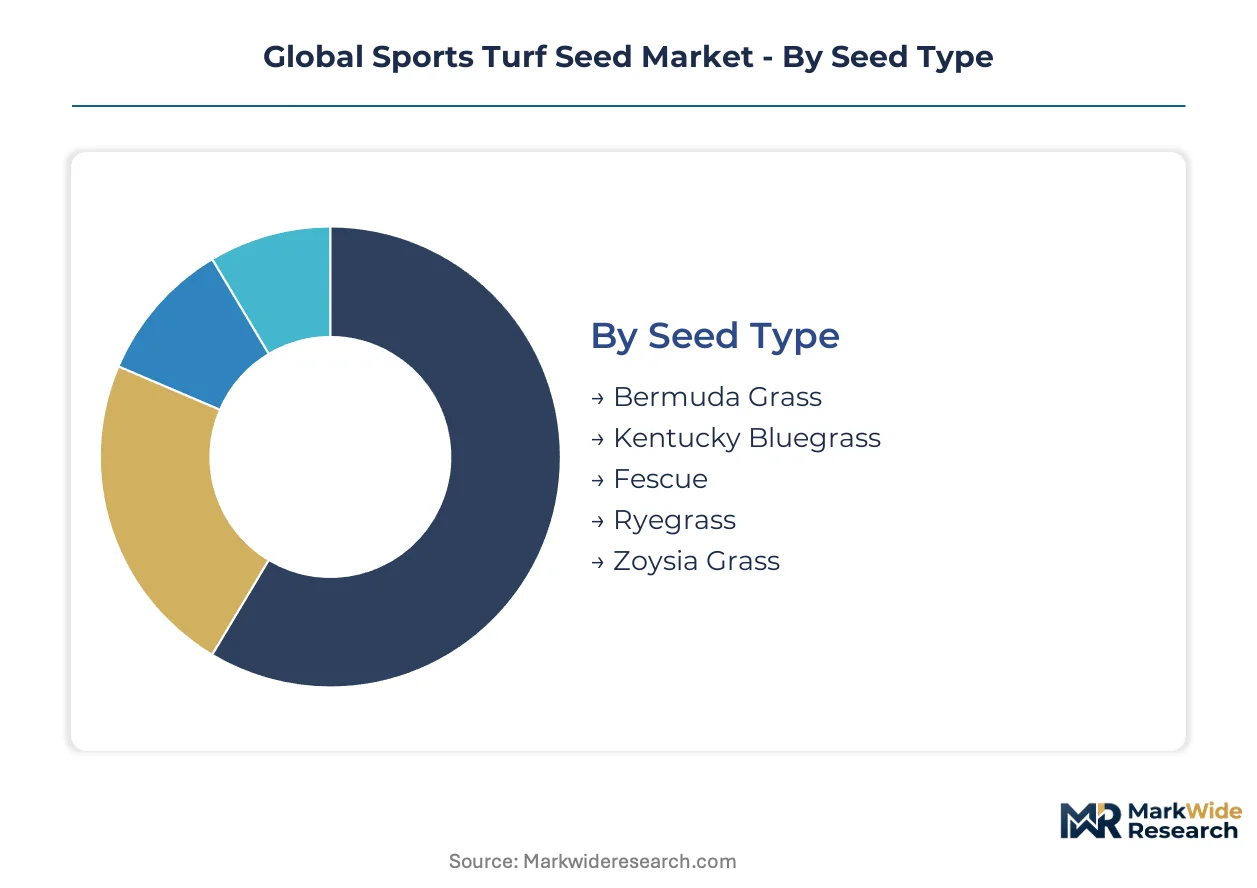
Sports turf seed segmentation reflects divergent performance specifications across playing surfaces and procurement authority structures. Breeders configure cultivar portfolios around wear tolerance, climatic adaptation, and establishment speed to match distinct end-use requirements.
Seed Type:
Genetic improvement trajectories and climate-zone specialization define competitive positioning within grass species portfolios.
- Kentucky Bluegrass:Dense sod-forming perennial with rhizomatous recovery mechanisms bred for visual uniformity under broadcast lighting. FIFA Quality Pro stadium specifications in Germany and England specify bluegrass-dominant blends for elite football pitches.
- Bermuda Grass:Warm-season C4 species with aggressive stoloniferous spread and heat tolerance extending playable seasons. Transition-zone golf courses from North Carolina to Portugal replant with improved varieties for six-to-eight-week season extensions.
- Ryegrass:Rapid-establishment cool-season option with endophyte-enhanced cultivars improving insect resistance.
- Fescue:Drought-tolerant bunchgrass for low-input municipal applications.
- Zoysia Grass:Slow-establishing warm-season species prized for shade tolerance and reduced nitrogen requirements.
Kentucky Bluegrass leads on scale through professional stadium certification mandates; Bermuda Grass leads on momentum via transition-zone golf course replanting cycles.
Application:
Surface-quality broadcasting standards and player-safety liability thresholds concentrate specification authority differently across venue tiers.
- Professional Stadiums:FIFA and UEFA certification protocols mandate certified seed lots with documented germination rates and purity analysis. Venue operators in Spain and Italy face compressed procurement cycles as infrastructure deadlines accelerate.
- Golf Courses:USGA green specifications and playability demands drive cultivar selection for ball roll consistency and divot recovery. Heat-tolerant Bermuda grass breeding programs target transition-zone facilities seeking extended revenue seasons.
- Recreational Fields:Municipal budget constraints favor lower-input fescue and ryegrass blends with reduced irrigation requirements.
- Schools:Liability-focused purchasing prioritizes wear-tolerant mixtures for multi-sport usage intensity.
- Parks:Aesthetic and passive recreation needs support commodity-grade seed specifications with minimal certification overhead.
Professional Stadiums concentrate premium pricing power; Golf Courses are expanding most quickly through climate-adaptation replanting investments.
End User:
Procurement sophistication and technical staffing levels fragment purchasing behavior across institutional categories.
- Sports Complex Operators:Portfolio managers overseeing multiple venues face certification synchronization challenges across state and national boundaries with misaligned germination testing protocols.
- Municipal Authorities:Fragmented purchasing authority across parks departments favors smaller polywoven packaging units over bulk procurement.
- Landscape Contractors:Volume-driven margin pools attract bulk bag configurations for installation-scale projects.
- Athletic Clubs:Member-funded renovation budgets support mid-tier certified blends without elite stadium certification requirements.
Sports Complex Operators command specification influence; Municipal Authorities represent the deepest volume pool.
Packaging Type:
Logistics configuration and inventory turnover economics shape format selection across distribution channels.
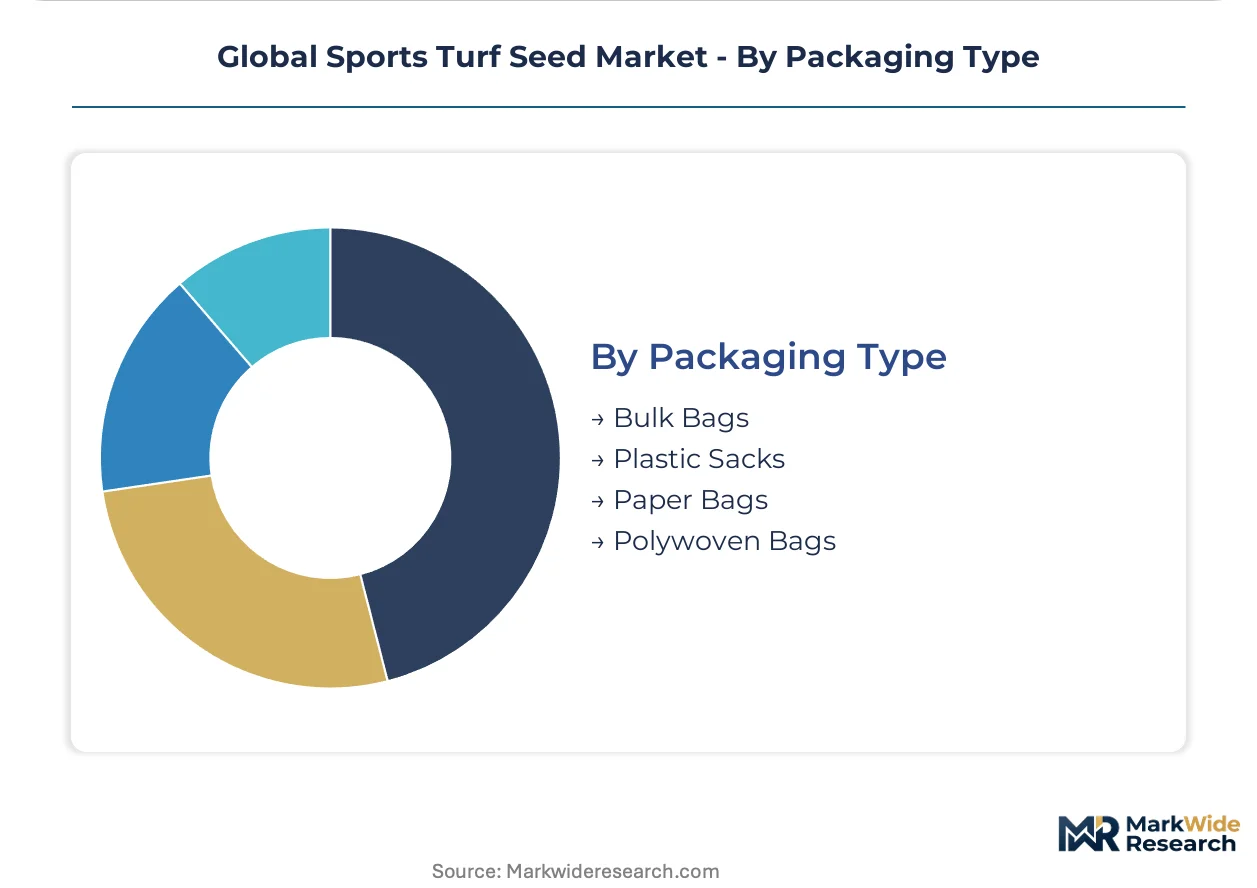
- Bulk Bags:One-ton flexible intermediate bulk containers capture contractor-scale volume with minimized handling costs for landscape installation fleets.
- Polywoven Bags:Laminated polypropylene units with moisture barriers protect coated seed treatments during extended storage for municipal procurement cycles.
- Plastic Sacks:Standard polyethylene packaging for commodity-grade blends with shorter inventory turns.
- Paper Bags:Biodegradable option for environmental procurement mandates with limited moisture protection.
Bulk Bags dominate contractor channel economics; Polywoven Bags are gaining share fastest through coated seed premiumization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Oregon's Willamette Valley anchors the global sports turf seed industry through concentrated breeding infrastructure and state-level certification programs administered by the Oregon State University Seed Laboratory.
United States
Major League Baseball and NFL franchise spending on playing surfaces continues climbing across the Sun Belt and Upper Midwest. EPA re-registration timelines for turfgrass protectants create supply uncertainty that groundskeepers monitor when planning renovation cycles. Municipal ballparks in the Upper Midwest and Northeast source certified cool-season blends through state procurement frameworks.
Germany
Bundesliga stadium operators now require certified seed blends meeting updated FIFA Quality Pro pitch protocols. ECHA REACH registration requirements constrain active ingredient availability for seed coating formulations, pushing breeders toward biological alternatives. Breeding stations in Bavaria and Lower Saxony supply elite football pitches with cultivars selected for wear tolerance.
Spain
La Liga venue operators face compressed procurement cycles as infrastructure deadlines accelerate under UEFA stadium infrastructure criteria. The country's national seed regulator enforces germination testing protocols that eliminate uncertified suppliers from elite tender processes. Madrid and Barcelona metropolitan facilities concentrate specification authority with in-house agronomists demanding independent wear-testing data.
Australia
Stadium infrastructure upgrades in Sydney and Melbourne demand turf cultivars selected for spectral uniformity under LED broadcast illumination. Municipal rate hikes across the southeast compress operating budgets for Bermuda grass-dependent facilities. The Australian Pesticides and Veterinary Medicines Authority regulates seed coating chemistry availability for professional venue applications.
India
Board of Control for Cricket in India infrastructure mandates create first-time demand for certified perennial ryegrass in Mumbai, Bangalore, and Chennai venues. BIS certification requirements for imported seed lots shape procurement legality for stadium modernization projects. Sovereign wealth-funded developments in Gujarat and Maharashtra employ European-trained turf managers who negotiate directly with breeders.
Global Sports Turf Seed Market Competitive Landscape
Portfolio diversification dominates the current landscape as breeders expand cultivar libraries beyond commodity grades toward certified elite germplasm. The vendor base concentrates around four major breeding stations with proprietary wear-tolerant cultivars, limiting second-source availability for venue operators. Three strategic archetypes prevail: integrated breeders with captive endophyte strain libraries, North American distributors anchoring retail and direct-to-groundskeeper channels, and regional specialists supplying municipal authorities with fragmented purchasing authority. M&A activity and geographic licensing agreements represent the dominant competitive vectors as players seek access to restricted germplasm pools.
Within the integrated breeder tier, Barenbrug Group and DLF-Pickseed USA exemplify archetypes built around breeding station control and certification infrastructure. The Scotts Miracle-Gro Company occupies a position representing North American distribution scale through retail and professional channels. These three entities anchor the competitive structure by controlling access to proprietary cultivars and coating formulation capabilities.
| Leading Market Players |
|---|
| Ampac Seed Company |
| BrettYoung |
| The Scotts Miracle-Gro Company |
| Nufarm Limited |
| Columbia Seeds |
| Barenbrug Group |
| Pennington Seed |
| Central Garden & Pet Company |
| DLF-Pickseed USA |
| Others |
Supply & Pricing Matrix
Family-owned breeding stations in Oregon, Denmark, and the Netherlands anchor supply discipline through multi-generational cultivar development programs that resist short-term pricing pressure. Their captive control over elite germplasm enables selective release strategies that sustain premium positioning for certified seed lots while constraining volume availability for commodity-grade competitors.
Pricing Analysis
Distributor margin capture runs through three distinct tiers: breeders command premium positioning for FIFA Quality Pro certified blends, regional distributors extract markup on mid-tier municipal specifications, and retail channels serve fragmented groundskeeper demand with polywoven packaging premiums. Price differentiation hinges on certification grade and volume scale, with elite stadium contracts tolerating substantial premiums for documented germination rates while municipal authorities negotiate aggressively on per-pound economics. Pricing pressure stems from ECHA REACH re-registration delays that force reformulation investments toward unproven biological coatings. Municipal authorities exhibit highest price sensitivity due to fragmented procurement authority, whereas sovereign wealth-funded stadium developments in Saudi Arabia and Qatar demonstrate minimal elasticity for custom blend formulations.
Supply Chain Analysis
Single-source vulnerability sits with Oregon's Willamette Valley, where concentrated breeding infrastructure and Oregon State University certification programs dominate global cool-season turf supply. Geographic supply concentration extends to Denmark and the Netherlands for elite football pitch cultivars, with secondary warm-season germplasm development anchored in Georgia and Texas for Bermuda grass varieties. Raw material dependencies include proprietary endophyte strain libraries, moisture-retention polymer coatings, and fungicidal actives subject to regulatory restriction. Supply chain risk centers on EPA re-registration timelines that create formulation uncertainty for seed coating chemistry. Distribution feeds from breeder-direct channels for elite venues, layered distribution for municipal authorities, and retail networks for groundskeeper procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily through irreversible infrastructure mandates from FIFA and UEFA that harden pitch certification standards across professional venues worldwide.
For Market Incumbents: Anticipate compressed procurement cycles as EU F-Gas Regulation deadlines accelerate renovation timing by twelve to eighteen months. Deepen backward integration into captive endophyte strain libraries to defend germplasm exclusivity against biological coating competitors. Expand inventory depth in transition-zone markets where heat-tolerant Bermuda grass breeding commands six-to-eight-week season extensions. For New Entrants and Emerging Players: Enter via India's cricket stadium modernization wave, where Board of Control for Cricket in India mandates create first-time certified perennial ryegrass demand without entrenched supplier relationships. Target municipal ballpark operators in the US Upper Midwest through direct-to-groundskeeper digital channels that disintermediate traditional distribution layers. Lead with biostimulant-coated seed offerings that open premium positioning for establishment-guarantee contracts. For Investors and Strategic Acquirers: Valuations sit cheapest among regional specialists supplying fragmented municipal authorities with commodity-grade fescue and ryegrass blends. Long-term viability rests on breeding station control and certification infrastructure rather than distribution scale alone. Watch for BIS certification enforcement in India as an inflection indicator that separates legitimate importers from gray-market suppliers in stadium modernization projects.| Strategic Initiative | Industry Significance |
|---|---|
| Endophyte Strain Library Acquisition | Captive fungal partnerships marginalize commodity suppliers lacking proprietary symbiont access. |
| Direct-to-Groundskeeper Digital Platform | Mobile specification tools disintermediate traditional distribution for municipal ballpark procurement. |
| Biostimulant Coating Formulation Investment | Mycorrhizal inoculants combined with polymers open premium establishment-guarantee positioning. |
| Transition-Zone Bermuda Grass Breeding Program | Heat-tolerant varieties extend playable seasons across North Carolina to Portugal golf facilities. |
| India Cricket Stadium Certification Partnership | BIS-compliant supply relationships secure first-mover positioning in Mumbai and Bangalore venues. |
Research Methodology
Coverage spans North America, Europe, Asia-Pacific, and Middle East, with primary inputs from each region combined with secondary validation. Interviews with breeding station agronomists, stadium groundskeepers, municipal procurement officers, and seed coating formulators informed cultivar development timelines and certification protocol evolution. Secondary sources included USDA germination standards documentation, ECHA REACH registration databases, FIFA Quality Pro pitch certification records, and state-level seed laboratory purity reports. Bottom-up demand modeling triangulated against top-down market sizing from breeder shipment disclosures and distribution channel volume estimates.
Granularity-level modeling operated at grass species, application tier, and end-user sophistication dimensions across the analysis window. Kentucky bluegrass, Bermuda grass, ryegrass, fescue, and zoysia grass trajectories were developed separately with distinct climate-zone penetration assumptions. Professional stadium, golf course, recreational field, school, and park applications each carried unique certification overhead and pricing elasticity parameters. CAGRs were derived from segmented growth rate reconciliation against aggregate market expansion. Forecast inputs incorporated LED broadcast lighting proliferation rates, EU F-Gas Regulation equipment replacement deadlines, and India cricket infrastructure investment schedules.
Inputs from breeder shipment disclosures and state certification programs were available through the study window; gaps in real-time municipal procurement transaction data introduce uncertainty bands around recreational field and school segment estimates. Forecasts reflect assumptions regarding regulatory enforcement continuity, climate adaptation breeding success rates, and sovereign wealth stadium development commitment levels. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Europe Quinoa Seed Market
Seeds
Global Sunflower Seed (Seed for Sowing) Market
Seeds
Russia Forage Seed Market
Seeds
Global Sunflower Market
Seeds
Pumpkin Seeds Market
Seeds
Helianthus Annuus (Sunflower) Market
Seeds
Asia-Pacific Vegetable Seed Market
Seeds
United States Garden Seeds Market
Seeds
Guar Market
Seeds
Global Oilseed Market
Seeds
Asia-Pacific Grain Seed Market
Seeds
Agricultural Seeder Market
Seeds
Watermelon Seeds Market
Seeds
Americas Seeds Market
Seeds
Genetically Modified Seeds Market
Seeds
Southeast Asia Seed Market