
 Genetically Modified Seeds Market | 2026-2036
Genetically Modified Seeds Market Size, Share, and Industry Trends Forecast 2026-2036
Genetically Modified Seeds Market Analysis
Trait licensing as a recurring service layer is decoupling germplasm ownership from farmer access, transforming how seed companies monetize their intellectual property. Bayer leverages its digital agriculture platform to bundle herbicide tolerance traits with variable-rate prescriptions. Corteva anchors its revenue through multi-year trait agreements with North American corn growers. Syngenta competes by extending insect resistance stacks into specialty vegetable segments.
Genetically modified seeds are crop propagules engineered through recombinant DNA technology to express targeted traits such as Bacillus thuringiensis Cry proteins or glyphosate-insensitive 5-enolpyruvylshikimate-3-phosphate synthase enzymes, enabling selective weed control and lepidopteran pest suppression in commercial agriculture. Corn dominates product type volumes due to its integration into both feed and ethanol value chains, while herbicide tolerance traits command the widest planted footprint across soybean and canola geographies. Insect resistance stacks in cotton retain premium pricing in geographies where bollworm pressure drives replanting economics, and drought tolerance represents the fastest-expanding trait category as water-stressed regions adopt dryland production protocols.
The EPA regulates plant-incorporated protectants under FIFRA, requiring extensive non-target organism studies that extend registration timelines and elevate development costs for novel trait stacks. The USDA's APHIS oversees interstate movement and environmental release of bioengineered organisms, with state-level seed certification laws in Iowa and Illinois adding compliance complexity for multichannel distribution. Stakeholders must monitor pending revisions to EPA endangered species assessments, as these rulings could restrict trait approvals in ecologically sensitive watersheds and reshape breeding program priorities.
Market Dynamics
Trait licensing as a recurring service layer is decoupling germplasm ownership from farmer access, transforming how seed companies monetize intellectual property and compressing breeding program timelines across major agricultural economies.
Growth Catalysts
- Biofuel Feedstock Demand:EPA's evolving framework for renewable fuel volumes is accelerating offtake of high-yield corn and soybean varieties by ethanol refiners in the US Midwest.
- Water-Stressed Region Expansion:Drought tolerance trait stacks are gaining traction in Australia's wheat belt and India's Maharashtra state as irrigation constraints intensify.
- CRISPR-Cas9 Editing:Precision breeding platforms are shortening trait development cycles from eight years to four, enabling faster regulatory submission packages.
Market Restraints
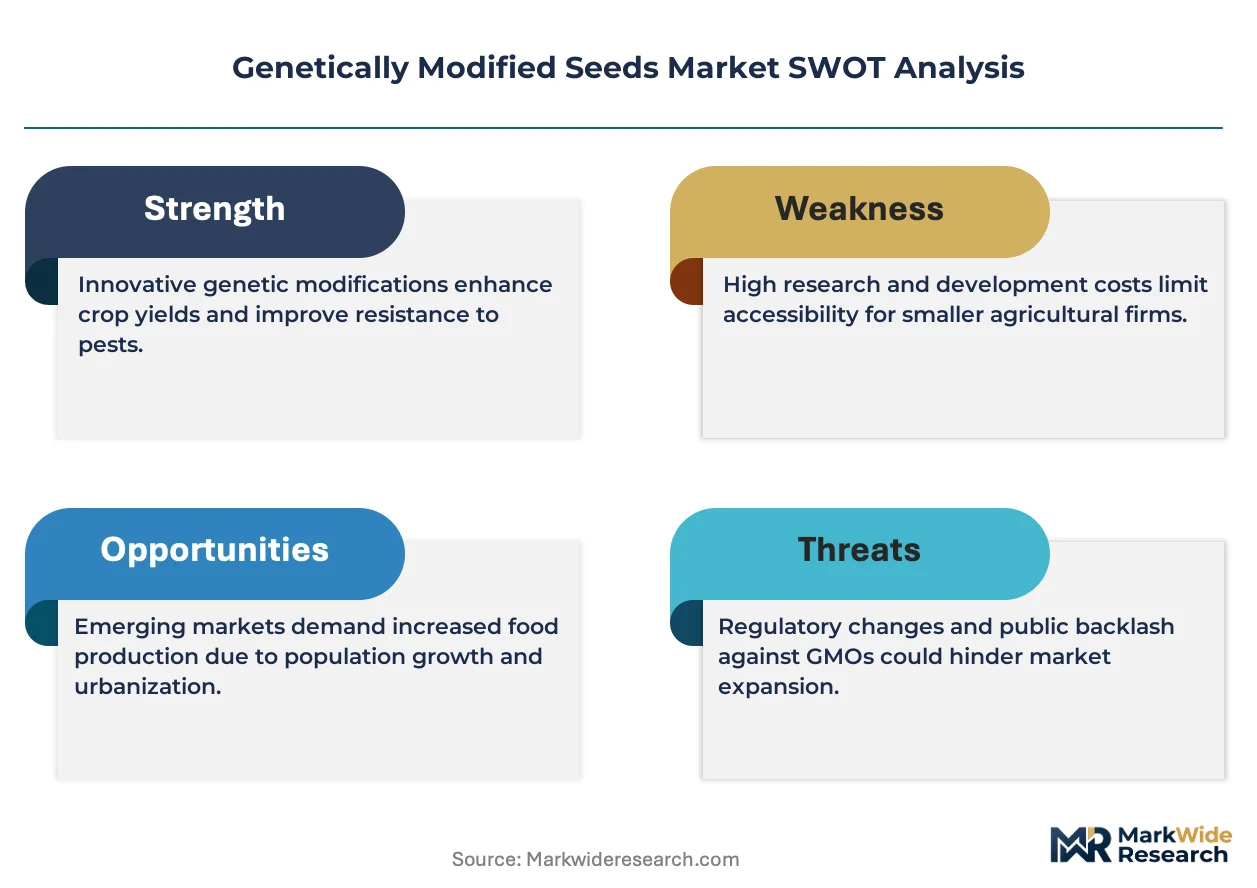
- EPA Registration Timelines:FIFRA-mandated non-target organism studies extend novel trait stack approvals to seven-plus years, elevating development costs beyond $150 million per major release.
- Seed Sector Concentration:Four firms control 60% of proprietary germplasm, creating dependency risk for farmers in Brazil's Cerrado and Argentina's Pampas.
- Gene Flow Containment:Pollen-mediated trait transfer to organic acreage triggers liability exposure and buffer zone mandates in Iowa and Illinois.
Strategic Opportunities
- Sub-Saharan Africa Penetration:Water-efficient maize varieties for smallholders in Kenya and Nigeria remain undersupplied by current licensing structures.
- Carbon Credit Stacking:Nitrogen-use-efficient traits qualify for compliance offsets under emerging soil carbon protocols in the EU and California.
- Direct-to-Farmer Platforms:Digital agriculture channels are bypassing traditional distributor networks in India's Punjab and Haryana states.
Industry Challenges
- Gene Editing Regulatory Divergence:The EU's Court of Justice ruling classifying CRISPR as GMO creates misalignment with USDA's product-based oversight, fragmenting export compliance.
- Trait Stacking Complexity:Pyramiding eight-plus insect resistance genes introduces expression instability and regulatory data package expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Genetically Modified Seeds Market |
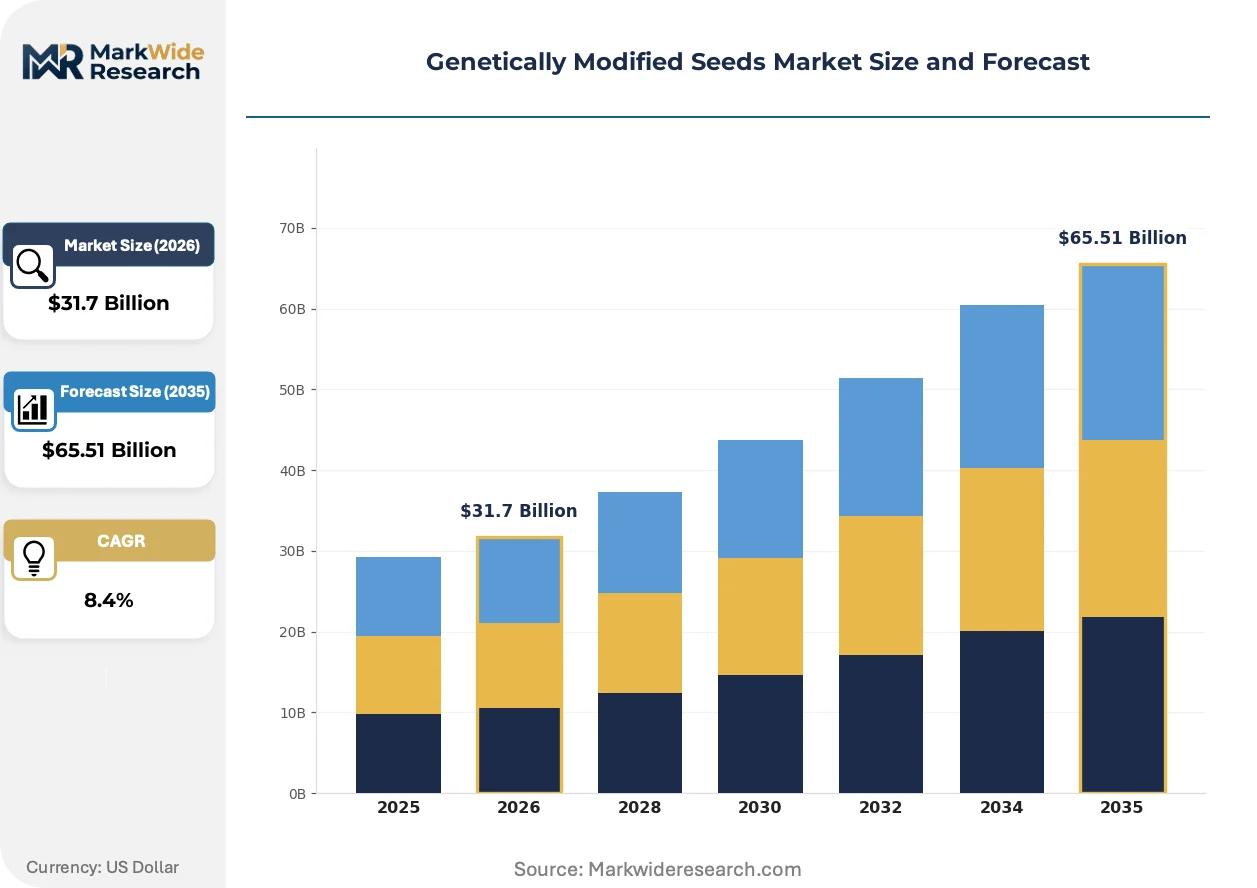
| Market Size in 2026 | $31.7 Billion |
| Market Size in 2035 | $65.51 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corn, Soybean, Cotton, Canola End Use Industry: Agriculture, Horticulture, Forestry, Biofuel Trait: Herbicide Tolerance, Insect Resistance, Drought Tolerance, Nutritional Enhancement Distribution Channel: Direct Sales, Retail, Online, Wholesalers |
| Companies Covered | Bayer, Corteva, Syngenta, BASF, Monsanto, DuPont, Groupe Limagrain, KWS, Land O'Lakes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Genetically Modified Seeds Market Emerging Trajectories
Gene editing platforms and digital trait deployment systems are compressing development timelines while regulatory fragmentation across major jurisdictions forces parallel compliance strategies.
CRISPR-Cas12a multiplex editing is rewriting the economics of complex trait stacking by enabling simultaneous modification of four yield-related loci. Large-scale corn growers in Iowa and Illinois are piloting these varieties under limited release permits. The technology is rewriting how seed firms allocate R&D budgets away from transgenic pipelines toward native gene optimization.
REACH's extension to novel genomic techniques is creating registration uncertainty for EU-bound soybean exports from South America. The European Commission's 2023 policy consultation has stalled trait approval pipelines. Specialty oilseed crushers in the Netherlands and Germany are diversifying sourcing toward non-edited canola to preempt supply disruption.
Farmer purchasing committees are consolidating input procurement across 5,000-plus acre operations in the US Corn Belt, displacing individual farm-level seed decisions. These aggregators negotiate multi-year trait licensing directly with breeders, compressing distributor margins. The pattern is most visible in Nebraska and Kansas where cooperative buying groups now command 30% of certified seed volume.
Genetically Modified Seeds Market Segmentation
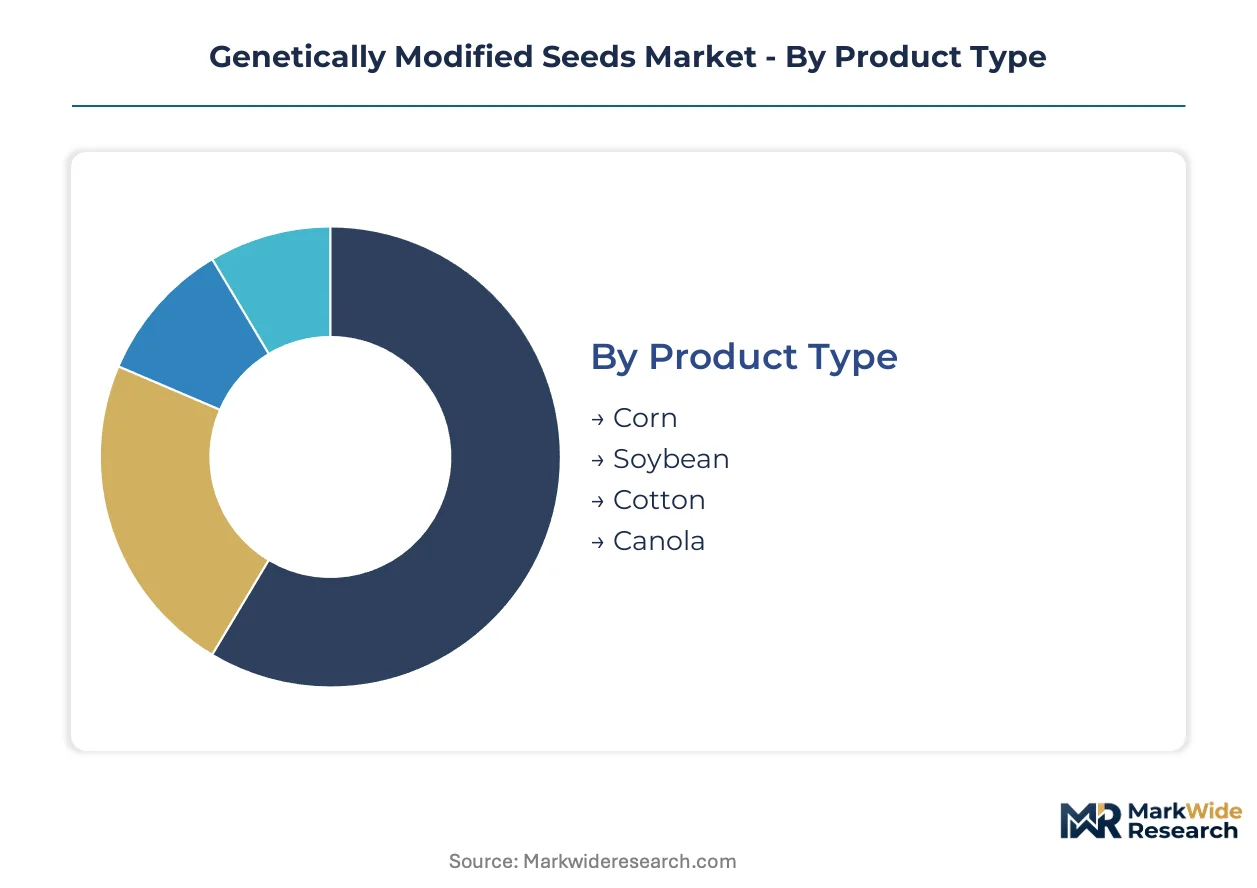
Segmentation in genetically modified seeds reveals how trait economics, channel control, and crop-specific value chains determine purchasing patterns. Farmers select varieties based on stacked trait premiums, ethanol contract terms, and distributor financing arrangements rather than germplasm alone.
Product Type:
Crop selection hinges on downstream commodity pricing and biofuel offtake contracts rather than agronomic fit alone.
- Corn:Engineered with Cry1Ab endotoxins and glyphosate-insensitive EPSPS enzymes, corn dominates feed and ethanol value chains. Demand concentrates in Iowa and Illinois where ethanol refiners contract high-yield varieties under volume-based pricing structures.
- Soybean:Herbicide-tolerant Roundup Ready and XtendFlex varieties enable dicamba-based weed management in no-till systems. Planting concentrates in Brazil's Mato Grosso state where port logistics and crush capacity determine seed selection timing.
- Cotton:Bollgard III stacks with Cry1Ac, Cry2Ab, and Vip3A proteins target lepidopteran pressure in water-stressed regions.
- Canola:High-oleic acid variants serve specialty oil processors in the EU and Canada with identity-preserved contracting.
Volume sits with corn; growth tilts toward canola as crush margins for high-oleic oils expand.
End Use Industry:
Downstream processor requirements dictate trait stacking depth and certification standards across seed procurement decisions.
- Agriculture:Row-crop producers prioritize yield stability and herbicide rotation flexibility in corn-soybean systems. Procurement clusters around cooperative buying groups in Nebraska and Kansas negotiating multi-year trait licenses.
- Horticulture:Specialty vegetable growers adopt insect-resistant stacks for protected cultivation in Spain's Almería and Mexico's Sinaloa valleys.
- Forestry:Engineered eucalyptus and poplar varieties accelerate pulp yield cycles in Brazil's planted forests.
- Biofuel:EPA renewable volume obligations drive ethanol refiner demand for high-starch corn hybrids with accelerated dry-down traits.
Procurement scale concentrates in agriculture; margin expansion favors biofuel with RIN value stacking.
Trait:
Trait selection reflects pest pressure cycles, chemistries losing efficacy, and irrigation access constraints.
- Herbicide Tolerance:Glyphosate, glufosinate, and 2,4-D tolerance genes enable post-emergent weed control in reduced-tillage systems. Adoption spreads across Argentina's Pampas as glyphosate-resistant Palmer amaranth intensifies.
- Insect Resistance:Pyramided Bt Cry and Vip proteins target rootworm and lepidopteran complexes. Refuge requirements complicate planting decisions in cotton belts from Texas to Maharashtra.
- Drought Tolerance:CspB and other stress-response genes stabilize yields in rain-fed production. Australia's wheat belt and India's Karnataka state show accelerating uptake as groundwater access contracts.
- Nutritional Enhancement:Lysine-enhanced corn and high-oleic soybeans command identity-preserved premiums from poultry integrators and food oil processors.
Planted footprint favors herbicide tolerance; development pipelines prioritize drought tolerance as water stress intensifies.
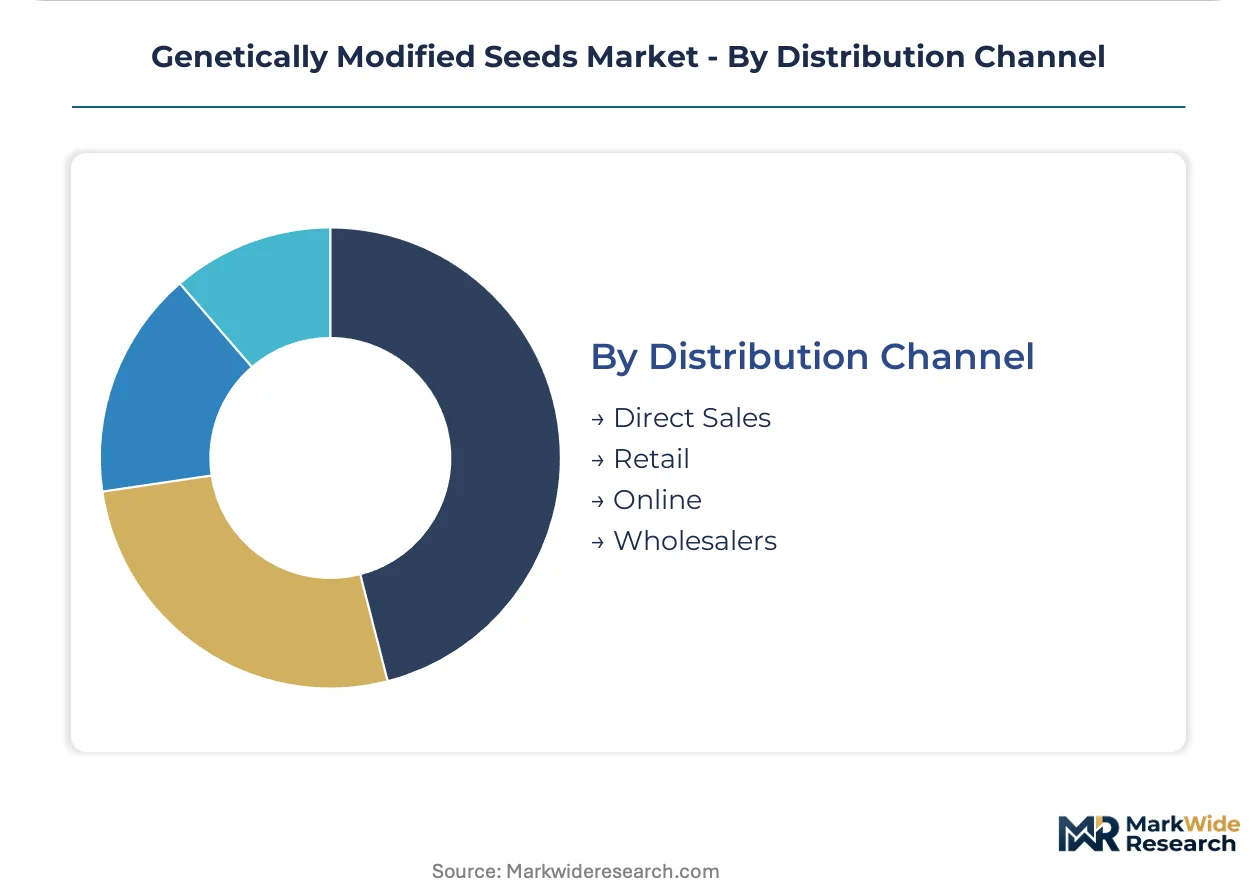
Distribution Channel:
Channel selection determines financing terms, agronomic support intensity, and trait licensing flexibility.
- Direct Sales:Seed companies bypass distributors to capture margin and deploy digital agriculture bundling. Bayer's Climate FieldView integrates variable-rate prescriptions with trait licenses in the US Corn Belt.
- Retail:Independent dealers provide credit access and localized agronomic advice in fragmented farming regions.
- Online:E-commerce platforms penetrate India's Punjab and Haryana with price-transparent trait comparisons and direct-to-farmer delivery.
- Wholesalers:Volume aggregators serve cooperative buying groups and input retailers across Eastern Europe and the Black Sea region.
Transaction volume flows through retail; channel share shifts fastest toward online as digital penetration deepens in Asia.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in the United States and Brazil, where corn and soybean seed multiplication fields supply domestic farmers and export markets. Consumption patterns diverge between biofuel-driven demand in North America and livestock feed requirements in Asia.
United States
Iowa and Illinois ethanol refiners contract high-starch corn hybrids under volume-based pricing structures. The EPA regulates plant-incorporated protectants under FIFRA, requiring extensive non-target organism studies. Nebraska cooperative buying groups now command 30% of certified seed volume through multi-year trait licenses.
Brazil
Mato Grosso farmers convert Cerrado pasture to intensive row-crop production for soybean export to China crush facilities. ANVISA oversees biosafety approvals for commercial release of genetically modified organisms. Port logistics in Santos and Paranaguá determine seed selection timing for second-crop corn planting windows.
Argentina
Pampas growers adopt glyphosate-tolerant soybeans as resistant Palmer amaranth intensifies across no-till systems. The country's national agricultural biotechnology regulator coordinates with seed certification bodies for variety release. Rosario crushing clusters anchor procurement decisions for high-protein meal export to Southeast Asia.
India
Maharashtra and Karnataka smallholders accelerate uptake of drought-tolerant cotton as groundwater access contracts in the Deccan Plateau. The Genetic Engineering Appraisal Committee under the Ministry of Environment clears environmental release of biotech crops. Punjab and Haryana digital agriculture platforms bypass traditional distributor networks with direct-to-farmer trait licensing.
Australia
Wheat belt growers trial water-efficient canola varieties under dryland production protocols as irrigation allocations tighten. The Office of the Gene Technology Regulator administers licensing for intentional release of genetically modified organisms. Western Australia grain handlers coordinate identity-preserved contracting for high-oleic oilseed exports to EU specialty processors.
Genetically Modified Seeds Market Vendor Landscape
Top-tier vendors anchor germplasm ownership and trait licensing revenue, while mid-scale regional breeders compete on localized adaptation and price-accessible varieties. Four firms control 60% of proprietary germplasm, creating dependency risk for farmers in concentrated production zones. Strategic archetypes include integrated life-science conglomerates with digital agriculture bundling, specialized row-crop genetics houses with multi-year grower agreements, and regional seed cooperatives with distribution density in fragmented farming areas. Dominant competitive moves include backward integration into gene editing platforms and geographic expansion through trait licensing partnerships in underserved markets.
Among integrated life-science conglomerates, Bayer and Corteva exemplify the platform-bundling archetype, combining herbicide tolerance traits with variable-rate prescription services. Syngenta occupies a position bridging commodity row crops and specialty vegetable segments with extended insect resistance stacks. These three anchors represent divergent approaches to decoupling germplasm ownership from farmer access through recurring service-layer monetization.
| Leading Market Players |
|---|
| Bayer |
| Corteva |
| Syngenta |
| BASF |
| Monsanto |
| DuPont |
| Groupe Limagrain |
| KWS |
| Land O'Lakes |
| Others |
Supply Flow & Price Mechanics
EPA endangered species assessment revisions gate qualified supply for trait stacks and premium-tier pricing access, compressing margins for non-compliant breeders while concentrating pricing power among registrants with completed non-target organism data packages.
Pricing Analysis
Margin tightening in standard-tier germplasm reflects gene editing platform commoditization as CRISPR-Cas9 licensing fees drop. Three-tier pricing structure across premium, standard, and economy levels separates multi-stack insect resistance varieties from single-trait herbicide tolerance from saved-seed brown-bag channels. Cost-down pressure on economy tiers accelerates because cooperative buying groups in Nebraska and Kansas consolidate procurement across 5,000-plus acre operations. Price differentiation hinges on trait stacking depth and refuge compliance support, with smallholder segments in India's Maharashtra state exhibiting highest sensitivity versus ethanol refiner contract growers showing lowest.
Supply Chain Analysis
Regional distribution centers in Des Moines and São Paulo anchor hub-and-spoke patterns for certified seed movement. Supply concentrates in the United States, Brazil, and Argentina, where corn and soybean multiplication fields feed domestic farmers and export markets. Raw material dependencies include proprietary inbred lines, CRISPR guide RNA synthesis, and glyphosate-tolerance gene constructs. Single-source vulnerability around Bayer's LibertyLink trait portfolio creates concentration risk. Distribution runs through cooperative buying groups displacing independent retail dealers across the US Corn Belt.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FIFRA-mandated non-target organism studies erect a cost-of-compliance barrier exceeding $150 million per major trait stack, moating registrants with EPA plant-incorporated protectant approvals against undercapitalized challengers.
For Market Incumbents: Extend digital agriculture bundling to capture recurring service revenue beyond germplasm sales, integrating Bayer-style Climate FieldView variable-rate prescriptions with multi-year trait licenses. Deepen backward integration into CRISPR-Cas12a multiplex editing platforms to compress development cycles and outpace regulatory submission timelines. Defend against gene editing regulatory divergence by maintaining parallel transgenic and native gene optimization pipelines.
For New Entrants and Emerging Players: Launch via direct-to-farmer digital platforms in India's Punjab and Haryana, bypassing distributor networks that incumbent conglomerates control. Target drought-tolerance trait licensing for smallholders in Kenya and Nigeria, where current supply structures underserve water-stressed regions. Pursue carbon credit stacking partnerships under emerging EU and California soil carbon protocols to differentiate nitrogen-use-efficient varieties.
For Investors and Strategic Acquirers: EPA registration timeline compression for novel trait stacks is the leading indicator that gene editing platform acquisitions will outperform transgenic pipeline buys. Long-term viability favors breeders with stacked regulatory expertise across FIFRA, USDA-APHIS, and divergent EU frameworks. Watch for ANVISA approval acceleration in Brazil's Cerrado conversion zones as the signal for South American licensing value inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Trait Licensing Platform Expansion | Decouples germplasm ownership from farmer access via recurring service-layer monetization. |
| CRISPR-Cas12a Multiplex Editing Adoption | Compresses trait development cycles from eight years to four for faster regulatory submissions. |
| Direct-to-Farmer Digital Channel Buildout | Bypasses traditional distributor networks in India's Punjab and Haryana with price-transparent delivery. |
| Carbon Credit Stacking Partnership | Qualifies nitrogen-use-efficient traits for compliance offsets under EU and California protocols. |
| Sub-Saharan Africa Trait Licensing | Penetrates underserved smallholder markets in Kenya and Nigeria with water-efficient maize varieties. |
Methodological Framework
Independent corroboration across seed company R&D executives, EPA regulatory affairs leads, cooperative buying group procurement managers, and ethanol refiner agronomists underwrites the qualitative findings. Secondary validation draws from USDA-APHIS interstate movement records, EPA FIFRA registration databases, ANVISA biosafety approval filings, and customs data on certified seed trade flows. Bottom-up acreage adoption modeling and top-down trait licensing revenue triangulation anchor market sizing.
Rate-of-change decomposition across the analysis window segments volume and value by crop type, trait category, distribution channel, and regional regulatory cluster. CAGRs derive from acreage penetration curves, trait royalty rate trajectories, and ethanol offtake contract volumes. Industry-specific forecast inputs include EPA renewable volume obligation trajectories and groundwater depletion indices for drought-tolerance adoption modeling.
Regulatory approval delays, gene editing policy reversals, and pollen-mediated gene flow liability rulings are the dominant revision risks. Forecasts reflect documented assumptions on trait stacking depth, licensing fee structures, and channel migration rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Africa Vegetable Seed Market
Seeds
Europe Grain Seed Market
Seeds
Middle East and Africa Cannabis Seeds Market
Seeds
India Seed Market
Seeds
Asia-Pacific Chia Seed Market
Seeds
Canary Seeds Market
Seeds
Vietnam Seed Market
Seeds
North America Grain Seed Market
Seeds
Uganda Seeds Market
Seeds
Philippines Seed Market
Seeds
Mexico Vegetable Seed Market
Seeds
South Africa Seed Market
Seeds
Asia-Pacific Rice Seed Market
Seeds
United States Vegetable Seed Market
Seeds
Asia-Pacific Forage Seed Market
Seeds
Vietnam Vegetable Seed Market