
 Pigeon Pea Market | 2026-2036
Pigeon Pea Market Size, Share, and Industry Trends Forecast 2026-2036
Pigeon Pea Market Intelligence
Yellow split peas is decoupling from traditional whole-bean pricing in commodity pulse markets, creating margin arbitrage for processors who fractionate into higher-value ingredients. Archer Daniels Midland Company leverages its North American protein extraction infrastructure to supply fractionated pulse isolates to alternative meat formulators. Olam International Limited anchors African origination networks, sustaining farmer procurement relationships across Tanzania and Mozambique that secure volume for export milling.
Pigeon pea (Cajanus cajan) is a diploid legume containing approximately 21-25% protein by dry weight, with a carbohydrate fraction rich in amylose and resistant starch; the crop fixes atmospheric nitrogen through rhizobial symbiosis, reducing synthetic fertilizer requirements in intercropping systems. Its primary commercial purpose spans human food consumption, particularly in South Asian and East African cuisines where dal preparations dominate, plus emerging use in gluten-free flour blends and extruded snack matrices. Split pigeon peas command the dominant volume position within product type categories due to processing efficiency and shorter cooking times, while powdered forms represent the fastest-expanding margin pool as beverage and bakery manufacturers seek clean-label protein fortification. The food industry end-use segment absorbs the majority of processed volume, though animal feed applications for detoxified seed cake are gaining traction as soybean meal price volatility persists.
India's FSSAI mandates pesticide residue limits and mycotoxin thresholds for packaged pulse products, directly influencing processing investments in optical sorting and dehulling technology. The EU's REACH framework and EFSA novel food guidelines shape market access for pigeon pea protein isolates entering European ingredient supply chains. USDA grading standards for whole and split peas establish quality benchmarks that govern import acceptance at U.S. ports. Stakeholders must monitor evolving carbon accounting methodologies for nitrogen-fixing crops, as differentiated sustainability credentials increasingly influence procurement contracts from major food manufacturers.
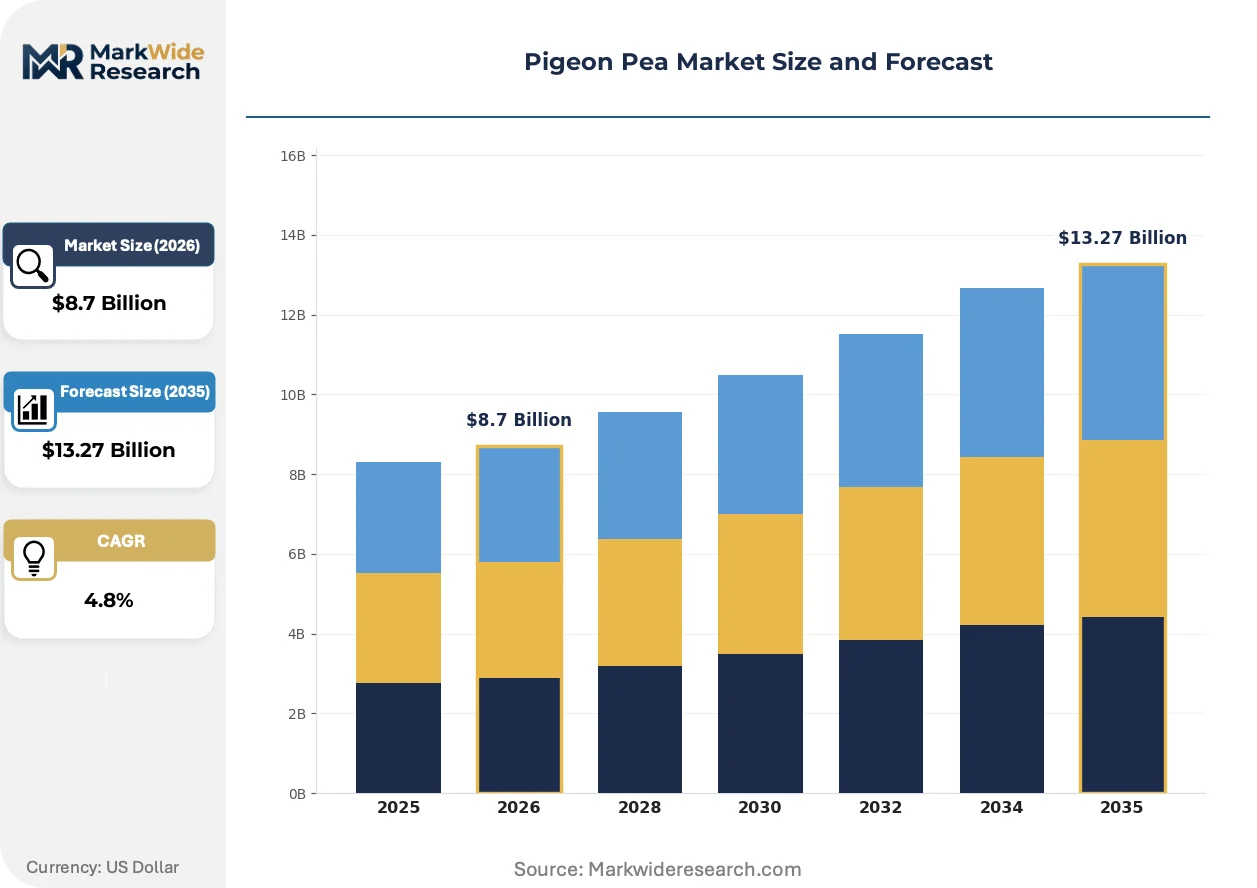
Market Dynamics
Fractionation technology is splitting the commodity pigeon pea trade into parallel value chains, with protein isolates commanding ingredient premiums while whole beans face margin compression in bulk export markets.
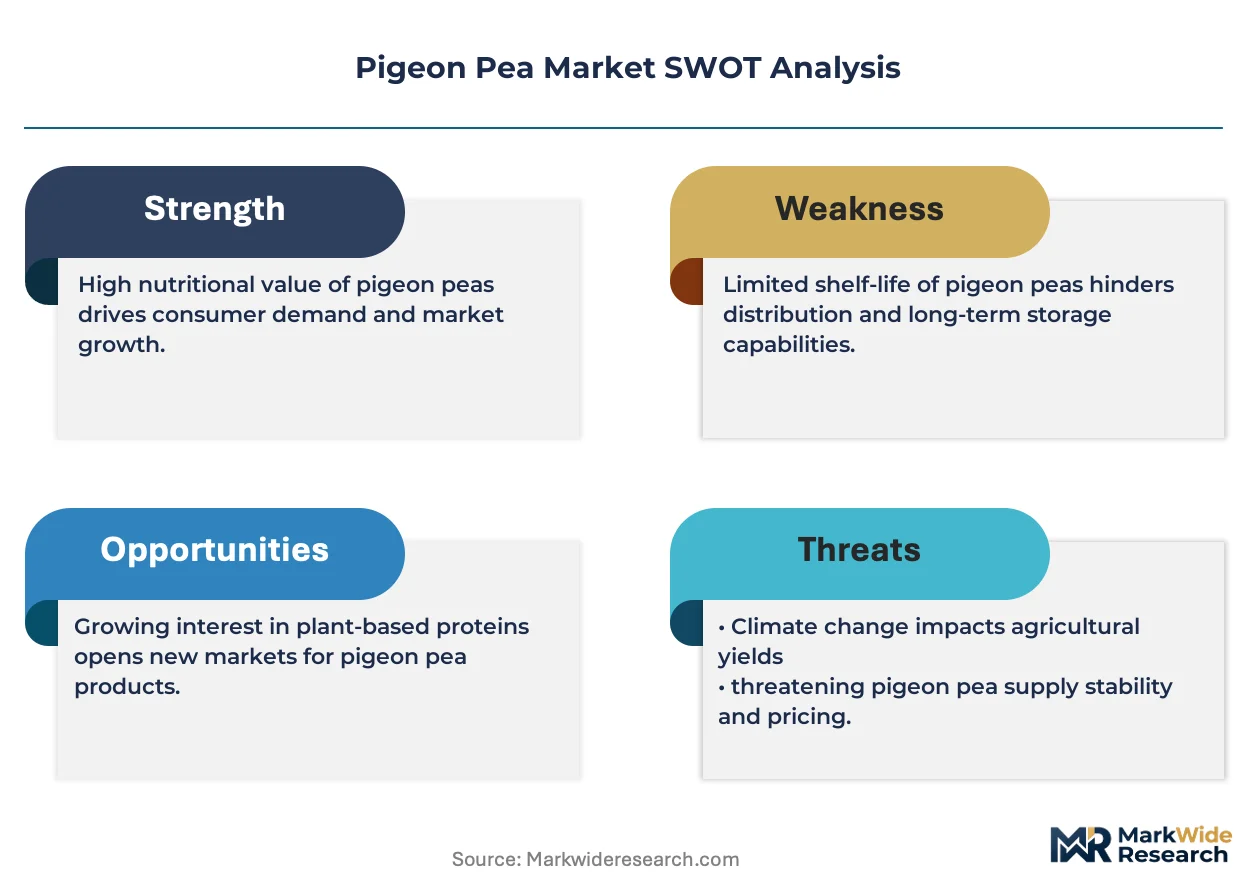
Growth Catalysts
- India's PLI scheme for food processing:The production-linked incentive program subsidizes capital investment in dehulling and powdering lines, accelerating domestic value-addition capacity.
- Pulse protein demand from plant-based meat formulators:Clean-label protein fortification requirements in extruded snacks and beverage matrices are pulling split and powdered pigeon pea volumes into premium ingredient channels.
- Rhizobial nitrogen fixation:Intercropping systems reduce synthetic fertilizer dependency, lowering input costs for smallholder farmers in Tanzania and Mozambique while generating carbon credit eligibility.
Market Restraints
- Input cost volatility in synthetic fertilizer markets:Phosphate and potash price swings disrupt intercropping economics for farmers who supplement biological nitrogen fixation with chemical inputs.
- Supply concentration in Indian subcontinent origination:Maharashtra and Karnataka states control dominant exportable surplus volumes, creating weather-dependent volume risk for importers.
- Technical limitation in protein extraction yields:Current aqueous fractionation processes recover only 60-70% of available protein, constraining isolate economics against established soy and pea protein benchmarks.
Strategic Opportunities
- Underpenetrated East African import markets:Kenya and Tanzania are concentrating demand for canned and dried varieties as urbanization accelerates convenience food consumption.
- Regulatory tailwind from EU Green Deal carbon accounting:Nitrogen-fixing crop credentials are entering procurement specifications for European ingredient buyers seeking scope 3 emissions reductions.
- Technology convergence between optical sorting and AI-driven defect detection:Real-time mycotoxin screening integrated with color sorters is reducing rejection rates at EU and US ports.
Industry Challenges
- Skill gap in protein isolate process engineering:Qualified technicians for membrane filtration and spray-drying operations are scarce in African and South Asian processing hubs.
- Capex intensity for optical sorting and dehulling infrastructure:FSSAI-mandated pesticide residue compliance requires capital deployment that small and mid-scale millers cannot self-finance.
- Certification timeline for EFSA novel food approval:Pigeon pea protein isolate dossiers face extended safety evaluation periods before European market authorization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pigeon Pea Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.27 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Green Pigeon Peas, Yellow Pigeon Peas, Split Pigeon Peas, Whole Pigeon Peas End Use: Food Industry, Animal Feed, Fertilizers, Snack Products Form: Dried, Canned, Frozen, Powdered Distribution Channel: Online Retail, Supermarkets, Wholesale, Direct Sales |
| Companies Covered | Archer Daniels Midland Company, Bunge Limited, Olam International Limited, Sun Impex, Wilmar International Limited, Export Trading Group, Louis Dreyfus Company, Interamsa Agroindustrial SAC, Cargill, Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pigeon Pea Market Strategic Shifts & Innovations
Processing technology and procurement specifications are diverging the pigeon pea trade into ingredient-grade and commodity-grade lanes, with quality differentiation now embedded in contract structures rather than spot market premiums.
Near-infrared spectroscopy coupled with machine learning classification is decentralizing quality assessment from centralized laboratories to origin-level procurement points. African and Indian millers deploy portable NIR units at farmgate collection centers, enabling real-time protein content verification and rejecting substandard lots before transport costs accumulate. This shift is compressing price discovery cycles and reducing arbitrage windows for intermediaries who previously exploited information asymmetries between farmers and exporters.
India's FSSAI pesticide residue limits and mycotoxin thresholds are mandating capital deployment in optical sorting infrastructure. Processing facilities must install color sorters and dehulling lines to achieve packaged product compliance, effectively raising minimum efficient scale for domestic market participation. Small-scale millers without upgrade capacity are exiting branded retail channels and retreating into unregulated bulk trade.
Buyer concentration among plant-based meat and beverage manufacturers is compressing supplier qualification timelines. Ingredient procurement teams now require carbon footprint documentation, regenerative agriculture certifications, and allergen-free handling protocols before contract award. East African and Indian exporters who cannot provide chain-of-custody traceability are losing position in premium ingredient tenders to vertically integrated processors with captive farming networks.
Pigeon Pea Market Segmentation
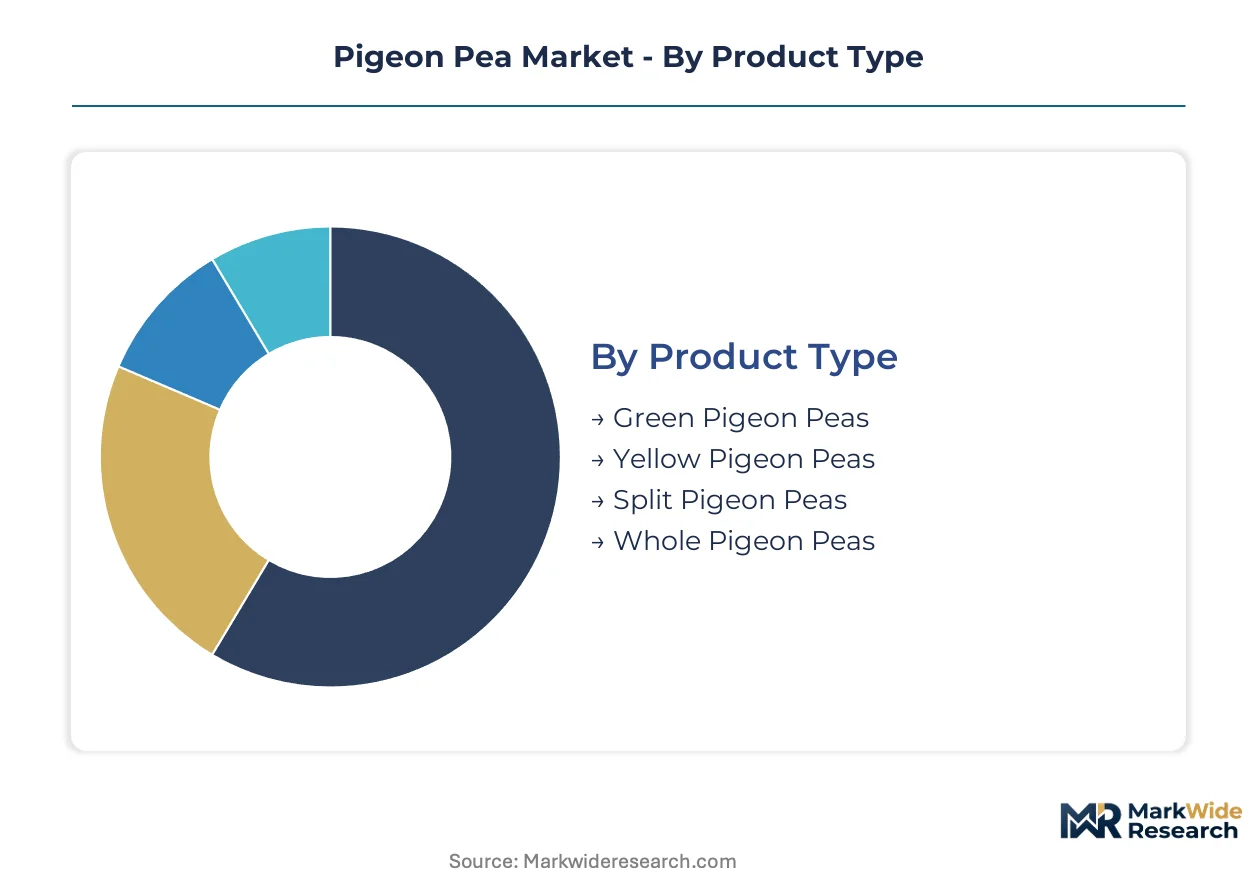
Pigeon pea processors navigate divergent margin structures across physical form and end-use specifications. Clean-label protein demand from beverage and plant-based meat formulators is compressing traditional commodity channels while opening premium ingredient lanes.
Product Type:
Volume concentration favors processed forms, yet whole beans retain origination control for exporters managing farmer procurement networks.
- Split Pigeon Peas:Mechanical dehulling and splitting reduce cooking time by 60% compared to whole beans. Dal manufacturers in India and East Africa concentrate procurement here, though margin compression from commoditization is accelerating processor investment in powdering capacity.
- Whole Pigeon Peas:Intact seed form preserves germination viability and extends storage stability in tropical climates. Exporters in Maharashtra and Karnataka anchor origination volume here, with FSSAI-mandated optical sorting infrastructure determining export eligibility.
- Green Pigeon Peas:Immature harvest at 60-70% moisture content delivers fresh vegetable markets.
- Yellow Pigeon Peas:Fully mature dried seed with higher starch gelatinization temperature suits extended cooking applications.
Mature deployment sits with Split Pigeon Peas. Newer deployment is concentrated in value-added fractionation targeting protein isolate production.
End Use:
Customer specifications diverge sharply between ingredient-grade protein demand and bulk commodity offtake.
- Food Industry:Human consumption spans traditional dal preparations, gluten-free flour blends, and extruded snack matrices. Plant-based meat formulators in North America and Europe are pulling split and powdered volumes into premium ingredient contracts with carbon footprint documentation requirements.
- Animal Feed:Detoxified seed cake from oil extraction and dehulling operations substitutes for soybean meal in ruminant and poultry rations. Price volatility in soybean markets is expanding formulation trials across Brazilian and Southeast Asian feed compounders.
- Snack Products:Roasted and flavored whole seed formats target convenience channels.
- Fertilizers:Residual biomass and rhizobial inoculant applications support organic farming systems.
Revenue concentration favors Food Industry procurement. Fastest volume expansion is occurring in Animal Feed as detoxification protocols mature.
Form:
Moisture content and shelf stability determine logistics economics and market access radius.
- Dried:Reduced moisture to 10-12% enables ambient storage and containerized ocean freight. Kenyan and Tanzanian importers concentrate procurement here for milling and retail repackaging.
- Powdered:Fine particle size below 200 micron enables protein fortification in beverages and bakery matrices. EFSA novel food approval timelines constrain European market entry despite clean-label demand from alternative protein formulators.
- Canned:Thermal processing in brine extends ready-to-eat convenience.
- Frozen:Blast-frozen green peas supply foodservice and retail vegetable channels.
Processing infrastructure concentrates on Dried forms. Steepest expansion trajectory belongs to Powdered formats as fractionation technology scales.
Distribution Channel:
Channel selection determines traceability depth and margin capture for processors.
- Wholesale:Bulk container sales to millers and traders dominate export volume from Indian and East African origins. FSSAI and USDA grading standards govern contract specifications, with rejection risk at port driving investment in pre-shipment inspection.
- Supermarkets:Branded retail packs with pesticide residue compliance and nutritional labeling command domestic Indian and urban African shelf space.
- Direct Sales:Captive offtake from vertically integrated processors to food manufacturers.
- Online Retail:E-commerce platforms aggregate diaspora demand in North America and Europe.
Volume flows through Wholesale channels. Premium positioning is concentrating in Direct Sales as ingredient manufacturers qualify suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import procurement concentrates in East African urban corridors while value-added processing capacity clusters in South Asian export zones. Supply origination remains concentrated in Maharashtra and Karnataka states, with demand fragmentation accelerating across convenience food channels.
India
Dal manufacturers and plant-based protein formulators drive processed pigeon pea demand through dehulling and powdering lines. The FSSAI mandates pesticide residue limits and mycotoxin thresholds that force capital deployment in optical sorting infrastructure. Maharashtra and Karnataka anchor exportable surplus volumes, with processing clusters in Mumbai and Bengaluru scaling fractionation capacity for ingredient-grade isolates.
Kenya
Urbanization accelerates convenience food consumption, concentrating import demand for canned and dried varieties in Nairobi and Mombasa retail channels. The country's national food safety regulator enforces mycotoxin standards that filter supplier eligibility at port of entry. Mombasa's milling corridor processes bulk imports for redistribution across East African Community markets.
Tanzania
Smallholder intercropping systems supply regional origination networks while Dar es Salaam importers concentrate procurement for domestic milling and re-export. Rhizobial nitrogen fixation programs generate carbon credit eligibility under voluntary offset schemes. The Southern Highlands farming belt anchors farmer procurement relationships that secure volume for export milling operations.
United States
Alternative meat formulators and clean-label beverage manufacturers pull split and powdered volumes into premium ingredient contracts. USDA grading standards for whole and split peas establish quality benchmarks governing import acceptance at Gulf and West Coast ports. California and Midwest food technology clusters drive formulation trials for extruded snack matrices.
Germany
EFSA novel food approval timelines constrain European market entry for pigeon pea protein isolates despite clean-label demand from bakery and beverage manufacturers. The EU Green Deal carbon accounting framework enters procurement specifications for ingredient buyers seeking scope 3 emissions reductions. Hamburg's port infrastructure handles containerized pulse imports for redistribution to continental processing facilities.
Pigeon Pea Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with commodity trading houses dominating bulk origination while ingredient processors capture premium fractionation margins. Market structure tiers into three archetypes: agricultural conglomerates with origination networks, regional millers with FSSAI-compliant processing infrastructure, and specialty ingredient houses supplying isolate-grade protein. Competitive moves concentrate on backward integration into farmer procurement and capacity expansion in powdering and fractionation lines.
Within the agricultural conglomerate tier, Archer Daniels Midland Company and Bunge Limited exemplify North American infrastructure leverage for protein extraction and isolate supply. Olam International Limited anchors African origination networks, sustaining procurement relationships across Tanzania and Mozambique that secure volume for export milling. These three entities occupy positions spanning commodity origination through value-added ingredient channels, with geographic diversification reducing weather-dependent volume risk.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Bunge Limited |
| Olam International Limited |
| Sun Impex |
| Wilmar International Limited |
| Export Trading Group |
| Louis Dreyfus Company |
| Interamsa Agroindustrial SAC |
| Cargill, Incorporated |
| Others |
Cost & Logistics Intelligence
Skilled membrane filtration technicians in Maharashtra and Karnataka command wage premiums that compress margins at mid-scale processors, widening the spread between commodity whole-bean pricing and isolate-grade ingredient premiums. Labor-cost differentials between South Asian processing hubs and East African origination zones stratify pricing tiers across export markets.
Pricing Analysis
Volume concentration in whole-bean commodity channels faces margin compression while protein isolate fractions capture ingredient premiums. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-compliant isolate-grade powder from FSSAI-certified packaged retail from bulk export whole beans. Pricing pressure stems from aqueous fractionation yield limitations that constrain isolate economics against soy protein benchmarks. Small-scale millers without optical sorting infrastructure exhibit highest price sensitivity, while plant-based meat formulators demonstrate lowest sensitivity given clean-label procurement mandates.
Supply Chain Analysis
Dual-sourcing requirements from European and North American ingredient buyers mandate multi-supplier qualification across Indian and East African origins. Geographic supply concentration centers on Maharashtra and Karnataka states in India, with Tanzania and Mozambique anchoring African origination. Raw material dependencies include rhizobial inoculants for nitrogen fixation, phosphate and potash supplements, and membrane filtration consumables. Single-source vulnerability concentrates in Maharashtra's exportable surplus during monsoon-disrupted harvests. Distribution runs through Mombasa and Dar es Salaam port corridors for East African redistribution, with Mumbai and Bengaluru processing clusters serving containerized ocean freight to European and North American markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FSSAI-mandated pesticide residue compliance creates a cost-of-compliance moat that filters sub-scale competitors from branded retail channels, consolidating margin capture among capitalized processors with optical sorting infrastructure.
For Market Incumbents: Cement backward integration into farmer procurement networks across Tanzania's Southern Highlands and Maharashtra's Deccan Plateau to secure volume against weather-dependent supply shocks. Expand powdering and fractionation capacity in Bengaluru and Mumbai clusters to capture isolate-grade premiums before EFSA novel food approvals unlock European demand. Defend against emerging African millers acquiring Chinese optical sorting equipment by locking long-term offtake contracts with plant-based meat formulators requiring carbon footprint documentation. For New Entrants and Emerging Players: Foodservice distributors in Kenya's Nairobi corridor offer channel access with lower qualification barriers than European ingredient tenders. Target underpenetrated canned and dried convenience formats in Tanzania's urbanizing Dar es Salaam market, where import demand concentrates without domestic processing competition. Pursue co-manufacturing arrangements with established millers lacking EFSA-compliant isolate capacity as the go-to-market angle. For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale Indian millers possessing FSSAI-compliant infrastructure and untapped powdering capacity given PLI scheme capital subsidy tailwinds. Long-term viability over the five-to-ten year horizon hinges on carbon credit monetization for nitrogen-fixing crop credentials entering scope 3 procurement specifications. Watch for EFSA novel food approval timeline acceleration as the inflection signal indicating European isolate market unlock.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Farmer Procurement | Captive supply from Tanzania's Southern Highlands reduces weather-dependent volume risk for exporters. |
| Fractionation Capacity Expansion | Membrane filtration and spray-drying lines in Mumbai clusters capture protein isolate premiums. |
| EFSA Novel Food Approval Pathway | Regulatory authorization unlocks European ingredient contracts with bakery and beverage formulators. |
| Carbon Credit Certification Program | Rhizobial nitrogen fixation credentials enter scope 3 emissions reduction procurement specifications. |
| Optical Sorting Infrastructure Deployment | FSSAI-mandated pesticide compliance raises minimum efficient scale for domestic market participation. |
Research Approach
Document review covered customs and trade databases, FSSAI regulatory filings, and EFSA novel food submission records, complemented by interviews with pulse processing plant managers, procurement leads at plant-based meat formulators, agricultural commodity traders, and food technology R&D directors. Secondary validation drew from USDA grading standards documentation, EU Green Deal carbon accounting frameworks, and Indian PLI scheme implementation guidelines. Bottom-up volume estimates from farmer procurement networks triangulated against top-down import demand aggregation from Kenyan and Tanzanian port authorities.
Cross-referencing historical price series against industry panel inputs anchored the analytical framework across the analysis window. Segmentation dimensions modeled include physical form, end-use specification, moisture content category, and distribution channel depth. CAGRs derived from trend extrapolation adjusted for PLI scheme capacity addition timelines and EFSA approval pathway progression. Industry-specific forecast inputs incorporated fractionation technology yield improvement curves and intercropping system adoption rates in East African smallholder networks.
Caveats apply where EFSA novel food approval delays, monsoon disruption severity in Maharashtra, or phosphate and potash price volatility could materially shift the outlook. Deviation in any of these triggers would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Seed Cracker Market
Seeds
North America Vegetable Seed Market
Seeds
Mexico Seed Market
Seeds
Pasture Seeds Market
Seeds
Asia-Pacific Cannabis Seeds Market
Seeds
Drought Tolerant Seeds Market
Seeds
E. Angustifolium Market
Seeds
Bangladesh Seed Market
Seeds
Psyllium Seed Market
Seeds
Spain Forage Seed Market
Seeds
Field Crop Seeds Market
Seeds
Europe Quinoa Seed Market
Seeds
Global Forage Sorghum Seed Market
Seeds
Wax Gourd Seed Market
Seeds
South America Vegetable Seed Market
Seeds
India Forage Seed Market