
 United States Organic Fertilizers Market | 2026-2036
United States Organic Fertilizers Market Size, Share, and Industry Trends Forecast 2026-2036
United States Organic Fertilizers Market Analytics
USDA Organic certification is unwinding the competitive landscape by requiring third-party verification of input materials and prohibiting synthetic nutrient sources. The Espoma Company leverages its long-standing OMRI-listed product portfolio to sustain shelf space dominance across independent garden centers. Darling Ingredients Inc. anchors its position through backward integration into animal byproduct processing, securing captive supply of nitrogen-rich organic materials. Scotts Miracle-Gro competes by extending its conventional distribution muscle into organic lines through specialty retail partnerships.
United States organic fertilizers comprise nutrient amendments derived from plant, animal, or mineral sources containing minimum organic carbon content and processed without synthetic chemical alteration, typically delivering nitrogen through proteins and amino acids that require microbial mineralization for plant availability. These inputs serve commercial agriculture and consumer horticulture by rebuilding soil organic matter while meeting crop nutritional needs under restricted-input regimes. Liquid fertilizers lead volume in greenhouse and nursery channels where fertigation systems demand soluble delivery, while granular formats dominate field crop applications where broadcast spreading equipment prevails. Pellet fertilizers capture premium positioning in turf management where dust-free handling and controlled dispersion justify higher price points.
USDA's National Organic Program, EPA's Clean Water Act nutrient management provisions, and state-level fertilizer registration requirements in California and Florida collectively shape product formulation standards and market access pathways. The USDA Organic seal functions as a demand gatekeeper by restricting approved input substances and requiring documented chain of custody from production through application. Stakeholders must monitor evolving state phosphorus runoff regulations and carbon intensity scoring frameworks that could redefine which organic fertilizer sources qualify for preferred procurement programs.
Market Dynamics
USDA Organic certification requirements are compressing input choice sets while precision application technologies reduce per-acre nutrient waste, forcing suppliers to document chain of custody from raw material through field application.
Growth Catalysts
- USDA National Organic Program tightening:Third-party verification mandates for input materials are eliminating synthetic nutrient alternatives and expanding addressable market for OMRI-listed suppliers.
- Fertigation system adoption:Greenhouse and nursery operators in California and Florida are converting irrigation infrastructure to deliver soluble organic nutrients through existing drip lines.
- Processor organic specifications:Food manufacturers sourcing corn and soybeans are requiring documented organic fertility management, pulling row crop operators toward certified input procurement.
Market Restraints
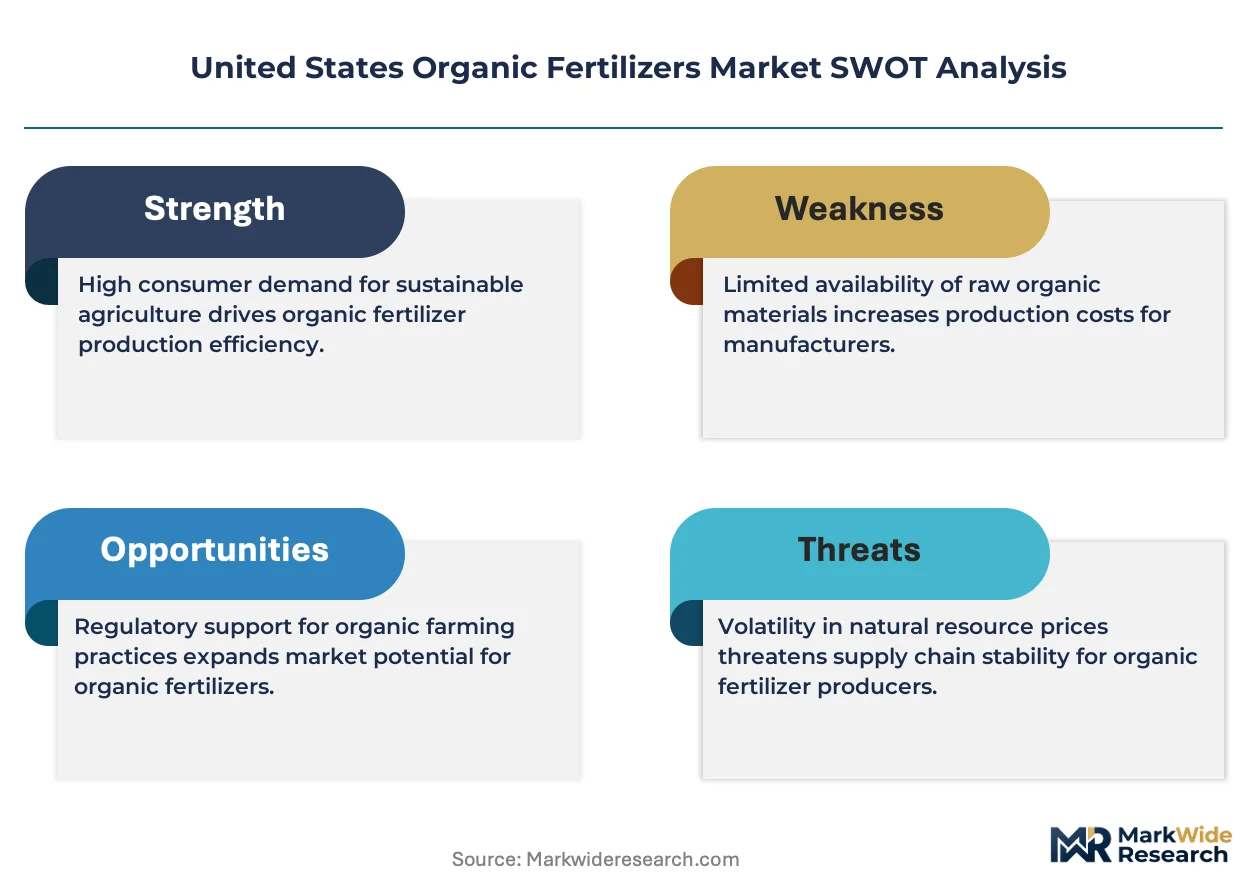
- Animal byproduct supply concentration:Nitrogen-rich organic material sourcing clusters in Midwest rendering facilities, creating geographic dependency and transport cost penalties for coastal buyers.
- Phosphorus runoff regulations:State-level restrictions in Florida and Chesapeake Bay watershed jurisdictions limit application timing and rates, constraining product utility windows.
- Mineralization rate variability:Microbial nitrogen release from protein-based materials lags synthetic alternatives by weeks, compressing yield response predictability during critical growth stages.
Strategic Opportunities
- Carbon intensity scoring frameworks:Emerging procurement programs in California and Washington State are creating preference tiers for low-carbon organic fertilizer sources, advantaging regional composting operations.
- Biostimulant convergence:Formulators combining humic acids with microbial inoculants are capturing premium positioning in specialty crop channels seeking multi-function inputs.
- Direct-to-farm digital channels:Agronomy platforms are bypassing traditional distribution to connect organic certifiers, applicators, and growers in closed-loop procurement networks.
Industry Challenges
- OMRI listing timeline compression:Certification review cycles extending 12-18 months are delaying product commercialization and freezing R&D pipeline visibility.
- Soil microbiome expertise scarcity:Agronomists trained in microbial mineralization dynamics and carbon-to-nitrogen ratio management remain concentrated in university extension programs, limiting field-level advisory capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Organic Fertilizers Market |
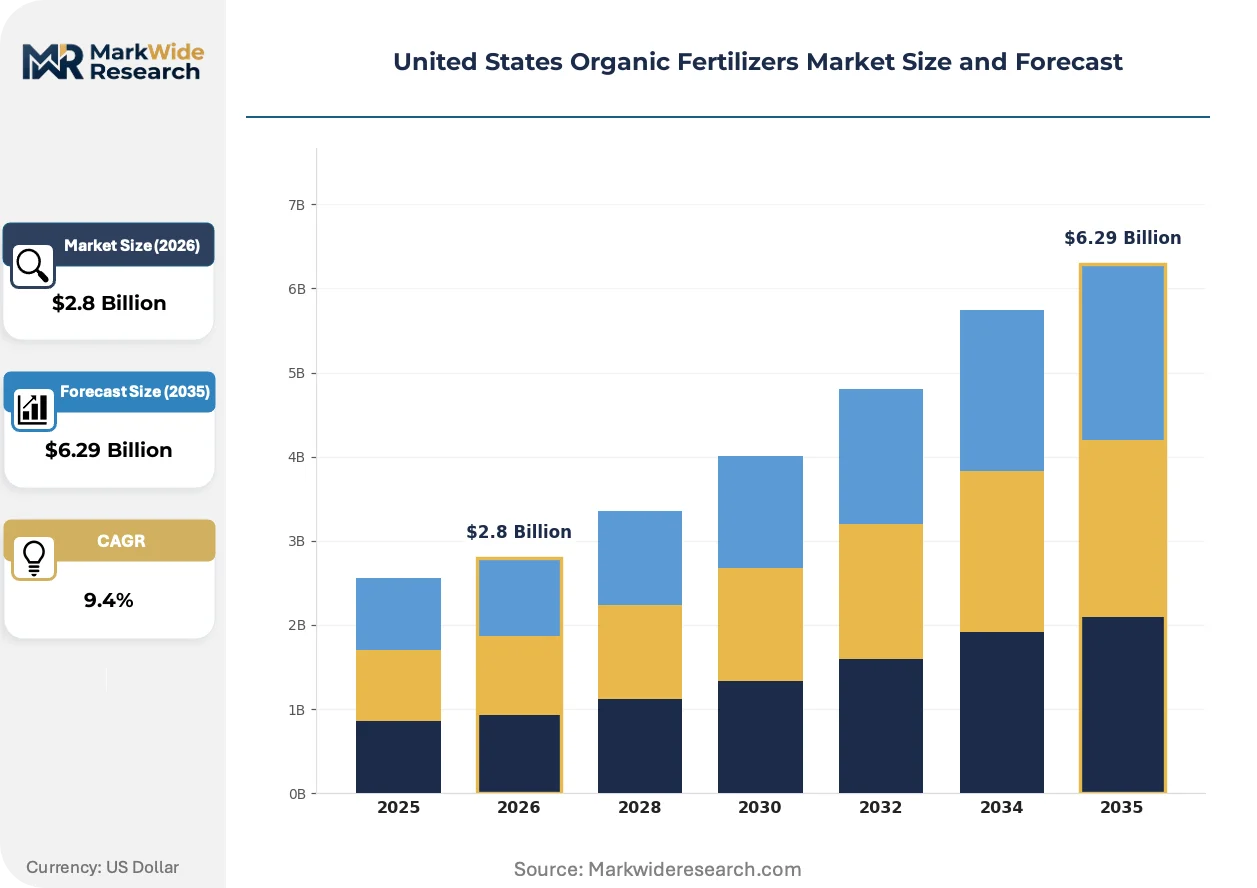
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.29 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Fertilizers, Granular Fertilizers, Pellet Fertilizers, Powder Fertilizers End User: Farmers, Turf, Greenhouses, Nurseries Application: Agricultural Crops, Horticultural Crops, Residential Gardening, Landscape Distribution Channel: Online Retail, Specialty Stores, Agricultural Cooperatives, Wholesale Distributors |
| Companies Covered | California Organic Fertilizers Inc., The Espoma Company, Sustane Natural Fertilizer Inc., Cedar Grove Composting Inc., Darling Ingredients Inc., The Scotts Miracle-Gro Company, True Organic Products, Inc., Sigma AgriScience, BioStar Systems, LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Organic Fertilizers Market Evolving Landscape
Biological activation technologies and carbon-accounting integration are redefining product value propositions, while digital traceability systems reshape how organic integrity is verified from production through application.
Microbially-activated organic fertilizers containing consortiums of nitrogen-mineralizing bacteria and phosphorus-solubilizing fungi are supplanting raw manure and compost products in high-value vegetable production. Large-scale specialty crop operators in California's Central Valley are adopting these inoculated materials at accelerating rates. The shift is compressing demand for unprocessed organic amendments while elevating formulation science capabilities among suppliers.
EPA's Clean Water Act nutrient management provisions are tightening discharge permits for concentrated animal feeding operations, redirecting manure streams toward commercial organic fertilizer processing. Industrial consequence includes new capital investment in anaerobic digestion and composting infrastructure adjacent to livestock clusters. Corn Belt states with high CAFO density are experiencing the most pronounced facility construction activity.
Certification-driven preference shifts are consolidating purchasing authority among food processors and export-oriented grain handlers who specify organic fertility protocols. Independent row crop operators are losing procurement autonomy as handlers bundle input sourcing with contracting arrangements. This concentration is most visible in Iowa and Illinois where organic soybean exports to Asian markets require documented input chain of custody.
United States Organic Fertilizers Market Segmentation
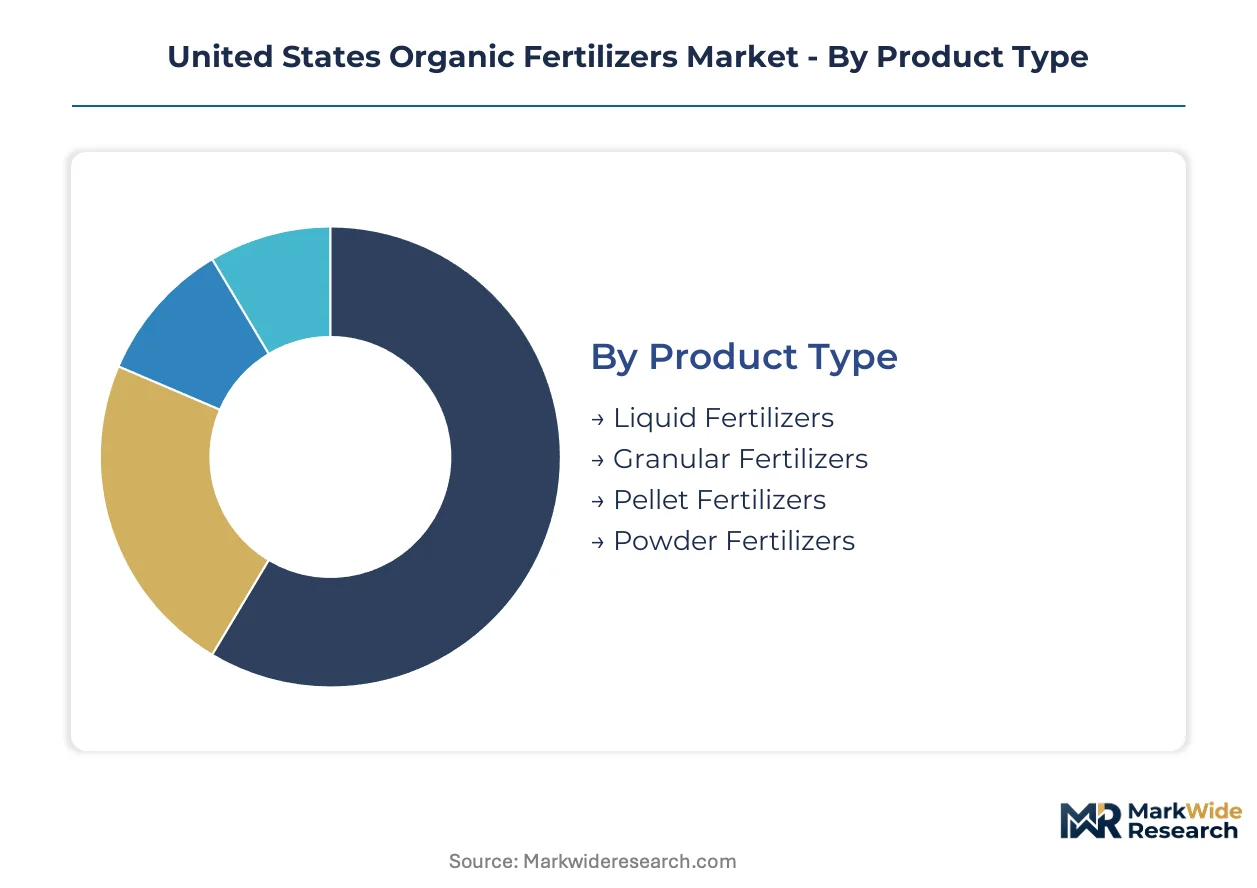
Segmentation in the United States organic fertilizers market reveals how product form, end-use requirements, and procurement channels create distinct competitive arenas with varying margin profiles. Understanding these divisions exposes where suppliers can defend pricing power versus where volume competition dominates.
Product Type:
Margins concentrate in formats that command premium positioning through handling advantages or application precision.
- Liquid Fertilizers:Soluble concentrates designed for fertigation systems deliver nitrogen through proteins and amino acids in aqueous suspension. California Central Valley vegetable growers and Florida greenhouse operators are converting irrigation infrastructure to accommodate these inputs, pulled by precision application requirements and labor cost reduction.
- Granular Fertilizers:Broadcast-spreadable materials dominate field crop applications across Iowa, Illinois, and Indiana where row crop operators mechanize fertility programs. The format sacrifices solubility for storage stability and equipment compatibility, anchoring volume leadership despite lower per-ton margins.
- Pellet Fertilizers:Dust-free handling and controlled dispersion characteristics justify premium positioning in turf management and high-value ornamental production.
- Powder Fertilizers:Fine-ground organic materials serve specialty blenders and compost tea formulators seeking rapid microbial activation.
The dominant share belongs to Granular Fertilizers, while Liquid Fertilizers is closing the gap fastest.
End User:
Customer type determines whether procurement flows through certified channels with documentation requirements or spot-market transactions.
- Farmers:Row crop and specialty crop operators purchasing under USDA Organic certification constraints require chain-of-custody documentation from input through application. Corn Belt states and California Central Valley concentration creates geographic clustering of demand tied to processor organic specifications.
- Greenhouses:Controlled-environment agriculture operators in Florida and California prioritize soluble, low-residue formulations compatible with recirculating irrigation systems.
- Turf:Golf courses, sports fields, and municipal grounds managers seek dust-free handling and uniform dispersion characteristics.
- Nurseries:Containerized plant producers balance slow-release requirements with transplant timing flexibility.
Farmers command the largest volume position, though Greenhouses demonstrates the steepest expansion trajectory as controlled-environment agriculture scales.
Application:
Application context dictates formulation requirements from bulk nutrient delivery to precision micronutrient management.
- Agricultural Crops:Corn, soybean, and wheat operations transitioning portions of acreage to organic certification drive tonnage demand across Midwest states. Processor contracting requirements are pulling conventional operators toward documented organic fertility management.
- Horticultural Crops:Vegetable and fruit producers in California and Florida face the tightest USDA Organic verification requirements, concentrating premium product demand.
- Residential Gardening:Consumer horticulture channels favor small-package, OMRI-listed products with retail shelf presence.
- Landscape:Commercial installation and maintenance contractors prioritize cost-efficient bulk procurement with reliable availability.
Agricultural Crops retains volume leadership, while Horticultural Crops gains share fastest on specialty crop premiumization.
Distribution Channel:
Channel structure determines whether suppliers capture margin through direct relationships or concede value to intermediaries.
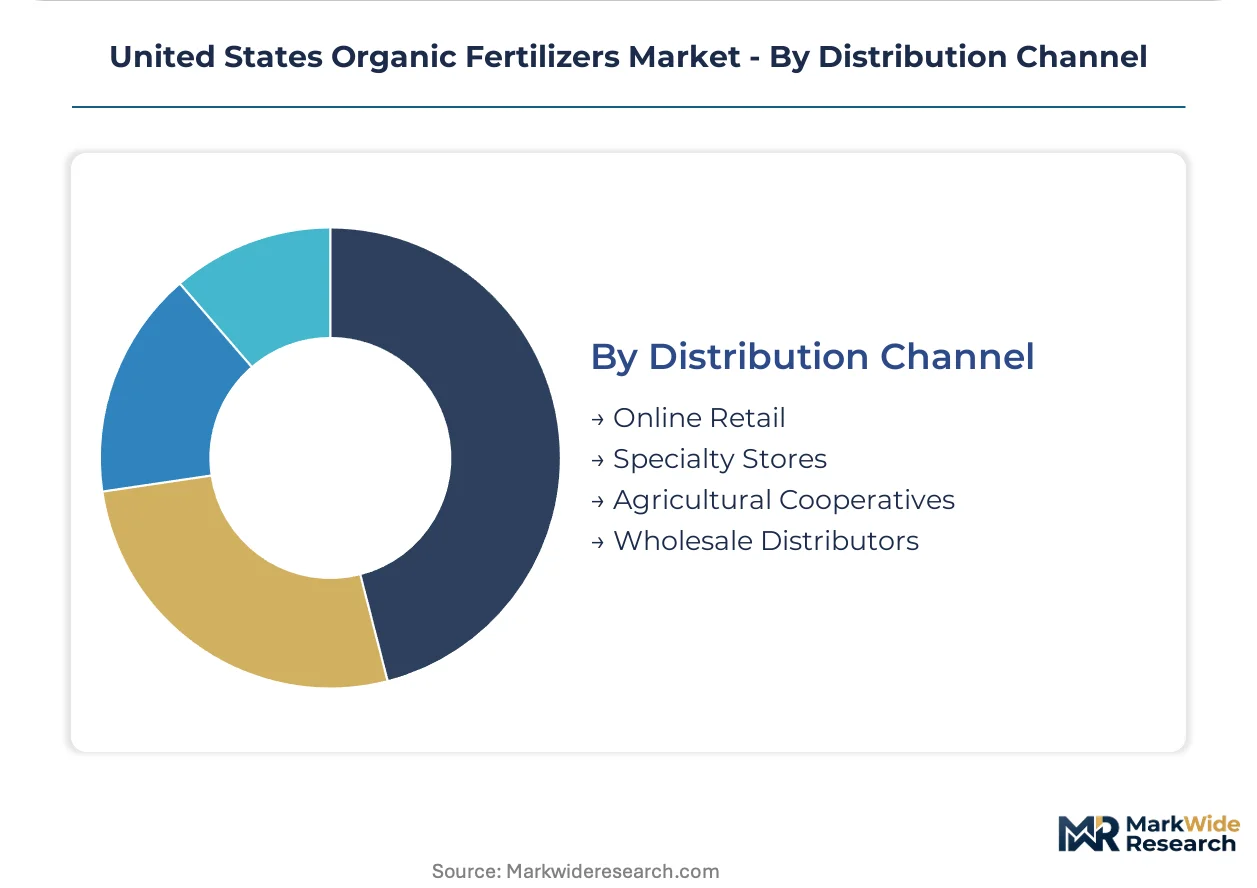
- Wholesale Distributors:Bulk handling infrastructure and established relationships with farm supply retailers anchor volume throughput across Corn Belt states. These intermediaries consolidate procurement for independent row crop operators while bundling credit and logistics services.
- Agricultural Cooperatives:Member-owned purchasing entities in Iowa, Minnesota, and Nebraska negotiate collective procurement terms for organic-certified inputs, concentrating buyer power.
- Specialty Stores:Independent garden centers and farm supply retailers serve consumer horticulture and small-scale commercial operators with technical advisory services.
- Online Retail:Direct-to-farm platforms and agronomy marketplaces are bypassing traditional distribution layers to connect certifiers, applicators, and growers in closed-loop networks.
Wholesale Distributors holds the dominant position, though Online Retail is expanding most quickly as digital procurement platforms mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
USDA Organic certification incentives and processor contracting requirements are redistributing organic fertilizer demand across distinct agricultural regions, with state-level regulations accelerating adoption in high-value crop zones.
California
Central Valley vegetable growers and Salinas Valley leafy green producers drive soluble liquid fertilizer consumption through fertigation infrastructure. The state's Department of Food and Agriculture enforces strict organic input registration alongside regional water quality control boards limiting nitrogen runoff. Fresno and Monterey counties concentrate precision application technology deployment as growers document fertility management for processor export contracts.
Florida
Greenhouse operators in the Lake Alfred region and sugarcane producers in the Everglades Agricultural Area convert irrigation systems to organic-compatible fertigation. State phosphorus runoff restrictions under the Everglades Forever Act constrain application timing and rates, compressing product utility windows. Miami-Dade County nurseries and Palm Beach turf managers command premium pellet formulations for dust-free handling requirements.
Iowa
Corn Belt row crop operations transitioning acreage to organic certification drive granular fertilizer tonnage through broadcast spreading equipment. The Iowa Department of Agriculture and Land Stewardship administers cost-share programs for organic transition alongside nutrient management plan requirements for impaired watersheds. Sioux City and Des Moines corridor distribution hubs consolidate procurement for soybean exporters documenting chain of custody for Asian markets.
Illinois
Central Illinois organic soybean producers face processor contracting requirements that bundle input sourcing with grain handling arrangements. The Illinois EPA enforces Clean Water Act nutrient management provisions affecting application windows in the Mississippi River watershed. Champaign-Urbana and Springfield agricultural cooperatives negotiate collective procurement terms for certified organic inputs, concentrating buyer power.
Texas
High Plains cotton growers and Rio Grande Valley citrus producers adopt organic amendments for export market access and groundwater protection. The Texas Commission on Environmental Quality regulates fertilizer registration while regional water districts enforce nutrient management in the Edwards Aquifer recharge zone. Lubbock and McAllen distribution points serve expanding organic cotton acreage destined for textile certification programs.
United States Organic Fertilizers Market Competitive Landscape
Listed leaders compete with private specialists across certification documentation and supply chain integration dimensions, producing a tiered structure where scale advantages clash with nimble regulatory compliance. Public companies leverage distribution infrastructure and retail shelf presence while private operators exploit backward integration into raw material streams. Three archetypes dominate: animal byproduct processors securing captive nitrogen supply, garden center brands commanding consumer recognition, and regional composters capturing carbon intensity premiums. Consolidation pressures intensify through cooperative procurement networks and processor bundling arrangements that freeze out undifferentiated suppliers.
Within the animal byproduct processing tier, Darling Ingredients Inc. anchors supply security through rendering facility ownership, while The Espoma Company exemplifies OMRI-listed portfolio positioning across independent retail channels. The Scotts Miracle-Gro Company occupies the scale-driven mass-market vector, extending conventional distribution relationships into certified organic lines. California Organic Fertilizers Inc. and True Organic Products, Inc. represent regional formulators competing on geographic proximity to high-value specialty crop zones. These players collectively illustrate how certification compliance, raw material access, and channel control separate viable competitors from marginal participants.
| Leading Market Players |
|---|
| California Organic Fertilizers Inc. |
| The Espoma Company |
| Sustane Natural Fertilizer Inc. |
| Cedar Grove Composting Inc. |
| Darling Ingredients Inc. |
| The Scotts Miracle-Gro Company |
| True Organic Products, Inc. |
| Sigma AgriScience |
| BioStar Systems, LLC |
| Others |
Value Network & Pricing Analysis
USDA Organic certification functions as a dual gatekeeper, simultaneously filtering which suppliers qualify for market participation and stratifying price premiums across OMRI-listed versus non-certified alternatives. This regulatory architecture compresses supplier margins on unverified materials while amplifying pricing power for documented chain-of-custody providers.
Pricing Analysis
Certification level creates the primary spread between premium OMRI-listed formulations and commodity organic alternatives. Three-tier pricing structure separates certified liquid concentrates for greenhouse fertigation from standard granular field crop materials and economy bulk compost products. Cost compression in economy tiers is intensifying because Midwest rendering facilities face transport cost penalties to coastal buyers. Specialty crop operators in California demonstrate lowest price sensitivity due to processor export contract requirements, while Corn Belt row crop transitioners exhibit highest sensitivity as they balance organic premium capture against yield risk.
Supply Chain Analysis
Strategic stockpile preferences dominate among California and Florida greenhouse operators facing seasonal supply constraints, while Corn Belt row crop buyers favor just-in-time procurement through cooperative networks. Supply concentrates in Midwest rendering facilities, Florida composting operations, and California regional formulators. Raw material flows draw from animal byproduct processing, municipal organic waste streams, and plant-derived protein meals. Single-source vulnerability runs through concentrated animal feeding operation manure streams redirected by EPA discharge permit tightening. Distribution runs through agricultural cooperatives in Iowa and Illinois, wholesale distributors across the Corn Belt, and direct-to-farm digital platforms bypassing traditional intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Organic fertilizer penetration sits at early-cycle expansion as processor contracting requirements pull conventional row crop operators toward certified input procurement faster than supply infrastructure can scale.
For Market Incumbents: Secure backward integration into animal byproduct processing or regional composting infrastructure to defend against nitrogen supply concentration risk. Anchor shelf space dominance through OMRI-listing pipeline acceleration, compressing review timelines that currently freeze R&D visibility. Capacity addition in California Central Valley and Florida greenhouse corridors captures fastest-expanding demand channels. For New Entrants and Emerging Players: OMRI fast-track certification programs create entry pathways into specialty crop segments where documentation requirements exceed incumbent capacity. White-space targets concentrate in biostimulant-convergent formulations combining microbial inoculants with humic acids, and in direct-to-farm digital channels connecting certifiers with growers. Turf management pellet formulations offer penetrable premium positioning with lower certification barrier than agricultural channels. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across anaerobic digestion and composting infrastructure as EPA Clean Water Act provisions redirect manure streams toward commercial processing. Five-to-ten year viability favors regional formulators with captive raw material supply and geographic proximity to high-value specialty crop zones. Acquisition target archetypes include Midwest rendering-adjacent processors and California composting operations positioned for carbon intensity scoring premiums. The signal to watch is California and Washington State procurement program implementation timelines for low-carbon fertilizer preference tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rendering | Darling Ingredients anchors nitrogen supply security through captive animal byproduct processing infrastructure. |
| OMRI Listing Acceleration | The Espoma Company compresses certification timelines to sustain independent garden center shelf space dominance. |
| Biostimulant Formulation Convergence | Sigma AgriScience captures premium positioning by combining microbial inoculants with humic acid delivery systems. |
| Direct-to-Farm Digital Platform | Agronomy marketplaces bypass wholesale distribution layers to connect organic certifiers with closed-loop grower networks. |
| Carbon Intensity Scoring Alignment | Regional composters in California position for procurement preference tiers under emerging state-level low-carbon fertilizer programs. |
Research Methodology
A standing panel of agronomists specializing in microbial mineralization dynamics, organic certification compliance officers, agricultural cooperative procurement managers, and specialty crop operations directors provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with these stakeholders alongside secondary validation through USDA National Organic Program filings, EPA Clean Water Act discharge permit databases, state fertilizer registration records in California and Florida, and agricultural cooperative procurement disclosures. Bottom-up volume modeling triangulated against top-down value estimates derived from distribution channel throughput analysis.
Consistency checks validated volume and value outputs against external benchmarks including agricultural input trade flow data and processor organic contracting disclosure patterns. Segmentation modeling spanned product form, end-user type, application context, and distribution channel across the projection horizon. CAGRs were derived from trend extrapolation calibrated to documented organic acreage transition rates and fertigation infrastructure conversion timelines. Industry-specific forecast inputs incorporated OMRI listing pipeline velocity and state-level phosphorus runoff regulatory evolution.
The analysis sits within stated boundaries; outcomes outside sustained processor organic specification tightening or accelerated EPA nutrient management enforcement would require recalibration. Forecasts reflect assumptions regarding microbial activation technology adoption curves and carbon intensity scoring framework implementation. Revision becomes warranted when state-level procurement program thresholds cross implementation tipping points or when CAFO manure stream redirection volumes exceed anaerobic digestion capacity expansion rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
China Controlled Release Fertilizer Market
Fertilizers
India Controlled Release Fertilizer Market
Fertilizers
Global NPK Fertilizer Market
Fertilizers
North America Fertilizers Market
Fertilizers
China Micronutrient Fertilizer Market
Fertilizers
Brazil Organic Fertilizer Market
Fertilizers
India Organic Fertilizer Market
Fertilizers
Humate Fertilizer Market
Fertilizers
Global Urea Market
Fertilizers
Soil Conditioners Market
Fertilizers
Asia Pacific Controlled Release Fertilizers Market
Fertilizers
Malaysia NPK Fertilizer Market
Fertilizers
Mineral Fertilizers Market
Fertilizers
Ammonium Thiosulfate Fertilizer Market
Fertilizers
South America Micronutrient Fertilizer Market
Fertilizers
United States Specialty Fertilizer Market