
 Dodder Seed Market | 2026-2036
Dodder Seed Market Size, Share, and Industry Trends Forecast 2026-2036
Dodder Seed Market Analysis
China is tilting its dodder seed processing capacity toward GMP-certified extraction facilities in Shaanxi Province. Novoherb Technologies leverages vertical integration from cultivation to standardized extract production. Jiaherb, Inc. anchors its competitiveness through intensive R&D on flavonoid fingerprinting for pharmaceutical clients. Yan'an Pharmaceuticals Co., Ltd. dominates regional supply chains through direct contracts with farmers in the Loess Plateau growing belt.
Dodder seed comprises the dried ripe seeds of Cuscuta species, typically containing flavonoids such as quercetin and kaempferol alongside chlorogenic acid and polysaccharides, with pharmaceutical grade requiring minimum 5% total flavonoid content by UV spectrophotometry. Brown Dodder extracts command premium positioning in renal tonification formulations across East Asian pharmacopeias, while Yellow Dodder supplies bulk agricultural inoculant applications where price sensitivity limits margin expansion. The Research application segment is registering accelerated procurement from universities validating neuroprotective mechanisms, though Agricultural Crops still occupies the largest volume share through parasitic plant management programs.
China's NMPA enforces pharmacognostic identification standards under the Chinese Pharmacopoeia that restrict market access for non-compliant imports. The EU EMA requires THR registration or traditional-use registration for dodder seed products marketed with therapeutic claims in member states. Stakeholders must monitor evolving monograph updates from both regulators to determine whether to prioritize pharmaceutical-grade extraction investments or maintain agricultural commodity positioning.
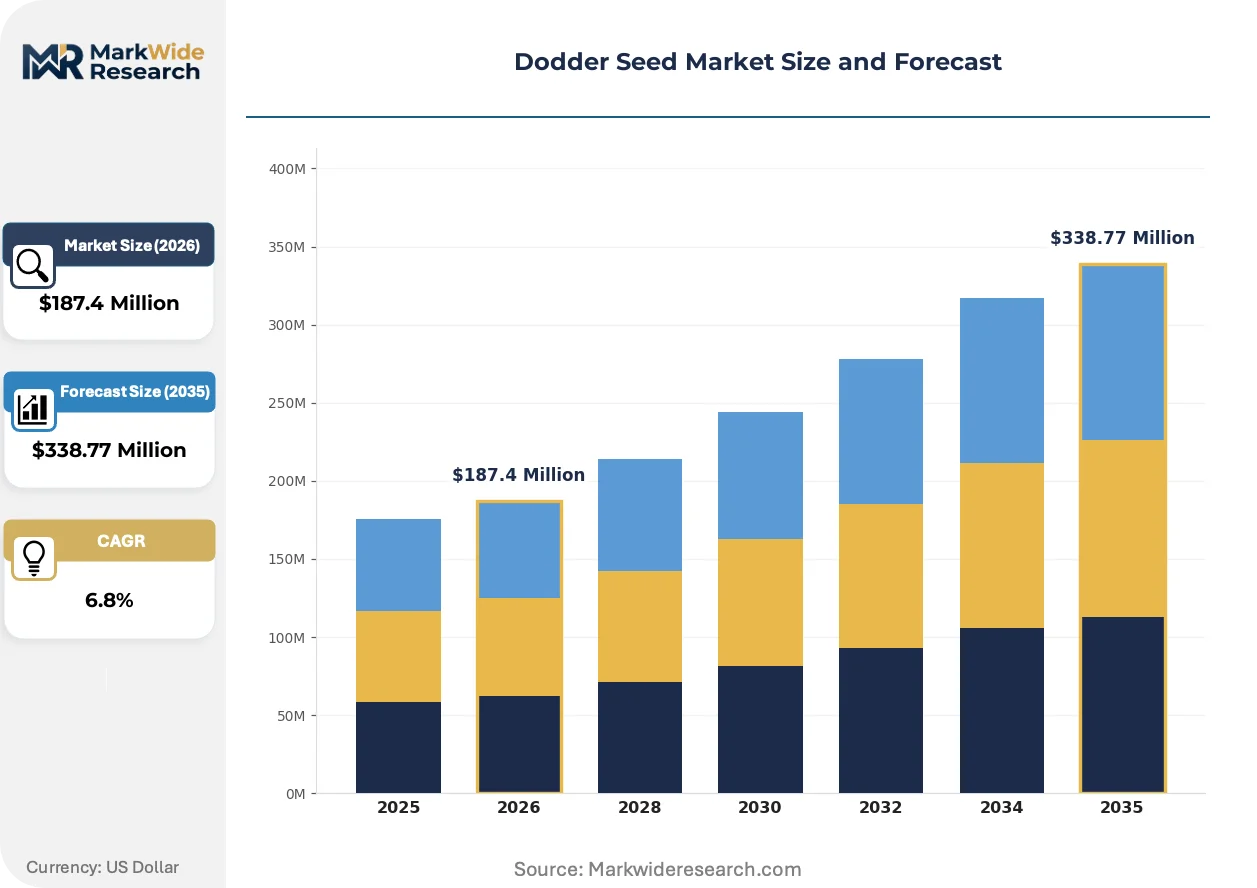
Market Dynamics
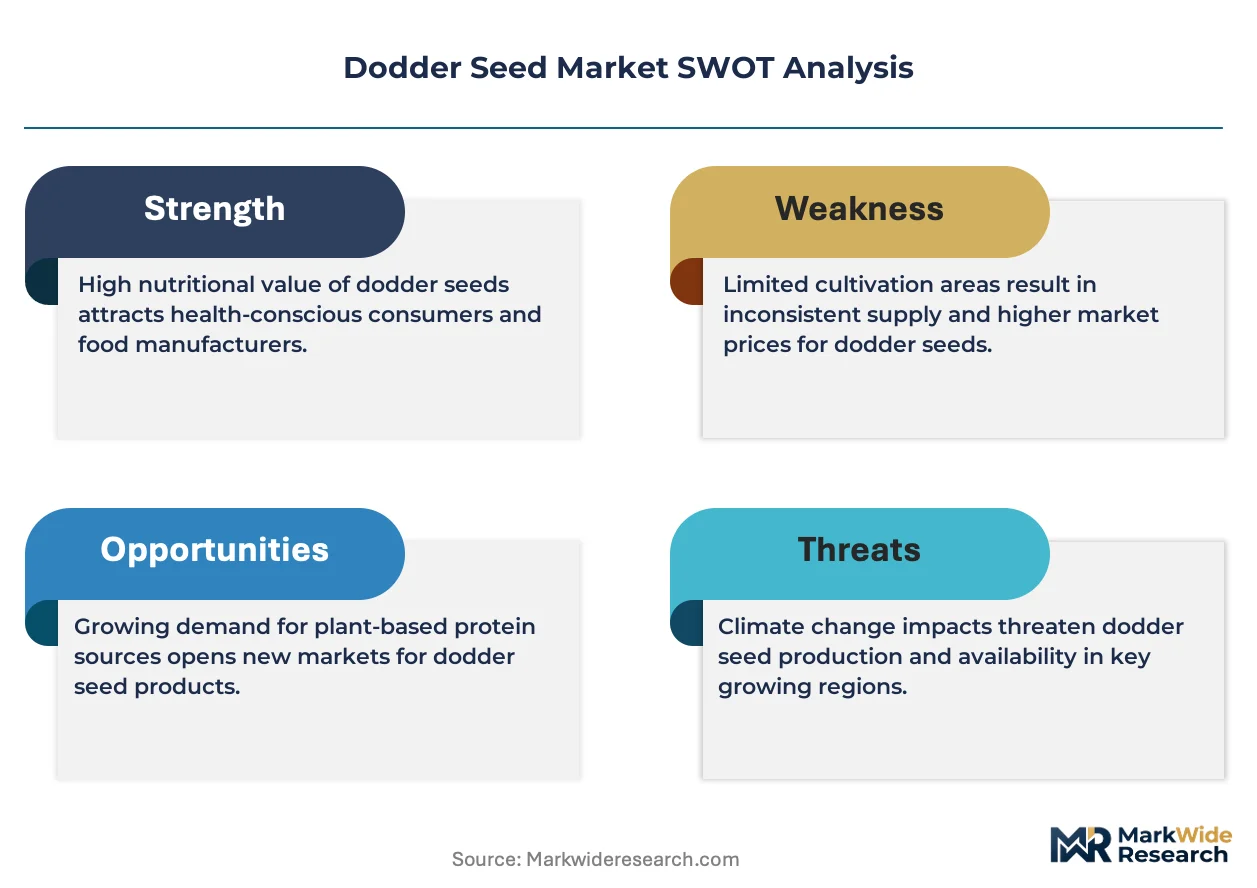
Pharmaceutical-grade flavonoid standardization is compressing margins for commodity-grade suppliers while concentrating procurement power among GMP-certified extractors in Shaanxi and Henan provinces.
Growth Catalysts
- EU Herbal Medicinal Products Directive:Quality certification requirements under the THR registration pathway are filtering out uncertified competitors and expanding addressable market share for compliant extractors serving renal wellness formulators.
- Neuroprotective research validation:University procurement for mechanistic studies on quercetin and kaempferol derivatives is creating a dedicated Research application channel with premium pricing tolerance.
- China's Loess Plateau cultivation belt:Direct farmer contracts by processors in Yan'an and Yulin are securing captive raw material supply with traceable provenance for export-grade extraction.
Market Restraints
- Input cost volatility:Fluctuations in labor-intensive hand-harvesting costs across Shaanxi's hilly terrain compress margins for non-integrated processors lacking captive cultivation.
- Regulatory friction:Divergent pharmacognostic standards between China's NMPA Pharmacopoeia and EU EMA monographs force dual-certification investments that exclude smaller agricultural commodity traders.
- Substitution pressure:Synthetic flavonoid production and alternative botanical sources for renal tonification formulations threaten Brown Dodder's premium positioning in price-sensitive East Asian markets.
Strategic Opportunities
- Underpenetrated German pharmaceutical procurement:Formulators in Baden-Württemberg and Bavaria are expanding hepatic wellness R&D pipelines with limited domestic extraction capacity, creating import dependency.
- Technology convergence:Integration of HPLC fingerprinting with AI-driven batch consistency prediction is enabling real-time quality assurance that reduces pharmaceutical client audit cycles.
- PLI scheme alignment:India's production-linked incentive framework for active pharmaceutical ingredients offers tariff-advantaged manufacturing for exporters targeting European markets.
Industry Challenges
- Flavonoid quantification expertise gap:UV spectrophotometry and HPLC method validation require analytical chemists in short supply across China's inland processing zones.
- Dual-certification timeline compression:Simultaneous NMPA GMP and EU EMA THR compliance audits demand 18-24 month capital lockup periods that strain mid-cap extractor balance sheets.
- Legacy supply chain reconfiguration:Shifting from spot-market raw material purchasing to contracted farmer networks requires working capital restructuring and rural logistics investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dodder Seed Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Brown Dodder, Yellow Dodder, Hairy Dodder, Other Types Application: Agricultural Crops, Horticulture, Research, Bio-control Distribution Channel: Direct Sales, Online Retail, Agricultural Cooperatives, Others End User: Farmers, Research Institutions, Agricultural Companies, Universities |
| Companies Covered | Novoherb Technologies, Jiaherb, Inc., Yan'an Pharmaceuticals Co., Ltd., Parchem Fine & Specialty Chemicals, Linden Botanicals, Nutra Green Biotechnology Co., Ltd., Evergreen Biotech Inc., Xi'an Realin Biotechnology Co., Ltd., Hangzhou Botanical Technology Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dodder Seed Market Emerging Trajectories
Extraction technology and regulatory data integrity requirements are restructuring competitive advantage around certified traceability and standardized bioactive content rather than raw volume throughput.
Supercritical CO2 extraction with ethanol co-solvent modification is hybridizing traditional solvent-based methods for flavonoid recovery. Pharmaceutical formulators in Germany and Switzerland are specifying this hybrid process in procurement tenders to minimize residual solvent detection. The technology is hybridizing equipment investment patterns, forcing agricultural-grade processors to choose between capital-intensive upgrade or permanent commodity-tier positioning.
EMA's evolving THR registration requirements for traditional herbal medicinal products are tightening botanical identity verification protocols. Industrial consequence includes mandatory DNA barcoding and chromatographic fingerprint submission for new product approvals. Brown Dodder extracts marketed with renal tonification claims face the most stringent scrutiny, driving consolidation among extractors with in-house analytical capabilities.
Direct contracting between pharmaceutical formulators and cultivation clusters is displacing layered trader intermediaries in raw material procurement. This channel compression is most visible in China's Shaanxi Province, where Novoherb Technologies and similar integrated processors now supply finished extracts rather than seeds. Japanese and South Korean buyers are replicating this model through equity stakes in Henan cultivation cooperatives.
Dodder Seed Market Segmentation
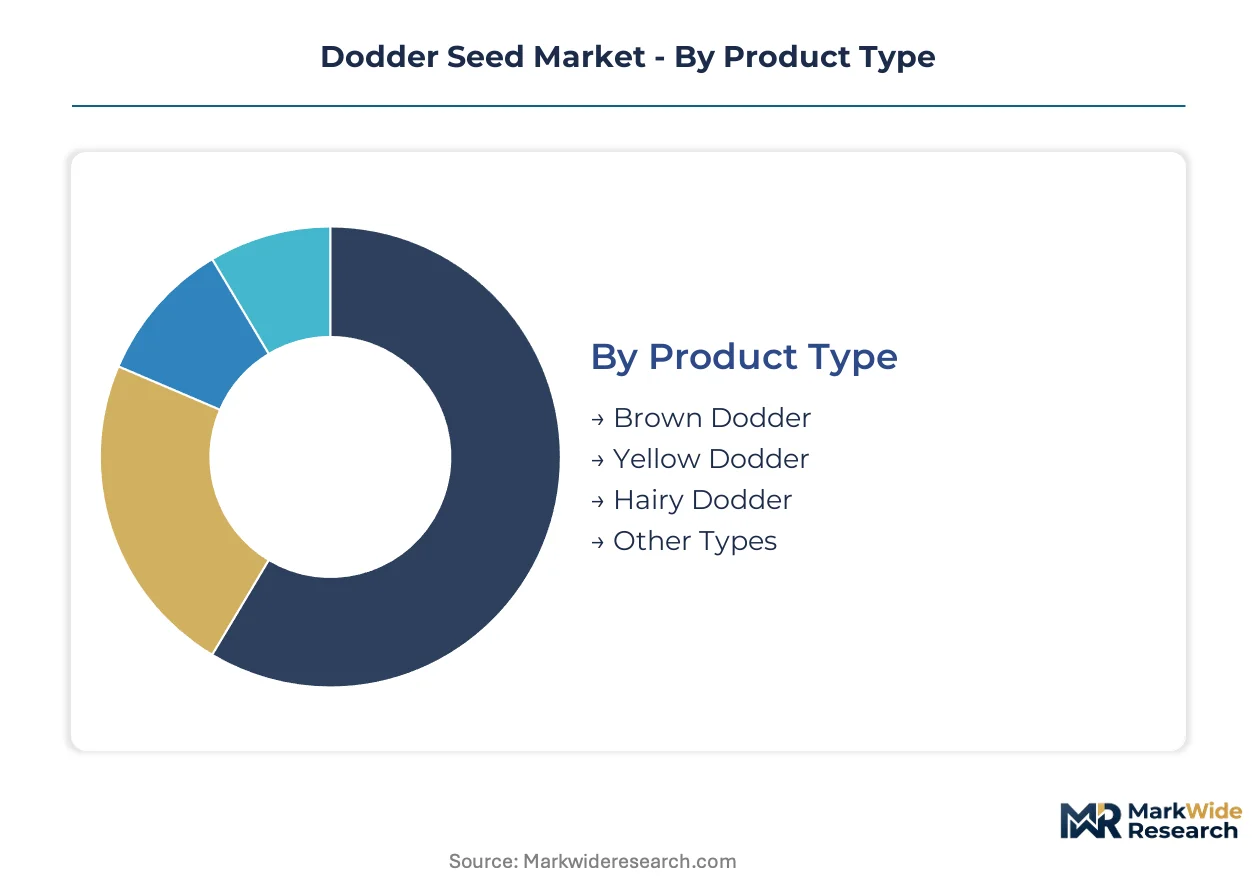
Dodder seed segmentation reveals divergent margin structures across pharmaceutical-grade extraction and agricultural commodity channels. Procurement specifications from German formulators and Chinese traditional medicine manufacturers create distinct quality tiers that reshape supplier competitive positioning.
Product Type:
After-sales service intensity varies sharply across product types, with pharmaceutical-grade Brown Dodder requiring batch-specific analytical support and agricultural Yellow Dodder demanding minimal technical follow-through.
- Brown Dodder:Contains elevated flavonoid concentrations including quercetin and kaempferol derivatives, with pharmaceutical specifications requiring minimum 5% total flavonoid content by UV spectrophotometry. Procurement from Shaanxi Province's GMP-certified extractors concentrates in renal tonification formulations for East Asian pharmacopeias, where EMA THR registration requirements filter out uncertified competitors.
- Yellow Dodder:Standardized for bulk agricultural inoculant applications with lower bioactive thresholds. Price sensitivity in parasitic plant management programs across China's Henan Province limits margin expansion, though volume throughput sustains processor economies of scale.
- Hairy Dodder:Niche positioning in traditional medicine formulations with regional pharmacognostic recognition under China's Pharmacopoeia standards.
- Other Types:Minor species including Cuscuta epithymum serving specialized research applications and botanical collection markets.
Brown Dodder holds the largest share; momentum sits with pharmaceutical-grade standardization.
Application:
Application segmentation tracks divergent R&D intensity, with Research channel procurement requiring mechanistic validation support versus Agricultural Crops demand focused on field efficacy demonstration.
- Agricultural Crops:Dominates volume throughput through parasitic plant management programs in China's cereal-producing regions. Procurement specifications prioritize cost efficiency over flavonoid standardization, with spot-market purchasing patterns prevailing among non-integrated distributors.
- Research:University procurement for neuroprotective mechanism studies on quercetin derivatives commands premium pricing tolerance. German and Swiss institutions specify HPLC fingerprinting documentation, creating dedicated channel differentiation from commodity supply.
- Horticulture:Specialty crop protection applications in protected cultivation systems across Japan and South Korea.
- Bio-control:Emerging integration with integrated pest management protocols requiring ecological impact assessment documentation.
Agricultural Crops retains volume leadership; Research climbs the fastest with premium pricing structures.
Distribution Channel:
Channel segmentation reflects working capital intensity variation, with Direct Sales demanding extended payment terms and Online Retail requiring minimal inventory commitment.
- Direct Sales:Pharmaceutical formulators in Germany's Baden-Württemberg region contract directly with Shaanxi extraction facilities, bypassing layered trader intermediaries. This channel compression demands 18-24 month compliance audit cycles but secures captive offtake.
- Online Retail:Agricultural cooperatives in China's inland provinces access spot-market pricing through digital procurement platforms, minimizing working capital lockup.
- Agricultural Cooperatives:Collective purchasing structures in Henan Province aggregate smallholder demand for standardized seed specifications.
- Others:Trader-mediated spot markets serving price-sensitive buyers without certification requirements.
Direct Sales commands margin premiums; Online Retail expands most quickly with reduced capital barriers.
End User:
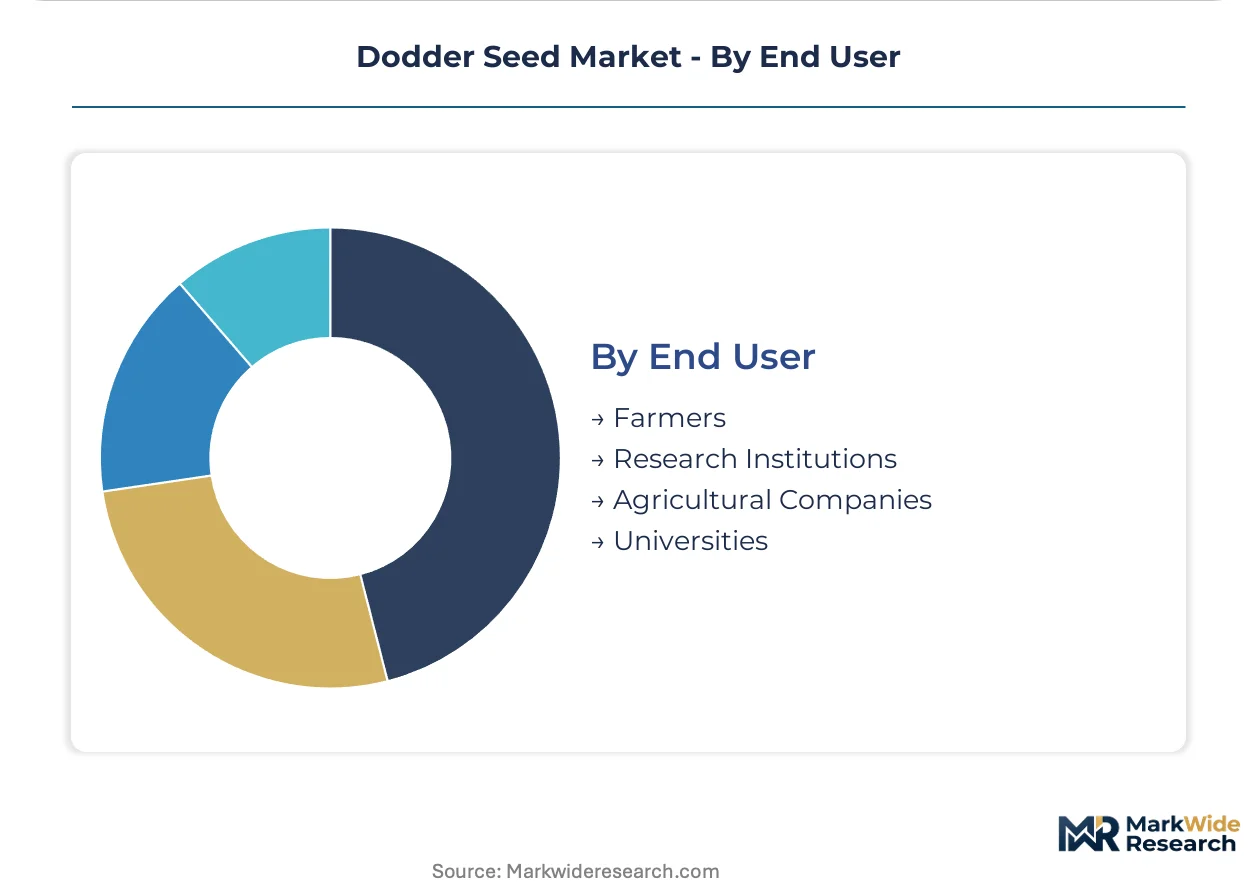
End user segmentation separates specification sophistication, with Research Institutions demanding chromatographic documentation versus Farmers prioritizing field-proven efficacy.
- Farmers:China's Loess Plateau cultivation belt generates concentrated demand through direct processor contracts. Yan'an and Yulin growing clusters supply traceable provenance for export-grade extraction, with hand-harvesting labor costs compressing margins for non-integrated suppliers.
- Research Institutions:Mechanistic studies on neuroprotective flavonoid derivatives require validated analytical methods. UV spectrophotometry and HPLC expertise scarcity across China's inland processing zones creates supply bottlenecks for compliant extractors.
- Agricultural Companies:Integrated pest management program operators seeking bio-control formulation inputs.
- Universities:Academic procurement for pharmacognostic identification studies under divergent NMPA and EMA standards.
Farmers represent the largest volume base; Research Institutions drive steepest expansion trajectory with premium specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Lanzhou-Xinjiang railway and associated cold-chain logistics corridors underpin Shaanxi Province's emergence as the dominant export hub for pharmaceutical-grade dodder seed extracts.
China
Shaanxi and Henan provinces generate concentrated pharmaceutical demand through GMP-certified extraction facilities in Yan'an and Yulin. NMPA Pharmacopoeia standards enforce pharmacognostic identification that restricts import competition. The Loess Plateau cultivation belt supplies traceable provenance for export-grade Brown Dodder through direct processor-farmer contracts.
Germany
Baden-Württemberg and Bavaria host expanding hepatic wellness R&D pipelines with limited domestic extraction capacity. EMA THR registration requirements filter uncertified competitors from renal tonification formulations. Formulators in Stuttgart and Munich increasingly source standardized extracts through direct procurement from Shaanxi facilities.
Switzerland
Swissmedic oversight tightens botanical identity verification for traditional herbal medicinal products. Basel-based pharmaceutical formulators specify supercritical CO2 extraction with ethanol co-solvent modification in procurement tenders. The country's precision analytical instrumentation sector supports HPLC fingerprinting requirements for neuroprotective research validation.
India
CDSCO regulatory alignment with pharmacognostic standards creates pathway for export-oriented extraction investment. The PLI scheme for active pharmaceutical ingredients offers tariff-advantaged manufacturing for European market targeting. Maharashtra and Gujarat processing zones develop backward integration into cultivation networks for captive raw material security.
Japan
PMDA oversight of kampo medicine formulations sustains demand for standardized Cuscuta extracts. Tokyo and Osaka-based manufacturers replicate China's direct contracting model through equity stakes in Henan cultivation cooperatives. METI industrial policy supports analytical method validation infrastructure for flavonoid quantification compliance.
Dodder Seed Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in fragmented supply chains. The vendor base separates into GMP-certified extractors with captive cultivation, agricultural commodity traders without certification, and research-oriented analytical service providers. Strategic archetypes include vertically integrated processors, spot-market intermediaries, and contract research organizations. Competitive moves concentrate on backward integration into farmer networks and dual-certification investments for NMPA and EMA compliance.
Among Shaanxi-based integrated processors, Novoherb Technologies and Yan'an Pharmaceuticals Co., Ltd. exemplify the vertical integration archetype through captive supply from Loess Plateau growing belts. Jiaherb, Inc. occupies a position within the R&D-intensive tier, representing specialists in flavonoid fingerprinting for pharmaceutical client validation. These three entities anchor distinct competitive vectors: upstream cultivation control, analytical differentiation, and regional supply chain dominance.
| Leading Market Players |
|---|
| Novoherb Technologies |
| Jiaherb, Inc. |
| Yan'an Pharmaceuticals Co., Ltd. |
| Parchem Fine & Specialty Chemicals |
| Linden Botanicals |
| Nutra Green Biotechnology Co., Ltd. |
| Evergreen Biotech Inc. |
| Xi'an Realin Biotechnology Co., Ltd. |
| Hangzhou Botanical Technology Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Shaanxi Province's GMP-certified extraction cluster concentrates upstream pharmaceutical-grade supply, anchoring margin pools downstream with German formulators in Baden-Württemberg and Swiss buyers in Basel. Hand-harvesting labor costs across the Loess Plateau cultivation belt compress tier-one margins while spot-market Yellow Dodder traders absorb residual price volatility.
Pricing Analysis
EMA's THR registration requirements dictate the pricing tier structure for Brown Dodder extracts, separating pharmaceutical-grade batches with chromatographic fingerprint documentation from commodity agricultural grades lacking certification. Three-tier pricing structure across premium, standard, and economy levels reflects flavonoid concentration thresholds, GMP compliance status, and provenance traceability depth. Cost compression in the standard tier is intensifying because synthetic flavonoid substitutes threaten botanical sourcing for renal tonification formulations. Agricultural cooperatives in Henan Province exhibit highest price sensitivity, while Swiss and German pharmaceutical formulators tolerate premium positioning for validated neuroprotective research inputs.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk calculus for extractors serving EMA-registered product channels. Raw material sourcing draws from Shaanxi and Henan cultivation belts, with captive processor-farmer contracts replacing layered trader intermediaries. Critical input dependencies include hand-harvested Cuscuta seeds, analytical-grade solvents for HPLC validation, and supercritical CO2 extraction equipment with ethanol co-solvent modification capability. Distribution runs through direct sales contracts for pharmaceutical-grade output and digital procurement platforms for agricultural commodity spot purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement consolidation among German pharmaceutical formulators is shifting buyer power toward direct contracting with Shaanxi extraction facilities, compressing margins for non-integrated intermediaries.
For Market Incumbents: Insulate captive supply positions through backward integration into Loess Plateau farmer networks and dual NMPA-EU EMA certification investments. Synthetic flavonoid substitution threats from East Asian chemical manufacturers demand defensive R&D spending on botanical identity verification protocols. Channel control through direct sales contracts with Stuttgart and Munich formulators protects margin pools against spot-market price erosion. For New Entrants and Emerging Players: India's underpenetrated extraction infrastructure offers white-space opportunity through PLI scheme alignment for European market targeting. Maharashtra and Gujarat processing zones lack backward-integrated cultivation networks, creating entry points for contract manufacturing partnerships with Shaanxi-based GMP extractors. Go-to-market positioning should emphasize analytical method validation services for university research procurement channels in Germany and Switzerland. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated processors with captive cultivation and in-house HPLC fingerprinting capabilities. Long-term viability rests on regulatory moat durability across NMPA Pharmacopoeia and EMA THR compliance thresholds. Watch for EMA monograph updates on botanical identity verification as inflection indicators for consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation Networks | Captive supply from Loess Plateau growing belts secures traceable provenance for EMA-registered exports. |
| Dual Certification Investment | Simultaneous NMPA GMP and EU EMA THR compliance opens pharmaceutical-grade procurement channels in Germany. |
| HPLC Fingerprinting Capability Buildout | In-house analytical validation reduces pharmaceutical client audit cycles and supports premium pricing tolerance. |
| Direct Sales Channel Establishment | Bypassing trader intermediaries captures margin pools from Baden-Württemberg formulator consolidation. |
| Synthetic Flavonoid Substitution Defense | R&D investment in botanical identity verification protects Brown Dodder positioning against chemical alternatives. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with GMP-certified extraction facility managers, pharmaceutical procurement leads in Germany and Switzerland, agricultural cooperative directors in Henan Province, and university research procurement officers. Secondary validation drew from NMPA Pharmacopoeia monographs, EMA THR registration databases, Chinese customs trade data on Cuscuta seed exports, and SEC filings of publicly traded botanical extract companies. Bottom-up volume estimates from cultivation belt surveys were triangulated against top-down pharmaceutical demand projections.
Calibration against historical flavonoid standardization adoption curves and regulatory approval timelines anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product grade tier, application channel, end-user sophistication level, and regional regulatory cluster. CAGRs were derived from growth rate convergence analysis applied to procurement volume trends and extraction capacity expansion plans. Industry-specific forecast inputs incorporated EMA monograph revision schedules and PLI scheme uptake rates in Maharashtra processing zones.
Practitioners should monitor EMA botanical identity verification protocol updates and synthetic flavonoid production cost curves for early signals of forecast revision triggers. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Garden Seeds Market
Seeds
Asparagus Seeds Market
Seeds
South America Vegetable Seed Market
Seeds
Hemp Seed Oil Market
Seeds
Europe Seed Market
Seeds
Cherry Tomato Seeds Market
Seeds
Organic Chia Seeds Market
Seeds
China Rice Seed Market
Seeds
Drought Tolerant Seeds Market
Seeds
Guar Market
Seeds
South America Forage Seed Market
Seeds
Asia Pacific Tomato Seed Oil Market
Seeds
Vietnam Seed Market
Seeds
United States Garden Seeds Market
Seeds
Europe Sesame Seed Market
Seeds
Thailand Vegetable Seed Market