
 Cotton Seed Treatment Market | 2026-2036
Cotton Seed Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Cotton Seed Treatment Market Analysis
Modular treatment packages combining fungicides with bio-stimulants is broadening buyer choice across commercial farming operations. Bayer Crop Science anchors its position through captive supply of proprietary active ingredients. Syngenta AG differentiates via precision coating technologies that reduce chemical load per seed. BASF SE competes through integrated seed-health platforms spanning diagnosis to treatment.
Cotton seed treatment encompasses chemical and biological applications applied to Gossypium seeds prior to planting to suppress soil-borne pathogens, early-season insects, and abiotic stress, typically involving active ingredient loadings of 0.5–5 grams per kilogram of seed. The primary commercial purpose centers on securing stand establishment and reducing replant risk in intensive monoculture systems. Fungicide-based treatments still occupy the largest value share, though bio-stimulant segments are recording the fastest expansion as residue-conscious buyers shift from synthetic chemistry. Film coating dominates treatment method value pools due to superior active retention and planter compatibility, while seed pelleting retains niche strength in precision-drilled organic operations.
EPA registration requirements under FIFRA govern active ingredient approval and label claims in the United States, while REACH compliance in Europe constrains which chemistries manufacturers can import and formulate. India's Central Insecticides Board and Registration Committee mandates sequential efficacy trials before treated seeds enter interstate commerce. Stakeholders must monitor evolving residue thresholds in import-dependent markets and calibrate R&D portfolios toward biologically derived alternatives ahead of regulatory phase-outs.
Market Dynamics
Film coating technology is compressing treatment costs while tightening residue compliance, forcing formulators to consolidate around precision application equipment and biologically derived chemistries that satisfy multiple regulatory jurisdictions simultaneously.
Growth Catalysts
- REACH phase-outs of neonicotinoid seed treatments:European growers are accelerating adoption of microbial inoculants and bio-fungicide combinations as ECHA restrictions eliminate conventional chemistry options from 2026 labels.
- Commercial farming consolidation in Gujarat:Large-scale cotton operations in India's western belt are purchasing treated seed in bulk volumes, creating procurement pull for integrated seed-health service packages bundling diagnostics with application.
- Film coating equipment penetration:Brazilian treatment facilities are retrofitting lines with precision coaters that reduce active ingredient waste by half compared to conventional soaking drums.
Market Restraints
- Active ingredient supply concentration:Three Chinese manufacturers control over 70 percent of technical-grade fungicide supplies, exposing formulators to input volatility and trade policy disruptions.
- Registration timeline friction:India's Central Insecticides Board mandates sequential field trials across three agro-climatic zones, stretching product launch timelines to 4-6 years for novel biological actives.
- Biological efficacy variability:Microbial seed treatments demonstrate inconsistent performance across soil pH gradients above 7.5, limiting reliable adoption in alkaline cotton belts of Pakistan and Egypt.
Strategic Opportunities
- Underpenetrated organic cotton in Turkey's Aegean region:Bio-stimulant formulations certified for organic use command 40-60 percent price premiums over conventional treatments, with local cooperatives seeking dedicated supply partnerships.
- Integrated digital agronomy platforms:Treatment providers bundling seed coating with soil sensor networks and predictive disease modeling are capturing multi-year service contracts from precision agriculture adopters in Australia's Murray-Darling basin.
- EU Green Deal bio-input incentives:Member state subsidy programs for low-carbon farming inputs are defraying 30-50 percent of biological treatment costs for cotton growers in Greece and Spain.
Industry Challenges
- Formulation chemist scarcity:The specialized expertise required to stabilize living microbial cultures in seed coating matrices commands salary premiums exceeding 50 percent above standard agrochemical formulation roles.
- Cross-border seed shipment compliance:Treated seed lots face divergent phytosanitary documentation requirements between export origin and import destination, creating customs delays and lot rejection risks.
- Planter equipment calibration complexity:Film-coated seeds demand adjusted vacuum and disc settings that vary by equipment manufacturer, requiring technical support investments that strain distributor margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cotton Seed Treatment Market |
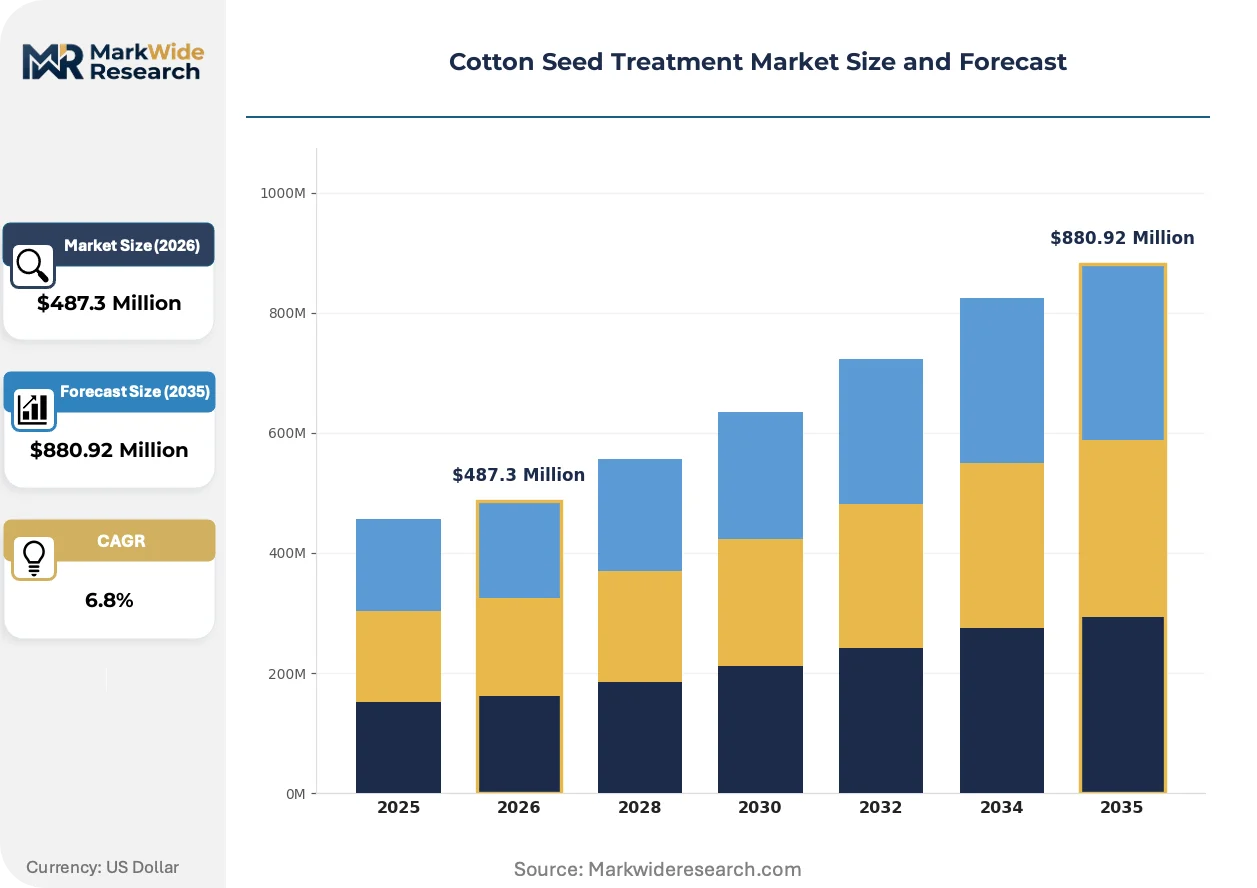
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fungicides, Insecticides, Bio-stimulants, Herbicides Treatment Method: Coating, Soaking, Seed Pelleting, Film Coating End Use Industry: Agriculture, Commercial Farming, Organic Farming, Research Institutions Packaging Type: Bags, Containers, Sachets, Drums |
| Companies Covered | Syngenta AG, BASF SE, Bayer Crop Science AG, Corteva Agriscience, UPL Ltd., FMC Corporation, Nufarm Ltd., Adama Agricultural Solutions, Valent USA LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cotton Seed Treatment Market Emerging Trajectories
Active ingredient innovation is pivoting toward biological modes of action as residue thresholds tighten across import-dependent markets, while application technology and procurement models compress treatment economics toward integrated service contracts.
Polymer-based film coatings incorporating micro-encapsulated bio-stimulants are expanding into high-value seed segments where stand establishment risk justifies premium input costs. Large-scale cotton operations in Brazil's Mato Grosso region are adopting these systems at rates exceeding 15 percent annually. The technology is expanding into mid-tier commercial farms as equipment leasing models reduce capital barriers.
EPA registration requirements under FIFRA are tightening data requirements for systemic insecticides applied to food and feed crops, including cottonseed oil derivatives. Manufacturers must now submit extended pollinator risk assessments and soil metabolite studies, extending development timelines by 18-24 months. Biological treatment developers are redirecting R&D portfolios toward exempted microbial and biochemical categories that bypass these review queues.
Buyer consolidation among ginning cooperatives and integrated textile supply chains is compressing seed treatment procurement into multi-year framework agreements with volume guarantees. These arrangements displace spot-market purchases and independent distributor relationships across Turkey's Aegean organic cotton belt. The shift is most visible where ginners operate captive seed conditioning facilities and internalize treatment quality control.
Cotton Seed Treatment Market Segmentation
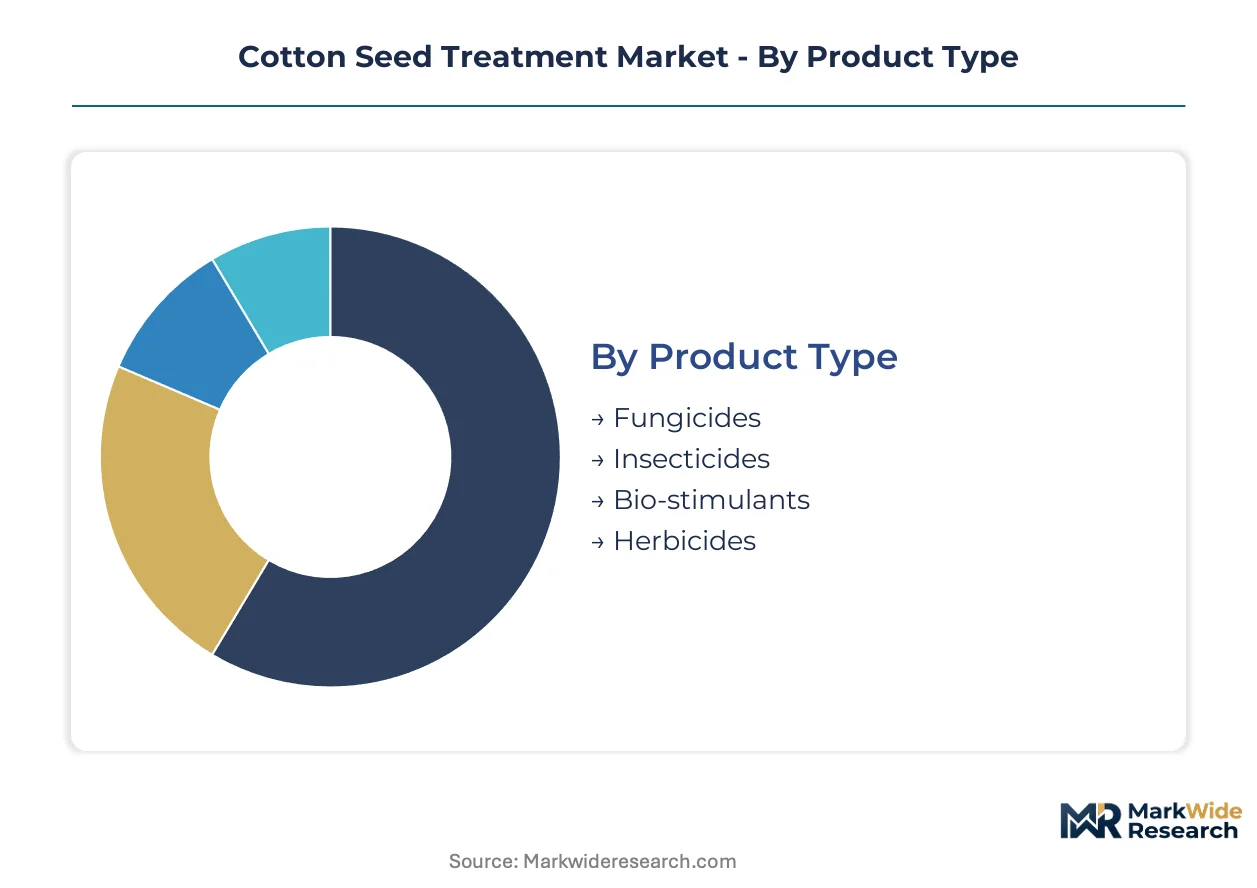
Cotton seed treatment markets fragment across four distinct dimensions, each governed by divergent regulatory pathways and procurement economics. Product chemistry determines FIFRA or REACH compliance burdens, while treatment method shapes capital intensity and residue profiles. End-use concentration and packaging logistics further stratify competitive positioning across commercial channels.
Product Type:
FIFRA registrations govern synthetic actives in the United States, while REACH phase-outs are accelerating biological alternatives in Europe. India's Central Insecticides Board imposes sequential field trials that stretch novel biological approvals across multiple growing seasons.
- Fungicides:Chemical formulations targeting Pythium and Rhizoctonia species dominate commercial cotton belts, with thiram and metalaxyl-based systems anchoring procurement volumes in Brazil's Mato Grosso region. EPA registration renewals are tightening residue data requirements, compressing reformulation timelines for legacy chemistries.
- Insecticides:Neonicotinoid-based treatments face ECHA restrictions eliminating conventional options from European labels, forcing pivot toward anthranilic diamide alternatives. Gujarat's commercial farming consolidation is sustaining demand in India despite tightening residue limits on export-bound lint.
- Bio-stimulants:Microbial inoculants and seaweed-derived formulations command organic certification premiums in Turkey's Aegean region.
- Herbicides:Safener-treated seeds for resistance management occupy niche positions in precision-drilled systems.
Leading the category by volume: Fungicides. Expanding most quickly: Bio-stimulants.
Treatment Method:
Capital equipment requirements stratify this category, with precision coating lines demanding retrofit investments that exclude smaller conditioning facilities.
- Film Coating:Polymer-based application systems achieve active ingredient retention above 95 percent while reducing chemical load per seed. Brazilian treatment facilities are retrofitting lines at rates exceeding 15 percent annually as residue compliance tightens.
- Coating:Conventional binder-based systems retain cost advantages in mid-tier commercial farms where equipment leasing models remain underdeveloped.
- Soaking:Immersion drums are being displaced across Brazilian cotton belts due to active waste and residue variability.
- Seed Pelleting:Encapsulation technology retains niche strength in organic operations requiring precision drilling compatibility.
Fastest technology shift: Film Coating displacing Soaking. Highest margin retention: Seed Pelleting in certified organic channels.
End Use Industry:
Procurement scale and certification requirements fragment demand across farming typologies, with integrated textile supply chains internalizing quality control.
- Commercial Farming:Large-scale operations in Gujarat and Australia's Murray-Darling basin are consolidating seed treatment procurement into multi-year framework agreements with volume guarantees, displacing spot-market purchases.
- Agriculture:Generalist cotton growers represent the volume base for standard fungicide-insecticide combinations across conventional production belts.
- Organic Farming:Bio-stimulant formulations certified for organic use command 40-60 percent price premiums in Turkey's Aegean region, with local cooperatives seeking dedicated supply partnerships.
- Research Institutions:Field trial demand for novel biological actives supports small-batch formulation services with specialized stabilization protocols.
Procurement concentration highest: Commercial Farming. Fastest contract model evolution: Organic Farming through ginning cooperative integration.
Packaging Type:
Logistics economics and lot traceability requirements shape container specifications across export-dependent supply chains.
- Bags:Woven polypropylene units dominate smallholder procurement in India, where distributor networks handle last-mile delivery.
- Containers:Rigid intermediate bulk containers support bulk treated seed shipments from Brazilian ginning cooperatives to commercial farming operations.
- Sachets:Unit-dose microbial formulations serve research institutions and precision organic trials requiring batch-level traceability.
- Drums:Steel and fiber drums retain position in liquid formulation logistics for soaking equipment retrofits.
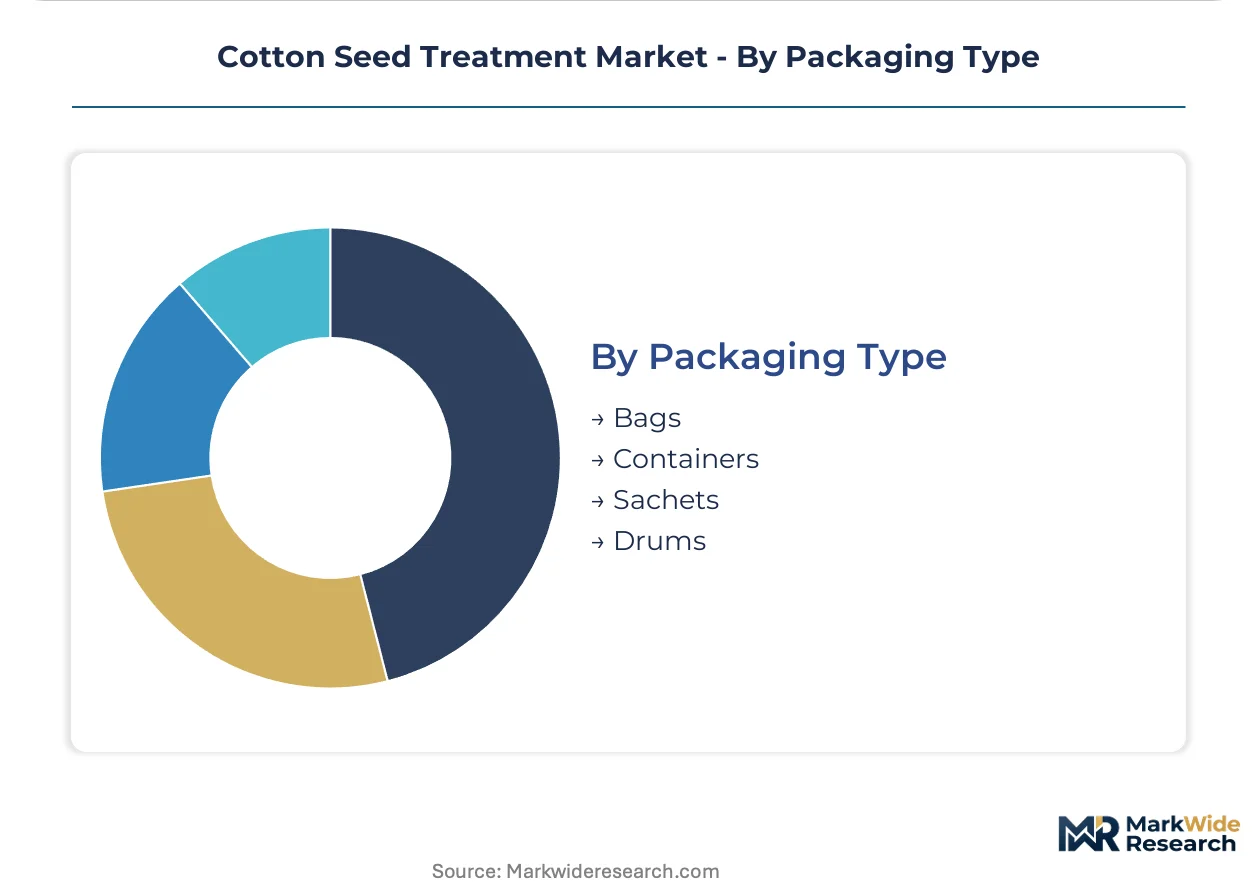
Volume leader: Bags in smallholder channels. Fastest format shift: Containers consolidating bulk commercial procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gujarat's Special Economic Zones for agro-processing concentrate treated seed demand through tax-advantaged ginning and conditioning facilities serving export-oriented textile clusters.
United States
EPA registration requirements under FIFRA govern active ingredient approvals for cottonseed oil derivatives, with extended pollinator risk assessments stretching development timelines. The Mississippi Delta cotton belt sustains demand for fungicide-insecticide combinations, while Texas High Plains operations adopt precision coating systems to reduce chemical load per seed.
Brazil
Mato Grosso's large-scale commercial farms drive film coating equipment retrofits exceeding fifteen percent annually as residue compliance tightens. ANVISA aligns with international residue standards, enabling treated seed exports to European textile markets. Ginning cooperatives in the Cerrado region consolidate procurement into multi-year framework agreements with volume guarantees.
India
Gujarat's commercial farming consolidation creates procurement pull for integrated seed-health service packages bundling diagnostics with application. The Central Insecticides Board mandates sequential field trials across three agro-climatic zones, stretching biological product launches to four-to-six years. Maharashtra's Vidarbha region maintains secondary demand for conventional soaking methods among mid-tier operations.
Turkey
The Aegean region's organic cotton cooperatives seek dedicated supply partnerships for bio-stimulant formulations commanding forty-to-sixty percent price premiums. EU Green Deal bio-input incentives defray thirty-to-fifty percent of biological treatment costs for growers in Greece-bordering provinces. Izmir-based ginning operations internalize treatment quality control through captive seed conditioning facilities.
Australia
The Murray-Darling basin's precision agriculture adopters sign multi-year service contracts bundling seed coating with soil sensor networks and predictive disease modeling. The country's national agricultural regulator maintains residue thresholds aligned with export market requirements. Queensland's Darling Downs cotton cluster represents the fastest-adopting region for integrated digital agronomy platforms.
Cotton Seed Treatment Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across a moderately consolidated vendor base where three strategic archetypes predominate. Integrated agrochemical-seed majors leverage captive active ingredient supply and proprietary coating technologies. Mid-tier formulators compete through regional registration expertise and distributor relationships. Biological treatment developers occupy emerging positions as residue thresholds tighten. Dominant competitive moves include precision application equipment partnerships and backward integration into microbial culture production.
Among diversified agrochemical conglomerates, Syngenta AG and BASF SE exemplify the integrated platform archetype, while Bayer Crop Science AG anchors the seed-health-to-textile value chain control position. These three companies represent the primary competitive anchors around which mid-tier formulators and biological specialists position differentiated offerings.
| Leading Market Players |
|---|
| Syngenta AG |
| BASF SE |
| Bayer Crop Science AG |
| Corteva Agriscience |
| UPL Ltd. |
| FMC Corporation |
| Nufarm Ltd. |
| Adama Agricultural Solutions |
| Valent USA LLC |
| Others |
Supply Flow & Price Mechanics
Formulation chemist scarcity in Western Europe and North America widens pricing-tier spreads, as salary premiums exceeding fifty percent above standard agrochemical roles force manufacturers to pass specialized labor costs through premium product lines while economy-tier offerings draw from lower-cost technical talent pools in India and China.
Pricing Analysis
Lead-time-driven pricing separates urgent procurement from planned orders, with short-lead-time film coating services commanding premiums of twenty to thirty percent above standard delivery windows. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with organic-certified bio-stimulant formulations at the top and conventional soaking treatments at the base. Cost compression in economy tiers is intensifying because Chinese technical-grade fungicide suppliers are consolidating pricing power. Commercial farming operations in Gujarat demonstrate lowest price sensitivity due to volume-scale procurement, while mid-tier Brazilian farms exhibit highest sensitivity to per-seed treatment costs.
Supply Chain Analysis
Warehouse-distribution layers in the cotton seed treatment market operate through hub-and-spoke patterns anchored in Mato Grosso, Gujarat, and Izmir, with regional distribution centers feeding ginning cooperatives and commercial farming clusters. Supply concentration rests on China, India, and Germany for technical-grade actives, precision coating equipment, and polymer formulation inputs respectively. Raw material dependencies center on thiram and metalaxyl fungicides, microbial culture media, and film-forming polymers. Single-source vulnerability from three Chinese manufacturers controlling over seventy percent of technical-grade fungicide supplies exposes formulators to trade policy disruptions. Distribution runs through ginning cooperative networks in Brazil and India, with direct-to-farm container shipments displacing distributor channels in Australia's Murray-Darling basin.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cotton seed treatment market is becoming a vertical-integration race, with players pursuing backward integration into microbial culture production to secure supply of proprietary biological actives ahead of REACH phase-outs.
For Market Incumbents: Anchor market position through captive supply of film coating equipment and proprietary active ingredient pipelines, while investing in sequential field trial capabilities across India's three agro-climatic zones to compress biological product launch timelines. Defensive consolidation should target mid-tier formulators with established distributor relationships in Brazil's Cerrado region, where ginning cooperatives are consolidating procurement into multi-year framework agreements. Threat substitution from microbial inoculants with inconsistent alkaline soil performance creates window for synthetic-fungicide platforms in Pakistan and Egypt. For New Entrants and Emerging Players: Organic cotton cooperatives in Turkey's Aegean region represent the most penetrable buyer archetype, as dedicated supply partnerships for certified bio-stimulant formulations command forty-to-sixty percent price premiums with limited incumbent competition. White-space targets include precision-drilled organic operations requiring seed pelleting compatibility, and research institutions seeking small-batch formulation services with specialized microbial stabilization protocols. Go-to-market angle should bundle soil sensor diagnostics with treatment application to mirror integrated digital agronomy platforms capturing multi-year service contracts in Australia's Murray-Darling basin. For Investors and Strategic Acquirers: Re-rating potential sits with biological treatment developers given EU Green Deal bio-input incentives defraying thirty-to-fifty percent of treatment costs across Greece-bordering Turkish provinces. Long-term viability over the five-to-ten year window favors specialists with in-house microbial culture production and precision coating equipment partnerships, as residue thresholds tighten across import-dependent markets. Acquisition target archetype: mid-tier formulators with regional registration expertise and established distributor relationships in underpenetrated organic cotton belts. Signal to watch: ANVISA alignment with international residue standards enabling treated seed export qualification to European textile markets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Microbial Culture Production | Secures proprietary bio-stimulant supply ahead of ECHA neonicotinoid restrictions eliminating conventional chemistry options. |
| Precision Coating Equipment Partnership | Brazilian treatment facilities retrofitting lines at rates exceeding fifteen percent annually as residue compliance tightens. |
| Sequential Field Trial Capability Investment | Compresses biological product launch timelines from four-to-six years across India's Central Insecticides Board mandated zones. |
| Integrated Digital Agronomy Platform Launch | Murray-Darling basin precision agriculture adopters sign multi-year service contracts bundling seed coating with soil sensor networks. |
| Organic Certification Premium Positioning | Turkey's Aegean region bio-stimulant formulations command forty-to-sixty percent price premiums over conventional treatments. |
Methodological Framework
Document review covered EPA FIFRA registration filings, ECHA restriction dossiers, India's Central Insecticides Board approval records, and ANVISA residue standard alignments, complemented by interviews with seed treatment formulators, ginning cooperative procurement managers, precision agriculture platform engineers, and microbial R&D directors. Secondary validation drew from customs trade data, agrochemical industry association reports, and SEC filings of diversified agrochemical conglomerates. Bottom-up triangulation across product chemistry, treatment method, end-use industry, and packaging type segments was cross-referenced with top-down macroeconomic and regulatory scenario analysis.
Historical volume and value trajectories were cross-referenced against panel input from industry stakeholders to derive expansion rates across the analysis window. Segmentation dimensions modeled included product chemistry tier, treatment method capital intensity, farming typology procurement scale, and logistics format specifications. CAGRs were derived through regression analysis of historical adoption curves adjusted for regulatory phase-in schedules and technology substitution elasticities. Industry-specific forecast inputs incorporated film coating equipment retrofit rates, biological efficacy variability across soil pH gradients, and ginning cooperative consolidation patterns.
Revisions become necessary when ECHA accelerates neonicotinoid restriction timelines, when India's Central Insecticides Board modifies sequential trial requirements, or when Chinese technical-grade active ingredient supply concentration triggers trade policy disruptions. Forecasts reflect documented assumptions regarding regulatory stability, microbial culture stabilization protocol advances, and precision agriculture adoption curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Field Crop Seeds Market
Seeds
Europe Amaranth Market
Seeds
India Maize Seed Market
Seeds
Cucumber Seeds Market
Seeds
Brazil Forage Seed Market
Seeds
Europe Grain Seed Market
Seeds
Mexico Vegetable Seed Market
Seeds
Southeast Asia Vegetable Seed Market
Seeds
South America Vegetable Seed Market
Seeds
United States Vegetable Seed Market
Seeds
Vietnam Seed Market
Seeds
Morocco Seed Market
Seeds
Global Wheat Seed Market
Seeds
Asia-Pacific Chia Seed Market
Seeds
Sri Lanka Seed Market
Seeds
Garlic Chive Seeds Market