
 China Seed Market | 2026-2036
China Seed Market Size, Share, and Industry Trends Forecast 2026-2036
China Seed Market Outlook
Synthetic seed coating polymers are repositioning cost structures across the China seed industry as biodegradable alternatives displace conventional chemical treatments. Syngenta Group leverages its global germplasm library to dominate hybrid corn development in Northeast China. Yuan Longping High-Tech Agriculture Co Ltd anchors rice seed innovation through sustained investment in super-hybrid varieties. Beidahuang Kenfeng Seed Co Ltd controls distribution networks across Heilongjiang's mechanized farming belt.
China seed encompasses propagative material bred for agricultural and horticultural reproduction, typically graded by germination rate, genetic purity, and moisture content below thirteen percent. The primary commercial purpose centers on securing crop yield consistency and trait uniformity for food security and export commodity production. Hybrid seeds command the dominant margin pool as farmers pay technology fees for verified yield advantages in corn and rice. Field crops absorb the largest volume share, while vegetable seeds generate premium pricing per kilogram through specialized greenhouse supply chains. Conventional seeds retain substantial acreage among smallholder operations with limited capital for biotechnology inputs.
China's Ministry of Agriculture and Rural Affairs enforces seed quality certification through GB standards and variety approval protocols that filter market access for domestic and imported genetic material. The National Intellectual Property Administration strengthened plant breeders' rights enforcement, redirecting R&D investment toward proprietary inbred lines. Seed producers must monitor how MIIT's biotech crop approval timelines and provincial subsidy allocations for certified seed reshape planting decisions each season.
Market Dynamics
Synthetic seed coating polymers are compressing chemical input costs while China's revised Seed Law redirects R&D investment toward proprietary germplasm development. The tension between biodegradable treatment adoption and legacy chemical inventory clearance defines current capital allocation.
Growth Catalysts
- GB Standards Certification:China's Ministry of Agriculture and Rural Affairs enforces mandatory seed quality protocols that filter substandard genetic material from commercial channels. Large-scale wheat operations in the North China Plain now demand certified hybrid varieties exclusively.
- Biodegradable Polymer Coatings:Synthetic seed treatments derived from plant-based polymers reduce environmental runoff liability. Commercial vegetable growers in Shandong province are expanding orders for coated tomato and pepper seeds.
- Heilongjiang Mechanization:Beidahuang Kenfeng Seed Co Ltd controls distribution networks across China's most mechanized farming belt. Corn seed volumes concentrate where tractor density exceeds 15 units per 100 hectares.
Market Restraints
- Petrochemical Input Volatility:Conventional seed coating chemicals depend on ethylene derivatives whose pricing fluctuates with crude oil benchmarks. Margin compression hits smaller coating facilities without long-term supply contracts.
- Germplasm Import Dependency:Hybrid corn development in Northeast China relies on access to international genetic libraries. Trade friction restricts germplasm exchange with North American breeding programs.
- Smallholder Capital Constraints:Conventional seeds retain substantial acreage among operations with limited access to biotechnology financing. Technology fee structures exclude farmers cultivating below 5 hectares.
Strategic Opportunities
- Greenhouse Vegetable Supply Chains:Premium pricing per kilogram for specialized pepper and tomato seeds exceeds field crop margins by multiples. Protected agriculture expansion in Hebei province creates concentrated demand nodes.
- Dual Carbon Policy Alignment:China's national emissions targets incentivize low-carbon seed production methods. Biodegradable coating adoption qualifies for provincial sustainability subsidies.
- Gene Editing Convergence:CRISPR applications intersect with traditional hybrid breeding to accelerate trait development. Regulatory clarity from MIIT on edited crop approval timelines would unlock commercial deployment.
Industry Challenges
- Plant Breeders' Rights Enforcement:The National Intellectual Property Administration strengthened legal frameworks but provincial courts vary in case resolution speed. IP disputes over proprietary inbred lines delay licensing negotiations.
- Biotech Crop Approval Timelines:MIIT regulatory review periods for genetically modified seeds extend across multiple growing seasons. Capital remains locked in pre-commercial varieties awaiting field trial clearance.
- Moisture Control Infrastructure:Seed moisture content must remain below thirteen percent through storage and transport. Cold chain gaps in western provinces degrade germination rates before planting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Seed Market |
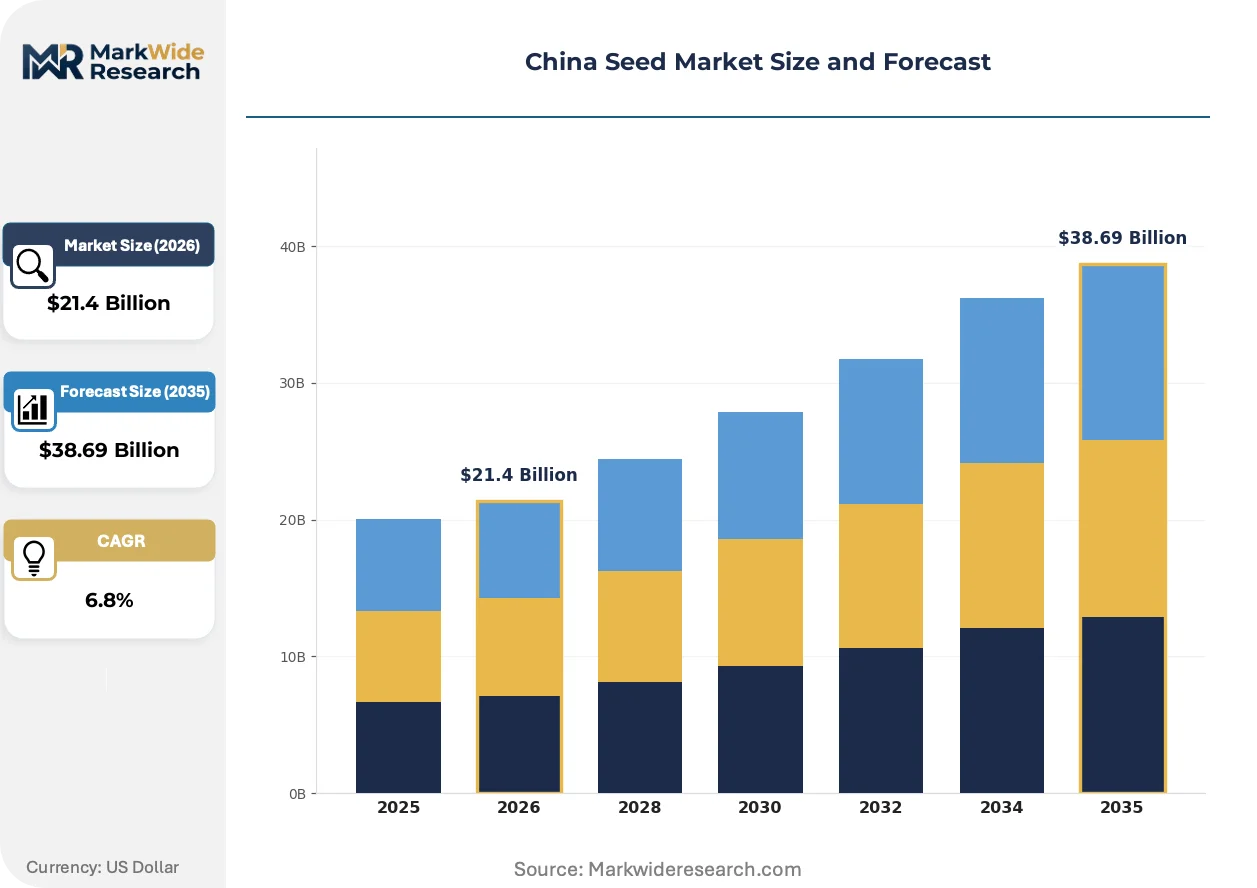
| Market Size in 2026 | $21.4 Billion |
| Market Size in 2035 | $38.69 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vegetable Seeds, Fruit Seeds, Field Crops, Flower Seeds End Use Industry: Agriculture, Horticulture, Forestry, Turf Management Technology: Hybrid Seeds, Genetically Modified Seeds, Conventional Seeds, Organic Seeds Distribution Channel: Retail, Wholesale, E-commerce, Direct Sales |
| Companies Covered | Anhui Tsuen Yin Hi-Tech Seed Industry Co Ltd, Sakata Seeds Corporation, Syngenta Group, Rijk Zwaan Zaadteelt en Zaadhandel BV, Groupe Limagrain, Beidahuang Kenfeng Seed Co Ltd, China National Seed Group Co Ltd, BASF SE, Yuan Longping High-Tech Agriculture Co Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Seed Market Strategic Shifts
Biodegradable materials and digital traceability systems are compressing cost structures while regulatory enforcement tightens around genetic provenance documentation. The market pivots toward verifiable sustainability credentials.
Polymer seed coatings derived from chitosan and lignin are rewriting treatment economics across China's commercial vegetable sector. Shandong greenhouse operators are adopting these materials at accelerating rates to satisfy export market phytosanitary requirements. The technology is compressing chemical residue testing costs while opening European Union market access previously blocked by synthetic pesticide thresholds.
China's revised Seed Law mandates variety approval protocols that trace genetic lineage through multi-generation documentation. The National Intellectual Property Administration coordinates with provincial agriculture departments to verify breeder claims. Hybrid rice developers in Hunan province face the steepest compliance burden as super-hybrid varieties require extensive field trial records.
Certified seed procurement now demands blockchain-verified provenance documentation from large-scale corn operations in Heilongjiang. Provincial subsidy allocations increasingly tie payment release to digital traceability system participation. The behavioral shift is most visible among cooperatives managing 500+ hectare blocks where input cost transparency affects credit access from rural commercial banks.
China Seed Market Segmentation
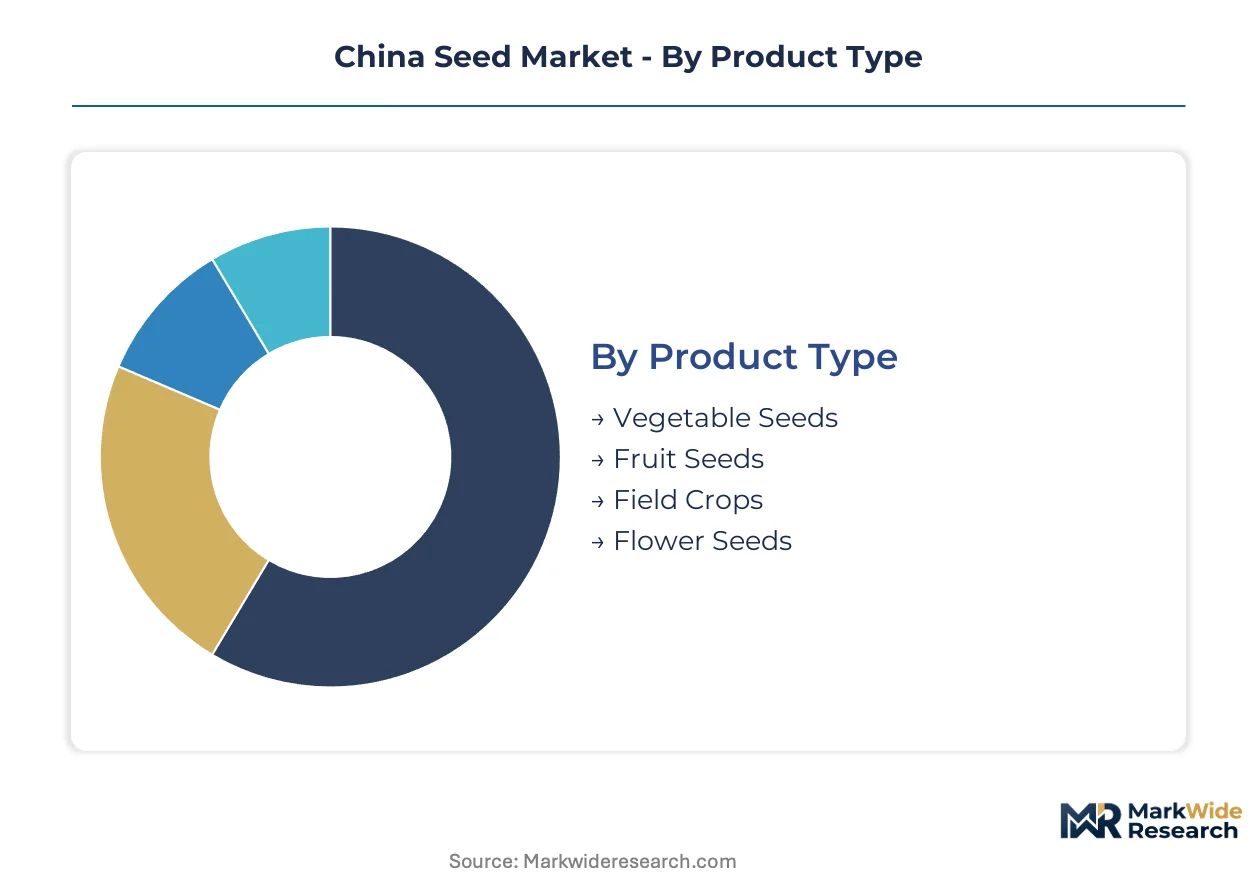
China's seed market segments reveal divergent margin structures between high-volume field crops and premium vegetable varieties. Understanding these splits helps producers allocate breeding investment across germplasm development, coating technologies, and distribution infrastructure.
Product Type:
Field crops dominate planted acreage while vegetable seeds command the steepest per-kilogram premiums through specialized supply chains.
- Field Crops:Wheat, corn, and rice seeds constitute the volume foundation of China's seed market. Demand concentrates in the North China Plain where large-scale operations above 500 hectares require certified hybrid varieties for mechanized planting.
- Vegetable Seeds:Hybrid tomato and pepper varieties generate premium pricing multiples above field crop margins. Shandong and Hebei greenhouse operators are expanding orders for coated seeds that satisfy EU phytosanitary thresholds.
- Fruit Seeds:Watermelon and melon seeds serve protected agriculture clusters in Xinjiang and Hainan with specialized germination requirements.
- Flower Seeds:Ornamental varieties support urban landscaping contracts and export cut-flower operations in Yunnan province.
Mature deployment sits with Field Crops. Newer deployment is concentrated in Vegetable Seeds.
End Use Industry:
Agriculture absorbs the dominant seed volume while horticulture generates the most specialized technical requirements.
- Agriculture:Commercial grain and oilseed production drives hybrid corn and super-hybrid rice demand. Heilongjiang's mechanized farming belt requires seeds compatible with precision planting equipment.
- Horticulture:Greenhouse vegetable and fruit operations in Shandong demand coated seeds with verified low-residue profiles. MIIT's variety approval protocols add compliance layers for protected agriculture inputs.
- Forestry:Reforestation programs in southwestern provinces source certified tree seeds for carbon sequestration projects aligned with dual carbon goals.
- Turf Management:Golf course and sports field maintenance in coastal cities drives demand for drought-tolerant grass varieties.
Volume leadership belongs to Agriculture. Horticulture carries the steepest technology fee structures.
Technology:
Hybrid technology commands the dominant margin pool while conventional seeds retain substantial smallholder acreage.
- Hybrid Seeds:Cross-pollinated varieties in corn and rice deliver verified yield advantages that justify technology fees. Yuan Longping High-Tech Agriculture Co Ltd anchors innovation through sustained super-hybrid development.
- Conventional Seeds:Open-pollinated varieties persist among operations below 5 hectares with limited biotechnology financing. These seeds bypass royalty structures but lack yield consistency guarantees.
- Genetically Modified Seeds:Biotech crop varieties await MIIT regulatory clearance timelines that extend across multiple growing seasons. Capital remains locked in pre-commercial lines pending field trial approval.
- Organic Seeds:Uncoated, non-GMO varieties serve certified organic operations in mountainous provinces with premium export contracts.
Commercial maturity centers on Hybrid Seeds. Regulatory clarity would unlock Genetically Modified Seeds deployment fastest.
Distribution Channel:
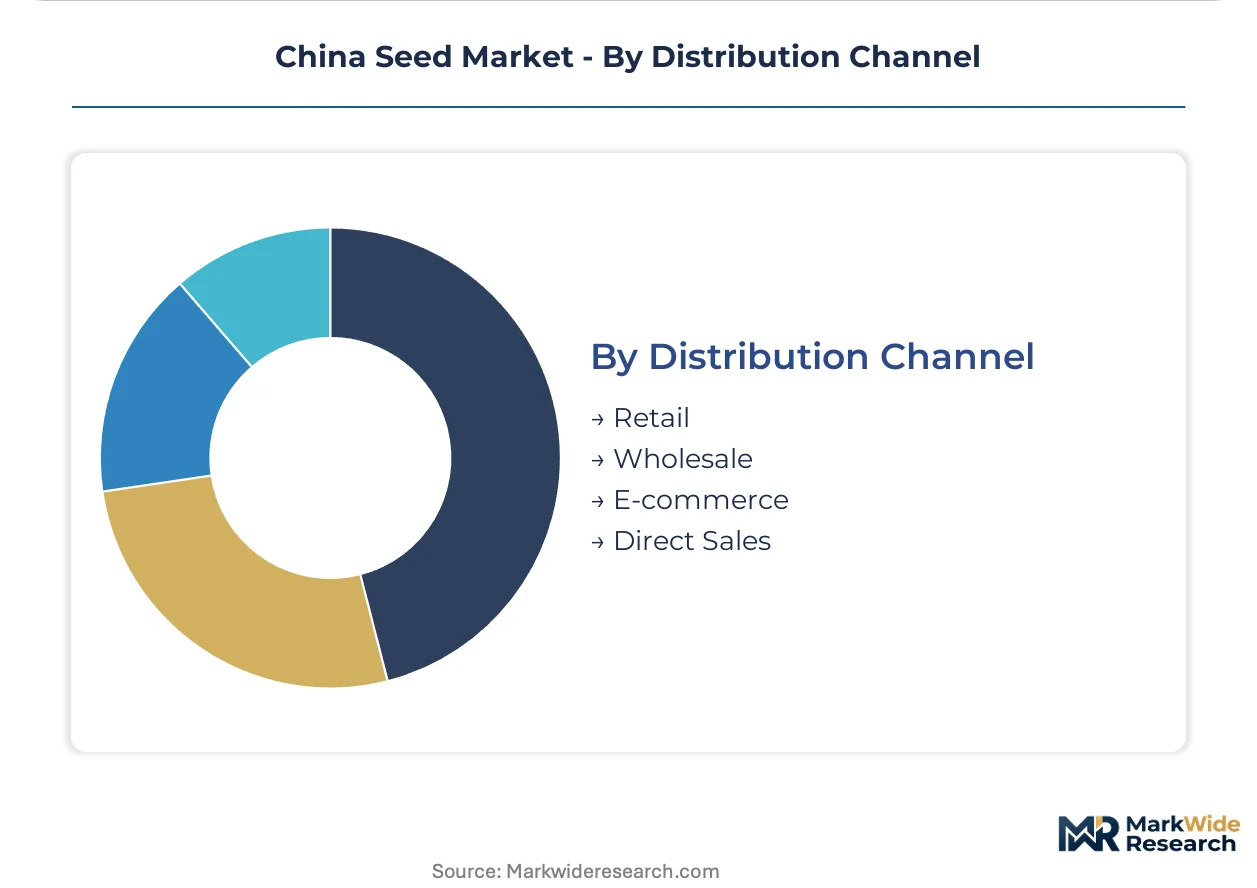
Wholesale networks control volume flows while direct sales capture the most specialized technical relationships.
- Wholesale:Provincial distributors aggregate seed volumes for agricultural supply cooperatives across the North China Plain. Beidahuang Kenfeng Seed Co Ltd leverages these networks across Heilongjiang's mechanized belt.
- Direct Sales:Large-scale operators above 500 hectares procure certified seeds through breeder-direct contracts with blockchain-verified provenance documentation.
- Retail:County-level agrochemical shops serve smallholders with conventional varieties and basic hybrid lines.
- E-commerce:Digital platforms are gaining traction for specialty vegetable seeds among greenhouse operators in Hebei seeking transparent pricing.
Wholesale channels handle established volume. Direct Sales is expanding most quickly among certified seed procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's seed demand concentrates in provincial farming belts where mechanization and scale create distinct procurement patterns. Sub-regional specialization shapes variety approval priorities and distribution infrastructure investments.
Heilongjiang Province
Mechanized corn operations above 500 hectares drive certified hybrid seed procurement across China's northernmost farming belt. MIIT's biotech crop approval timelines particularly affect planting decisions here. Harbin-based distribution networks coordinate seed delivery to tractor-dense zones exceeding 15 units per 100 hectares.
Shandong Province
Greenhouse vegetable growers in Weifang and Qingdao are expanding coated tomato and pepper seed orders for export compliance. GB standards certification filters substandard genetic material from commercial channels. The province's protected agriculture clusters generate premium pricing multiples through EU-aligned phytosanitary protocols.
Hebei Province
Beijing-Tianjin-Hebei integration concentrates demand for certified wheat varieties in the North China Plain. Provincial subsidy allocations tie payment release to digital traceability system participation. Baoding and Shijiazhuang anchor distribution nodes where large-scale operators procure blockchain-verified provenance documentation.
Hunan Province
Super-hybrid rice development absorbs sustained breeding investment from state-backed agricultural institutes. The National Intellectual Property Administration coordinates variety approval protocols requiring multi-generation genetic lineage documentation. Changsha anchors research clusters where field trial records determine commercial release timelines.
Xinjiang Autonomous Region
Cotton seed demand intersects with mechanized picking operations across the Tarim Basin. Cold chain infrastructure gaps in western provinces challenge moisture control below thirteen percent through storage. Ürümqi distribution hubs coordinate seed transport to oasis farming belts with specialized germination requirements.
China Seed Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with state-affiliated entities controlling volume flows and international breeders capturing premium vegetable tiers. The vendor base organizes around three strategic archetypes: germplasm developers with proprietary inbred lines, distribution-integrated provincial operators, and technology licensors with global variety portfolios. Competitive moves center on variety approval acceleration and coating technology licensing rather than capacity expansion.
Within the germplasm development tier, Yuan Longping High-Tech Agriculture Co Ltd exemplifies sustained investment in super-hybrid rice innovation. Syngenta Group occupies a position representing international technology access for hybrid corn development. Beidahuang Kenfeng Seed Co Ltd anchors the distribution-integrated archetype across Heilongjiang's mechanized farming belt.
| Leading Market Players |
|---|
| Anhui Tsuen Yin Hi-Tech Seed Industry Co Ltd |
| Sakata Seeds Corporation |
| Syngenta Group |
| Rijk Zwaan Zaadteelt en Zaadhandel BV |
| Groupe Limagrain |
| Beidahuang Kenfeng Seed Co Ltd |
| China National Seed Group Co Ltd |
| BASF SE |
| Yuan Longping High-Tech Agriculture Co Ltd |
| Others |
Value Chain & Pricing Dynamics
Hybrid breeding specialists concentrated in Hunan province drive labor-cost differentials that widen pricing-tier spreads between super-hybrid rice varieties and conventional open-pollinated lines. GB standards certification and blockchain-verified provenance documentation further stratify procurement economics across China's seed market.
Pricing Analysis
Volume leadership in field crops contrasts with margin concentration in vegetable seeds, where coated tomato and pepper varieties command technology-fee multiples above commodity grain pricing. Price differentiation rests on certification grade under Ministry of Agriculture and Rural Affairs protocols and volume scale among Heilongjiang cooperatives managing 500+ hectare blocks. Cost compression in conventional seed tiers is intensifying because petrochemical input volatility squeezes smaller coating facilities. Smallholder operations below 5 hectares exhibit the highest price sensitivity, while large-scale mechanized farms demonstrate inelastic demand for certified hybrid varieties with verified germination rates.
Supply Chain Analysis
Workforce availability for specialized breeding operations concentrates in Hunan and Hubei provinces, where state-backed agricultural institutes anchor super-hybrid rice development. Raw material dependencies center on ethylene-derived coating chemicals, chitosan and lignin polymer feedstocks, and cold chain refrigeration equipment for moisture control below thirteen percent. Single-source vulnerability runs through germplasm import channels restricted by trade friction with North American breeding programs. Distribution runs through provincial wholesale networks controlled by Beidahuang Kenfeng Seed Co Ltd across Heilongjiang's mechanized belt, with direct sales expanding among blockchain-verified procurement systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's seed market is consolidating as GB standards certification and strengthened plant variety protection force substandard genetic material out of commercial channels, eliminating smaller players lacking R&D scale for proprietary inbred line development.
For Market Incumbents: Acquire proprietary germplasm libraries to secure hybrid corn breeding pipelines against germplasm import dependency risks from trade friction. Expand backward integration into biodegradable polymer coating production to capture margin from Shandong greenhouse operators adopting EU-aligned phytosanitary treatments. Lock in long-term supply contracts for ethylene derivatives to insulate coating operations from petrochemical input volatility. For New Entrants and Emerging Players: Capture white-space in organic seed supply chains serving mountainous provinces with certified export contracts, where technology fee structures exclude conventional hybrid penetration. Target e-commerce distribution for specialty vegetable seeds among Hebei greenhouse operators seeking transparent pricing outside wholesale networks. Lead with digital traceability system participation to unlock provincial subsidy allocations tied to blockchain-verified provenance documentation. For Investors and Strategic Acquirers: Re-rating potential sits with distribution-integrated provincial operators given Heilongjiang mechanization trends and tractor density expansion above 15 units per 100 hectares. Long-term viability favors entities controlling cold chain infrastructure for moisture management through western province storage gaps. Watch MIIT regulatory clarity on gene-edited crop approval timelines as the inflection indicator for capital deployment into CRISPR-convergent breeding platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Biodegradable Coating Production | Captures margin from Shandong greenhouse operators adopting EU phytosanitary protocols. |
| Blockchain-Verified Provenance System Deployment | Unlocks provincial subsidy allocations tied to digital traceability participation in Hebei. |
| Proprietary Germplasm Library Acquisition | Secures hybrid corn pipelines against North American breeding program access restrictions. |
| Cold Chain Infrastructure Expansion | Addresses moisture control gaps degrading germination rates in western province storage. |
| Gene Editing Regulatory Engagement | Positions for CRISPR commercial deployment pending MIIT edited crop approval clarity. |
Study Parameters
Multi-period observation of certified seed procurement volumes, tractor density metrics, and greenhouse expansion rates anchored the trend analysis, supplemented by interviews with plant breeding directors at provincial agricultural institutes, seed coating facility operations managers, procurement leads at Heilongjiang farming cooperatives, and regulatory affairs specialists at MIIT. Secondary validation drew from Ministry of Agriculture and Rural Affairs variety approval databases, GB standards certification registries, National Intellectual Property Administration plant breeders' rights filings, and provincial subsidy allocation records. Bottom-up acreage estimates and top-down market value reconstructions were triangulated against trade flow data.
Input-output matrices mapped seed production volumes through distribution channels to end-use applications across the projection horizon. Segmentation dimensions modeled include product type, technology tier, end-use industry, and distribution channel structure. CAGRs were derived from regression analysis of historical procurement patterns and forward assumptions on mechanization penetration and regulatory enforcement intensity. Forecast inputs incorporated MIIT biotech crop approval timeline scenarios and dual carbon policy subsidy allocation trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to germplasm import policy shifts, cold chain infrastructure buildout pace, and gene editing regulatory clarity. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Europe Cannabis Seeds Market
Seeds
North America Chia Seeds Market
Seeds
Pasture Seeds Market
Seeds
Philippines Hybrid Rice Seed Market
Seeds
Celery Seed Oil Market
Seeds
Helianthus Annuus (Sunflower) Market
Seeds
Myanmar Rice Seed Market
Seeds
Asia-Pacific Grain Seed Market
Seeds
Sweet Corn Seeds Market
Seeds
Philippines Rice Seed Market
Seeds
Sri Lanka Seed Market
Seeds
Garlic Chive Seeds Market
Seeds
Global Sunflower Market
Seeds
India Vegetable Seed Market
Seeds
Vietnam Vegetable Seed Market
Seeds
Fruit Seed Waste Market