
 Organic Seed Market | 2026-2036
Organic Seed Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Seed Market Intelligence
The gap between certified organic germplasm and untreated conventional seed is realigning procurement standards across the supply chain. Vitalis Organic Seeds leverages its Dutch breeding stations to sustain European vegetable variety leadership. Johnny's Selected Seeds anchors northeastern US grower loyalty through trial-field validation programs. Baker Creek Heirloom Seeds differentiates via rare-variety preservation and direct-to-farmer catalog distribution.
Organic seed comprises reproductive plant material produced through cultivation methods excluding synthetic pesticides, genetically modified organisms, and petroleum-based fertilizers, with germination rates and genetic integrity verified under third-party certification protocols. Vegetable seed types command premium positioning due to shorter breeding cycles and direct consumer-facing traceability demands. Drought tolerance traits attract investment focus as climate volatility intensifies grower risk exposure. Paper envelope packaging dominates small-lot heritage sales, while bulk bags serve commodity organic grain operators.
The USDA National Organic Program and EU Organic Regulation jointly enforce seed sourcing hierarchies that privilege certified organic over conventional untreated alternatives. Seed Savers Exchange navigates these compliance layers through participatory breeding networks that document provenance chains. Stakeholders must monitor pending revisions to organic equivalency agreements between major trading blocs, as divergence in genetic engineering contamination thresholds threatens cross-border seed movement.
Market Dynamics
Certification hierarchies under the USDA National Organic Program and EU Organic Regulation are compressing conventional seed access channels. Breeders now face mandatory organic-origin requirements that favor vertically integrated seed cooperatives over commodity distributors.
Growth Catalysts
- EU Organic Regulation genetic purity mandates:Tighter contamination thresholds for genetically modified material are redirecting procurement toward certified organic germplasm stocks.
- Specialty vegetable grower procurement volumes:Direct-to-consumer produce channels demand traceable seed provenance that untreated conventional alternatives cannot document.
- Pacific Northwest breeding cluster concentration:Cooperative networks in Oregon and Washington concentrate heirloom expertise that accelerates variety development cycles.
Market Restraints
- Organic land conversion lag:Multi-year field preparation requirements delay certified seed production scaling relative to demand acceleration.
- Heritage grain supply concentration:Heritage wheat and rye germplasm remains concentrated among fewer than twelve North American preservation banks.
- Genetic uniformity limitations:Narrow trait diversity in commercially available organic vegetable lines restricts climate adaptation options.
Strategic Opportunities
- Underpenetrated drought-tolerance breeding:Water-stress adaptive traits in organic tomatoes and peppers remain commercially underdeveloped across Mediterranean-climate growing regions.
- Digital catalog direct distribution:Seed savers and heritage preservationists are bypassing wholesale distributors through subscription-based variety release platforms.
- USDA Organic Research and Promotion Program funding:Federal cost-share mechanisms for organic breeding infrastructure reduce capital barriers for regional seed cooperatives.
Industry Challenges
- Participatory breeding documentation burdens:Provenance chain record-keeping requirements under third-party certification protocols consume technical staff capacity at smaller seed enterprises.
- Cross-border equivalency negotiation delays:Pending revisions to US-EU organic trade agreements create inventory positioning uncertainty for multi-territory seed suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Seed Market |
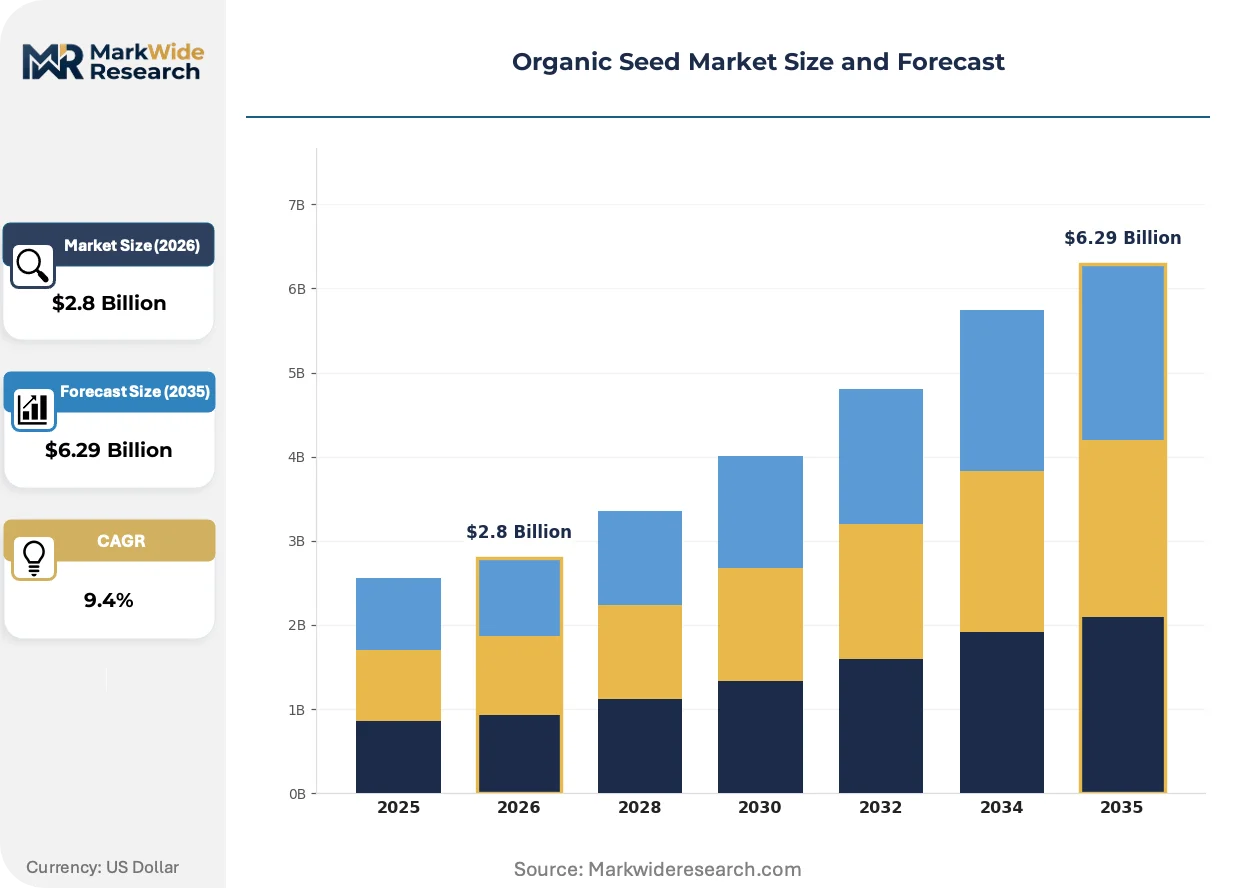
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.29 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Seed Type: Cereal Grains, Legumes, Vegetables, Oilseeds, Forage Seeds, Herbs Trait: Drought Tolerance, Pest Resistance, High Nutrient Content, Early Maturity, Enhanced Germination, Disease Resistance Crop Application: Cereal Cultivation, Pulse Farming, Horticulture, Oil Crop Production, Pasture Establishment, Botanical Herb Gardening Packaging Type: Bulk Bags, Paper Envelopes, Jute Sacks, Plastic Packets, Vacuum Sealed Packs, Biodegradable Pouches |
| Companies Covered | Vitalis Organic Seeds, Seeds of Change Inc., Johnny's Selected Seeds, Fedco Seeds, Southern Exposure Seed Exchange, Baker Creek Heirloom Seeds, High Mowing Organic Seeds, Seed Savers Exchange, Adaptive Seeds, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Seed Market Strategic Shifts & Innovations
Digital phenotyping tools and decentralized breeding networks are compressing variety development timelines. Seed enterprises now integrate field-level data capture with participatory selection protocols that accelerate trait stabilization.
Marker-assisted selection platforms are electrifying organic breeding programs by enabling trait tracking without transgenic insertion. Vegetable seed specialists in the Netherlands and Pacific Northwest cooperative networks are deploying these tools to compress generational cycles from eight years to four. The technology is electrifying competitive positioning among mid-scale breeders previously excluded from molecular breeding access.
REACH chemical registration requirements in Europe are restricting conventional seed treatment compounds that organic systems already exclude. This regulatory convergence is narrowing the compliance gap between certified organic and untreated conventional sourcing. Vegetable seed importers into EU member states now face equivalent documentation burdens regardless of organic claim status.
Direct-to-farmer catalog distribution is displacing wholesale seed dealer networks for heritage and specialty varieties. Baker Creek Heirloom Seeds and regional cooperative exchanges are capturing grower loyalty through trial-field validation content and provenance storytelling. This channel shift concentrates most visibly among Pacific Northwest and northeastern US vegetable producers with established organic certification histories.
Organic Seed Market Segmentation
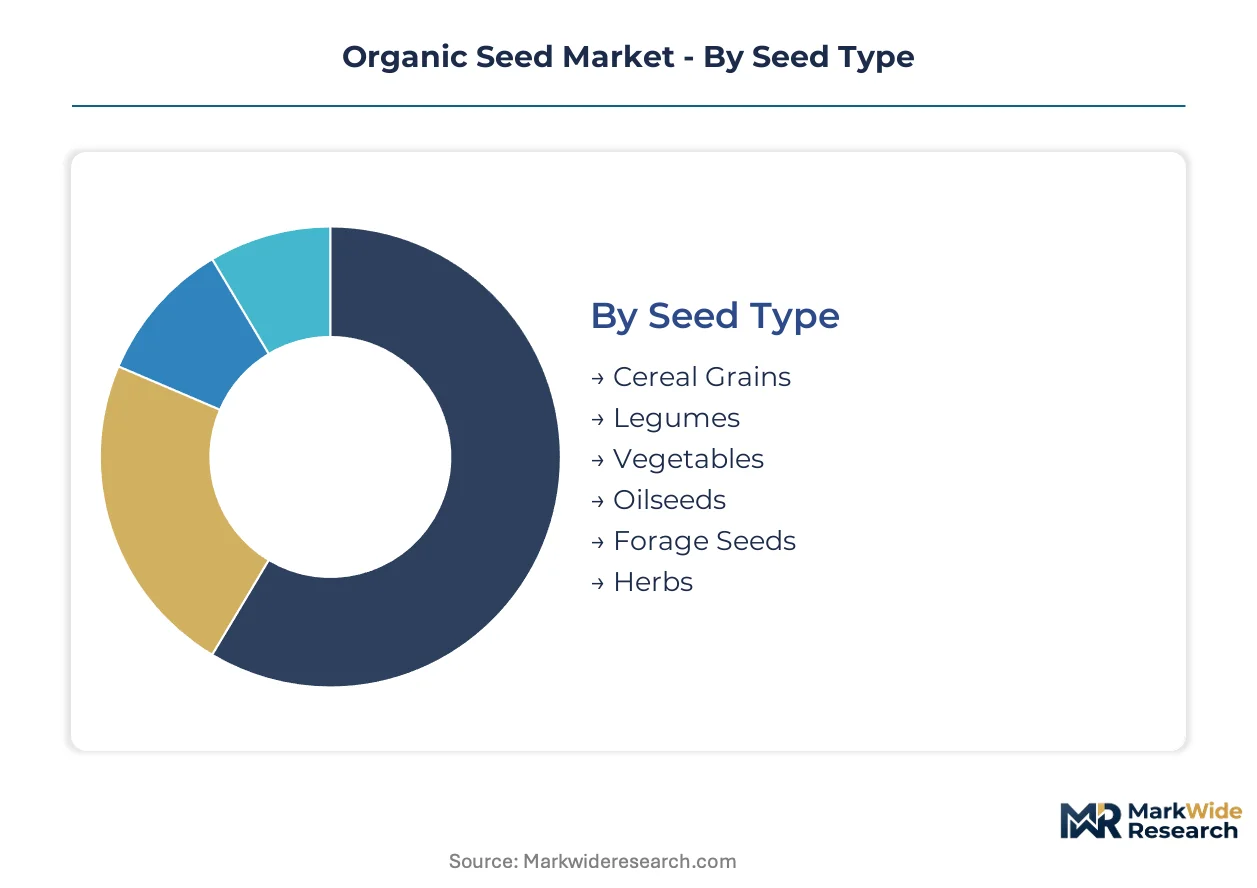
Organic seed procurement patterns diverge sharply across crop categories and trait specifications. Breeders must align varietal development with certification hierarchies that privilege traceable germplasm over conventional alternatives.
Seed Type:
Replacement cycles accelerate where breeding infrastructure concentrates and direct-to-consumer channels demand provenance documentation.
- Vegetables:Shorter generational cycles enable rapid trait stabilization for tomatoes, peppers, and leafy greens. Specialty growers in the Pacific Northwest and Netherlands drive procurement volumes through cooperative breeding networks that compress development timelines. Direct-to-consumer produce channels mandate genetic integrity documentation that untreated conventional seed cannot satisfy.
- Cereal Grains:Heritage wheat and rye germplasm requires multi-year field preparation before certified organic production scaling. Supply concentrates among fewer than twelve North American preservation banks, constraining procurement flexibility for millers seeking ancient variety access.
- Legumes:Nitrogen-fixing properties align with organic rotation protocols.
- Oilseeds:Sunflower and flax varieties serve organic oil pressing operations.
- Forage Seeds:Pasture establishment demands persist across dairy and livestock conversions.
- Herbs:Culinary and medicinal varieties command premium positioning through catalog distribution.
Volume placements concentrate in Vegetables; the faster expansion belongs to Cereal Grains as heritage grain millers scale procurement.
Trait:
Cost tiers separate molecular-assisted breeding platforms from participatory selection protocols.
- Drought Tolerance:Water-stress adaptive traits in organic tomatoes and peppers remain underdeveloped across Mediterranean-climate growing regions. Grower risk exposure from climate volatility intensifies investment focus, though commercial variety availability lags demand acceleration in Spain, Italy, and California.
- Disease Resistance:Marker-assisted selection enables trait tracking without transgenic insertion, compressing generational cycles from eight years to four. Dutch vegetable specialists and Pacific Northwest cooperatives deploy these platforms to electrify competitive positioning among mid-scale breeders.
- Pest Resistance:Natural defense mechanisms reduce synthetic input dependency.
- High Nutrient Content:Biofortification targets align with consumer-facing traceability demands.
- Early Maturity:Shortened harvest windows mitigate weather risk exposure.
- Enhanced Germination:Uniform emergence rates reduce replanting costs for certified operations.
Procurement prioritizes Disease Resistance for immediate yield protection; Drought Tolerance is gaining share fastest as climate adaptation urgency intensifies.
Crop Application:
Customer type differentiation separates commodity grain operators from specialty vegetable producers.
- Horticulture:Direct-to-consumer produce channels demand traceable seed provenance with complete documentation chains. Trial-field validation programs anchor grower loyalty in the northeastern United States through variety performance transparency.
- Cereal Cultivation:Bulk procurement patterns dominate organic grain operations supplying millers and food manufacturers. USDA National Organic Program certification requirements enforce sourcing hierarchies that privilege certified organic germplasm over conventional untreated alternatives.
- Pulse Farming:Legume rotations support nitrogen management in organic systems.
- Oil Crop Production:Pressing operations require specific fatty acid profiles.
- Pasture Establishment:Forage mixtures serve livestock conversion protocols.
- Botanical Herb Gardening:Small-lot preservation networks maintain rare variety access.
Revenue concentration sits with Horticulture; steepest expansion trajectory belongs to Cereal Cultivation as organic grain processing capacity scales.
Packaging Type:
Supply concentration shapes format selection across volume tiers and distribution channels.
- Paper Envelopes:Heritage variety preservationists and small-scale growers favor this format for catalog-distributed rare varieties. Baker Creek Heirloom Seeds and regional cooperative exchanges capture loyalty through provenance storytelling that aligns with paper packaging aesthetics.
- Bulk Bags:Commodity organic grain operators require ton-scale packaging for wheat, rye, and oat seeding operations. REACH chemical registration convergence in Europe narrows compliance gaps between certified organic and untreated conventional sourcing documentation.
- Jute Sacks:Biodegradable fiber aligns with organic certification aesthetics.
- Plastic Packets:Standard retail formats serve garden center distribution.
- Vacuum Sealed Packs:Extended viability preservation supports long-term storage.
- Biodegradable Pouches:Emerging formats target plastic reduction commitments.
Shipment volumes cluster in Bulk Bags; packaging innovation investment concentrates in Biodegradable Pouches as sustainability commitments harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Willamette Valley corridor in Oregon anchors North American organic seed breeding density, with cooperative networks concentrating heirloom expertise and generational knowledge transfer.
United States
Pacific Northwest vegetable growers and northeastern direct-market producers drive procurement volumes through established organic certification histories. The USDA National Organic Program enforces sourcing hierarchies that privilege certified organic germplasm over conventional untreated alternatives. Oregon and Washington cooperative breeding clusters compress development timelines for tomatoes, peppers, and leafy greens through participatory selection protocols.
Netherlands
Dutch vegetable seed specialists command European market positioning through molecular-assisted breeding platforms that track traits without transgenic insertion. REACH chemical registration requirements restrict conventional seed treatment compounds, narrowing compliance gaps between certified organic and untreated conventional sourcing. Wageningen-area breeding stations accelerate generational cycles from eight years to four for disease-resistant varieties.
Germany
Heritage grain millers and organic oil pressing operations scale procurement of ancient wheat and rye germplasm. The EU Organic Regulation mandates tighter contamination thresholds for genetically modified material, redirecting demand toward certified organic stocks. Bavarian and Baden-Württemberg preservation banks maintain narrow supply concentration among fewer than twelve North American and European germplasm repositories.
Spain
Mediterranean-climate vegetable producers face acute drought tolerance variety gaps in organic tomatoes and peppers. EU Organic Regulation genetic purity mandates accelerate procurement shifts toward certified germplasm with documented provenance chains. Andalusian and Valencian growing regions exhibit accelerating grower risk exposure from climate volatility that commercial variety availability has not matched.
Canada
Prairie organic grain operators and eastern horticulture producers expand certified seed sourcing as domestic processing capacity scales. Health Canada and PMRA oversight converges with USDA National Organic Program equivalency frameworks for cross-border germplasm movement. Ontario and Quebec seed cooperatives leverage federal cost-share mechanisms to reduce capital barriers for regional breeding infrastructure.
Organic Seed Market Key Industry Players
Premium-margin players sit above commodity-margin players across certification documentation and provenance storytelling capabilities. The vendor base organizes into three functional tiers: multinational breeding houses with molecular platforms, regional cooperative networks with participatory protocols, and heritage preservationists with rare-variety catalogs. Dominant competitive moves include geographic expansion through catalog distribution networks and backward integration into captive breeding stations.
Within the heritage preservationist tier, Baker Creek Heirloom Seeds and Seed Savers Exchange occupy positions defined by rare-variety access and direct-to-farmer distribution. Johnny's Selected Seeds anchors the trial-field validation segment through northeastern US grower loyalty programs. Vitalis Organic Seeds represents the multinational platform archetype with Dutch breeding station infrastructure sustaining European vegetable variety leadership.
| Leading Market Players |
|---|
| Vitalis Organic Seeds |
| Seeds of Change Inc. |
| Johnny's Selected Seeds |
| Fedco Seeds |
| Southern Exposure Seed Exchange |
| Baker Creek Heirloom Seeds |
| High Mowing Organic Seeds |
| Seed Savers Exchange |
| Adaptive Seeds |
| Others |
Cost & Logistics Intelligence
Captive breeding station networks anchor supply positioning and pricing power for organic seed enterprises, with Dutch vegetable specialists and Pacific Northwest cooperatives leveraging in-house germplasm development to command premium positioning over commodity distributors. USDA National Organic Program certification hierarchies and EU Organic Regulation genetic purity mandates compress conventional seed access channels, forcing procurement toward vertically integrated operators who control both breeding infrastructure and provenance documentation.
Pricing Analysis
Yield-guarantee pricing anchors organic vegetable seed transactions, with germination rate commitments and genetic integrity warranties justifying substantial premiums over untreated conventional alternatives. Three-tier pricing structure across premium, standard, and economy levels separates heritage preservationist catalogs from regional cooperative networks and commodity grain bulk suppliers. Cost compression in standard-tier vegetable lines is intensifying because REACH chemical registration convergence narrows compliance gaps between certified organic and conventional untreated sourcing. Specialty vegetable growers with direct-to-consumer channels exhibit lowest price sensitivity due to traceability mandates, while commodity organic grain operators face acute pressure on bulk procurement costs.
Supply Chain Analysis
Freight cost differentials between paper envelope catalog distribution and bulk bag commodity shipments concentrate procurement patterns across distinct buyer archetypes. Supply concentrates in the Netherlands, the United States, and Germany, with Wageningen-area breeding stations, Oregon-Washington cooperative networks, and Bavarian preservation banks anchoring germplasm availability. Raw material dependencies include heritage wheat and rye accessions, marker-assisted selection laboratory infrastructure, and certified organic field acreage for seed multiplication. Single-source vulnerability runs through the twelve North American and European germplasm repositories controlling heritage grain varieties. Distribution runs through direct-to-farmer catalog platforms for specialty lines and agricultural wholesale channels for commodity organic grain operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Marker-assisted selection platforms are displacing traditional eight-year generational breeding cycles, compressing variety development timelines to four years and rewarding early technology adopters with accelerated trait stabilization capabilities.
For Market Incumbents: Extend molecular breeding infrastructure investments to defend against Pacific Northwest cooperative networks capturing heirloom vegetable market share. Prioritize backward integration into captive organic field acreage to secure seed multiplication capacity ahead of USDA National Organic Program equivalency revisions. Certification documentation automation reduces technical staff burdens from participatory breeding provenance requirements.
For New Entrants and Emerging Players: Mediterranean-climate vegetable growers represent an underserved buyer archetype with acute drought tolerance variety gaps in organic tomatoes and peppers. Target Spain and California growing regions where commercial variety availability lags climate adaptation urgency. Subscription-based digital catalog distribution bypasses wholesale dealer networks and captures grower loyalty through trial-field validation content.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by multinational breeding houses seeking regional cooperative network integration and rare-variety catalog assets. Long-term viability favors enterprises with demonstrated organic certification maintenance and documented germplasm provenance chains. Watch pending US-EU organic trade agreement revisions as the critical inflection signal for cross-border inventory positioning risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Marker-Assisted Breeding Platform Deployment | Wageningen-area stations compress generational cycles from eight years to four for disease-resistant vegetable varieties. |
| Direct-to-Farmer Catalog Distribution Expansion | Baker Creek Heirloom Seeds and regional cooperatives bypass wholesale networks through subscription-based variety release platforms. |
| Backward Integration into Organic Field Acreage | Johnny's Selected Seeds anchors northeastern US loyalty through trial-field validation programs on captive production plots. |
| Participatory Breeding Network Documentation Automation | Seed Savers Exchange reduces technical staff capacity burdens from third-party certification provenance requirements. |
| Drought Tolerance Trait Development Partnership | Andalusian and Valencian growing regions in Spain exhibit accelerating demand unmatched by commercial variety availability. |
Research Approach
USDA National Organic Program filings, EU Organic Regulation compliance databases, and REACH chemical registration records formed the secondary backbone of this analysis. Primary interviews with organic seed cooperative breeding directors, heritage preservationist catalog operators, specialty vegetable growers, and certified organic grain millers validated germplasm sourcing patterns and certification hierarchy impacts. Trade data from organic processing facilities and seed import customs records supplemented demand-side triangulation. Bottom-up variety-level procurement estimates and top-down organic acreage conversion trajectories were reconciled across the analysis window.
Historical certified organic seed production volumes and acreage conversion timelines established baseline trendlines for projection modeling. Segmentation dimensions included crop type, trait specification, packaging format, and regional regulatory cluster. CAGRs were derived through logarithmic trend fitting across the modeling period. Forecast inputs incorporated organic land conversion lag parameters, heritage grain germplasm repository concentration constraints, and digital catalog distribution adoption curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to US-EU organic equivalency agreement revisions and climate volatility impacts on drought tolerance trait demand. Forecasts reflect documented assumptions regarding certification hierarchy enforcement and cooperative network expansion trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Flax Seed Market
Seeds
Organic Chia Seeds Market
Seeds
Garden Seeds Market
Seeds
Lupin Market
Seeds
Sesame Seeds Market
Seeds
Okra Seed Market
Seeds
Seed Cracker Market
Seeds
Russia Forage Seed Market
Seeds
India Rice Seed Market
Seeds
Buckwheat Market
Seeds
United States Garden Seeds Market
Seeds
Mexico Vegetable Seed Market
Seeds
Europe Vegetable Seed Market
Seeds
Caraway Seeds Market
Seeds
Spain Forage Seed Market
Seeds
Guar Market