
 Cannabis Seeds Market | 2026-2036
Cannabis Seeds Market Size, Share, and Industry Trends Forecast 2026-2036
Cannabis Seeds Market Analysis
Licensed cultivation expertise is bifurcating the competitive landscape into specialist genetic houses and scaled distribution platforms. Humboldt Seed Company leverages its California heritage to anchor premium positioning in legacy and legal markets alike. Royal Queen Seeds competes through broad European distribution, while Sensi Seeds sustains decades of breeding credibility with institutional growers.
Cannabis seeds are botanically classified as dormant embryonic plants encased in protective testa, requiring controlled humidity below 10 percent and stable temperatures near 4 degrees Celsius for viable long-term storage. Their commercial purpose centers on propagating uniform, sex-identified, and chemotype-stable plant stock for regulated agricultural production. Feminized seeds command the dominant share of commercial transactions because they eliminate male plant culling and optimize canopy efficiency. Autoflowering varieties represent the fastest-expanding product class as greenhouse operators adopt short-cycle genetics to increase annual harvest frequency. CBD-dominant seeds concentrate margin pools in jurisdictions with restrictive THC limits, particularly European medical programs.
The United States Department of Agriculture oversees hemp seed certification under the 2018 Farm Bill, while individual state cannabis regulators impose batch-level testing and traceability mandates that reshape supplier qualification requirements. Health Canada and the European Medicines Agency maintain divergent THC thresholds for seed classification, fragmenting import protocols and forcing multi-jurisdiction inventory segregation. Stakeholders must monitor pending federal rescheduling proceedings and emerging EU novel food determinations for hemp-derived extracts, as these rulings will recalibrate which genetic lines qualify for broad agricultural distribution versus controlled-substance channels.
Market Dynamics
Feminized and autoflowering genetics are compressing cultivation cycles while fragmenting supplier qualification requirements across incompatible national seed certification regimes.
Growth Catalysts
- USDA hemp certification:The 2018 Farm Bill established interstate commerce frameworks for hemp seeds below 0.3% THC, enabling agricultural distributors to enter the category with existing infrastructure.
- Greenhouse automation:Dutch and Spanish controlled-environment agriculture operators are standardizing on 10-12 week autoflowering varieties to triple annual harvest frequency.
- Medical program expansion:Germany's 2024 cannabis legalization created demand for GMP-certified genetics, pulling EU-based breeders into pharmaceutical-grade production protocols.
Market Restraints
- Federal-state divergence:US seed suppliers face banking exclusion under Schedule I classification despite state-level legality, forcing cash-intensive operations and limiting scale.
- Genetic homogenization risk:Concentration of elite breeding stock in California and the Netherlands creates vulnerability to pathogen outbreaks and climate disruption.
- Cross-border testing inconsistency:Health Canada's THC threshold for seed classification conflicts with EMA standards, requiring parallel inventory segregation and doubling compliance overhead.
Strategic Opportunities
- Thailand medical cannabis:Southeast Asia's first legal medical program lacks domestic breeding capacity, creating import demand for stabilized CBD-dominant lines.
- Seed-to-sale blockchain integration:California and Colorado regulators are mandating genetic provenance tracking, opening software-hardware bundles for verification technology providers.
- Novel food pathway:Pending EFSA determinations on hemp seed protein could unlock food-grade distribution channels separate from controlled-substance frameworks.
Industry Challenges
- Phytosanitary certification backlog:Multi-month approval timelines for international seed shipments disrupt planting schedules and strain working capital.
- Phenotypic drift in tissue culture:Micropropagation labs struggle to maintain chemotype stability across successive generations, undermining contractual THC/CBD specifications.
- Cross-pollination liability:Outdoor hemp and cannabis operations in contiguous jurisdictions generate pollen-mediated contamination disputes with no settled insurance framework.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cannabis Seeds Market |
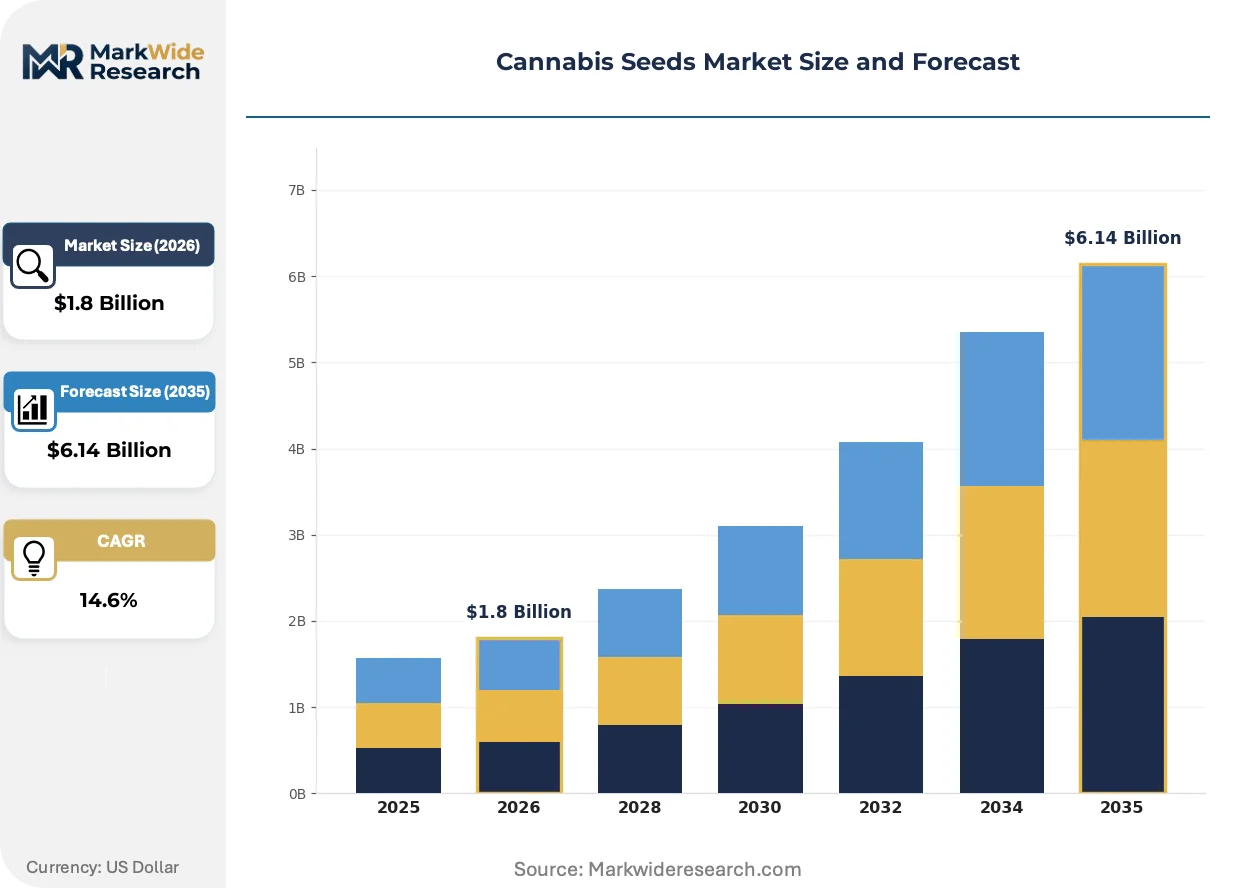
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Regular Seeds, Feminized Seeds, Autoflowering Seeds, CBD Seeds End User: Commercial Growers, Home Growers, Research Institutions, Dispensaries Distribution Channel: Online Retail, Specialty Stores, Distributors, Garden Centers Geographical Market: North America, Europe, Asia-Pacific, Latin America |
| Companies Covered | Homegrown Cannabis Co, ILGM, Seed Supreme, Humboldt Seed Company, Sensi Seeds, DNA Genetics, Premium Cultivars, Barney’s Farm, Royal Queen Seeds, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cannabis Seeds Market Emerging Trajectories
Genetic stabilization technologies and regulatory data infrastructure are reconfiguring how seed quality is verified, financed, and traded across previously siloed markets.
Marker-assisted selection is supplanting traditional phenotype-based breeding programs. Large-scale Canadian and Israeli cultivators now genotype seedlings at 72 hours to discard males and off-target chemotypes before transplant. This compression of selection timelines is collapsing the 18-24 month variety development cycle toward 8-12 months for major traits.
EMA's 2023 revised guidance on cannabis-derived medicinal products is forcing seed suppliers to adopt pharmaceutical-grade batch documentation. German and Polish medical operators now require genetic stability studies across five generations, diverting R&D expenditure from agronomic traits toward regulatory dossier preparation.
Direct-to-cultivator digital platforms are displacing wholesale distributor networks in North American markets. California and Oregon operators increasingly purchase verified genetics through breeder-hosted e-commerce with embedded testing documentation, compressing margin capture for traditional intermediaries and concentrating price transparency among sophisticated buyers.
Cannabis Seeds Market Segmentation
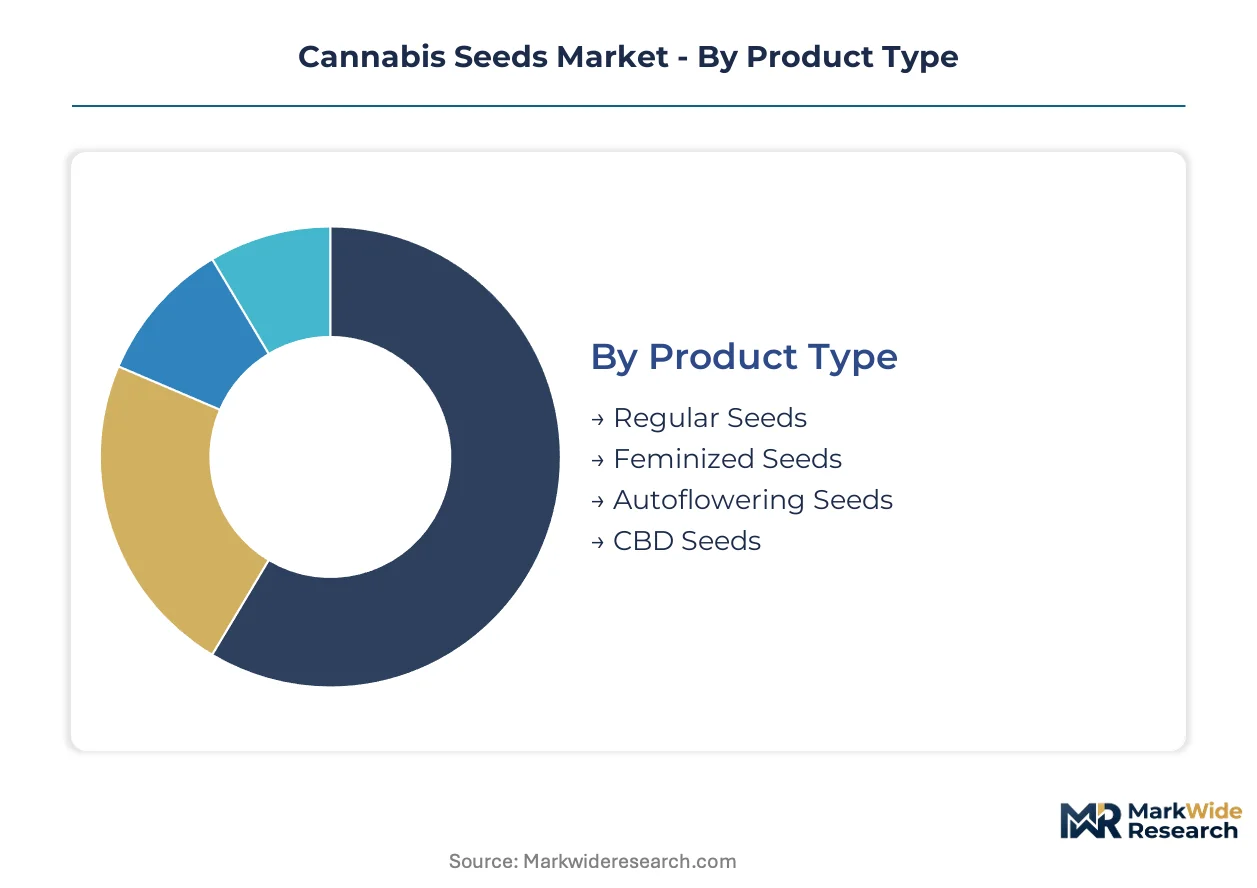
Cannabis seed suppliers route distinct genetic categories through channel-specific pathways. Commercial cultivators demand batch-certified feminized stock via distributor networks, while home growers source autoflowering varieties through direct-to-consumer platforms. Segmentation strategy determines which product lines absorb compliance costs and which capture margin through premium positioning.
Product Type:
Feminized and autoflowering genetics dominate commercial procurement channels, while regular seeds concentrate in breeding programs and CBD-dominant lines flow through medical program tenders.
- Feminized Seeds:These seeds undergo colloidal silver or ethylene treatment to suppress male chromosome expression, producing 99%+ female plant rates. Commercial growers in California, Colorado, and the Netherlands specify feminized stock to eliminate male culling labor and maximize canopy efficiency. Health Canada and German medical programs mandate feminized genetics for pharmaceutical-grade production to ensure batch chemotype consistency.
- Autoflowering Seeds:Ruderalis-crossed genetics switch from vegetative to flowering based on age rather than photoperiod, compressing total cycle time to 10-12 weeks. Greenhouse operators in Spain and the Netherlands adopt autoflowering varieties to triple annual harvest frequency. The USDA hemp certification framework accommodates autoflowering CBD lines under the 0.3% THC threshold, enabling agricultural channel distribution.
- Regular Seeds:Untreated sexual diploid seeds maintain genetic diversity for breeding programs. Humboldt Seed Company and legacy California breeders preserve regular seed lines for pheno-hunting and strain development.
- CBD Seeds:Chemotype-bred varieties expressing 15-20% CBD with sub-0.3% THC content. European medical programs in Germany, Poland, and Italy tender for CBD-dominant genetics to meet EMA pharmaceutical specifications.
By volume, feminized seeds lead commercial transactions. By growth pace, autoflowering varieties are expanding most quickly as greenhouse automation spreads.
End User:
Cost tier stratification separates high-volume commercial procurement from premium-priced home cultivation and regulated research access.
- Commercial Growers:Licensed multi-acre operations in California, Oregon, and Colorado purchase feminized and autoflowering seeds in 10,000-unit batches with embedded COA documentation. These buyers absorb GMP certification premiums to satisfy state track-and-trace mandates.
- Home Growers:Adult-use legal jurisdictions permit personal cultivation of 4-12 plants, driving demand for 3-5 seed retail packs. Canadian and Oregon markets show strongest home cultivation penetration.
- Research Institutions:Universities and pharmaceutical laboratories in Israel and Canada access Schedule I research licenses for chemotype stability studies. Health Canada and DEA permitting creates procurement bottlenecks.
- Dispensaries:Vertically integrated retailers in Colorado and Washington maintain clone and seed sales as customer acquisition tools. Dispensary seed margins compress against online breeder-direct competition.
Commercial growers generate the highest absolute revenue. Research institutions command the steepest per-seed pricing due to regulatory scarcity.
Distribution Channel:
Supply concentration in breeder-direct platforms is displacing traditional wholesale intermediaries across North American markets.
- Online Retail:Breeder-hosted e-commerce with embedded genetic testing documentation captures margin from legacy distributor networks. California and Oregon operators increasingly verify chemotypes through digital platforms before purchase.
- Specialty Stores:Amsterdam-based seed banks and California dispensary-adjacent retailers maintain curated genetic libraries. Sensi Seeds and Royal Queen Seeds anchor European specialty retail presence.
- Distributors:Agricultural supply houses in the Netherlands and Spain handle bulk autoflowering seed logistics for greenhouse operators. Phytosanitary certification backlogs strain distributor working capital cycles.
- Garden Centers:General agricultural retailers in US hemp-legal states stock CBD seed varieties under USDA certification. Garden center penetration remains shallow due to federal-state regulatory divergence.
Distributors still handle the largest seed volumes. Online retail channels are gaining share fastest among sophisticated commercial buyers.
Geographical Market:
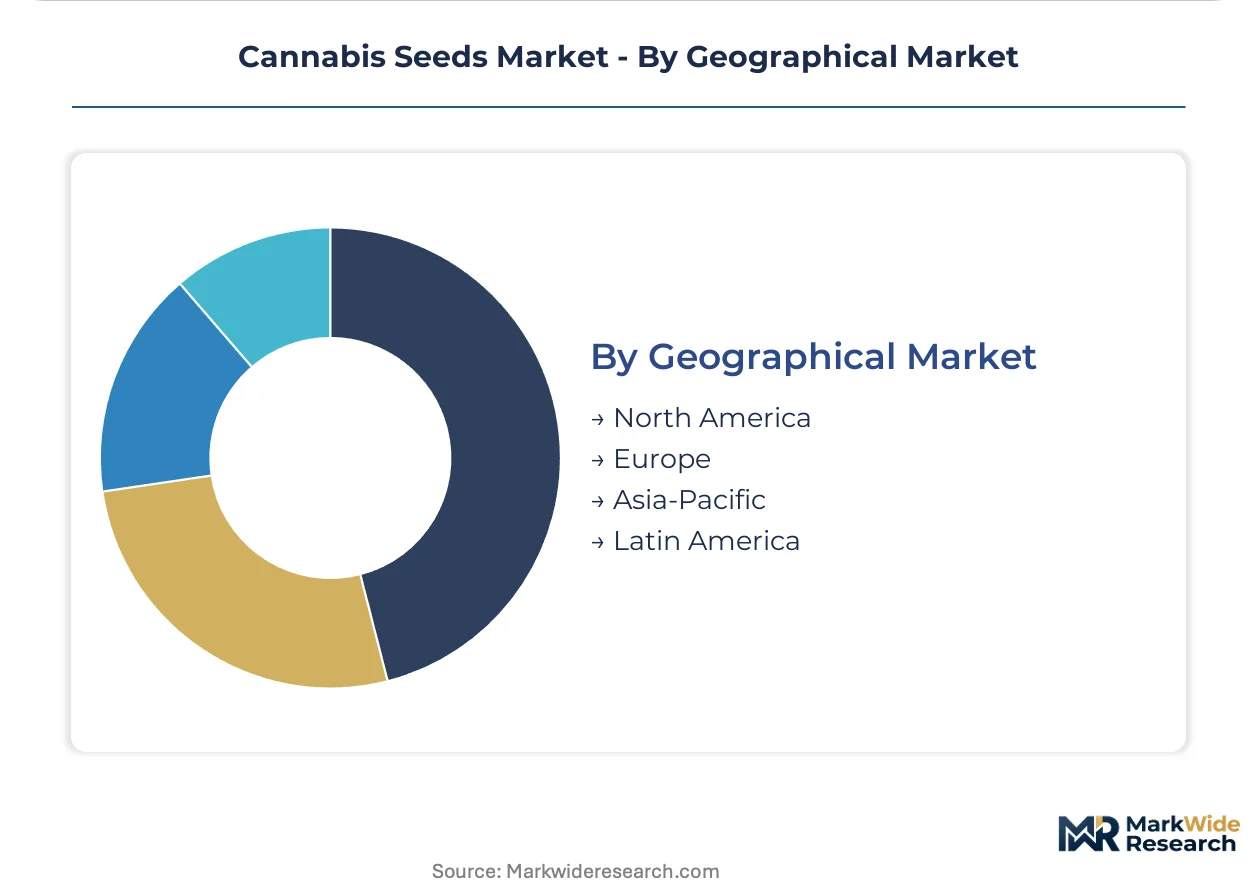
Regulatory maturity determines which geographies permit broad agricultural distribution versus controlled-substance channel access.
- North America:US state-level legalization and Canadian federal frameworks create the deepest commercial seed markets. California, Colorado, and Oregon anchor North American breeding infrastructure.
- Europe:German medical program expansion and Dutch greenhouse automation drive feminized and autoflowering demand. EMA pharmaceutical-grade requirements reshape supplier qualification protocols.
- Asia-Pacific:Thailand's medical cannabis program lacks domestic breeding capacity, creating import demand for stabilized CBD lines. Australian and Israeli research institutions access limited Schedule I licenses.
- Latin America:Colombia and Uruguay licensed cultivation programs remain nascent, with seed supply dependent on North American and European imports. Brazilian ANVISA pharmaceutical pathways show early CBD seed demand.
North America leads by installed cultivation capacity. Asia-Pacific shows the steepest expansion trajectory as Thailand and Australia develop medical frameworks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The USDA anchors the dominant geography through its 2018 Farm Bill hemp certification framework, while Health Canada and Germany's BfArM impose divergent pharmaceutical-grade requirements that fragment cross-border seed trade protocols.
United States
California, Colorado, and Oregon licensed cultivators drive feminized seed procurement at commercial scale. State-level cannabis regulators mandate batch-level COA documentation and genetic provenance tracking, forcing suppliers to maintain parallel compliance systems. Humboldt County and the Emerald Triangle anchor North American breeding infrastructure with decades of legacy genetics expertise.
Germany
The 2024 cannabis legalization created immediate demand for GMP-certified autoflowering genetics among medical program operators. BfArM pharmaceutical specifications require genetic stability documentation across five generations, diverting breeder R&D toward regulatory dossier preparation. Berlin and North Rhine-Westphalia concentrate import-dependent cultivation facilities lacking domestic breeding capacity.
Netherlands
Dutch greenhouse automation operators standardize on 10-12 week autoflowering varieties to triple annual harvest frequency. The country's phytosanitary certification regime enables seamless EU seed distribution, though EMA novel food determinations for hemp-derived extracts remain pending. Westland and Aalsmeer controlled-environment agriculture clusters drive varietal selection toward short-cycle genetics.
Canada
Health Canada's THC threshold for seed classification conflicts with EMA standards, requiring multi-jurisdiction inventory segregation. Israeli and Canadian research institutions access Schedule I licenses for chemotype stability studies, creating procurement bottlenecks. British Columbia and Ontario licensed producers generate concentrated demand for feminized pharmaceutical-grade stock.
Thailand
Southeast Asia's first legal medical cannabis program lacks domestic breeding infrastructure, creating import demand for stabilized CBD-dominant lines. The country's national pharmaceutical regulator establishes import protocols for foreign genetics while local cultivation capacity develops. Bangkok and Chiang Mai medical operators depend entirely on North American and European seed suppliers.
Cannabis Seeds Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the cannabis seeds market. Specialist genetic houses concentrate breeding expertise and phenotypic stabilization capabilities, while scaled distribution platforms optimize logistics and regulatory compliance overhead. Three archetypes dominate: legacy heritage breeders with decades of strain libraries, digital-native direct-to-cultivator platforms, and agricultural supply houses with phytosanitary certification infrastructure. Competitive moves center on breeder-direct e-commerce displacement of wholesale intermediaries and pharmaceutical-grade batch documentation investments for medical program qualification.
Within the heritage breeder tier, Humboldt Seed Company and Sensi Seeds exemplify geographic credibility anchors—California and Amsterdam respectively—that translate into premium positioning across legacy and legal markets. Royal Queen Seeds occupies a position within the scaled European distribution archetype, leveraging broad market access to compete against direct-to-cultivator digital platforms. These three entities represent contrasting strategic postures: regional heritage concentration versus continental logistics optimization.
| Leading Market Players |
|---|
| Homegrown Cannabis Co |
| ILGM |
| Seed Supreme |
| Humboldt Seed Company |
| Sensi Seeds |
| DNA Genetics |
| Premium Cultivars |
| Barney's Farm |
| Royal Queen Seeds |
| Others |
Supply Flow & Price Mechanics
Batch-size scale economies in feminized seed production concentrate pricing power among California and Dutch operators with stabilized genetic libraries. Large-volume procurement contracts from Canadian and German licensed cultivators establish price floors that smaller breeders cannot match without sacrificing margin.
Pricing Analysis
California seed pricing diverges from European benchmarks by 40-60 percent due to phytosanitary certification costs and cross-border banking friction. Three-tier pricing structure across premium heritage lines, standard certified stock, and economy bulk autoflowering tiers captures buyer sophistication variation. Cost compression in the economy tier intensifies as greenhouse operators in Spain and the Netherlands consolidate procurement volumes. Commercial growers with 10,000-unit batch requirements exhibit lowest price sensitivity; home cultivators in Oregon and Colorado drive hardest bargain hunting.
Supply Chain Analysis
Strategic stockpiling of elite breeding stock dominates inventory strategy as genetic drift risks render just-in-time propagation unreliable for pharmaceutical-grade contracts. Supply concentrates in California, the Netherlands, and Canada as pathogen-free tissue culture hubs. The chain draws from specialized agar media suppliers, controlled-environment propagation facilities, and batch-testing laboratories. Single-source vulnerability concentrates in California's Emerald Triangle breeding stock repositories. Distribution runs through breeder-direct e-commerce platforms displacing legacy wholesale seed banks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Genetic stabilization expertise functions as the scarce capability separating viable competitors from margin-compressed commodity suppliers. Breeding programs capable of five-generation chemotype documentation command sustainable positioning.
For Market Incumbents: Secure GMP certification pathways in Germany and Poland before regulatory windows narrow. Lock exclusive distribution partnerships with Thai medical importers lacking domestic breeding infrastructure. Vertical integration into tissue culture micropropagation insulates against phenotypic drift liabilities threatening contract specifications. For New Entrants and Emerging Players: USDA hemp certification fast-track offers lowest-friction entry into interstate commerce under the 2018 Farm Bill. White-space concentrates in CBD-dominant autoflowering lines for European medical tenders and Thai import substitution. Direct-to-cultivator digital platforms with embedded testing documentation bypass entrenched distributor networks. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors breeders with marker-assisted selection capabilities and pharmaceutical-grade batch documentation infrastructure. Five-to-ten year viability hinges on regulatory rescheduling outcomes and EMA novel food determinations. Acquisition targets should demonstrate genetic stability studies across multiple generations. The signal to watch is federal rescheduling proceedings recalibrating banking access and interstate commerce frameworks.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Certification Investment | Unlocks German BfArM medical program access requiring five-generation stability documentation. |
| Seed-to-Sale Blockchain Integration | California and Colorado regulators mandate genetic provenance tracking for compliance verification. |
| Autoflowering Genetics R&D | Dutch greenhouse automation operators standardize on 10-12 week cycles tripling annual harvest frequency. |
| Thai Import Partnership | Southeast Asia's first legal medical program lacks domestic breeding capacity creating supply dependency. |
| Phytosanitary Infrastructure Buildout | Multi-month certification backlogs strain working capital and disrupt planting schedules for international shipments. |
Methodological Framework
Desk research of seed certification protocols, regulatory filings with Health Canada and Germany's BfArM, and trade flow databases preceded structured interviews with breeding program directors, phytosanitary certification officers, and licensed cultivation procurement managers. Primary fieldwork across California, the Netherlands, and Ontario triangulated against secondary validation from USDA hemp program documentation and EMA pharmaceutical guidance. Bottom-up volume estimates from breeder production capacity reconciled with top-down market sizing from import-export customs records.
Variance decomposition across product type, end-user tier, distribution channel, and geographic regulatory cluster shaped the analytical framework throughout the projection horizon. CAGRs derived from segment-level growth rate reconciliation against aggregate market expansion. Modeled inputs included feminized seed penetration rates, autoflowering adoption curves in controlled-environment agriculture, and medical program expansion trajectories in Germany and Thailand.
Decision-makers should treat outputs as directional under assumptions of continued state-level US legalization and stable EU pharmaceutical regulatory frameworks; material deviation would warrant model refresh. Revision becomes warranted when federal rescheduling proceedings or EFSA novel food determinations cross implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
E. Angustifolium Market
Seeds
Perilla Seed Oil Market
Seeds
India Forage Seed Market
Seeds
Helianthus Annuus (Sunflower) Market
Seeds
Organic Seed Market
Seeds
Sesame Seeds Market
Seeds
Agricultural Seeder Market
Seeds
Dragon Fruit Seeds Market
Seeds
Myanmar Rice Seed Market
Seeds
Hemp Seed Oil Market
Seeds
Eucommia Seed Oil Market
Seeds
Europe Chia Seeds Market
Seeds
Cherry Tomato Seeds Market
Seeds
Fruit Seed Waste Market
Seeds
Genetically Modified Seeds Market
Seeds
Melon Seed Market