
 Ketoanalogue for Kidney Disease Market | 2026-2036
Ketoanalogue for Kidney Disease Market Size, Share, and Industry Trends Forecast 2026-2036
Ketoanalogue for Kidney Disease Market Foresight
Maintenance and compliance support bundled with ketoanalogue prescriptions is shifting how value gets captured in renal nutrition. Fresenius Kabi AG leverages its dialysis service infrastructure to anchor recurring ketoanalogue sales alongside equipment contracts. B. Braun Melsungen AG competes through integrated renal care platforms that sustain patient adherence programs across Europe and Asia.
Ketoanalogue comprises nitrogen-free ketoacid derivatives of essential amino acids, formulated at specific ratios to reduce urea generation while preserving protein balance in patients with impaired renal function. Tablet formulations dominate current volume due to dosing convenience and established reimbursement pathways, while liquid formulations represent the fastest-growing segment as swallowing difficulties in advanced chronic kidney disease patients drive format diversification. Dialysis centers capture the deepest margin pools through bulk procurement and protocol-driven prescribing, whereas home care channels are expanding fastest as peritoneal dialysis adoption rises.
The US FDA oversees ketoanalogue approval under orphan drug and renal therapeutic pathways, while EMA frameworks govern market access across European member states through centralized and decentralized procedures. India's CDSCO and China's NMPA impose distinct bioequivalence and local trial requirements that shape entry timelines for multinational manufacturers. Stakeholders must monitor evolving renal dietary supplement classification debates, as reclassification between drug and medical food status would fundamentally alter distribution economics and prescriber access.
Market Dynamics
The Ketoanalogue for Kidney Disease Market is being reshaped by the tension between dialysis center consolidation and the rise of home-based peritoneal dialysis, which fragments prescribing authority and forces manufacturers to build dual-channel capabilities.
Growth Catalysts
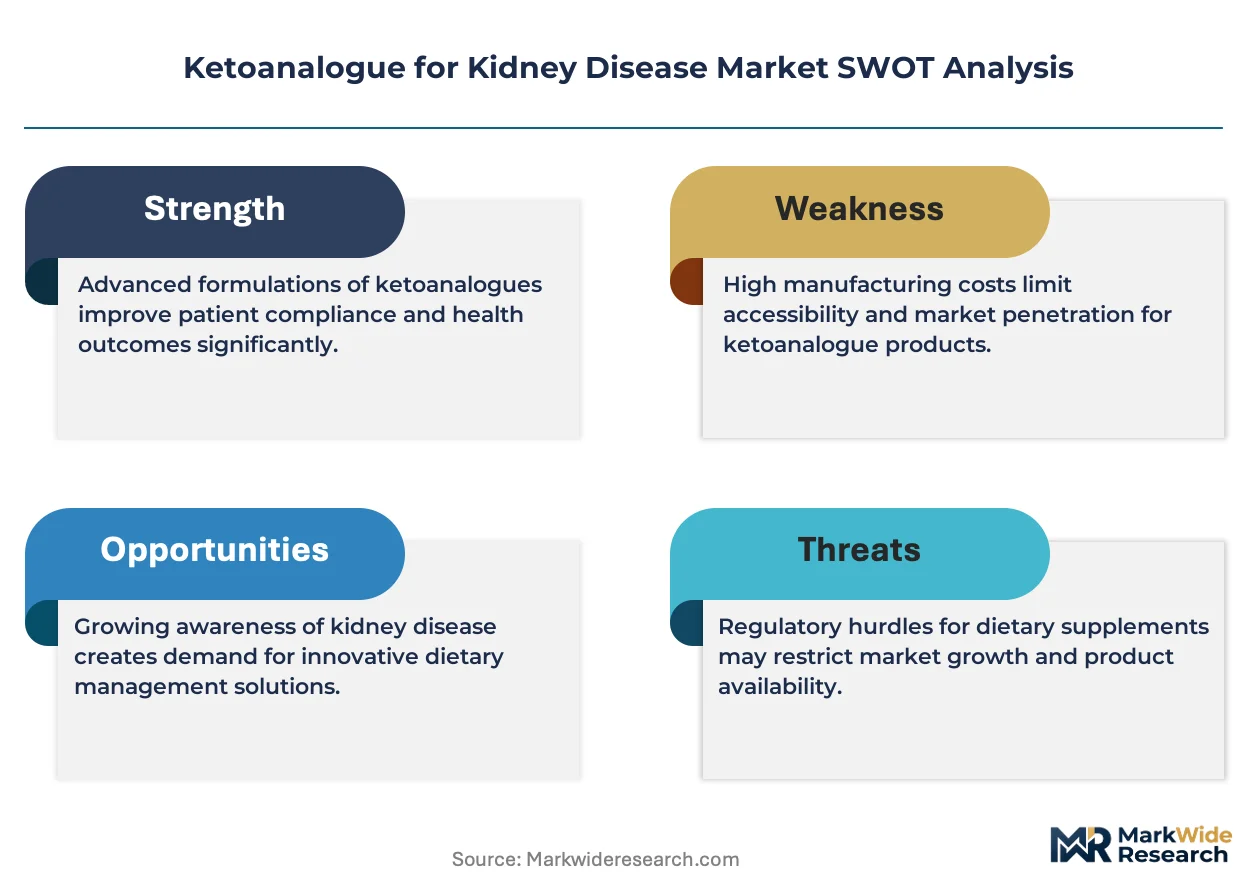
- EMA Renal Therapeutic Pathways:Centralized marketing authorization procedures accelerate cross-border patient access for ketoanalogue formulations in European member states with harmonized reimbursement.
- Peritoneal Dialysis Expansion:Home care channels in India and China create volume pull as patients seek alternatives to in-center hemodialysis.
- Tablet-to-Liquid Format Diversification:Swallowing difficulties in advanced chronic kidney disease patients drive demand for alternative dosage forms.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Synthesis of nitrogen-free ketoacid derivatives depends on specialized contract manufacturers concentrated in select geographies.
- CDSCO Bioequivalence Requirements:India's local trial mandates extend entry timelines for multinational manufacturers seeking market access.
- Medical Food Reclassification Risk:Shifts between drug and dietary supplement status in key jurisdictions would alter distribution economics and prescriber access.
Strategic Opportunities
- Home Care Channel Penetration:Peritoneal dialysis adoption in China creates whitespace for direct-to-patient distribution models bypassing institutional procurement.
- Integrated Renal Care Platforms:Bundling ketoanalogue prescriptions with maintenance support and adherence programs captures recurring revenue streams.
- PLI Scheme Manufacturing:India's production-linked incentive framework for pharmaceuticals offers cost advantages for export-oriented production.
Industry Challenges
- Nephrology Specialist Shortage:Prescribing ketoanalogues requires trained renal nutrition expertise that remains scarce in tier-2 and tier-3 cities.
- Cross-Jurisdictional Registration Complexity:Navigating simultaneous FDA, EMA, NMPA, and CDSCO submissions strains regulatory affairs capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ketoanalogue for Kidney Disease Market |
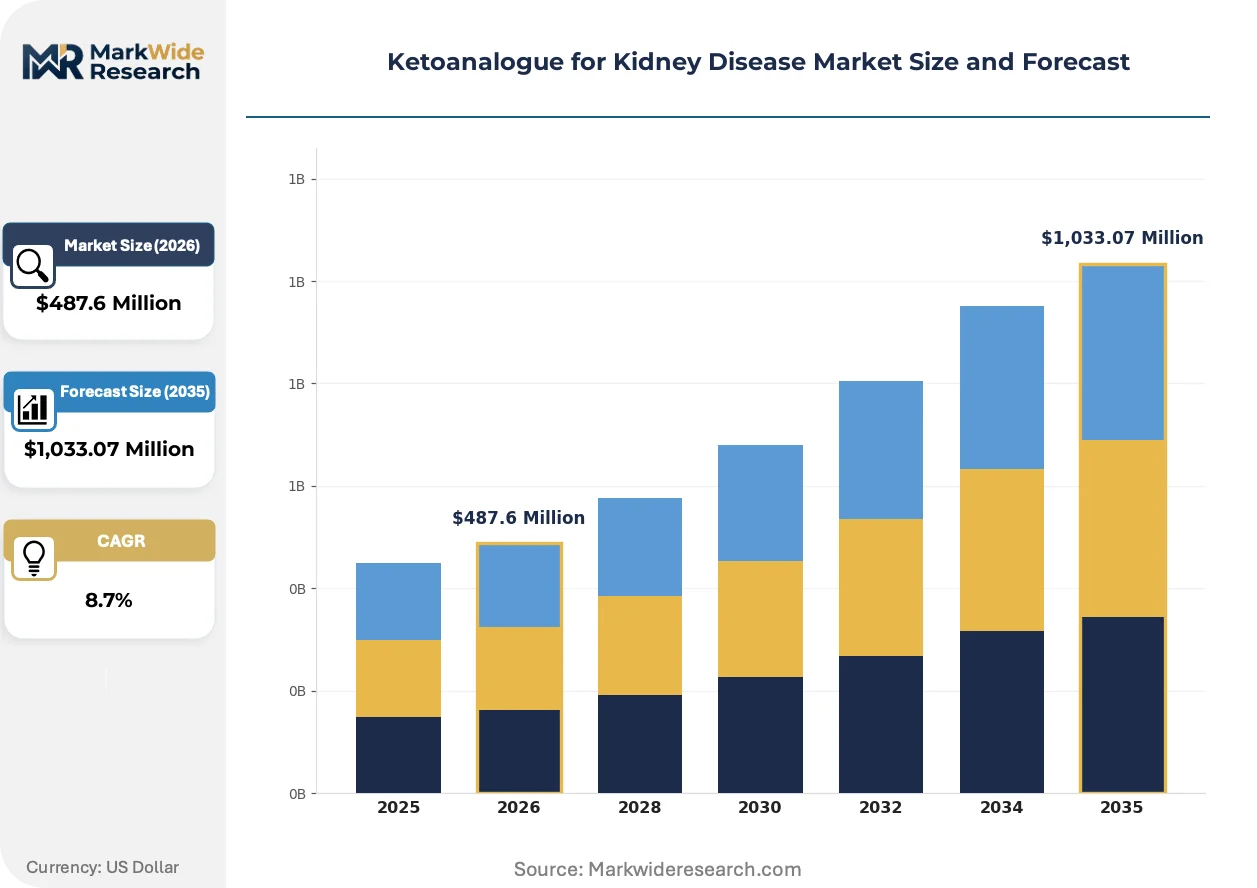
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Powders, Capsules, Liquid Formulations End User: Hospitals, Home Care, Specialty Clinics, Dialysis Centers Delivery Mode: Oral, Parenteral, Enteral, Intravenous Application: Chronic Kidney Disease, Pre-Dialysis, Dialysis Support, Renal Transplantation |
| Companies Covered | Alniche Life Sciences Pvt. Ltd., Steadfast Medishield Private Limited, Fresenius Kabi AG, Ajanta Pharma Limited, Panacea Biotec, B. Braun Melsungen AG, La Renon Healthcare Pvt Ltd, Centaur Pharmaceuticals, RPG Life Sciences Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ketoanalogue for Kidney Disease Market Shifts & Advancements
Digital adherence monitoring and personalized dosing algorithms are compressing the gap between clinical protocol and real-world patient compliance in renal nutrition management.
Microencapsulation technology for taste-masking and gastric protection is integrating into liquid ketoanalogue formulations. Pediatric and geriatric dialysis centers in Japan are adopting these enhanced delivery systems fastest. The technology is integrating compliance data capture directly into dosing devices, enabling outcome-linked reimbursement pilots.
REACH registration requirements for novel excipients in European pharmaceutical formulations are tightening supply qualification timelines. Manufacturers must now document full substance volume tracking from synthesis to finished dose. Dialysis center procurement departments in Germany and France are responding by pre-qualifying fewer, larger excipient suppliers.
Hospital pharmacy committees are consolidating vendor lists for renal nutrition products, shifting purchasing authority from individual nephrologists to centralized formulary managers. This compression of buying nodes favors suppliers with broad portfolio breadth and dedicated clinical support teams. The pattern is most visible in US integrated delivery networks and UK NHS trust procurement frameworks.
Ketoanalogue for Kidney Disease Market Segmentation
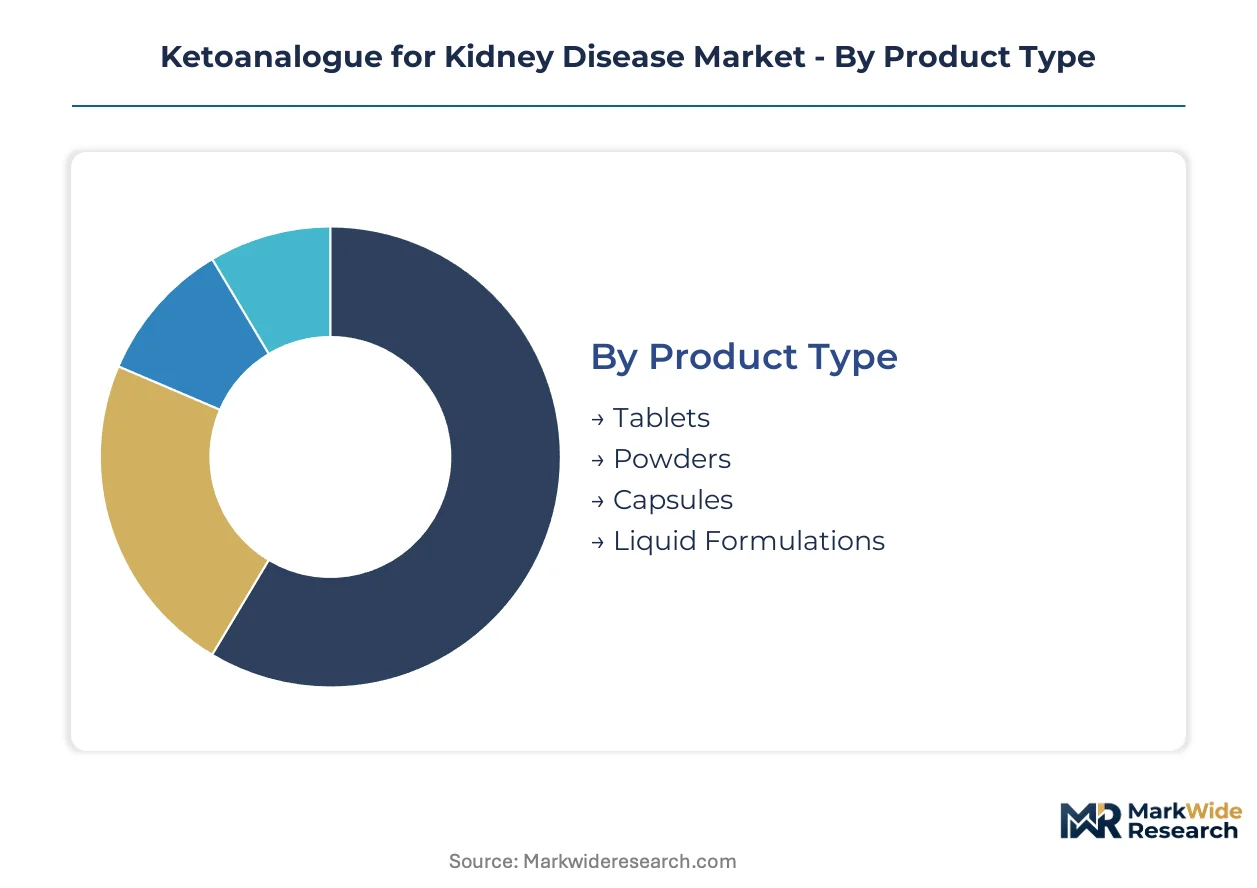
Ketoanalogue market segmentation reveals how regulatory pathways, patient compliance needs, and care settings fragment commercial opportunities. Manufacturers must align formulation choices with specific FDA, EMA, and national pharmaceutical classification frameworks to secure reimbursement access.
Product Type:
EMA centralized marketing authorization and FDA orphan drug pathways impose distinct stability and bioequivalence requirements on each formulation class, shaping which formats multinational suppliers prioritize for cross-border registration.
- Tablets:Compressed nitrogen-free ketoacid derivatives in fixed-dose combinations dominate procurement volumes at dialysis centers in Germany and France due to established reimbursement codes and protocol-driven prescribing. Hospital pharmacy committees in US integrated delivery networks consolidate tablet purchasing through centralized formulary contracts that favor suppliers with dedicated clinical support teams.
- Liquid Formulations:Microencapsulation technology for taste-masking and gastric protection addresses swallowing difficulties in advanced chronic kidney disease patients. Pediatric and geriatric dialysis centers in Japan adopt these enhanced delivery systems fastest, with compliance data capture integrating directly into dosing devices for outcome-linked reimbursement pilots.
- Powders:Reconstitutable sachets offer dose flexibility for peritoneal dialysis patients managing protein intake at home in India and China.
- Capsules:Gelatin and HPMC shell variants provide alternative administration for patients with tablet intolerance, though EMA excipient qualification timelines under REACH requirements constrain supplier options.
Leading the category by volume: Tablets. Growing fastest: Liquid Formulations.
End User:
Procurement authority concentrates differently across institutional settings, with bulk purchasing power shifting from individual nephrologists to centralized pharmacy committees in mature markets while fragmented home care channels demand direct-to-patient logistics capabilities.
- Dialysis Centers:In-center hemodialysis facilities in the US, Germany, and Japan capture deepest margin pools through bulk procurement and protocol-driven prescribing. Fresenius Kabi AG anchors recurring ketoanalogue sales alongside equipment service contracts, while B. Braun Melsungen AG sustains patient adherence programs across European and Asian networks.
- Home Care:Peritoneal dialysis expansion in China and India fragments prescribing authority and creates whitespace for direct-to-patient distribution models bypassing institutional procurement. Manufacturers must build dual-channel capabilities to serve both consolidated dialysis centers and dispersed home settings.
- Hospitals:Acute care settings initiate ketoanalogue therapy for pre-dialysis chronic kidney disease patients, with prescribing constrained by nephrology specialist availability in tier-2 and tier-3 cities.
- Specialty Clinics:Outpatient renal nutrition practices in urban India and China provide patient education and compliance support bundled with prescriptions.
Volume concentrates at Dialysis Centers. Home Care channels are expanding most quickly as peritoneal dialysis adoption rises.
Delivery Mode:
Route selection determines manufacturing complexity, with oral and enteral formulations qualifying under medical food or dietary supplement pathways in some jurisdictions while parenteral and intravenous routes trigger full pharmaceutical registration requirements.
- Oral:Swallowed tablets and capsules constitute the standard of care for ambulatory chronic kidney disease patients, with bioequivalence studies required by India's CDSCO and China's NMPA extending entry timelines for multinational manufacturers.
- Enteral:Tube-administered formulations serve hospitalized patients with swallowing dysfunction, particularly in Japanese geriatric facilities adopting enhanced delivery systems.
- Parenteral:Subcutaneous and intramuscular injections require sterile manufacturing capabilities and full drug registration, limiting supplier base to established pharmaceutical manufacturers.
- Intravenous:Hospital-administered infusions for acute metabolic management face stringent stability and compatibility testing under FDA and EMA guidelines.
Oral delivery dominates prescription volumes. Enteral administration is gaining share fastest among hospitalized geriatric populations.
Application:
Clinical indication shapes dosing protocols and reimbursement eligibility, with pre-dialysis and dialysis support applications qualifying for pharmaceutical coverage while renal transplantation adjunct use often falls under dietary supplement classification debates.
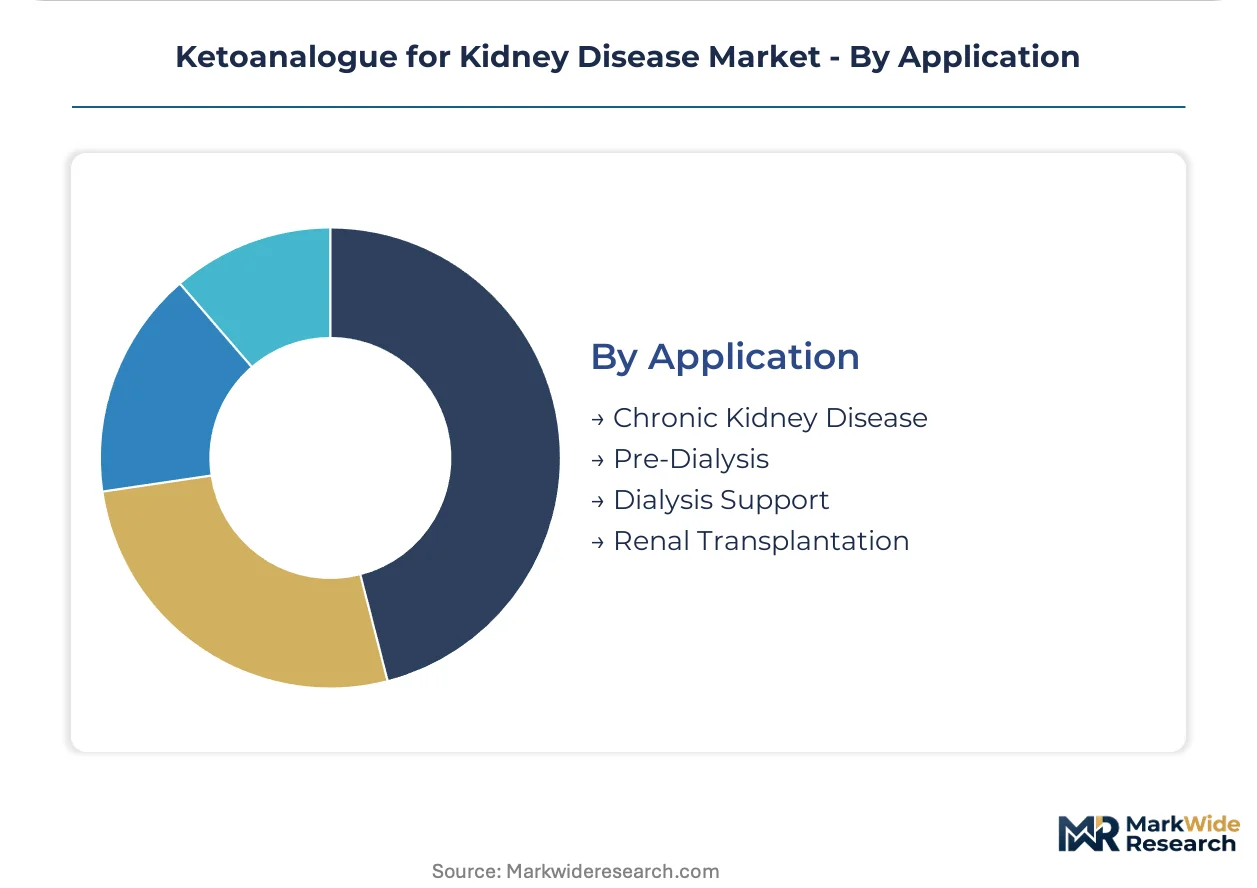
- Chronic Kidney Disease:Pre-dialysis patients with estimated glomerular filtration rates between 15-45 mL/min represent the addressable population for nitrogen-free ketoacid therapy to delay dialysis initiation. EMA renal therapeutic pathways and FDA orphan drug designations accelerate access for this indication in European member states and the US.
- Dialysis Support:Maintenance hemodialysis and peritoneal dialysis patients require ongoing ketoanalogue supplementation to preserve protein balance while minimizing urea generation. India's expanding dialysis infrastructure and China's peritoneal dialysis growth create concentrated volume opportunities.
- Pre-Dialysis:Early-stage intervention protocols in German and French nephrology practices emphasize nutritional management to slow disease progression.
- Renal Transplantation:Post-transplant metabolic support applications face classification uncertainty between drug and medical food status, altering distribution economics and prescriber access.
Chronic Kidney Disease captures the largest patient population. Dialysis Support applications are climbing the fastest as treatment infrastructure expands in India and China.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of nitrogen-free ketoacid derivatives concentrates in India and China, while consumption clusters in Germany, Japan, and the United States where dialysis infrastructure and reimbursement frameworks sustain prescription volumes.
United States
FDA orphan drug pathways accelerate market access for ketoanalogue formulations targeting chronic kidney disease populations. Dialysis center consolidation across Texas and Florida creates bulk procurement nodes that favor suppliers with dedicated clinical support teams. Integrated delivery networks in California and New York Metro increasingly centralize renal nutrition purchasing through hospital pharmacy committees.
Germany
EMA centralized marketing authorization procedures enable cross-border patient access for ketoanalogue therapies across European member states. REACH registration requirements for novel excipients tighten supply qualification timelines for manufacturers serving Bavarian and North Rhine-Westphalian dialysis networks. Fresenius Kabi AG anchors recurring sales through equipment service contracts spanning German renal care facilities.
India
CDSCO bioequivalence requirements and local trial mandates extend entry timelines for multinational manufacturers seeking market access. The PLI scheme for pharmaceuticals offers cost advantages for export-oriented production of nitrogen-free ketoacid derivatives in Gujarat and Maharashtra. Expanding dialysis infrastructure in Delhi-NCR and Karnataka creates concentrated volume opportunities for domestic and imported formulations.
China
NMPA imposes distinct bioequivalence and local trial requirements that shape registration timelines for ketoanalogue entrants. Peritoneal dialysis expansion in the Yangtze River Delta and Pearl River Delta fragments prescribing authority and creates whitespace for direct-to-patient distribution models. Home care channels bypass institutional procurement as patients seek alternatives to in-center hemodialysis.
Japan
PMDA oversight governs pharmaceutical registration for renal nutrition products entering Japanese markets. Pediatric and geriatric dialysis centers in Kanto and Kansai regions adopt microencapsulated liquid formulations with compliance data capture integrated into dosing devices. Outcome-linked reimbursement pilots compress the gap between clinical protocol and real-world patient adherence.
Ketoanalogue for Kidney Disease Market Competitive Landscape
Capital-heavy producers with integrated dialysis service infrastructure compete with asset-light pharmaceutical specialists focused on formulation development and regional distribution partnerships. The supplier base fragments across three tiers: multinational renal care conglomerates bundling equipment and nutrition products, mid-cap generic manufacturers leveraging cost-optimized production in India and China, and domestic specialists capturing share through prescriber relationships and compliance support programs. Dominant competitive moves include strategic partnerships with dialysis center chains and portfolio diversification into liquid and enteral dosage formats.
Within the multinational conglomerate tier, Fresenius Kabi AG and B. Braun Melsungen AG exemplify asset-heavy positioning through integrated renal care platforms. Among India-based specialists, Alniche Life Sciences Pvt. Ltd. and Steadfast Medishield Private Limited occupy positions shaped by domestic manufacturing advantages and prescriber network density. These named entities represent archetypes rather than exhaustive enumeration of active competitors.
| Leading Market Players |
|---|
| Alniche Life Sciences Pvt. Ltd. |
| Steadfast Medishield Private Limited |
| Fresenius Kabi AG |
| Ajanta Pharma Limited |
| Panacea Biotec |
| B. Braun Melsungen AG |
| La Renon Healthcare Pvt Ltd |
| Centaur Pharmaceuticals |
| RPG Life Sciences Limited |
| Others |
Supply & Pricing Matrix
Specialized organic synthesis chemists concentrated in Gujarat and Maharashtra create labor-cost differentials that widen pricing-tier spreads between premium branded ketoanalogues and economy generic alternatives.
Pricing Analysis
Margin tightening in economy-tier tablet formulations reflects CDSCO-mandated local bioequivalence trials that inflate entry costs for multinational suppliers. Three-tier pricing structure across premium, standard, and economy levels separates Fresenius Kabi's bundled dialysis contracts from mid-tier Indian generics and unbranded local alternatives. Price differentiation hinges on certification grade—FDA/EMA-approved products command substantial premiums over domestic-only registrations—and vertical integration into captive API production. Hospital pharmacy committees in US integrated delivery networks exhibit lowest price sensitivity due to protocol-driven prescribing, while peritoneal dialysis patients in China's home care channel drive hardest bargains through direct-to-patient procurement platforms.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Mumbai anchor hub-and-spoke patterns that feed dialysis center networks across Europe, Asia-Pacific, and South Asia. Active pharmaceutical ingredient synthesis draws from specialized contract manufacturers in India, China, and Switzerland, with nitrogen-free ketoacid derivative production resting on pyruvic acid and essential amino acid precursors. Single-source vulnerability concentrates in Swiss-German excipient suppliers facing REACH registration bottlenecks. Distribution runs through dialysis service conglomerates bundling equipment, consumables, and nutrition products under long-term service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ketoanalogue market sits in a formulation-transition phase as microencapsulated liquid delivery systems displace legacy tablet formats in geriatric and pediatric populations.
For Market Incumbents: Acquire direct-to-patient logistics capabilities to serve fragmented peritoneal dialysis home care channels in China and India. Defend against mid-tier Indian generic encroachment by deepening backward integration into API production under India's PLI scheme. Anchor recurring revenue through adherence-monitoring technology bundled with dosing devices. For New Entrants and Emerging Players: Telemedicine-integrated prescription platforms offer the lowest-friction entry path for reaching nephrology-underserved tier-2 and tier-3 Indian cities. Target reconstitutable powder sachets for peritoneal dialysis patients managing protein intake at home, where institutional procurement bypass creates whitespace. Build prescriber relationships through renal nutrition education programs that substitute for scarce specialist availability. For Investors and Strategic Acquirers: Re-rating potential sits with integrated renal care platforms given EMA centralized marketing authorization harmonization across European member states. Long-term viability favors asset-heavy operators bundling equipment service contracts with nutrition product recurring revenue. Monitor NMPA registration timeline compression in China as the inflection signal for market entry feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Microencapsulation Technology Licensing | PMDA-registered taste-masking formulations unlock Japanese geriatric reimbursement pilots. |
| Dual-Channel Distribution Buildout | Parallel institutional and direct-to-patient capabilities capture peritoneal dialysis expansion. |
| CDSCO Bioequivalence Investment | Local trial infrastructure accelerates multinational access to India's dialysis volume growth. |
| Adherence Data Platform Integration | Outcome-linked reimbursement pilots in German and Japanese nephrology practices favor connected devices. |
| PLI Scheme Manufacturing Footprint | Export-oriented API production in Gujarat and Maharashtra lowers cost positions for global supply. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with nephrology specialists, dialysis center procurement managers, regulatory affairs leads at multinational manufacturers, and formulary directors at US integrated delivery networks. Bottom-up prescription volume modeling triangulated against top-down market sizing from EMA centralized procedure databases, FDA orphan drug designations, CDSCO approval records, and NMPA registration filings. Primary fieldwork validated dosing protocol variations across German, Japanese, Indian, and Chinese clinical settings.
Data-stream reconciliation across patient population estimates, treatment penetration rates, and per-patient annual consumption yielded volume and value outputs across the projection horizon. Segmentation dimensions modeled include formulation type, end-use setting, delivery mode, and application indication, with regional regulatory clusters capturing FDA, EMA, CDSCO, NMPA, and PMDA pathway differences. CAGRs derived from log-linear trend fitting adjusted for peritoneal dialysis adoption curves and dialysis center consolidation patterns.
Inputs from regulatory databases and trade customs were available through the study window; gaps in real-time peritoneal dialysis patient registries introduce uncertainty bands around home care channel projections. Forecasts reflect documented assumptions regarding reimbursement stability and classification status between drug and medical food designations. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nephrology
Global Nephroblastoma Treatment Market
Nephrology
Renal Stent Market
Nephrology
US Dialysis Centers Market
Nephrology
Kidney Fibrosis Treatment Market
Nephrology
Global Hepatorenal Syndrome Treatment Market
Nephrology
Hollow Fiber Dialyzers Market
Nephrology
Complement 3 Glomerulopathy (C3G) Treatment Market
Nephrology
Membranous Nephropathy Treatment Market
Nephrology
Hemodialysis Services Market
Nephrology
US Hemodialysis and Peritoneal Dialysis Market
Nephrology
ICU-Acquired Acute Kidney Treatment Market
Nephrology
Global Dialyzer Market
Nephrology
Chronic Kidney Disease Market
Nephrology
Aldosterone-Renin Screening Market
Nephrology
Renal Cell Carcinoma Market
Nephrology
Radiation Nephropathy Treatment and Management Market