
 China Spinal Surgery Devices Market | 2026-2036
China Spinal Surgery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
China Spinal Surgery Devices Market Outlook
Multi-source procurement for titanium alloy rods and pedicle screw systems is shifting from imported single-source contracts toward dual domestic-foreign supplier arrangements. Medtronic PLC leverages its established distribution infrastructure to sustain premium positioning in tier-1 hospital accounts. Beijing Fule Science & Technology anchors its competitive stance through backward integration into raw titanium processing. Weigao Orthopaedic dominates Shandong province through direct sales teams that control regional procurement channels.
Spinal surgery devices comprise implantable hardware and associated instrumentation designed to stabilize vertebral segments, restore alignment, or decompress neural elements, typically manufactured from titanium alloys meeting ASTM F136 standards for surgical implant applications. These systems serve to treat degenerative disc disease, spinal deformities, and traumatic fractures through mechanical fixation and biological fusion promotion. Minimally invasive surgery systems command expanding shelf space as hospitals prioritize reduced tissue disruption and shorter length of stay metrics. Titanium material grades retain the dominant margin pool due to osseointegration performance requirements and NMPA biocompatibility testing protocols. Complex surgery instrumentation represents the fastest-growing surgery type segment as tertiary hospitals build capability for deformity correction and revision procedures.
NMPA medical device registration regulations and GB standards for surgical implants shape product entry timelines and clinical trial obligations for both domestic and imported devices. China's dual carbon goals and MEE environmental compliance requirements are forcing titanium foundries and polymer processors to upgrade emissions control systems, adding cost layers to supply chains. Stakeholders must monitor NMPA draft guidance on patient-specific implant customization pathways and assess whether in-house 3D printing investments align with evolving quality management system expectations.
Market Dynamics
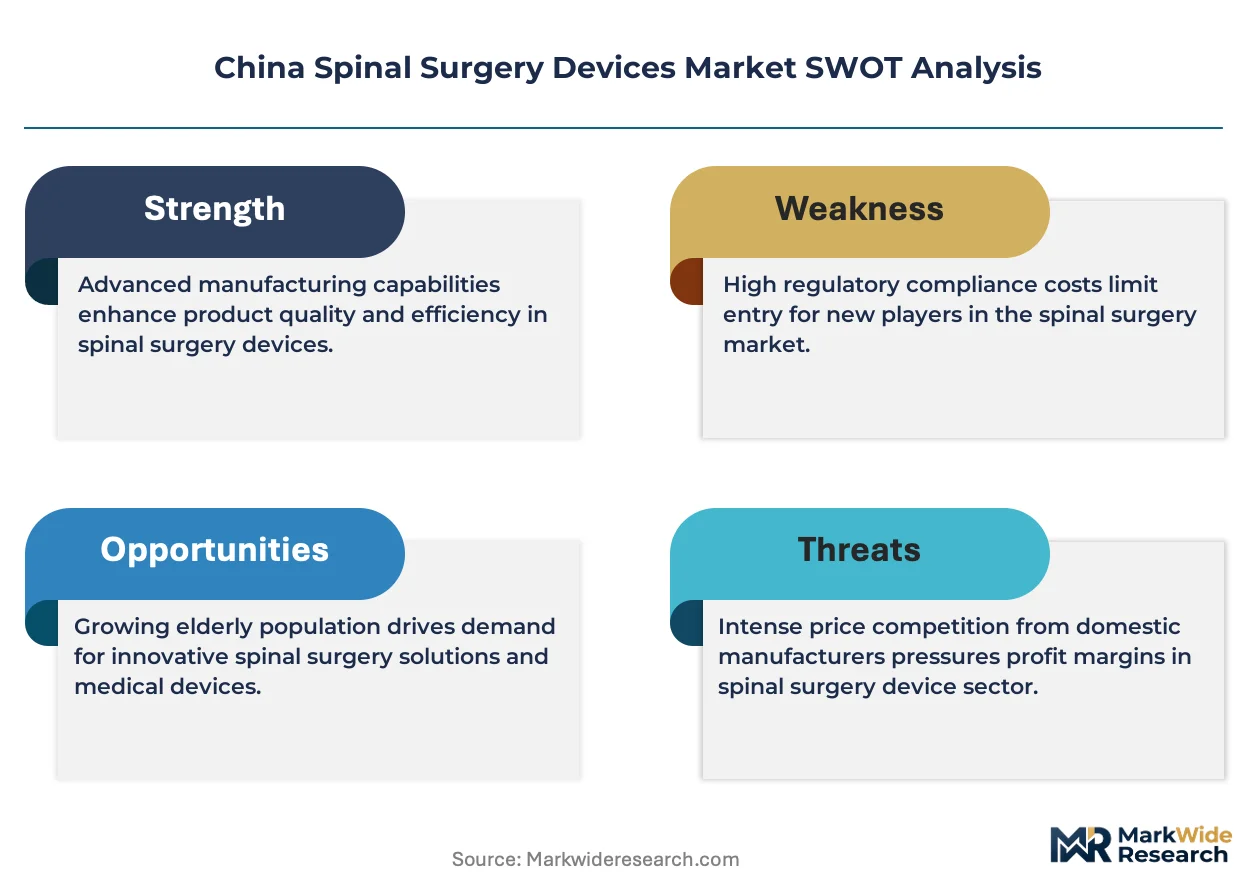
NMPA's tightened medical device classification rules and revised implant registration requirements are compressing product entry timelines while forcing manufacturers toward captive titanium processing capabilities.
Growth Catalysts
- Dual carbon goals compliance:MEE environmental mandates are accelerating foundry consolidation and pushing surviving suppliers toward premium-grade ASTM F136 titanium production that commands higher reimbursement rates in tier-3 hospitals.
- Minimally invasive surgery systems:Reduced tissue disruption protocols are electrifying demand from provincial capital hospitals seeking shorter length-of-stay metrics and competitive differentiation in spinal fusion programs.
- Patient-specific implant customization:NMPA draft guidance on 3D-printed spinal hardware is opening regulatory pathways for domestic manufacturers to capture revision surgery volumes previously served by imported legacy systems.
Market Restraints
- Titanium alloy input volatility:GB standards-compliant surgical-grade titanium sponge supply concentrates in limited domestic smelters, exposing device manufacturers to price swings and qualification delays.
- Biocompatibility testing bottlenecks:NMPA's expanded clinical trial obligations for novel implant geometries extend registration timelines by 18-24 months, freezing capital in development pipelines.
- Polymer-based motion preservation:Artificial disc replacement systems using PEEK-OPTIMA and other biomaterials threaten fusion hardware volumes in younger patient demographics.
Strategic Opportunities
- Central China expansion:Hubei and Hunan province hospital networks remain underpenetrated by advanced deformity correction instrumentation, offering first-mover positioning for complex surgery capability builders.
- Digital surgical planning integration:Convergence of preoperative 3D modeling software with patient-matched implant design is creating service revenue streams beyond hardware margins.
- Direct provincial procurement channels:Shandong and Jiangsu province centralized tendering platforms are opening to dual-source domestic-foreign supplier arrangements that bypass traditional distribution markups.
Industry Challenges
- Spinal deformity surgery specialization:Tertiary hospitals face acute shortages of fellowship-trained surgeons capable of executing complex three-column osteotomies and revision constructs.
- Legacy quality management system retrofitting:NMPA's evolving expectations for patient-specific implant traceability force manufacturers to rebuild ERP and production documentation infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Spinal Surgery Devices Market |
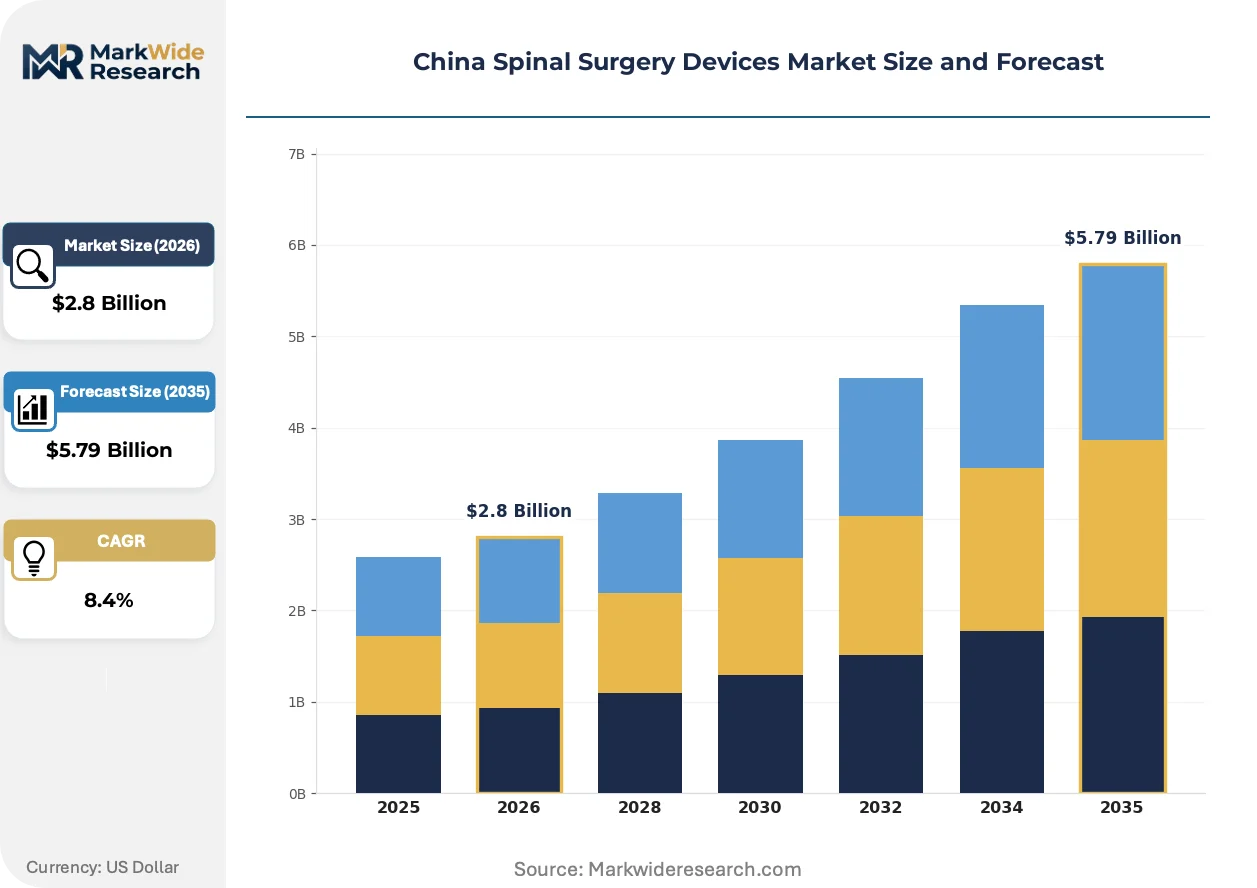
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
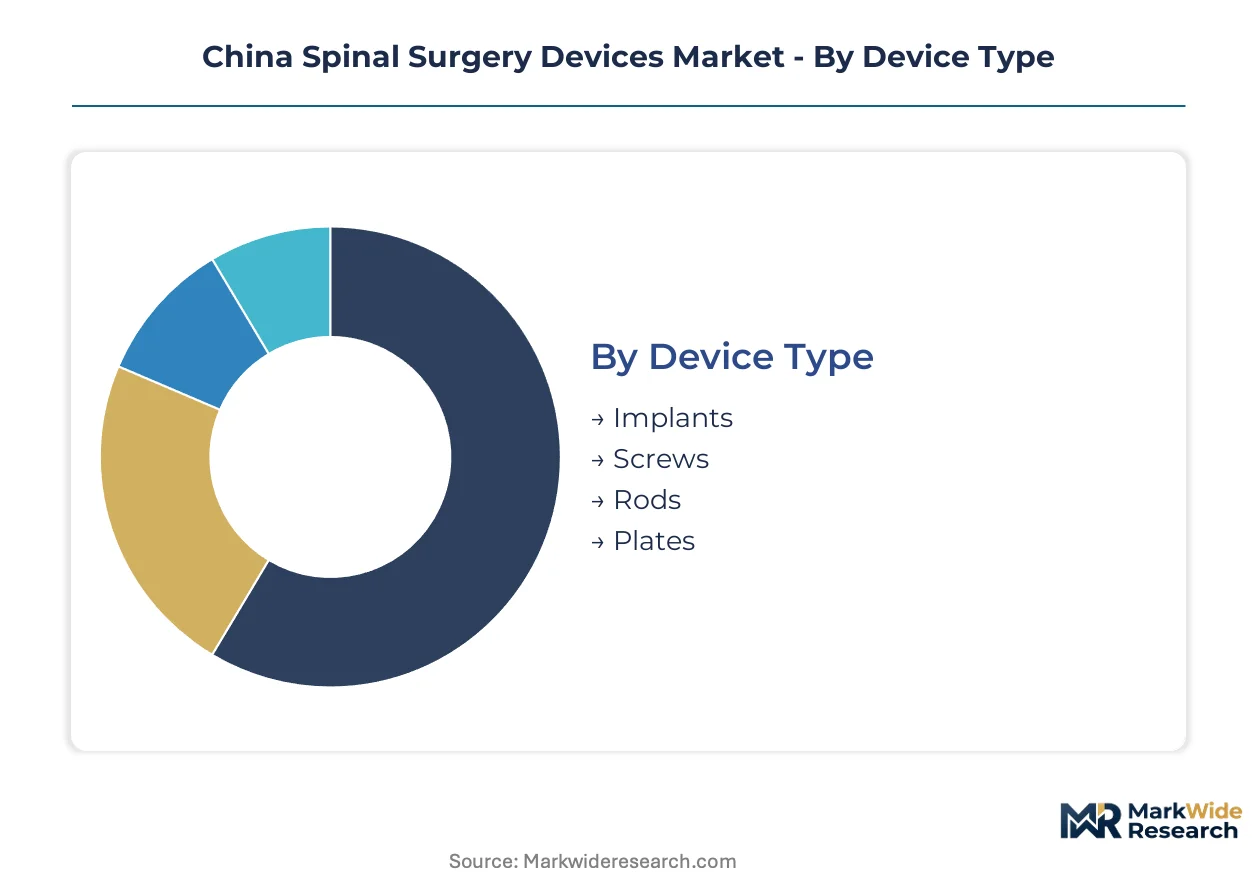
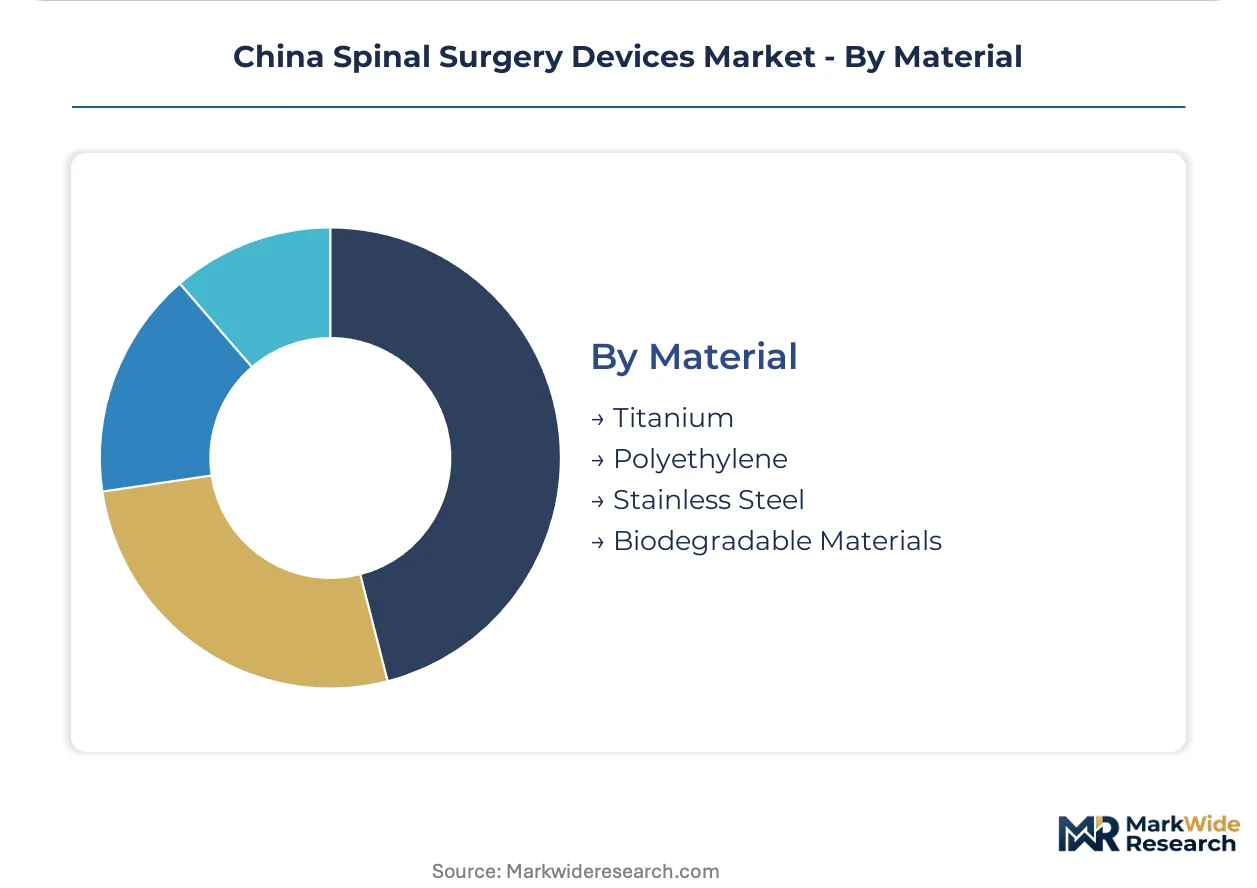
| Segmentation | Device Type: Implants, Screws, Rods, Plates Surgery Type: Minimally Invasive Surgery, Open Surgery, Complex Surgery, Elective Surgery End User: Hospitals, Outpatient Clinics, Rehabilitation Centers, Specialty Clinics Material: Titanium, Polyethylene, Stainless Steel, Biodegradable Materials |
| Companies Covered | Medtronic PLC, Stryker Corporation, Johnson & Johnson, Beijing Fule Science & Technology, AK Medical, Chunlizhengda Medical Instruments, Globus Medical, Weigao Orthopaedic, Sanyou Medical, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Spinal Surgery Devices Market Strategic Shifts
Robotic-assisted navigation and additive manufacturing are compressing the gap between standard implant catalogs and anatomically matched hardware, while procurement centralization restructures how provincial hospital networks source spinal systems.
Robot-guided pedicle screw placement systems are electrifying surgical accuracy benchmarks in tier-1 hospitals. Shanghai and Beijing tertiary centers are adopting these platforms to reduce revision rates and justify premium pricing. The technology is electrifying competitive differentiation as hospitals publish outcome data to attract complex deformity referrals.
NMPA's revised medical device classification rules are resegmenting registration pathways by risk tier. Class III implantable hardware now faces mandatory clinical trials conducted within China, eliminating foreign data reliance. Domestic manufacturers with established GB standards compliance infrastructure are capturing accelerated approval timelines.
Provincial centralized procurement platforms are consolidating purchasing authority previously dispersed across individual hospital supply chains. Jiangsu and Shandong health commissions now negotiate volume-based contracts directly with manufacturers. This concentration is visible in Yangtze River Delta cluster hospitals, where multi-year framework agreements are displacing spot purchasing.
China Spinal Surgery Devices Market Segmentation
Segmentation in China's spinal surgery devices market reveals how procurement authority, surgical capability, and material certification requirements stratify demand across hospital tiers and geographic clusters. Understanding these divisions exposes where NMPA registration investments yield highest returns and which patient populations remain underserved by current product configurations.
Device Type:
Procurement volume splits according to whether hospitals perform fusion, fixation, or hybrid stabilization procedures.
- Implants:Interbody fusion cages and vertebral body replacement devices machined from ASTM F136 titanium dominate tier-3 hospital purchasing. Shanghai and Jiangsu province networks concentrate demand as these facilities expand spinal fusion programs under NMPA's tightened classification rules.
- Screws:Pedicle screw systems with polyaxial heads enable multi-segment fixation in deformity correction. Provincial capital hospitals prioritize dual-source domestic-foreign supplier arrangements for these high-rotation consumables.
- Rods:Titanium alloy rods connect screw anchors into load-bearing constructs. Jiangsu manufacturing hubs supply raw material to domestic device manufacturers qualifying under revised GB standards.
- Plates:Anterior cervical and thoracolumbar plating systems address trauma and degenerative pathologies. NMPA biocompatibility testing protocols extend registration timelines for novel plate geometries.
Implants lead volumes today; screws are gaining share fastest as minimally invasive surgery adoption accelerates instrument rotation rates.
Surgery Type:
Hospital reimbursement tiers and surgeon training availability determine which procedure categories absorb capital equipment investment.
- Minimally Invasive Surgery:Percutaneous screw placement and tubular retractor systems reduce tissue disruption. Yangtze River Delta cluster hospitals prioritize these platforms to compress length-of-stay metrics and attract patient referrals.
- Complex Surgery:Three-column osteotomies and revision constructs demand advanced deformity correction instrumentation. Tertiary hospitals in Beijing and Shanghai build this capability to capture cases beyond provincial hospital reach.
- Open Surgery:Traditional posterior approaches retain dominance in tier-2 hospitals with limited navigation infrastructure. These procedures consume standard pedicle screw and rod inventory at higher volume but lower per-case value.
- Elective Surgery:Scheduled degenerative disc disease interventions concentrate in tier-3 hospitals expanding dedicated spinal service lines. NMPA draft guidance on patient-specific implants targets this procedural category.
Open surgery retains the highest procedure count; complex surgery climbs the fastest as fellowship-trained specialists concentrate in tertiary centers.
End User:
Facility licensing tier and procurement autonomy shape which device configurations reach which patient access points.
- Hospitals:Tier-1, tier-2, and tier-3 hospitals hold divergent procurement authority. Tier-3 facilities in provincial capitals negotiate directly with manufacturers under centralized tendering platforms in Jiangsu and Shandong.
- Outpatient Clinics:Ambulatory surgical centers perform limited discectomy and decompression procedures. These sites source disposable instrument kits rather than capital-intensive navigation platforms.
- Rehabilitation Centers:Post-surgical recovery facilities do not implant hardware but influence referral patterns back to surgical centers. Device manufacturers cultivate relationships here for downstream case capture.
- Specialty Clinics:Orthopedic-focused private practices concentrate in urban cores. These entities lack NMPA Class III implant procurement licenses and refer surgical cases to affiliated hospitals.
Hospitals absorb the dominant procurement value; outpatient clinics are expanding most quickly as same-day surgery protocols proliferate.
Material:
Biocompatibility certification grade and environmental compliance cost structure differentiate input sourcing strategies.
- Titanium:ASTM F136 surgical-grade titanium sponge supplies concentrate in limited domestic smelters. MEE environmental mandates force foundry consolidation, pushing surviving suppliers toward premium-grade production.
- Polyethylene:PEEK-OPTIMA and similar polymers enable motion preservation in artificial disc replacement. These biomaterials threaten fusion hardware volumes in younger patient demographics.
- Stainless Steel:Lower-cost alternative for trauma fixation in budget-constrained tier-2 hospitals. NMPA registration requirements for surgical implants apply equally regardless of base material.
- Biodegradable Materials:Experimental magnesium and polymer composites for temporary fixation. NMPA clinical trial obligations for novel materials extend development timelines substantially.
Titanium commands the dominant revenue pool today; polyethylene shows the steepest expansion trajectory as motion preservation gains clinical acceptance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NMPA's tightened registration requirements are compressing product entry timelines while MEE environmental mandates force titanium foundry consolidation. Domestic manufacturers with captive raw material processing capabilities capture cost-of-compliance advantages as imported devices face extended clinical trial obligations.
Shanghai
Tier-1 hospitals in Shanghai anchor demand for robotic-assisted navigation platforms and patient-matched implant systems. NMPA draft guidance on 3D-printed spinal hardware accelerates regulatory pathway development for tertiary centers. The Yangtze River Delta cluster concentrates minimally invasive surgery adoption as hospitals compete on length-of-stay metrics.
Jiangsu Province
Provincial capital hospitals in Nanjing and Suzhou expand spinal fusion programs under centralized tendering platforms. GB standards-compliant titanium rod and pedicle screw manufacturing clusters supply raw material to domestic device producers. Dual-source domestic-foreign supplier arrangements displace traditional distribution markups in volume-based procurement negotiations.
Beijing
Tertiary hospitals in Beijing build complex deformity correction capability to capture revision surgery volumes beyond provincial hospital reach. NMPA's revised medical device classification rules mandate China-conducted clinical trials for Class III implantable hardware. Fellowship-trained surgeon concentration supports three-column osteotomy program expansion.
Shandong Province
Direct sales teams control regional procurement channels through centralized health commission tendering. Weigao Orthopaedic anchors competitive positioning in this market through backward integration into distribution infrastructure. Provincial hospital networks prioritize standard pedicle screw and rod inventory for open surgery dominance.
Sichuan-Chongqing
Western China hospital networks remain underpenetrated by advanced deformity correction instrumentation. Tier-3 facilities in Chengdu and Chongqing expand spinal service lines as patient referral patterns concentrate in regional hubs. MEE environmental compliance costs for titanium processing limit supplier entry into this geographic expansion corridor.
China Spinal Surgery Devices Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue patient-specific customization pathways through additive manufacturing investments. Market structure stratifies across three tiers: multinational corporations with legacy distribution infrastructure, domestic champions with captive titanium processing, and regional specialists controlling provincial procurement channels. Two dominant competitive moves define current positioning: backward integration into raw material qualification and direct engagement with centralized provincial tendering platforms.
Among multinational anchors, Medtronic PLC and Stryker Corporation exemplify premium-tier positioning through established tier-1 hospital relationships. Beijing Fule Science & Technology represents domestic vertical integration archetypes with upstream titanium processing control. Weigao Orthopaedic occupies the regional dominance position through Shandong province channel capture.
| Leading Market Players |
|---|
| Medtronic PLC |
| Stryker Corporation |
| Johnson & Johnson |
| Beijing Fule Science & Technology |
| AK Medical |
| Chunlizhengda Medical Instruments |
| Globus Medical |
| Weigao Orthopaedic |
| Sanyou Medical |
| Others |
Value Chain & Pricing Dynamics
A certification-grade divergence between ASTM F136 surgical titanium and commodity-grade alternatives manifests in both reimbursement rates and raw material sourcing configurations. Tier-3 hospitals in provincial capitals command premium pricing for NMPA-registered Class III implants while tier-2 facilities absorb standard-grade inventory through centralized tendering platforms.
Pricing Analysis
Distributor margins in traditional supply chains face compression as Jiangsu and Shandong health commissions negotiate volume-based contracts directly with manufacturers. Pricing stratifies across premium, standard, and economy tiers based on NMPA registration tier and titanium grade certification. Cost compression in the standard tier intensifies because domestic manufacturers with captive titanium processing capture compliance cost advantages. Tier-2 hospital procurement committees demonstrate highest price sensitivity; tier-1 tertiary centers prioritize clinical outcome metrics over unit cost.
Supply Chain Analysis
Direct-to-hospital channels handle tier-3 facility demand in Yangtze River Delta cluster markets. Geographic supply concentration centers on Jiangsu province titanium rod manufacturing hubs, Shandong pedicle screw assembly facilities, and limited domestic smelters producing GB standards-compliant surgical-grade titanium sponge. Raw material dependencies include ASTM F136 titanium sponge, polyaxial screw head components, and PEEK-OPTIMA polymer stock. Single-source vulnerability in certified titanium sponge supply exposes device manufacturers to qualification delays. Distribution runs through provincial centralized tendering platforms that displace traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's spinal surgery devices market functions as a stable compounder anchored by irreversible demographic aging and degenerative disease prevalence. NMPA regulatory tightening creates sustainable competitive moats for compliant domestic manufacturers.
For Market Incumbents: Anchor market position through backward integration into raw titanium processing capabilities that satisfy MEE environmental mandates and GB standards. Deepen hospital system partnerships in tier-3 provincial capitals where spinal fusion program expansion concentrates procurement authority. Defend against PEEK-OPTIMA motion preservation systems by emphasizing titanium osseointegration performance in revision surgery populations.
For New Entrants and Emerging Players: Launch via digital surgical planning integration services that attach to patient-matched implant design revenue streams beyond hardware margins. Target Sichuan-Chongqing western China corridors where advanced deformity correction instrumentation remains underpenetrated and tier-3 facility expansion creates first-mover positioning. Penetrate through NMPA draft guidance pathways for 3D-printed spinal hardware that accelerate domestic manufacturer approval timelines.
For Investors and Strategic Acquirers: Consolidation pressure builds where MEE environmental compliance costs force titanium foundry consolidation and eliminate subscale domestic competitors. Five-to-ten year viability favors manufacturers with captive raw material qualification infrastructure and established provincial tendering platform relationships. Acquisition target archetype: regional specialists controlling Shandong or Jiangsu procurement channels with backward integration into distribution. Signal to watch: NMPA final guidance on patient-specific implant customization pathways that would validate additive manufacturing capital deployment.
| Strategic Initiative | Industry Significance |
|---|---|
| NMPA Class III Registration Investment | Captures accelerated approval timelines under revised medical device classification rules. |
| Backward Integration into Titanium Processing | Absorbs MEE environmental compliance cost layers that eliminate non-integrated competitors. |
| Provincial Tendering Platform Engagement | Bypasses distributor markups through direct volume-based contract negotiation with health commissions. |
| Digital Surgical Planning Integration | Creates service revenue streams beyond hardware margins through preoperative 3D modeling software. |
| Patient-Specific Implant Customization Pathway | Opens regulatory channels for 3D-printed hardware in revision surgery volumes. |
Study Parameters
Multiple input streams — hospital procurement database analysis, titanium supply chain mapping, and NMPA regulatory filing review — were reconciled against primary interviews with spinal surgeons, biomedical engineers, hospital purchasing committee members, and GPO contracts managers. Secondary validation drew from NMPA medical device registration databases, provincial health commission tendering records, MEE environmental compliance disclosures, and GB standards technical documentation. Bottom-up demand modeling by device type and hospital tier cross-referenced top-down market sizing through the analysis window.
Historical shipment data and expert panel input on NMPA registration timeline expectations shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include device type, surgery type, hospital tier, and material grade certification. CAGRs were derived from procedure volume trajectories, reimbursement rate evolution, and titanium input cost assumptions. Forecast inputs incorporated fellowship-trained surgeon supply growth and minimally invasive surgery adoption curves in provincial capital hospitals.
Forecast precision tightens around the base case; tail outcomes carry wider variance under NMPA regulatory acceleration or MEE environmental mandate enforcement shifts. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Outsourced Orthopedic Manufacturing Market
Orthopedic Devices
Cartilage Repair Market
Orthopedic Devices
High Energy Shockwave Therapy Units Market
Orthopedic Devices
Wrist Replacement Orthopedic Devices Market
Orthopedic Devices
Japan Spinal Surgery Devices Market
Orthopedic Devices
Orthopedic Joint Reconstruction Market
Orthopedic Devices
Distal Compression Plates Market
Orthopedic Devices
Patient Lifts Market
Orthopedic Devices
Orthopedic Artificial Bone Defect Repair Materials Market
Orthopedic Devices
Podiatry Laser Market
Orthopedic Devices
USA Spinal Surgery Devices Market
Orthopedic Devices
Europe Knee Cartilage Repair Market
Orthopedic Devices
Global Artificial Joints Market
Orthopedic Devices
Europe Orthopedic Navigation Systems Market
Orthopedic Devices
Femoral Head Prostheses Market
Orthopedic Devices
Global Patient Lateral Transfer Devices Market