
 Hemodialysis Consumables Market | 2026-2036
Hemodialysis Consumables Market Size, Share, and Industry Trends Forecast 2026-2036
Hemodialysis Consumables Market Insights
The capital-intensity gap between integrated dialyzer manufacturers and standalone tubing suppliers is collapsing as membrane chemistry becomes the decisive cost driver. Fresenius Medical Care leverages captive polymer sourcing and in-house dialyzer production to sustain margin structures that pure-play competitors cannot match. Baxter International anchors its position through end-to-end bloodline systems, while B. Braun differentiates via automated manufacturing lines that reduce lot-to-lot variability in high-volume tubing sets.
Hemodialysis consumables comprise single-use sterile components—dialyzers with hollow-fiber membranes typically 180-220 microns in inner diameter, blood tubing sets, central venous catheters, and dialysis filters—engineered to extract uremic toxins while maintaining hematological compatibility during extracorporeal circulation. Polysulfone and polyethersulfone membranes now dominate dialyzer architecture due to superior biocompatibility and ultrafiltration precision compared to earlier cellulose-based materials. Blood tubing sets represent the highest-volume segment with stable replacement economics, while online hemodiafiltration technology commands premium positioning as clinics upgrade from conventional modalities. Portable dialysis systems remain nascent but concentrate venture-stage investment as home care channels expand reimbursement eligibility.
FDA 510(k) clearance requirements and ISO 10993 biocompatibility standards govern US market access, while the EU Medical Device Regulation imposes stricter clinical evidence thresholds for dialyzer reclassification. Japan's PMDA maintains distinctive polymer master file protocols that favor domestic membrane suppliers. Stakeholders must monitor how CMS bundled payment adjustments and comparable national pricing mechanisms in Germany and Japan reshape procurement incentives between in-center and home dialysis modalities.
Market Dynamics
Polymer membrane chemistry has displaced capital equipment as the decisive cost driver in dialyzer manufacturing, collapsing the margin advantage once held by integrated producers over component specialists.
Growth Catalysts
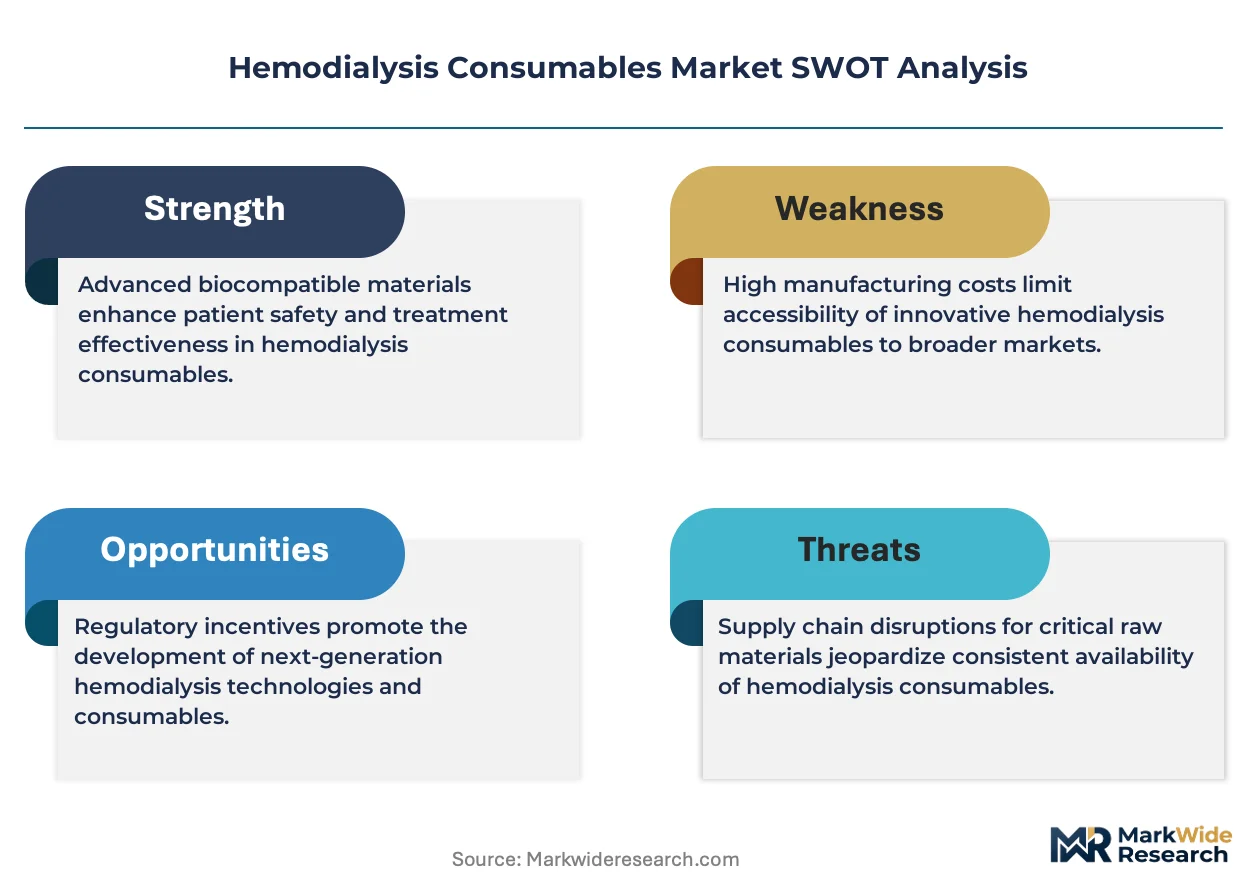
- CMS bundled payment expansion:Reimbursement rule changes in the United States now cover home hemodialysis training and equipment, redirecting patient volume from in-center facilities.
- Polysulfone membrane biocompatibility:Superior ultrafiltration precision and reduced complement activation drive clinic upgrading from cellulose-based dialyzers.
- Japan polymer innovation clusters:Domestic membrane suppliers anchored in Osaka and Tokyo sustain regional supply security and accelerate regulatory approval cycles.
Market Restraints
- Polymer feedstock concentration:Specialized polysulfone and polyethersulfone resin supply concentrates among three European chemical producers, exposing dialyzer manufacturers to input cost volatility.
- PMDA master file rigidity:Japan's distinctive polymer documentation protocols favor incumbent domestic suppliers and extend market access timelines for foreign membrane entrants.
- Peritoneal dialysis substitution:Continuous ambulatory peritoneal dialysis captures incident ESRD patients in markets with limited vascular access infrastructure, compressing hemodialysis consumables addressable demand.
Strategic Opportunities
- Home dialysis channel expansion:Portable system development targets reimbursement-eligible patients in Germany seeking to avoid thrice-weekly clinic visits.
- Online hemodiafiltration upgrade cycles:Clinics in France and Italy replace conventional modalities with high-volume convection therapies requiring premium filter sets.
- EU MDR clinical evidence pathways:Stricter biocompatibility documentation requirements for dialyzer reclassification create first-mover advantage for manufacturers with established ISO 10993 testing infrastructure.
Industry Challenges
- Membrane fabrication talent scarcity:Hollow-fiber spinning expertise concentrates among retiring engineers in Japan and Germany, constraining quality-assured production scale-up.
- 510(k) clearance timeline compression:FDA submission backlogs for novel dialyzer geometries extend time-to-revenue for iterative product improvements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hemodialysis Consumables Market |
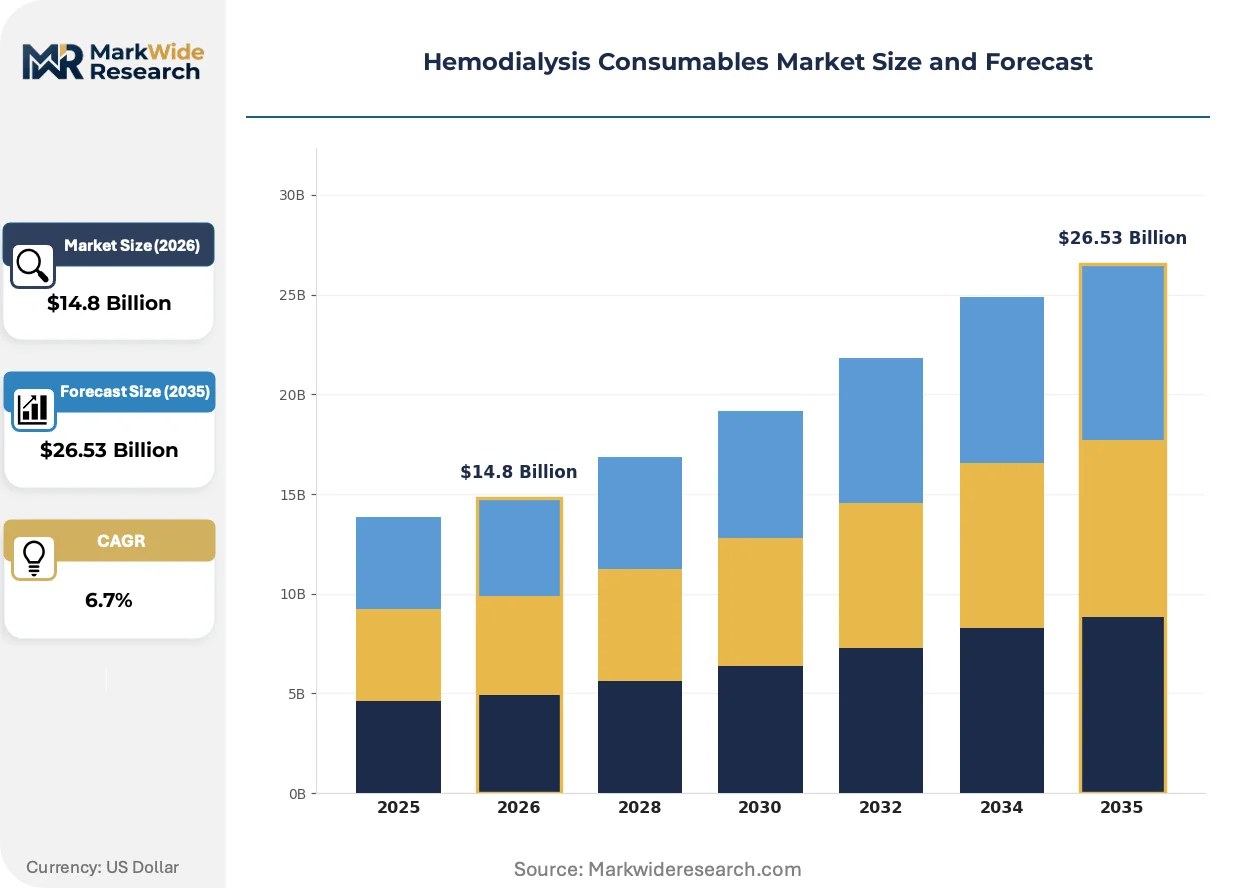
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
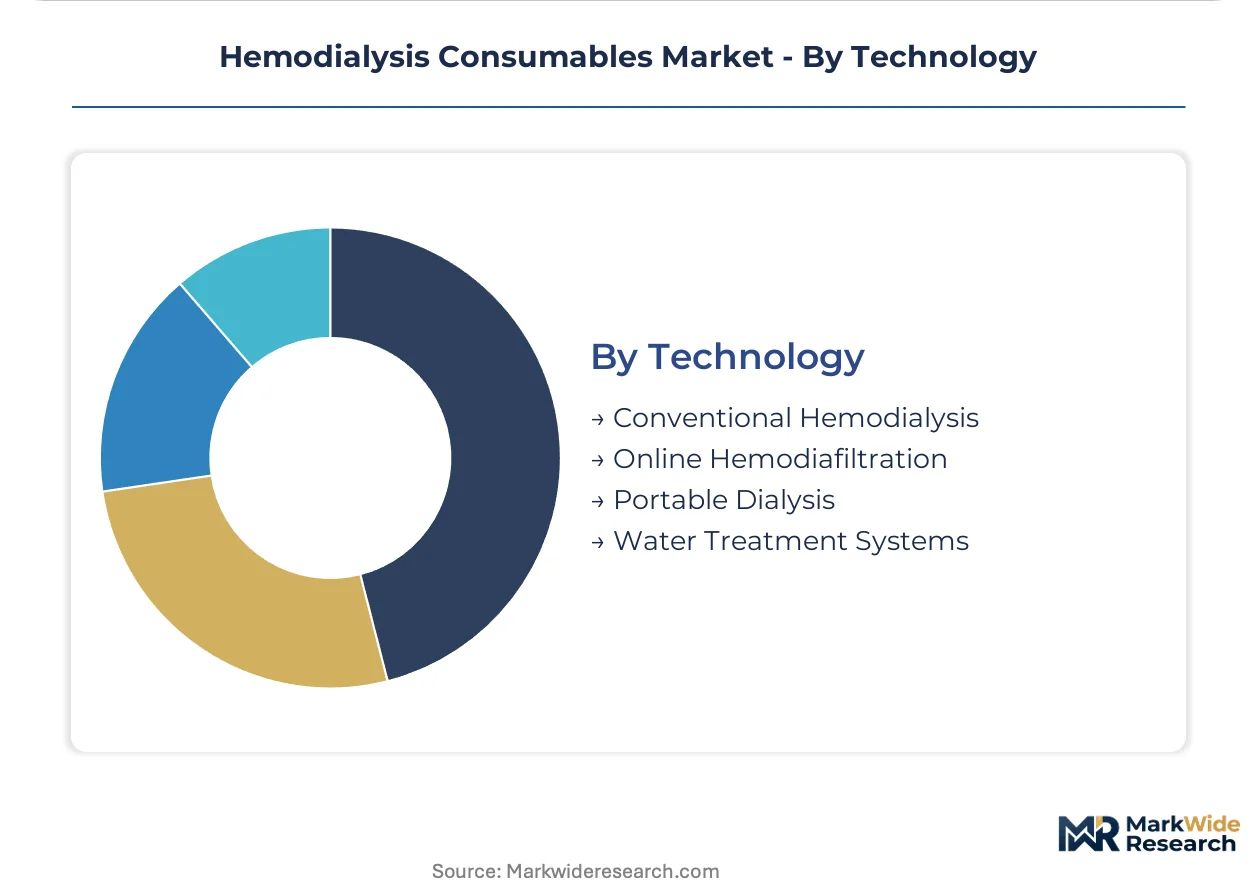
| Segmentation | Product Type: Dialyzers, Blood Tubing Sets, Catheters, Dialysis Filters End User: Hospitals, Clinics, Home Care, Long-term Care Facilities Material: Polycarbonate, Polyethylene, PVC, Polysulfone Technology: Conventional Hemodialysis, Online Hemodiafiltration, Portable Dialysis, Water Treatment Systems |
| Companies Covered | Fresenius Medical Care, Baxter International, B. Braun, Nipro Corporation, Nikkiso Co., Ltd., Asahi Kasei Corporation, Toray Industries, JMS Co., Ltd., Rockwell Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hemodialysis Consumables Market Trends and Innovations
Extracorporeal circuit design is converging with connected health infrastructure, embedding sensors and data transmission into disposable components previously treated as passive commodity items.
Synthetic polymer membranes is supplanting modified cellulose architectures in dialyzer construction. Polysulfone and polyethersulfone formulations now dominate new clinic procurement in Western Europe and North America. This materials transition is compressing the addressable market for regenerated cellulose suppliers and elevating polymer chemistry capabilities to core competitive differentiation.
EU Medical Device Regulation reclassification requirements are extending clinical evidence obligations for dialyzer manufacturers seeking CE marking renewal. Substantial equivalence pathways have narrowed, forcing additional biocompatibility studies. German and Italian notified bodies are processing submissions most aggressively, while smaller member state regulators lag, fragmenting market access timelines across the single market.
Consolidated purchasing by large dialysis clinic operators is compressing supplier margins and demanding unbundled component pricing previously embedded in system contracts. Blood tubing set procurement now separates from dialyzer sourcing in United States and German markets. This specification fragmentation favors manufacturers with standalone certification for individual component categories rather than integrated system providers.
Hemodialysis Consumables Market Segmentation
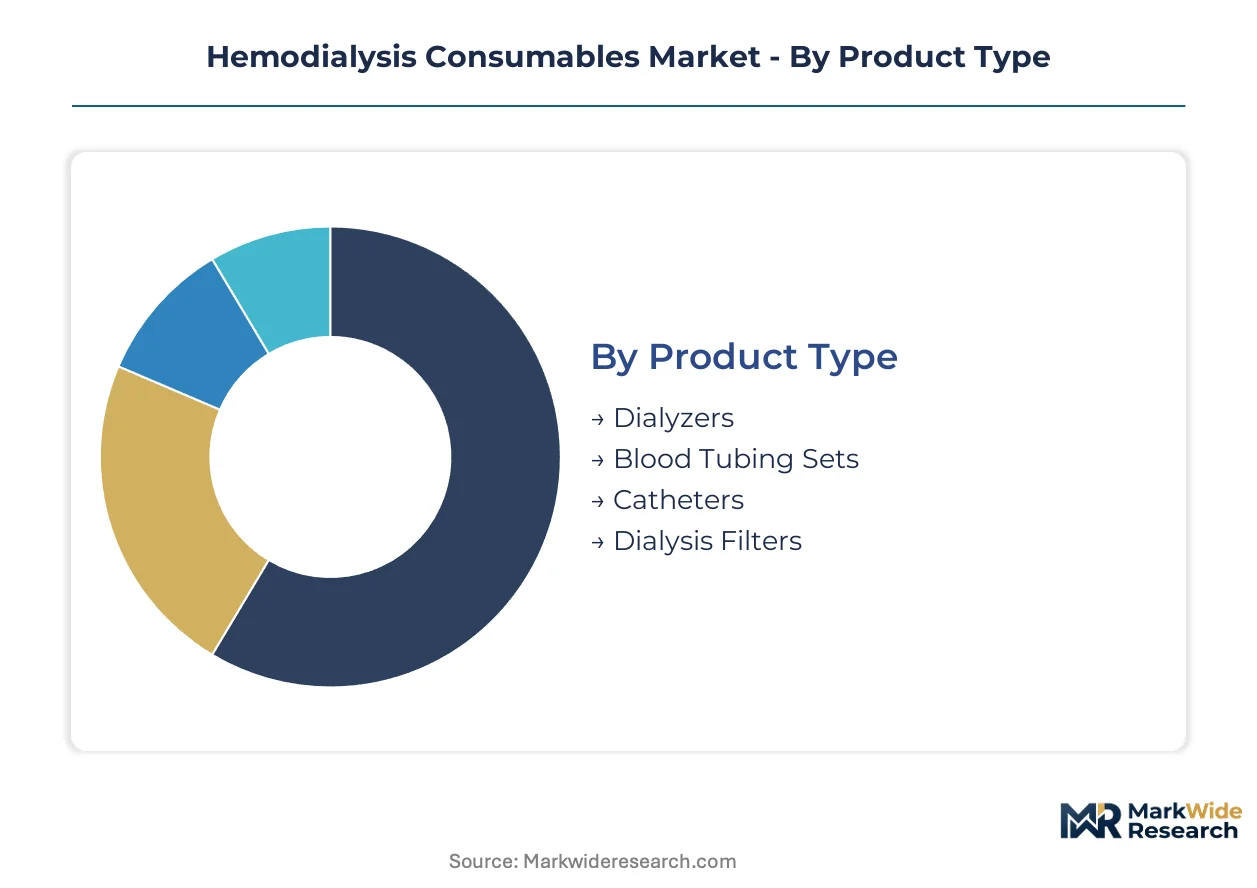
Segmentation in hemodialysis consumables reveals how procurement authority, reimbursement pathways, and clinical workflow requirements reshape vendor priorities. Material chemistry and technology modality now determine margin capture more than volume scale alone.
Product Type:
Margin pools concentrate in membrane-intensive components where polymer chemistry expertise creates pricing power and regulatory defensibility.
- Dialyzers:Hollow-fiber membrane devices with 180-220 micron inner diameters extract uremic toxins during extracorporeal circulation. Demand clusters in Japan and Germany where polymer innovation clusters from Osaka to Frankfurt sustain premium positioning for high-flux variants.
- Blood Tubing Sets:Sterile single-use circuits connecting patient vascular access to the dialyzer represent the highest-volume segment with stable replacement economics. Procurement in United States markets increasingly separates tubing from dialyzer sourcing, compressing bundled pricing power.
- Catheters:Central venous access devices for acute or transitional dialysis support.
- Dialysis Filters:Online hemodiafiltration-compatible membranes commanding premium positioning in French and Italian clinic upgrade cycles.
Dialyzers hold installed capacity. Dialysis filters are rotating up the share rankings.
End User:
Volume concentration follows reimbursement eligibility and capital infrastructure availability, with channel shifts altering procurement specifications.
- Hospitals:Acute care settings managing incident ESRD cases and complex comorbidities requiring intensive monitoring. United States hospital procurement increasingly favors integrated system contracts covering dialyzer, tubing, and monitoring interface.
- Clinics:Dedicated dialysis centers conducting thrice-weekly maintenance sessions for prevalent ESRD populations. German clinic operators consolidate purchasing through multi-site agreements demanding unbundled component transparency.
- Home Care:Patient-managed dialysis enabled by portable systems and remote monitoring infrastructure. CMS bundled payment expansion in United States redirects patient volume from in-center facilities toward home-based modalities.
- Long-term Care Facilities:Skilled nursing settings managing elderly ESRD patients with limited transportation capacity.
Clinics hold installed capacity. Home care is rotating up the share rankings.
Material:
Biocompatibility certification and ultrafiltration precision now determine supplier selection, elevating synthetic polymers over commodity plastics.
- Polysulfone:Dominant membrane material for high-flux dialyzers due to superior complement activation profiles and hydraulic permeability. Japanese manufacturers anchored in Osaka polymer clusters leverage PMDA master file advantages to defend supply security.
- Polyethersulfone:Variant formulation offering enhanced thermal stability and sterilization tolerance for extended-use dialyzers. European chemical producers concentrate specialized resin supply, exposing manufacturers to input cost volatility.
- Polycarbonate:Rigid housing and connector components requiring gamma sterilization compatibility.
- Polyethylene:Flexible tubing extrusion with leachable-controlled formulations for blood contact applications.
- PVC:Legacy tubing material facing substitution pressure from DEHP-free alternatives under EU MDR and state-level United States restrictions.
Polysulfone holds installed capacity. Polyethersulfone is rotating up the share rankings.
Technology:
Clinical outcome differentiation and reimbursement coding determine technology migration timelines, with convection-based modalities gaining procedural share.
- Online Hemodiafiltration:High-volume convection therapy combining diffusive clearance with substantial convective removal of middle-molecular-weight toxins. French and Italian clinics lead replacement cycles from conventional modalities, requiring premium filter sets and ultrapure water infrastructure.
- Conventional Hemodialysis:Diffusion-based clearance through hollow-fiber membranes remains the procedural standard across emerging markets and cost-constrained systems.
- Portable Dialysis:Compact systems enabling patient-managed home therapy concentrate venture-stage investment as reimbursement eligibility expands.
- Water Treatment Systems:Reverse osmosis and ultrafiltration infrastructure producing dialysate-quality water for clinic operations.
Conventional hemodialysis holds installed capacity. Online hemodiafiltration is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across geographies. Japanese clinics absorb premium membrane pricing through PMDA-favored domestic supply chains, while Indian procurement remains acutely cost-sensitive amid limited reimbursement depth.
United States
CMS bundled payment expansion redirects patient volume toward home-based modalities, creating dual-channel demand for portable systems and conventional clinic supplies. FDA 510(k) clearance timelines for novel dialyzer geometries extend market entry for iterative improvements. Dialysis service concentration in Texas and Florida drives consolidated purchasing through multi-site operators.
Germany
Clinic operators demand unbundled component transparency, separating blood tubing procurement from dialyzer sourcing. EU MDR clinical evidence requirements for dialyzer reclassification elevate ISO 10993 testing infrastructure to competitive necessity. Polymer innovation clusters around Frankfurt sustain high-flux membrane development.
Japan
PMDA master file protocols favor domestic membrane suppliers, extending market access timelines for foreign entrants. Osaka and Tokyo polymer clusters anchor regional supply security for polysulfone formulations. Aging demographics compress incident ESRD growth but sustain replacement economics for premium dialyzers.
France
Online hemodiafiltration upgrade cycles concentrate in Paris and Lyon clinic networks, requiring premium filter sets and ultrapure water infrastructure. ANSM biocompatibility enforcement aligns with EU MDR reclassification timelines. Reimbursement coding favors convection-based modalities with documented clinical outcome differentiation.
China
NMPA regulatory pathways for imported dialyzers emphasize polymer master file equivalence to domestic reference standards. Provincial procurement centralization in Jiangsu and Guangdong compresses supplier margins through volume aggregation. Local membrane fabrication capacity expands but hollow-fiber spinning expertise remains concentrated with experienced engineers.
Hemodialysis Consumables Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with membrane chemistry capabilities determining margin capture. The capital-intensity gap between dialyzer manufacturers and standalone tubing suppliers has collapsed as polymer formulation became the decisive cost driver. Three archetypes dominate: vertically integrated system providers with captive polymer sourcing, membrane specialists leveraging regulatory master files, and component fabricators competing on automated production scale. Consolidated purchasing by large clinic operators and capacity expansion in hollow-fiber spinning represent the dominant competitive vectors.
Among integrated system providers, Fresenius Medical Care and Baxter International exemplify archetypes with differentiated positioning. Fresenius Medical Care anchors the vertically integrated tier through in-house dialyzer production and captive polymer supply chains. Baxter International occupies a position emphasizing end-to-end bloodline systems. B. Braun represents the automated manufacturing archetype, reducing lot-to-lot variability in high-volume tubing sets.
| Leading Market Players |
|---|
| Fresenius Medical Care |
| Baxter International |
| B. Braun |
| Nipro Corporation |
| Nikkiso Co., Ltd. |
| Asahi Kasei Corporation |
| Toray Industries |
| JMS Co., Ltd. |
| Rockwell Medical |
| Others |
Pricing and Supply Chain Analysis
EU MDR reclassification timelines gate both supply qualification and price differentiation simultaneously, elevating ISO 10993 testing infrastructure to a cost of entry that separates certified membrane suppliers from commodity component vendors. This regulatory threshold concentrates pricing power among manufacturers with established biocompatibility documentation, while forcing price compression on legacy cellulose-based dialyzers lacking clinical evidence for premium positioning.
Pricing Analysis
After-sales revenue from replacement dialyzer contracts and tubing set replenishment drives lifetime value capture. Contract-based long-term offtake dominates procurement, with pricing stratifying across high-flux polysulfone membranes, standard polyethersulfone variants, and economy cellulose alternatives. Price differentiation rests on FDA 510(k) clearance tier and volume scale commitments from multi-site clinic operators. Cost compression in blood tubing sets intensifies as German and United States markets separate component sourcing from bundled system contracts. Dialysis service operators demonstrate highest price sensitivity, while Japanese clinics absorb premium membrane pricing through PMDA-favored domestic supply security.
Supply Chain Analysis
Just-in-time inventory strategies dominate dialyzer production, though strategic stockpiling of specialized polysulfone resin buffers against European chemical producer concentration. Hollow-fiber membrane fabrication concentrates in Japan, Germany, and the United States, drawing from polysulfone and polyethersulfone resin supply anchored in European chemical production. Raw material dependencies include specialized polymer master files, gamma-sterilizable housing compounds, and leachable-controlled tubing formulations. Single-source vulnerability in polymer resin supply exposes manufacturers to input cost volatility. Distribution runs through consolidated purchasing organizations and group purchasing organizations serving multi-site dialysis clinic operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from remote monitoring infrastructure and home dialysis training programs expands faster than hardware sales, reframing consumables procurement as recurring patient management relationships rather than transactional component supply.
For Market Incumbents: Secure hollow-fiber spinning expertise through targeted acquisition of retiring engineer talent pools in Osaka and Frankfurt polymer clusters. Defend margin structures by accelerating backward integration into polysulfone resin formulation, countering input cost volatility from European chemical producer concentration. Channel control through exclusive bloodline system contracts with large United States dialysis service operators remains critical. For New Entrants and Emerging Players: FDA 510(k) clearance fast-tracks for iterative dialyzer geometries offer market access acceleration. White-space targets include portable dialysis system components for CMS-reimbursed home care channels and DEHP-free tubing alternatives for EU MDR compliance. The most penetrable segment lies in German clinic unbundled procurement, where standalone component certification separates from integrated system requirements. Go-to-market positioning should emphasize ISO 10993 testing infrastructure as competitive proof point. For Investors and Strategic Acquirers: EU MDR reclassification reshapes the acquisition landscape toward manufacturers with established clinical evidence dossiers. Long-term viability over the projection horizon favors membrane specialists with PMDA master file advantages or captive polymer supply chains. Target acquisition archetype: automated tubing set fabricators with lot-to-lot variability reduction capabilities. The signal to watch is CMS bundled payment expansion velocity for home dialysis modalities.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Master File Investment | Accelerates regulatory approval cycles for Japanese membrane suppliers defending regional supply security. |
| Automated Manufacturing Scale-Up | Reduces lot-to-lot variability in high-volume tubing sets for German clinic procurement consolidation. |
| Home Dialysis Reimbursement Strategy | Aligns portable system development with CMS bundled payment expansion in United States markets. |
| Backward Integration into Polymer Sourcing | Counters European resin supply concentration and stabilizes input cost structures for dialyzer production. |
| ISO 10993 Testing Infrastructure Expansion | Creates first-mover advantage for EU MDR dialyzer reclassification and CE marking renewal pathways. |
Research Methodology
Initial hypotheses were tested against primary input from dialysis clinic procurement managers, biomedical engineers, GPO contracts specialists, and polymer R&D directors, and refined through secondary validation against FDA 510(k) filings, PMDA approval databases, CMS Medicare reimbursement data, and EU MDR notified body submission records. Bottom-up demand modeling from clinic-level consumption patterns triangulated with top-down market sizing from manufacturer capacity disclosures.
Variance decomposition across product type, material chemistry, end-user channel, and technology modality segments structured the analytical framework. CAGRs were derived from segment-level growth trajectory blending and cross-referenced against reimbursement policy elasticity assumptions. Forecast inputs incorporated hollow-fiber spinning capacity expansion timelines, polymer innovation cluster output trajectories, and regulatory approval cycle compression factors.
The analysis sits within stated boundaries; outcomes outside sustained CMS reimbursement expansion or EU MDR enforcement consistency would require recalibration. Forecasts reflect documented assumptions regarding patient modality migration and polymer feedstock supply stability. Revision becomes warranted when home dialysis reimbursement eligibility crosses threshold acceleration or when polymer resin supply concentration shifts structurally.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Global Burn Ointment Market
Medical Supplies
Global Dental Sterilization Market
Medical Supplies
Healthcare Adhesive Tapes Market
Medical Supplies
North America Insulin Syringe Market
Medical Supplies
Acid Citrate Dextrose Tubes Market
Medical Supplies
Nasal Oxygen Cannula Market
Medical Supplies
Global Enema Based Products Market
Medical Supplies
Transfusion Bottles Market
Medical Supplies
Middle East and North Africa Disposable Gloves Market
Medical Supplies
Medical Supply Delivery Service Market
Medical Supplies
Breast Shells Market
Medical Supplies
Global Medical Protective Equipment Market
Medical Supplies
Resuscitation Masks Market
Medical Supplies
Super Absorbent Dressings Market
Medical Supplies
Medical Plastics Market
Medical Supplies
Medical Specialty Bags Market