
 Commercial Parachute Market | 2026-2036
Commercial Parachute Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Parachute Market Outlook
Certified parachute rigger workforce shortages across North America and Western Europe is unwinding delivery timelines for military and commercial orders alike. Airborne Systems leverages its vertical integration across canopy design, harness assembly, and pyrotechnic deployment to sustain throughput despite labor bottlenecks. Safran anchors European defense supply chains through its long-standing relationship with French airborne units and NATO interoperability programs. Mills Manufacturing specializes in precision cargo delivery systems, occupying a niche where controlled descent accuracy determines contract awards.
A commercial parachute is a load-bearing aerial deceleration device engineered from high-tenacity nylon or Kevlar fabric, typically rated for deployment velocities between 120 and 300 knots depending on mission profile, designed to safely lower personnel, cargo, or equipment from aircraft to ground. Ram-air parachutes dominate professional military and sport applications where glide ratio and steerability determine operational utility, while round parachutes retain cost advantages in static-line training and mass-cargo scenarios where precision landing is secondary. Tandem parachutes command premium pricing due to dual-harness certification complexity and liability exposure, whereas cargo parachutes face margin compression from commoditization in humanitarian airdrop contracts.
FAA Technical Standard Orders govern civilian skydiving equipment airworthiness, while military procurement adheres to MIL-PRF-8654 and NATO STANAG specifications that mandate flame resistance, opening shock limits, and multi-environment reliability testing. EASA coordinates with national aviation authorities across EU member states to harmonize certification pathways, though divergence in emergency services procurement standards persists. Stakeholders must monitor evolving drone-parachute recovery regulations and urban air mobility payload safety mandates, as these adjacent sectors threaten to divert engineering talent and textile supply capacity from traditional parachute manufacturing.
Market Dynamics
Certified parachute rigger workforce shortages are compressing delivery timelines across both military and civilian order books, forcing manufacturers to restructure production workflows and accelerate automated sewing cell deployment. This labor bottleneck intersects with evolving FAA TSO-C23e technical standards to create a dual squeeze on throughput and compliance timelines.
Growth Catalysts
- TSO-C23e Modernization:FAA's updated technical standard orders are mandating enhanced reserve container designs, driving replacement cycles across the US civilian skydiving fleet.
- Special Operations Sustainment Budgets:US Special Operations Command procurement is expanding precision cargo delivery system orders for contested logistics scenarios.
- Kevlar-Nylon Hybrid Canopy Adoption:Advanced textile blends are extending service intervals for military parachute systems, reducing total lifecycle ownership costs.
Market Restraints
- Aramid Fiber Price Volatility:Kevlar supply concentration with DuPont creates input cost exposure for canopy manufacturers during aerospace demand surges.
- Certified Rigger Pipeline Collapse:FAA-certified rigger training program throughput has stagnated, capping assembly and inspection capacity regardless of capital investment.
- Drone Payload Recovery Substitution:Fixed-wing UAV parachute recovery systems are diverting textile engineering talent from traditional personnel parachute development.
Strategic Opportunities
- Urban Air Mobility Payload Safety Mandates:Emerging eVTOL cargo and passenger regulations in the United States are creating certified emergency descent system requirements.
- NATO STANAG Harmonization:Standardized interoperability specifications are opening cross-border military procurement for European manufacturers.
- Automated Precision Airdrop:GPS-guided cargo parachute systems are penetrating humanitarian logistics contracts previously served by unguided round canopies.
Industry Challenges
- FAA-EASA Certification Divergence:Misaligned emergency services equipment approval pathways force redundant testing for transatlantic suppliers.
- Pyrotechnic Deployment System Integration:Automated activation mechanisms for drone recovery are requiring new electronics-software-hardware competency stacks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Parachute Market |
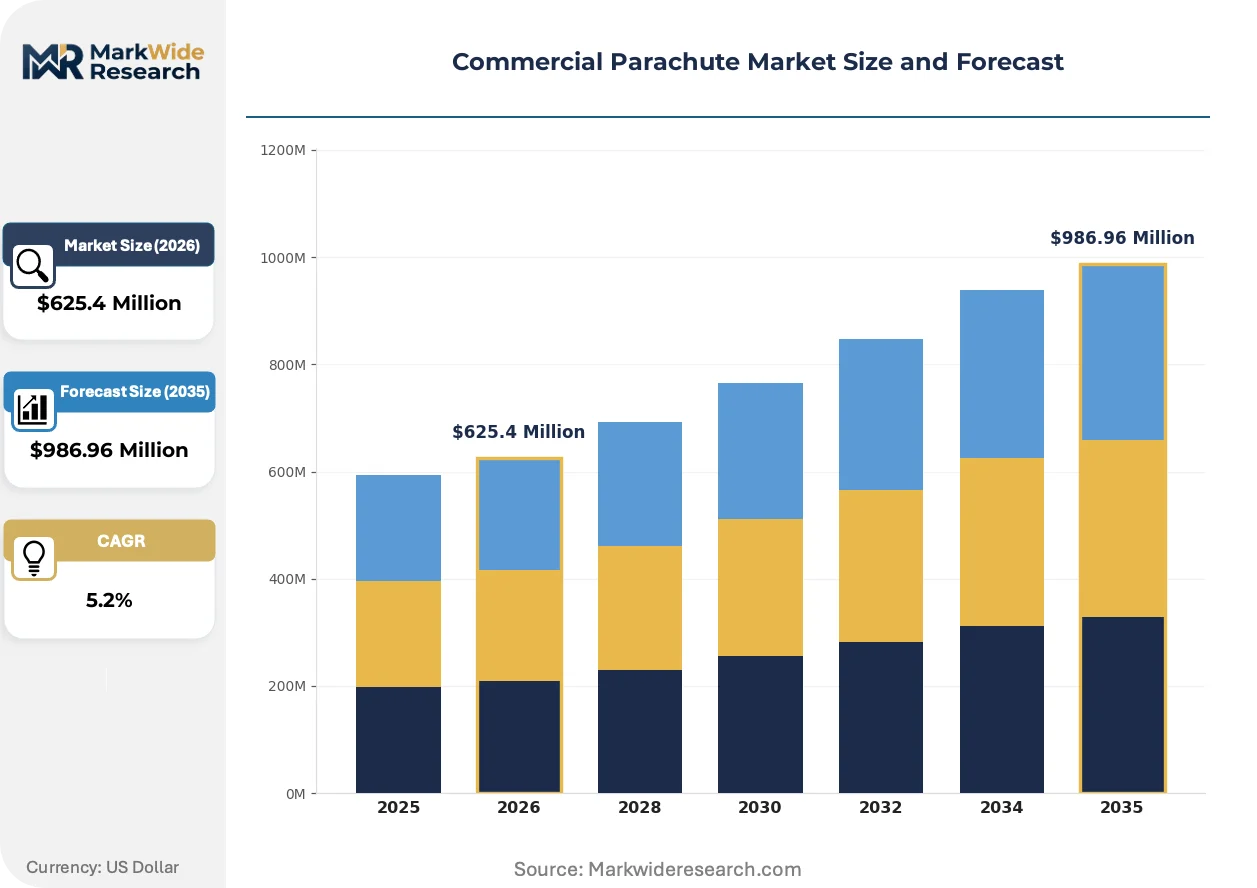
| Market Size in 2026 | $625.4 Million |
| Market Size in 2035 | $986.96 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Round Parachutes, Ram-Air Parachutes, Tandem Parachutes, Cargo Parachutes Application: Military Use, Airborne Training, Aerial Photography, Stunt & Spectacle End User: Government Agencies, Recreational Jumpers, Film Production Companies, Emergency Services Deployment: Static Line Deployment, Freefall Deployment, Controlled Descent, Rapid Deployment |
| Companies Covered | Airborne Systems, FXC Corporation, Butler Parachute Systems, Complete Parachute Solutions, Mills Manufacturing, Aerodyne Research, BAE Systems, Safran, Sächsische Spezialkonfektion GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Parachute Market Strategic Shifts
Computational fluid dynamics simulation is collapsing traditional canopy design iteration cycles, while regulatory pressure on urban air mobility safety systems is opening adjacent equipment categories. These forces are reshaping how manufacturers allocate engineering resources between core parachute systems and emerging aerial deceleration applications.
Ram-air parafoil architectures with variable geometry control surfaces are decomposing the historical trade-off between glide performance and packing volume. Military freefall units are fielding these systems for high-altitude, low-opening insertions where precision landing determines mission success. The technology is decomposing demand for conventional cruciform canopies in special operations procurement.
REACH chemical substance restrictions in the European Union are forcing reformulation of fire-resistant canopy coatings previously reliant on legacy brominated compounds. Manufacturers serving French airborne units must now validate alternative treatments through accelerated environmental aging protocols. This regulatory pressure is compressing supplier qualification timelines for European defense contracts.
Skydiving tourism operators are unbundling equipment ownership from instruction services, shifting toward lease-to-operate models for tandem harness-container systems. This restructuring concentrates asset ownership with specialized fleet managers in Florida and Arizona drop zones. The model is visible most acutely in US civilian markets where liability insurance costs are driving operational consolidation.
Commercial Parachute Market Segmentation
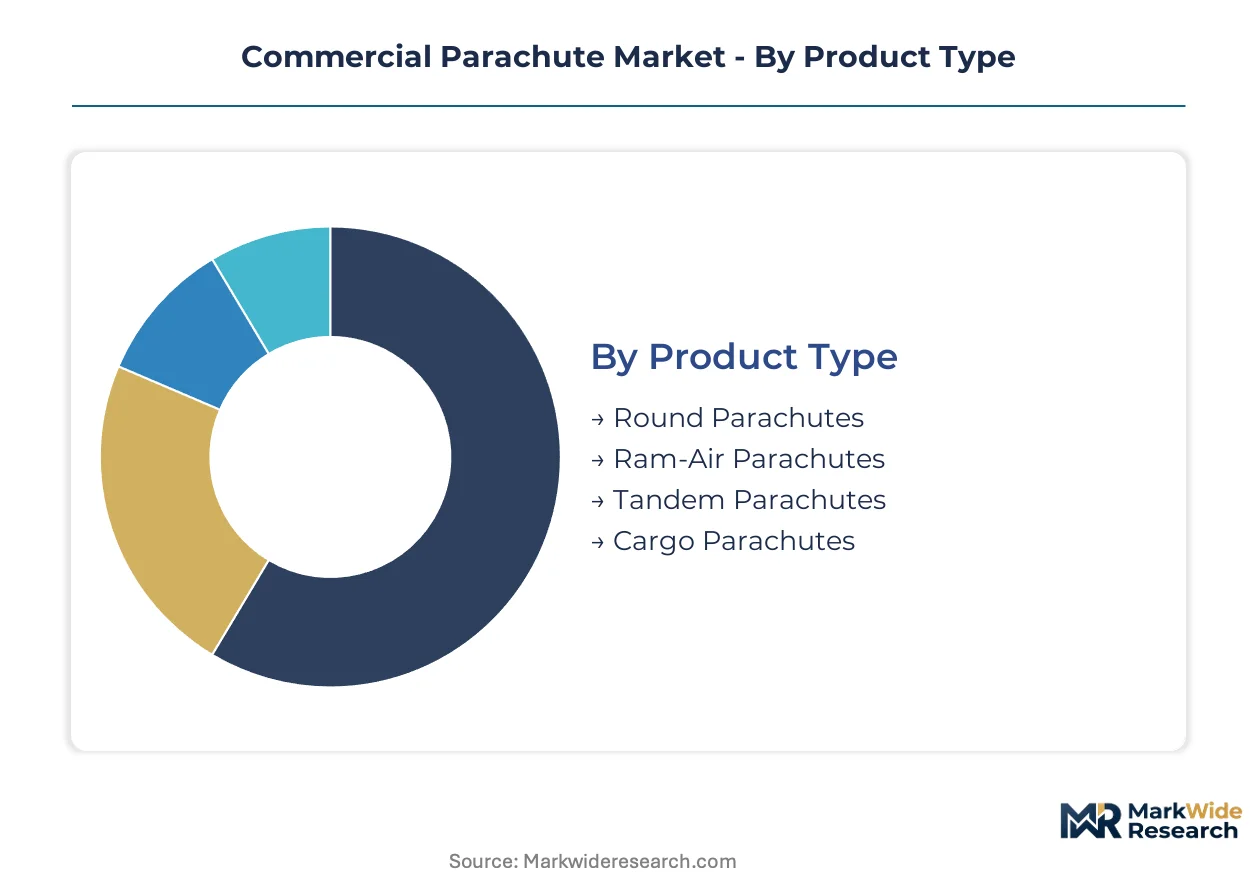
Parachute manufacturers face divergent technical requirements across product categories, forcing portfolio decisions between high-volume military contracts and specialized civilian applications. Segmentation reveals where engineering talent and textile capacity generate the highest returns.
Product Type:
Drone recovery systems and guided airdrop technologies are displacing conventional personnel parachutes in defense procurement, reshaping which canopy architectures retain pricing power.
- Round Parachutes:Cruciform and conical designs constructed from low-porosity nylon fabrics dominate static-line training and mass-cargo scenarios. United States Army airborne school contracts sustain volume production despite minimal steerability, with procurement concentrated at Fort Benning and Fort Bragg training installations.
- Ram-Air Parachutes:Rectangular cells inflate to create wing-like lift surfaces with glide ratios exceeding 3:1. Special Operations Command precision insertion requirements in the United States drive demand for high-performance parafoils with GPS-guided landing capabilities.
- Tandem Parachutes:Dual-harness systems rated for combined loads up to 500 pounds serve skydiving tourism operators. FAA TSO-C23e certification complexity limits supplier field to established rigging houses.
- Cargo Parachutes:Heavy-duty platforms with reinforced suspension lines handle payloads from 2,000 to 42,000 pounds. Humanitarian airdrop contracts from USAID and World Food Programme create price-competitive bidding environments.
Round parachutes anchor the volume base while ram-air systems gain share at the steepest rate.
Application:
Military procurement budgets concentrate in contested logistics and special operations, diverting manufacturing capacity from civilian entertainment segments.
- Military Use:Personnel insertion, equipment delivery, and emergency escape systems for fixed-wing and rotary aircraft. Pentagon procurement through Defense Logistics Agency contracts prioritizes multi-environment reliability testing under MIL-PRF-8654 specifications.
- Airborne Training:Static-line and accelerated freefall instruction programs require high-cycle durability canopies. United States civilian drop zones in Arizona and Florida generate recurring replacement demand from skydiving schools.
- Aerial Photography:Cinematography platforms demand ultra-stable descent characteristics with minimal oscillation. Production companies in Los Angeles and Atlanta lease specialized equipment for action sequence filming.
- Stunt & Spectacle:Stadium entertainment and live event performances require pyrotechnic integration and crowd-safe landing zones. Liability insurance costs constrain operator expansion in the United States.
Military use commands the dominant revenue share while aerial photography climbs fastest as streaming content production expands.
End User:
Government procurement cycles and recreational consumer spending move on disconnected timelines, complicating capacity planning for manufacturers serving both segments.
- Government Agencies:Defense departments, national guard units, and federal emergency management organizations. United States Special Operations Command sustainment budgets prioritize precision cargo systems for denied-area logistics.
- Recreational Jumpers:Individual sport skydivers and skydiving tourism participants. United States Parachute Association membership data indicates concentration in sun-belt states with year-round operating weather.
- Film Production Companies:Major studios and independent producers requiring certified stunt coordination. California OSHA regulations govern aerial performance safety protocols.
- Emergency Services:Search-and-rescue units, smokejumper crews, and disaster response teams. United States Forest Service smokejumper bases in Montana and Idaho specify fire-resistant canopy materials.
Government agencies provide the stable demand foundation while emergency services expand most quickly as climate-driven disaster response requirements intensify.
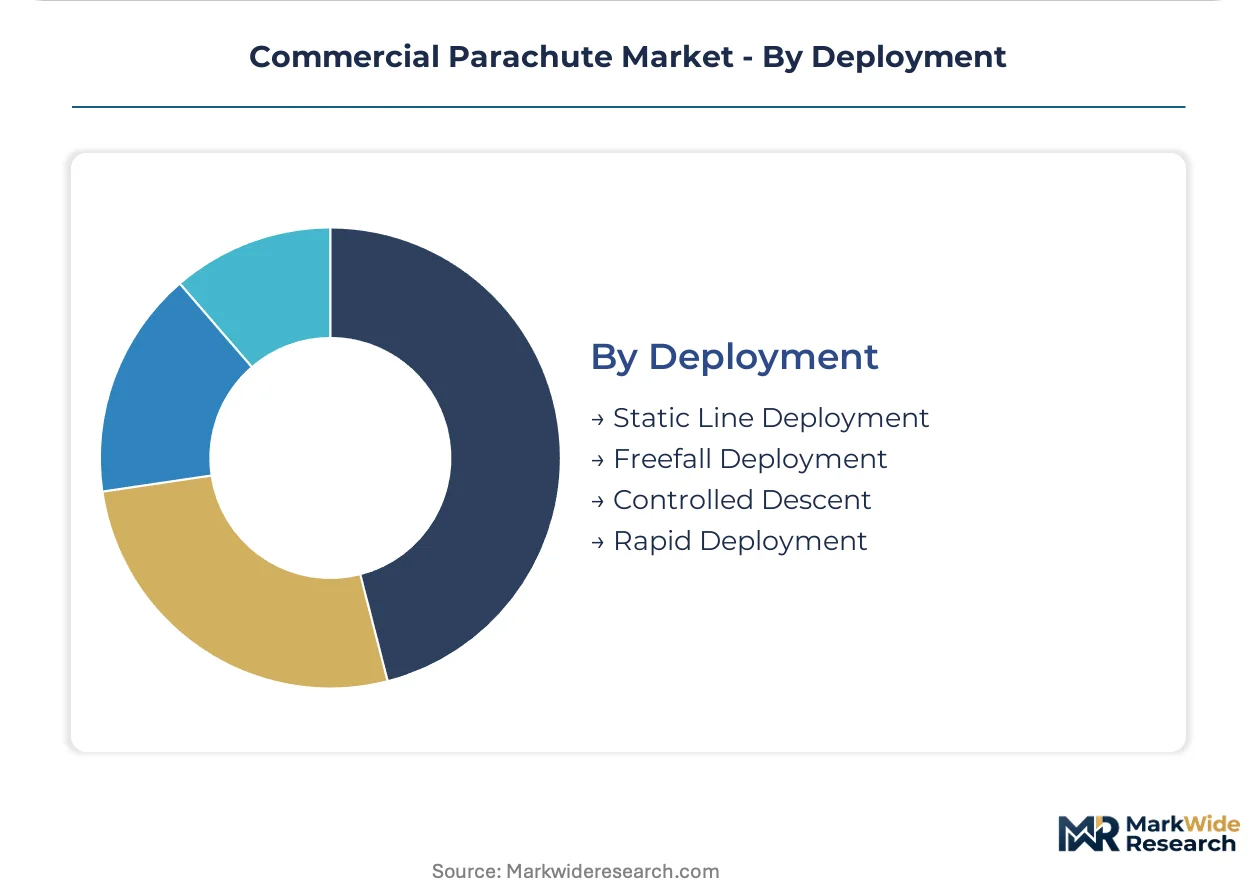
Deployment:
Automation in deployment mechanisms is bifurcating the market between human-actuated systems and pyrotechnic-electronic integrations for unmanned platforms.
- Static Line Deployment:Fixed-length cord automatically extracts parachute upon jumper exit from aircraft. United States Army airborne training at Fort Moore maintains the largest static-line jump volume globally.
- Freefall Deployment:Manual or automatic activation devices trigger canopy inflation after controlled delay. Sport skydivers in the United States prefer customizable automatic activation device altimeter settings.
- Controlled Descent:GPS-guided parafoil systems steer to designated landing coordinates. Precision airdrop contracts from United States Transportation Command specify circular error probable requirements.
- Rapid Deployment:Ballistic extraction systems for emergency escape and unmanned aircraft recovery. FAA drone parachute recovery regulations are creating new certification categories.
Static line deployment retains the highest unit volume while controlled descent systems are gaining share fastest as guided airdrop technology matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA certification requirements in the United States establish the technical baseline that shapes procurement standards across allied defense programs and civilian skydiving markets worldwide.
United States
Special Operations Command sustainment budgets and civilian skydiving tourism infrastructure generate dual revenue streams for manufacturers. FAA TSO-C23e technical standards mandate enhanced reserve container designs that drive replacement cycles across the domestic fleet. Drop zones in Arizona and Florida concentrate equipment demand from skydiving schools and tandem operators.
France
French airborne units and NATO interoperability programs anchor European defense supply chains for precision insertion systems. EASA coordination with national aviation authorities harmonizes certification pathways for emergency services equipment. The country's airborne forces maintain procurement relationships with domestic rigging houses for static-line and freefall platforms.
Germany
Bundeswehr procurement through NATO STANAG specifications prioritizes multi-environment reliability testing for contested logistics scenarios. REACH chemical substance restrictions force reformulation of fire-resistant canopy coatings previously reliant on legacy brominated compounds. Industrial clusters in southern Germany host specialized textile engineering operations for Kevlar-nylon hybrid architectures.
United Kingdom
Ministry of Defence precision cargo delivery requirements align with United States Transportation Command circular error probable specifications for guided airdrop systems. Divergence between FAA and European emergency services equipment approval pathways forces redundant testing for transatlantic suppliers. Military freefall training installations sustain demand for high-performance parafoils with GPS-guided landing capabilities.
Canada
Search-and-rescue units and disaster response teams specify fire-resistant canopy materials for smokejumper and emergency services applications. Health Canada and Transport Canada coordinate on urban air mobility payload safety mandates that create certified emergency descent system requirements. Western provinces host training infrastructure for static-line and accelerated freefall instruction programs.
Commercial Parachute Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in the commercial parachute market. The upper tier commands defense contracts through captive canopy design, harness assembly, and pyrotechnic deployment capabilities. Mid-scale fabricators compete on precision cargo delivery accuracy where controlled descent determines contract awards. Competitive moves concentrate on automated sewing cell deployment to offset certified rigger workforce shortages, and on GPS-guided parafoil development for humanitarian logistics contracts.
Among the integrated defense suppliers, Airborne Systems exemplifies vertical control across the full production stack, while Safran anchors European procurement relationships through long-standing airborne unit contracts. Mills Manufacturing occupies a position within the precision cargo specialization tier where accuracy metrics drive vendor selection. FXC Corporation and Butler Parachute Systems represent mid-scale specialists serving civilian skydiving and training markets with FAA-certified reserve and tandem systems.
| Leading Market Players |
|---|
| Airborne Systems |
| FXC Corporation |
| Butler Parachute Systems |
| Complete Parachute Solutions |
| Mills Manufacturing |
| Aerodyne Research |
| BAE Systems |
| Safran |
| Sächsische Spezialkonfektion GmbH |
| Others |
Value Chain & Pricing Dynamics
Scale economies in automated canopy cutting and automated sewing cell deployment concentrate manufacturing throughput among vertically integrated defense suppliers, compressing price floors for mid-scale fabricators while elevating entry barriers for new competitors. FAA TSO-C23e certification complexity and MIL-PRF-8654 military specifications create dual compliance cost structures that stratify pricing power between integrated tier-one suppliers and specialist rigging houses.
Pricing Analysis
United States civilian skydiving equipment commands 15-25% premiums over European equivalents due to FAA certification stringency and liability insurance bundling requirements. Three-tier pricing structure across military-specification, professional sport, and training-economy levels separates vendors by certification grade and after-sales service intensity. Cost compression in humanitarian cargo parachutes is intensifying because USAID and World Food Programme contracts favor lowest-bid procurement over performance metrics. Recreational jumpers exhibit highest price sensitivity, while Special Operations Command procurement prioritizes reliability over unit cost.
Supply Chain Analysis
Just-in-time Kevlar-nylon fabric sourcing from DuPont and Teijin dominates canopy production, though strategic stockpiling of pyrotechnic deployment components persists among defense contractors facing NATO interoperability deadlines. Manufacturing concentrates in the United States, France, and Germany, with textile engineering clusters in southern Germany and Florida drop-zone proximity driving regional specialization. Raw material dependencies center on aramid fiber from DuPont, high-tenacity nylon from Invista, and pyrotechnic initiators from limited qualified suppliers. Single-source vulnerability in Kevlar supply creates exposure during aerospace demand surges. Distribution runs through defense logistics agencies, specialized rigging houses, and direct-to-drop-zone fleet managers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The commercial parachute market is emerging from a cyclical trough as Special Operations Command sustainment budgets expand and FAA TSO-C23e modernization drives replacement demand across the civilian fleet.
For Market Incumbents: Fortify captive control over pyrotechnic deployment system integration and automated sewing cell capacity to offset certified rigger workforce shortages threatening throughput. Deepen backward integration into Kevlar-nylon hybrid textile engineering to reduce DuPont supply concentration exposure. Prioritize GPS-guided parafoil R&D investment to defend position against drone recovery system substitution eroding traditional personnel parachute procurement. For New Entrants and Emerging Players: Anchor in urban air mobility emergency descent system certification, where FAA drone parachute recovery regulations and eVTOL payload safety mandates create uncrowded white space. Target aerial photography and cinematography equipment leasing, where Los Angeles and Atlanta production companies demand ultra-stable descent platforms with minimal established supplier relationships. Pursue lease-to-operate fleet management models for tandem harness-container systems, bypassing capital-intensive manufacturing entry barriers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision cargo delivery specialists with GPS-guided airdrop capabilities and established USAID contract relationships. Long-term viability over the projection horizon rests on urban air mobility adjacency exposure and NATO STANAG interoperability certification depth. Acquisition targets should demonstrate automated sewing cell deployment and pyrotechnic-electronic integration competency stacks. The signal to watch is FAA-eVTOL emergency descent system rulemaking velocity as inflection indicator for adjacent market timing.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Sewing Cell Deployment | Offsets certified rigger workforce shortages compressing delivery timelines across military and civilian order books. |
| GPS-Guided Parafoil Development | Penetrates humanitarian logistics contracts and Special Operations Command precision airdrop requirements. |
| Pyrotechnic-Electronic Integration | Addresses FAA drone parachute recovery regulations and unmanned aircraft recovery certification categories. |
| Kevlar-Nylon Hybrid Textile Investment | Extends service intervals under MIL-PRF-8654 specifications while reducing lifecycle ownership costs. |
| Urban Air Mobility Certification | Captures eVTOL emergency descent system mandates before traditional aerospace suppliers pivot capacity. |
Study Parameters
Operator-level perspectives from military procurement officers at United States Special Operations Command, certified parachute riggers at Arizona and Florida drop zones, FAA certification engineers, and textile supply managers at DuPont and Teijin anchored the qualitative base. Primary interviews combined with secondary validation from FAA TSO-C23e technical standard orders, MIL-PRF-8654 specification documents, NATO STANAG interoperability protocols, and Defense Logistics Agency contract announcements. Bottom-up unit demand modeling across product type, application, end user, and deployment mechanism triangulated against top-down defense budget allocation analysis.
Sensitivity analysis tested forecast outputs against alternative scenarios for Special Operations Command sustainment budget trajectories and certified rigger training program throughput recovery. Segmentation dimensions modeled encompassed round, ram-air, tandem, and cargo product architectures; military, training, aerial photography, and stunt applications; government agency, recreational jumper, film production, and emergency services end users; and static-line, freefall, controlled descent, and rapid deployment mechanisms. CAGRs derived from equipment replacement cycle analysis and procurement pipeline visibility across the analysis window.
Decision-makers should treat outputs as directional under assumptions of sustained geopolitical tension elevating airborne readiness requirements and stable FAA-EASA certification pathway divergence; material deviation would warrant model refresh. Revision becomes warranted when urban air mobility payload safety mandates accelerate beyond current rulemaking velocity or aramid fiber supply concentration shifts alter input cost structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Safety Systems
Helicopter Emergency Flotation System Market
Aircraft Safety Systems
Commercial Aircraft Evacuation System Market
Aircraft Safety Systems
Military Aircraft Collision Avoidance Systems Market
Aircraft Safety Systems
Aircraft Docking Systems Market
Aircraft Safety Systems
Military Airborne Collision Avoidance Systems (ACAS) Market
Aircraft Safety Systems
Aircraft Fire Protection Systems Market
Aircraft Safety Systems
Helicopter Ice Protection Systems Market
Aircraft Safety Systems
Aircraft Smoke Detection and Fire Extinguishing System Market
Aircraft Safety Systems
Aviation Life Rafts Market
Aircraft Safety Systems
South Korea Aircraft Windshield Wiper and Washer System Market
Aircraft Safety Systems
Aircraft Evacuation Slide Market
Aircraft Safety Systems
Aircraft Survivability Equipment Market
Aircraft Safety Systems
Aircraft Evacuation Systems Market
Aircraft Safety Systems
Global Aircraft Brakes Market
Aircraft Safety Systems
Aircraft Survival Equipment Market
Aircraft Safety Systems
Aerospace & Aircraft Collision Avoidance System Market