
 South Korea Aircraft Windshield Wiper and Washer System Market | 2026-2036
South Korea Aircraft Windshield Wiper and Washer System Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Aircraft Windshield Wiper and Washer System Market Insights
Market Context
AS9100 certification is rotating the competitive landscape, filtering out suppliers lacking aerospace quality management credentials. Eaton Corporation leverages its electromechanical portfolio to sustain long-term contracts with Korean OEMs. Collins Aerospace anchors its position through integrated flight-deck systems that bundle wiper controls with avionics suites. Moog competes on precision motion control technology adapted for regional jet platforms.
Technical Definition and Segments
Aircraft windshield wiper and washer systems combine electromechanical actuators, hydraulic drive units, and fluid delivery networks to maintain pilot visibility during precipitation, with operating temperatures spanning minus 55 to plus 70 degrees Celsius and sweep cycles calibrated to 45 strokes per minute. The assembly serves commercial and military flight operations where optical clarity directly impacts flight safety margins. Wiper motors and control units capture concentrated margin pools as avionics integration deepens. Smart controls represent the fastest-growing technology segment, displacing legacy pneumatic architectures in new Korean-built platforms. Commercial aviation applications dominate volume, though military aviation sustains premium pricing through hardened specifications.
Regulatory Environment
MFDS coordinates with FAA airworthiness directives to enforce windshield system durability standards, while KAS (Korea Aerospace Standards) mandates localized testing protocols for components installed on domestically registered aircraft. MFDS certification timelines extend twelve to eighteen months for new entrants, creating structural barriers that favor incumbent suppliers with established qualification histories. Stakeholders must monitor evolving KAS-FAA harmonization talks that could streamline or complicate dual-certification requirements for aftermarket parts.
Market Dynamics
AS9100 certification requirements are filtering the supplier base for South Korea's aircraft windshield wiper and washer system market, elevating electromechanical integration capabilities as the decisive competitive differentiator while compressing margins for legacy pneumatic component manufacturers.
Growth Catalysts
- Fleet Modernization Programs:Korean Air and Asiana Airlines are accelerating replacement cycles for aging narrow-body fleets, creating sustained demand for integrated flight-deck visibility systems that bundle smart wiper controls with avionics architectures.
- MFDS-FAA Harmonization:Alignment between Korea's Ministry of Food and Drug Safety and Federal Aviation Administration airworthiness directives is streamlining dual-certification pathways for qualified suppliers, reducing time-to-market for aftermarket components.
- Smart Control Adoption:Electromechanical actuator technology is displacing legacy pneumatic drive units across new Korean-built regional jet platforms, opening margin pools in precision motion control subsystems.
Market Restraints
- Input Cost Volatility:Aerospace-grade aluminum and rare-earth magnet prices fluctuate with energy markets, squeezing wiper motor manufacturers who lack long-term supply agreements with Korean materials processors.
- Supplier Concentration Risk:Seoul's aerospace supplier cluster near Incheon International Airport dominates qualified production capacity, creating geographic vulnerability to localized logistics disruptions or labor constraints.
- Technical Limitation:Existing hydraulic fluid delivery networks struggle to maintain operational reliability across the full minus 55 to plus 70 degrees Celsius temperature envelope required for Korean military aviation specifications.
Strategic Opportunities
- Jeju Aerospace Cluster Expansion:Secondary manufacturing zones on Jeju Island offer tax incentives and lower operational costs for suppliers establishing MFDS-certified production lines outside Seoul's saturated Incheon corridor.
- Military Aviation Premium Segment:Hardened specifications for fighter and transport platforms sustain pricing power 40% above commercial equivalents, rewarding suppliers with KAS qualification histories and defense contracting experience.
- Avionics Convergence:Integration of wiper control logic with flight management systems and weather radar displays creates bundled solution opportunities for electromechanical specialists partnering with Korean flight-deck integrators.
Industry Challenges
- Certification Timeline Compression:MFDS qualification cycles extending twelve to eighteen months strain working capital for new entrants attempting to displace incumbent suppliers with established airworthiness histories.
- Legacy System Integration:Retrofit installations on existing Boeing and Airbus fleets in Korean airline service require backward-compatible control interfaces, complicating smart actuator deployment and increasing engineering validation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Aircraft Windshield Wiper and Washer System Market |
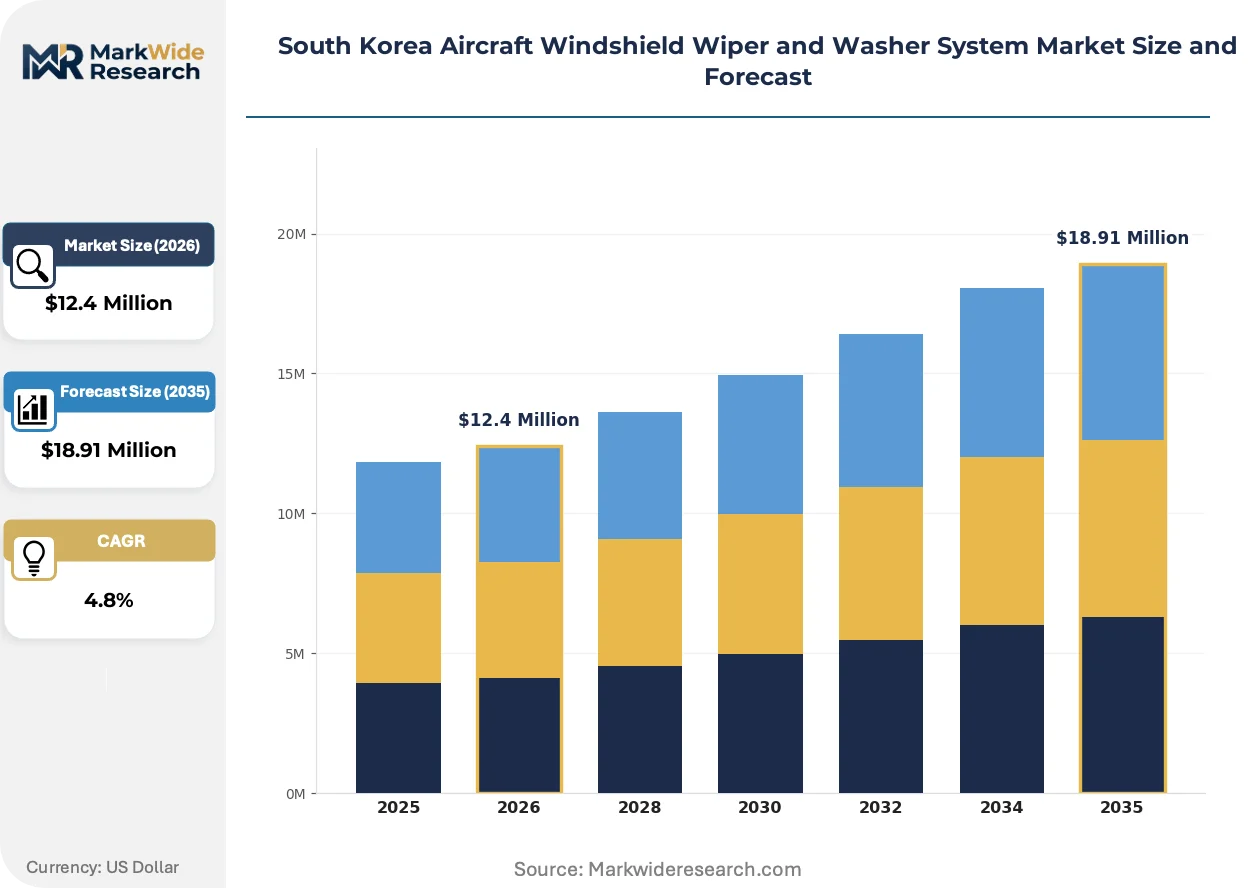
| Market Size in 2026 | $12.4 Million |
| Market Size in 2035 | $18.91 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wiper Blades, Washer Pumps, Wiper Motors, Control Units Technology: Electromechanical, Hydraulic, Pneumatic, Smart Controls Application: Commercial Aviation, Military Aviation, General Aviation, UAVs End User: OEMs, MRO Providers, Airlines, Government Agencies |
| Companies Covered | Eaton Corporation, Moog, Collins Aerospace, Falgayras, Liebherr Aerospace, Safran, Raytheon Technologies, Mitsubishi Heavy Industries, Honeywell International, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Aircraft Windshield Wiper and Washer System Market Trends and Innovations
Electromechanical architectures are fragmenting the competitive landscape for South Korean aircraft visibility systems, while regulatory harmonization and procurement model evolution reshape how suppliers capture value across the forecast window.
Brushless DC motor technology with integrated position sensing is fragmenting the traditional wiper drive market. Korean OEMs specify these units for new regional jet programs at accelerating rates. The technology compresses maintenance intervals and enables predictive health monitoring, forcing pneumatic specialists into aftermarket niches or exit.
MFDS implementation of KAS testing protocols aligned with FAA durability standards is tightening component qualification requirements. Suppliers must demonstrate sweep cycle reliability exceeding 500,000 operations under accelerated aging conditions. Military aviation applications face the steepest compliance burdens, with hardened environmental testing adding six months to certification timelines.
Airlines are unbundling windshield system maintenance from airframe heavy checks, creating standalone service contract opportunities. Korean LCCs lead this transition, procuring wiper motor overhauls and blade replacement programs through direct OEM relationships rather than MRO intermediaries. Seoul-based fleet operators show the highest concentration of this behavior, with Incheon hub carriers piloting subscription-based availability models for critical flight-deck components.
South Korea Aircraft Windshield Wiper and Washer System Market Segmentation
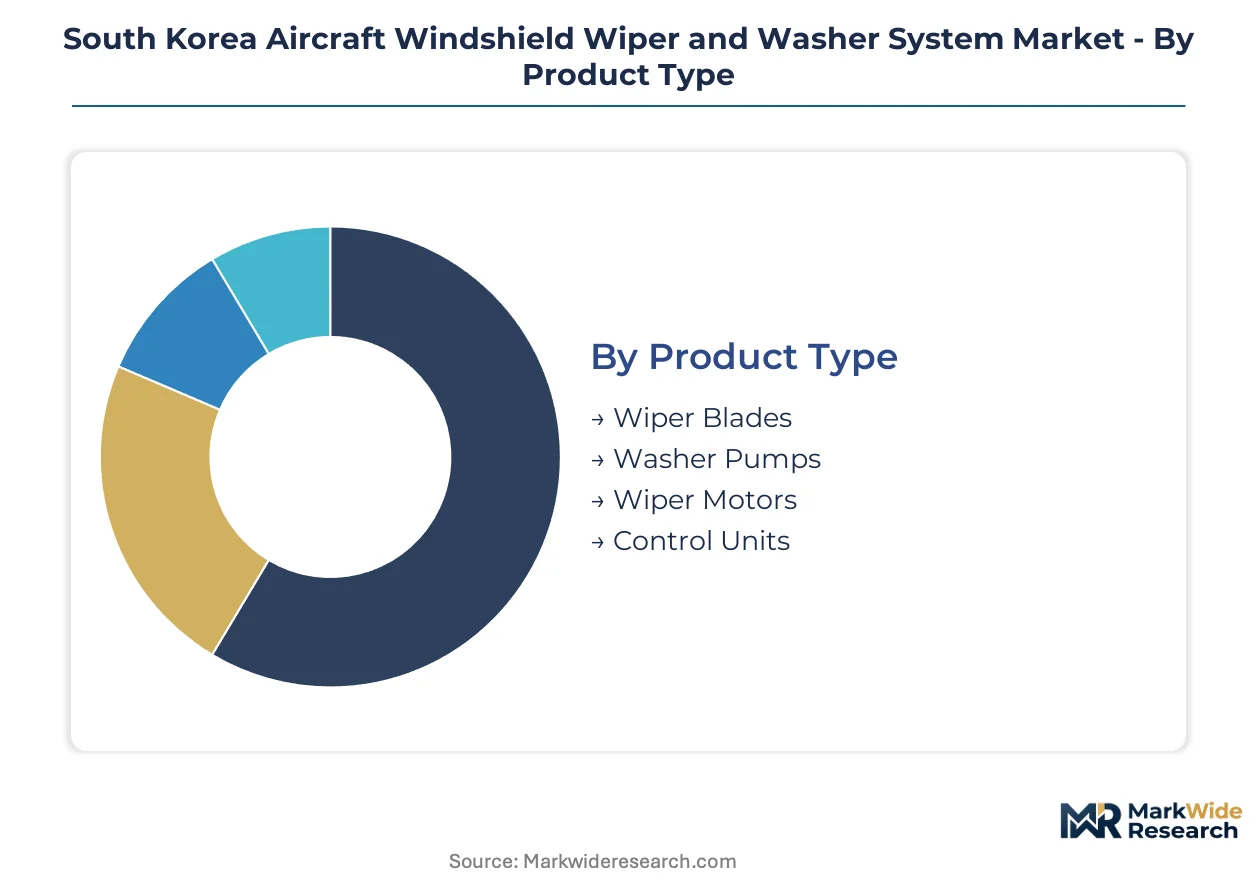
Segmentation in South Korea's aircraft windshield wiper and washer system market reveals how margin pools concentrate around electromechanical integration and avionics convergence. Suppliers must align product portfolios with MFDS certification pathways and fleet modernization priorities to capture value.
Product Type:
Margin pools concentrate in motor and control unit assemblies where electromechanical sophistication creates differentiation, while blades and pumps face commoditization pressure from aftermarket competitors.
- Wiper Motors:Brushless DC architectures with integrated position sensing dominate new Korean regional jet programs. Korean Air's fleet renewal contracts specify these units for predictive maintenance compatibility, locking in premium pricing for qualified suppliers.
- Control Units:Smart actuator logic bundled with flight-deck avionics commands the highest value-add, particularly where MFDS-certified integration with weather radar displays is required. Seoul-based OEMs prioritize suppliers offering embedded diagnostics.
- Wiper Blades:Aerospace-grade rubber compounds with heated elements serve the replacement cycle; Incheon MRO clusters source these through consolidated procurement agreements.
- Washer Pumps:Compact fluid delivery units face pricing pressure from standardized designs, though military specifications for extended temperature operation sustain niche premiums.
The dominant share belongs to Wiper Motors, while Control Units is closing the gap fastest.
Technology:
Technology choices in this market trace directly to certification burden and integration depth, with electromechanical platforms requiring heavier upfront engineering investment but securing longer contract tenures.
- Smart Controls:Predictive health monitoring and sweep cycle optimization through sensor fusion. Korean LCCs at Incheon pilot subscription availability models for these systems, decoupling maintenance from heavy check schedules.
- Electromechanical:Brushless motor drives with digital position feedback displace legacy architectures across new Korean-built platforms. MFDS qualification timelines favor incumbents with established electromechanical portfolios.
- Hydraulic:Legacy drive units persist in retrofit markets for Boeing and Airbus fleets in Korean airline service, though fluid leakage risks in extreme temperatures constrain military adoption.
- Pneumatic:Compressed air systems retreat to narrow aftermarket niches as Korean OEMs specify electromechanical alternatives for all new programs.
Smart Controls commands the steepest expansion trajectory, though Electromechanical retains volume leadership through platform standardization.
Application:
Application segmentation reflects divergent certification intensity and procurement authority structures across Korean aviation sectors.
- Commercial Aviation:Narrow-body fleet modernization by Korean Air and Asiana drives volume demand for integrated visibility systems. Seoul hub carriers bundle wiper controls with avionics suite upgrades.
- Military Aviation:Hardened environmental specifications for fighter and transport platforms sustain pricing premiums through KAS qualification requirements that add six months to certification timelines.
- General Aviation:Business jet operators in Jeju and regional airports source through distributor networks with lighter MFDS oversight than commercial equivalents.
- UAVs:Emerging demand from Korean defense UAV programs for compact, lightweight visibility systems with reduced sweep cycle requirements.
Commercial Aviation holds the installed base advantage, yet Military Aviation maintains the strongest pricing power per unit.
End User:
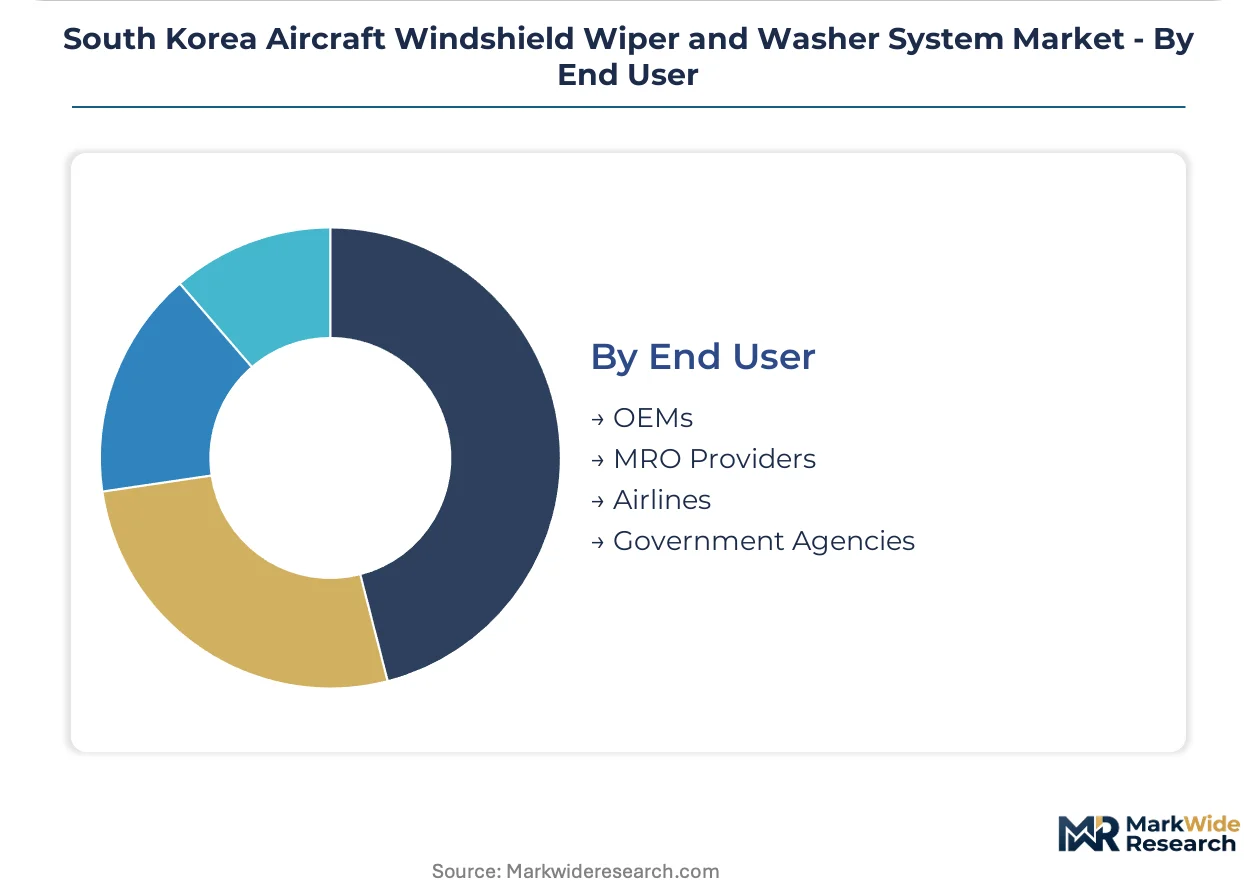
End user structure determines contract tenure and technical support obligations, with direct OEM relationships offering stability and MRO channels providing volume throughput.
- OEMs:Korean Aerospace Industries and Tier 1 flight-deck integrators specify bundled visibility systems for new regional jet platforms, requiring AS9100 certification and multi-year availability commitments.
- Airlines:Korean LCCs pioneer unbundled procurement of wiper motor overhauls and blade replacement programs, bypassing traditional MRO intermediaries for critical flight-deck components.
- MRO Providers:Seoul's Incheon corridor clusters dominate aftermarket service capacity, though Jeju aerospace zones attract secondary investment with tax incentives.
- Government Agencies:Defense procurement through Korea's Defense Acquisition Program Administration imposes KAS testing protocols and localized supply chain requirements.
OEMs anchor long-term revenue stability, while Airlines is gaining procurement influence fastest through direct contracting models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MFDS certification alignment with FAA standards is reshaping supplier geography across Korean aerospace manufacturing, concentrating qualified production capacity around regulatory hubs while tax incentives draw secondary investment to peripheral zones.
Seoul Capital Area
Korean Air and Asiana Airlines anchor fleet modernization demand from their Incheon hub bases. MFDS enforces twelve-to-eighteen-month certification timelines that favor incumbent suppliers with established airworthiness histories. The Incheon International Airport corridor clusters AS9100-qualified production facilities for electromechanical actuator assemblies.
Busan-Ulsan
Korea Aerospace Industries operates regional jet final assembly lines that specify integrated flight-deck visibility systems. The Defense Acquisition Program Administration channels KAS-mandated testing protocols through local defense contractors. Ulsan's heavy industrial zones supply aerospace-grade aluminum processing for wiper motor housings.
Daejeon-Sejong
Government research institutes pilot predictive health monitoring algorithms for smart wiper controls under national technology development programs. Sejong's administrative city status attracts regulatory coordination functions between MFDS and defense procurement agencies. Daejeon-based testing laboratories accelerate environmental qualification for military aviation specifications.
Jeju Island
Secondary manufacturing zones exploit tax incentives for MFDS-certified production lines outside Seoul's saturated supply corridor. Business aviation operators source general aviation visibility systems through distributor networks with lighter regulatory oversight. Jeju's aerospace cluster targets standalone service contract opportunities from Korean LCCs unbundling maintenance from heavy checks.
Daegu-Gyeongbuk
Defense UAV programs generate emerging demand for compact, lightweight visibility systems with reduced sweep cycle requirements. Regional suppliers develop backward-compatible control interfaces for retrofit installations on existing Boeing and Airbus fleets. Daegu's manufacturing base transitions from automotive to aerospace electromechanical component production.
South Korea Aircraft Windshield Wiper and Washer System Market Competitive Landscape
Player mix skews toward diversified electromechanical conglomerates with established aerospace quality credentials, creating a tiered structure where AS9100 certification filters out component specialists lacking integrated flight-deck system capabilities. Three strategic archetypes dominate: avionics integrators bundling wiper controls with weather radar displays, precision motion control specialists supplying brushless DC architectures, and legacy hydraulic system providers retreating to aftermarket retrofit niches. Competitive moves concentrate on strategic partnerships with Korean OEMs and technology licensing for predictive maintenance compatibility.
Within the diversified conglomerate tier, Eaton Corporation and Collins Aerospace occupy positions as anchors for long-term Korean OEM relationships, while Moog exemplifies the precision motion control specialist archetype targeting regional jet platforms. These three entities represent distinct competitive vectors—electromechanical portfolio breadth, integrated flight-deck bundling, and actuator precision—rather than overlapping market positions.
| Leading Market Players |
|---|
| Eaton Corporation |
| Moog |
| Collins Aerospace |
| Falgayras |
| Liebherr Aerospace |
| Safran |
| Raytheon Technologies |
| Mitsubishi Heavy Industries |
| Honeywell International |
| Others |
Pricing and Supply Chain Analysis
MFDS certification alignment with FAA airworthiness directives gates both supplier qualification and price differentiation simultaneously, compressing margin pools for uncertified pneumatic specialists while elevating electromechanical incumbents to premium contract tiers. Korean Air and Asiana Airlines unbundle maintenance procurement from heavy checks, forcing pricing transparency across motor overhaul and blade replacement programs.
Pricing Analysis
Certification level creates the primary spread between qualified electromechanical suppliers and aftermarket pneumatic alternatives. Three-tier pricing structure across premium smart-control systems, standard electromechanical units, and economy hydraulic retrofits dominates contract structures. Cost compression in legacy pneumatic tiers intensifies because Korean LCCs demand predictive maintenance compatibility. Airlines with narrow-body fleet modernization programs show least price sensitivity, while general aviation operators in Jeju exhibit highest sensitivity to unit procurement costs.
Supply Chain Analysis
Just-in-time inventory strategies dominate Seoul's Incheon aerospace corridor, where AS9100-qualified facilities maintain minimal buffer stock of aerospace-grade aluminum and rare-earth magnet inputs. Supply concentrates in South Korea, Japan, and Germany for precision actuator components. Raw material dependencies span aerospace-grade aluminum, neodymium magnets, and specialized hydraulic fluids. Single-source vulnerability in rare-earth magnet processing creates structural exposure to energy market volatility. Distribution runs through OEM direct channels for new regional jet platforms and MRO intermediaries for aftermarket blade and pump replacements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Korea's aircraft windshield wiper and washer system market sits in early-cycle expansion, with smart control adoption in Korean-built regional jets creating penetration headroom for electromechanical specialists. Fleet modernization programs at Korean Air and Asiana Airlines sustain demand visibility through sustained replacement cycles.
For Market Incumbents: Fortify AS9100-certified production capacity in Seoul's Incheon corridor to defend against Jeju-based secondary manufacturing zones attracting tax-incentivized competitors. Deepen backward integration into aerospace-grade aluminum processing to offset raw material volatility squeezing wiper motor margins. Lock multi-year availability commitments with Korean Aerospace Industries before MFDS-FAA harmonization accelerates new entrant qualification timelines. For New Entrants and Emerging Players: Predictive health monitoring service gaps in Korean LCC aftermarket contracts offer white-space entry points where incumbents under-serve unbundled procurement models. Target standalone wiper motor overhaul agreements at Incheon hub carriers piloting subscription-based availability structures. Pursue KAS qualification for military aviation specifications where hardened environmental testing sustains pricing premiums above commercial equivalents. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with dormant aerospace electromechanical divisions lacking MFDS certification histories. Long-term viability hinges on exposure to Korean OEM platform standardization and defense UAV program expansion. Watch smart control integration rates with flight management systems as the inflection signal separating electromechanical consolidation from pneumatic obsolescence.| Strategic Initiative | Industry Significance |
|---|---|
| AS9100 Certification Investment | MFDS qualification timelines favor incumbents with established aerospace quality credentials. |
| Smart Control Platform Integration | Bundled avionics compatibility with weather radar displays commands premium contract positioning. |
| Jeju Manufacturing Footprint | Tax incentives attract secondary production capacity outside Seoul's saturated Incheon corridor. |
| Military Aviation Qualification | KAS-mandated testing protocols sustain pricing premiums through hardened environmental specifications. |
| Predictive Maintenance Service Launch | Korean LCCs pilot subscription availability models decoupling wiper system upkeep from heavy checks. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with aerospace procurement officers, MFDS regulatory specialists, fleet maintenance directors at Korean carriers, and electromechanical engineering leads; and secondary validation through FAA airworthiness directive filings, KAS testing protocol documentation, Korea Aerospace Industries supplier qualification records, and customs data on aerospace-grade aluminum imports. Bottom-up triangulation across component-level bill-of-materials analysis and top-down fleet modernization spend projections anchored value estimates.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning product type, technology architecture, application sector, and end-user procurement authority. CAGRs derived from fitted adoption curves for electromechanical displacement of pneumatic systems and elasticity-adjusted pricing responses to rare-earth input volatility. Forecast inputs incorporated Korean Air and Asiana Airlines fleet replacement schedules and Defense Acquisition Program Administration UAV program procurement timelines.
Forecasts assume regulatory continuity in MFDS-FAA harmonization and KAS military specification stability; material policy shifts in certification reciprocity or defense procurement localization would require re-modeling. Revision becomes warranted when smart control penetration in new Korean-built platforms crosses thresholds that trigger pneumatic supplier exit acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Safety Systems
Free Fall Sensor Market
Aircraft Safety Systems
Aircraft Arresting System Market
Aircraft Safety Systems
Commercial Parachute Market
Aircraft Safety Systems
Helicopter Emergency Flotation System Market
Aircraft Safety Systems
Commercial Aircraft Carbon Brakes Market
Aircraft Safety Systems
Military Airborne Collision Avoidance Systems (ACAS) Market
Aircraft Safety Systems
Commercial Aircraft Collision Avoidance System Market
Aircraft Safety Systems
Aircraft Ice Protection System Market
Aircraft Safety Systems
Commercial Aircraft Evacuation System Market
Aircraft Safety Systems
Rescue Hoist System Market
Aircraft Safety Systems
Identification Friend or Foe Systems Market
Aircraft Safety Systems
Aircraft Lightning Protection Market
Aircraft Safety Systems
Aircraft Door Dampers Market
Aircraft Safety Systems
Instrument Landing System (ILS) Market
Aircraft Safety Systems
Aerospace Lightning Strike Protection Market
Aircraft Safety Systems
Aviation Life Rafts Market