
 Ice Protection Systems Market | 2026-2036
Ice Protection Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Ice Protection Systems Market Outlook
The ice protection market is pivoting on a widening gap between certified aerospace-grade systems and commodity de-icing chemicals for ground operations. Honeywell International Inc. leverages its integrated avionics-to-thermal-management pipeline to dominate cockpit and wing leading-edge contracts. Clariant AG anchors its position through captive supply of glycol-based formulations and specialty surfactants for runway and aircraft applications. Curtiss-Wright Corporation differentiates via electromechanical actuator expertise that extends into heated probe and sensor protection for military platforms.
Ice protection systems encompass engineered thermal, mechanical, and chemical solutions designed to prevent or remove ice accumulation on critical surfaces operating below freezing, typically employing resistive heating elements, pneumatic boots, or hygroscopic fluids with operational thresholds between minus forty and plus five degrees Celsius. Their primary purpose is sustaining aerodynamic integrity, structural load capacity, and sensor functionality across flight, maritime, and renewable energy infrastructure. Electro-thermal and smart systems categories are capturing margin pools as OEMs phase out legacy pneumatic boots in favor of lighter, digitally monitored architectures. Coatings and surface modification segments remain mature with compressed pricing, while hybrid solutions are gaining traction in wind energy blade applications where intermittent icing events demand adaptive response protocols.
FAA airworthiness standards under Part 25 Appendix C, EASA CS-25 icing certification requirements, and ISO 12494 atmospheric icing specifications for wind turbines collectively mandate validated performance across simulated glaze, rime, and mixed-phase conditions. These frameworks shape demand by disqualifying uncertified suppliers from OEM qualification lists and forcing recurrent retrofit investments when protocols tighten. Stakeholders must monitor evolving supercooled large droplet test envelopes and corresponding recertification timelines to anticipate engineering resource allocation and inventory positioning.
Market Dynamics
Electro-thermal architectures are systematically displacing pneumatic de-icing boots across commercial aviation platforms, forcing OEMs to requalify supply chains around resistive heating elements and integrated sensor networks rather than mechanical inflation systems.
Growth Catalysts
- FAA Part 25 Appendix C mandates:Stricter supercooled large droplet testing requirements compel fleet operators to retrofit legacy platforms with certified ice protection suites, sustaining replacement demand across narrow-body and regional aircraft categories.
- Wind energy blade scaling:Offshore turbine installations in the North Sea and Baltic regions encounter severe atmospheric icing, driving specification of hybrid electro-thermal and hydrophobic coating systems for rotor diameters exceeding 120 meters.
- Carbon fiber leading-edge adoption:Composite wing structures in next-generation single-aisle programs require embedded heating element integration rather than externally mounted boots, pulling specialized thermal management contracts toward tier-one aerostructures suppliers.
Market Restraints
- Specialized conductive polymer supply:Aerospace-grade polyimide films and silver nanowire inks concentrate among Japanese and German chemical processors, exposing system integrators to allocation risk during semiconductor industry demand spikes.
- EASA CS-25 recertification timelines:Amendment cycles for ice detection algorithm validation extend eighteen to thirty-six months, freezing engineering resources and delaying platform entry-into-service schedules for derivative aircraft programs.
- Glycol-based ground de-icing substitution:Runway de-icing fluid formulations using potassium acetate and sodium formate achieve comparable performance at lower unit costs, compressing addressable market scope for thermal in-flight systems in short-haul operations.
Strategic Opportunities
- Unmanned aerial system integration:Beyond-visual-line-of-sight drone operations in Nordic and Alpine corridors lack mature ice protection standards, creating first-mover positioning for lightweight electro-thermal mat suppliers serving logistics and surveillance platforms.
- EU Green Deal aviation decarbonization incentives:Funding mechanisms for sustainable aviation technologies prioritize weight-reduction initiatives, advantaging electro-thermal systems over pneumatic alternatives in competitive tender evaluations for regional aircraft retrofits.
- Predictive maintenance convergence:Ice detection sensor data streams fused with digital twin architectures enable condition-based heating activation rather than continuous operation, opening software and analytics revenue layers atop hardware supply contracts.
Industry Challenges
- Multiphysics simulation expertise scarcity:Coupled thermal-structural-aerodynamic modeling for heated leading-edge certification requires specialized computational fluid dynamics competencies concentrated among legacy aerospace engineering centers in Wichita, Toulouse, and Hamburg.
- Legacy platform integration complexity:Retrofitting electro-thermal systems onto aircraft originally designed for pneumatic boots demands extensive wiring harness modification and power distribution upgrades, extending downtime and maintenance cost estimates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ice Protection Systems Market |
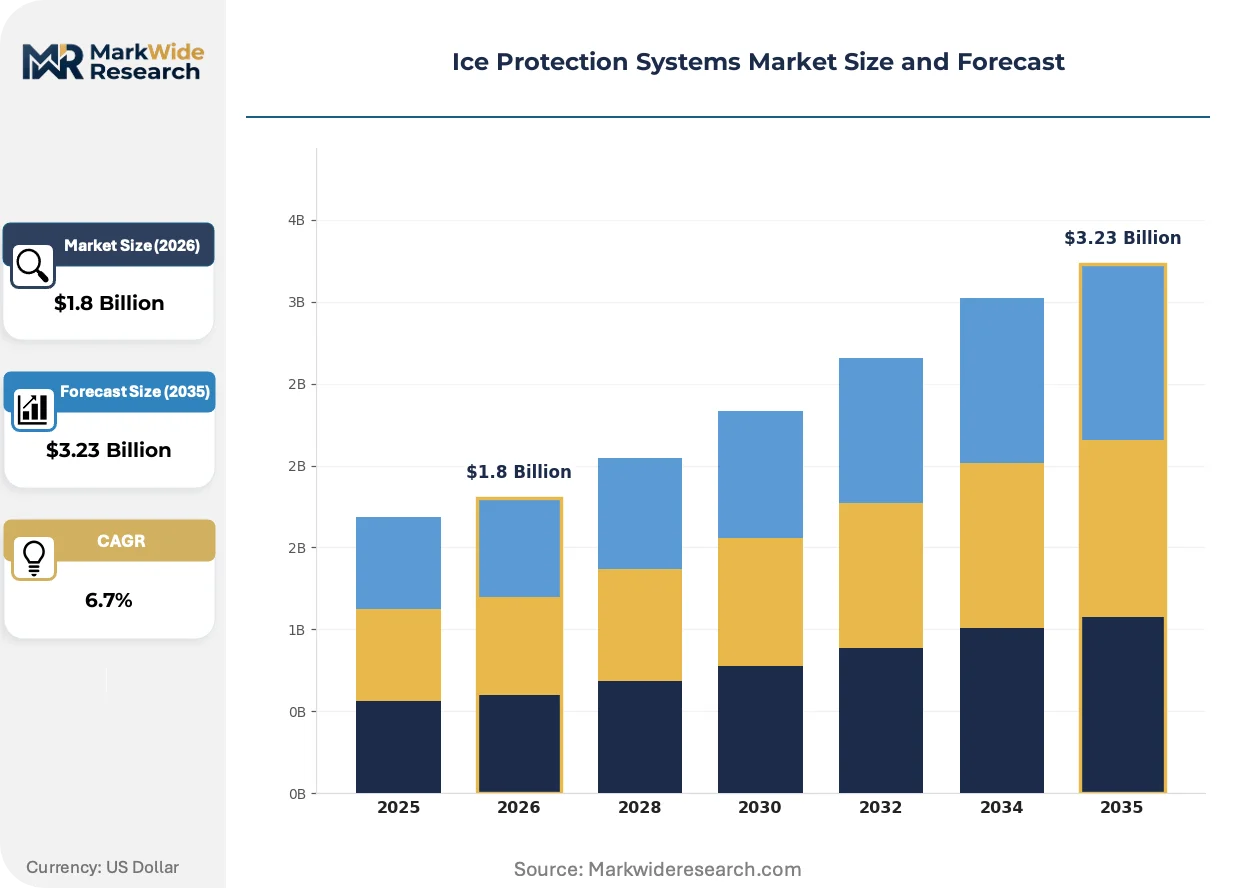
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heating Systems, Coatings, De-icing Agents, Anti-icing Systems Application: Aerospace, Marine, Wind Energy, Transportation Technology: Conventional Systems, Smart Systems, Hybrid Solutions, Surface Modification End User: OEMs, Utilities, Transportation Companies, Maintenance Services |
| Companies Covered | Honeywell International Inc., Clariant AG, The Dow Chemical Company, Curtiss-Wright Corporation, JBT Corporation, Collins Aerospace, Meggitt PLC, Zodiac Aerospace, CAV Ice Protection, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ice Protection Systems Market Strategic Shifts
Digitalization of thermal management is converging with advanced materials science to produce adaptive ice protection architectures that respond to real-time atmospheric conditions rather than operating on fixed schedules.
Carbon nanotube heating films are integrating into wing leading-edge structures as lightweight alternatives to etched-foil resistive elements. Bombardier and Embraer regional jet programs specify these materials for their improved power density and damage tolerance. The technology is integrating thermal management directly into composite manufacturing processes, compressing subsystem count and assembly labor hours.
REACH restrictions on perfluorinated compounds are compelling reformulation of hydrophobic coatings used in runback ice prevention. European suppliers accelerate bio-based surfactant development to maintain water-repellency performance without restricted chemistries. Wind turbine OEMs in Denmark and Germany face compressed qualification timelines as coating suppliers scramble to validate alternatives before 2026 restriction enforcement.
Airline technical procurement departments consolidate vendor relationships around full-wing ice protection system integrators rather than component-level sourcing. Maintenance, repair, and overhaul facilities in the United States and United Kingdom now contract directly with thermal management specialists for heated probe and sensor refurbishment, bypassing traditional avionics distributors. This channel compression concentrates pricing leverage among qualified system houses with captive repair station networks.
Ice Protection Systems Market Segmentation
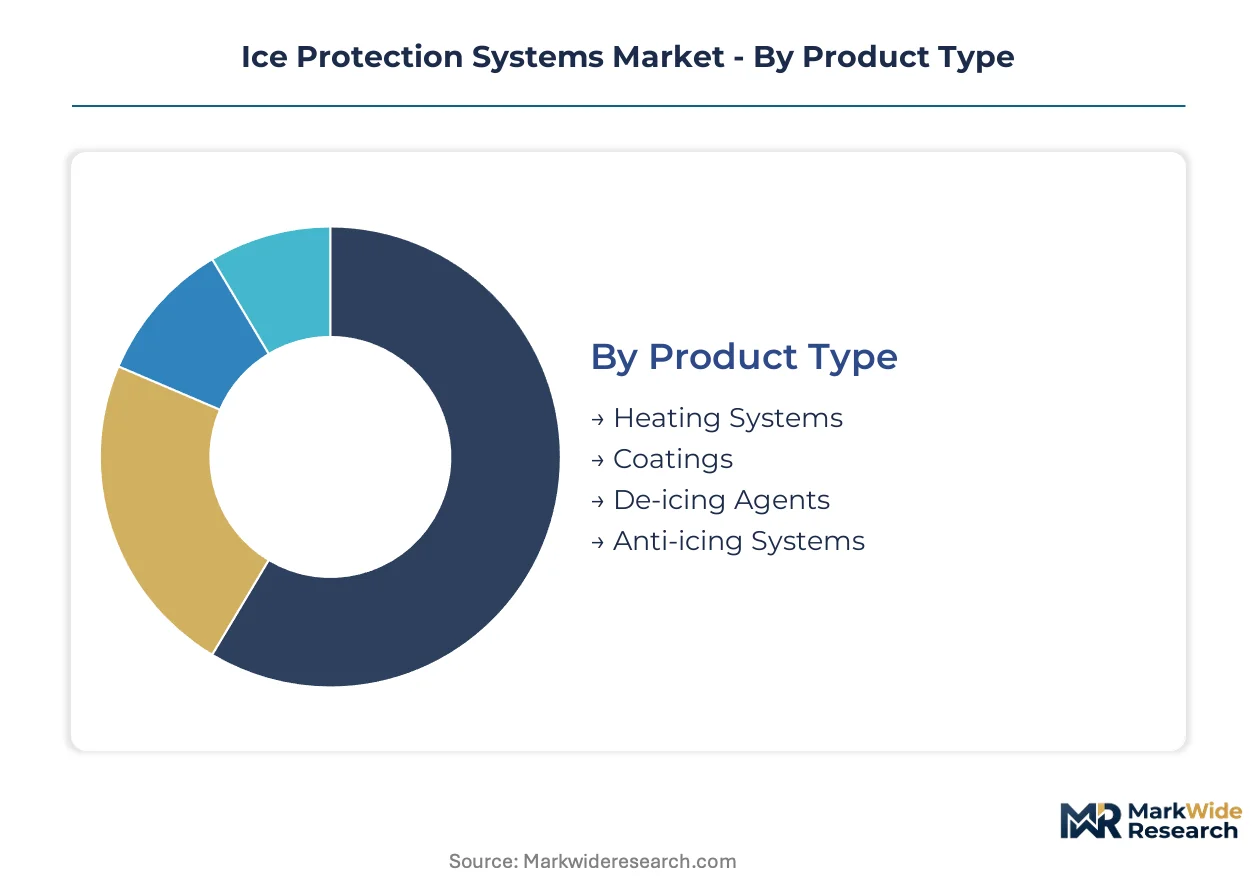
Ice protection systems fragment across four intersecting dimensions where technology maturity, regulatory certification tiers, and end-use operational intensity create distinct margin profiles. Understanding these segment boundaries clarifies where engineering resources concentrate versus where commodity substitution threatens pricing power.
Product Type:
Retrofit cycles and platform renewal timelines determine which product categories capture procurement budgets across aviation and energy infrastructure.
- Heating Systems:Electro-thermal architectures employing resistive heating elements embedded in composite leading edges dominate commercial aviation specifications. Boeing and Airbus single-aisle programs in the United States and France specify these systems for their weight advantage over pneumatic alternatives, with FAA Part 25 Appendix C compliance driving fleet-wide replacement demand.
- Coatings:Hydrophobic and ice-phobic surface treatments reduce ice adhesion strength through chemical modification rather than active thermal input. Wind turbine OEMs in Denmark specify these for rotor blade leading edges where intermittent icing events favor passive protection, though REACH restrictions on perfluorinated compounds are forcing reformulation investments.
- De-icing Agents:Glycol-based and potassium acetate formulations remove accumulated ice through chemical melting action, primarily deployed for ground operations.
- Anti-icing Systems:Continuous-flow fluid systems prevent ice formation on critical surfaces through hygroscopic film maintenance.
Volume placements concentrate in Heating Systems; the faster expansion belongs to Coatings.
Application:
Operational environment severity and asset criticality shape specification intensity across end-use sectors.
- Aerospace:Commercial and military aircraft demand certified thermal management for wings, engines, and sensor probes. EASA CS-25 icing certification requirements in Germany and France mandate validated performance across supercooled large droplet conditions, with regional jet programs in Brazil and Canada specifying carbon nanotube heating films for improved power density.
- Wind Energy:Offshore turbine installations in the North Sea encounter atmospheric icing that degrades aerodynamic efficiency and structural loading. Danish and German OEMs specify hybrid electro-thermal and coating systems for rotor diameters exceeding 120 meters, with ISO 12494 compliance required for Baltic region projects.
- Marine:Vessel superstructures and offshore platforms require ice management for operational safety in polar routes.
- Transportation:Rail and roadway infrastructure deploy chemical and thermal systems for switch heating and tunnel de-icing.
Procurement volumes cluster in Aerospace; Wind Energy is climbing the fastest as offshore scaling accelerates.
Technology:
Digital integration and materials science advances are compressing the performance gap between established and emerging technical approaches.
- Smart Systems:Sensor-networked architectures with predictive ice detection algorithms enable condition-based heating activation rather than continuous operation. These systems integrate with digital twin platforms for maintenance optimization, with United States-based airlines contracting directly with thermal management specialists for heated probe refurbishment.
- Hybrid Solutions:Combined electro-thermal and passive coating approaches adapt protection intensity to real-time atmospheric conditions. Wind energy applications in Norway and Sweden favor these for variable icing severity, with power consumption optimization driving specification over pure thermal systems.
- Conventional Systems:Pneumatic boots and resistive foil heaters maintain installed base across legacy aircraft platforms.
- Surface Modification:Microstructured and chemically treated surfaces alter ice nucleation behavior without active energy input.
Installed base dominance remains with Conventional Systems; Hybrid Solutions are gaining share fastest through adaptive response protocols.
End User:
Procurement centralization and technical capability determine whether system integrators or component suppliers capture contract value.
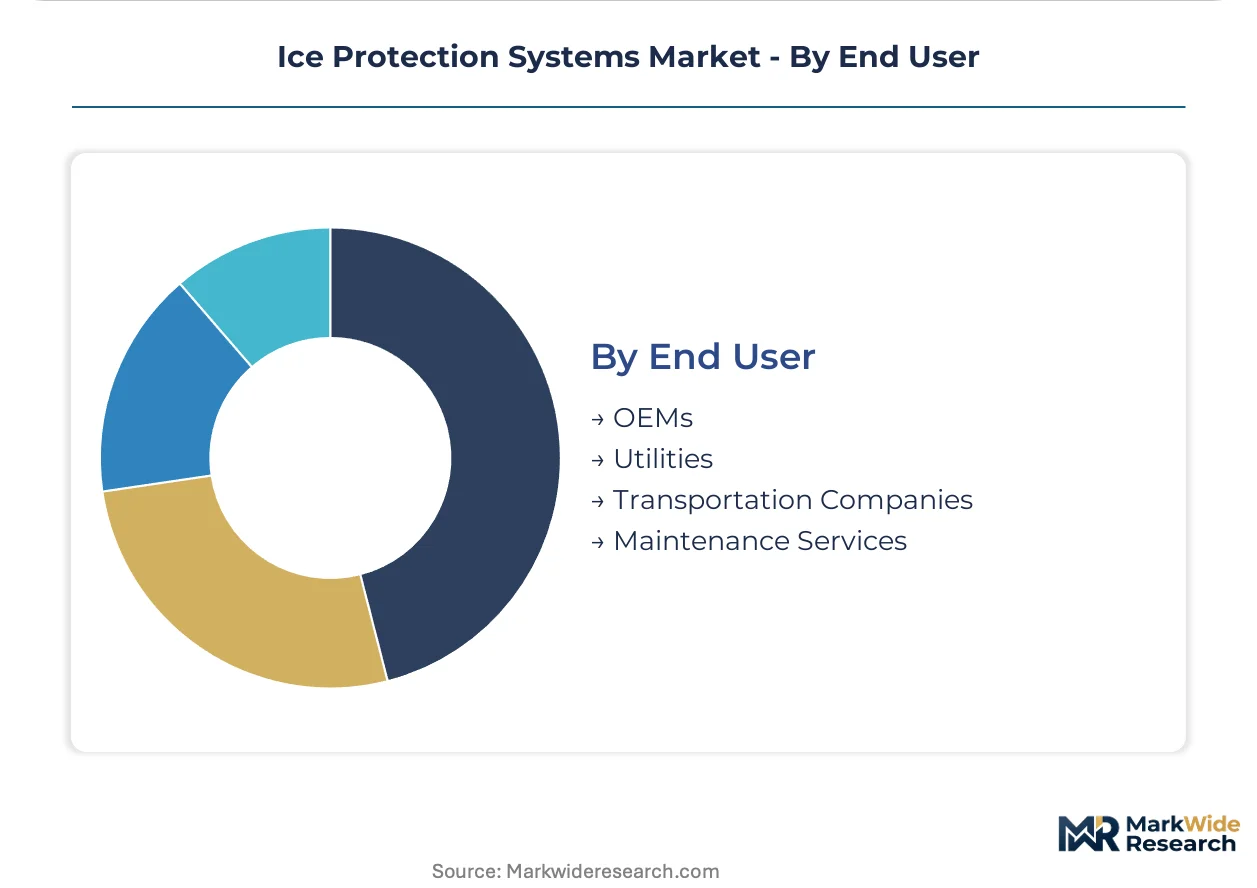
- OEMs:Original equipment manufacturers in commercial aviation and wind energy consolidate vendor relationships around full-wing ice protection system integrators rather than component sourcing. Boeing and Airbus thermal management contracts in the United States and France pull specialized heating element suppliers into tier-one aerostructures partnerships.
- Utilities:Wind farm operators in Germany and Denmark contract for blade ice protection as part of turbine supply agreements, with service-level commitments driving long-term maintenance arrangements.
- Transportation Companies:Airlines and rail operators manage retrofit programs and scheduled replacements.
- Maintenance Services:MRO facilities in the United Kingdom and United States bypass traditional avionics distributors for heated probe and sensor refurbishment.
Contract value concentrates with OEMs; Maintenance Services show the steepest expansion trajectory as channel compression intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wichita, Kansas anchors aerospace engineering concentration for ice protection systems, with embedded thermal management expertise concentrated among legacy engineering centers. Toulouse and Hamburg sustain parallel aerostructures development clusters for heated leading-edge certification. Industrial specialization across these corridors shapes procurement patterns for resistive heating elements and integrated sensor networks.
United States
FAA Part 25 Appendix C mandates drive fleet-wide retrofit demand across narrow-body and regional aircraft categories. Defense modernization budgets sustain premium system orders for military platforms requiring heated probe and sensor protection. Wichita engineering centers concentrate multiphysics simulation expertise for coupled thermal-structural-aerodynamic modeling.
Germany
Wind energy blade scaling in the North Sea and Baltic regions accelerates specification of hybrid electro-thermal and hydrophobic coating systems. EASA CS-25 recertification timelines for ice detection algorithm validation extend engineering resource commitments. Hamburg aerostructures clusters integrate carbon nanotube heating films into composite manufacturing processes for regional jet programs.
France
EU Green Deal aviation decarbonization incentives prioritize weight-reduction initiatives in competitive tender evaluations. EASA icing certification requirements mandate validated performance across supercooled large droplet conditions. Toulouse engineering centers concentrate thermal management contract awards for single-aisle platform development.
United Kingdom
Maintenance, repair, and overhaul facilities contract directly with thermal management specialists for heated probe refurbishment. REACH restrictions on perfluorinated compounds compel reformulation investments for runway de-icing applications. Channel compression concentrates pricing leverage among qualified system houses with captive repair station networks.
Denmark
Offshore turbine installations encounter severe atmospheric icing that degrades aerodynamic efficiency and structural loading. ISO 12494 atmospheric icing specifications mandate compliance for Baltic region wind energy projects. Danish OEMs specify hybrid electro-thermal and coating systems for rotor diameters exceeding 120 meters.
Ice Protection Systems Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the ice protection systems value chain. Integrated system houses with captive aerostructures partnerships capture full-wing thermal management contracts, while specialized component suppliers concentrate on resistive heating elements and sensor modules. Three archetypes dominate: vertically integrated aerospace conglomerates with avionics-to-thermal pipelines; chemical processors with captive surfactant and glycol formulation capabilities; and electromechanical specialists extending actuator expertise into heated probe applications. Competitive moves center on strategic partnerships for composite embedding qualifications and geographic expansion into Nordic wind energy corridors.
Among diversified industrial conglomerates, Honeywell International Inc. and Curtiss-Wright Corporation exemplify the integrated-systems archetype, anchoring positions through breadth across avionics and thermal management domains. Clariant AG represents the chemical-specialist tier, with AG suffix indicating Swiss corporate structure and positioning grounded in formulation chemistry rather than electromechanical hardware. These three entities occupy distinct competitive spaces—Honeywell and Curtiss-Wright competing for aerospace platform integration contracts, Clariant securing ground-de-icing and coating supply relationships—without direct product overlap in core thermal architectures.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Clariant AG |
| The Dow Chemical Company |
| Curtiss-Wright Corporation |
| JBT Corporation |
| Collins Aerospace |
| Meggitt PLC |
| Zodiac Aerospace |
| CAV Ice Protection |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal aviation decarbonization incentives gate qualified supply and premium-tier pricing access for ice protection systems, restricting OEM procurement lists to suppliers with validated lightweight electro-thermal architectures and embedded composite heating qualifications. REACH restrictions on perfluorinated compounds further bifurcate the coatings segment between reformulation-compliant European suppliers and price-compressed commodity alternatives.
Pricing Analysis
Fleet uptime guarantees anchor value-based pricing for certified ice protection suites, with contracts tied to operational availability rather than hardware unit costs. Three-tier pricing structure across premium, standard, and economy levels separates FAA Part 25 Appendix C-certified systems from uncertified alternatives and ground-de-icing commodities. Cost compression in the coatings tier is intensifying because potassium acetate formulations achieve comparable runway performance at lower unit costs. Regional airlines and short-haul operators exhibit highest price sensitivity; defense modernization programs and offshore wind utilities demonstrate lowest.
Supply Chain Analysis
Aerospace-grade polyimide films and silver nanowire inks rest on Japanese and German specialty chemical processors, exposing system integrators to allocation risk during semiconductor industry demand spikes. Carbon nanotube heating films and resistive element substrates draw from United States composite manufacturing clusters and French aerostructures partnerships. Single-source vulnerability concentrates in conductive polymer supply channels. Distribution runs through tier-one aerostructures suppliers with captive repair station networks rather than traditional avionics distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ice protection systems represent a consolidation play as EASA CS-25 recertification timelines and specialized multiphysics simulation requirements force weaker engineering houses out of qualified supplier lists.
For Market Incumbents: Hedge against pneumatic boot obsolescence by accelerating carbon nanotube heating film integration into composite manufacturing processes. Secure backward integration into silver nanowire ink supply through long-term offtake agreements with Japanese chemical processors. Channel control via captive repair station networks in the United Kingdom and United States defends margin position against direct airline procurement of component-level suppliers. For New Entrants and Emerging Players: Enter via unmanned aerial system ice protection for beyond-visual-line-of-sight logistics platforms in Nordic and Alpine corridors, where mature standards do not yet exist. Wind energy blade applications in Norway and Sweden offer penetrable white-space for hybrid electro-thermal and coating system specialists. Go-to-market leverage centers on predictive maintenance software layers atop hardware supply contracts. For Investors and Strategic Acquirers: FAA Part 25 Appendix C retrofit program announcements across narrow-body fleets are the leading indicator that replacement demand cycles are accelerating. Five-to-ten year viability favors acquisition targets with embedded composite heating qualifications and existing EASA certification relationships. Watch for supercooled large droplet test envelope expansions as the signal forcing recurrent engineering resource commitments.| Strategic Initiative | Industry Significance |
|---|---|
| Composite Embedding Qualification | Carbon nanotube heating film integration into Boeing and Airbus single-aisle programs compresses subsystem assembly labor. |
| Backward Integration into Conductive Polymers | Captive supply of silver nanowire inks from Japanese processors reduces allocation exposure during semiconductor demand spikes. |
| Predictive Maintenance Software Development | Digital twin architectures for condition-based heating activation open recurring revenue atop hardware contracts. |
| Nordic Wind Energy Corridor Expansion | Hybrid system specifications for Baltic region offshore turbines capture ISO 12494 compliance premiums. |
| Repair Station Network Acquisition | Channel compression in United States and United Kingdom MRO facilities concentrates pricing leverage among qualified system houses. |
Study Parameters
Independent corroboration across thermal management engineering directors, airline technical procurement officers, wind farm operations managers, and EASA certification specialists underwrites the qualitative findings in this study. Primary interviews with OEM platform engineers and tier-one aerostructures suppliers combined with secondary validation from FAA airworthiness directive filings, EASA CS-25 amendment records, and ISO 12494 wind turbine icing specifications. Customs data on conductive polymer trade flows and SEC filings from diversified industrial conglomerates provided demand-side triangulation against bottom-up segment modeling.
Rate-of-change decomposition across the analysis window separates volume growth from price-mix effects in electro-thermal system displacement of pneumatic boots. Segmentation dimensions modeled include product type, application intensity, technology maturity, and end-user procurement centralization, with additional granularity on certification tier and composite integration depth. CAGRs derive from installed base retirement schedules and platform entry-into-service timelines, incorporating wind energy blade scaling curves and defense modernization budget trajectories as industry-specific inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under supercooled large droplet test envelope expansions or REACH restriction acceleration. Forecasts reflect documented assumptions on fleet renewal timing and offshore wind installation rates. A small set of named triggers—EASA algorithm validation delays, conductive polymer supply shocks, and EU Green Deal funding disbursement pacing—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Environment Control
Airborne Molecular Contamination Control Services Market
Aircraft Environment Control
Turbine Air Filtration Market
Aircraft Environment Control
Commercial Aircraft Air Management System Market
Aircraft Environment Control
Aircraft Air Conditioning Unit Market
Aircraft Environment Control
Gas Turbine Air Filtration Market
Aircraft Environment Control
HUD-Compatible Low-Haze Windshield Defogging Coating Systems Market
Aircraft Environment Control
Aircraft Waste Tank Market
Aircraft Environment Control
Aerospace Flight Control System Market