
 Helicopter Flight Control Systems Market | 2026-2036
Helicopter Flight Control Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Helicopter Flight Control Systems Market Analysis
The premium-commodity split in helicopter flight control systems is shifting toward software-defined architectures with integrated health monitoring, while mechanical and basic hydraulic systems face contracting margins in legacy fleet sustainment. Boeing leverages deep integration with military prime contracts to sustain long-term platform control. Safran Helicopter Engines anchors European supply through dedicated rotorcraft actuator and FADEC production. Honeywell International differentiates via integrated avionics-flight control bundles that dominate the commercial and military retrofit channel.
Helicopter flight control systems comprise the hardware and software assemblies that translate pilot inputs into aerodynamic surface commands, typically incorporating actuators, sensors, and computing modules operating at response latencies below 50 milliseconds to maintain rotorcraft stability in hover and low-speed regimes. The primary commercial purpose centers on reducing pilot workload while expanding operational envelopes in degraded visual environments. Fly-by-wire architectures now lead system type demand as military operators mandate handling quality improvements and weight reduction in next-generation rotorcraft. Digital control technology within the technology segment captures the fastest expansion trajectory, driven by artificial intelligence-assisted flight envelope protection and sensor fusion requirements. Search and rescue and aerial surveillance applications concentrate margin pools where mission-critical reliability commands premium pricing and multi-year sustainment contracts.
FAA Part 29 airworthiness standards and EASA CS-29 certification frameworks govern commercial and military derivative rotorcraft, with both regulators intensifying focus on software assurance levels under DO-178C for digital flight control. The EU AI Act introduces emerging compliance obligations for autonomous decision layers in next-generation stabilization systems. Stakeholders must monitor how civil-military certification convergence affects development timelines and whether dual-use qualification strategies can compress path-to-market for advanced control architectures.
Market Dynamics
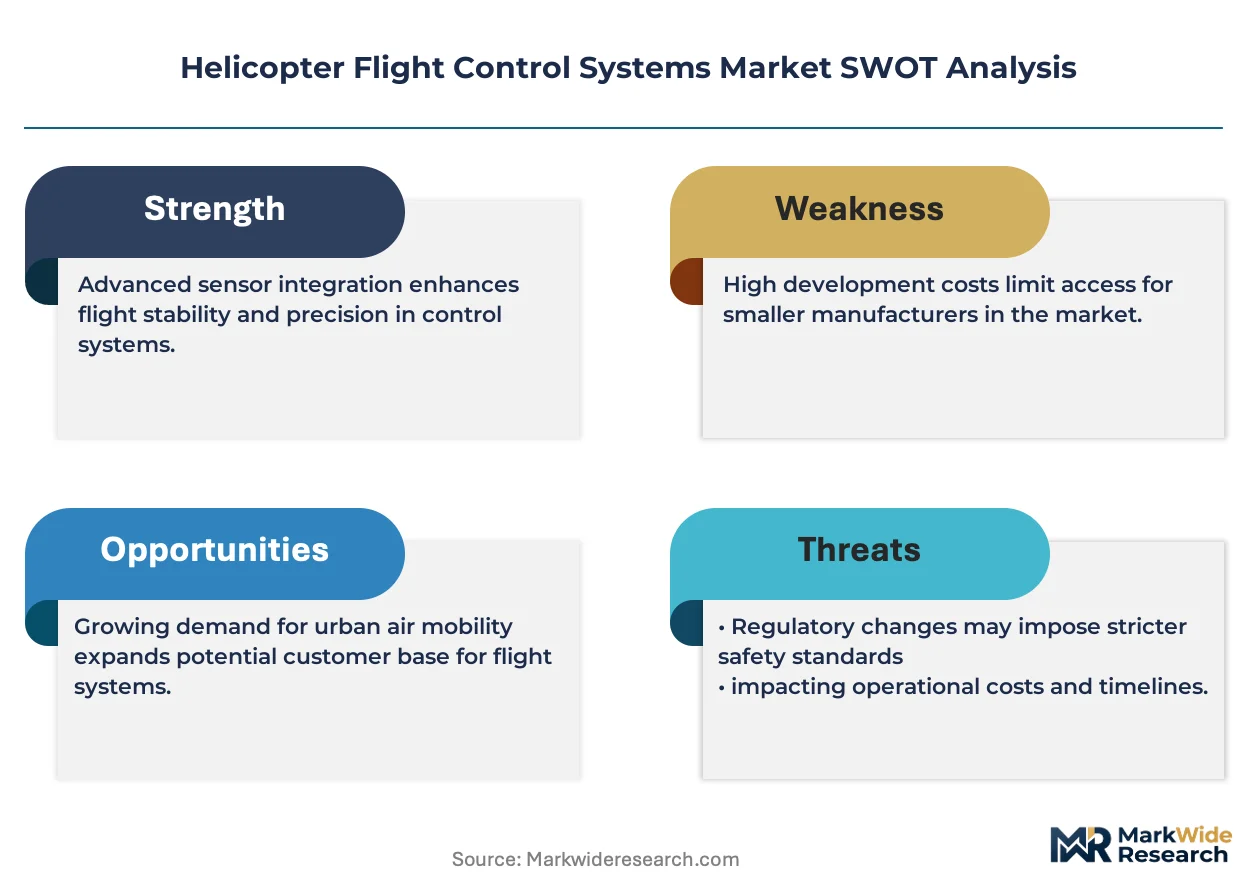
The military shift from mechanical to digital fly-by-wire architectures is compressing supplier margins on legacy hydraulic actuators while creating premium capture opportunities for integrated flight control-avionics bundles. FAA Part 29 certification tightening around DO-178C software assurance levels is extending development timelines and favoring incumbents with established validation infrastructure.
Growth Catalysts
- Army Future Vertical Lift procurement:The US Army's next-generation rotorcraft program mandates full-authority digital flight control systems, generating sustained demand for redundant computing architectures and electromechanical actuators across attack and utility helicopter variants.
- FAA Part 29 software validation standards:Stricter DO-178C certification requirements for commercial rotorcraft are forcing fleet operators toward certified digital control retrofits, accelerating replacement cycles for aging analog systems in offshore oil transport and emergency medical services.
- Artificial intelligence-assisted envelope protection:Machine learning algorithms for real-time stability augmentation are penetrating search and rescue and aerial surveillance platforms where mission-critical reliability commands extended sustainment contracts.
Market Restraints
- Semiconductor supply concentration:Specialized radiation-hardened processors for military flight computers source from a concentrated US and European foundry base, exposing programs to single-source risk and 18-24 month lead times.
- Titanium and rare earth magnet costs:High-performance actuator motors depend on neodymium and dysprosium supply chains concentrated in Chinese processing facilities, creating input cost volatility for electromechanical system manufacturers.
- DO-178C certification friction:The FAA's intensified software assurance documentation requirements add 12-18 months to digital control system qualification, compressing program profitability for competitive bids.
Strategic Opportunities
- Urban air mobility integration:Electric vertical takeoff and landing developers in Germany and the United States require lightweight, fault-tolerant flight control architectures, opening adjacent demand beyond traditional rotorcraft OEMs.
- EU AI Act autonomous systems pathway:The European Union's emerging framework for safety-critical artificial intelligence creates first-mover advantage for control system suppliers establishing compliant validation methodologies for next-generation stabilization algorithms.
- Health monitoring convergence:Sensor fusion between flight control actuators and predictive maintenance platforms enables subscription-based sustainment models, shifting revenue from hardware sales to recurring service contracts in commercial operator fleets.
Industry Challenges
- Embedded software engineering scarcity:DO-178C-qualified developers with rotorcraft domain expertise command premium compensation, constraining program staffing for mid-tier suppliers competing on military and commercial bids.
- Legacy platform integration complexity:Digital fly-by-wire retrofits into Vietnam-era airframes require mechanical-to-electrical interface engineering that prolongs qualification timelines and inflates non-recurring engineering costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Helicopter Flight Control Systems Market |
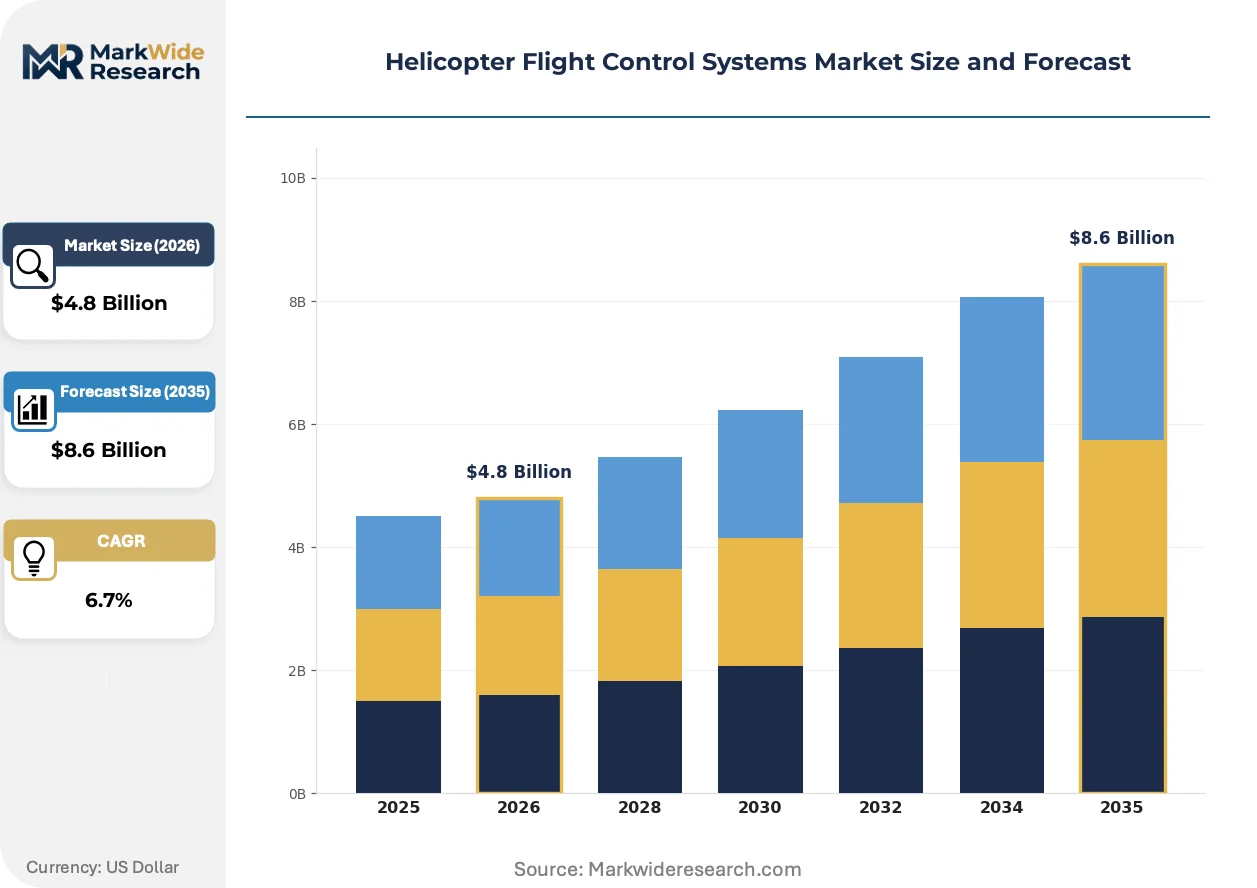
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Fly-by-Wire, Mechanical, Hydraulic, Hybrid End User: Military, Commercial, Emergency Services, Law Enforcement Technology: Digital Control, Stabilization Systems, Autopilot, Feedback Control Application: Search and Rescue, Cargo Transport, VIP Transportation, Aerial Surveillance |
| Companies Covered | Boeing, Bell Flight, BAE Systems, Safran Helicopter Engines, MD Helicopters, Honeywell International, Airbus Helicopters, Leonardo Helicopters, Thales, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Helicopter Flight Control Systems Market Emerging Trajectories
Software-defined architectures are displacing hardware-centric control implementations across military and commercial rotorcraft segments. Three forces are compressing traditional supplier margins while redistributing value toward integrated system providers.
Electromechanical actuators with integrated health monitoring are converging with artificial intelligence-driven predictive maintenance platforms. Military operators in NATO procurement programs are mandating these architectures for next-generation attack and heavy-lift platforms. The technology convergence is compressing supplier margins on standalone hydraulic actuators while enabling multi-year performance-based logistics contracts that lock in sustainment revenue.
The EU AI Act's safety-critical systems provisions are imposing new documentation burdens on autonomous decision layers in flight envelope protection. European helicopter OEMs must now establish algorithmic transparency and human-override protocols for certification. Commercial derivatives of military platforms face the steepest compliance ramps, with EASA CS-29 applicants restructuring development workflows to satisfy dual civil-military qualification paths.
Service-based contracting is displacing transactional hardware sales in offshore oil transport and emergency medical services fleets. Operators in the North Sea and Gulf of Mexico are unbundling control system procurement from integrated availability guarantees. This behavioral shift concentrates purchasing power with platform-agnostic maintenance providers and compresses OEM direct sales channels in mature commercial segments.
Helicopter Flight Control Systems Market Segmentation
Helicopter flight control system procurement follows distinct upgrade cycles across military and commercial fleets. Each segmentation dimension reveals where platform modernization concentrates investment and where legacy sustainment retains relevance.
System Type:
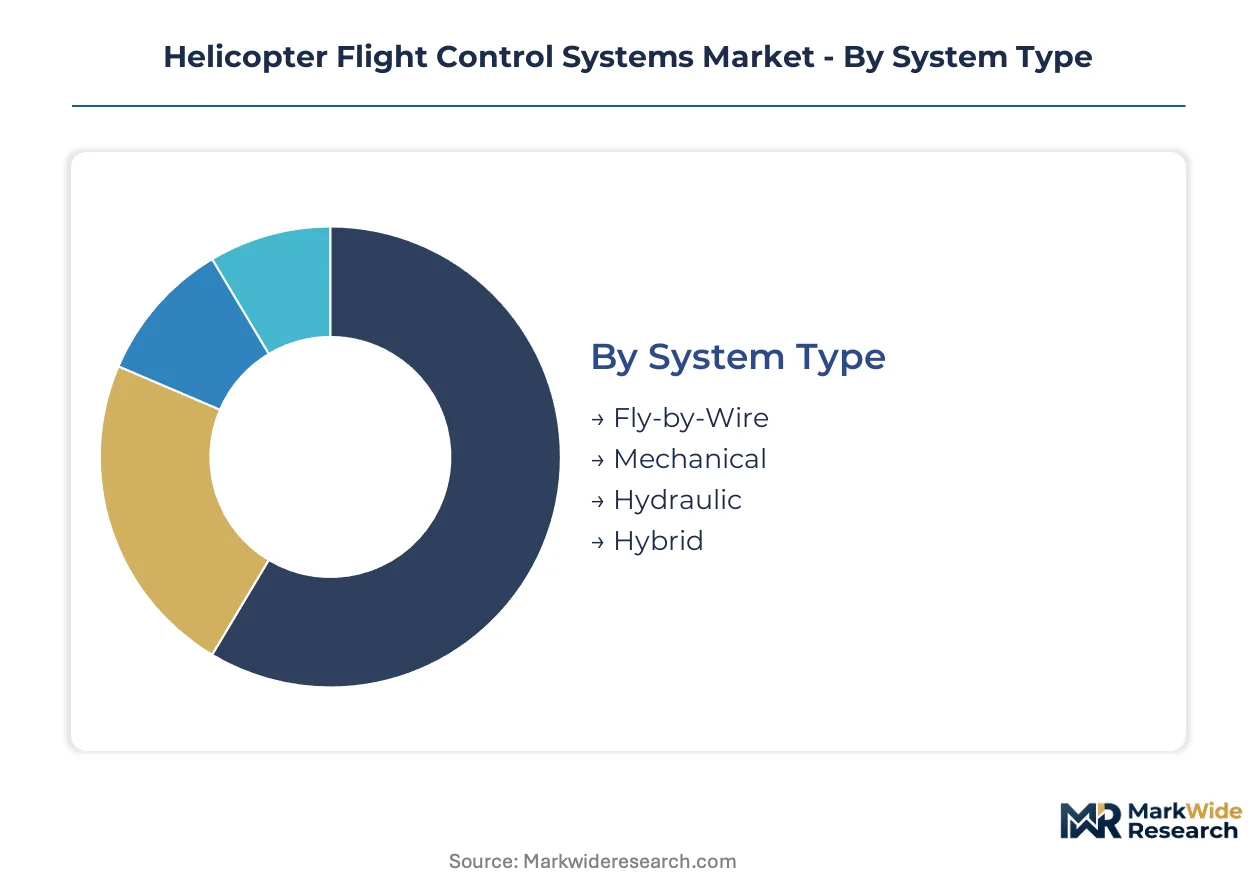
Platform replacement cycles drive divergence between installed-base sustainment and new-build specification, with digital architectures displacing mechanical and hydraulic alternatives in forward production.
- Fly-by-Wire:Full-authority digital architectures replace mechanical linkages with data buses and electromechanical actuators, achieving sub-50-millisecond response latencies. Military procurement across NATO members concentrates specification here, driven by weight reduction mandates and handling quality improvements in next-generation rotorcraft.
- Mechanical:Pushrod and cable systems persist in legacy fleet sustainment where certification grandfathering limits retrofit economics. Vietnam-era airframes in commercial utility roles retain these systems where DO-178C compliance costs exceed platform residual value.
- Hydraulic:Power-assisted mechanical systems dominate mid-life military platforms and heavy-lift commercial helicopters requiring high-force actuation. Supply chain concentration in titanium and rare earth magnet inputs creates cost volatility for electromechanical alternatives.
- Hybrid:Partial digital augmentation of mechanical backbones bridges certification timelines for derivatives of mature airframes. Offshore oil transport operators specify these architectures to gain envelope protection without full fly-by-wire recertification burden.
Volume placements concentrate in Hydraulic systems sustaining legacy fleets; the faster expansion belongs to Fly-by-Wire architectures capturing new military and urban air mobility specifications.
End User:
Procurement authority and mission-critical reliability requirements segment pricing power and contract structure across operator categories.
- Military:Multi-year performance-based logistics contracts dominate, with NATO procurement programs mandating integrated health monitoring and redundant computing architectures. Army Future Vertical Lift and Navy modernization programs generate sustained demand for attack and utility helicopter variants.
- Commercial:Offshore oil transport and emergency medical services fleets drive retrofit demand as FAA Part 29 software validation standards tighten. Operators unbundle hardware procurement from availability guarantees, shifting purchasing power toward maintenance providers.
- Emergency Services:Search and rescue platforms command premium pricing for mission-critical reliability and extended sustainment terms.
- Law Enforcement:Aerial surveillance configurations prioritize cost containment over envelope protection, favoring proven architectures with established supply chains.
Contract value concentrates in Military multi-year awards; Emergency Services delivers the steepest margin expansion through mission-specific customization.
Technology:
Software assurance requirements under DO-178C and emerging EU AI Act provisions are restructuring competitive position across technology tiers.
- Digital Control:Integrated computing modules with artificial intelligence-assisted flight envelope protection capture specification in next-generation platforms. EASA CS-29 applicants face dual civil-military qualification paths that favor incumbents with established validation infrastructure.
- Stabilization Systems:Augmentation computers for hover and low-speed regimes address degraded visual environment operations. Search and rescue and aerial surveillance applications concentrate demand where sensor fusion requirements command premium pricing.
- Autopilot:Coupled steering and altitude hold functions reduce pilot workload in extended overwater and instrument flight rule operations.
- Feedback Control:Real-time actuator position monitoring enables predictive maintenance platforms and subscription-based sustainment models.
Revenue gravity sits with Digital Control commanding new-build specification; Feedback Control is climbing the fastest through health monitoring convergence and service-based contracting adoption.
Application:
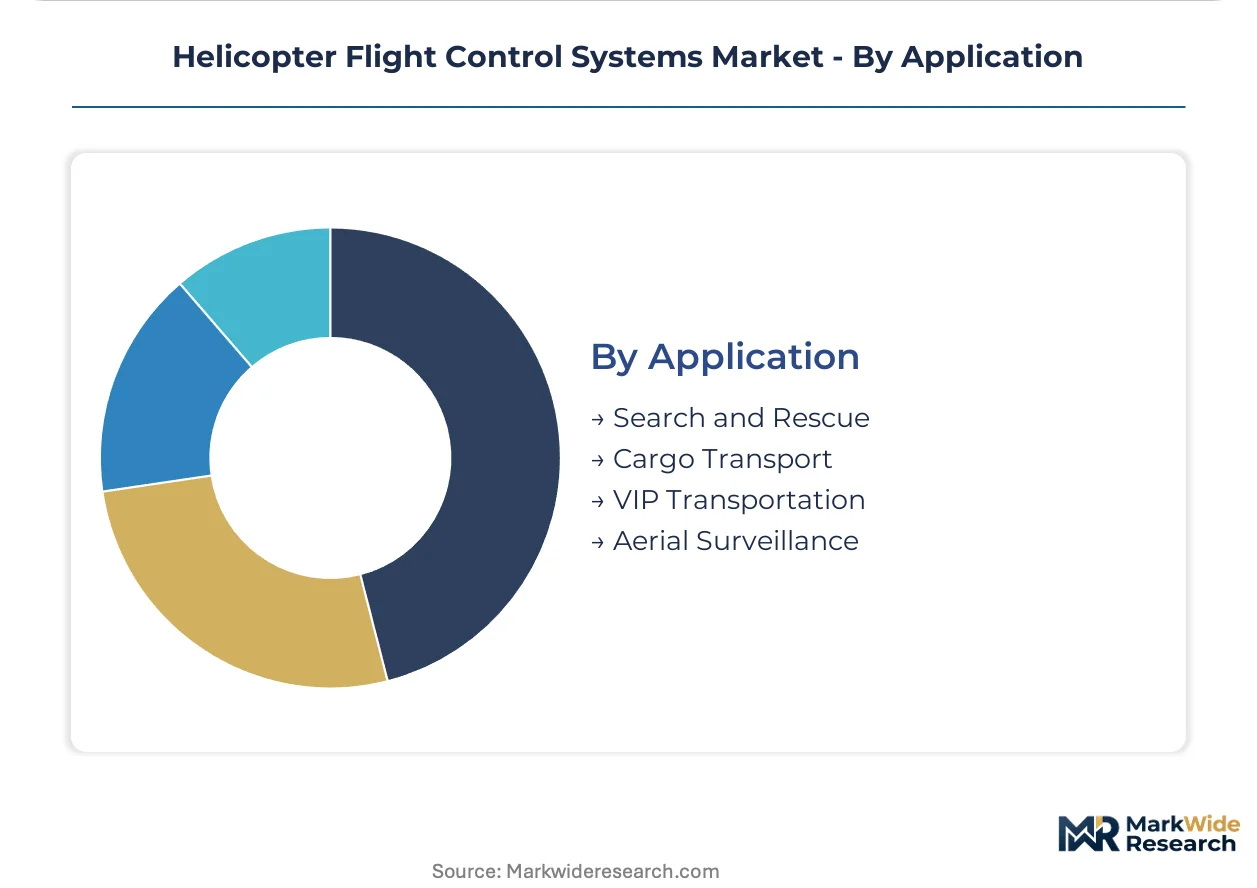
Mission profile determines reliability tiering and sustainment contract structure across operational use cases.
- Search and Rescue:All-weather operational requirements drive specification for redundant architectures with artificial intelligence-assisted stability augmentation. North Sea and Alpine operators mandate extended availability guarantees and multi-year sustainment contracts.
- Cargo Transport:Heavy-lift utility configurations prioritize payload capacity over envelope protection, sustaining demand for hydraulic power-assisted systems in legacy fleet renewal.
- VIP Transportation:Ride quality and noise reduction specifications favor digital control smoothing and autopilot precision.
- Aerial Surveillance:Endurance and sensor stability requirements concentrate margin pools where mission-critical reliability commands premium positioning.
Program scale concentrates in Cargo Transport fleet renewals; Search and Rescue is gaining share fastest through reliability-tier pricing and integrated service contracting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dallas-Fort Worth anchors North American rotorcraft control system engineering, hosting prime contractor integration facilities that feed Army Future Vertical Lift and Navy modernization programs.
United States
The US Army's Future Vertical Lift program and Navy helicopter fleet upgrades drive specification of full-authority digital fly-by-wire architectures. FAA Part 29 certification tightening around DO-178C software assurance levels extends development timelines for commercial retrofits. Connecticut's Hartford-Springfield aerospace corridor concentrates actuator and flight computer manufacturing for military and emergency medical services platforms.
Germany
Urban air mobility developers in Munich and Stuttgart require lightweight, fault-tolerant flight control architectures for electric vertical takeoff and landing prototypes. The EU AI Act imposes new documentation burdens on autonomous decision layers in flight envelope protection systems. Bavaria's aerospace cluster around Munich hosts integration facilities serving both civil certification paths and NATO military procurement.
France
Search and rescue operators in the Alps and North Sea mandate redundant architectures with extended availability guarantees. EASA CS-29 certification frameworks govern commercial rotorcraft derivatives with intensifying focus on software assurance levels. The Toulouse-Blagnac aerospace hub anchors European supply chains for integrated flight control-avionics bundles.
United Kingdom
RAF and Royal Navy rotorcraft modernization programs sustain demand for electromechanical actuators and redundant computing architectures. Military procurement specifications increasingly require integrated health monitoring for performance-based logistics contracts. The South West England aerospace cluster around Bristol and Yeovil concentrates flight control integration for attack and utility helicopter variants.
Japan
Coastal search and rescue and maritime surveillance missions drive specification for all-weather operational capability and sensor fusion requirements. METI industrial policy supports domestic rotorcraft subsystem development to reduce import dependency. The Nagoya aerospace manufacturing corridor hosts tier-one suppliers producing stabilization systems for regional helicopter OEMs.
Helicopter Flight Control Systems Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification infrastructure and software validation capability. The vendor base concentrates around three tiers: military prime integrators with long-term platform control, European engine and actuator specialists with dedicated rotorcraft production, and integrated avionics providers dominating retrofit channels. Two competitive moves define current positioning: consolidation around flight control-avionics bundles that compress standalone component margins, and service-based contracting shifts that lock in multi-year sustainment revenue.
Among US-based military prime integrators, Boeing exemplifies the platform-control archetype through deep integration with defense procurement programs. Safran Helicopter Engines anchors the European specialist tier with dedicated rotorcraft actuator and FADEC production capabilities. Honeywell International occupies the integrated systems position, bundling avionics and flight control architectures across commercial and military retrofit channels.
| Leading Market Players |
|---|
| Boeing |
| Bell Flight |
| BAE Systems |
| Safran Helicopter Engines |
| MD Helicopters |
| Honeywell International |
| Airbus Helicopters |
| Leonardo Helicopters |
| Thales |
| Others |
Supply Flow & Price Mechanics
Rare earth magnet costs cascade from Chinese processing facilities through electromechanical actuator pricing tiers, compressing margins on standard-grade systems while premium fly-by-wire architectures capture value through extended availability guarantees and performance-based logistics contracts.
Pricing Analysis
Mission uptime guarantees anchor value-based pricing for helicopter flight control systems, with NATO military procurement programs contracting on availability metrics rather than unit acquisition cost. Three-tier pricing structure across DO-178C certified digital, hybrid augmentation, and grandfathered mechanical tiers separates premium capture from commodity sustainment. Cost compression in hydraulic actuator segments intensifies because electromechanical alternatives achieve scale in next-generation rotorcraft specifications. Commercial offshore operators exhibit highest price sensitivity, while search and rescue platforms accept premium positioning for redundant architectures with integrated health monitoring.
Supply Chain Analysis
Freight costs for radiation-hardened processors amplify single-source vulnerability in military flight computer supply, with specialized foundry capacity concentrated in the United States and Europe. Neodymium and dysprosium feeds from Chinese rare earth processing facilities, titanium billet from Russian and Ukrainian mills, and precision bearings from Japanese and German manufacturers constitute critical input dependencies. Tariff exposure on Chinese-processed rare earth magnets creates input cost volatility for electromechanical actuator manufacturers. Distribution runs through military prime contractor integration facilities and commercial rotorcraft OEM final assembly lines, with aftermarket channels consolidating around platform-agnostic maintenance providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
DO-178C software assurance requirements erect a cost-of-compliance barrier that entrenches incumbents with established validation infrastructure while forcing mid-tier suppliers toward consolidation or exit.
For Market Incumbents: Extend certification infrastructure advantage by acquiring DO-178C-qualified engineering teams in Hartford-Springfield and Bavaria aerospace corridors, countering embedded software engineering scarcity that constrains competitor program staffing. Deepen backward integration into radiation-hardened processor supply through captive relationships with US and European foundries, mitigating single-source risk that exposes military programs to 18-24 month lead time volatility. For New Entrants and Emerging Players: Urban air mobility developers in Munich and Stuttgart represent an underserved buyer archetype requiring lightweight, fault-tolerant architectures outside traditional rotorcraft OEM procurement channels. Target electric vertical takeoff and landing prototype programs with modular flight control bundles that bypass full Part 29 certification burden through experimental airworthiness pathways. Establish EU AI Act compliance methodologies as first-mover differentiation for autonomous stabilization algorithms. For Investors and Strategic Acquirers: Army Future Vertical Lift program milestone awards are the leading indicator that full-authority digital architectures will consolidate platform control across next-generation military rotorcraft. Position acquisition strategy around DO-178C-validated software assets and electromechanical actuator production capacity with established military prime contractor relationships. Watch for EASA CS-29 dual-use qualification pathway convergence as signal of civil-military certification efficiency gains.| Strategic Initiative | Industry Significance |
|---|---|
| DO-178C Validation Infrastructure Investment | Compresses competitor qualification timelines while locking in military program access. |
| Electromechanical Actuator Capacity Expansion | Captures specification shift from hydraulic systems in Army Future Vertical Lift procurement. |
| Health Monitoring Platform Integration | Enables subscription-based sustainment contracts with North Sea and Gulf of Mexico operators. |
| EU AI Act Compliance Methodology Development | Establishes first-mover certification pathway for autonomous envelope protection algorithms. |
| Rare Earth Magnet Supply Agreement | Secures neodymium and dysprosium feedstock against Chinese processing concentration risk. |
Methodological Framework
SEC 10-K filings, FAA certification databases, and NATO procurement disclosure records formed the secondary backbone, cross-referenced with primary interviews spanning flight control system engineering directors at prime contractors, DO-178C validation leads at specialized software houses, and procurement officers at Army Aviation and Navy Air Systems Command. Bottom-up and top-down triangulation reconciled program-level contract values with fleet upgrade cycle assumptions across military and commercial operator segments.
Bottom-up modeling aggregated individual platform specification data by system type, technology tier, and end-user category, while top-down validation anchored aggregate market trajectories against defense budget appropriations and commercial fleet renewal patterns. Expansion rates across the analysis window derived from installed base age profiles, regulatory compliance deadlines, and new-build production schedules. Segmentation dimensions encompassed system architecture, control technology, application mission profile, and operator procurement authority.
Revisions become necessary when semiconductor foundry capacity constraints intensify, rare earth export restrictions materialize, or FAA-EASA certification timeline convergence accelerates beyond modeled assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Asia-Pacific Military Helicopters Market
Aircraft
Aero Wing Market
Aircraft
Aircraft Wheels Brakes Market
Aircraft
Aircraft Mounts Market
Aircraft
Light Electric Aircraft Market
Aircraft
Aircraft Inspection Covers Market
Aircraft
Military Multirole Aircraft Market
Aircraft
India Winglets Market
Aircraft
Reusable Launch Vehicles Market
Aircraft
North America General Aviation Market
Aircraft
Turboprop Aircraft Market
Aircraft
Docking System Market
Aircraft
America Attack Helicopter Market
Aircraft
Aircraft Window Frame Market
Aircraft
Global Commercial Aircraft Seat Actuation Market
Aircraft
Latin America General Aviation Market