
 Identification Friend or Foe Systems Market | 2026-2036
Identification Friend or Foe Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Identification Friend or Foe Systems Market Foresight
STANAG 4193 NATO standard certification is rotating the competitive landscape toward suppliers with proven Mode 5 interoperability credentials. RTX Corporation leverages its vertically integrated secure communications portfolio to sustain long-term military contracts across multiple NATO air forces. BAE Systems anchors European sovereign capability through its UK-based manufacturing and direct government relationships. Thales Group competes on dual-use technology transfer, extending its radar expertise from defense into civil aviation transponder markets.
Identification Friend or Foe systems are electronic interrogation-response architectures that operate across L-band frequencies, typically 1030 MHz uplink and 1090 MHz downlink, enabling automated discrimination between cooperative and non-cooperative platforms in contested electromagnetic environments. Active systems dominate current procurement budgets due to their proven resistance to passive detection, while combined architectures represent the fastest-growing technology segment as forces seek redundancy against jamming. Electronic technology leads platform integration programs, though optical adjuncts are gaining traction for short-range ground-based identification where radio silence is mandated.
FAA NextGen mandates and NATO STANAG requirements shape product roadmaps, with the FAA mandating ADS-B Out compatibility and Mode S Enhanced Surveillance for all civil aircraft operating in controlled airspace. The EU Green Deal's sustainable aviation framework indirectly pressures IFF manufacturers to reduce transponder power consumption and thermal signatures. Stakeholders must monitor the divergence between military encryption standards and civil aviation interoperability protocols, as this tension will determine which suppliers can bridge both markets without duplicating development costs.
Market Dynamics
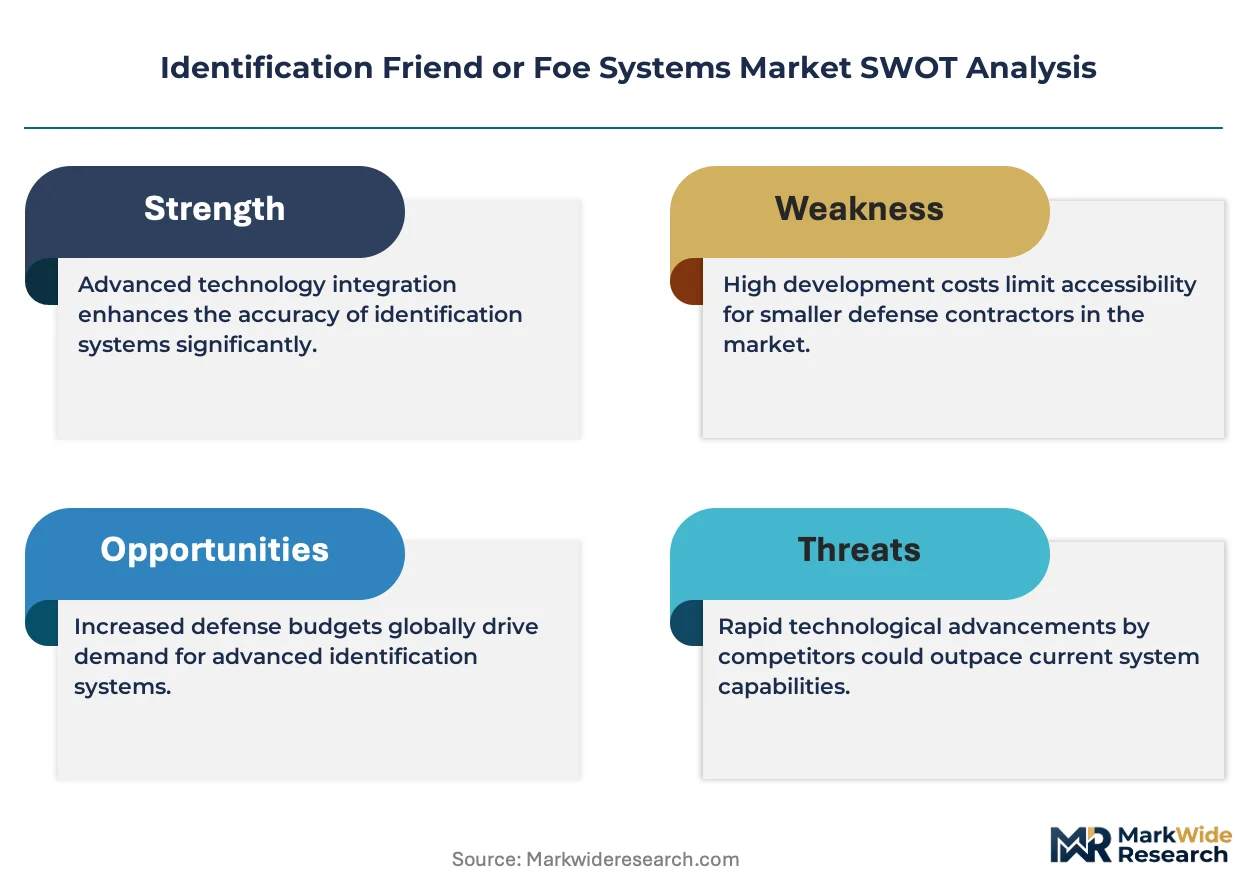
STANAG 4193 Mode 5 certification mandates are compressing the supplier base toward defense contractors with sovereign cryptographic capabilities, while FAA NextGen civil mandates create parallel demand streams that only dual-use architectures can capture.
Growth Catalysts
- NATO STANAG 4193 Mode 5 Mandate:Allied air forces across Europe and North America are retiring legacy Mode 4 transponders, forcing fleet-wide upgrades that favor certified suppliers with established military relationships.
- Electronic Warfare Proliferation:Contested electromagnetic environments in Eastern Europe and the Indo-Pacific are driving demand for encrypted interrogation-response systems resistant to spoofing and jamming.
- FAA NextGen Airspace Modernization:ADS-B Out and Mode S Enhanced Surveillance requirements for all civil aircraft operating in controlled US airspace are expanding addressable market beyond traditional defense applications.
Market Restraints
- Gallium Nitride Supply Concentration:Critical semiconductor substrates for high-power RF amplifiers concentrate among a handful of Asian foundries, creating input cost volatility and sovereign supply risk.
- Classification Barriers:US ITAR and EU dual-use export controls restrict technology transfer to non-allied nations, fragmenting addressable demand along geopolitical lines.
- Legacy Platform Integration Costs:Retrofitting fourth-generation fighter aircraft with Mode 5 architectures requires extensive airframe modifications that compress contractor margins on fixed-price upgrade contracts.
Strategic Opportunities
- Unmanned Systems Identification Gap:NATO and US DoD rules of engagement for autonomous platforms lack standardized cooperative identification protocols, creating first-mover advantage for suppliers defining technical standards.
- EU Green Deal Aviation Pressure:Sustainable aviation frameworks incentivize reduced transponder power consumption and thermal management improvements that differentiate next-generation civil offerings.
- Optical-RF Sensor Fusion:Converging electro-optical and radio-frequency identification architectures address ground-based short-range scenarios where radio silence is operationally mandated.
Industry Challenges
- Cryptographic Engineering Talent Scarcity:Qualified personnel with security clearance and expertise in NSA-certified encryption implementations remain concentrated among legacy defense primes, constraining new entrant scaling.
- Mode 5 Certification Timeline Compression:NATO's accelerated fielding targets for interoperable combat identification are colliding with multi-year security accreditation processes, straining program management capabilities.
- Multi-Domain Integration Complexity:Army ground-based identification systems must now interoperate with Air Force and Navy platforms across disparate frequency allocations and data link architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Identification Friend or Foe Systems Market |
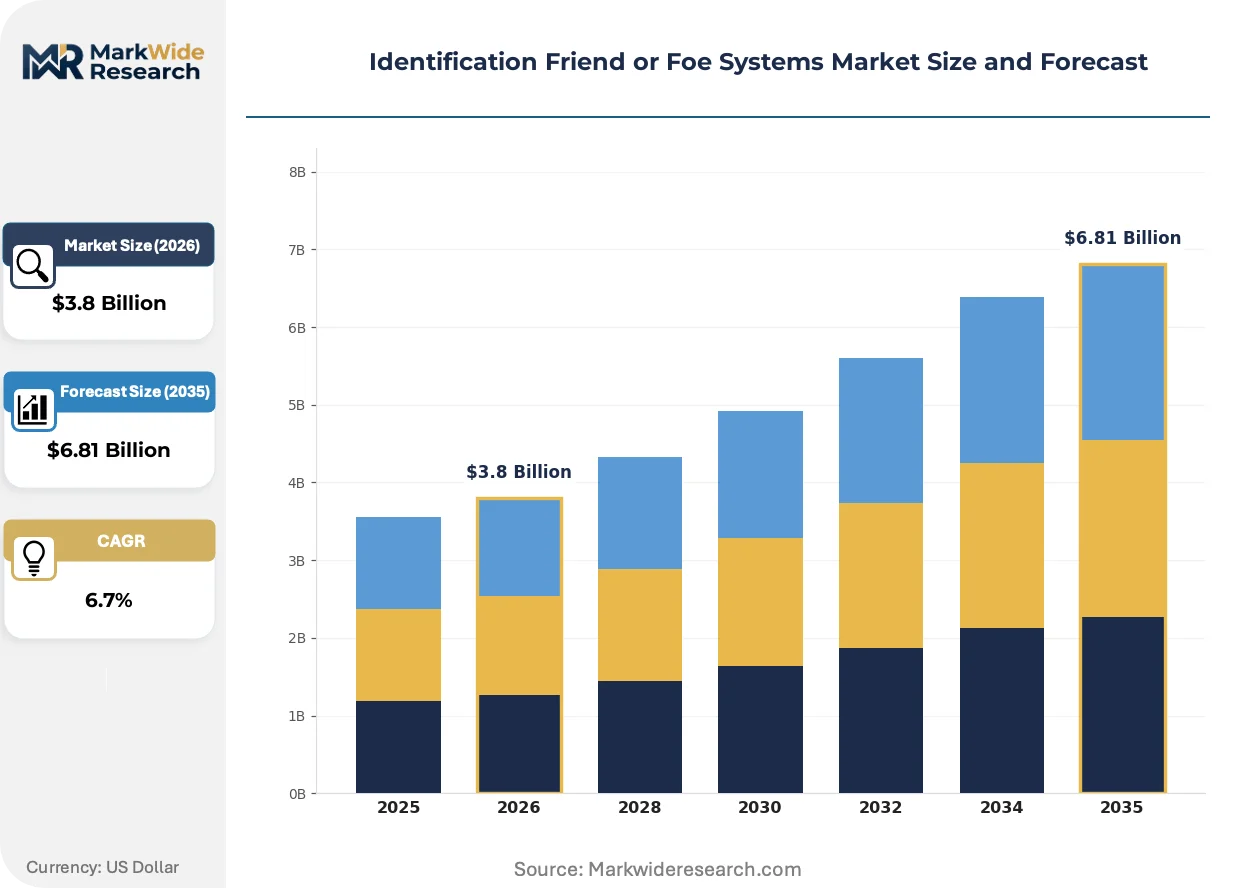
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Active, Passive, Combined, Hybrid Technology: Radar, Acoustic, Optical, Electronic End User: Military, Civil Aviation, Maritime, Security Agencies Application: Surveillance, Combat Identification, Air Traffic Control, Maritime Navigation |
| Companies Covered | RTX Corporation, General Dynamics Corporation, BAE Systems, HENSOLDT AG, ASELSAN A.S., Thales Group, Northrop Grumman Corporation, Indra Sistemas, Leonardo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Identification Friend or Foe Systems Market Shifts & Advancements
Defense procurement offices are bifurcating requirements between sovereign secure communications and civil aviation interoperability, forcing suppliers to maintain dual development tracks without duplicating certification costs.
Active interrogation architectures are bifurcating from passive detection reliance as electronic warfare threats intensify. Military operators in contested theaters prioritize encrypted L-band systems that resist direction-finding by adversary sensors. This technological split is compressing procurement timelines for combined active-passive architectures that offer redundancy against sophisticated jamming.
EU Green Deal sustainable aviation frameworks are mandating reduced power consumption and thermal signatures for civil transponder systems. Manufacturers serving European commercial aviation must now demonstrate energy efficiency gains alongside traditional performance metrics. This regulatory pressure is reshaping product roadmaps for suppliers with dual defense-civil portfolios.
Defense procurement offices are consolidating vendor relationships around long-term performance-based sustainment contracts rather than transactional hardware purchases. Prime contractors are absorbing lifecycle support obligations previously fragmented across third-party maintenance networks. This contracting evolution is most visible in US and UK military programs, where availability guarantees now determine source selection outcomes.
Identification Friend or Foe Systems Market Segmentation
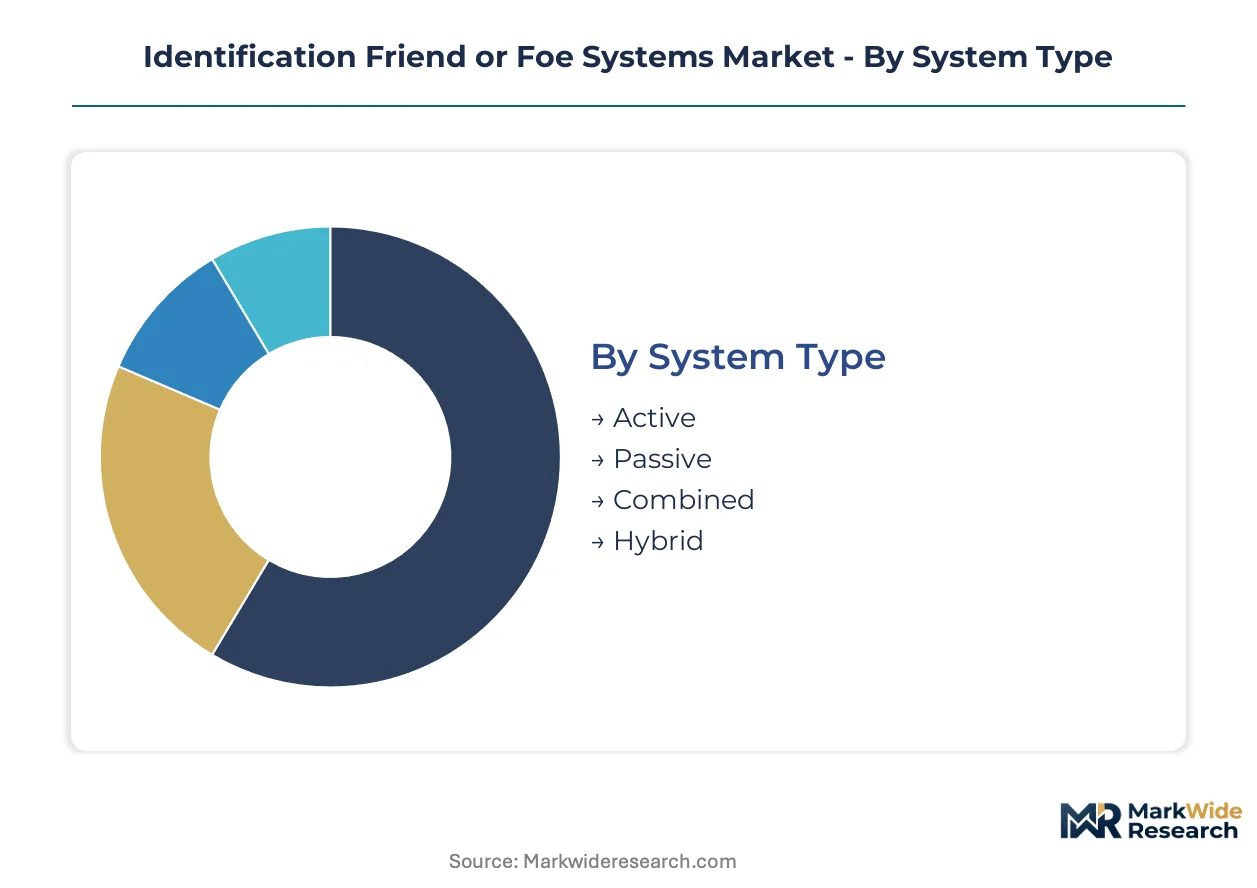
IFF system procurement bifurcates sharply between sovereign military programs with classified encryption requirements and civil aviation mandates governed by open interoperability standards. Segment performance diverges based on certification complexity, with STANAG 4193 Mode 5 compliance creating tiered supplier access across defense and commercial channels.
System Type:
Active architectures dominate domestic procurement within NATO member states, while combined and hybrid systems find stronger export traction in allied nations seeking multi-layer protection.
- Active:L-band interrogation-response systems transmit encrypted 1030 MHz uplink signals and receive 1090 MHz downlink replies, enabling positive identification without adversary detection of the interrogator. Demand concentrates in US Air Force and Royal Air Force fighter modernization programs where resistance to passive direction-finding is paramount. STANAG 4193 Mode 5 mandates are compressing upgrade timelines for legacy platforms.
- Combined:Integrated active-passive architectures fuse encrypted interrogation with electromagnetic signature analysis, delivering redundancy against sophisticated jamming in contested theaters. The Indo-Pacific allied navies are prioritizing these systems for carrier strike group coordination where electronic warfare threats are most acute. Dual-mode capability commands premium pricing in defense procurement.
- Passive:Non-emitting signature detection systems serve specialized reconnaissance roles where emission control is mandatory.
- Hybrid:Multi-sensor fusion architectures blend RF, electro-optical, and acoustic channels for ground-based short-range identification scenarios.
Active systems command the established base. The steepest expansion runs through combined architectures.
Technology:
Electronic and radar technologies absorb the majority of fixed-price development contracts, while optical systems attract cost-plus funding for classified special access programs.
- Electronic:Solid-state transponder and interrogator units process Mode 5 encrypted waveforms through GaN-based RF amplifiers, delivering the cryptographic throughput required for NATO interoperability. US Navy and Royal Navy surface combatant programs are standardizing on electronic architectures for fleet-wide combat identification. Gallium nitride substrate availability constrains production scaling.
- Radar:Pulsed and continuous-wave radar systems provide the primary detection backbone for airborne and maritime IFF, with Thales and RTX capturing long-term sustainment contracts through integrated radar-IFF offerings. French and German air defense networks rely on radar-integrated identification for ground-based air picture compilation. Frequency allocation harmonization across NATO remains incomplete.
- Optical:Laser-based identification systems serve ground forces operating under strict radio silence protocols.
- Acoustic:Underwater identification systems support submarine and anti-submarine warfare applications.
Radar technology anchors current procurement volumes. Electronic platforms are gaining share fastest through Mode 5 upgrade cycles.
End User:
Military end users drive specification-setting through sovereign cryptographic requirements, while civil aviation adoption follows FAA and EASA regulatory timelines with longer planning horizons.
- Military:Defense procurement offices across NATO and Five Eyes nations mandate STANAG 4193 Mode 5 encryption for all cooperative identification, with the US Department of Defense and UK Ministry of Defence representing the largest program-of-record commitments. Multi-domain integration requirements are forcing interoperability between Army ground-based, Air Force airborne, and Navy maritime systems. Classification barriers fragment supplier access along alliance lines.
- Civil Aviation:Commercial airlines and business aviation operators face FAA NextGen ADS-B Out and Mode S Enhanced Surveillance mandates for controlled airspace access, with European operators additionally navigating EU Green Deal energy efficiency pressures. US major carriers and European flag carriers are prioritizing transponder retrofits that minimize power consumption and thermal signature. Certification costs favor incumbent suppliers with established FAA relationships.
- Maritime:Commercial shipping lines adopt Automatic Identification System integration for collision avoidance.
- Security Agencies:Border patrol and coast guard organizations deploy portable interrogators for law enforcement identification.
Military end users dominate absolute spending. Civil aviation is expanding most quickly through regulatory mandate compliance.
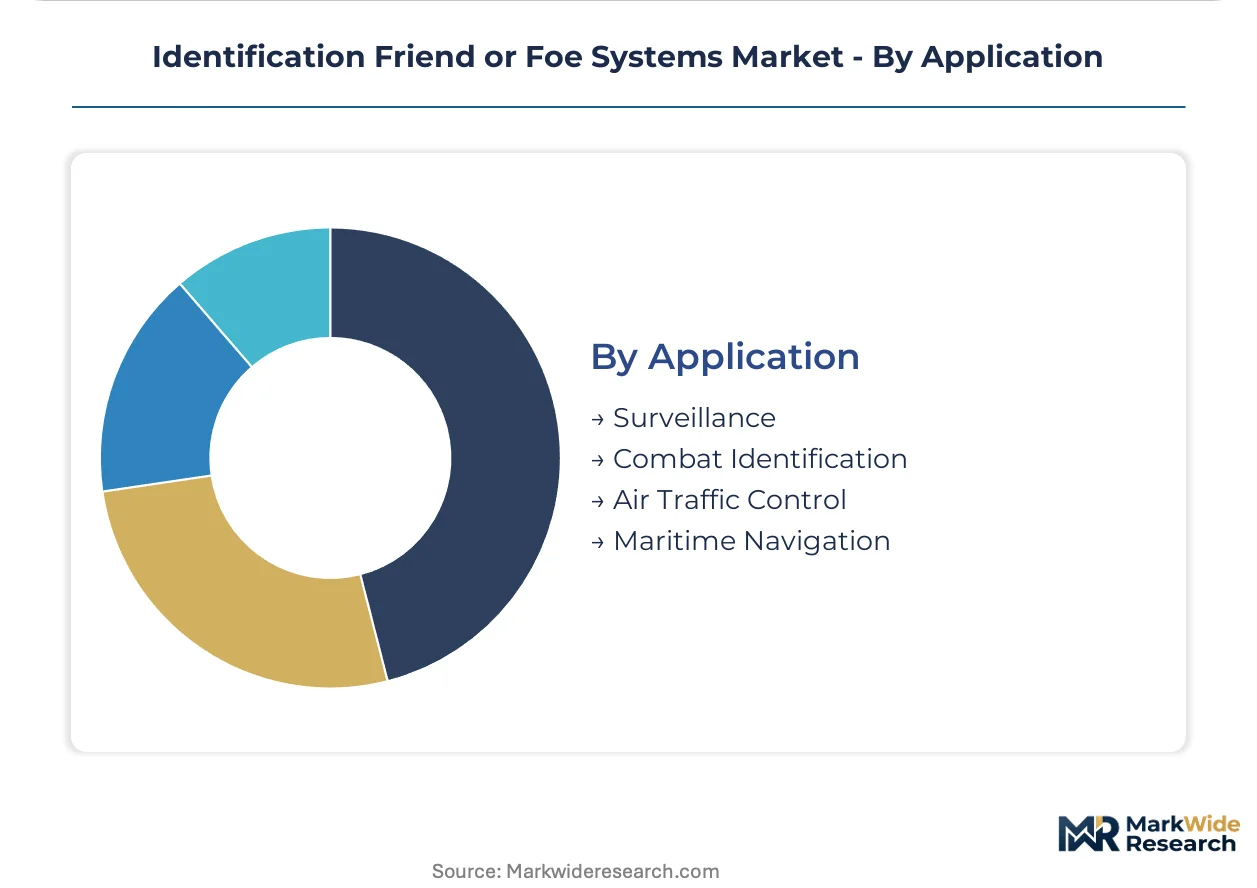
Application:
Combat identification applications concentrate in defense budgets with classified security accreditation requirements, while air traffic control follows open civil aviation standards with transparent certification pathways.
- Combat Identification:Battlefield positive identification systems prevent fratricide through encrypted challenge-response protocols resistant to replay and spoofing attacks. US Army ground-based identification programs and NATO allied close air support coordination represent the core demand centers. Electronic warfare proliferation in Eastern Europe is accelerating fielding timelines.
- Air Traffic Control:Civil aviation surveillance infrastructure relies on Mode S and ADS-B transponder interoperability for safe separation in dense airspace, with the FAA's NextGen mandate and EUROCONTROL harmonization efforts defining technical roadmaps. US terminal radar approach control facilities and European area control centers are modernizing interrogator infrastructure. Dual-use suppliers leverage defense-civil technology transfer.
- Surveillance:Border and coastal monitoring applications combine IFF with primary radar for comprehensive air picture compilation.
- Maritime Navigation:Vessel traffic services integrate IFF with AIS for port and waterway management.
Combat identification holds the revenue base. Air traffic control applications are climbing the fastest through civil mandate expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement offices and civil aviation regulators in NATO member states concentrate the bulk of IFF demand, with sovereign cryptographic requirements and airspace modernization mandates driving divergent certification pathways across national boundaries.
United States
The FAA's NextGen mandate requires ADS-B Out and Mode S Enhanced Surveillance for all civil aircraft in controlled airspace, compressing retrofit timelines for commercial carriers. The Department of Defense operates the largest Mode 5 upgrade program among NATO allies, with specific concentration around supplier clusters in Texas and Virginia where secure communications manufacturing concentrates.
Germany
The Luftwaffe's fleet-wide combat identification modernization aligns with NATO STANAG 4193 interoperability targets, creating sustained demand for encrypted interrogation-response architectures. The EU Green Deal's sustainable aviation framework pressures transponder manufacturers serving Lufthansa and other flag carriers to demonstrate reduced power consumption. Industrial activity clusters in Bavaria and Baden-Württemberg around radar-integrated systems production.
United Kingdom
The Ministry of Defence mandates Mode 5 encryption for all cooperative identification across Royal Air Force and Royal Navy platforms, with performance-based sustainment contracts replacing transactional hardware purchases. BAE Systems anchors sovereign capability through UK-based manufacturing and direct government relationships. The Southwest England defense industrial base supports integrated radar-IFF development programs.
France
The Direction Générale de l'Armement prioritizes dual-use technology transfer between defense and civil aviation markets, with Thales Group extending radar expertise into commercial transponder segments. French air defense networks rely on radar-integrated identification for ground-based air picture compilation. The Île-de-France region hosts prime contractor engineering centers focused on multi-domain integration.
Japan
The Ministry of Defense accelerates combat identification upgrades for Air Self-Defense Force fighter modernization programs, with specific emphasis on encrypted architectures resistant to electronic warfare threats in the Indo-Pacific. METI coordinates industrial policy around GaN semiconductor substrate security. The Kanto region around Tokyo concentrates systems integration and cryptographic engineering capabilities.
Identification Friend or Foe Systems Market Competitive Landscape
Player mix skews toward vertically integrated defense primes with sovereign cryptographic capabilities and established NATO certification relationships, compressing the addressable supplier base around a handful of long-term contract holders. Market structure reflects dual-track development pressures, with military STANAG mandates and civil FAA requirements forcing parallel certification investments. Dominant archetypes include secure communications integrators, radar-technology extenders, and sovereign capability anchors. Competitive moves concentrate on absorbing lifecycle sustainment obligations and securing performance-based availability guarantees.
Within the secure communications tier, RTX Corporation and Northrop Grumman Corporation represent archetypes of vertically integrated defense primes with multi-domain portfolio breadth. BAE Systems and Thales Group exemplify geographically anchored sovereign capability providers with direct government relationships spanning decades. Among European specialists, HENSOLDT AG and ASELSAN A.S. occupy positions as regional encryption-technology anchors with NATO-adjacent certification access. Leonardo and Indra Sistemas sit within the radar-technology extension archetype, leveraging integrated sensor offerings into identification system procurement cycles.
| Leading Market Players |
|---|
| RTX Corporation |
| General Dynamics Corporation |
| BAE Systems |
| HENSOLDT AG |
| ASELSAN A.S. |
| Thales Group |
| Northrop Grumman Corporation |
| Indra Sistemas |
| Leonardo |
| Others |
Supply & Pricing Matrix
Capacity utilization at GaN semiconductor foundries in Taiwan and Japan shapes both input cost floors and tiered supplier pricing power across NATO-certified and non-certified product lines. Scale economies in Mode 5 encryption module production compress margins for second-tier suppliers while sustaining premium capture among primes with sovereign cryptographic accreditation.
Pricing Analysis
Cost-plus contracts with Department of Defense procurement offices carry Defense Logistics Agency material cost indexation, insulating prime contractors from gallium nitride substrate volatility. Three-tier pricing structure across STANAG 4193-certified, Mode S civil-aviation, and legacy Mode 4 retrofit tiers reflects certification investment amortization. Price compression runs through the legacy upgrade segment as fixed-price contracts absorb airframe integration complexity. Civil aviation buyers exhibit highest price sensitivity due to EU Green Deal energy efficiency mandates, while military procurement offices prioritize availability guarantees over unit cost.
Supply Chain Analysis
Inbound logistics costs through the Port of Long Beach and Rotterdam container terminals amplify lead-time uncertainty for GaN substrates sourced from Taiwanese foundries. Critical semiconductor supply concentrates in Taiwan, Japan, and South Korea, with RF amplifier fabrication drawing from specialized compound semiconductor wafer production. Single-source vulnerability pervades the classified encryption module tier where NSA-certified packaging capabilities anchor in US and UK facilities. Distribution runs through defense prime contractor captive networks for military programs and avionics OEM channel partnerships for civil aviation retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market approaches a platform-economics inflection as NATO STANAG 4193 and FAA NextGen standards converge on interoperable transponder architectures, rewarding suppliers who bridge defense-civil certification pathways without duplicating development overhead.
For Market Incumbents: Consolidate sustainment contract portfolios around performance-based availability guarantees that lock out third-party maintenance networks. Absorb cryptographic engineering talent from cleared subcontractors to defend against emerging GaN foundry entrants in South Korea. Prioritize backward integration into GaN substrate qualification programs that reduce exposure to single-source foundry concentration. For New Entrants and Emerging Players: Lead with unmanned systems identification protocol development where NATO standardization gaps create first-mover standard-setting opportunity. Target the Indo-Pacific allied navy segment for combined active-passive architectures where electronic warfare threat intensity justifies premium positioning. Pursue cost-plus R&D contracts with defense procurement offices to amortize Mode 5 certification investment across development phases. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among primes with multi-year sustainment contracts and sovereign cryptographic accreditation that extends replacement cycles. Long-term viability hinges on dual-use architecture development spanning military STANAG and civil FAA certification pathways. Monitor GaN substrate supply diversification announcements as inflection indicator for input cost volatility and margin compression risk.| Strategic Initiative | Industry Significance |
|---|---|
| Mode 5 Certification Investment | STANAG 4193 accreditation unlocks NATO procurement access and sustains long-term contract capture. |
| GaN Substrate Supply Agreement | Long-term foundry partnerships mitigate Taiwan concentration risk and stabilize RF amplifier input costs. |
| Dual-Use Architecture Development | Converging military-civil certification pathways reduces R&D duplication and expands addressable market. |
| Performance-Based Sustainment Contract | Availability guarantees displace transactional hardware sales and deepen prime contractor lock-in. |
| Unmanned Systems Protocol Leadership | First-mover standard-setting for autonomous platform identification captures emerging NATO requirement. |
Research Methodology
Cross-validation between primary fieldwork with defense procurement officers and secondary analysis of NATO STANAG documentation anchors the qualitative findings. Interviews with avionics integration engineers, military cryptographic accreditation specialists, commercial airline fleet managers, and GaN semiconductor procurement leads informed demand-side segmentation. Secondary sources include FAA NextGen implementation reports, EUROCONTROL surveillance harmonization documentation, Department of Defense budget justification materials, and customs trade data for RF component flows. Bottom-up platform retrofit demand estimates triangulate against top-down defense budget allocation analysis.
Sensitivity analysis around GaN substrate price volatility and Mode 5 certification timeline compression tests forecast robustness across the projection horizon. Segmentation dimensions modeled include system architecture type, technology platform, end-user category, and application mission profile, with additional granularity around sovereign versus non-sovereign cryptographic requirement tiers. CAGRs derive from installed base replacement cycles, regulatory mandate compliance deadlines, and fleet modernization program announcements. Industry-specific inputs include NATO interoperability fielding targets and FAA ADS-B Out equipage rates.
Forecasts assume regulatory continuity in FAA NextGen mandates and NATO STANAG 4193 certification requirements; material policy shifts would require re-modeling. Classification barrier tightening or GaN export control expansion could fragment addressable demand along geopolitical lines. Practitioners should keep alternative scenarios live as Indo-Pacific electronic warfare threat intensity and EU Green Deal implementation timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Safety Systems
Commercial Parachute Market
Aircraft Safety Systems
Rescue Hoist System Market
Aircraft Safety Systems
Global Aircraft Brake System Market
Aircraft Safety Systems
Aerospace & Aircraft Collision Avoidance System Market
Aircraft Safety Systems
Aviation Life Rafts Market
Aircraft Safety Systems
Airborne Collision Avoidance System Market
Aircraft Safety Systems
Aviation Airbags Market
Aircraft Safety Systems
Military Aircraft Collision Avoidance Systems Market
Aircraft Safety Systems
Cloud-Connected Aircraft Safety Data Management Platforms Market
Aircraft Safety Systems
Commercial Aircraft Collision Avoidance System Market
Aircraft Safety Systems
Aircraft Arresting System Market
Aircraft Safety Systems
Free Fall Sensor Market
Aircraft Safety Systems
Aircraft Docking Systems Market
Aircraft Safety Systems
Aircraft Evacuation Systems Market
Aircraft Safety Systems
Instrument Landing System (ILS) Market
Aircraft Safety Systems
Helicopter Emergency Flotation System Market