
 Rare Disease Clinical Trials Market | 2026-2036
Rare Disease Clinical Trials Market Size, Share, and Industry Trends Forecast 2026-2036
Rare Disease Clinical Trials Market Intelligence
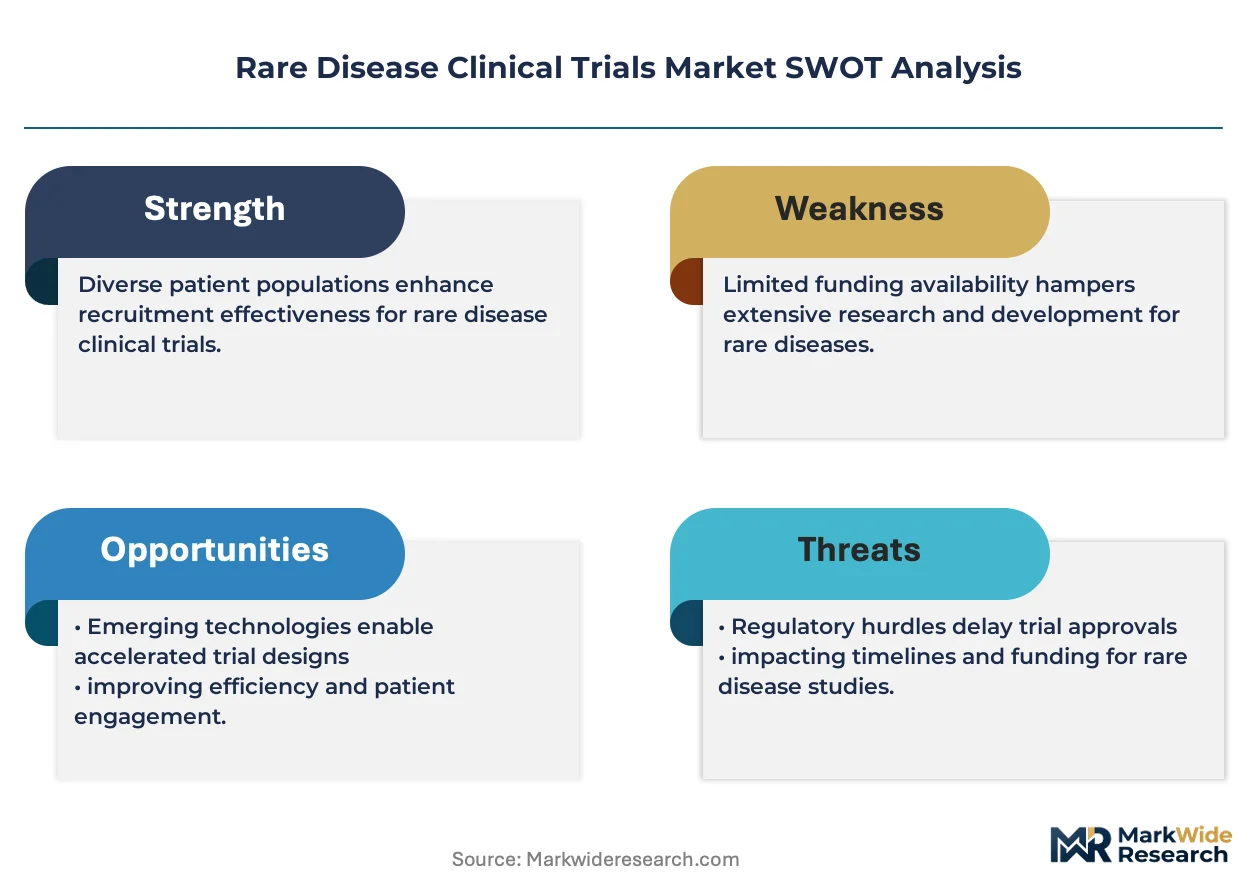
Pharmaceutical sponsor sourcing is decoupling from fully internalized clinical operations toward hybrid engagement with contract research organizations. Takeda Pharmaceutical Company Limited leverages its global development footprint to anchor complex multinational rare disease protocols. IQVIA competes through integrated data science platforms that streamline patient identification across dispersed populations.
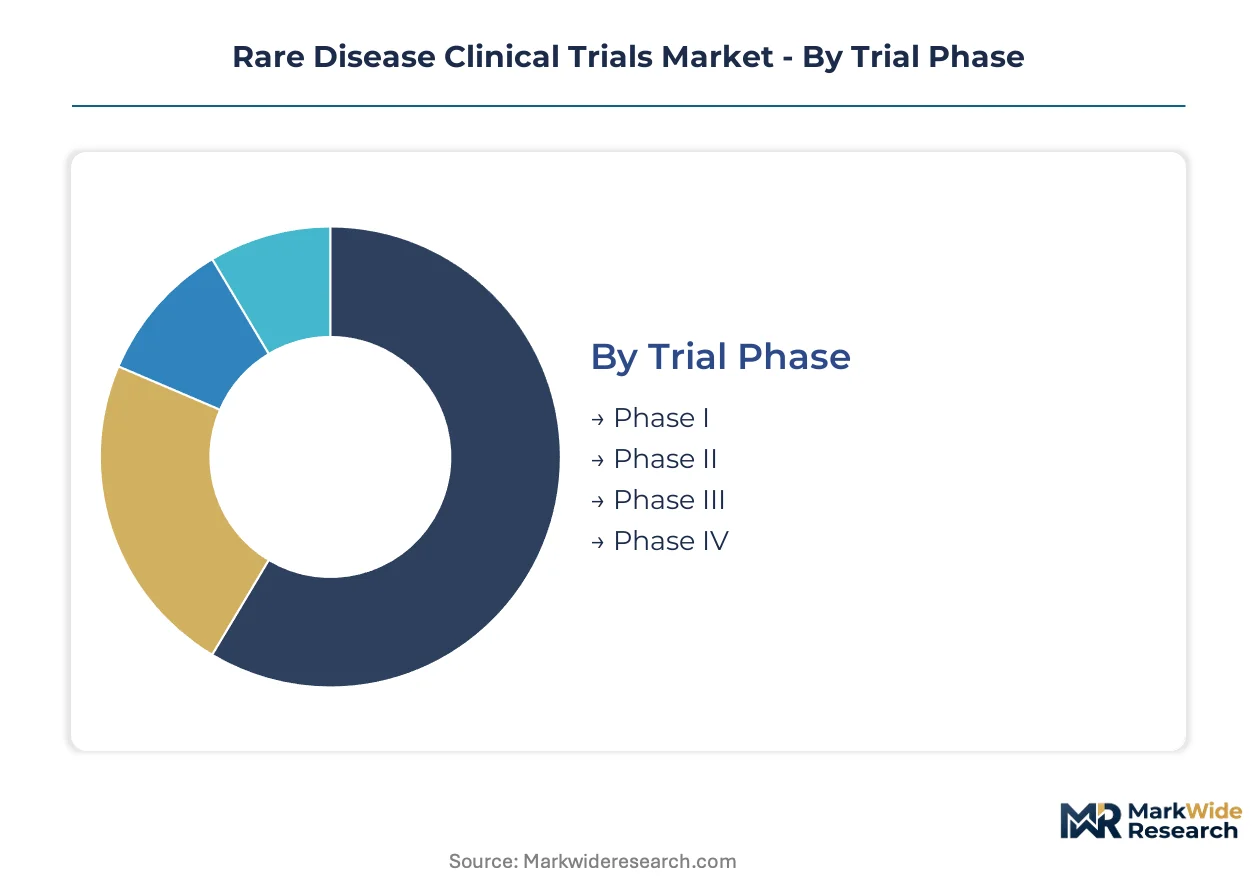
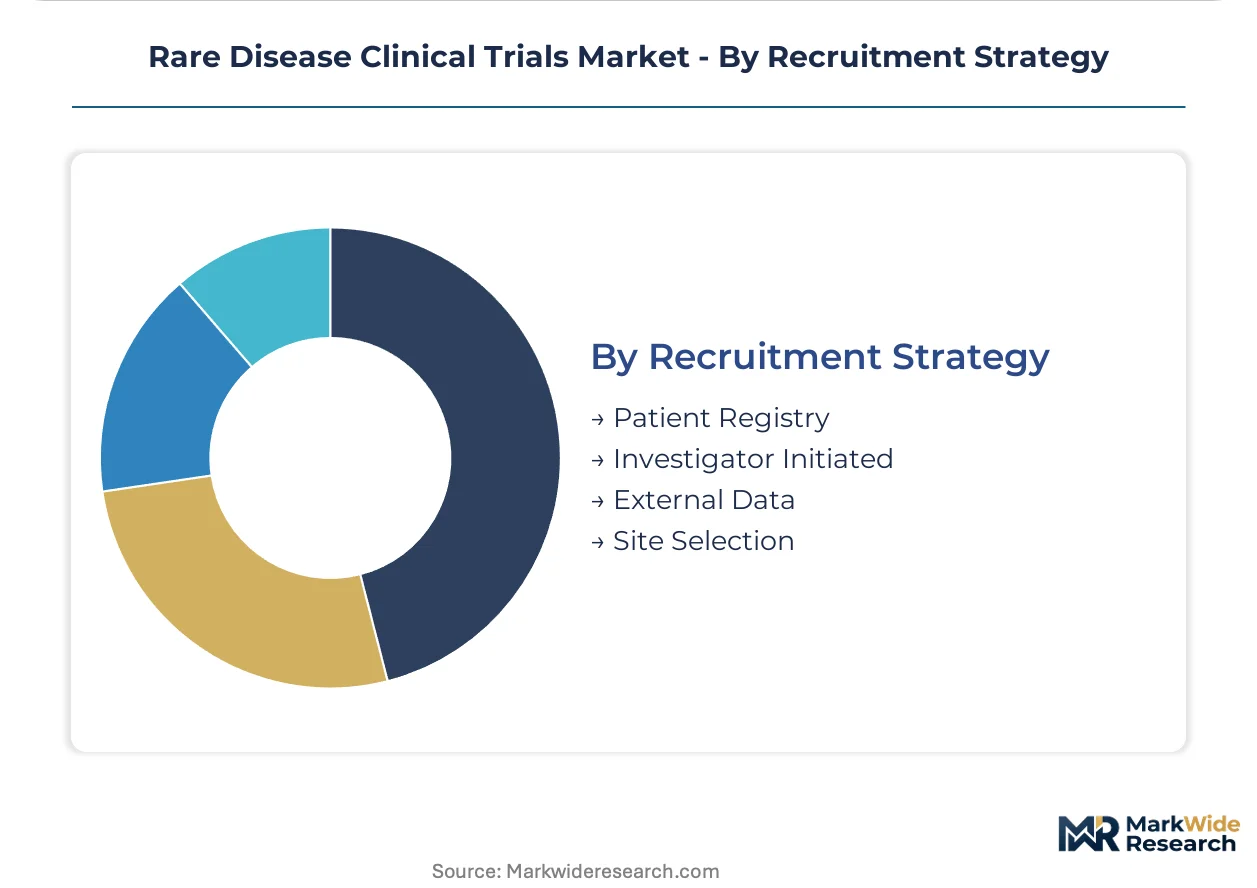
Rare disease clinical trials are prospective biomedical investigations involving limited participant pools, often fewer than one thousand subjects, that evaluate safety and efficacy for conditions affecting fewer than two hundred thousand individuals in the United States under the Orphan Drug Act threshold; these studies require adaptive statistical methodologies and specialized biomarker endpoints to compensate for small sample sizes and heterogeneous disease presentations. Phase III interventional studies occupy the largest value share due to their extended duration and intensive site monitoring requirements, while patient registry recruitment strategies represent the fastest-expanding segment as sponsors seek to reduce enrollment timelines through pre-qualified cohort databases.
The FDA Orphan Drug Act, EMA Committee for Orphan Medicinal Products, and ICH E11A pediatric extrapolation guidelines collectively shape protocol acceptability and market access timelines across major jurisdictions. Sponsors must demonstrate natural history data sufficiency to regulators before initiating pivotal trials, creating pre-competitive collaboration imperatives among industry and academic investigators. Stakeholders should monitor evolving FDA guidance on decentralized trial elements for rare disease populations with mobility constraints.
Market Dynamics
Adaptive statistical methodologies are compressing trial timelines as sponsors deploy Bayesian designs and master protocols to extract maximum inference from limited patient pools. This methodological shift is redrawing competitive boundaries between biopharmaceutical sponsors and specialized contract research organizations.
Growth Catalysts
- FDA Orphan Drug Act:Tax credits for qualified clinical testing expenses and seven-year market exclusivity provisions incentivize sponsor investment in ultra-rare indications.
- Natural history study infrastructure:Academic medical centers in the United States maintain longitudinal patient databases that accelerate enrollment for prospective interventional trials.
- Patient registry platforms:Pre-qualified cohort databases enable sponsors to identify genetically confirmed participants before site activation.
Market Restraints
- Site concentration risk:Rare disease expertise concentrates at fewer than two hundred specialized investigative sites globally, creating enrollment bottlenecks.
- Biomarker validation costs:Novel surrogate endpoint qualification requires extensive natural history data collection before FDA acceptance.
- Regulatory fragmentation:Divergent pediatric extrapolation requirements between FDA and EMA force redundant study designs.
Strategic Opportunities
- Decentralized trial elements:FDA draft guidance on remote monitoring and direct-to-patient drug shipment opens enrollment for mobility-constrained populations.
- Japan's Sakigake designation:Priority review and extended consultation pathways accelerate market access for innovative rare disease therapies.
- Real-world evidence integration:Convergence of electronic health record systems with wearable sensor data enables external control arm construction.
Industry Challenges
- Biostatistical talent scarcity:Adaptive trial design expertise remains concentrated among a limited pool of specialized consultants.
- Cross-border sample logistics:Temperature-controlled shipment of biological specimens from dispersed rare disease patients requires specialized cold chain infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rare Disease Clinical Trials Market |
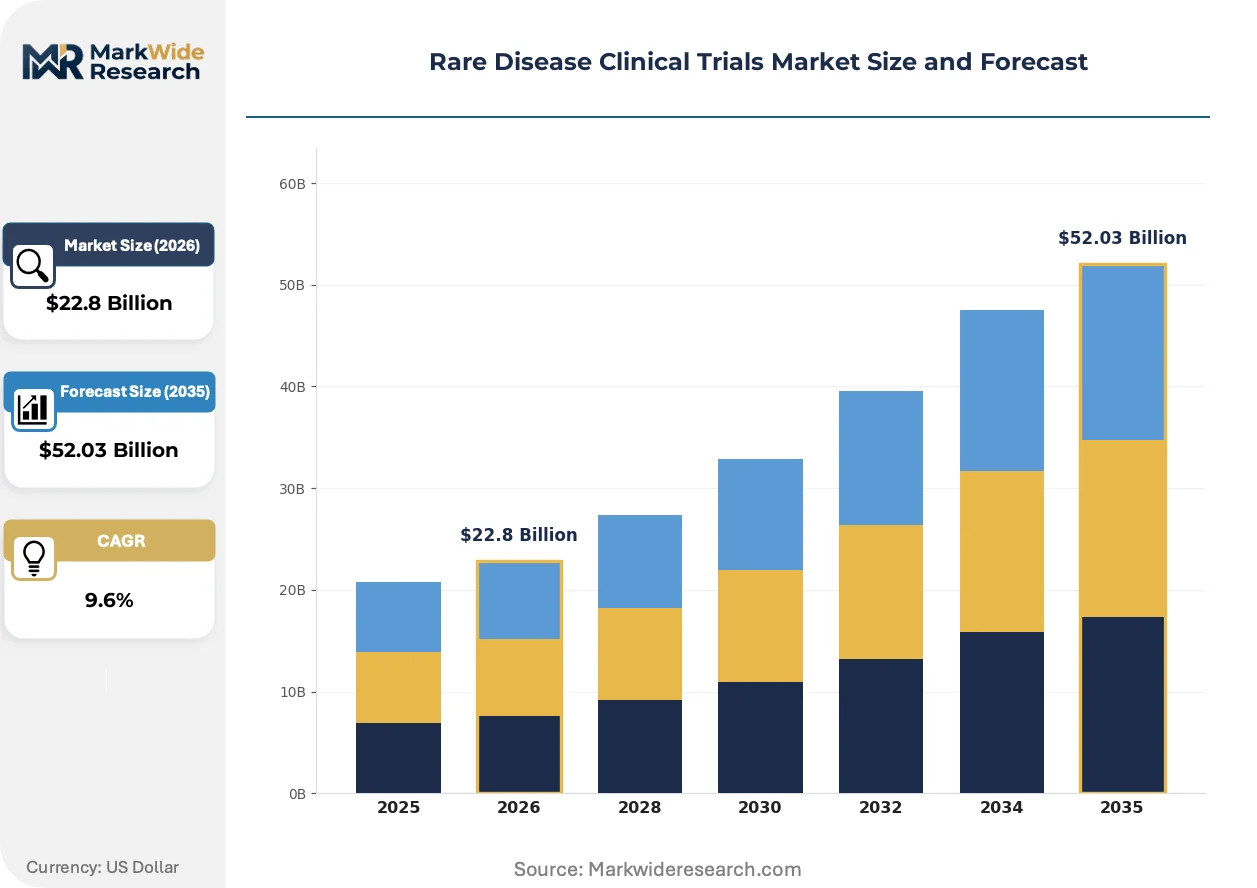
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $52.03 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Trial Phase: Phase I, Phase II, Phase III, Phase IV Therapeutic Area: Oncology, Neurology, Hematology, Metabolic Disorders Study Design: Observational, Interventional, Randomized, Non-randomized Recruitment Strategy: Patient Registry, Investigator Initiated, External Data, Site Selection |
| Companies Covered | Takeda Pharmaceutical Company Limited, F. Hoffmann-La Roche Ltd, Pfizer, AstraZeneca, Novartis AG, IQVIA, Parexel International Corporation, Icon PLC, Charles River Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rare Disease Clinical Trials Market Strategic Shifts & Innovations
Digital biomarker acquisition and federated data networks are reconfiguring how sponsors demonstrate efficacy in heterogeneous rare disease populations. These capabilities are shifting competitive advantage toward organizations with integrated data science infrastructure.
Master protocol designs with shared control arms are consolidating statistical power across multiple rare disease indications. Biopharmaceutical sponsors with late-stage pipelines are adopting these frameworks to compress development timelines. The approach is consolidating sponsor preference toward contract research organizations with centralized statistical operations centers.
EMA's updated guideline on extrapolation of efficacy and safety data in pediatric medicine development is mandating earlier natural history study initiation. Sponsors must now submit pediatric investigation plans before adult pivotal trial completion. This regulatory sequence is compressing development timelines for sponsors with pre-existing longitudinal cohort relationships.
Site-less recruitment through patient advocacy foundation partnerships is displacing traditional investigator-initiated enrollment. Sponsors are contracting directly with disease-specific organizations to access genetically confirmed registries. This channel shift is most visible in the United States where nonprofit natural history study infrastructure remains most developed.
Rare Disease Clinical Trials Market Segmentation
Rare disease clinical trials demand precise segmentation due to heterogeneous patient populations and fragmented site infrastructure. Trial sponsors align protocol design with specific recruitment channels and biomarker requirements to compress enrollment timelines.
Trial Phase:
Phase progression determines resource allocation intensity, with later-stage trials requiring extended site monitoring and adaptive statistical support.
- Phase I:First-in-human safety assessments in ultra-small cohorts, typically 10-30 participants, establish maximum tolerated dose and pharmacokinetic profiles. Demand concentrates in academic medical centers with specialized gene therapy units across the United States, driven by FDA gene therapy guidance requiring dedicated safety monitoring committees.
- Phase II:Efficacy signal detection in 50-200 patient cohorts using novel surrogate endpoints. Sponsors deploy Bayesian adaptive designs at specialized sites in Germany and the United Kingdom to maximize inference from limited pools.
- Phase III:Confirmatory trials with extended follow-up periods and intensive site monitoring requirements.
- Phase IV:Post-market surveillance studies capturing long-term safety in real-world settings.
Phase III sits at the top of the volume ranking, with patient registry recruitment climbing the fastest.
Therapeutic Area:
Biomarker maturity and natural history data availability segment sponsor investment across disease categories.
- Oncology:Genetically defined rare tumors with established companion diagnostic pathways. Demand concentrates in the United States at NCI-designated cancer centers, constrained by biomarker validation costs for novel surrogate endpoints.
- Neurology:Progressive neurodegenerative conditions with heterogeneous phenotypes requiring longitudinal cognitive assessment batteries. European sites in France and the Netherlands lead enrollment for pediatric neurology protocols under EMA pediatric investigation plan requirements.
- Hematology:Inherited bleeding and red cell disorders with well-characterized genotype-phenotype correlations.
- Metabolic Disorders:Enzyme replacement and gene therapy candidates targeting lysosomal storage diseases.
Oncology commands the largest sponsor investment, with neurology gaining share fastest on gene therapy pipeline expansion.
Study Design:
Regulatory acceptability and statistical power requirements shape methodology selection for small-population trials.
- Interventional:Controlled therapeutic trials with active treatment arms and predefined endpoints. Demand concentrates in the United States and Japan under PMDA Sakigake priority review pathways, driven by compressed development timelines for breakthrough therapies.
- Observational:Natural history studies establishing disease trajectories without therapeutic intervention. Academic sites in Canada and Australia maintain longitudinal registries for pre-competitive data sharing.
- Randomized:Parallel-arm designs with formal hypothesis testing and alpha allocation.
- Non-randomized:Single-arm trials with external historical controls.
Interventional designs dominate regulatory submissions, with observational studies expanding most quickly as pre-competitive collaboration infrastructure matures.
Recruitment Strategy:
Patient identification channel selection directly determines enrollment velocity and protocol amendment rates.
- Patient Registry:Pre-qualified genetically confirmed cohorts accessed through advocacy foundation partnerships. Demand concentrates in the United States at nonprofit natural history study platforms, driven by FDA emphasis on natural history data sufficiency for pivotal trial initiation.
- Site Selection:Investigator-initiated enrollment through specialized academic medical centers. European networks in Italy and Spain anchor multinational protocols under EMA centralized procedure requirements.
- Investigator Initiated:Clinician-driven protocol development with sponsor funding support.
- External Data:Real-world evidence integration and synthetic control arm construction.
Site selection retains the largest volume share, with patient registry platforms showing the steepest expansion trajectory as sponsors seek to reduce screening failure rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Greater Boston biopharma corridor anchors rare disease clinical trial infrastructure through its concentration of academic medical centers with longitudinal patient databases and gene therapy manufacturing capabilities.
United States
FDA Orphan Drug Act tax credits and seven-year market exclusivity provisions concentrate sponsor investment in ultra-rare indications. The FDA's draft guidance on decentralized trial elements enables remote monitoring for mobility-constrained patient populations. Massachusetts and North Carolina research triangles house specialized gene therapy units that anchor first-in-human safety assessments.
Germany
EMA centralized procedure requirements and pediatric investigation plan mandates drive multinational protocol anchoring through German investigative sites. The country's national pharmaceutical regulator maintains stringent biomarker validation standards that shape surrogate endpoint qualification timelines. Munich and Heidelberg academic networks lead enrollment for pediatric neurology protocols under European pediatric extrapolation frameworks.
Japan
PMDA Sakigake designation pathways accelerate priority review for innovative rare disease therapies with compressed development timelines. Japan's national pharmaceutical regulator emphasizes consultation-driven regulatory sequences that reduce protocol amendment rates. Tokyo and Osaka metropolitan clusters concentrate adaptive statistical expertise for Bayesian trial designs in ultra-small cohorts.
United Kingdom
NHS longitudinal patient registries and genomic medicine infrastructure enable pre-qualified cohort identification before site activation. MHRA post-Brexit regulatory autonomy permits streamlined pediatric investigation plan submissions for early-phase protocols. London and Cambridge biotech corridors anchor observational natural history studies that establish disease trajectories for regulatory submissions.
Switzerland
Swissmedic's streamlined orphan drug approval pathways and proximity to European regulatory harmonization attract sponsor protocol anchoring. The country's national pharmaceutical regulator emphasizes quality-by-design frameworks for complex biologic manufacturing. Basel and Zurich pharmaceutical clusters house centralized statistical operations centers that support master protocol designs across multiple rare disease indications.
Rare Disease Clinical Trials Market Key Industry Players
Global majors compete with regional champions across trial execution capabilities and specialized therapeutic expertise. The vendor base stratifies into three tiers: integrated contract research organizations with centralized data science infrastructure, mid-scale specialists in rare disease site networks, and boutique biostatistical consultancies with adaptive design capabilities. Strategic archetypes include platform-scale data integrators, site-network aggregators, and therapeutic-area pure-plays. Competitive moves center on patient registry platform acquisitions and federated data network partnerships that compress enrollment timelines.
Within the integrated platform tier, IQVIA exemplifies data science infrastructure consolidation through its patient identification capabilities across dispersed rare disease populations. Takeda Pharmaceutical Company Limited occupies a position as a sponsor archetype leveraging global development footprints for complex multinational protocol execution. Among specialized service providers, Charles River Laboratories and Parexel International Corporation represent site-network and regulatory consulting archetypes that anchor late-stage trial monitoring requirements.
| Leading Market Players |
|---|
| Takeda Pharmaceutical Company Limited |
| F. Hoffmann-La Roche Ltd |
| Pfizer |
| AstraZeneca |
| Novartis AG |
| IQVIA |
| Parexel International Corporation |
| Icon PLC |
| Charles River Laboratories |
| Others |
Cost & Logistics Intelligence
Cold chain logistics cost indices cascade through rare disease clinical trial pricing tiers, compressing margins for decentralized protocols while amplifying premium capture for sponsors with integrated biomarker processing capabilities. FDA gene therapy guidance mandates reshape procurement priorities across sponsor archetypes.
Pricing Analysis
Input-cost pass-through from specialized cold chain infrastructure and biomarker validation services intensifies pricing pressure on mid-tier contract research organizations. Three-tier pricing structure across premium, standard, and economy levels separates sponsors with proprietary patient registries from those relying on investigator-initiated recruitment. Quality grade and certification level—specifically FDA orphan drug designation tier—drive price differentiation. Emerging biopharmaceutical sponsors exhibit highest price sensitivity; large pharma with approved rare disease portfolios demonstrate lowest.
Supply Chain Analysis
Domestic-content mandates under FDA decentralized trial guidance reshape sourcing toward United States-based patient monitoring device manufacturers and domestic biomarker processing laboratories. Supply concentration centers on the United States, Germany, and Switzerland for specialized investigative sites and centralized statistical operations. Biological specimen collection kits, temperature-controlled shipping containers, and genomic sequencing reagents constitute critical input dependencies. Single-source vulnerability in qualified site networks for pediatric neurology protocols poses structural risk. Distribution runs through academic medical center procurement channels and direct-to-patient logistics partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rare disease clinical trials constitute a late-cycle quality story as sponsor demand shifts toward premium specifications—adaptive Bayesian designs and federated data networks—that compress enrollment timelines and reduce protocol amendment rates.
For Market Incumbents: Anticipate margin compression from mid-scale specialists acquiring patient registry platforms by deepening site-network exclusivity arrangements with academic medical centers in Massachusetts and North Carolina. Consolidate adaptive biostatistical talent through targeted hiring in Tokyo and Basel clusters to defend against platform-scale data integrators.
For New Entrants and Emerging Players: Launch via site-less recruitment partnerships with disease-specific advocacy foundations targeting ultra-rare metabolic disorders with underdeveloped natural history infrastructure. White-space opportunities concentrate in observational study design for pre-competitive data sharing and decentralized trial elements for mobility-constrained pediatric populations.
For Investors and Strategic Acquirers: Asymmetric upside sits with boutique biostatistical consultancies possessing adaptive design capabilities and established FDA surrogate endpoint qualification track records. Long-term viability hinges on regulatory relationship depth and master protocol execution experience. Watch FDA guidance finalization on decentralized trial elements as inflection indicator for valuation repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| Patient Registry Platform Acquisition | Compresses enrollment timelines by accessing pre-qualified genetically confirmed cohorts. |
| Adaptive Statistical Capability Buildout | Enables Bayesian trial designs that extract maximum inference from ultra-small patient pools. |
| Decentralized Trial Infrastructure Deployment | Opens enrollment for mobility-constrained populations under FDA draft guidance. |
| Natural History Study Partnership | Establishes disease trajectory baselines required for EMA pediatric investigation plans. |
| Federated Data Network Integration | Supports external control arm construction through electronic health record convergence. |
Research Approach
Multiple input streams—primary interviews with drug development executives, regulatory affairs leads, and site operations directors; secondary validation through FDA filings, EMA submissions, and ClinicalTrials.gov records; and bottom-up enrollment database analysis—were reconciled against top-down sponsor budget disclosures to construct market estimates.
Data-stream reconciliation anchored the analytical framework across the projection horizon, modeling segmentation by trial phase, therapeutic area, study design, and recruitment strategy. CAGRs were derived from sponsor pipeline velocity analysis and site capacity expansion trajectories, with inputs from biomarker validation timeline data and regulatory approval pathway durations.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA guidance revision scenarios or EMA pediatric extrapolation framework changes. Forecasts reflect assumptions about natural history study infrastructure maturation and decentralized trial adoption curves. A small set of named triggers—regulatory guidance finalization, patient registry platform consolidation events, and adaptive design methodology standardization—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Atypical Hemolytic Uremic Syndrome (Ahus) Treatment Market
Rare Diseases
Methylmalonic Acidemia Market
Rare Diseases
Menkes Syndrome Market
Rare Diseases
Dystrophic Epidermolysis Bullosa Treatment Market
Rare Diseases
Global Hereditary Angioedema Treatment Market
Rare Diseases
Gastrointestinal Rare Diseases Treatment Market
Rare Diseases
Rett Syndrome Market
Rare Diseases
Sarcoidosis Therapeutics Market
Rare Diseases
Metachromatic Leukodystrophy Market
Rare Diseases
Aicardi Syndrome Market
Rare Diseases
Erdheim-Chester Disease Market
Rare Diseases
North America Down Syndrome Market
Rare Diseases
Pure Red Cell Aplasia Market
Rare Diseases
Europe Rett Syndrome Market
Rare Diseases
Gaucher Disease Drugs Market
Rare Diseases
Cri-Du-Chat Syndrome Treatment Market