
 Europe Pharmaceutical Logistics Market | 2026-2036
Europe Pharmaceutical Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Pharmaceutical Logistics Market Analysis
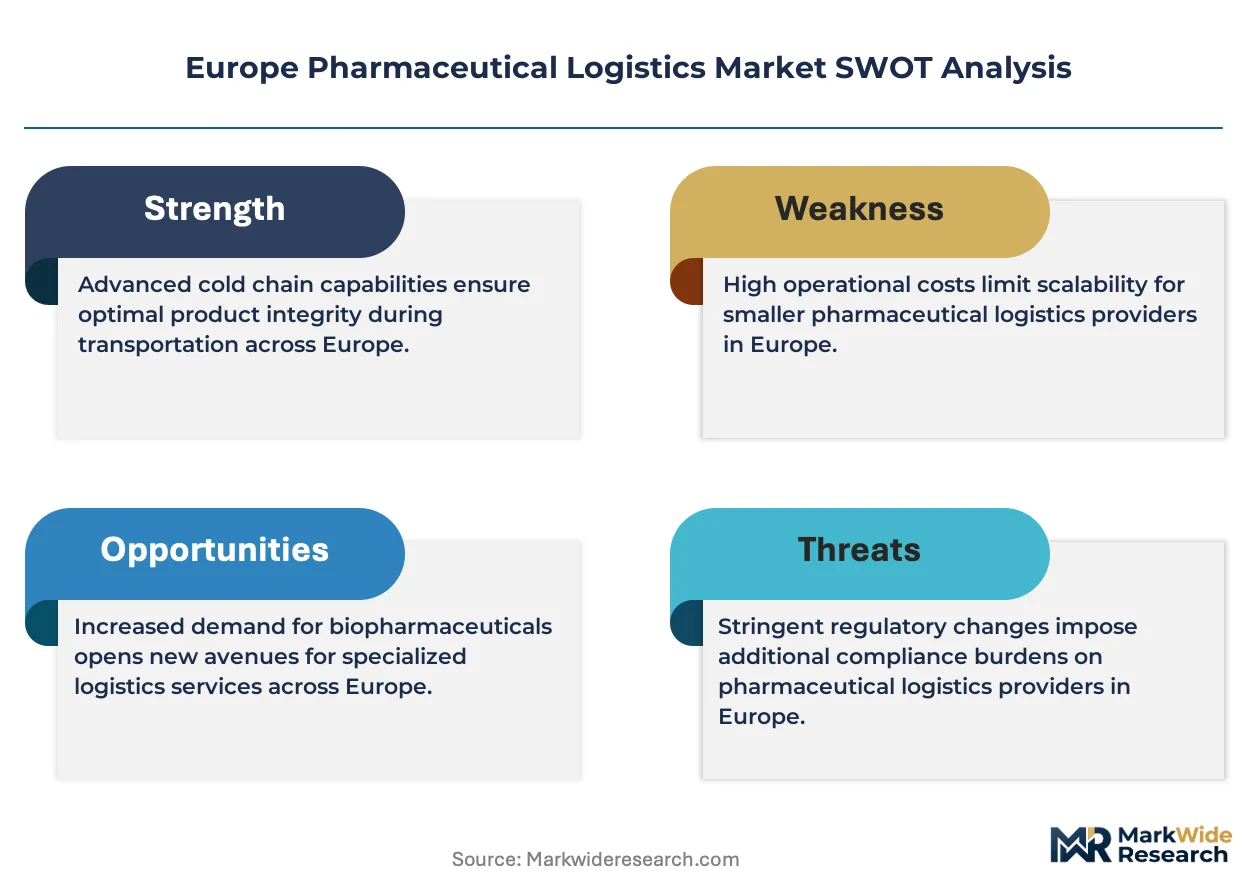
The EU Green Deal is recalibrating pharmaceutical logistics priorities across Europe. DHL Supply Chain leverages its pan-European cold chain infrastructure to serve biologics producers. Kuehne + Nagel International AG anchors temperature-controlled pharma distribution through its Swiss-European hub network. FedEx competes on express delivery speed for clinical trial materials.
Europe pharmaceutical logistics encompasses the specialized storage, handling, and distribution of medicinal products requiring temperature control, chain-of-custody documentation, and serialization compliance. Cold chain infrastructure maintains 2-8°C and -80°C ranges for biologics and cell therapies, while standard shipping handles ambient small molecules and generics. Biologics command premium logistics spend due to stringent thermal requirements, whereas express delivery segments capture margin from oncology and rare disease therapies with short shelf lives. Warehousing services sit at the mature core of the value chain, while inventory management systems integrating EMA serialization mandates represent the fastest-growing service layer.
EMA's Good Distribution Practice guidelines, the EU Falsified Medicines Directive, and national health authority inspections shape operational compliance costs and technology investment requirements. REACH and RoHS frameworks indirectly affect packaging material selection and waste handling protocols. Stakeholders must monitor how the EU AI Act and proposed pharmaceutical supply chain security rules reshape authentication and track-and-trace obligations.
Market Dynamics
EMA's Good Distribution Practice revisions are forcing wholesale reconfiguration of temperature monitoring infrastructure across European pharma corridors. Biologics producers now demand real-time chain-of-custody verification that legacy warehouse management systems cannot deliver.
Growth Catalysts
- EU Falsified Medicines Directive:Serialization mandates are accelerating investment in track-and-trace infrastructure across German and Dutch distribution hubs.
- Cell therapy commercialization:CAR-T manufacturers in Belgium and Switzerland require -80°C cryogenic logistics networks that did not exist five years ago.
- Rhine-Ruhr corridor concentration:Belgium's port of Antwerp anchors 40% of European pharma imports, creating dense cold chain ecosystems.
Market Restraints
- Refrigerant cost volatility:EU F-Gas Regulation phase-down is compressing availability of HFC-based cooling systems before CO2 alternatives achieve scale.
- Specialized fleet shortage:Qualified temperature-controlled vehicles remain concentrated among fewer than 12 certified European operators.
- Packaging material constraints:REACH compliance for insulated shippers limits supplier base to ECHA-registered producers with extended lead times.
Strategic Opportunities
- Central and Eastern Europe:Poland and Czech Republic lack GDP-certified warehousing capacity relative to their growing clinical trial activity.
- Direct-to-patient distribution:Home infusion therapies for rare diseases require last-mile cold chain capabilities that hospital-centric models cannot address.
- EU Green Deal alignment:Renewable-powered cold storage facilities qualify for CSRD-linked sustainability financing instruments.
Industry Challenges
- Qualified personnel scarcity:GDP-trained quality assurance auditors command 35% wage premiums across Benelux markets.
- Multi-site validation complexity:EMA inspections require harmonized documentation across 15+ national competent authorities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Pharmaceutical Logistics Market |
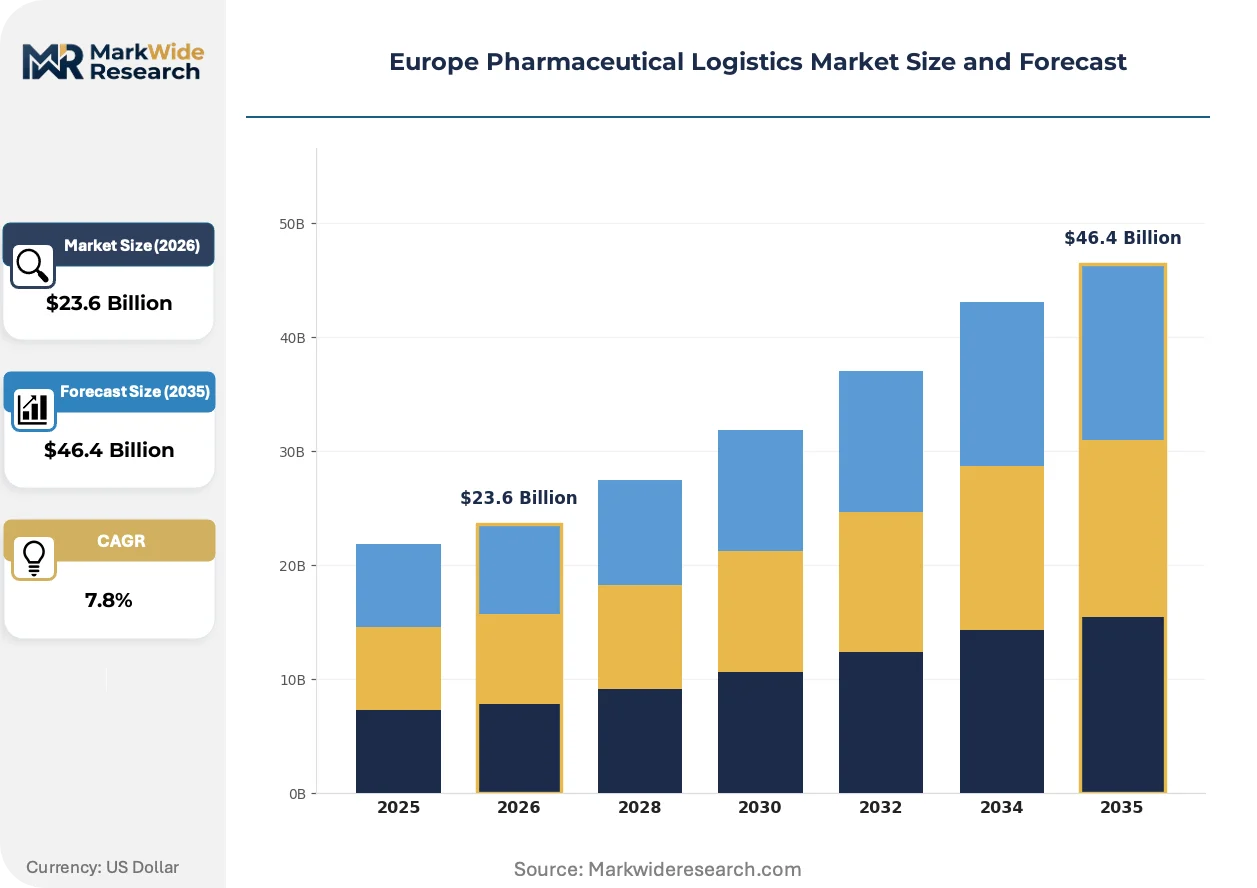
| Market Size in 2026 | $23.6 Billion |
| Market Size in 2035 | $46.4 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biologics, Small Molecules, Vaccines, Generics Delivery Mode: Cold Chain, Standard Shipping, Express Delivery, Home Delivery End User: Hospitals, Pharmacies, Clinics, Healthcare Providers Service Type: Warehousing, Distribution, Inventory Management, Customs Clearance |
| Companies Covered | United Parcel Service, DSV, DHL Supply Chain, Agility Logistics, C.H. Robinson Worldwide, Kuehne + Nagel International AG, CEVA Logistics, FedEx, DB Schenker, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Pharmaceutical Logistics Market Emerging Trajectories
Digital ledger technologies and passive thermal packaging advances are compressing verification timelines while extending viable shipping durations. These shifts are redrawing competitive boundaries between asset-heavy operators and technology-enabled intermediaries.
Blockchain-enabled temperature logging is decentralizing custody verification across multi-modal European pharma corridors. Third-party logistics providers in the Netherlands and Germany are deploying distributed ledger systems that eliminate paper-based handoff documentation. This architecture is decentralizing quality assurance responsibilities from centralized quality units to individual handling nodes.
EU AI Act provisions on high-risk AI systems are mandating algorithmic audit trails for automated warehouse temperature controls. Pharmaceutical distributors must now document training data provenance and decision logic for AI-driven climate management systems. Small and mid-size operators in Spain and Italy face disproportionate compliance burdens relative to integrated pan-European networks.
Hospital procurement departments are consolidating vendor panels around GDP-certified partners with integrated serialization capabilities. Traditional freight forwarders without pharmaceutical licensing are losing access to tender processes at major French and Italian hospital networks. This consolidation is most visible in oncology supply chains where product integrity claims require auditable cold chain documentation from manufacturer to infusion site.
Europe Pharmaceutical Logistics Market Segmentation
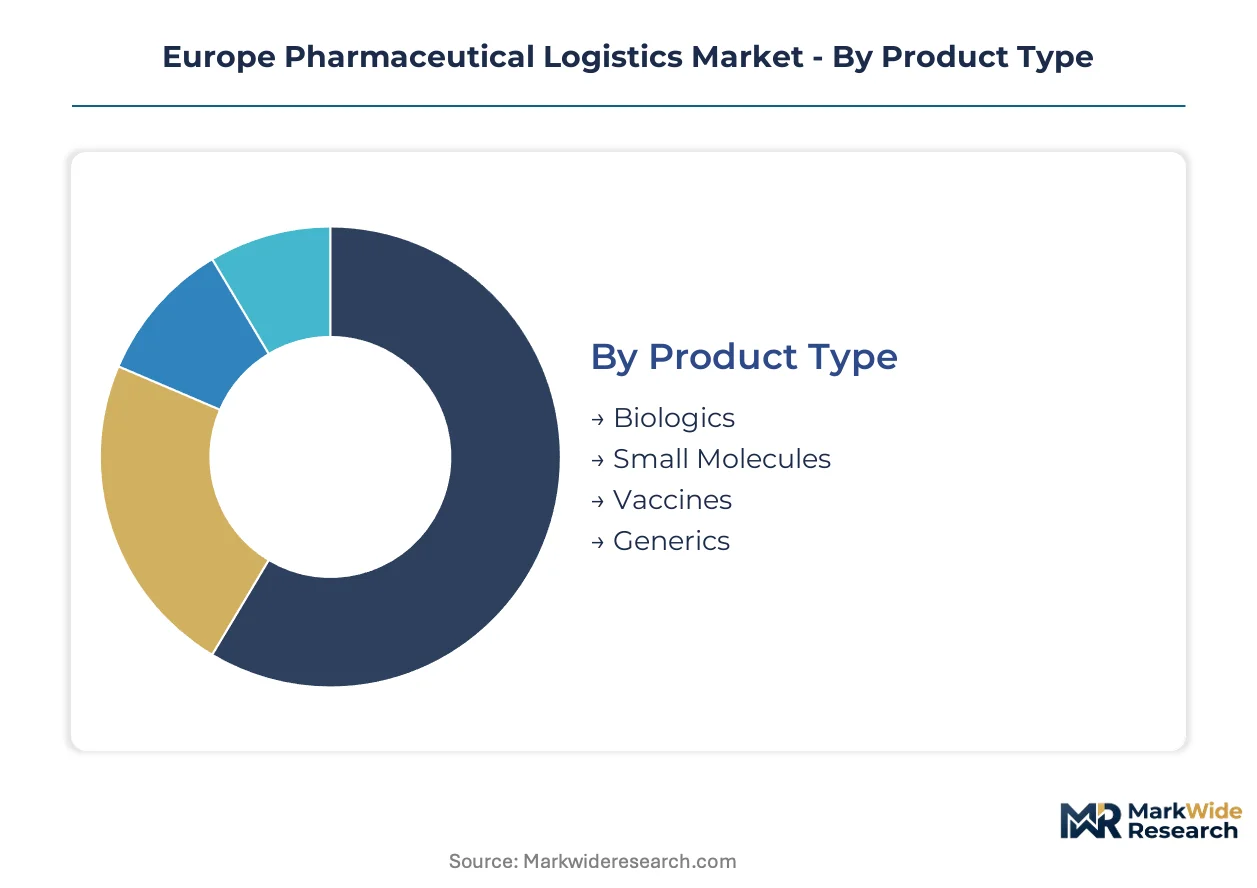
Pharmaceutical logistics segmentation in Europe maps directly to thermal requirements, regulatory compliance tiers, and distribution velocity needs. Each axis reveals distinct margin profiles and infrastructure investment thresholds that shape competitive positioning across the Rhine-Ruhr corridor and beyond.
Product Type:
Thermal sensitivity and molecular complexity define product-level logistics specifications across European distribution networks.
- Biologics:Protein-based therapeutics require continuous 2-8°C cold chain maintenance with real-time deviation alerts. German and Swiss manufacturers of monoclonal antibodies drive demand for GDP-validated cryogenic infrastructure that EMA inspections scrutinize intensively.
- Small Molecules:Chemical compounds tolerate ambient storage but demand serialization compliance under the EU Falsified Medicines Directive. Generic producers in Spain and Italy concentrate volume here, prioritizing cost-efficient palletized distribution over temperature-controlled unit handling.
- Vaccines:mRNA platforms require ultra-low -80°C storage capabilities that Belgium's Antwerp hub has expanded to accommodate.
- Generics:Off-patent small molecules compete on logistics cost minimization through consolidated cross-border truckloads.
Biologics leads on scale; vaccines leads on momentum.
Delivery Mode:
Speed-to-patient and thermal integrity requirements stratify delivery infrastructure across European corridors.
- Cold Chain:Refrigerated transport and storage networks maintain 2-8°C for biologics and -80°C for cell therapies. Belgium and Netherlands operators have densified qualified vehicle fleets to serve CAR-T commercialization.
- Standard Shipping:Ambient palletized freight handles generics and stable small molecules through consolidated hub-and-spoke networks. Rhine-Ruhr corridor concentration minimizes per-unit cost for high-volume pharmaceutical flows.
- Express Delivery:Time-definite services for clinical trial materials and short-shelf-life oncology therapies command premium pricing.
- Home Delivery:Last-mile cold chain for rare disease home infusion therapies requires patient-addressable GDP compliance that hospital-centric models cannot replicate.
Cold chain dominates revenue contribution; home delivery exhibits steepest expansion trajectory.
End User:
Procurement sophistication and regulatory liability exposure vary sharply across healthcare delivery settings.
- Hospitals:Acute care institutions in France and Italy consolidate vendor panels around GDP-certified partners with integrated serialization. Oncology supply chains here demand auditable cold chain documentation from manufacturer to infusion site.
- Pharmacies:Community and hospital pharmacy networks handle high SKU variety with limited storage depth, prioritizing inventory turnover velocity.
- Clinics:Outpatient settings concentrate demand for temperature-sensitive specialty therapies with limited on-site refrigeration capacity.
- Healthcare Providers:Integrated delivery networks negotiate consolidated logistics contracts spanning multiple care settings.
Hospitals anchor volume concentration; clinics gain share fastest.
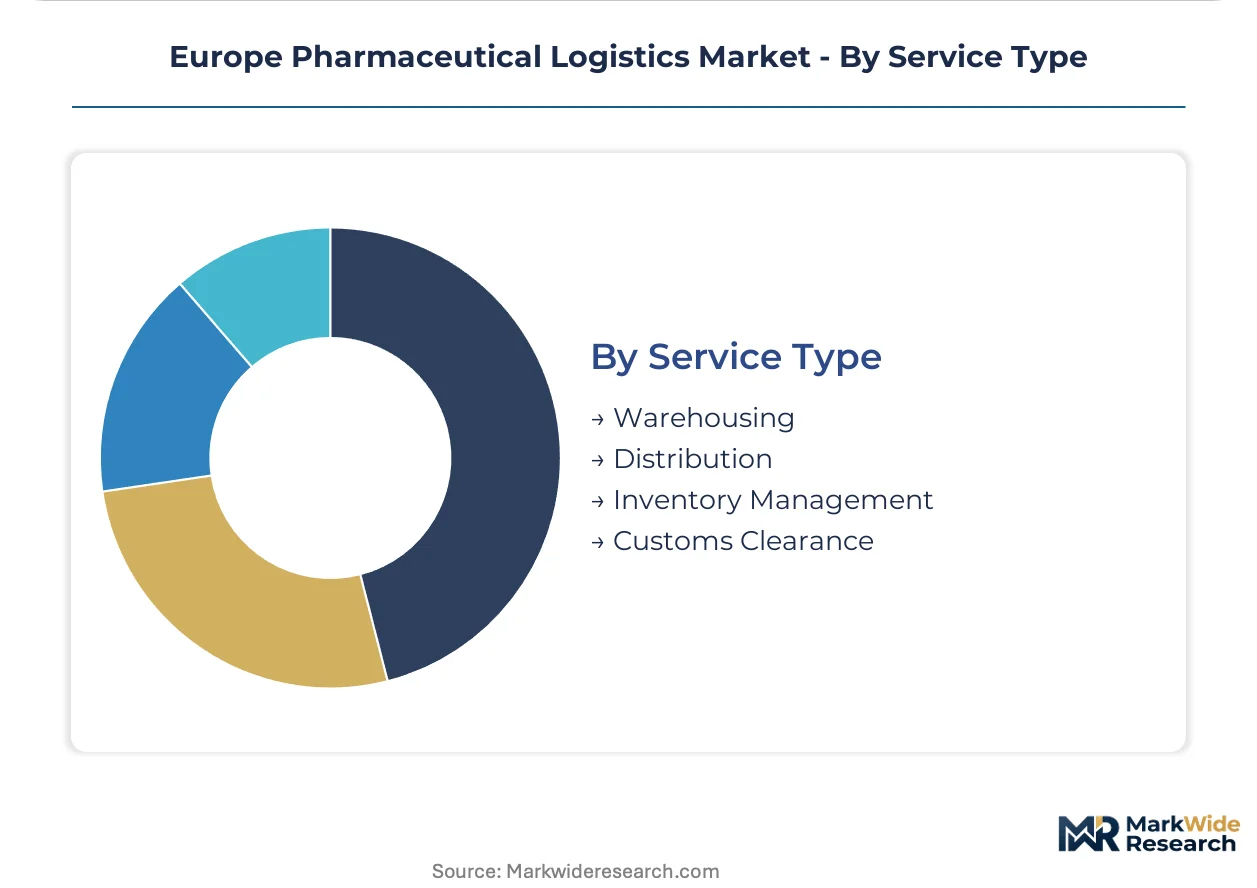
Service Type:
Value chain positioning determines margin capture and capital intensity across logistics functions.
- Warehousing:Temperature-controlled storage facilities represent the mature core of pharmaceutical logistics, with GDP certification requirements limiting qualified supply. Benelux markets command 35% wage premiums for trained quality assurance personnel.
- Distribution:Transport execution spans dedicated pharmaceutical fleets and qualified multi-user networks, with EMA inspections requiring harmonized documentation across 15+ national competent authorities.
- Inventory Management:Systems integrating EMA serialization mandates and AI-driven demand forecasting represent the service layer expanding most quickly.
- Customs Clearance:Post-Brexit regulatory divergence and EU pharmaceutical import verification requirements have elevated specialized brokerage capabilities.
Warehousing leads on installed base; inventory management leads on technology investment intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical logistics infrastructure in Europe traces its modern lineage to the post-war chemical and pharmaceutical industrialization of the Rhine-Ruhr corridor, where integrated supply chains first achieved GDP-compliant scale. This historical concentration continues to shape distribution patterns across the continent.
Germany
Monoclonal antibody manufacturers in Bavaria and Baden-Württemberg drive demand for qualified -80°C cryogenic storage. The country's national pharmaceutical regulator enforces GDP certification through state-level competent authorities with harmonized inspection protocols. The Rhine-Ruhr corridor anchors Europe's densest cold chain ecosystem, with DHL Supply Chain and DB Schenker operating GDP-validated multi-temperature facilities.
Belgium
CAR-T cell therapy commercialization from Brussels and Ghent biotech clusters requires ultra-low temperature logistics networks that did not exist five years ago. EMA's centralized marketing authorization procedures position Belgium as a natural distribution gateway for advanced therapies. The port of Antwerp handles 40% of European pharmaceutical imports, with specialized container terminals serving temperature-sensitive biologics.
Netherlands
Clinical trial logistics and comparator drug sourcing concentrate around Amsterdam and Rotterdam pharmaceutical services hubs. The EU Falsified Medicines Directive serialization mandates accelerate track-and-trace infrastructure investment at Dutch distribution centers. Schiphol Airport's cargo zone maintains one of Europe's highest densities of temperature-controlled pharmaceutical handling facilities.
Switzerland
Swissmedic's stringent marketing authorization requirements create a premium logistics tier serving Basel and Zurich biopharma headquarters. The country's non-EU status necessitates specialized customs brokerage capabilities for pharmaceutical transit. The Swiss-European hub network operated by Kuehne + Nagel International AG exemplifies integrated temperature-controlled distribution across regulatory boundaries.
United Kingdom
Post-Brexit regulatory divergence from EMA procedures forces UK-based manufacturers to maintain parallel qualified person systems and separate batch release protocols. The Medicines and Healthcare products Regulatory Agency operates distinct GDP inspection schedules from continental European counterparts. London and southeast England pharmaceutical services clusters face capacity constraints as companies rebuild UK-specific supply chain redundancies.
Europe Pharmaceutical Logistics Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification depth and temperature-control sophistication. The market structure consolidates around pan-European integrated networks with GDP-validated infrastructure, while regional specialists capture niche segments requiring localized regulatory expertise. Three archetypes dominate: asset-heavy cold chain operators, technology-enabled serialization platforms, and clinical trial express specialists. Capacity expansion and strategic partnerships constitute the dominant competitive moves as operators seek EMA inspection coverage across multiple national competent authorities.
Within the asset-heavy tier, DHL Supply Chain and Kuehne + Nagel International AG exemplify pan-European cold chain operators with GDP-validated multi-temperature infrastructure. FedEx occupies a position among express delivery specialists serving clinical trial materials and short-shelf-life oncology therapies. These three companies represent distinct strategic postures: integrated network scale, Swiss-European hub specialization, and time-definite clinical logistics respectively.
| Leading Market Players |
|---|
| United Parcel Service |
| DSV |
| DHL Supply Chain |
| Agility Logistics |
| C.H. Robinson Worldwide |
| Kuehne + Nagel International AG |
| CEVA Logistics |
| FedEx |
| DB Schenker |
| Others |
Supply Flow & Price Mechanics
HFC refrigerant price indices cascade through European pharmaceutical logistics tiers, compressing margins on legacy cold chain operations while amplifying premiums for CO2-based alternatives that qualify for CSRD-linked financing instruments.
Pricing Analysis
Three-tier pricing structure across GDP-certified premium, standard licensed, and unqualified economy levels stratifies the European market. Price differentiation hinges on EMA inspection coverage depth and real-time temperature verification capability. Cost compression in the standard tier is intensifying because REACH-registered packaging suppliers command extended lead times. Generic distributors in Spain and Italy exhibit highest price sensitivity, while CAR-T manufacturers in Belgium accept premium positioning for -80°C cryogenic assurance.
Supply Chain Analysis
Reverse logistics for temperature-deviated biologics and expired cell therapies creates specialized recovery flows that few operators have configured. Geographic supply concentration centers on Germany, Belgium, and the Netherlands, where GDP-validated warehousing clusters feed from Swissmedic-authorized Swiss hubs. Raw material dependencies span ECHA-registered insulated shippers, qualified refrigerants, and serialized authentication labels. Single-source vulnerability pervades the specialized fleet segment, where fewer than twelve certified European operators control qualified temperature-controlled vehicles. Distribution runs through Antwerp's pharmaceutical container terminals into Rhine-Ruhr corridor hub facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European pharmaceutical logistics represents a late-cycle quality story as hospital procurement departments consolidate vendor panels around GDP-certified partners with integrated serialization capabilities, displacing traditional freight forwarders from oncology supply chains.
For Market Incumbents: Deepen EMA inspection coverage across multiple national competent authorities to defend against emerging technology-enabled serialization platforms. Prioritize backward integration into renewable-powered cold storage facilities that qualify for CSRD-linked sustainability financing. Incumbent operators must anchor capacity expansion in Poland and Czech Republic before clinical trial activity outpaces GDP-certified warehousing supply. For New Entrants and Emerging Players: Direct-to-patient digital platforms offer the most penetrable route for specialized last-mile cold chain capabilities that hospital-centric incumbents cannot replicate. Target home infusion therapies for rare diseases in France and Italy, where patient-addressable GDP compliance requirements exceed existing infrastructure. A go-to-market angle anchored in blockchain-enabled temperature logging can decentralize custody verification without asset-heavy fleet investment. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-size operators possessing Swiss-European hub specialization and existing EMA inspection relationships across Benelux markets. Long-term viability in this sector hinges on regulatory compliance depth rather than pure scale. Acquisition targets should demonstrate coverage of multiple national competent authorities. The signal to watch is consolidation velocity among French and Italian hospital networks as procurement departments narrow vendor panels.| Strategic Initiative | Industry Significance |
|---|---|
| GDP Certification Expansion | EMA inspection coverage across 15+ national competent authorities secures hospital network access. |
| Cryogenic Infrastructure Buildout | -80°C capabilities in Belgium and Switzerland capture CAR-T commercialization flows. |
| Blockchain Temperature Logging | Distributed ledger systems eliminate paper-based handoff documentation across multi-modal corridors. |
| Renewable Cold Storage Investment | CSRD-linked sustainability financing instruments reduce capital costs for EU Green Deal alignment. |
| Central and Eastern Europe Capacity Addition | Poland and Czech Republic clinical trial activity outpaces existing GDP-certified warehousing supply. |
Methodological Framework
Direct dialogue with pharmaceutical logistics operations directors, EMA regulatory affairs specialists, hospital procurement managers, and cold chain quality assurance auditors grounded this analysis in operational reality. Secondary validation drew from EMA inspection reports, EU Falsified Medicines Directive implementation databases, REACH registration filings, and customs pharmaceutical trade statistics. Bottom-up capacity modeling across qualified vehicle fleets and GDP-certified warehousing square footage triangulated against top-down pharmaceutical production value flows.
Segment-level value outputs across the projection horizon reflect thermal requirement stratification, regulatory compliance tiering, and distribution velocity needs. The analytical framework modeled product type, delivery mode, end user, and service type dimensions alongside regional regulatory cluster variations. CAGRs were derived from capacity expansion pipelines, EMA inspection schedule densities, and clinical trial logistics demand trajectories. Cryogenic infrastructure investment cycles and serialization mandate compliance timelines served as key forecast inputs.
The model assumes a particular technology adoption path for AI-driven warehouse climate management; alternative pathways for passive thermal packaging advances would alter the outlook for digital ledger verification demand. Forecasts reflect base-case assumptions regarding EMA Good Distribution Practice revision implementation schedules and EU Falsified Medicines Directive enforcement intensity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Bruxism Management Market
Healthcare Services
Australia Senior Living Market
Healthcare Services
Vaccine Logistics Market
Healthcare Services
Professional Spa Services Market
Healthcare Services
Medical Peer & External Physician Review Services Market
Healthcare Services
US Healthcare Staffing Market
Healthcare Services
Healthcare CRO Services Market
Healthcare Services
Global Umbilical Cord Blood Banking Market
Healthcare Services
Inhaled and Intranasal Products Contract Service Providers Market
Healthcare Services
Global Perfusion Services Market
Healthcare Services
Global Mobile Clinics Market
Healthcare Services
Global Geriatric Care Services Market
Healthcare Services
Global Hospice Care Market
Healthcare Services
US Medical Billing Outsourcing Market
Healthcare Services
Asia-Pacific Healthcare Cold Chain Logistics Market
Healthcare Services
Metabolomics Services Market