
 Global Corporate Wellness Solutions Market | 2026-2036
Global Corporate Wellness Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Global Corporate Wellness Solutions Market Foresight
The capital-intensity divergence between platform-heavy and service-heavy providers is reorganizing competitive dynamics across the Global Corporate Wellness Solutions Market. UnitedHealth Group leverages its integrated payer-provider infrastructure to bundle wellness with medical cost management. CVS Health Corporation anchors its offering through pharmacy-based touchpoints and chronic care connectivity. Virgin Pulse competes via digital-first engagement architecture that scales across dispersed workforces.
Corporate wellness solutions encompass structured programs and technologies designed to improve employee physical health, mental resilience, and workplace productivity through biometric screening, behavioral coaching, and environmental design interventions. These systems typically integrate wearable data feeds, clinical risk algorithms, and personalized intervention pathways to reduce absenteeism and medical claims expenditure. The solution type dimension shows mental health services and digital platforms capturing disproportionate investment as hybrid work normalizes distributed care delivery. Fitness programs remain mature with stable employer penetration, while telehealth services within the delivery model segment represent the fastest expansion vector as asynchronous clinical access reduces per-employee program costs.
The US Department of Labor enforces ERISA standards that govern wellness incentive structures and data privacy protections for employee health information. The EU's GDPR and emerging AI Act constrain how European employers deploy algorithmic health scoring and predictive risk stratification. Stakeholders must monitor how regulatory fragmentation between HIPAA-governed US environments and GDPR-plus-CSRD European frameworks shapes vendor architecture decisions and cross-border program deployment feasibility.
Market Dynamics
Hybrid work permanence is bifurcating program delivery models across the Global Corporate Wellness Solutions Market, forcing vendors to architect simultaneous on-site and distributed engagement infrastructures while containing per-employee service costs.
Growth Catalysts
- CSRD Mandate:The EU's Corporate Sustainability Reporting Directive now compels workforce health disclosures from major employers, creating compliance-driven procurement of measurement and reporting platforms.
- Biometric Wearables:Continuous glucose monitors and stress-tracking wearables are embedding into employer risk stratification protocols, generating real-time intervention triggers.
- Financial Services:Large banks and insurers are expanding wellness budgets to address burnout-related attrition, prioritizing mental health service line items.
Market Restraints
- GDPR-Plus-AI Act Friction:European algorithmic health scoring faces dual regulatory constraints that increase compliance architecture costs and slow predictive analytics deployment.
- Clinical Talent Concentration:Licensed behavioral health providers cluster in metropolitan United States corridors, creating access deserts for distributed workforces in secondary markets.
- Employer-Sponsored Dependency:United States market depth ties revenue to commercial insurance cycles, exposing vendors to coverage contraction during economic downturns.
Strategic Opportunities
- Japan METI Incentives:Subsidies for workplace mental health programs are accelerating adoption among manufacturing exporters with aging workforces.
- Telehealth-Coaching Convergence:Asynchronous clinical access combined with AI-guided behavioral nudges is compressing per-episode costs below traditional EAP models.
- Small-Medium Enterprise Gap:Employers below one thousand workers remain underserved by platform economics designed for Fortune 500 scale, creating white space for modular solutions.
Industry Challenges
- Interoperability Debt:Legacy HRIS and benefits administration systems resist API integration with modern wellness platforms, forcing expensive middleware development.
- Outcome Attribution:Medical claims reduction and productivity gains resist clean causal isolation from wellness interventions, complicating ROI demonstration to CFO buyers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Corporate Wellness Solutions Market |
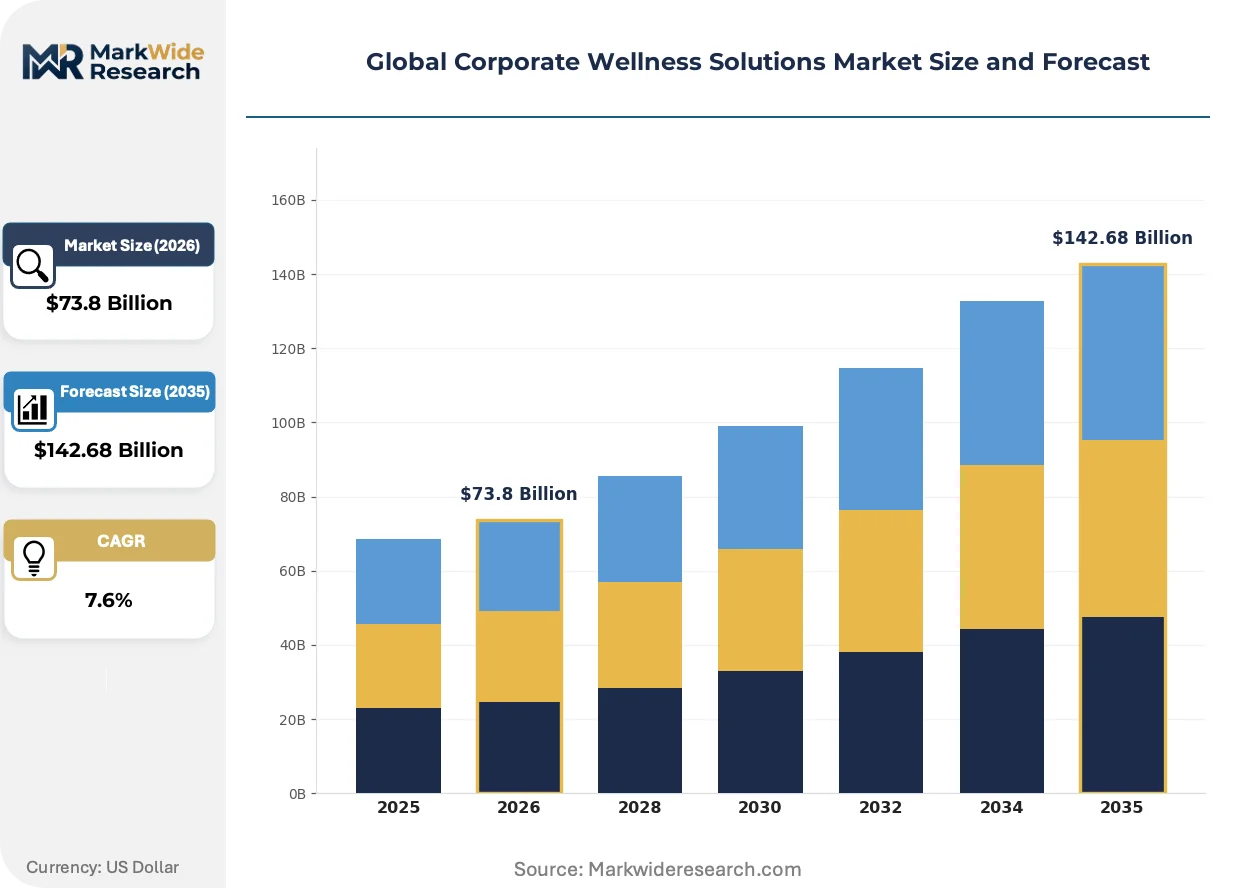
| Market Size in 2026 | $73.8 Billion |
| Market Size in 2035 | $142.68 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Health Risk Assessment, Fitness Programs, Mental Health Services, Nutrition Counseling, Ergonomics Solutions Application: Employee Engagement, Stress Management, Chronic Disease Prevention, Workplace Safety, Productivity Enhancement End User: Large Enterprises, Small & Medium Businesses, Government Agencies, Non-Profit Organizations, Startups Delivery Model: Onsite Programs, Digital Platforms, Hybrid Models, Telehealth Services, Mobile Apps |
| Companies Covered | UnitedHealth Group, CVS Health Corporation, ComPsych Corporation, Virgin Pulse, Cerner Corporation, Privia Health, Truworth Health Technologies, EXOS, Vitality Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Corporate Wellness Solutions Market Shifts & Advancements
Artificial intelligence is penetrating diagnostic and coaching workflows across the Global Corporate Wellness Solutions Market, compressing response latency while raising algorithmic accountability demands from both regulators and covered populations.
Generative AI coaching interfaces are fragmenting the traditional therapist-to-patient relationship model. Large employers in technology and professional services are piloting LLM-driven cognitive behavioral interventions for subclinical anxiety and sleep disruption. This automation is compressing unit economics for digital mental health platforms while creating tiered service models that reserve human clinicians for acute presentations.
GDPR and the emerging EU AI Act are constraining predictive health risk stratification across European employer programs. Algorithmic scoring of burnout probability or attrition risk now requires explicit consent documentation and human-in-the-loop review protocols. Vendors serving Germany, France, and the Netherlands are rearchitecting data pipelines to separate inference computation from identifiable record storage.
Chief Human Resource Officers are consolidating vendor relationships around platforms demonstrating medical cost impact rather than engagement metrics alone. This procurement compression favors integrated payer-provider systems over point-solution specialists in United States accounts. Financial services and healthcare provider employers are leading this consolidation, demanding single-contract accountability for biometric outcomes and absenteeism reduction.
Global Corporate Wellness Solutions Market Segmentation
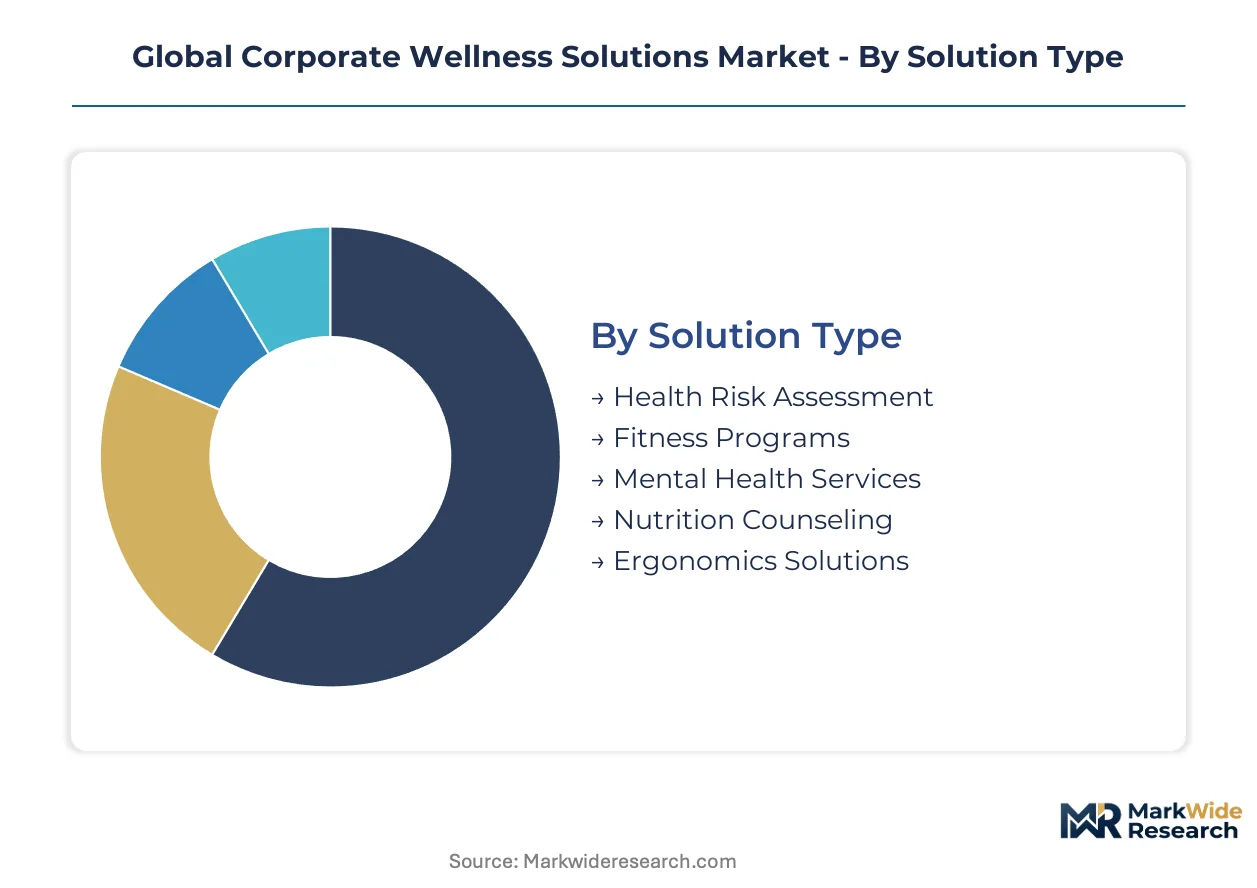
Corporate wellness solutions fragment across four intersecting dimensions that determine vendor architecture and pricing power. Solution type and delivery model combinations now dictate whether providers capture enterprise budgets or remain trapped in commoditized point-solution competition.
Solution Type:
Mental health services face acute substitution pressure from generative AI coaching interfaces that replicate cognitive behavioral therapy protocols at fractional cost, while fitness programs confront free consumer apps and employer gym subsidies.
- Mental Health Services:Structured clinical and subclinical interventions spanning licensed therapy, EAP counseling, and digital behavioral coaching. Demand concentrates among financial services employers in the United States and United Kingdom addressing burnout-related attrition through expanded service line items.
- Fitness Programs:On-site gym facilities, subsidized memberships, and group exercise classes. German and Japanese manufacturing employers sustain procurement despite commoditization through integration with occupational health mandates.
- Health Risk Assessment:Biometric screening and predictive analytics for chronic disease identification. HIPAA-covered entities in the United States drive adoption for medical cost management.
- Nutrition Counseling:Dietary intervention programs and metabolic health coaching. Indian IT services employers expand procurement for diabetes prevention in aging workforces.
- Ergonomics Solutions:Workstation design and musculoskeletal injury prevention. Australian mining and construction sectors anchor demand through occupational safety regulations.
Fitness programs retain volume leadership; mental health services hold the steepest expansion curve.
Application:
Cost tier differentiation separates acute clinical interventions from preventive engagement tools, with CFO buyers demanding outcome-based contracts for chronic disease prevention while HR purchasers accept engagement metrics for stress management.
- Chronic Disease Prevention:Diabetes, hypertension, and cardiovascular risk reduction protocols combining biometric monitoring with clinical coaching. UnitedHealth Group and CVS Health anchor United States enterprise procurement through integrated payer-provider accountability for medical claims reduction.
- Stress Management:Resilience training, mindfulness programs, and workload optimization tools. Professional services employers in London and Singapore pilot AI-guided interventions for subclinical anxiety.
- Employee Engagement:Gamified wellness challenges and social recognition systems. Virgin Pulse competes via digital-first architecture scaling across dispersed technology workforces.
- Workplace Safety:Injury prevention and occupational health compliance. Brazilian manufacturing exporters respond to ANVISA workplace health mandates.
- Productivity Enhancement:Sleep optimization, cognitive performance, and presenteeism reduction. Japanese METI subsidies accelerate adoption among automotive suppliers with aging workforces.
Employee engagement commands the widest employer penetration; chronic disease prevention captures the highest per-employee contract values.
End User:
Customer type determines platform economics viability, with Fortune 500 scale enabling vendor profitability while sub-thousand-employee organizations remain underserved by current pricing models.
- Large Enterprises:Employers exceeding ten thousand workers with dedicated wellness budgets and procurement teams. United States financial services and healthcare provider organizations lead consolidation around integrated platforms demanding single-contract biometric outcome accountability.
- Small & Medium Businesses:Employers between fifty and one thousand workers lacking dedicated wellness infrastructure. Modular solutions from emerging vendors target this white space with API-first architectures bypassing legacy HRIS integration debt.
- Government Agencies:Federal, state, and municipal employers with public-sector procurement constraints. EU member state civil service programs respond to CSRD workforce health disclosure mandates.
- Non-Profit Organizations:Mission-driven employers with constrained budgets prioritizing mission alignment over clinical sophistication. Canadian healthcare charities and United Kingdom social enterprises represent concentrated demand.
- Startups:High-growth technology employers with young, distributed workforces. Asynchronous digital platforms and mental health apps penetrate through founder-driven purchasing decisions.
Large enterprises dominate current vendor revenue; small and medium businesses offer the largest untapped addressable base.
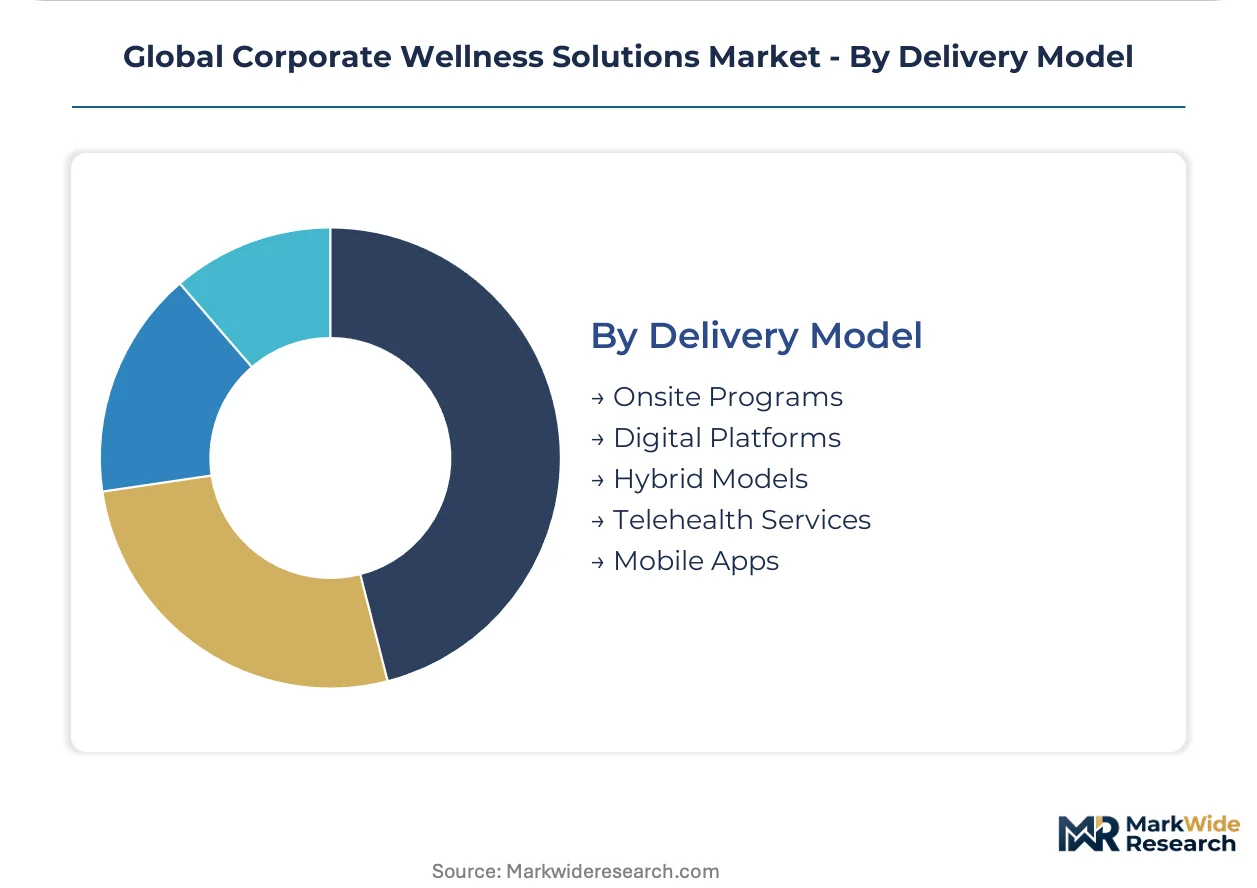
Delivery Model:
Supply concentration in clinical talent reshapes feasibility across delivery modalities, with licensed behavioral health providers clustering in metropolitan United States corridors and forcing telehealth expansion for geographic coverage.
- Telehealth Services:Asynchronous and synchronous clinical access reducing per-episode costs below traditional EAP models. United States employers drive fastest expansion as HIPAA-compliant platforms integrate with commercial insurance networks.
- Digital Platforms:Web and mobile-native wellness architectures with wearable data integration. GDPR and EU AI Act constraints force German and French vendors to separate inference computation from identifiable record storage.
- Hybrid Models:Coordinated on-site and distributed engagement infrastructures. Post-pandemic permanence of remote work bifurcates program design for financial services employers maintaining flagship offices alongside distributed teams.
- Onsite Programs:Physical facility-based services including biometric screening and fitness classes. Japanese manufacturing campuses and United States hospital systems sustain procurement through captive occupational health infrastructure.
- Mobile Apps:Smartphone-native engagement tools with push-notification behavioral nudges. Indian IT services employers deploy for diabetes prevention in field-based workforces.
Onsite programs retain contract value concentration; telehealth services are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The export-import balance for corporate wellness solutions tilts toward service and technology outflows from the United States and Western Europe, with Asia-Pacific markets importing digital platforms while building localized coaching capacity. Regulatory divergence between HIPAA-governed US environments and GDPR-plus-CSRD European frameworks shapes cross-border deployment feasibility.
United States
Employer-sponsored healthcare creates the deepest procurement incentives globally, with financial services firms in New York and Chicago expanding mental health budgets to combat burnout-related attrition. The Department of Labor enforces ERISA standards governing wellness incentive structures and data privacy protections for employee health information. The Boston-to-Washington corridor concentrates vendor headquarters and clinical talent pools, though licensed behavioral health providers cluster in metropolitan areas creating access deserts for distributed workforces.
Germany
Manufacturing employers sustain fitness program procurement through integration with occupational health mandates, while GDPR and the emerging EU AI Act constrain algorithmic health scoring deployments. The CSRD mandate now compels workforce health disclosures from major employers, creating compliance-driven procurement of measurement platforms. The Rhine-Ruhr industrial belt anchors demand from automotive and chemical exporters with aging workforces.
Japan
METI subsidies for workplace mental health programs accelerate adoption among manufacturing exporters facing demographic contraction. The country's national pharmaceutical regulator maintains strict boundaries between wellness coaching and clinical intervention, shaping vendor service architecture. The Nagoya-Chubu automotive supplier cluster leads implementation of productivity enhancement programs targeting sleep optimization and cognitive performance.
United Kingdom
Professional services employers in London pilot AI-guided interventions for subclinical anxiety, driving demand for digital mental health platforms. The Information Commissioner's Office enforces GDPR-derived constraints on employee health data processing that exceed baseline European requirements. The London-Southeast corridor concentrates financial services procurement, while regional cities struggle with clinical talent access for face-to-face services.
India
IT services employers expand nutrition counseling procurement for diabetes prevention in aging workforces, deploying mobile-native engagement tools for field-based employees. The country's central bank and securities regulator impose governance standards on employee welfare disclosures for listed companies. The Bangalore-Hyderabad technology corridor drives adoption of asynchronous digital platforms that bypass legacy HRIS integration challenges.
Global Corporate Wellness Solutions Market Competitive Landscape
Concentration sits with integrated payer-provider systems that bundle wellness with medical cost management, creating tiered competitive dynamics where platform-heavy and service-heavy providers diverge on capital intensity. UnitedHealth Group leverages its insurance infrastructure to capture enterprise accounts demanding single-contract biometric outcome accountability. CVS Health Corporation anchors through pharmacy-based touchpoints and chronic care connectivity. Virgin Pulse competes via digital-first engagement architecture. Dominant competitive moves include strategic partnerships with wearable device manufacturers and portfolio diversification into mental health service lines.
Within the integrated health systems tier, UnitedHealth Group and CVS Health Corporation represent archetypes of payer-provider convergence that capture Fortune 500 procurement consolidating around medical cost impact demonstration. Virgin Pulse occupies a position exemplifying digital-native platform economics designed for dispersed workforce scalability. Among specialized service providers, ComPsych Corporation and Cerner Corporation sit within distinct archetypes—employee assistance program heritage versus health information technology infrastructure—each facing pressure to demonstrate outcome attribution beyond engagement metrics.
| Leading Market Players |
|---|
| UnitedHealth Group |
| CVS Health Corporation |
| ComPsych Corporation |
| Virgin Pulse |
| Cerner Corporation |
| Privia Health |
| Truworth Health Technologies |
| EXOS |
| Vitality Group |
| Others |
Supply & Pricing Matrix
Outcome-based contracts with biometric outcome guarantees lock in multi-year supply access for large United States financial services employers while compressing price visibility for point-solution vendors lacking medical cost accountability. This contract-structure pattern concentrates procurement power among integrated payer-provider systems and fragments pricing power across service-heavy specialists competing for modular budget allocations.
Pricing Analysis
Large enterprise buyers anchor per-employee subscription pricing across tiered SaaS platforms, with Fortune 500 scale commanding volume discounts unavailable to sub-thousand-employee organizations. Price differentiation separates HIPAA-compliant integrated systems from GDPR-constrained European deployments, with certification tier and geographic delivery cost driving spreads between United States and EU contract values. Cost compression in digital mental health modules intensifies as generative AI coaching interfaces displace licensed therapist hours, eroding margins for traditional EAP providers. Small and medium businesses exhibit acute price sensitivity, while healthcare provider employers prioritize outcome-based contracts over per-seat economics.
Supply Chain Analysis
Inventory cycles for biometric wearables and clinical talent deployment extend lead times for enterprise program launches, particularly for distributed workforce configurations requiring geographic coverage density. Platform development concentrates in the United States, India, and Israel, while licensed behavioral health providers cluster in metropolitan United States corridors and London-Southeast England. Raw material dependencies include wearable sensor components, cloud infrastructure, and API middleware for legacy HRIS integration. Single-source vulnerability in clinical talent access creates coverage deserts for secondary United States markets and regional United Kingdom cities. Distribution runs through direct enterprise sales teams and benefits consultant channels, with consolidation favoring vendors demonstrating medical claims impact.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among United States Fortune 500 employers consolidating vendor relationships around integrated platforms, fragmenting procurement access for point-solution specialists and compressing contract values for undifferentiated service providers.
For Market Incumbents: Consolidate around biometric outcome accountability to defend against generative AI coaching entrants eroding traditional EAP margins. Deepen backward integration into wearable data infrastructure and captive clinical networks in metropolitan talent corridors. Lock in multi-year outcome-based contracts with financial services employers before procurement compression accelerates. For New Entrants and Emerging Players: Lead with modular API-first architectures targeting the underserved small and medium business segment below one thousand employees, where platform economics designed for Fortune 500 scale create persistent white space. Penetrate through Japan METI-subsidized mental health programs and Indian IT services diabetes prevention deployments. Anchor go-to-market through benefits technology marketplaces bypassing direct enterprise sales friction. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated payer-provider systems with medical cost demonstration capabilities over engagement-metric specialists. Long-term viability hinges on outcome attribution technology and regulatory compliance architecture spanning HIPAA and GDPR-plus-CSRD frameworks. Watch for EU AI Act enforcement actions as an inflection indicator for predictive analytics deployment feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Outcome Guarantee Contracts | UnitedHealth Group and CVS Health anchor Fortune 500 procurement through medical cost accountability. |
| Generative AI Coaching Integration | Virgin Pulse and digital-native platforms compress unit economics for subclinical anxiety interventions. |
| Wearable Data Infrastructure Partnership | Continuous glucose monitor and stress-tracking device manufacturers embed into employer risk stratification protocols. |
| GDPR-Compliant Architecture Separation | German and French vendors restructure data pipelines to isolate inference computation from identifiable records under EU AI Act constraints. |
| Small-Medium Business Modular Launch | API-first solutions bypass legacy HRIS integration debt to capture underserved employers below one thousand workers. |
Research Methodology
Desk research of SEC 10-K wellness program disclosures, EU CSRD workforce health filings, and hospital procurement databases preceded structured interviews with chief human resource officers, benefits consultants, digital health platform engineers, and licensed behavioral health providers. Secondary validation drew from HIPAA enforcement actions, GDPR regulatory guidance, and METI subsidy program documentation. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Variance decomposition across solution type, delivery model, end-user scale tier, and geographic regulatory cluster shaped the analytical framework. CAGRs were derived from segment-level growth rate reconciliation against aggregate market trajectory assumptions. Industry-specific forecast inputs included employer wellness budget elasticity coefficients and telehealth adoption curves for asynchronous clinical access.
Forecasts assume regulatory continuity in HIPAA-governed United States environments and GDPR-plus-CSRD European frameworks; material policy shifts in AI Act enforcement or ERISA incentive structure modifications would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Global Umbilical Cord Blood Banking Market
Healthcare Services
Metabolomics Services Market
Healthcare Services
Medical Spa Market
Healthcare Services
Funeral Products and Services Market
Healthcare Services
Global Mobile Clinics Market
Healthcare Services
Patient Throughput and Capacity Management Market
Healthcare Services
United States Senior Living Market
Healthcare Services
Contract Research Organization (CRO) Services Market
Healthcare Services
Primary Care Physicians Market
Healthcare Services
Private Healthcare Market
Healthcare Services
Global Healthcare Services Market
Healthcare Services
Contract Manufacturing Organization (CMO) Market
Healthcare Services
Healthcare Patent Filing Outsourcing Market
Healthcare Services
Global Operating Room Management Market
Healthcare Services
Global Healthcare Contract Development and Manufacturing Organization Market
Healthcare Services
Europe Pharmaceutical Logistics Market