
 US Healthcare Third-Party Logistics Market | 2026-2036
US Healthcare Third-Party Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
US Healthcare Third-Party Logistics Market Insights
Hospital procurement consolidation is pivoting toward centralized distribution networks that favor large-scale 3PL operators with national cold chain coverage. Cardinal Health leverages its integrated medical-surgical and pharmaceutical distribution platform to sustain hospital system contracts across major metropolitan hubs. FedEx Supply Chain anchors its competitive stance through temperature-controlled parcel infrastructure purpose-built for biologics and personalized medicine shipments. McKesson Corporation dominates wholesale-linked 3PL services, extending its reach through direct-to-pharmacy distribution and specialty pharmaceutical handling capabilities.
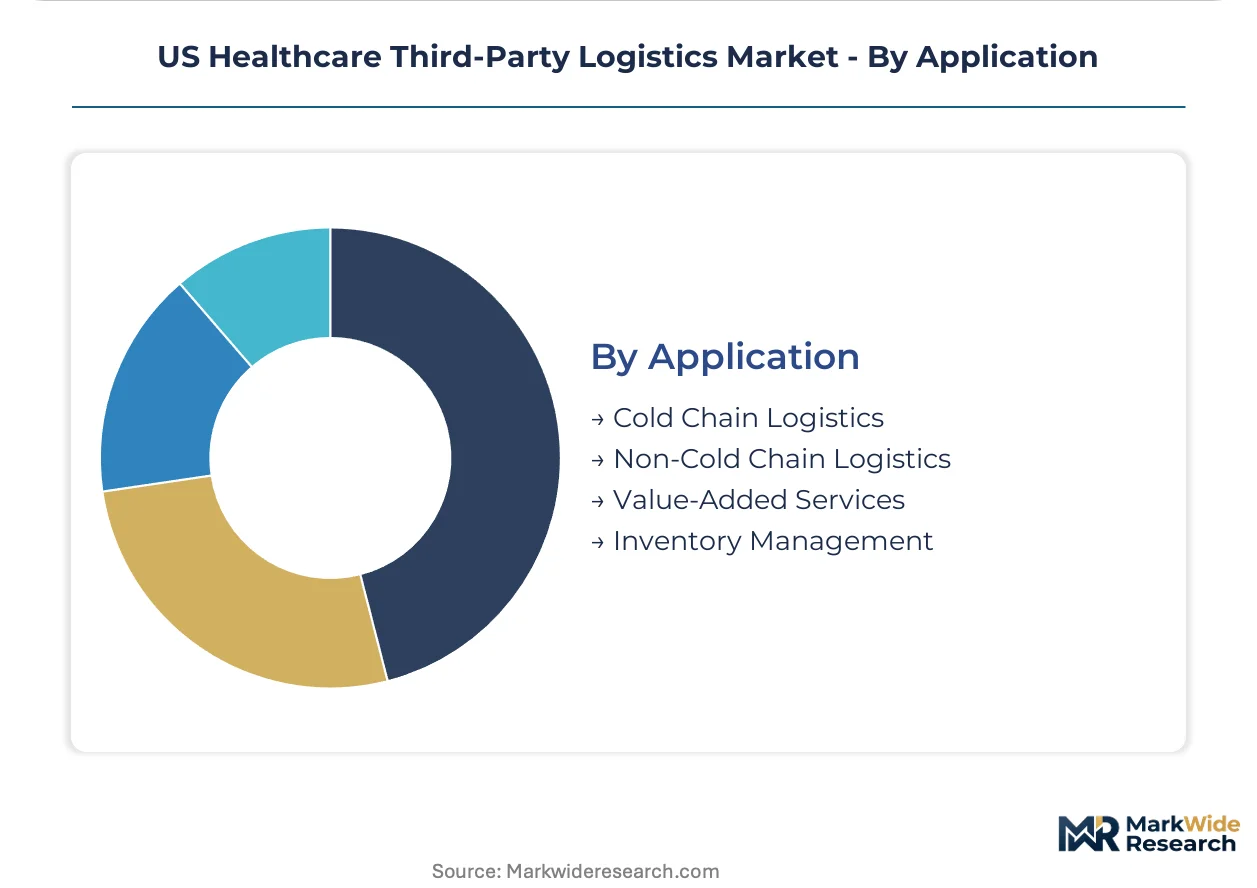
Healthcare third-party logistics encompasses the outsourced management of pharmaceutical, biologic, and medical device supply chains, requiring validated temperature monitoring systems, GDP-compliant warehousing, and serialized inventory tracking to maintain product integrity and regulatory compliance. The service type dimension segments into transportation, warehousing, packaging, and distribution functions, with cold chain warehousing commanding premium margins due to specialized infrastructure requirements and limited qualified facility supply. Application categories span cold chain logistics, non-cold chain logistics, value-added services, and inventory management, where cold chain logistics leads revenue contribution while value-added services such as kitting, serialization, and patient support programs represent the fastest-expanding margin pool.
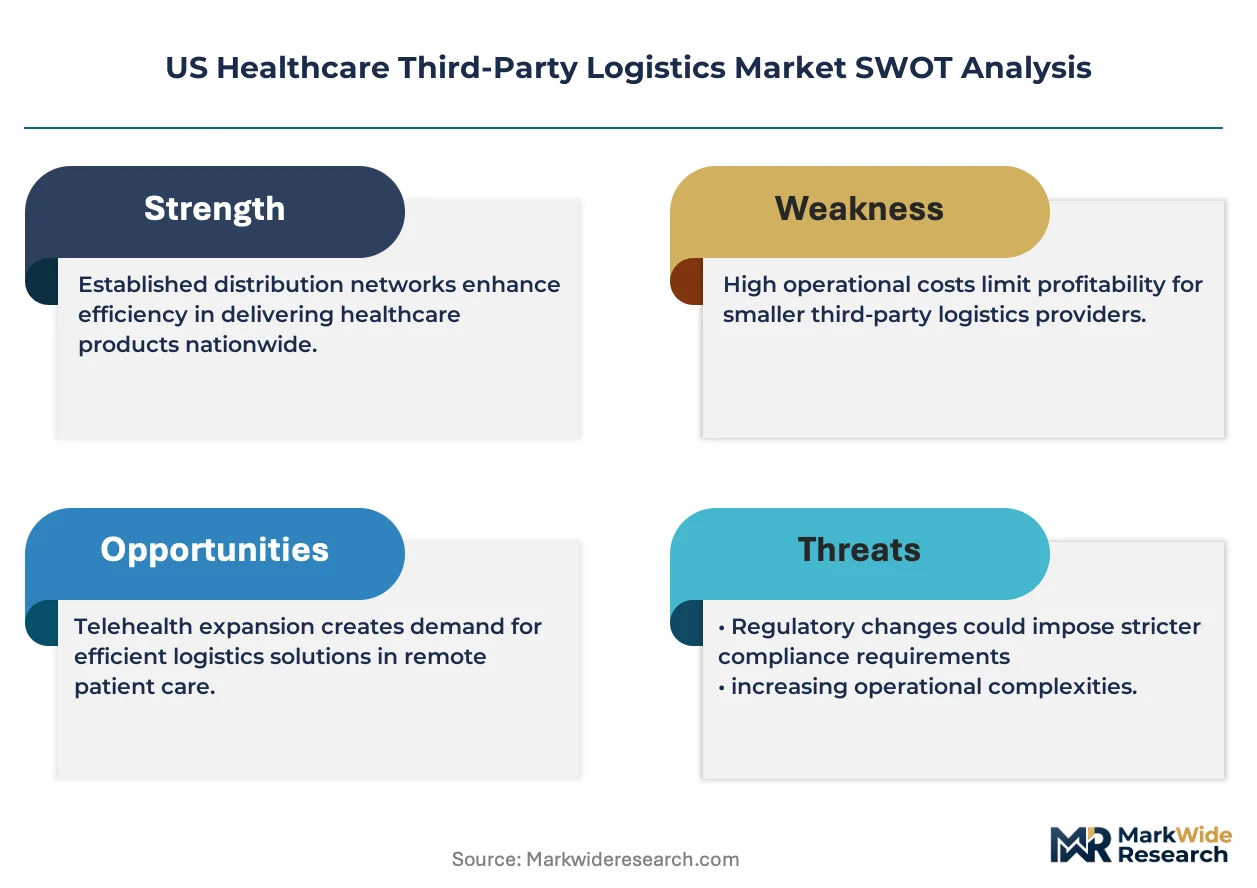
FDA DSCSA enforcement, HIPAA data security requirements for patient-directed shipments, and OSHA workplace safety standards collectively shape 3PL operational design, compliance cost structures, and technology investment priorities across the US healthcare supply chain. State-level pharmacy board regulations add further fragmentation, requiring multi-jurisdictional licensing and inspection protocols that favor established operators with regulatory affairs depth. Stakeholders must monitor how FDA guidance on advanced therapy medicinal products evolves, as these therapies demand novel chain-of-identity and chain-of-custody protocols that current 3PL systems only partially address.
Market Dynamics
Cell and gene therapy commercialization is compressing distribution timelines from weeks to days, forcing 3PLs to rebuild warehouse networks around patient proximity rather than wholesale efficiency. This shift is redrawing capital allocation across temperature-controlled infrastructure.
Growth Catalysts
- FDA DSCSA Serialization Mandates:Wholesalers and 3PLs must deploy track-and-trace systems by November 2024, creating captive demand for compliance-integrated logistics platforms.
- Biologics Manufacturing Clustering:New Jersey and Massachusetts pharmaceutical density generates specialized warehousing demand that generalist operators cannot serve.
- Real-Time Temperature Monitoring:IoT sensor networks enable predictive intervention before excursions occur, reducing product loss rates in cold chain lanes.
Market Restraints
- Qualified Facility Scarcity:GDP-compliant cold storage construction costs exceed standard warehousing by multiples, limiting new entrants in high-demand corridors.
- State Pharmacy Board Fragmentation:Multi-jurisdictional licensing requirements create compliance drag for operators seeking national coverage.
- Specialized Talent Bottleneck:Cold chain engineers and regulatory affairs specialists command premium compensation, compressing operator margins.
Strategic Opportunities
- Direct-to-Patient Distribution:Specialty pharmacies and home infusion services require last-mile cold chain capabilities that hospital-centric networks underserve.
- Advanced Therapy Medicinal Products:Chain-of-identity protocols for CAR-T therapies create first-mover advantage for 3PLs building cryogenic handling infrastructure.
- HIPAA-Compliant Data Services:Patient-directed shipment tracking generates recurring revenue streams beyond physical logistics.
Industry Challenges
- Serialized Inventory System Integration:Legacy warehouse management platforms require costly retrofitting to meet DSCSA verification requirements.
- Cryogenic Infrastructure Scaling:Liquid nitrogen storage and vapor shipper management demand capital commitments with uncertain utilization curves.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Healthcare Third-Party Logistics Market |
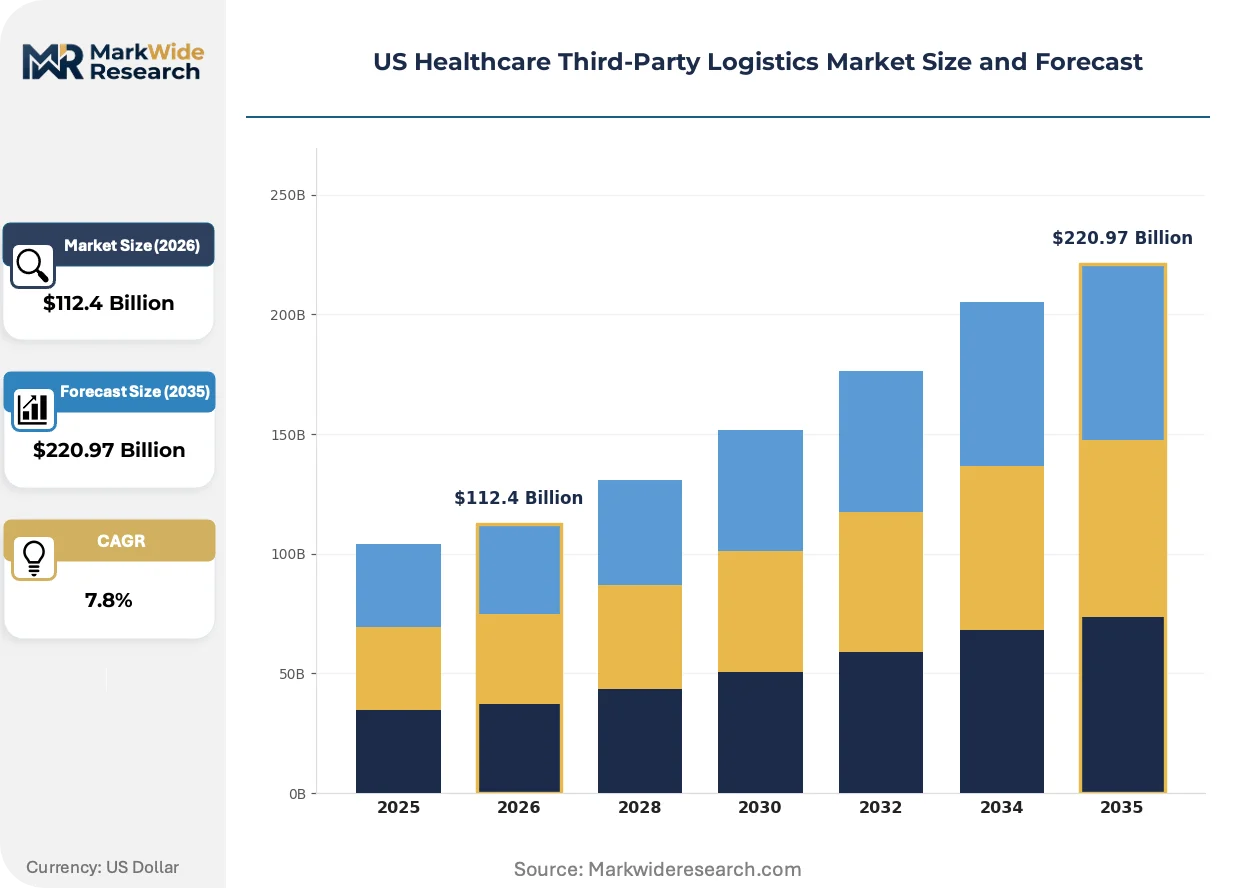
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $220.97 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Packaging, Distribution End User: Pharmaceutical Companies, Medical Device Manufacturers, Hospitals, Laboratories Delivery Mode: Air Freight, Ocean Freight, Road Transport, Courier Services Application: Cold Chain Logistics, Non-Cold Chain Logistics, Value-Added Services, Inventory Management |
| Companies Covered | Cardinal Health, UPS Healthcare, Kuehne + Nagel, Cencora, McKesson Corporation, DHL Group, AmerisourceBergen Corporation, FedEx Supply Chain, DB Schenker, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Healthcare Third-Party Logistics Market Trends and Innovations
Digital twin technology and blockchain verification are converging to create immutable chain-of-custody records, transforming how stakeholders prove compliance across multi-handoff supply chains.
Blockchain-based serialization is rewriting audit trail standards across pharmaceutical distribution. Wholesale distributors and specialty pharmacies are piloting distributed ledger systems to eliminate reconciliation delays between trading partners. This architecture compresses investigation timelines for suspected counterfeit products from months to hours.
FDA guidance on advanced therapy medicinal products is tightening documentation requirements for cell and gene therapy shipments. Manufacturers must now demonstrate continuous temperature control and identity preservation across all custody transfers. California and Massachusetts biotech clusters are driving earliest adoption of these protocols as they host the majority of commercial ATMP launches.
Hospital procurement consolidation is concentrating buying power among integrated delivery networks with national footprints. These systems are unbundling distribution contracts from group purchasing organizations, negotiating directly with 3PLs for dedicated cold chain capacity. The Southeast and Southwest regions show fastest transition toward this model as health system mergers accelerate.
US Healthcare Third-Party Logistics Market Segmentation
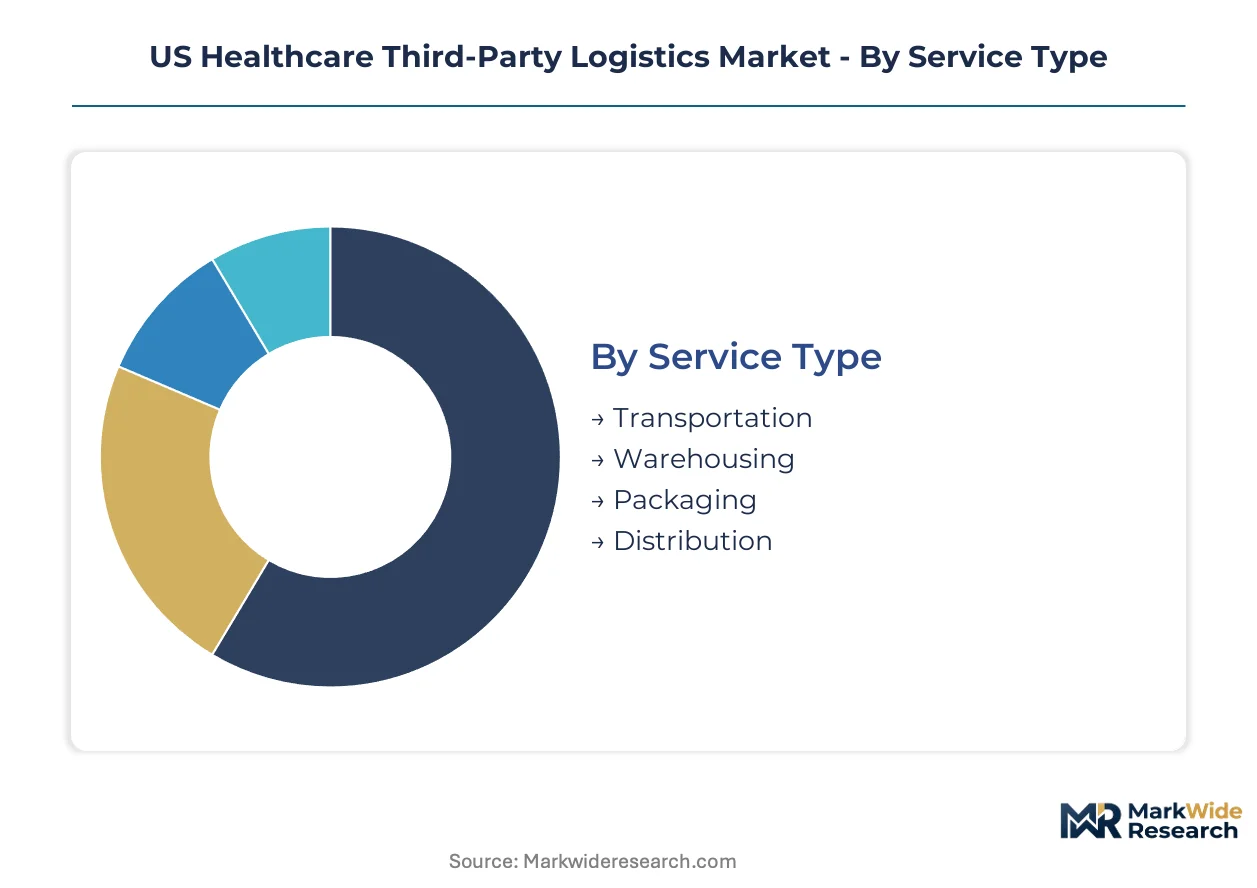
Healthcare third-party logistics segmentation reveals how specialized infrastructure requirements and regulatory compliance pressures concentrate value across distinct operational models. Each dimension exposes where capital deployment and margin capture diverge most sharply.
Service Type:
Cold chain infrastructure scarcity concentrates margin capture in warehousing, while transportation remains fragmented across asset-light and asset-heavy operators.
- Transportation:Temperature-controlled trucking and parcel networks move product between nodes, with lane density determining unit economics. Pharmaceutical manufacturers in New Jersey and Massachusetts drive highest volume through temperature-validated ground corridors.
- Warehousing:GDP-compliant facilities with validated refrigeration, freezer, and cryogenic zones command premium rates due to limited qualified supply. The Northeast corridor exhibits acute capacity constraints as biologics manufacturing clusters expand.
- Packaging:Insulated shippers, phase-change materials, and active temperature-controlled containers protect product integrity across handoffs. Demand concentrates in personalized medicine shipments requiring patient-specific thermal protection.
- Distribution:Consolidated fulfillment, cross-docking, and direct-to-pharmacy delivery integrate serialization compliance with last-mile execution. Hospital procurement consolidation favors operators with national cold chain coverage.
Warehousing absorbs the bulk of installed capacity; value-added distribution services are expanding most quickly.
End User:
Customer type determines service complexity tiers, with pharmaceutical and advanced therapy manufacturers demanding the most specialized handling protocols.
- Pharmaceutical Companies:Branded and generic drug manufacturers require DSCSA-compliant serialization, temperature monitoring, and wholesale distribution integration. Cell and gene therapy producers in California and Massachusetts drive demand for cryogenic chain-of-identity capabilities.
- Medical Device Manufacturers:Implantable and diagnostic device producers need sterile handling, lot tracking, and hospital-direct fulfillment. Orthopedic and cardiovascular device clusters in Indiana and Minnesota anchor regional demand.
- Hospitals:Integrated delivery networks seek consolidated medical-surgical and pharmaceutical distribution with inventory management services. IDN consolidation in Texas and Florida accelerates centralized procurement models.
- Laboratories:Clinical and research laboratories require specimen transport, reagent storage, and time-critical delivery windows. Reference lab networks in North Carolina and Illinois generate recurring specimen logistics demand.
Pharmaceutical companies dominate current revenue contribution; hospital systems are gaining share fastest as procurement centralization accelerates.
Delivery Mode:
Modal selection tracks product value density and temperature sensitivity, with premium biologics favoring speed over cost minimization.
- Air Freight:International and domestic air cargo enables rapid transit for high-value, temperature-sensitive biologics and clinical trial materials. Memphis and Louisville hub infrastructure supports pharmaceutical air freight consolidation.
- Ocean Freight:Temperature-controlled container shipping moves bulk pharmaceutical ingredients and stable finished goods with lower unit costs. Port congestion and customs delays limit adoption for time-critical shipments.
- Road Transport:Dedicated and less-than-truckload refrigerated trucking dominates domestic pharmaceutical distribution. Lane optimization between New Jersey, Pennsylvania, and Illinois manufacturing clusters drives network efficiency.
- Courier Services:Parcel networks handle direct-to-patient and direct-to-pharmacy shipments with real-time tracking and intervention capabilities. Last-mile cold chain gaps in rural markets create service differentiation opportunities.
Road transport carries the highest volume share; courier services are climbing the fastest on direct-to-patient expansion.
Application:
Application segmentation separates physical logistics from value-added services, revealing where technology and compliance investments generate margin expansion.
- Cold Chain Logistics:Continuous temperature control across storage and transport maintains product potency for biologics, vaccines, and cell therapies. FDA enforcement of temperature documentation drives investment in IoT monitoring infrastructure.
- Non-Cold Chain Logistics:Ambient temperature distribution serves stable pharmaceuticals, medical-surgical supplies, and durable medical equipment. Generic drug and commodity supply chains compete primarily on cost and reliability.
- Value-Added Services:Kitting, serialization, patient support programs, and data analytics extend 3PL relationships beyond physical handling. Specialty pharmacy and manufacturer services represent the steepest expansion trajectory.
- Inventory Management:Vendor-managed inventory, demand forecasting, and consignment models reduce working capital for healthcare providers. Hospital system adoption varies by procurement sophistication and IT integration capacity.
Cold chain logistics commands the largest revenue pool; value-added services are gaining share fastest on digital and patient-centric service expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical manufacturing density concentrates demand along the Northeast corridor, where biologics production clusters and hospital procurement consolidation reshape logistics infrastructure requirements across sub-regional markets.
Northeast Corridor
New Jersey and Massachusetts pharmaceutical manufacturing generates specialized cold chain warehousing demand that generalist operators cannot satisfy. FDA DSCSA serialization mandates compel wholesalers and 3PLs in this corridor to upgrade track-and-trace infrastructure by enforcement deadlines. The I-95 pharmaceutical belt from Trenton to Boston anchors national biologics distribution capacity.
Southeast
Hospital system mergers in Florida and Texas accelerate centralized procurement models favoring national cold chain coverage. State pharmacy board regulations across the Southeast create multi-jurisdictional licensing complexity that favors established operators with regulatory affairs depth. Atlanta and Miami emerge as distribution hubs serving expanding specialty pharmacy networks.
Midwest
Medical device manufacturing clusters in Indiana and Minnesota anchor regional demand for sterile handling and hospital-direct fulfillment. OSHA workplace safety standards shape warehouse operational design across Illinois and Ohio distribution centers. The Chicago-Indianapolis corridor supports orthopedic and cardiovascular device logistics networks.
Pacific Coast
California biotech clusters drive earliest adoption of advanced therapy medicinal product protocols requiring cryogenic chain-of-identity capabilities. HIPAA data security requirements for patient-directed shipments generate compliance investment priorities across San Francisco and San Diego logistics operations. The state hosts the majority of commercial cell and gene therapy launches.
US Healthcare Third-Party Logistics Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue patient-proximity distribution models that compress timelines from weeks to days. The market structure concentrates around integrated healthcare distributors with wholesale-linked 3PL services and parcel operators with temperature-controlled infrastructure. Three archetypes dominate: pharmaceutical wholesale-integrated platforms, global express carriers with healthcare verticals, and specialized cold chain operators. Competitive dynamics center on M&A for regulatory compliance capabilities and capacity expansion in qualified GDP-compliant facilities.
Within the wholesale-integrated tier, McKesson Corporation and Cencora occupy positions that exemplify pharmaceutical distribution scale. FedEx Supply Chain anchors the express carrier vertical with infrastructure purpose-built for biologics. These three entities represent how capital allocation toward temperature-controlled networks and serialization compliance separates market tiers.
| Leading Market Players |
|---|
| Cardinal Health |
| UPS Healthcare |
| Kuehne + Nagel |
| Cencora |
| McKesson Corporation |
| DHL Group |
| AmerisourceBergen Corporation |
| FedEx Supply Chain |
| DB Schenker |
| Others |
Pricing and Supply Chain Analysis
FDA DSCSA serialization mandates gate both qualified supply and premium-tier pricing access, as only GDP-compliant operators with track-and-trace infrastructure can serve pharmaceutical manufacturers facing November enforcement deadlines. Cold chain warehousing commands rate premiums exceeding standard facilities, while non-compliant operators face exclusion from wholesale-linked distribution networks.
Pricing Analysis
Volume concentrates in road transport and ambient warehousing, while margins pool in cryogenic storage and value-added serialization services. Three-tier pricing structure across GDP-validated premium, standard-compliant, and non-compliant economy levels reflects certification grade and temperature-control sophistication. Pricing pressure stems from qualified facility scarcity in the Northeast corridor, where construction cost multiples limit new supply. Generic drug distributors exhibit highest price sensitivity; cell and gene therapy manufacturers accept premium rates for chain-of-identity capabilities.
Supply Chain Analysis
GDP certification and FDA validation requirements restrict qualified supply to established operators with multi-jurisdictional licensing depth. Domestic pharmaceutical manufacturing clusters in New Jersey, Massachusetts, and California draw from specialized cold storage networks, with equipment and qualified engineering talent as critical inputs. Single-source vulnerability runs through limited cryogenic infrastructure for advanced therapy medicinal products. Distribution runs through wholesale-integrated platforms for hospital systems and courier networks for direct-to-patient channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market consolidation accelerates as FDA enforcement deadlines force capital-constrained operators to exit or sell. Serialization compliance costs and qualified facility scarcity favor scaled incumbents with regulatory affairs depth.
For Market Incumbents: To counter emerging specialized cold chain operators, acquire GDP-compliant facilities in the Southeast and Pacific Coast corridors where hospital procurement consolidation outpaces local supply. Deepen backward integration into temperature-monitoring IoT platforms to capture recurring revenue beyond physical logistics.
For New Entrants and Emerging Players: Rural specialty pharmacies represent the most penetrable buyer archetype, as national networks underserve last-mile cold chain gaps in non-metropolitan markets. Target direct-to-patient distribution for home infusion services, leveraging HIPAA-compliant data services as a differentiated entry wedge.
For Investors and Strategic Acquirers: FDA guidance publication on advanced therapy medicinal products is the leading indicator that cryogenic infrastructure valuations will decouple from standard cold chain assets. Five-to-ten year viability favors operators with patient-proximity warehouse networks and chain-of-identity technology stacks.
| Strategic Initiative | Industry Significance |
|---|---|
| DSCSA Compliance Integration | Track-and-trace infrastructure investments secure wholesale distribution contracts ahead of FDA enforcement. |
| Cryogenic Capacity Expansion | Liquid nitrogen storage buildout captures CAR-T therapy demand from California and Massachusetts biotech clusters. |
| Direct-to-Patient Network Build | Last-mile cold chain capabilities serve specialty pharmacy growth outside hospital-centric distribution models. |
| HIPAA-Compliant Data Services | Patient-directed shipment tracking generates recurring revenue streams beyond physical logistics handling. |
| Regulatory Affairs Capability Acquisition | Multi-jurisdictional licensing expertise reduces compliance drag across fragmented state pharmacy board regimes. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across 3PL operations directors, pharmaceutical supply chain executives, hospital procurement managers, and cold chain engineering specialists. FDA DSCSA guidance documents, state pharmacy board licensing databases, and GDP facility inspection reports provided validation layers. Bottom-up capacity assessments and top-down pharmaceutical shipment value estimates underwent triangulation to reconcile segment totals.
Data-stream reconciliation across service type, end user, delivery mode, and application dimensions enabled consistent projection modeling throughout the forecast period. CAGRs derived from pharmaceutical manufacturing output trajectories, biologics commercialization pipelines, and cold chain infrastructure investment cycles. Treatment modality shifts toward cell and gene therapies and hospital system merger velocity served as industry-specific demand drivers.
Revisions become necessary when FDA enforcement timelines shift, advanced therapy medicinal product guidance tightens documentation requirements, or hospital procurement consolidation accelerates beyond modeled rates. A model refresh is warranted upon material change in qualified facility construction costs or state-level pharmacy board regulatory harmonization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Global Ambulatory Services Market
Healthcare Services
US Biopharmaceutical Third-Party Logistics Market
Healthcare Services
Transitional Care Management Services Market
Healthcare Services
Professional Spa Services Market
Healthcare Services
Chronic Disease Management Service Market
Healthcare Services
Inhaled and Intranasal Products Contract Service Providers Market
Healthcare Services
South Korea Healthcare Cold Chain Logistics Market
Healthcare Services
Global Cath Lab Services Market
Healthcare Services
China Fertility Services Market
Healthcare Services
Healthcare Transportation Services Market
Healthcare Services
Outpatient Clinics Market
Healthcare Services
EMEA Home Infusion Services Market
Healthcare Services
Hospital Resource Management Market
Healthcare Services
US Medical Billing Outsourcing Market
Healthcare Services
Global Offsite Medical Case Management Market
Healthcare Services
US Acute Hospital Care Market